
 Pet Stain Remover and Odour Control Market | 2026-2036
Pet Stain Remover and Odour Control Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Stain Remover and Odour Control Market Analytics
Asset-light contract manufacturing and private-label leasing arrangements are narrowing the capital barrier for new entrants in enzymatic formulations. Tropiclean leverages captive biotech R&D partnerships to sustain formulation leadership in natural enzyme blends. Bissell anchors its position through backward integration into dispensing hardware that locks in recurring cleaner consumption. Nature's Miracle dominates the veterinary channel through clinic-exclusive concentrate systems that competitors cannot easily replicate.
Pet stain removers and odour control products comprise surfactant-enzyme cocktails, oxidizing agents, and probiotic cultures formulated to hydrolyse organic matter and neutralize volatile sulphur and nitrogen compounds at source rather than masking them. Spray cleaners lead volume due to convenience, while liquid concentrates capture the strongest margin pools through dilution economics and institutional bulk sales. Foam cleaners occupy a durable niche in upholstery applications where controlled spread prevents oversaturation of delicate fabrics.
EPA Safer Choice and REACH compliance in Europe now mandate biodegradability thresholds that exclude legacy solvent chemistry from institutional tenders. The FDA's veterinary oversight framework indirectly shapes demand by embedding hygiene protocols into accredited clinic operations. Stakeholders must monitor how tightening state-level VOC regulations in California and New York will cascade into reformulation requirements for national product lines.
Market Dynamics
Enzyme-based bio-catalytic chemistry is collapsing the legacy solvent segment as institutional procurement locks onto EPA Safer Choice and REACH biodegradability mandates, rewiring formulation economics and supplier qualification criteria across developed markets.
Growth Catalysts
- Veterinary clinic protocols:Accredited clinic operations now embed preventive hygiene standards that institutionalize recurring concentrate purchases.
- REACH compliance thresholds:European biodegradability mandates exclude legacy solvent chemistry from tender eligibility, accelerating enzymatic adoption.
- California VOC regulations:State-level air quality standards cascade into national reformulation requirements that favor low-emission enzymatic platforms.
Market Restraints
- Protease enzyme supply concentration:Fermentation capacity for industrial-grade enzymes clusters in select biotech manufacturing hubs, creating input vulnerability.
- REACH registration costs:Small and mid-size formulators face structural cost barriers to full European chemical compliance.
- DIY home remedy substitution:Vinegar-baking soda formulations compete on zero-cost positioning in price-sensitive household segments.
Strategic Opportunities
- Japanese premium household segment:Underpenetrated demand for clinic-grade home formulations offers white-space expansion for concentrate systems.
- Subscription dispensing hardware:IoT-enabled reordering devices create captive consumption loops and recurring revenue architecture.
- EU Green Deal procurement incentives:Public sector tender preferences for bio-based chemistry open institutional volume previously locked by solvent incumbents.
Industry Challenges
- Formulation stability expertise:Shortage of enzymatic chemists capable of optimizing multi-enzyme cocktail shelf life in varying temperature conditions.
- Dual certification timelines:Simultaneous EPA Safer Choice and EU Ecolabel pursuit extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Stain Remover and Odour Control Market |
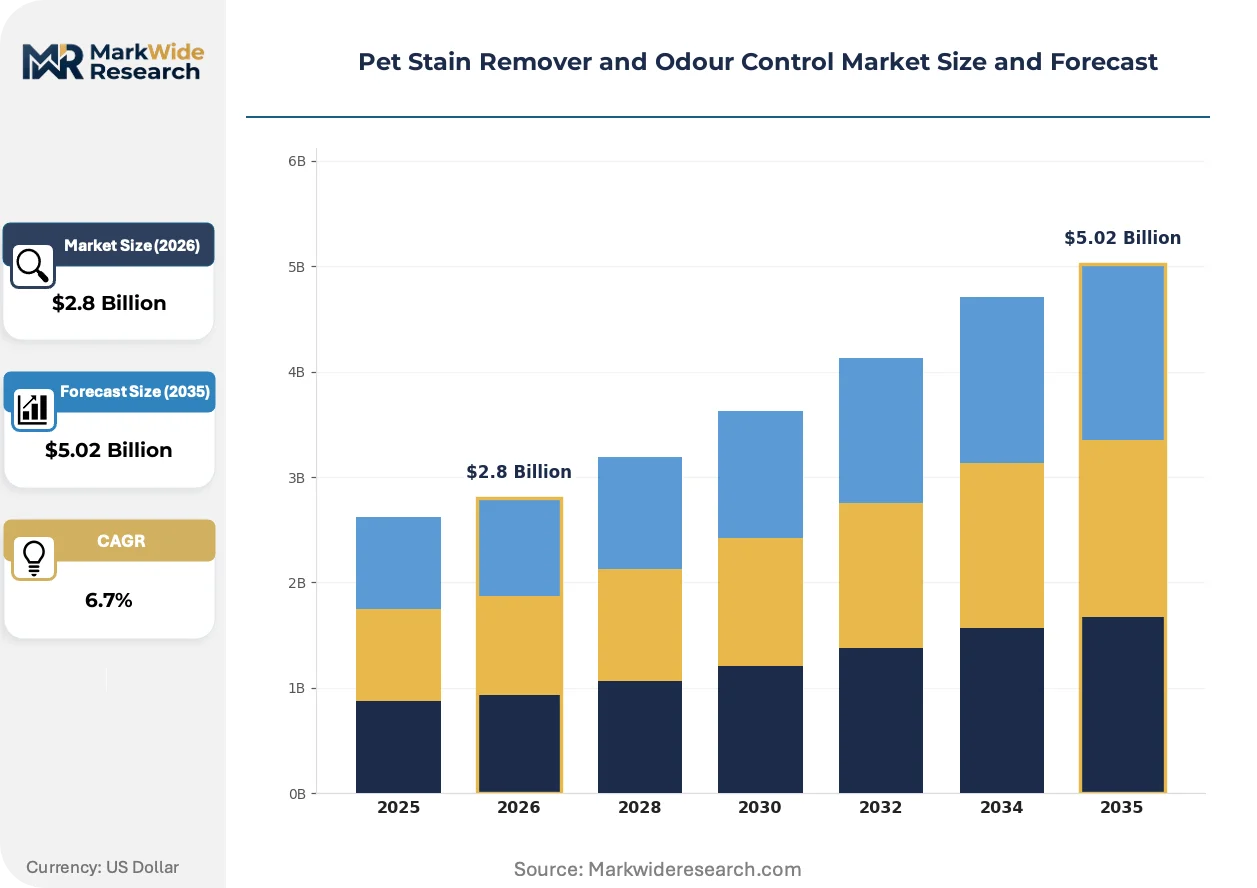
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Cleaners, Foam Cleaners, Spray Cleaners, Wipes Application: Carpets, Upholstery, Floors, Bedding Distribution Channel: Online Retailers, Supermarkets, Pet Stores, Pharmacies Customer Type: Pet Owners, Veterinary Clinics, Cleaning Services, Shelters |
| Companies Covered | Tropiclean, Vetoquinol, Rocco & Roxie Supply Co., Bissell, Out!, Simple Solution, Resolve, Nature's Miracle, Angry Orange, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Stain Remover and Odour Control Market Evolving Landscape
Formulation science, hardware-software integration, and procurement digitization are converging to transform how stain removal chemistry reaches end-users and locks in recurring consumption.
Bio-catalytic enzyme blends incorporating protease, amylase, and lipase fractions are collapsing the performance gap with solvent-based predecessors while eliminating volatile organic compound emissions. Veterinary clinics and hospitality operators are adopting these systems fastest, driven by liability concerns and indoor air quality protocols. The technology is collapsing premium pricing tiers as manufacturing scale drives unit economics toward parity with legacy chemistry.
EPA Safer Choice standards now govern federal and state institutional procurement in the United States, disqualifying non-biodegradable formulations from school, hospital, and government facility tenders. The regulation compresses addressable market share for solvent incumbents and forces portfolio restructuring toward enzymatic platforms. California and New York state implementations are tightening fastest, creating geographic compliance complexity for national product lines.
Subscription-enabled dispensing hardware is replacing episodic retail purchasing in premium household segments, with connected devices triggering automatic replenishment based on usage telemetry. Specialty pet retailers and direct-to-consumer channels are capturing this shift, displacing mass-market shelf space dependence. Germany and Japan show the strongest adoption velocity where smart home penetration intersects with pet ownership density.
Pet Stain Remover and Odour Control Market Segmentation
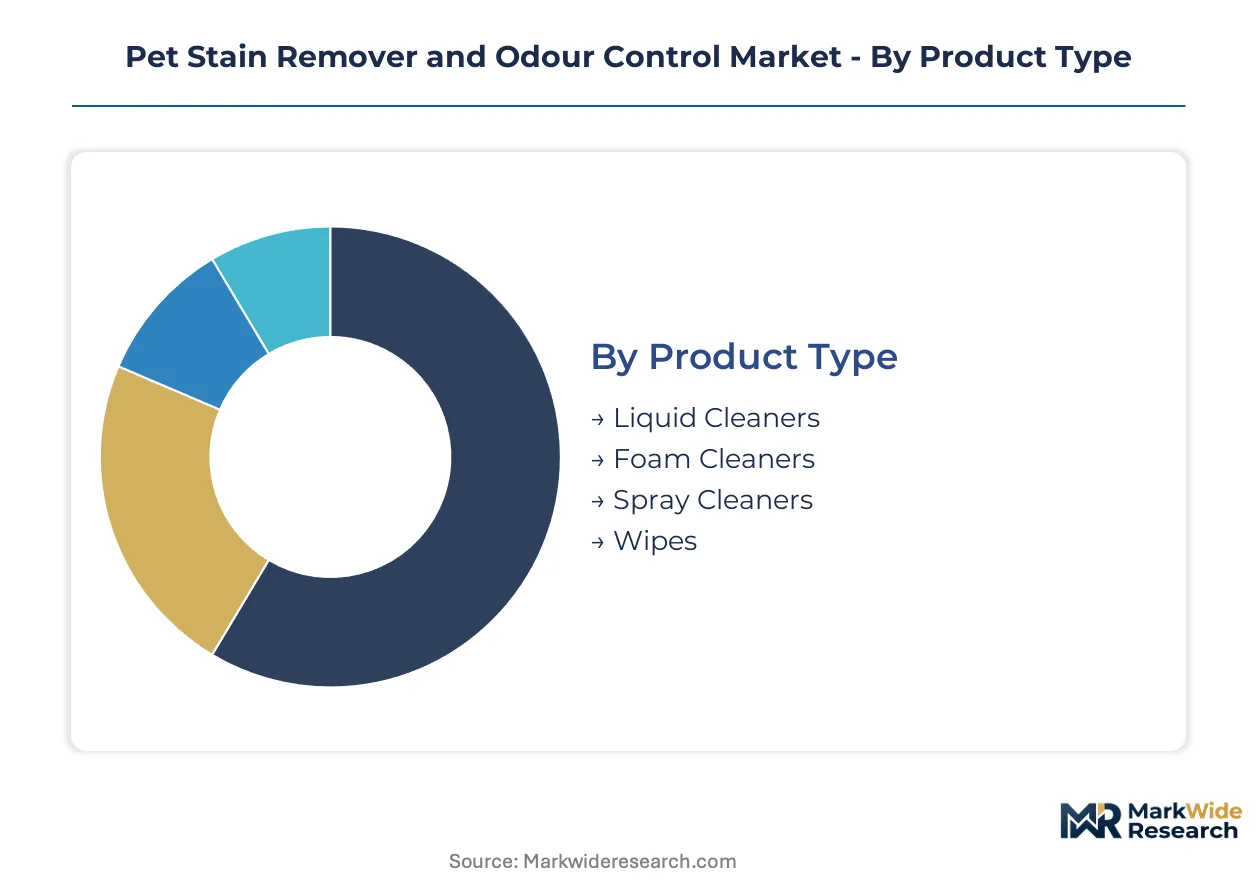
Segmentation in pet stain removers reveals how formulation chemistry, application surface, and procurement channel intersect to create distinct margin architectures. Understanding these splits exposes where enzymatic premiumization commands pricing power versus where solvent legacy products still compete on cost.
Product Type:
The use-case spectrum spans quick spot treatments through deep extraction systems, with each format demanding different enzymatic stability engineering and packaging investment.
- Liquid Cleaners:Concentrated enzymatic cocktails requiring dilution deliver the strongest unit economics through bulk institutional sales. Veterinary clinics in Germany and Japan now specify these systems for floor-machine compatibility and cost-per-use accountability.
- Spray Cleaners:Pre-diluted formulations in trigger-dispense packaging dominate household convenience purchasing. United States pet owners drive volume here, though California VOC compliance is forcing reformulation toward lower-emission propellant systems.
- Foam Cleaners:Controlled-expansion formulations prevent oversaturation of delicate upholstery fibers. Premium furniture retailers in Japan bundle these with white-glove delivery services.
- Wipes:Impregnated nonwoven substrates offer portability for travel and emergency spot treatment. Limited enzymatic shelf stability constrains formulation potency versus liquid alternatives.
The dominant share belongs to Spray Cleaners, while Liquid Cleaners is closing the gap fastest.
Application:
Surface material porosity and fiber chemistry dictate enzymatic dwell time requirements and pH tolerance thresholds.
- Carpets:Dense synthetic and natural fiber matrices trap organic matter deep in pile backing. Truck-mounted extraction systems used by United States cleaning services demand high-concentrate enzymatic pre-sprays compatible with hot-water rinse cycles.
- Upholstery:Delicate fabric blends and leather alternatives require pH-neutral formulations with controlled moisture delivery. Italian luxury furniture manufacturers specify EU Ecolabel-certified products for warranty compliance.
- Floors:Hard surface sealants and grout lines present different hydrolysis challenges than fiber. REACH-compliant enzymatic formulations are displacing solvent-based mop concentrates in French hospital procurement.
- Bedding:Direct skin contact protocols demand fragrance-free, residue-rinseable chemistry. Shelters in the United Kingdom prioritize these specifications for animal welfare certification audits.
Carpets holds the revenue base, though Bedding applications are expanding most quickly in shelter and rescue network procurement.
Distribution Channel:
Channel selection determines margin capture versus volume velocity, with subscription mechanics now disrupting traditional retail throughput.
- Online Retailers:Direct-to-consumer platforms enable auto-replenishment algorithms and review-driven discovery. German smart home integration is accelerating connected-dispenser bundling through these channels.
- Supermarkets:Mass-market shelf space rewards velocity pricing and promotional frequency. United States big-box retailers are reducing SKU count to favor EPA Safer Choice-certified formulations exclusively.
- Pet Stores:Specialty staff consultation supports premium enzymatic positioning and bundle economics. Independent United States chains are developing private-label concentrate systems to compete with veterinary-exclusive brands.
- Pharmacies:Clinical credibility positioning targets senior pet owners and prescription-adjacent purchasing. French pharmacy networks are expanding veterinary hygiene adjacencies.
Online Retailers command the steepest expansion trajectory, while Supermarkets retain the volume foundation.
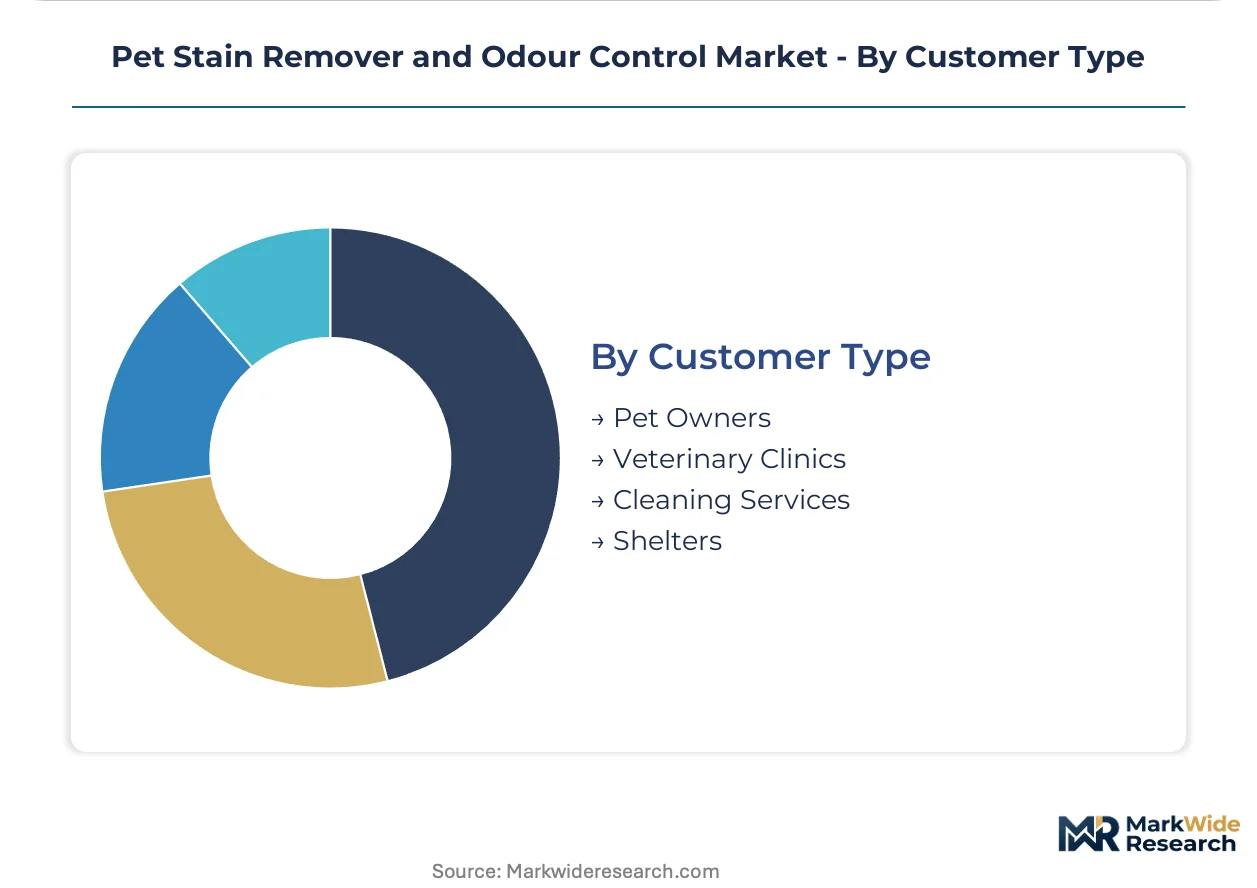
Customer Type:
Professional versus household procurement separates recurring concentrate purchasing from episodic retail buying patterns.
- Pet Owners:Household decision-makers balance convenience format against per-treatment cost. Japanese premium households show strongest adoption of subscription dispensing hardware.
- Veterinary Clinics:Accredited facilities embed preventive hygiene protocols with recurring concentrate procurement. EPA Safer Choice compliance is now mandatory for United States federal veterinary facility tenders.
- Cleaning Services:Commercial operators prioritize dilution economics and equipment compatibility. Italian contract cleaners are fastest to adopt probiotic culture formulations for ongoing odor suppression.
- Shelters:High-turnover, resource-constrained environments demand bulk concentrate value. United Kingdom rescue networks are consolidating procurement through cooperative purchasing agreements.
Veterinary Clinics anchor the premium tier, while Cleaning Services are gaining share fastest through commercial route expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of enzymatic concentrates from German and United States biotech fermentation hubs now exceed import dependency on legacy solvent chemistry. Trade balances favor countries with captive EPA Safer Choice and REACH certification infrastructure.
United States
Federal veterinary facility tenders now mandate EPA Safer Choice compliance, locking institutional volume into domestic enzymatic supply chains. California's CARB VOC regulations cascade into national reformulation requirements that disadvantage imported solvent-based alternatives. Cincinnati and Chicago host the densest clusters of contract fermentation capacity serving private-label concentrate brands.
Germany
EU Ecolabel procurement preferences in hospital and municipal cleaning contracts accelerate enzymatic displacement of solvent chemistry. REACH registration costs filter out small importers, protecting domestic formulators with established compliance infrastructure. The Rhine-Ruhr corridor concentrates industrial biotechnology capacity for protease and lipase enzyme production.
Japan
Premium household demand for clinic-grade home formulations outpaces supply of certified enzymatic concentrates. METI's chemical substance management framework tightens biodegradability thresholds for institutional tenders. Osaka and Nagoya manufacturing clusters specialize in pH-neutral upholstery formulations for luxury furniture export markets.
United Kingdom
Animal shelter certification audits drive procurement standardization around fragrance-free, residue-rinseable bedding formulations. The country's national chemical regulator enforces REACH-aligned biodegradability mandates post-Brexit through retained EU law. Manchester and Birmingham cooperative purchasing networks consolidate rescue sector volume to extract bulk concentrate pricing.
France
Hospital procurement directives prioritize bio-based chemistry for floor and surface hygiene protocols. ANSM oversight of veterinary clinic accreditation embeds preventive hygiene standards into recurring concentrate purchasing. Lyon and Marseille industrial cleaning service networks pilot probiotic culture formulations for ongoing odor suppression contracts.
Pet Stain Remover and Odour Control Market Competitive Landscape
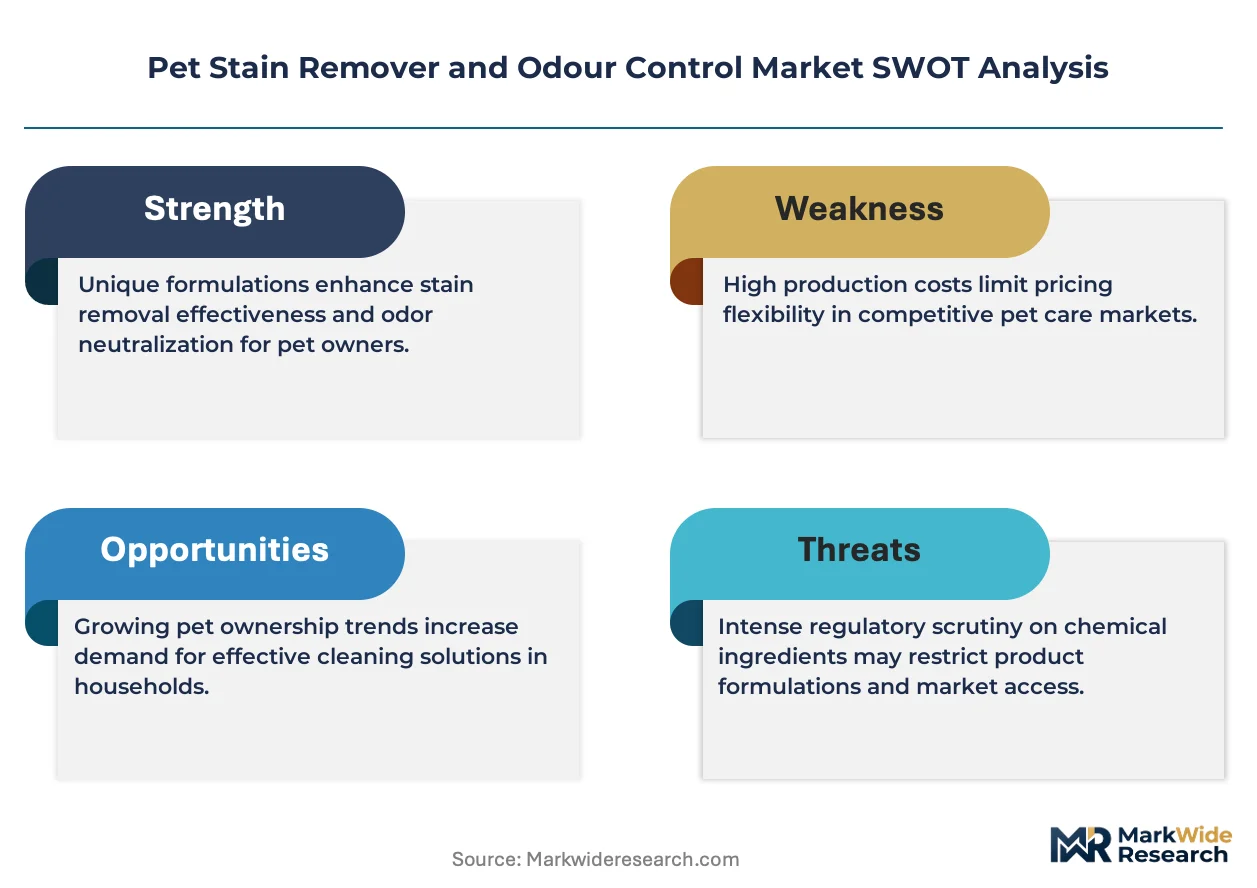
On the supply side, the industry is bifurcating between asset-light contract manufacturers and vertically integrated formulators with captive biotech partnerships. Concentration is moderate at the premium tier, with enzymatic specialists holding pricing power through certification moats, while private-label volume fragments across regional compounders. Two strategic archetypes dominate: fermentation-backed formulation leaders and hardware-integrated system providers. Competitive moves center on backward integration into dispensing hardware and exclusive clinic distribution agreements that lock in recurring concentrate consumption.
Within the enzymatic specialist tier, Tropiclean and Nature's Miracle occupy positions that exemplify divergent channel strategies—natural enzyme blend leadership versus veterinary-exclusive concentrate systems. Bissell anchors the hardware-integrated archetype through captive dispensing equipment that binds cleaner consumption to proprietary refills. These three represent the dominant competitive vectors shaping procurement relationships across institutional and premium household segments.
| Leading Market Players |
|---|
| Tropiclean |
| Vetoquinol |
| Rocco & Roxie Supply Co. |
| Bissell |
| Out! |
| Simple Solution |
| Resolve |
| Nature's Miracle |
| Angry Orange |
| Others |
Value Network & Pricing Analysis
Fermentation capacity for industrial-grade protease and lipase enzymes clusters in United States and German biotech manufacturing hubs, concentrating upstream supply power and directing margin capture toward formulators with captive R&D partnerships or long-term offtake agreements with veterinary clinic networks.
Pricing Analysis
Veterinary clinic buyers anchor a three-tier pricing structure across premium, standard, and economy levels in this market. Price differentiation rests on EPA Safer Choice certification tier and volume procurement scale, with accredited clinic networks capturing steepest discounts through recurring concentrate commitments. Cost compression in the standard tier is intensifying because private-label contract manufacturers narrow formulation gaps at lower unit economics. Household retail purchasers show highest price sensitivity, while institutional cleaning services demonstrate lowest sensitivity due to dilution economics and liability-driven quality mandates.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize supplier financing arrangements between enzymatic concentrate formulators and veterinary clinic distributors, stretching working capital requirements downstream. Manufacturing draws from United States, Germany, and Japanese industrial biotechnology clusters, with raw material dependencies spanning fermentation feedstocks, specialized enzyme stabilizers, and pH-neutral surfactant bases. Single-source vulnerability concentrates in protease enzyme supply, where limited fermentation facilities create input bottlenecks during demand surges. Distribution runs through specialty pet retail channels, direct-to-consumer platforms, and institutional procurement cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pet stain remover market is recovering from a cyclical trough driven by post-pandemic veterinary clinic expansion and tightening hygiene accreditation standards that institutionalize recurring concentrate purchasing.
For Market Incumbents: Harden formulation stability expertise through captive enzymatic chemist hiring and multi-enzyme cocktail shelf-life optimization investments. Secure exclusive distribution agreements with accredited veterinary clinic networks to lock in recurring revenue streams against emerging private-label contract manufacturers. Deepen backward integration into dispensing hardware development to create captive consumption loops that competitors cannot easily replicate. For New Entrants and Emerging Players: Build out white-space presence in Japanese premium household segments, where clinic-grade home formulation demand outpaces certified supply. Target shelter and rescue network cooperative purchasing agreements in the United Kingdom, where fragrance-free bedding formulation specifications are consolidating procurement volume. Pursue direct-to-consumer subscription dispensing hardware bundled with auto-replenishment algorithms to bypass mass-market shelf space barriers. For Investors and Strategic Acquirers: Capital is best deployed toward enzymatic specialists with established EPA Safer Choice and REACH certification infrastructure, where regulatory moats protect pricing power across the analysis window. Acquisition candidates should demonstrate captive biotech R&D partnerships or exclusive veterinary channel agreements that generate predictable concentrate replenishment revenue. Watch for inflection signals in California CARB VOC regulation enforcement cascades, which would accelerate national reformulation requirements and disadvantage solvent-based competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Fermentation | Captive protease supply secures input cost stability against biotech hub concentration risk. |
| Subscription Dispensing Hardware Launch | IoT-enabled reordering devices bind household consumption to proprietary concentrate refills. |
| Dual Certification Investment | Simultaneous EPA Safer Choice and EU Ecolabel pursuit unlocks federal and institutional tender eligibility. |
| Veterinary Clinic Exclusive Distribution | Accredited facility agreements institutionalize recurring concentrate purchases through embedded hygiene protocols. |
| Private-Label Contract Manufacturing | Asset-light leasing arrangements narrow capital barriers for regional enzymatic formulation entrants. |
Research Methodology
Initial hypotheses were tested against primary input from veterinary clinic procurement managers, enzymatic formulation R&D directors, specialty pet retail buyers, and contract manufacturing operations leads, then refined through secondary validation against EPA Safer Choice certification databases, REACH registration filings, customs trade flow records, and institutional tender documentation. Bottom-up volume estimates from segment-level procurement patterns were triangulated against top-down market sizing from production capacity and channel throughput analysis.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by product format, application surface, distribution channel, and customer archetype, with CAGRs derived from elasticity-adjusted growth rate projections and input-output coefficients linking enzyme fermentation capacity to downstream formulation output. Forecast inputs incorporated veterinary clinic accreditation expansion rates, state-level VOC regulatory tightening trajectories, and smart home device penetration curves in premium household segments.
Stress conditions across protease enzyme supply disruption, REACH registration cost inflation, and DIY home remedy substitution intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement continuity and certification timeline stability. Macroeconomic contraction, accelerated state-level VOC regulation, or breakthrough probiotic culture formulation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Scouring Pads Market
Household Items
Pet Fur Remover Market
Household Items
Toilet Cistern Blocks Market
Household Items
Party Supplies Market
Household Items
Dishwasher Tablets Market
Household Items
Robotic Pool Cleaner Market
Household Items
Alarm Clocks Market
Household Items
Latex Mattress Market
Household Items
Germany Digital Showers Market
Household Items
Portable Steam Cleaners Market
Household Items
HEPA Vacuum Cleaners Market
Household Items
Domestic Sauna Heaters Market
Household Items
Hand Wash Station Market
Household Items
Smart Air Purifier Market
Household Items
Stainless Steel Vacuum Flask Market
Household Items
Global Ceramic Tableware Market