
 Kneeboard Market | 2026-2036
Kneeboard Market Size, Share, and Industry Trends Forecast 2026-2036
Kneeboard Market Analytics
ISO 9001 quality management certification is collapsing as a meaningful differentiator among kneeboard manufacturers and instead functions as a baseline market-access threshold. HO Sports leverages in-house compression molding to sustain margin control across its premium product lines. O'Brien anchors its position through deep distribution partnerships with specialty watersports retailers across the southeastern United States. JOBE competes aggressively on price in European markets while maintaining CE marking compliance across its entire towable kneeboard catalog.
A kneeboard is a watersports device ridden in a kneeling position, typically constructed from polyurethane foam cores wrapped in fiberglass or compression-molded PVC shells, designed for towed aquatic recreation behind motorized watercraft. The device features integrated hook straps for front handle retention and contoured deck pads for rider stability during aerial maneuvers. Performance kneeboards command the highest margin pool due to their composite-intensive construction and professional-athlete endorsement dependencies. Towable kneeboards represent the fastest-expanding product type as multi-rider configurations attract family-oriented recreational users. Fiberglass-reinforced construction dominates the material mix among premium and luxury price tiers, while PVC-based manufacturing occupies economy and mid-range segments.
CE marking under EU recreational craft directives governs market access across European member states, while the US Coast Guard collaborates with ASTM International to establish voluntary equipment safety standards for towed watersports devices. The Consumer Product Safety Commission maintains oversight of recall protocols for kneeboard strap and hook failures reported through its incident database. Stakeholders must monitor evolving state-level liability frameworks for rental services and school programs, as these end-user segments increasingly influence bulk procurement specifications and insurance underwriting requirements.
Market Dynamics
Wake sports culture in the United States is compressing replacement cycles as riders upgrade equipment seasonally, while ISO 9001 certification collapses from differentiator to baseline threshold for retail chain access. This structural shift forces manufacturers to compete on manufacturing control and distribution depth rather than quality signaling alone.
Growth Catalysts
- Recreational boating participation:North American lakes and coastal waterways are seeing expanded participation rates, directly expanding the addressable user base for towed watersports equipment.
- CE marking compliance:The EU recreational craft directive enables seamless cross-border distribution across European member states, reducing regulatory friction for compliant manufacturers.
- Compression molding technology:In-house adoption of this manufacturing process allows premium producers to sustain margin control while maintaining consistent shell durability across product lines.
Market Restraints
- Composite material cost volatility:Fiberglass and resin input prices fluctuate with energy markets, compressing margins on performance-grade kneeboards where composite construction is mandatory.
- Specialty retailer concentration:Deep distribution partnerships in the southeastern United States create gatekeeper effects that limit market entry for new competitors.
- Hook strap liability exposure:Consumer Product Safety Commission recall protocols for strap and hook failures create downstream insurance and litigation costs for rental services and school programs.
Strategic Opportunities
- Family-oriented multi-rider configurations:Towable kneeboard designs accommodating multiple simultaneous riders capture underserved recreational segments seeking shared aquatic experiences.
- ASTM International voluntary standards:US Coast Guard collaboration on equipment safety standards creates pathway for compliant manufacturers to differentiate through certified construction.
- State-level liability framework evolution:Emerging regulations governing rental services and school programs in Florida and California create bulk procurement specifications that favor standardized, insurable equipment.
Industry Challenges
- Professional-athlete endorsement dependencies:Performance kneeboard marketing requires sustained athlete relationship investment, creating fixed cost burdens that scale poorly for mid-tier producers.
- ASTM compliance timeline compression:Voluntary standard evolution pressures manufacturers to accelerate redesign cycles while maintaining inventory flow.
- Regional wake sports cluster fragmentation:Demand concentration in Florida and California requires geographically dispersed fulfillment infrastructure to serve replacement cycle timing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kneeboard Market |
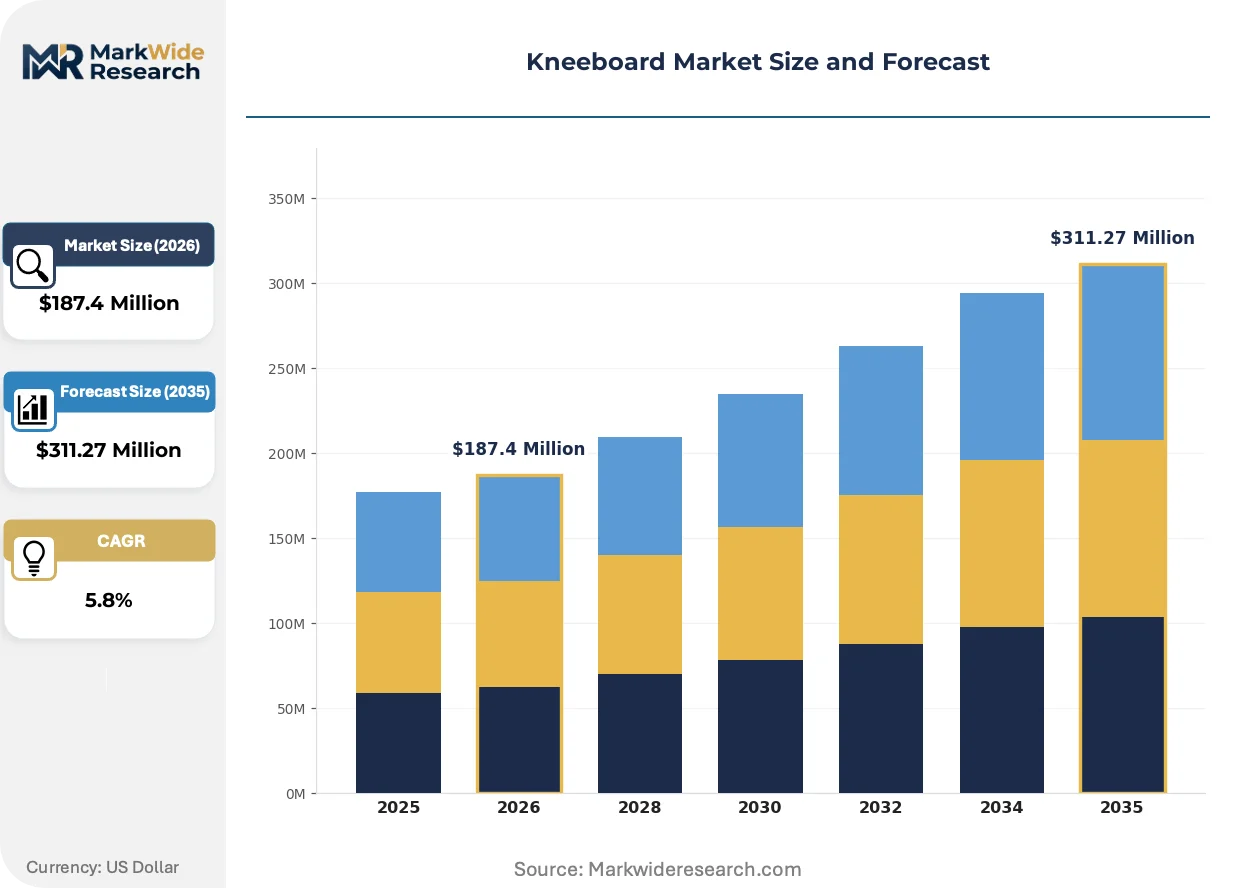
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Kneeboards, Towable Kneeboards, Custom Kneeboards, Performance Kneeboards Material: Foam, Polyurethane, Fiberglass, PVC End User: Recreational Users, Professional Athletes, Schools, Rental Services Price Tier: Economy, Mid-Range, Premium, Luxury |
| Companies Covered | O'Brien, Connelly, HO Sports, JOBE, Hot Shot, RAVE, Liquid Force, Kent Water Sports, ZUP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kneeboard Market Evolving Landscape
Material science and regulatory compliance frameworks are actively restructuring how kneeboard manufacturers compete, with differentiation shifting from quality certification to manufacturing control and distribution architecture.
Compression-molded PVC shell construction is bifurcating the market into performance and economy tiers. Family-oriented recreational users in the southeastern United States are adopting PVC-based boards at accelerating rates for their durability and lower replacement sensitivity. This technology is bifurcating competitive positioning, forcing fiberglass-intensive premium producers to defend margin pools through athlete endorsement and composite performance claims while economy manufacturers capture volume through retail chain partnerships.
ASTM International equipment safety standards are tightening voluntary compliance requirements for towed watersports devices. Manufacturers seeking access to US rental services and school programs must now document structural integrity and strap retention under standardized test protocols. The performance segment is most affected, with composite-intensive construction requiring additional certification investment to satisfy insurance underwriting requirements in Florida and California.
Specialty watersports retailers are consolidating procurement authority across the southeastern United States. Independent dealers are ceding shelf space to chains with centralized buying and exclusive territory arrangements, displacing direct manufacturer relationships. This channel compression is most visible in wake sports clusters where replacement cycle timing demands immediate inventory availability and localized technical support.
Kneeboard Market Segmentation
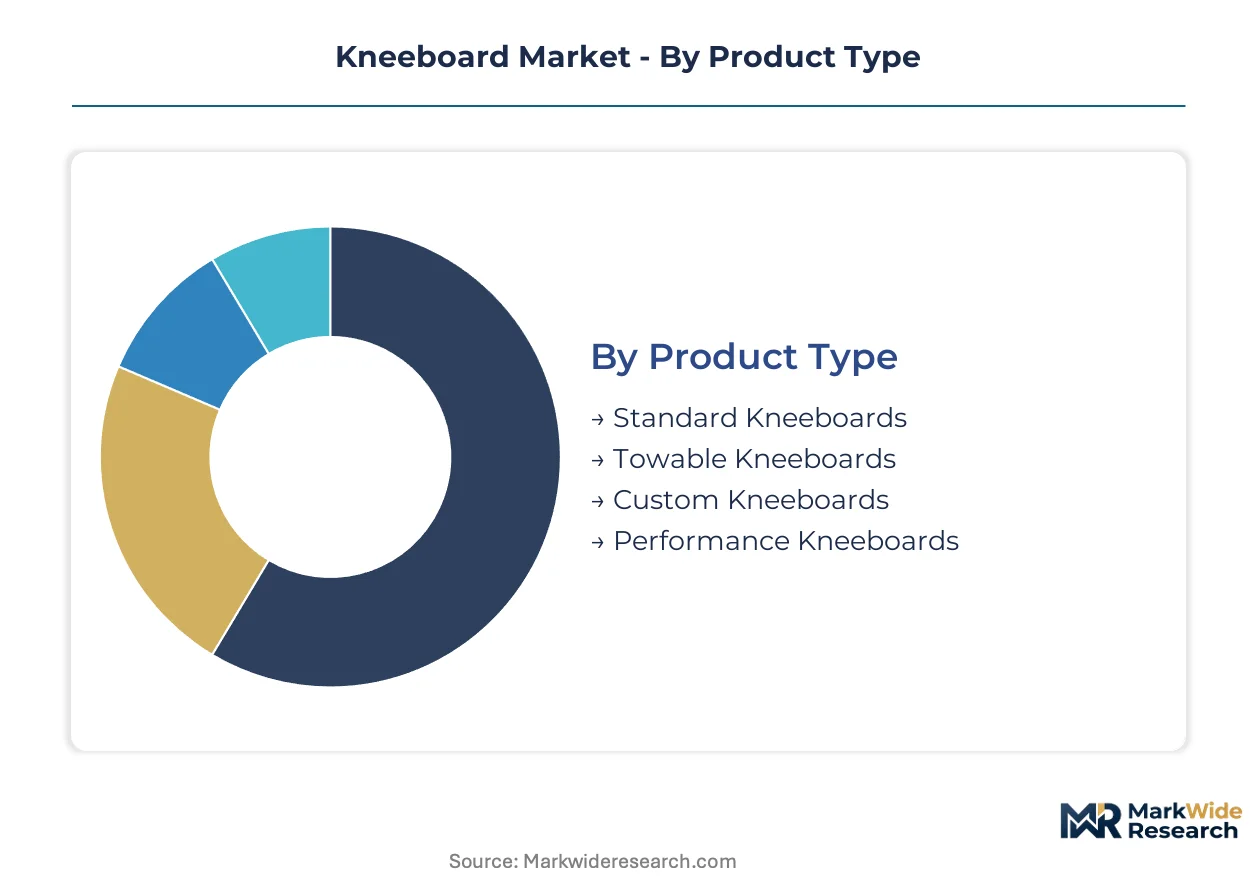
Kneeboard segmentation reveals how manufacturing technology and liability exposure split demand across divergent channel strategies. Manufacturers must align product architecture with end-user risk profiles and replacement cycle timing to capture margin pools effectively.
Product Type:
Channel mix varies sharply by construction complexity, with compression-molded products flowing through mass retail while composite-intensive lines depend on specialty dealer networks for technical support and fitting services.
- Standard Kneeboards:Polyurethane foam cores wrapped in fiberglass or PVC shells serve entry-level recreational users through big-box sporting goods retailers. Demand clusters in Florida and California lake communities where seasonal replacement cycles drive volume.
- Towable Kneeboards:Multi-rider configurations with reinforced tow points and expanded surface areas attract family-oriented users seeking shared aquatic experiences. This segment is gaining share fastest as rental services and school programs in the southeastern United States bulk-procure durable, standardized equipment.
- Custom Kneeboards:Bespoke dimensions and graphic treatments for competitive riders with specific stance preferences and weight requirements.
- Performance Kneeboards:Composite-intensive construction with carbon fiber reinforcement and precision-machined fins for professional athletes and dedicated enthusiasts.
Standard kneeboards dominate installed base. Towable kneeboards are where expansion concentrates.
Material:
Cost tier alignment determines material selection, with premium producers absorbing composite volatility while economy manufacturers exploit PVC scale economies through retail chain partnerships.
- Foam:Expanded polystyrene or polyethylene cores providing buoyancy and impact absorption in entry-level constructions.
- Polyurethane:Denser foam formulations offering improved compression resistance for mid-range products targeting regular recreational use.
- Fiberglass:Woven glass fiber reinforcement with epoxy or polyester resin matrices delivering torsional rigidity and responsive flex patterns. Professional athletes in California wake sports clusters drive specification intensity as equipment performance directly affects competitive outcomes.
- PVC:Compression-molded shells with integrated color and texture layers enabling high-volume production with consistent durability. Rental services across Florida waterways specify PVC construction to minimize damage liability and extend replacement intervals.
Fiberglass commands premium pricing. PVC captures volume expansion.
End User:
Customer type dictates procurement authority concentration, with institutional buyers consolidating specifications while individual consumers fragment across retail channels.
- Recreational Users:Individual consumers purchasing through direct retail or e-commerce for personal watercraft towing.
- Professional Athletes:Sponsored riders and competitive participants receiving equipment through manufacturer endorsement programs.
- Schools:Institutional programs requiring ASTM-compliant construction and documented strap retention testing for insurance underwriting in state-regulated environments.
- Rental Services:Commercial operators in Florida and California specifying standardized, insurable equipment with hook strap redundancy and damage-resistant shell construction to satisfy evolving liability frameworks.
Recreational users represent the largest addressable population. Rental services are where procurement standardization is accelerating.
Price Tier:
Margin structure separates captive manufacturing investments from outsourced assembly, with premium tiers defending position through athlete relationships and in-house molding capabilities.
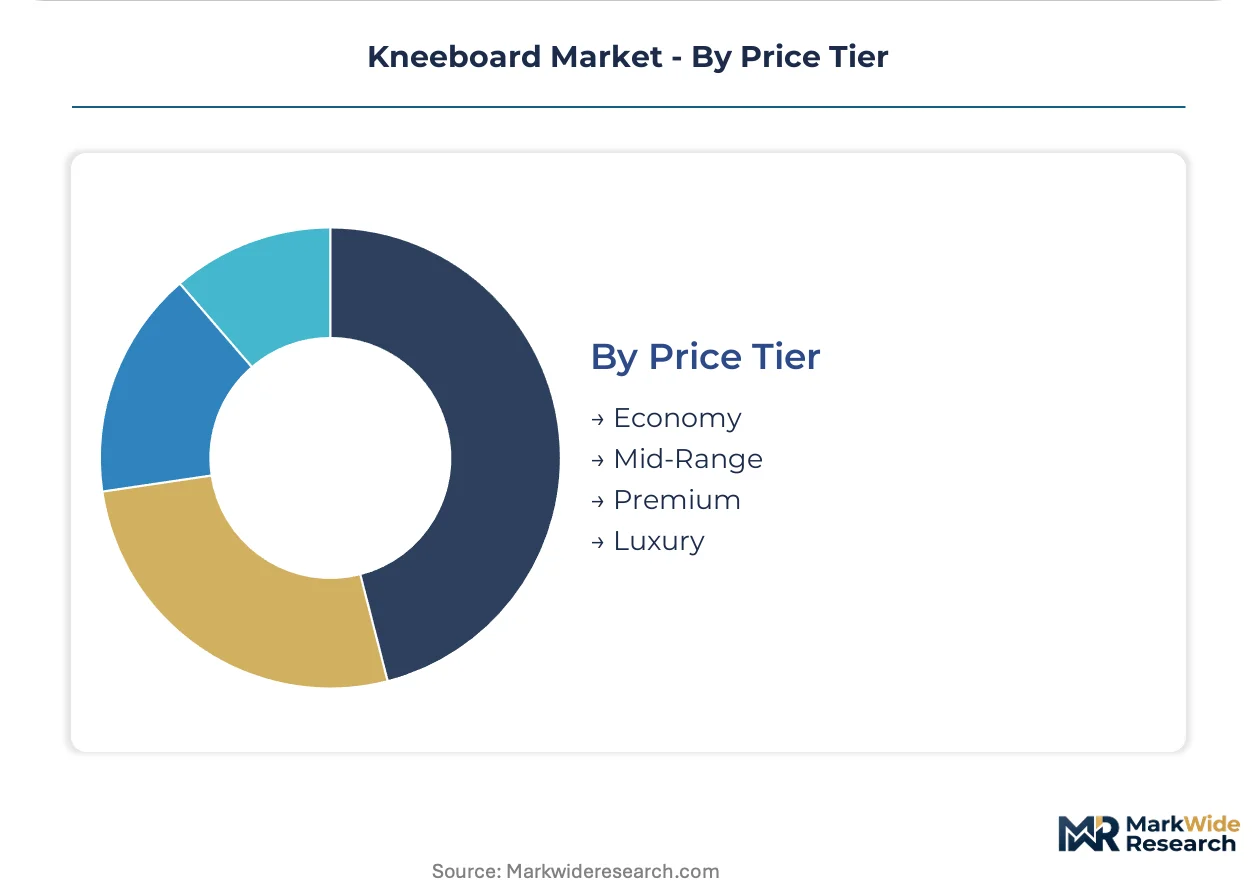
- Economy:PVC-based construction with basic strap systems distributed through mass merchants and online marketplaces.
- Mid-Range:Hybrid foam-fiberglass constructions balancing durability and performance for regular recreational users.
- Premium:Compression-molded precision shells with contoured deck pads and integrated hook systems. Specialty watersports retailers in the southeastern United States concentrate distribution for this tier, requiring ISO 9001 certification as a baseline access condition.
- Luxury:Custom-laminated carbon fiber and Kevlar constructions with athlete-tuned flex profiles and exclusive graphic treatments.
Premium tier generates highest margin per unit. Economy tier drives manufacturing scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recreational boating participation concentrates wake sports demand in freshwater lake communities and coastal waterways. Institutional buyers in rental services and school programs are consolidating procurement authority through state-level liability frameworks. The report identifies five countries where kneeboard consumption patterns diverge by end-user type and regulatory environment.
United States
Wake sports culture in Florida and California drives seasonal replacement cycles among individual consumers. The US Coast Guard collaborates with ASTM International on voluntary equipment safety standards for towed watersports devices. Rental services across southeastern waterways specify standardized equipment to satisfy evolving insurance underwriting requirements.
Germany
Inland lake recreation on the Bavarian lakes and North Sea coast sustains steady equipment turnover among recreational users. CE marking under EU recreational craft directives governs market access and enables seamless cross-border distribution. Specialty watersports retailers in Hamburg and Munich concentrate distribution authority for premium product tiers.
Australia
Coastal waterway access and competitive wake sports participation generate consistent demand for performance-grade equipment. The country's consumer protection regulator maintains oversight of product safety recalls for watersports equipment. Sydney and Gold Coast clusters host concentrated rental service operations influencing bulk procurement specifications.
France
Lake Annecy and Mediterranean coastal zones support recreational boating participation among family-oriented users. CE marking compliance remains mandatory for all recreational craft marketed within EU member states. Watersports schools in Provence-Alpes-Côte d'Azur are standardizing equipment specifications to satisfy regional liability insurance requirements.
Canada
Freshwater lake communities in Ontario and British Columbia sustain seasonal equipment replacement among recreational boaters. Transport Canada collaborates with industry associations on voluntary safety guidelines for towed watersports devices. Rental operators in the Muskoka region are consolidating procurement through centralized buying arrangements.
Kneeboard Market Competitive Landscape
Player mix skews toward specialty watersports manufacturers with captive molding capabilities and deep distribution partnerships. Market structure exhibits tiered concentration, with premium producers defending margin pools through athlete relationships while economy manufacturers capture volume through retail chain access. Two strategic archetypes dominate: compression-molding specialists with in-house production control, and distribution-anchored players with exclusive territory arrangements in high-density wake sports clusters. Competitive moves center on manufacturing technology licensing and geographic expansion into underpenetrated lake communities.
Within the premium-tier vector, HO Sports and O'Brien occupy positions that exemplify divergent channel strategies. HO Sports represents the captive manufacturing archetype with in-house compression molding sustaining margin control. O'Brien anchors the distribution-depth archetype through partnerships with specialty retailers. JOBE sits within the European-focused compliance-driven tier, maintaining CE marking coverage across product lines.
| Leading Market Players |
|---|
| O'Brien |
| Connelly |
| HO Sports |
| JOBE |
| Hot Shot |
| RAVE |
| Liquid Force |
| Kent Water Sports |
| ZUP |
| Others |
Value Network & Pricing Analysis
ISO 9001 certification gates both supply qualification and price differentiation simultaneously, forcing manufacturers to absorb compliance costs upfront while competing for retail chain access on margin-thin terms. This dual gating mechanism compresses mid-tier positioning and rewards players with captive molding capabilities.
Pricing Analysis
Cost-plus contracts with fiberglass and resin indexation dominate procurement between premium manufacturers and composite suppliers. Three-tier pricing structure across premium, standard, and economy levels separates performance kneeboards with athlete endorsements from PVC-based towable units sold through mass merchants. Pricing pressure stems from energy-linked resin volatility, which squeezes margins on fiberglass-intensive construction. Rental services and school programs exhibit highest price sensitivity due to bulk procurement and insurance-driven standardization, while professional athletes show lowest sensitivity given sponsorship offsets.
Supply Chain Analysis
Inventory lead times for compression-molded PVC shells run shorter than composite lamination cycles, favoring just-in-time fulfillment for high-volume retail channels. Manufacturing concentrates in China for molded components, the United States for final assembly and distribution, and Germany for precision-machined fin hardware. Raw material dependencies center on fiberglass roving, polyurethane foam cores, and marine-grade resins. Single-source vulnerability in carbon fiber supply creates concentration risk for luxury tier producers. Distribution runs through specialty watersports retailers in Florida and California wake sports clusters, with mass merchants capturing economy segment volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive dynamics as rental services and school programs consolidate procurement through standardized equipment specifications, creating interoperability requirements that favor manufacturers with documented ASTM compliance and insurable construction.
For Market Incumbents: Secure exclusive territory arrangements with southeastern United States specialty retailers before channel consolidation accelerates. Deepen in-house compression molding capabilities to defend margin pools against PVC-based economy competitors. ASTM International voluntary standard evolution presents both threat and lever—invest in certified construction documentation to satisfy insurance underwriting requirements for rental services and school programs.
For New Entrants and Emerging Players: Anchor in family-oriented multi-rider towable configurations where demand expansion outpaces supply responsiveness from established fiberglass-focused manufacturers. Target underpenetrated lake communities in Canada and inland Germany where wake sports participation is growing but specialty retail density remains low. Pursue direct-to-rental-service go-to-market models bypassing gatekeeper specialty dealers.
For Investors and Strategic Acquirers: State-level liability framework evolution in Florida and California reshapes the acquisition landscape, privileging manufacturers with documented strap retention testing and hook redundancy design. Long-term viability favors players with captive molding technology and established rental service relationships over pure brand licensors. Monitor CPSC recall frequency as inflection indicator for insurance cost trajectories affecting rental service procurement specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Expansion | Enables seamless cross-border distribution across EU member states for compliant manufacturers. |
| Backward Integration into Compression Molding | HO Sports exemplifies margin control through in-house PVC shell production capabilities. |
| Specialty Retailer Partnership Consolidation | O'Brien's southeastern United States distribution depth creates defensible channel positioning. |
| ASTM Compliance Certification Investment | Documented structural integrity testing satisfies insurance underwriting for rental services. |
| Multi-Rider Towable Product Line Extension | Family-oriented configurations capture fastest-expanding recreational user segment. |
Research Methodology
A standing panel of watersports equipment buyers, rental service operators, specialty retailer procurement managers, and marine insurance underwriters provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against US Coast Guard incident databases, ASTM International standard development records, and CPSC recall filings. Bottom-up equipment shipment data triangulated against top-down recreational boating participation surveys.
Consistency checks validated volume and value outputs against external benchmarks including trade association equipment registration data and regional wake sports event participation metrics. Segmentation modeling incorporated product type, material construction, end-user category, and price tier dimensions across the projection horizon. CAGRs derived from trend extrapolation of replacement cycle timing and participation rate trajectories, with fiberglass resin price indices and state-level liability insurance cost trends as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of stable recreational boating participation and continued ASTM standard evolution; material deviation in composite material costs or regulatory enforcement intensity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Athletic Mask Market
Sports Equipment
Sports and Leisure Equipment Market
Sports Equipment
Gear Bicycle Market
Sports Equipment
Swimming Gear Market
Sports Equipment
Turbo Trainer Market
Sports Equipment
Global Golf Accessories Market
Sports Equipment
Balance Bike Market
Sports Equipment
United States Running Gear Market
Sports Equipment
Pickleball Pitching Machine Market
Sports Equipment
Global Badminton Equipment and Facilities Market
Sports Equipment
North America Kickboxing Equipment Market
Sports Equipment
Shooting Ranges Market
Sports Equipment
Global Basketball Shoes Market
Sports Equipment
Fresh Water Rowing Boats Market
Sports Equipment
Global Stand-Up Paddleboard Market
Sports Equipment
Germany Horse Riding Equipment Market