
 Germany Horse Riding Equipment Market | 2026-2036
Germany Horse Riding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Horse Riding Equipment Market Insights
Amateur riders and leisure equestrians is bifurcating demand away from traditional professional buyers across the German market. Waldhausen leverages its vertical manufacturing footprint to control costs across saddle and bridle lines. HKM Sports Equipment anchors its position through broad distribution across specialty stores and equestrian clubs. Stubben differentiates via precision-crafted leather goods that command premium positioning among competitive riders.
Horse riding equipment encompasses saddles, bridles, stirrups, and protective gear engineered from leather, synthetic fabrics, and metal alloys to ensure rider safety and equine performance during training and competition. German manufacturers typically employ hand-stitched leather construction with stainless steel hardware, meeting DIN EN 13138 safety standards for impact resistance and material durability. Saddles and bridles dominate value pools given their high unit prices and replacement cycles tied to horse growth and rider progression. Synthetic fabric segments gain traction as bio-based polyurethane and recycled textile alternatives address sustainability mandates without sacrificing weather resistance. Distribution through specialty stores and equestrian clubs captures the majority of volume, though online retail channels expand fastest among younger amateur riders seeking convenience and price transparency.
KBA oversees transport safety standards for horse trailers and mobile equipment used in competition logistics, while REACH and the EU Green Deal constrain chemical inputs in leather tanning and synthetic manufacturing processes. DIN standards and CE marking requirements shape product certification timelines, particularly for protective headgear and body protectors sold across German retail channels. Stakeholders must monitor evolving material compliance thresholds and channel migration patterns to align inventory positioning with where amateur demand accumulates.
Market Dynamics
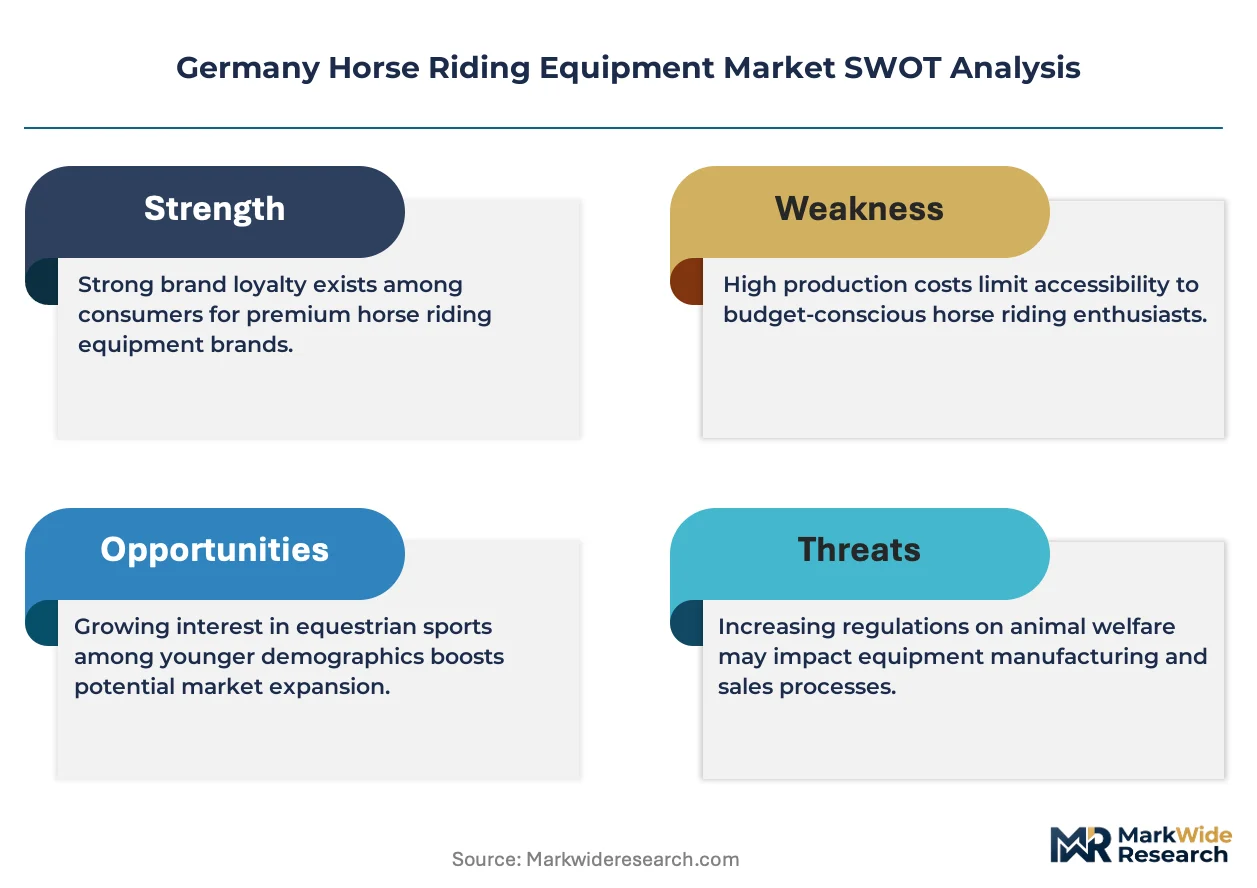
The amateur rider segment is pulling demand away from traditional professional buyers, forcing manufacturers to recalibrate product portfolios and distribution investments toward leisure equestrians who prioritize comfort and accessibility over competitive-grade specifications.
Growth Catalysts
- EU Green Deal mandates:Sustainability frameworks are accelerating bio-based synthetic material adoption and chrome-free leather tanning processes across German manufacturing facilities.
- Bavaria and Baden-Württemberg club density:Concentrated equestrian infrastructure in these southern states anchors equipment procurement volumes through established training networks.
- Synthetic fabric innovation:Bio-based polyurethane and recycled textile alternatives are capturing share from traditional leather without sacrificing weather resistance or durability standards.
Market Restraints
- REACH chemical compliance costs:Leather tanning input restrictions are elevating production expenses and compressing margins for small-to-mid manufacturers.
- Specialty retail concentration:Equipment distribution depends heavily on physical equestrian clubs and specialty stores, limiting direct-to-consumer penetration.
- Metal alloy price volatility:Stainless steel hardware costs fluctuate with global commodity markets, creating margin pressure on saddle and bridle production.
Strategic Opportunities
- Online retail channel expansion:Younger amateur riders are migrating toward digital platforms that offer price transparency and convenience, opening white space beyond traditional club networks.
- Protective gear certification premium:DIN EN 13138 compliance for headgear and body protectors creates differentiation leverage for safety-focused product lines.
- Sustainability-driven club procurement:Equestrian facilities are formalizing green purchasing criteria, rewarding manufacturers with verified bio-based supply chains.
Industry Challenges
- Master craftsperson scarcity:Hand-stitched leather construction requires specialized skills that are aging out of the workforce faster than apprenticeship programs replenish them.
- CE marking timeline compression:Protective equipment certification cycles are lengthening as DIN standards evolve, delaying new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Horse Riding Equipment Market |
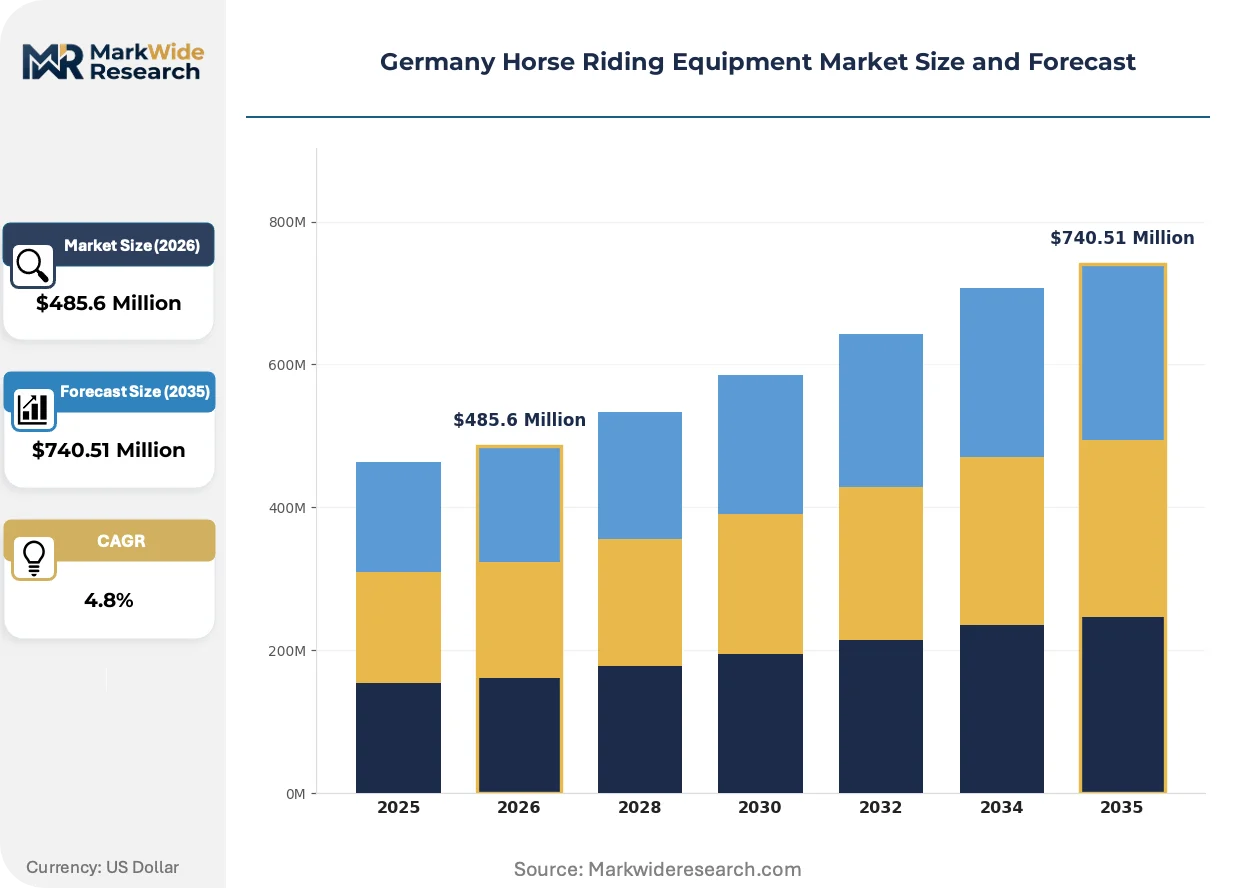
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $740.51 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Saddles, Bridles, Stirrups, Riding Boots End User: Professional Riders, Amateur Riders, Trainers, Event Organizers Material: Leather, Synthetic Fabric, Rubber, Metal Distribution Channel: Online Retail, Specialty Stores, Equestrian Clubs, Trade Shows |
| Companies Covered | Beris, Likit, HKM Sports Equipment, SWING, E·L·T, Waldhausen, GPA, Stubben, Wintec, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Horse Riding Equipment Market Trends and Innovations
Material science breakthroughs and regulatory sustainability mandates are converging to reshape how German manufacturers engineer rider safety and equine performance equipment across all price tiers.
Bio-based synthetic fabrics are bifurcating the traditional leather-dominated market by offering weather-resistant alternatives that satisfy EU Green Deal compliance without sacrificing durability. Amateur riders and leisure equestrians are adopting these materials fastest, drawn by lower maintenance requirements and explicit sustainability credentials. This shift is compressing demand for entry-level leather goods while reinforcing premium positioning for hand-crafted artisanal leather among competitive segments.
REACH chemical restrictions and the EU Green Deal are forcing systematic reformulation of tanning agents and synthetic polymer inputs across German production facilities. Manufacturers must now validate chrome-free processes and bio-based content claims through third-party certification to maintain retail access. Protective gear categories face the steepest compliance burden, as DIN EN 13138 safety standards intersect with evolving material regulations to extend product development cycles.
Digital-native amateur riders are bypassing traditional club-based procurement in favor of direct online channels that provide transparent pricing and peer review validation. Specialty stores and equestrian clubs retain volume dominance among established competitive riders, but younger leisure entrants are consolidating purchases through platforms that aggregate multiple brands. This channel migration is most pronounced in urban centers like Munich and Stuttgart, where time-constrained professionals prioritize convenience over hands-on fitting services.
Germany Horse Riding Equipment Market Segmentation
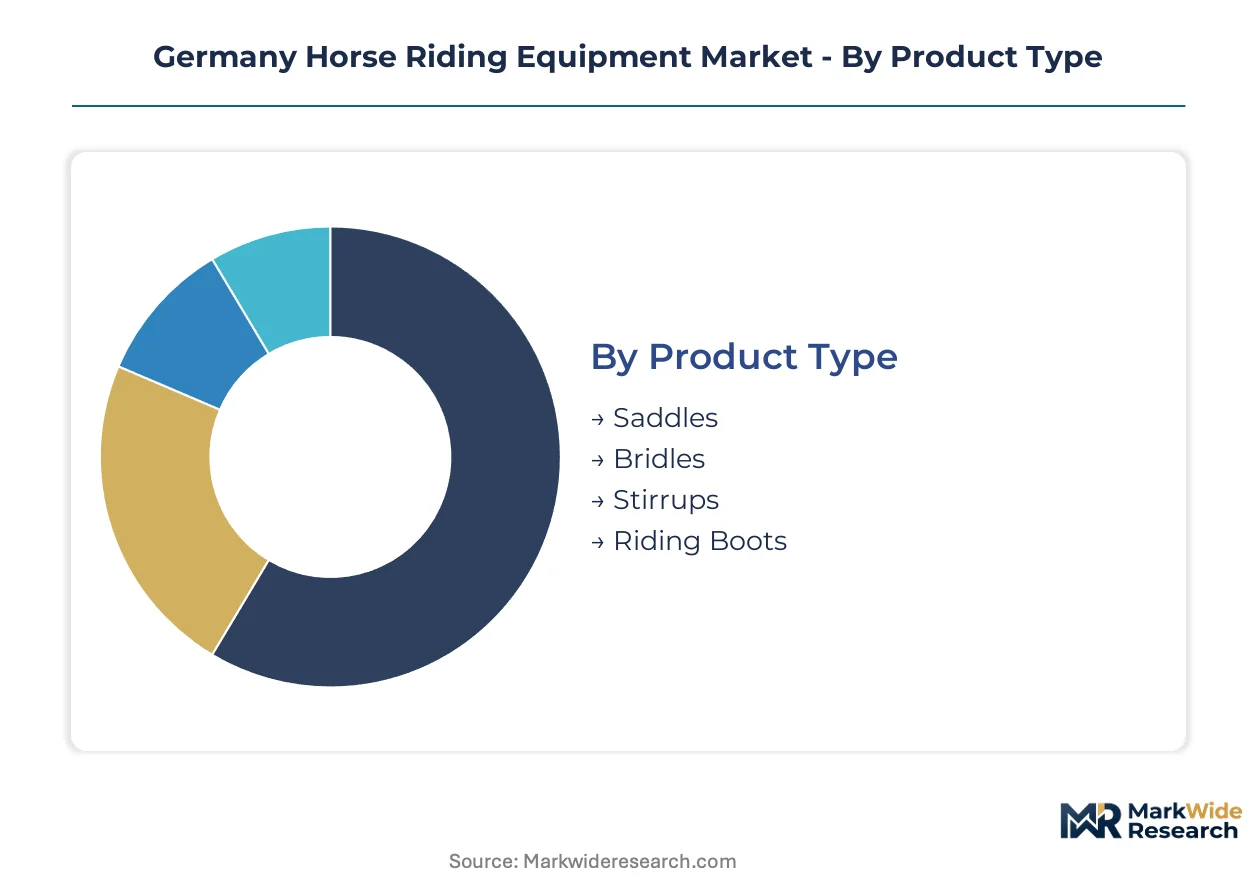
Segmentation in the German horse riding equipment market reveals how channel preferences diverge between competitive and leisure equestrians. Manufacturers must align product portfolios with distinct procurement behaviors across professional training networks and digital-native amateur segments.
Product Type:
Saddles and bridles flow predominantly through specialty stores and equestrian clubs where hands-on fitting services command premium positioning, while stirrups and riding boots capture stronger online retail traction among price-sensitive amateur riders.
- Saddles:Hand-stitched leather construction with stainless steel tree frames dominates competitive segments in Bavaria and Baden-Württemberg. Amateur riders are shifting toward synthetic alternatives with bio-based polyurethane shells that reduce maintenance burdens while meeting DIN EN 13138 safety benchmarks.
- Bridles:Precision-crafted leather goods with anatomical crown and noseband designs anchor premium positioning among Olympic training facilities. Chrome-free tanning processes mandated by REACH compliance are elevating production costs and compressing margins for entry-level leather bridles.
- Stirrups:Stainless steel and aluminum alloy variants with anti-slip tread patterns serve safety-conscious riders across all tiers.
- Riding Boots:Leather and synthetic combinations with reinforced toe caps and moisture-wicking linings address durability demands in wet German climates.
By volume, riding boots lead through broad amateur adoption. By growth pace, synthetic saddles are expanding most quickly as sustainability credentials reshape club procurement criteria.
End User:
Cost tiers stratify sharply across user categories, with professional riders absorbing premium pricing for hand-crafted equipment while amateur segments drive volume through mid-tier synthetic alternatives.
- Professional Riders:Olympic training facilities and competitive circuits in southern Germany demand precision-fitted saddles with custom tree widths and billet configurations. REACH-mandated chrome-free leather tanning and extended CE marking timelines for protective gear are lengthening replacement cycles.
- Amateur Riders:Leisure equestrians in urban centers like Munich and Stuttgart prioritize convenience and price transparency through online retail channels. Bio-based synthetic materials with explicit sustainability certifications are capturing share fastest among this digitally native segment.
- Trainers:Instruction professionals require durable, standardized equipment suitable for multiple horse-horse combinations across lesson programs.
- Event Organizers:Competition logistics demand certified protective gear and transport-compliant trailer equipment under KBA oversight.
By volume, amateur riders dominate procurement. By margin contribution, professional riders sustain premium leather craftsmanship despite shrinking absolute numbers.
Material:
Supply concentration for raw inputs shapes regional manufacturing footprints, with leather tanneries clustering in traditional craft regions and synthetic polymer suppliers anchoring near chemical processing hubs.
- Leather:Full-grain and top-grain hides processed through chrome-free tanning meet EU Green Deal mandates for competitive riders. Master craftsperson scarcity in Baden-Württemberg is constraining hand-stitched production capacity.
- Synthetic Fabric:Bio-based polyurethane and recycled textile alternatives from German chemical manufacturers address sustainability procurement criteria without sacrificing weather resistance. Amateur riders in Bavaria are adopting these materials fastest for everyday training.
- Rubber:Molded grip compounds for stirrup treads and boot soles provide cost-effective traction solutions.
- Metal:Stainless steel hardware for buckles, stirrup irons, and saddle trees faces commodity price volatility affecting bridle and saddle production economics.
By volume, synthetic fabrics are gaining share fastest. By value retention, leather maintains premium positioning despite regulatory compliance burdens.
Distribution Channel:
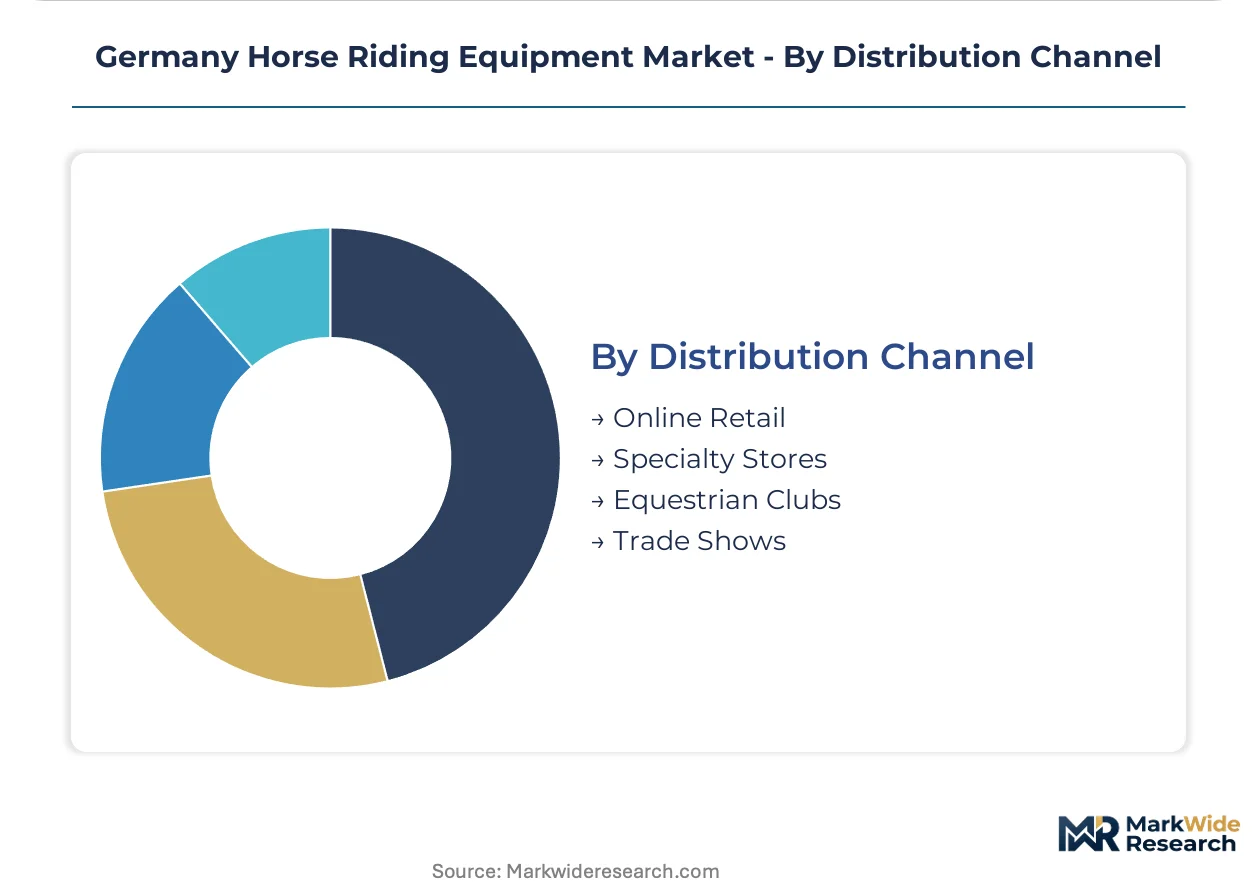
Customer type determines channel affinity, with established competitive riders relying on club-based fitting expertise while younger entrants bypass traditional networks for digital convenience.
- Online Retail:Aggregator platforms with peer review validation and transparent pricing are consolidating amateur rider purchases in urban centers. Younger leisure equestrians prioritize convenience over hands-on saddle fitting services.
- Specialty Stores:Independent retailers with certified fitting staff capture professional rider loyalty through custom saddle adjustment and anatomical assessment services. These outlets dominate high-value transactions in Bavaria's dense equestrian club networks.
- Equestrian Clubs:Training facilities with formal green purchasing criteria are channeling collective procurement toward manufacturers with verified bio-based supply chains.
- Trade Shows:Annual events like Equitana serve new product launches and bulk institutional purchasing for event organizers and large training facilities.
By volume, specialty stores and equestrian clubs retain dominance. By expansion trajectory, online retail channels are climbing the fastest among amateur segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision-crafted leather goods and synthetic riding equipment across European equestrian markets, with Austria, Switzerland, France, and the Netherlands serving as primary destination corridors for premium saddles and protective gear.
Bavaria
Olympic training facilities in Munich and Rosenheim drive concentrated demand for competition-grade saddles with custom tree configurations. KBA transport safety standards govern trailer equipment used in regional competition logistics. The Chiemgau equestrian cluster anchors procurement volumes through dense club networks and year-round training programs.
Baden-Württemberg
Master leather craftsmen in Stuttgart and Karlsruhe supply hand-stitched bridles to professional riders across southern Germany. REACH chemical compliance mandates chrome-free tanning processes that elevate production costs for small workshops. The Black Forest region hosts specialized tanneries serving premium saddle manufacturers with full-grain hide processing.
North Rhine-Westphalia
Amateur rider populations in Cologne and Düsseldorf prioritize convenience-driven online procurement of synthetic training equipment. DIN EN 13138 safety certification requirements shape protective headgear distribution through specialty retail channels. The Münsterland horse-breeding corridor generates replacement demand for everyday riding gear across leisure equestrian segments.
Lower Saxony
Event organizers in Hanover source certified protective equipment for international show jumping competitions under strict material compliance protocols. EU Green Deal sustainability frameworks push procurement officers toward bio-based synthetic alternatives with verified supply chain documentation. The Celle state stud facility influences equipment standards through institutional purchasing power and breeder network recommendations.
Hesse
Urban leisure riders in Frankfurt am Main accelerate digital channel adoption for price-transparent equipment comparison and peer-reviewed product selection. KBA oversight extends to mobile stable units and competition transport vehicles operating across the Rhine-Main metropolitan area. The Taunus mountain riding trails sustain steady equipment wear-and-replacement cycles among weekend recreational users.
Germany Horse Riding Equipment Market Competitive Landscape
Player mix skews toward vertically integrated leather specialists and synthetic fabric innovators competing across distinct price-performance tiers. Market structure remains moderately fragmented, with no single entity commanding dominant share across all equipment categories. Three strategic archetypes define competitive positioning: heritage leather craftsmen with multi-generational craft traditions, synthetic material pioneers leveraging German chemical engineering capabilities, and broad-line distributors optimizing logistics across club networks. Consolidation pressure manifests through selective acquisition of master tanneries and strategic partnerships with bio-based polymer suppliers.
Within the heritage craftsmanship tier, Waldhausen and Stubben occupy positions as representatives of precision leather construction traditions. HKM Sports Equipment exemplifies the distribution-optimized archetype with broad specialty store penetration. These three German entities anchor competitive dynamics through divergent strategic postures—vertical manufacturing control, artisanal premium positioning, and channel breadth respectively—while Wintec and GPA represent synthetic innovation vectors that challenge leather dominance among amateur segments.
| Leading Market Players |
|---|
| Beris |
| Likit |
| HKM Sports Equipment |
| SWING |
| E·L·T |
| Waldhausen |
| GPA |
| Stubben |
| Wintec |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Baden-Württemberg leather workshops shapes both supply concentration and price floors, as master craftsperson scarcity limits hand-stitched output and elevates artisanal premiums. This constraint ripples through Bavarian club procurement networks, where synthetic alternatives gain ground on price accessibility while chrome-free compliance costs compress margins across tanning operations.
Pricing Analysis
Current-generation bio-based synthetic saddles command mid-tier positioning against prior-generation petroleum-based alternatives and next-generation smart-fitted designs still in pilot. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and customization depth. Pricing pressure stems from REACH-mandated chrome-free tanning elevating leather production costs. Amateur riders exhibit highest price sensitivity through online aggregator platforms, while Olympic training facilities absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Just-in-time inventory strategies dominate synthetic fabric procurement from German chemical manufacturers, while strategic stockpiling persists for full-grain hides sourced through Italian and Spanish tanneries. Supply concentration rests on Baden-Württemberg craft workshops, Bavarian polymer processors, and Austrian hardware forgers. Raw material dependencies span chrome-free tanning agents, bio-based polyurethane feedstocks, and stainless steel alloys. Single-source vulnerability concentrates in master craftsperson networks aging out faster than apprenticeship replenishment. Distribution runs through specialty stores and equestrian clubs, with online retail climbing fastest among urban amateur segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The narrowing pipeline of master leather craftsmen capable of hand-stitched construction creates a structural bottleneck that rewards early movers securing artisanal capacity. This scarcity dynamic amplifies acquisition premiums for workshops with verified chrome-free processes and DIN EN 13138 certification histories.
For Market Incumbents: Secure captive supply of chrome-free tanned hides through backward integration into Baden-Württemberg tannery networks. Acquire distressed mid-tier competitors to consolidate fitting-service capacity in Bavarian club corridors before synthetic alternatives erode leather share further. For New Entrants and Emerging Players: Lead with sustainability-certified synthetic saddles targeting Munich and Stuttgart amateur riders through direct-to-consumer platforms with peer-review validation. Exploit white space in urban convenience-driven procurement where established players maintain club-centric distribution. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated manufacturers with in-house tanning and fitting-service networks that lock in club procurement contracts. Long-term viability favors entities with bio-based material validation and KBA transport-equipment certification spanning the analysis window. Acquisition targets should display verified chrome-free supply chains and DIN compliance histories. The signal to watch is synthetic fabric adoption rates crossing threshold penetration in southern German club procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Chrome-Free Tanning Certification | REACH compliance unlocks retail access across EU Green Deal procurement frameworks. |
| Master Craftsman Apprenticeship Programs | Pipeline replenishment secures hand-stitched capacity against demographic attrition. |
| Bio-Based Polyurethane Scale-Up | Domestic chemical partnerships reduce import dependency for synthetic saddle shells. |
| Online Platform Integration | Aggregator partnerships capture Munich and Stuttgart amateur rider convenience demand. |
| DIN EN 13138 Safety Investment | Certified protective gear commands premium positioning in competitive rider segments. |
Research Methodology
A standing panel of saddle-fitting specialists, equestrian club procurement officers, leather tannery operations managers, and KBA compliance auditors provided ongoing calibration across primary fieldwork. Secondary validation drew from DIN standards documentation, REACH substance restriction databases, EU Green Deal implementation reports, and German equestrian federation membership records. Bottom-up equipment shipment data triangulated against top-down consumer expenditure surveys across Bavaria, Baden-Württemberg, and North Rhine-Westphalia.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled encompass product type, material composition, end-user category, and distribution channel, with regional club density and urbanization patterns as overlay variables. CAGRs derived from fitted growth curves applied to equipment replacement cycles and rider demographic shifts. Industry-specific forecast inputs incorporated synthetic material adoption curves and chrome-free tanning capacity expansion timelines.
Underlying assumptions cover stable REACH enforcement intensity and sustained EU Green Deal procurement incentives, with deviation risk concentrated in master craftsperson attrition rates and synthetic fabric performance validation. Forecasts reflect these documented conditions. Revision becomes warranted when bio-based material cost parity crosses threshold competitiveness against leather alternatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Concussion Helmets Market
Sports Equipment
Global Cycling Power Meters Market
Sports Equipment
Basketball Shooting Machine Market
Sports Equipment
Stadium Seating Market
Sports Equipment
Kiteboarding Equipment Market
Sports Equipment
Portable Basketball Hoops Market
Sports Equipment
Bicycle Shoe Market
Sports Equipment
Running Gear Market
Sports Equipment
Mountain Bicycle Cassette Market
Sports Equipment
Mixed Martial Arts Equipment Market
Sports Equipment
Global Sports Sunglasses Market
Sports Equipment
Tennis Ball Machine Market
Sports Equipment
Sports and Leisure Equipment Market
Sports Equipment
Boxing Gear Market
Sports Equipment
GCC Running Gear Market
Sports Equipment
Hydration Belt Market