
 Global Climbing Shoes Market | 2026-2036
Global Climbing Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Climbing Shoes Market Analysis
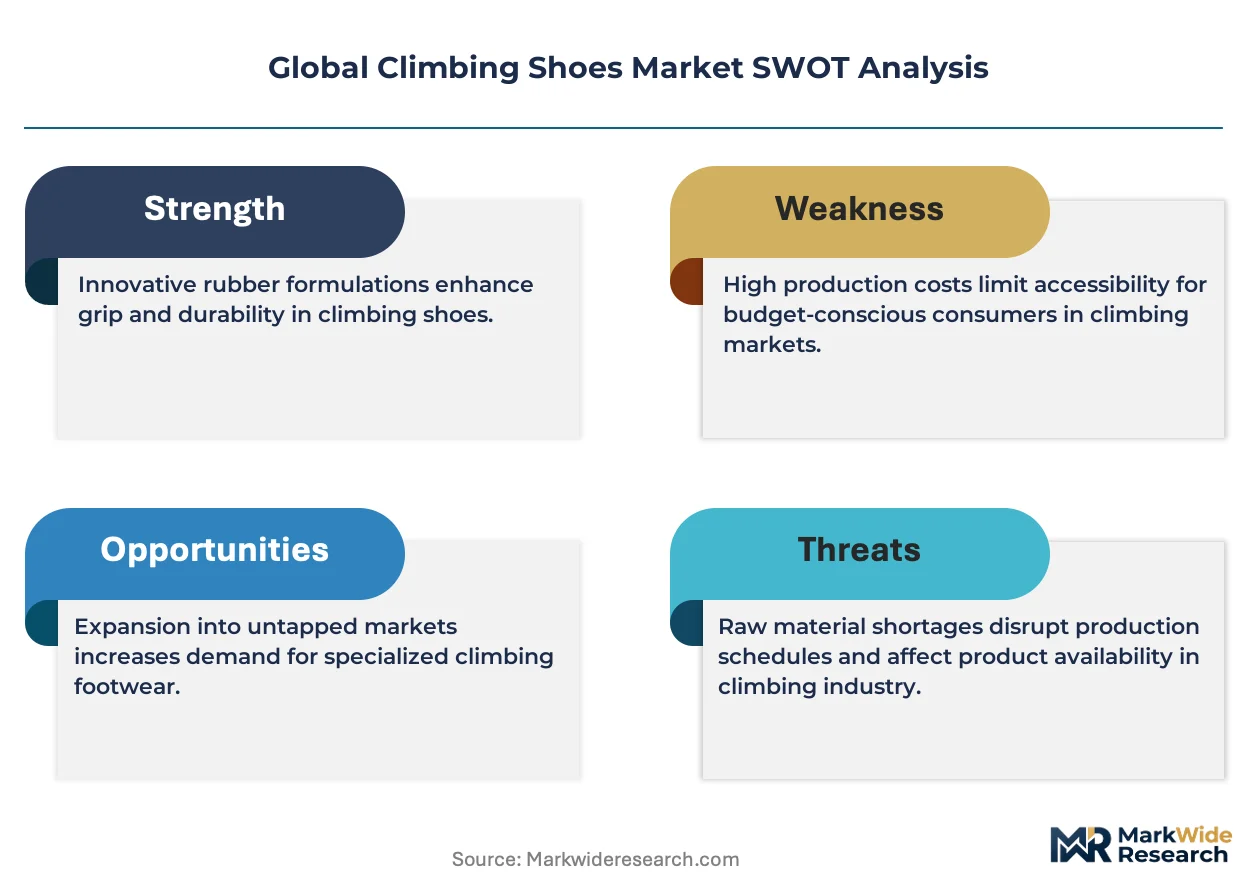
Modular sole replacement systems and resole-ready constructions are repositioning buyer choice away from disposable footwear cycles. La Sportiva leverages its European manufacturing base to sustain premium positioning in technical alpine categories. Scarpa competes through specialized last shapes that dominate European sport climbing segments. Evolv anchors its presence in North American indoor climbing channels through controlled gym partnerships and custom colorway programs.
Global climbing shoes are close-fitting footwear engineered with downturned profiles, specialized rubber rand compounds typically measuring 3-5 mm thickness, and pre-tensioned heel cups designed to maximize friction on rock surfaces and artificial holds. Their primary commercial purpose centers on transferring climber force precisely to footholds while protecting the foot during dynamic movements. Sport climbing and bouldering categories lead volume due to gym proliferation and competition format standardization, while lace-up closure types retain margin concentration among trad climbers prioritizing adjustable fit across multi-pitch routes. Synthetic materials are displacing leather in entry-level segments where cost consistency and vegan positioning drive purchasing decisions.
REACH in Europe restricts certain chemical additives in rubber formulations, pushing manufacturers toward compliant compound reformulations that alter grip durability profiles. The US Consumer Product Safety Commission monitors children's climbing footwear for choking hazards in closure hardware, shaping design constraints for junior product lines. ISO standards for footwear testing provide baseline benchmarks that influence warranty terms and retail buyer specifications. Stakeholders must monitor how resole infrastructure scaling affects replacement cycle economics and brand loyalty retention.
Market Dynamics
Indoor climbing gym proliferation is restructuring footwear procurement patterns, with facility operators negotiating direct supply agreements that bypass traditional retail markup structures and compress replacement cycles for entry-level inventory.
Growth Catalysts
- REACH rubber compound reformulation:European chemical compliance mandates are accelerating investment in compliant grip formulations, opening premium positioning for manufacturers with in-house polymer labs.
- Gym partnership channel development:North American climbing facilities are consolidating footwear procurement through exclusive vendor programs that lock in volume commitments and custom colorway production.
- Synthetic upper displacement:Vegan material adoption is expanding addressable demand among younger demographics and institutional buyers with sustainability procurement policies.
Market Restraints
- Natural rubber price volatility:Plantation supply disruptions in Southeast Asia are squeezing margin structures for manufacturers dependent on imported crepe and sole-grade compounds.
- Last development tooling costs:Foot mold precision requirements for anatomical fit specialization demand six-figure capital outlays that deter mid-tier entrants from technical category expansion.
- Resole infrastructure concentration:Authorized repair networks cluster in urban climbing hubs, leaving rural and secondary market users with replacement-only options that accelerate brand switching.
Strategic Opportunities
- Indian metropolitan gym rollout:Mumbai, Bangalore, and Delhi climbing facility construction is outpacing established footwear distribution, creating first-mover positioning for direct-to-gym supply models.
- Junior sizing standardization:US Consumer Product Safety Commission closure hardware guidelines are prompting dedicated children's line development with certified choke-resistant designs.
- Rental hygiene technology convergence:UV-C sterilization integration with automated dispensing systems is enabling premium rental tier creation in high-traffic Japanese and South Korean facilities.
Industry Challenges
- Master lastmaker talent scarcity:Hand-carved wooden form expertise concentrates among aging European and Japanese craftsmen, constraining new anatomical fit development timelines.
- Multi-standard certification complexity:Simultaneous ISO footwear testing, CE marking, and country-specific junior safety approvals extend product launch windows by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Climbing Shoes Market |
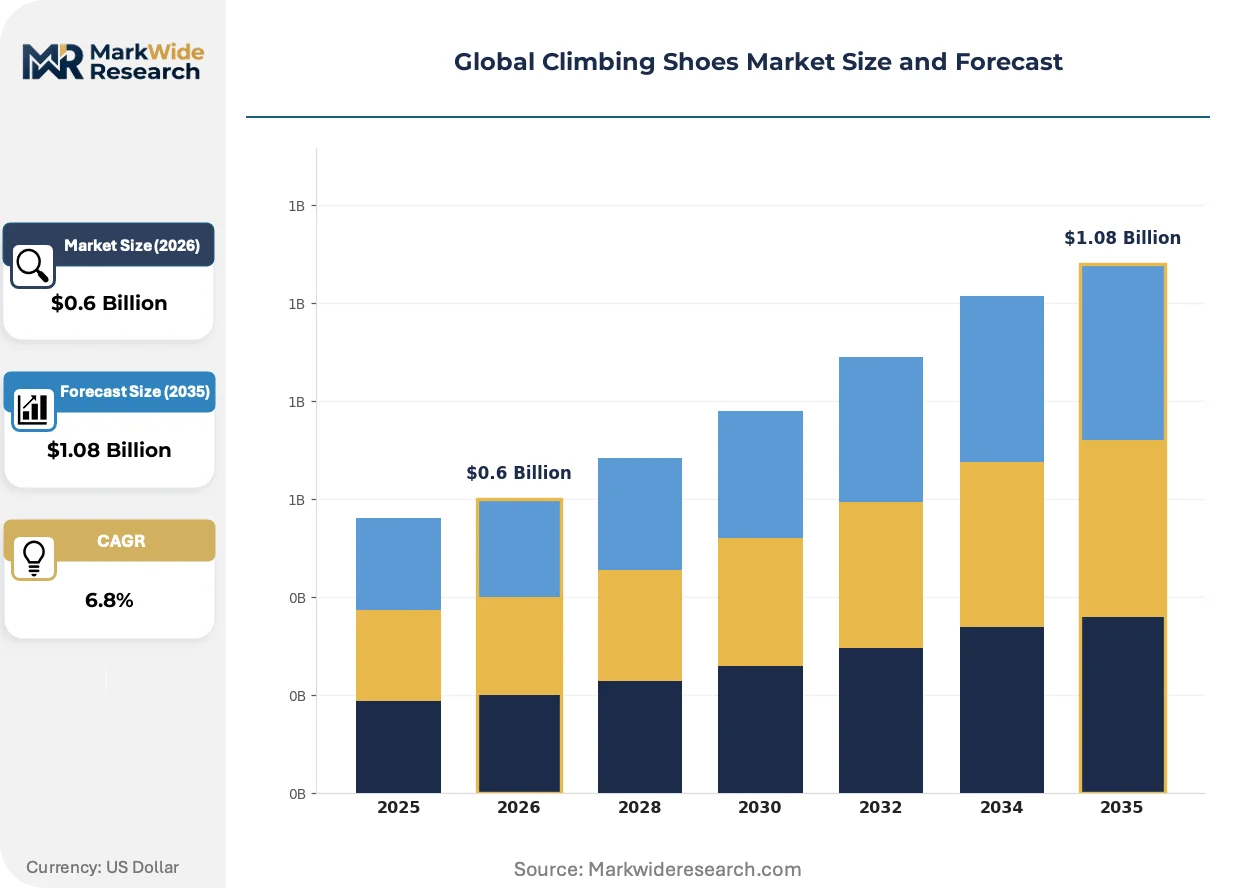
| Market Size in 2026 | $0.6 Billion |
| Market Size in 2035 | $1.08 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sport Climbing, Trad Climbing, Bouldering, Indoor Climbing Closure Type: Velcro, Lace-Up, Slip-On, Hybrid End User: Beginners, Intermediate Climbers, Professional Climbers, Casual Enthusiasts Material: Leather, Synthetic, Rubber, Canvas |
| Companies Covered | Black Diamond Equipment, Tenaya, La Sportiva, Butora, Mad Rock, Scarpa, Evolv, Boreal, Adidas (Five Ten), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Climbing Shoes Market Emerging Trajectories
Material science advances and regulatory chemistry constraints are converging to reshape rubber formulation priorities, while distribution channel control shifts toward facility-level procurement consolidation.
Micro-adjustment closure systems incorporating BOA dial mechanisms and proprietary cable routing are decentralizing fit customization away from traditional lace-up expertise. Intermediate climbers in United States and German gym networks are adopting these systems at rates exceeding velcro or conventional closure categories. The technology is decentralizing aftermarket resole economics by extending upper lifespan and reducing fit-related replacement triggers.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons in rubber formulations are forcing compound reformulations that trade absolute grip coefficient for durability longevity. Italian and Spanish manufacturers with captive polymer blending facilities are absorbing compliance costs more efficiently than outsourced producers. Sport climbing categories face the steepest reformulation timelines due to friction-critical performance requirements.
Subscription-based footwear access models are emerging as facility-operated alternatives to outright purchase in high-churn beginner segments. North American climbing gym chains are piloting monthly fee structures that include unlimited shoe rotation and maintenance, displacing traditional retail relationships for first-time buyers. This pattern concentrates in metropolitan markets with transient professional populations and limited storage space.
Global Climbing Shoes Market Segmentation
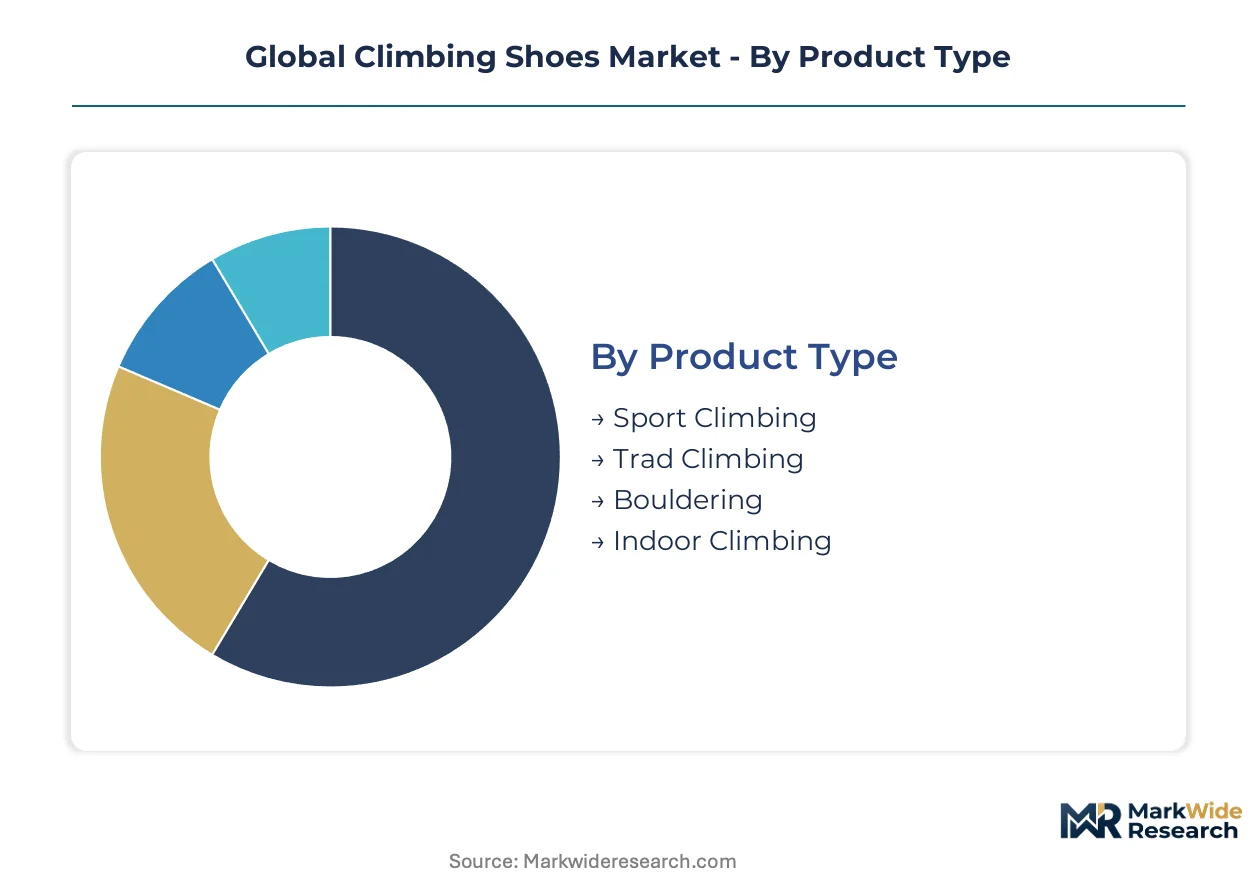
Climbing shoe segmentation reflects divergent capital requirements across manufacturing tiers. Rubber compound laboratories and anatomical last development impose distinct upfront burdens that reshape competitive entry barriers by category.
Product Type:
Sport climbing and bouldering categories demand the heaviest capital allocation for polymer R&D and downturned profile tooling.
- Sport Climbing:Aggressive downturned profiles with 3-4mm rubber rands require precision-molded last forms and pre-tensioned heel cup engineering. German and Italian gym networks drive procurement volume as competition formats standardize on specific hold types.
- Bouldering:Maximum friction compounds with reinforced toe patches for toe-hooking movements. North American indoor facilities prioritize bulk acquisition of entry-level variants for rental programs and beginner instruction.
- Trad Climbing:Flatter lasts with stiffer midsoles for all-day comfort on multi-pitch routes.
- Indoor Climbing:Synthetic uppers with enhanced breathability for climate-controlled environments.
Sport climbing absorbs the bulk of installed capacity; bouldering is expanding most quickly.
Closure Type:
Mechanism complexity determines tooling amortization schedules and aftermarket service infrastructure.
- Lace-Up:Micro-adjustable fit systems utilizing 6-8 independent eyelets for customizable tension across the forefoot. Trad climbers in Yosemite and Joshua Tree corridors sustain demand for replaceable lace configurations.
- Velcro:Triple-strap configurations with hook-and-loop fasteners enabling rapid on-off transitions. Japanese gym operators specify antimicrobial strap linings for high-rotation rental fleets.
- Slip-On:Elastic gusset construction with tensioned heel retention.
- Hybrid:BOA dial systems with proprietary cable routing for distributed pressure mapping.
Velcro commands the highest production throughput; hybrid systems are climbing the fastest among intermediate demographics.
End User:
Customer lifetime value calculations favor segments with predictable replacement cadences and brand loyalty retention.
- Beginners:Neutral lasts with thicker rubber for durability over sensitivity. Mumbai and Bangalore climbing gyms are negotiating direct supply agreements that bypass retail markup structures.
- Intermediate Climbers:Moderate downturn with asymmetric toe boxes marking the transition to technical footwear. South Korean facilities pilot subscription-based access models with UV-C sterilization integration.
- Professional Climbers:Custom-molded prototypes with athlete-specific modifications.
- Casual Enthusiasts:Crossover designs compatible with approach hiking.
Beginners represent the largest addressable base; intermediate climbers show the steepest expansion trajectory.
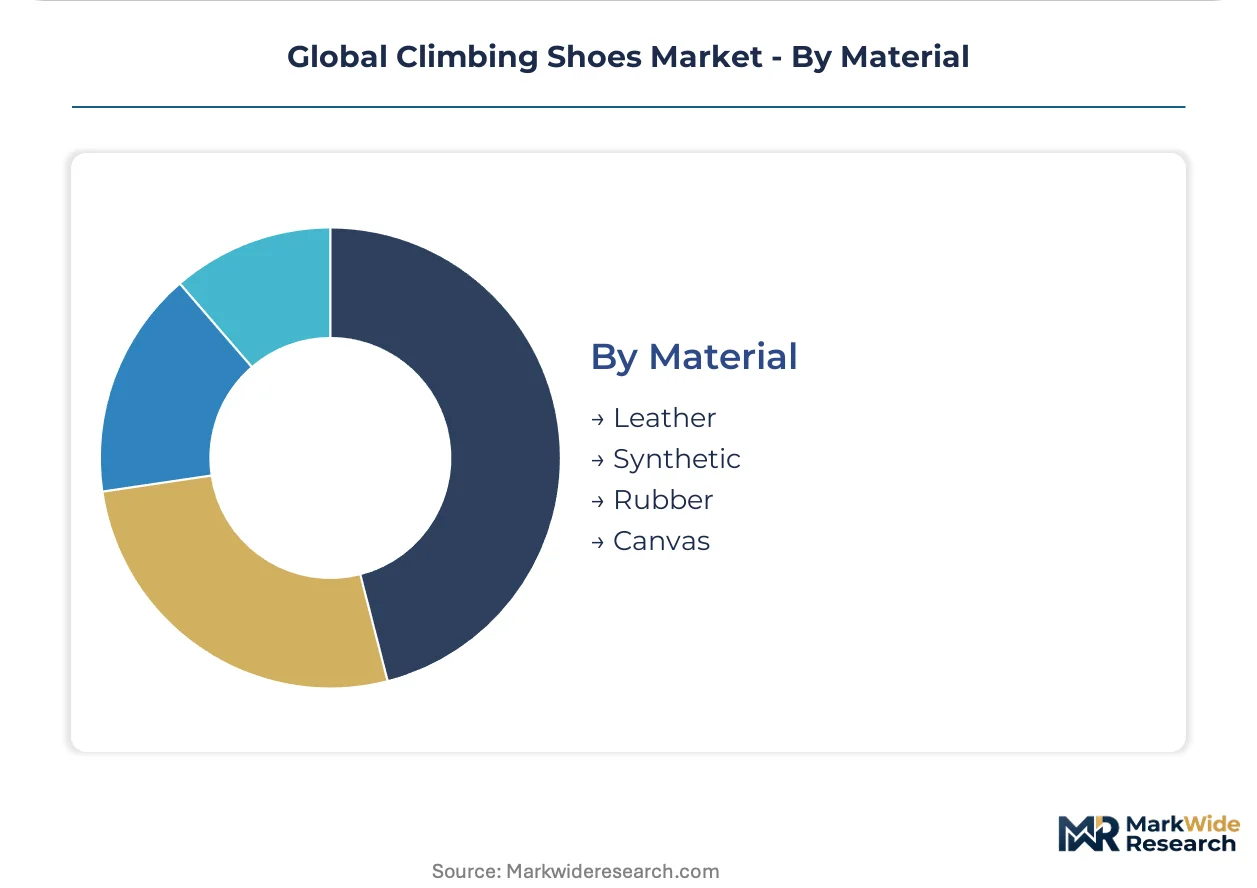
Material:
Raw material sourcing exposure and compliance certification burdens differentiate margin structures across substrate categories.
- Synthetic:Microfiber uppers with polyurethane coatings enabling consistent dye lots and vegan positioning. REACH Annex XVII compliance is accelerating displacement of leather in European entry-level segments.
- Rubber:Sole-grade compounds with Shore A hardness ratings of 70-80 for optimal friction coefficients. Southeast Asian plantation supply disruptions are squeezing crepe-dependent manufacturers.
- Leather:Full-grain cowhide with natural stretch characteristics for personalized fit break-in.
- Canvas:Woven cotton uppers with limited stretch for casual approach applications.
Synthetic materials absorb the bulk of installed capacity; rubber formulation is gaining share fastest due to performance-critical specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian and Spanish manufacturers dominate premium rubber formulation while Asian facilities handle volume production for entry-level segments. Consumption concentrates in North American and European gym markets where facility partnerships reshape procurement economics.
United States
Climbing gym membership growth in Denver, Salt Lake City, and New York Metro outpaces traditional recreational categories. The US Consumer Product Safety Commission monitors children's footwear for closure hardware choking hazards, constraining junior line design. Pacific Northwest and Colorado Front Range clusters host the densest concentrations of specialized resole infrastructure.
Germany
Frankfurt and Munich gym networks standardize competition formats that drive specific hold-type footwear procurement. ECHA REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons force rubber compound reformulations trading grip for durability. Bavarian manufacturing clusters leverage captive polymer labs to absorb compliance costs more efficiently than outsourced producers.
Japan
Tokyo and Osaka facilities pilot UV-C sterilization integration with automated rental dispensing systems. METI industrial standards influence footwear testing protocols that shape warranty terms across Asian export markets. Kansai region manufacturers specialize in antimicrobial strap linings for high-rotation gym fleets.
South Korea
Seoul climbing chains test subscription-based footwear access models with monthly rotation and maintenance inclusion. MFDS consumer safety guidelines parallel US CPSC closure hardware standards for junior segments. Busan-Ulsan manufacturing corridors supply synthetic upper materials to regional footwear assemblers.
India
Mumbai, Bangalore, and Delhi metropolitan gym construction outpaces established footwear distribution networks. BIS textile and rubber standards create baseline certification requirements for imported climbing footwear. Maharashtra and Karnataka climbing facilities negotiate direct supply agreements that bypass traditional retail markup structures.
Global Climbing Shoes Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Italian and Spanish heritage manufacturers anchor premium technical categories through captive rubber formulation capabilities. Korean and Chinese fabricators concentrate on volume production for entry-level gym procurement. Strategic moves center on exclusive facility partnership programs and resole-ready construction patents that extend product lifecycles.
Within the European heritage tier, La Sportiva and Scarpa exemplify manufacturing-base differentiation strategies. La Sportiva leverages its Italian production footprint for alpine technical positioning. Scarpa competes through specialized last development that dominates European sport climbing segments. Among North American specialists, Evolv anchors presence through controlled gym partnerships and custom colorway programs. Black Diamond Equipment represents diversified outdoor conglomerate positioning that spans multiple vertical categories beyond footwear.
| Leading Market Players |
|---|
| Black Diamond Equipment |
| Tenaya |
| La Sportiva |
| Butora |
| Mad Rock |
| Scarpa |
| Evolv |
| Boreal |
| Adidas (Five Ten) |
| Others |
Supply Flow & Price Mechanics
REACH Annex XVII compliance gates both qualified rubber compound supply and premium-tier pricing access, as European chemical restrictions disqualify non-compliant formulations from high-margin distribution channels while certified manufacturers capture pricing power through scarcity positioning.
Pricing Analysis
Cost-down pressure on entry-level tiers accelerates because synthetic upper displacement and gym-direct procurement compress traditional retail markups. Three-tier pricing structure across premium, standard, and economy levels stratifies by rubber formulation grade and resole-ready construction certification. Price differentiation hinges on REACH-compliant compound sourcing and captive polymer lab ownership. Beginner segments exhibit highest price sensitivity; professional climbers with custom-molded requirements show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Southeast Asian natural rubber plantations, where crepe-grade supply disruptions ripple through sole compound availability. Manufacturing concentrates in Italy, Spain, and China, with Bavarian and Korean facilities anchoring premium formulation and volume assembly respectively. Raw material dependencies encompass Malaysian plantation rubber, Italian microfiber synthetics, and Japanese antimicrobial strap components. Tariff exposure on Chinese-assembled footwear threatens margin structures. Distribution runs through facility-direct partnerships bypassing traditional retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around manufacturers with captive polymer laboratories, as REACH compliance costs and last-development tooling investments force weaker capitalized players toward exit or acquisition.
For Market Incumbents: Anchor defensive positioning through exclusive gym partnership lock-ins and resole-ready construction patent portfolios. Deepen backward integration into rubber formulation to absorb ECHA compliance costs more efficiently than outsourced competitors. Prioritize lastmaker talent retention as aging European craftsmen constrain new anatomical development timelines.
For New Entrants and Emerging Players: BOA dial micro-adjustment systems offer technology-first wedge into intermediate climber segments underserved by traditional lace-up specialists. Target Indian metropolitan gym construction in Mumbai and Bangalore where distribution infrastructure lags facility rollout. Pursue direct-to-gym supply models bypassing established retail channels.
For Investors and Strategic Acquirers: Authorized resole network density is the leading indicator that regional brand loyalty has achieved defendable scale. Frame long-term viability around subscription-based access model pilots in South Korean and North American facilities. Target acquisition profiles toward mid-tier specialists with compliant rubber formulations and established gym relationships.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Polymer Laboratory Investment | REACH Annex XVII compliance costs concentrate advantage among in-house formulation owners. |
| Exclusive Gym Partnership Programs | Direct supply agreements with Denver and Salt Lake City facilities displace retail intermediaries. |
| Resole-Ready Construction Patenting | Modular sole replacement systems extend product lifecycles and reduce brand switching. |
| Lastmaker Talent Acquisition | Hand-carved wooden form expertise scarcity in Japan and Italy constrains competitor fit development. |
| Subscription Access Model Piloting | Monthly fee structures with UV-C sterilization integration capture transient metropolitan climbers. |
Methodological Framework
Multi-period observation of gym membership growth rates, rubber compound pricing indices, and REACH enforcement patterns anchored the trend analysis, supplemented by interviews with climbing gym operators, footwear procurement managers at facility chains, rubber compound laboratory directors, and specialized resole service technicians. Secondary validation drew from ECHA regulatory filings, US Consumer Product Safety Commission guidance documents, customs trade data on rubber imports, and ISO footwear testing standard revisions. Bottom-up facility procurement volume estimates and top-down manufacturer capacity assessments were triangulated.
Segment-weighting across product type, closure mechanism, end-user skill tier, and material substrate shaped the analytical framework. CAGRs were derived from facility expansion pipelines, replacement cycle compression rates, and synthetic material adoption curves. Industry-specific inputs included climbing competition format standardization timelines and junior safety certification approval durations.
Several conditions sit outside the modeled scope, including abrupt plantation supply disruptions, trade policy shifts affecting Chinese assembly, and breakthrough biodegradable rubber formulations. Forecasts reflect documented assumptions on gym construction cadence and regulatory enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
United States and Europe Horse Racing Market
Outdoor and Adventure Activities
Leisure Centers Market
Outdoor and Adventure Activities
Power Sports Market
Outdoor and Adventure Activities
Ski Vacation Market
Outdoor and Adventure Activities
Global Climbing Holds Market
Outdoor and Adventure Activities
Climbing Harness Market
Outdoor and Adventure Activities
Hydration Packs Market
Outdoor and Adventure Activities
Recreational Sports Activities Market
Outdoor and Adventure Activities
North America Personal Watercraft Market
Outdoor and Adventure Activities
Hiking Accessories Market
Outdoor and Adventure Activities
Snorkeling Market
Outdoor and Adventure Activities
Adventure Gear Market
Outdoor and Adventure Activities
North America Climbing Gears Market
Outdoor and Adventure Activities
Recreational Use Water Chute Market
Outdoor and Adventure Activities
Ski Gear and Equipment Market
Outdoor and Adventure Activities
Parasailing Equipment Market