
 Web Real-Time Communication (Webrtc) Market | 2026-2036
Web Real-Time Communication (Webrtc) Market Size, Share, and Industry Trends Forecast 2026-2036
Web Real-Time Communication (Webrtc) Market Analysis
Subscription-based API pricing is recalibrating how WebRTC capabilities monetize across developer ecosystems. Twilio Inc. leverages tiered usage models to capture high-volume messaging and voice workloads. Cisco Systems Inc. anchors enterprise-grade security certifications within its collaboration stack. Vonage Holdings Corp. competes on programmable video APIs tailored to vertical-specific customization.
Web Real-Time Communication denotes an open-source framework enabling peer-to-peer audio, video, and data transmission through standard web browsers without proprietary plugins or native application installs, utilizing JavaScript APIs, ICE/STUN/TURN protocols for NAT traversal, and DTLS-SRTP encryption for secure media channels. Its primary commercial purpose centers on embedding real-time interactive media into customer service portals, telehealth consultations, and remote education platforms without end-user software friction. The Software Development Kits segment dominates vendor R&D allocation as enterprises demand white-label customization. Cloud-Based deployment absorbs the fastest capacity expansion as hyperscaler co-location reduces latency for global user bases. Audio technology retains maturity while video and data sharing segments attract premium engineering investment for resolution scaling and screen-compositing features.
The FCC governs interstate communications infrastructure and spectrum allocation affecting WebRTC service quality guarantees in the United States. GDPR and the EU AI Act impose cross-border data handling constraints that shape European deployment architectures and consent management layers. Stakeholders must monitor how browser vendors evolve codec support policies and encryption standards, as these unilateral technical decisions can obsolete existing implementations faster than regulatory cycles adapt.
Market Dynamics
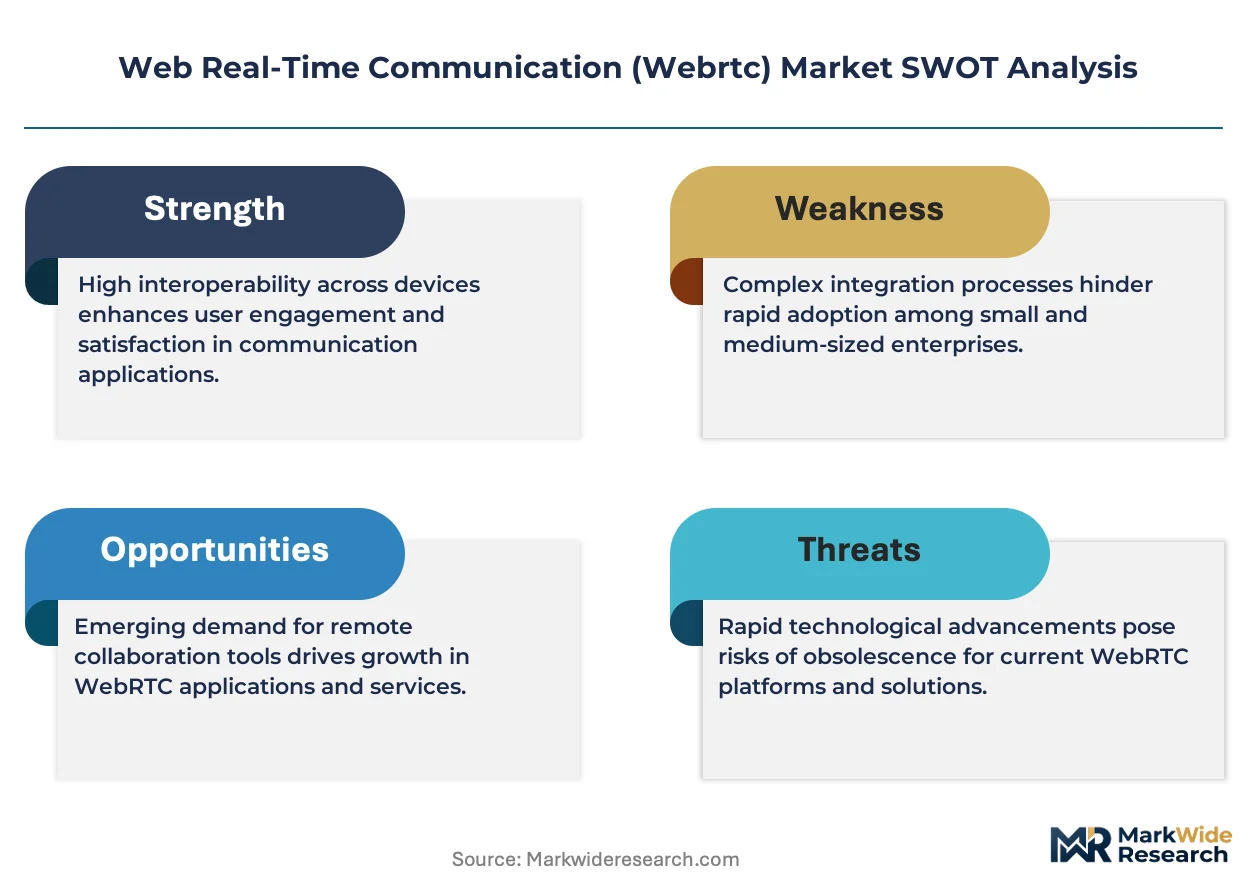
Browser vendors unilaterally deprecating codec support and encryption standards is compressing WebRTC implementation lifecycles faster than enterprise IT roadmaps can adapt, forcing continuous engineering reinvestment.
Growth Catalysts
- Telehealth Infrastructure Mandates:Post-pandemic healthcare delivery frameworks in the United States permanently embedded video consultation into reimbursement codes, sustaining platform procurement.
- GDPR Consent Architecture:European data handling requirements compelled vendors to build granular permission layers that now differentiate compliant offerings in privacy-sensitive sectors.
- Remote Work Tooling:Enterprise cloud migration patterns in financial services and technology verticals sustain embedded real-time collaboration demand.
Market Restraints
- Browser Dependency Risk:Google's Chrome and Mozilla's Firefox control rendering engine roadmaps, exposing implementations to unilateral API changes without vendor recourse.
- Codec Licensing Friction:H.264 and emerging AV1 patent pool complexity inflates royalty exposure for high-resolution video pipelines.
- Hyperscaler Concentration:AWS, Google Cloud, and Microsoft Azure absorb the majority of TURN server and signaling infrastructure deployment, creating single-source vulnerability.
Strategic Opportunities
- Edge Computing Convergence:WebRTC mesh networks combined with 5G multi-access edge computing enable sub-50ms latency for industrial AR remote assistance applications.
- India Digital Health Mission:National telemedicine guidelines and health stack interoperability standards create greenfield procurement for regional platform vendors.
- EU AI Act Compliance Layer:Real-time biometric identification restrictions in public-facing deployments favor privacy-preserving WebRTC implementations with on-device processing.
Industry Challenges
- WebRTC Engineering Talent Scarcity:Deep expertise in ICE negotiation, SFU architecture, and browser compatibility debugging commands premium compensation and constrains team scaling.
- Legacy PBX Integration Complexity:SIP trunk interoperability and on-premise telephony system replacement cycles delay full-stack unified communications migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Web Real-Time Communication (Webrtc) Market |
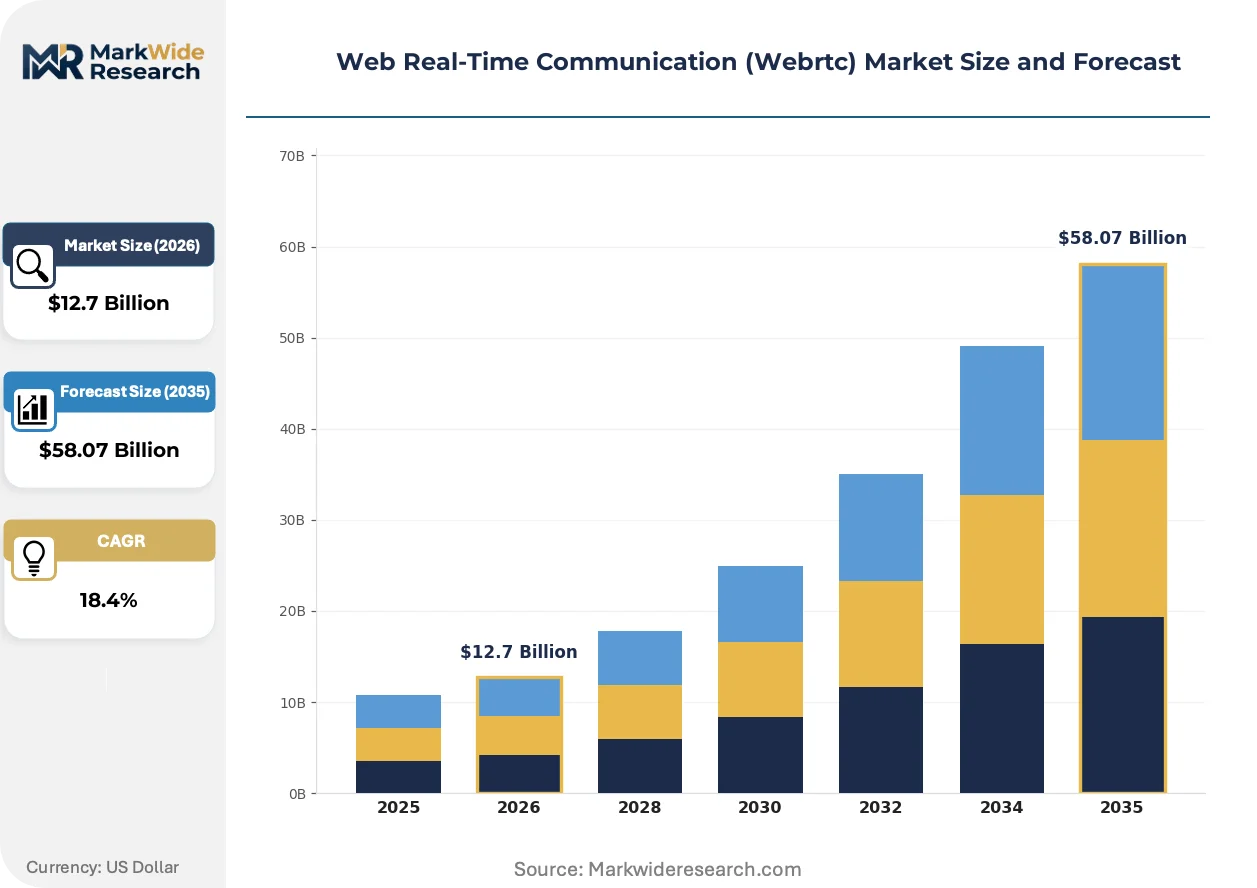
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $58.07 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Development Kits, Browsers, Applications, Middleware End User: Telecommunications, Healthcare Providers, Educational Institutions, Enterprises Deployment: On-Premise, Cloud-Based, Hybrid, Virtualized Technology: Audio, Video, Data Sharing, Signaling Protocols |
| Companies Covered | Cisco Systems Inc., Twilio Inc., AT&T Inc., Vonage Holdings Corp., Oracle Corporation, Agora, Avaya Inc., Ribbon Communications Operating Company Inc., Plivo Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Web Real-Time Communication (Webrtc) Market Emerging Trajectories
Artificial intelligence inference at the network edge is restructuring how real-time media flows are processed, compressed, and delivered across browser-based communication stacks.
Machine learning-based bandwidth estimation is automating adaptive bitrate algorithms that previously required manual tuning per network topology. Telehealth platforms and financial services contact centers are deploying these models at scale to maintain session quality across asymmetric consumer broadband. This automation is compressing the operational overhead that previously differentiated managed service offerings from raw API providers.
The EU AI Act's real-time biometric identification prohibitions in public spaces are reshaping deployment architectures for customer-facing video applications. Vendors must now implement on-device face detection and gesture analysis to avoid transmitting raw video streams to centralized processing. European retail banking and municipal service portals are most affected, accelerating investment in edge-based computer vision pipelines.
Developer procurement of communications infrastructure has pivoted toward consumption-based API contracts with embedded usage analytics. Enterprise buyers now demand granular visibility into per-minute costs, geographic routing efficiency, and quality-of-service metrics as standard contract terms. This pattern is most visible in United States technology and healthcare verticals, where procurement teams have absorbed cloud-native purchasing disciplines into real-time communications sourcing.
Web Real-Time Communication (Webrtc) Market Segmentation
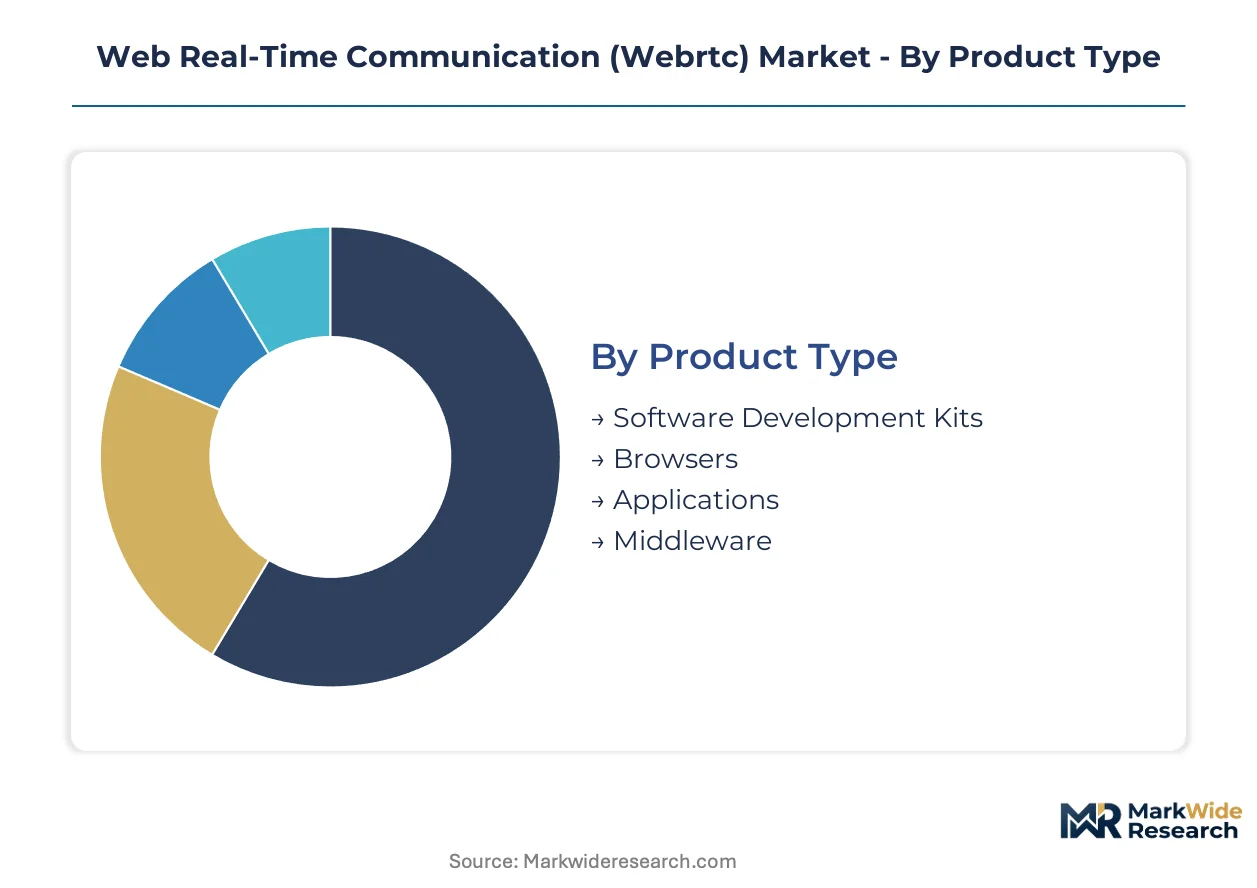
WebRTC market segmentation reflects how infrastructure investments concentrate around developer tooling versus end-user delivery, and how deployment architectures split between legacy control and cloud-native elasticity. Understanding these divisions clarifies where vendor R&D budgets flow and where procurement decisions stall.
Product Type:
Supply concentration in WebRTC infrastructure tilts heavily toward programmable components that enterprises embed rather than standalone applications they adopt outright.
- Software Development Kits:Pre-built libraries exposing JavaScript APIs, ICE negotiation handlers, and codec abstraction layers. Healthcare platforms in the United States and telehealth vendors across Germany demand white-label customization for branded patient portals, driving premium pricing for SDKs with HIPAA and GDPR compliance modules built in.
- Browsers:Native WebRTC implementations within Chrome, Firefox, and Safari rendering engines. Google's unilateral control over Chrome's codec roadmap and deprecation policies constrains enterprise IT planning cycles, forcing continuous engineering reinvestment to maintain compatibility.
- Applications:End-user software with pre-configured WebRTC stacks for video conferencing and screen sharing. Enterprises in regulated sectors favor these for faster procurement cycles despite reduced customization flexibility.
- Middleware:Signaling servers, TURN relay infrastructure, and session border controllers bridging WebRTC to SIP trunking. Financial services contact centers deploy these for legacy PBX interoperability during phased cloud migration.
Software Development Kits absorb the bulk of installed capacity; Cloud-Based deployment configurations within vendor offerings are expanding most quickly.
End User:
Cost tier differentiation separates verticals with compliance-driven procurement budgets from those optimizing per-seat economics.
- Telecommunications:Carriers embedding WebRTC into consumer messaging apps and enterprise unified communications suites. Tier-1 operators in India and Brazil leverage programmable APIs to bypass legacy infrastructure buildouts.
- Healthcare Providers:Hospital systems and telehealth platforms requiring encrypted video consultation with audit logging. United States reimbursement codes permanently covering remote patient visits sustain procurement momentum despite capital budget pressures elsewhere.
- Educational Institutions:Universities and K-12 districts deploying virtual classroom infrastructure. Budget constraints favor browser-native solutions over licensed applications, compressing vendor margins.
- Enterprises:Cross-industry corporate deployments for remote collaboration and customer service. Technology and financial services verticals in the United States lead consumption-based API contracting with embedded usage analytics requirements.
Healthcare Providers command the highest per-seat pricing; Enterprises represent the steepest expansion trajectory as cloud-native procurement disciplines spread across sectors.
Deployment:
Volume concentration patterns reveal how latency requirements and data sovereignty concerns fragment infrastructure choices across geographies.
- On-Premise:Self-managed signaling and media servers within enterprise data centers. German manufacturing and Japanese financial institutions favor these for regulatory audit control despite higher operational overhead.
- Cloud-Based:Hyperscaler-hosted infrastructure with global TURN server distribution. AWS, Google Cloud, and Microsoft Azure absorb the majority of new capacity as latency-sensitive applications demand edge-adjacent processing.
- Hybrid:Split architectures keeping signaling on-premise while offloading media relay to cloud. European enterprises navigating GDPR data residency requirements deploy these to satisfy cross-border handling constraints.
- Virtualized:Containerized WebRTC stacks orchestrated via Kubernetes for elastic scaling. Technology sector adopters in the United States and India favor these for DevOps-aligned operational models.
Cloud-Based deployments hold the dominant share of new provisioning; Virtualized configurations are gaining share fastest among cloud-native enterprises.
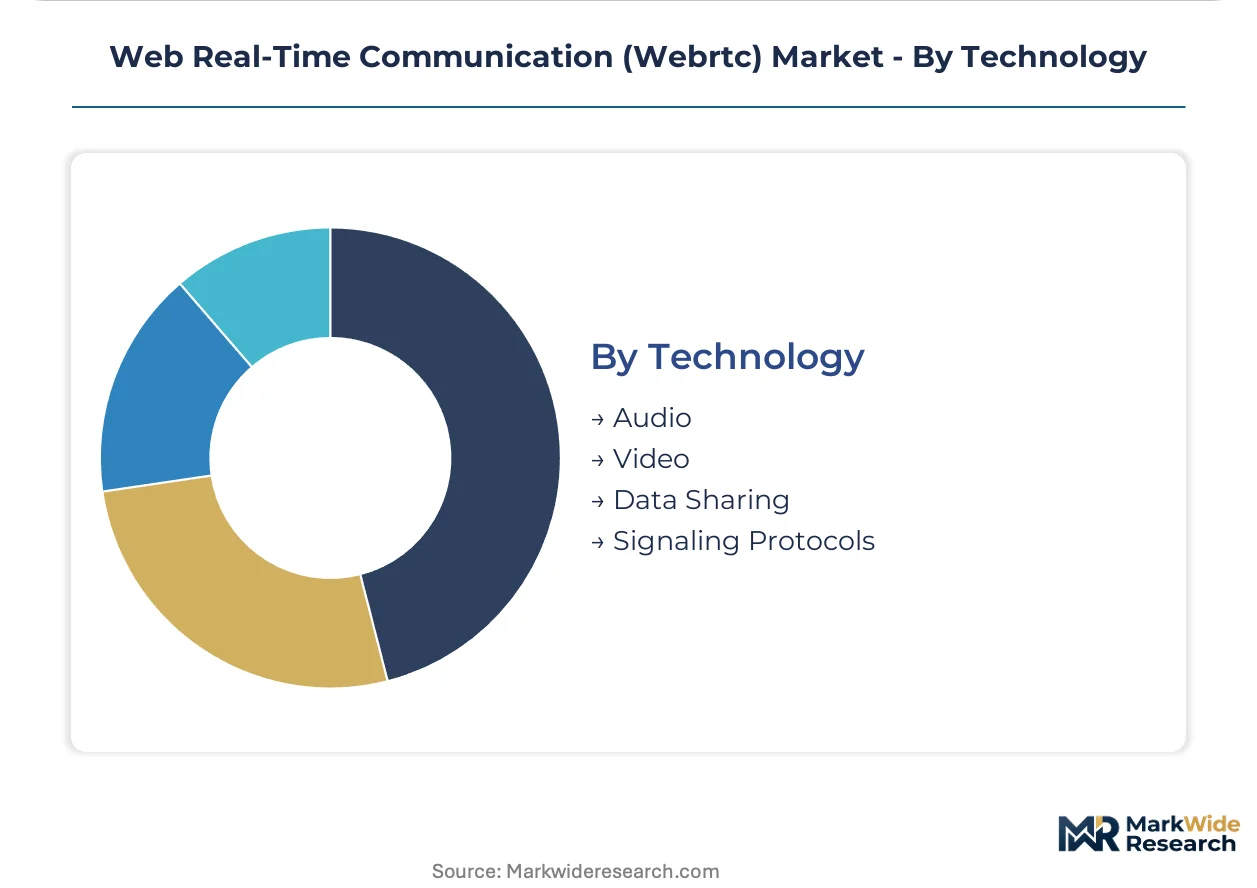
Technology:
Margin structures diverge sharply between mature audio stacks and video pipelines requiring continuous codec optimization.
- Audio:Opus codec implementations with adaptive bitrate and packet loss concealment. Mature engineering investment profiles and stable patent licensing sustain thin margins except in specialized broadcast-quality applications.
- Video:VP8, VP9, H.264, and emerging AV1 codec pipelines with simulcast and selective forwarding. Telehealth and financial services contact centers drive demand for resolution scaling and screen-compositing features that command premium engineering investment.
- Data Sharing:Peer-to-peer file transfer, screen sharing, and real-time collaboration protocols. Remote work tooling sustain embedded demand for these capabilities within broader platform procurement.
- Signaling Protocols:WebSocket, SIP over WebSocket, and proprietary signaling layers managing session establishment. Interoperability complexity with legacy PBX systems constrains migration velocity and sustains middleware vendor revenues.
Video technology captures the bulk of vendor R&D allocation; Data Sharing is climbing the fastest as collaboration platforms integrate whiteboarding and co-editing features.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates the majority of WebRTC consumption through enterprise cloud migration and telehealth reimbursement permanence, while India and Germany concentrate engineering talent and manufacturing integration respectively. Production of core infrastructure components clusters near hyperscaler regions and specialized telecommunications hubs.
United States
Enterprise procurement of embedded video APIs and telehealth platform infrastructure sustains dominant demand volume. FCC net neutrality frameworks and HIPAA enforcement shape vendor compliance investments. San Francisco Bay Area technology clusters and Seattle hyperscaler corridors host the primary engineering centers for browser-native communication stacks.
Germany
Industrial manufacturing and automotive sectors deploy WebRTC for remote equipment assistance and quality control visualization. GDPR consent architecture requirements and the EU AI Act's biometric restrictions compel edge-based processing investments. Munich and Stuttgart engineering clusters concentrate SFU architecture development for privacy-sensitive European deployments.
India
National telemedicine guidelines under the Digital Health Mission and PLI scheme incentives accelerate domestic platform procurement. TRAI data localization consultations influence vendor infrastructure placement decisions. Bengaluru and Hyderabad technology corridors absorb the fastest expansion of WebRTC engineering talent for global delivery.
Japan
Financial services contact centers and precision manufacturing remote assistance sustain premium-tier API consumption. METI cybersecurity guidelines and JIS standards certification requirements filter vendor eligibility. Tokyo-Osaka industrial corridors concentrate deployment of low-latency mesh networks for industrial AR applications.
United Kingdom
Financial services regulatory technology and legal sector client consultation platforms drive embedded communication demand. FCA operational resilience requirements and post-Brexit data handling constraints shape deployment architectures. London fintech clusters and Manchester media technology hubs concentrate vendor service delivery operations.
Web Real-Time Communication (Webrtc) Market Vendor Landscape
Top-tier vendors anchor enterprise-grade security certifications and global hyperscaler partnerships, while mid-tier specialists compete on vertical-specific customization and regional compliance modules. The vendor base stratifies across three tiers: full-stack platform providers, programmable API specialists, and legacy telecommunications integrators. Dominant competitive moves include M&A activity targeting SFU architecture talent and strategic partnerships with cloud infrastructure providers to secure TURN server distribution.
Within the programmable API tier, Twilio Inc. and Vonage Holdings Corp. exemplify consumption-based pricing models with embedded usage analytics. Cisco Systems Inc. occupies a position representing enterprise security certification anchoring. These three entities collectively illustrate how vendor positioning diverges between developer ecosystem capture and regulated vertical penetration.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Twilio Inc. |
| AT&T Inc. |
| Vonage Holdings Corp. |
| Oracle Corporation |
| Agora |
| Avaya Inc. |
| Ribbon Communications Operating Company Inc. |
| Plivo Inc. |
| Others |
Supply Flow & Price Mechanics
Enterprise technology procurement teams in United States healthcare and financial services verticals anchor demand for consumption-based API contracts with embedded usage analytics, forcing vendors toward granular per-minute pricing transparency rather than bundled licensing arrangements.
Pricing Analysis
Margin tightening in mid-tier programmable video APIs reflects hyperscaler co-location cost escalation and engineering talent scarcity. Three-tier pricing structure across premium, standard, and economy levels stratifies by HIPAA/GDPR certification grade and geographic routing redundancy. Cost-down pressure on raw API providers accelerates because machine learning-based bandwidth estimation automates quality management that previously justified premium service tiers. Educational institutions exhibit highest price sensitivity; telehealth platforms demonstrate lowest sensitivity due to reimbursement code permanence.
Supply Chain Analysis
Single-source vulnerability sits with AWS, Google Cloud, and Microsoft Azure for TURN server and signaling infrastructure deployment. Component manufacturing concentrates in United States hyperscaler corridors, Taiwan semiconductor foundries, and India engineering talent pools. Supply chain risk hinges on browser vendor unilateral deprecation policies that compress implementation lifecycles faster than enterprise IT roadmaps adapt. Distribution runs through direct API marketplace contracting and channel partner systems integration for legacy PBX interoperability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Browser vendor control over codec roadmaps and encryption standards is forcing continuous engineering reinvestment that favors well-capitalized incumbents with dedicated SFU architecture teams, squeezing margin-thin competitors toward exit or acquisition.
For Market Incumbents: Cement enterprise-grade security certification anchoring by pursuing FedRAMP and ISO 27001 accreditations that procurement teams in United States financial services mandate. Acquire SFU architecture talent pools in Bengaluru and Hyderabad to defend against hyperscaler native service encroachment. Deepen backward integration into edge computing infrastructure to reduce latency-dependent customer churn. For New Entrants and Emerging Players: EU AI Act biometric identification restrictions in European public-facing deployments open a window for privacy-preserving edge-based computer vision pipelines. Target German industrial manufacturing remote assistance applications where GDPR consent architecture requirements filter incumbent eligibility. Pursue white-label SDK positioning for India Digital Health Mission platform vendors seeking rapid compliance modularization. For Investors and Strategic Acquirers: The window for entry favors specialized SFU architecture boutiques with demonstrated browser compatibility debugging expertise. Long-term viability rests on engineering talent density rather than customer scale given implementation lifecycle compression. Monitor Google Chrome codec deprecation announcements as the critical inflection signal for portfolio revaluation timing.| Strategic Initiative | Industry Significance |
|---|---|
| SFU Architecture Talent Acquisition | Deep ICE negotiation expertise commands premium compensation and constrains team scaling velocity. |
| Edge Computing Infrastructure Partnership | 5G multi-access edge computing enables sub-50ms latency for industrial AR remote assistance applications. |
| GDPR Consent Module Development | Granular permission layers differentiate compliant offerings in European privacy-sensitive healthcare sectors. |
| Legacy PBX Interoperability Certification | SIP trunk bridging sustains middleware vendor revenues during phased cloud migration cycles. |
| Hyperscaler Co-location Expansion | AWS, Google Cloud, and Microsoft Azure absorb majority of new TURN server capacity provisioning. |
Methodological Framework
SEC filings, hyperscaler capex disclosures, and TRAI consultation documents formed the secondary backbone for infrastructure deployment trajectory validation. Primary interviews with CTOs at telehealth platforms, IT procurement officers at financial services contact centers, platform engineers at programmable API vendors, and integration specialists at channel partners cross-referenced capacity expansion plans against secondary indicators. Bottom-up and top-down triangulation reconciled vendor-reported SDK deployment volumes with enterprise adoption surveys.
Bottom-up modeling aggregated individual segment trajectories across deployment architecture, end-user vertical, and technology layer dimensions. Top-down validation checked aggregate figures against hyperscaler revenue disclosures and browser vendor engineering roadmap announcements. CAGRs were derived from fitted growth curves calibrated to reimbursement code permanence in United States healthcare and PLI scheme acceleration in India. Industry-specific forecast inputs included FCC net neutrality enforcement patterns and EU AI Act implementation timelines.
Caveats apply where browser vendor unilateral codec deprecation decisions or GDPR cross-border data handling enforcement shifts could materially shift the outlook. Forecasts reflect assumptions about telehealth reimbursement permanence and enterprise cloud migration velocity that regulatory or macroeconomic disruptions could revise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Key Management As a Service (Kmaas) Market
Digital Solutions
Social Employee Recognition Systems Market
Digital Solutions
Digital Workplace Market
Digital Solutions
Service Lifecycle Management Application Market
Digital Solutions
Global Service Delivery Platform Market
Digital Solutions
Europe Digital Signage Market
Digital Solutions
AI Infrastructure Solutions Market
Digital Solutions
Cloud Project Portfolio Management (CPPM) Market
Digital Solutions
Captioning and Subtitling Solutions Market
Digital Solutions
Global Transport Management Software Market
Digital Solutions
Data Converter Market
Digital Solutions
Ticket Admission Systems Market
Digital Solutions
Tail Spend Management Solutions Market
Digital Solutions
Connected Stadium Solution Market
Digital Solutions
Legal Transcription Market
Digital Solutions
Australia ICT Market