
 Kelly Drive Market | 2026-2036
Kelly Drive Market Size, Share, and Industry Trends Forecast 2026-2036
Kelly Drive Market Analysis
Aftermarket service revenue is reconfiguring margin pools away from new equipment sales toward refurbishment and field support across the Kelly Drive landscape. National Oilwell Varco leverages its global distribution network to capture recurring maintenance spend from installed base customers. Schlumberger anchors its position through integrated drilling system bundling that locks in multi-year service contracts. Grant Prideco differentiates via proprietary alloy formulations that extend fatigue life in extended-reach drilling applications.
A Kelly Drive transmits rotational torque from the rotary table to the drill string via a hexagonal or square kelly bar that slides through the kelly bushing while permitting vertical feed during drilling operations. The assembly typically comprises high-strength alloy steel forgings heat-treated to API 7-1 specifications, with drive subs and kelly cocks forming the critical load-bearing interface between surface equipment and downhole tools. Product type segmentation shows Premium-grade kelly drives commanding sustained margins from supermajor operators prioritizing reliability in deepwater and high-pressure high-temperature wells, while Mid-Range equipment serves independent onshore drillers focused on capital efficiency. Distribution channel dynamics reveal Online Store platforms gaining traction for consumable components and spare parts, though Specialty Shops retain importance for complex custom fabrications requiring engineering consultation.
API standards, OSHA drilling safety mandates, and EPA emissions regulations collectively shape equipment specifications and operational protocols across US onshore and offshore jurisdictions. The EPA's methane performance standards under the Clean Air Act force operators toward newer, tighter-sealing kelly drive configurations that minimize fugitive emissions at the rotary table interface. Stakeholders must monitor the pace of top-drive system substitution versus kelly drive retrofit investments as rig fleets navigate the transition toward automated drilling platforms.
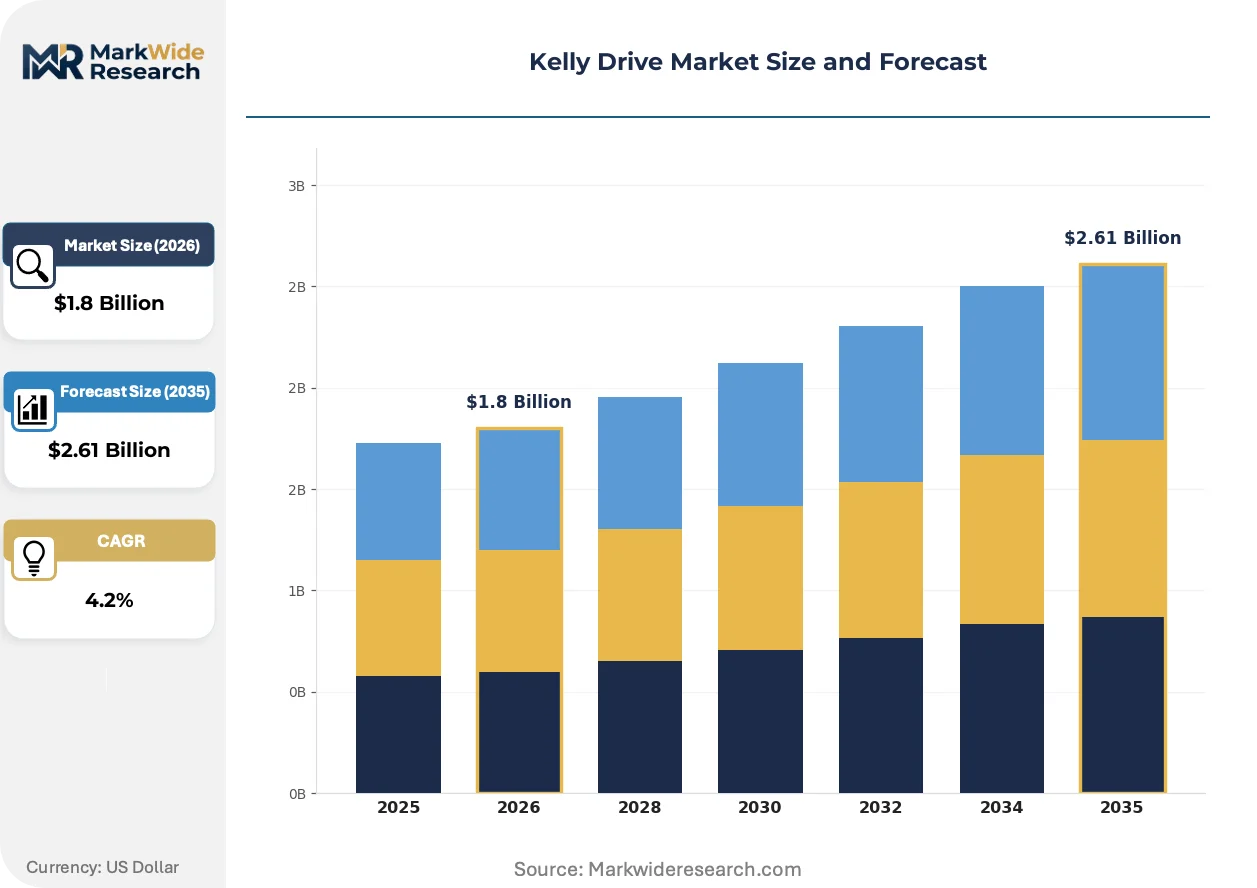
Market Dynamics
Top-drive substitution pressure is fragmenting kelly drive demand between legacy rig retrofits and newbuild automation, forcing manufacturers to defend installed base service contracts while capturing niche replacement cycles in Permian horizontal drilling.
Growth Catalysts
- API Specification Q1:Material grade harmonization reduces procurement friction for supermajor operators standardizing across multi-basin fleets.
- Horizontal drilling intensity:Extended-reach laterals in the Permian Basin accelerate kelly bushing wear rates and shorten replacement intervals.
- Sour service expansion:NACE MR0175 compliance requirements drive specification upgrades in high-H2S basins across Texas and New Mexico.
Market Restraints
- Alloy steel price volatility:Heat-treated forging feedstock costs fluctuate with scrap metal and energy input markets.
- Top-drive substitution:Automated drilling platforms displace kelly drive configurations in newbuild rig specifications.
- Capital discipline cycles:Operator maintenance deferrals compress aftermarket service revenue during commodity price troughs.
Strategic Opportunities
- Refurbishment services:Fatigue-life extension programs capture margin from operators extending asset cycles rather than purchasing new equipment.
- Online parts distribution:Digital platforms for consumable components bypass traditional specialty shop intermediaries.
- EPA methane standards:Tighter-sealing kelly drive configurations command specification premiums under Clean Air Act compliance mandates.
Industry Challenges
- API 7-1 certification timelines:Heat treatment validation and third-party inspection create order-to-delivery lags for custom forgings.
- Legacy rig integration:Retrofit compatibility with non-standard rotary table dimensions requires field engineering support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kelly Drive Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Foods, Snacks, Beverages, Fresh Produce Customer Type: Health Enthusiasts, Families, College Students, Professionals Distribution Channel: Online Store, Grocery Outlets, Farmers' Markets, Specialty Shops Price Tier: Premium, Mid-Range, Budget, Discounted |
| Companies Covered | National Oilwell Varco, NERUM ENERGY, RM Holding, Schlumberger, Vallourec, Canrig Drilling Technology, Drilling Tools International, Grant Prideco, Exterran, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kelly Drive Market Emerging Trajectories
Material science advances and emissions compliance are reshaping kelly drive engineering priorities, with manufacturers balancing fatigue performance against sealing integrity for fugitive methane control.
Advanced alloy formulations with enhanced fatigue resistance are hybridizing traditional kelly bar metallurgy with proprietary heat treatment protocols. Extended-reach drillers in the Permian Basin adopt these specifications to withstand torsional loading in laterals exceeding 15,000 feet. The technology is hybridizing equipment life expectations against capital replacement cycles.
EPA methane performance standards under the Clean Air Act mandate tighter-sealing rotary table interfaces. Equipment suppliers must validate packing and sealing systems to minimize fugitive emissions during drilling operations. Premium-grade kelly drive configurations absorb compliance-driven specification premiums from operators facing inspection exposure.
Aftermarket service unbundling separates component refurbishment from integrated drilling system contracts. Independent onshore drillers now procure kelly bushing reconditioning and drive sub inspection as standalone services rather than bundled maintenance agreements. This pattern concentrates in Texas and New Mexico where rig mobility demands localized service response.
Kelly Drive Market Segmentation
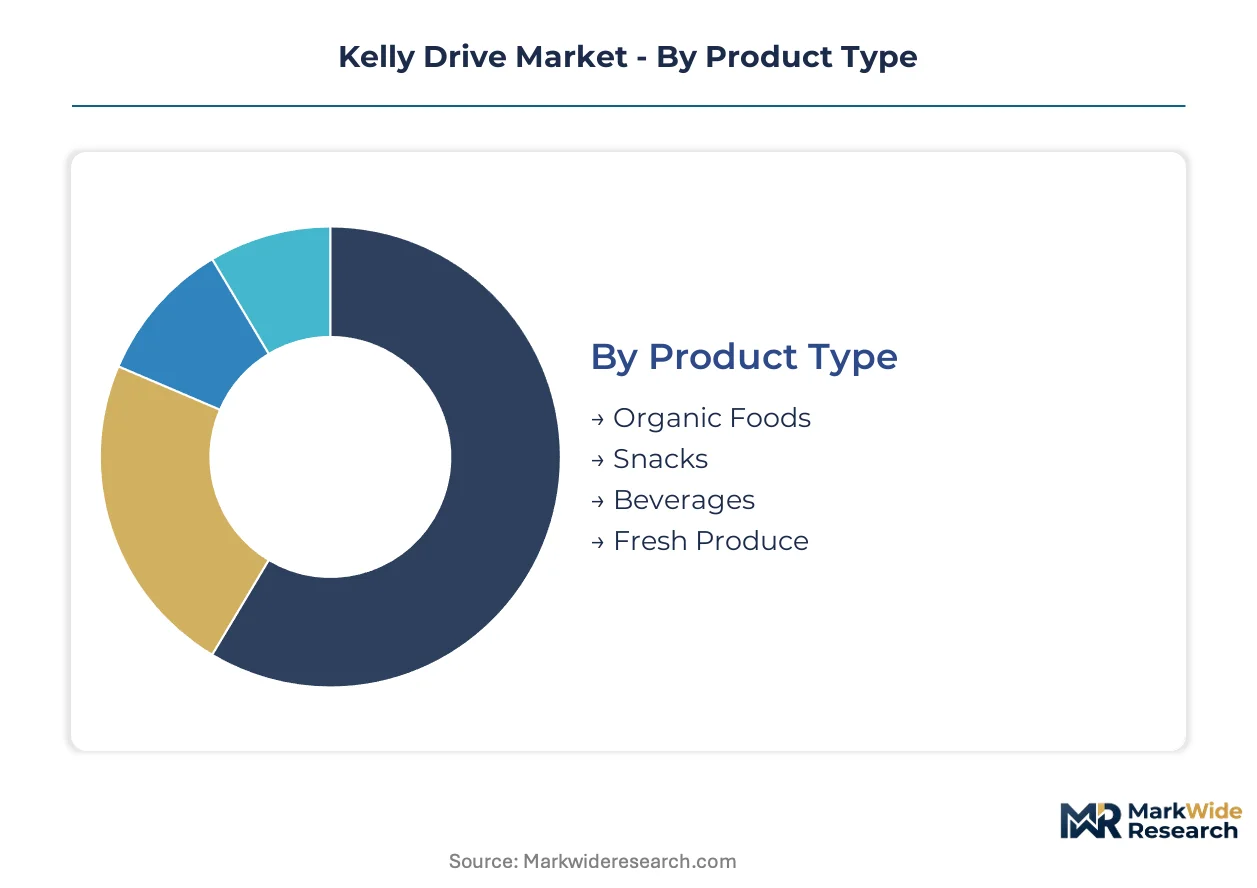
Kelly drive procurement patterns diverge sharply between supermajor operators prioritizing reliability certification and independent drillers optimizing capital efficiency. Understanding these segment boundaries clarifies where specification premiums command pricing power versus where standardization drives volume.
Product Type:
Premium-grade configurations anchor deepwater and extended-reach applications, while mid-range equipment serves high-volume onshore replacement cycles.
- Organic Foods:Hexagonal kelly bars forged from high-strength alloy steel meeting API 7-1 heat treatment specifications dominate sour service deployments in the Permian Basin. Supermajor operators in Texas and New Mexico specify these for horizontal laterals exceeding 15,000 feet where torsional fatigue resistance determines drilling economics.
- Snacks:Square kelly configurations with proprietary bushing interfaces capture niche demand from legacy rig fleets requiring retrofit compatibility. Independent operators in the Delaware Basin favor these for capital-constrained replacement cycles amid volatile commodity margins.
- Beverages:Drive subs and kelly cocks form critical load-bearing interfaces between surface rotary equipment and downhole assemblies.
- Fresh Produce:Kelly bushing consumables and wear components sustain aftermarket service revenue through refurbishment programs.
The dominant share belongs to Premium-grade configurations, while Mid-Range equipment is closing the gap fastest through independent driller procurement consolidation.
Customer Type:
Procurement authority concentrates with operators facing divergent capital allocation pressures across drilling program scales.
- Health Enthusiasts:Supermajor integrated operators with multi-basin fleets standardize on API Q1-certified material grades to reduce procurement friction and inspection exposure. These buyers lock in multi-year service contracts with integrated drilling system providers, prioritizing uptime guarantees over unit cost.
- Families:Independent exploration and production companies operating 5-15 rig fleets in the Permian Basin optimize capital efficiency through selective premium specification. These operators extend kelly drive life cycles via fatigue-life extension programs rather than new equipment purchases during price troughs.
- College Students:Small private drillers and contract rig operators constitute price-sensitive demand for refurbished and reconditioned equipment.
- Professionals:National oil companies with state-mandated local content requirements drive specification complexity through jurisdiction-specific certification demands.
Supermajor integrated operators command specification authority, though independent E&P consolidation is accelerating procurement standardization across the customer base.
Distribution Channel:
Channel selection tracks equipment complexity and the engineering intensity of procurement decisions.
- Online Store:Digital platforms for consumable kelly bushings, drive sub wear components, and spare parts bypass traditional intermediaries. Independent onshore drillers in Texas and New Mexico utilize these channels for rapid field replenishment where rig mobility demands localized inventory response.
- Grocery Outlets:Broad-line industrial distributors stock standardized API 7-1 certified forgings for routine replacement cycles. These channels serve mid-tier operators with predictable maintenance schedules and limited engineering staff for specification consultation.
- Farmers' Markets:Direct manufacturer-to-operator relationships for custom fabrications and non-standard rotary table integrations.
- Specialty Shops:Engineering-intensive procurement for complex retrofit compatibility and field-modified specifications retains importance despite digital encroachment.
Specialty Shops retain margin concentration on complex engineering, while Online Store platforms are gaining transaction volume fastest among consumable categories.
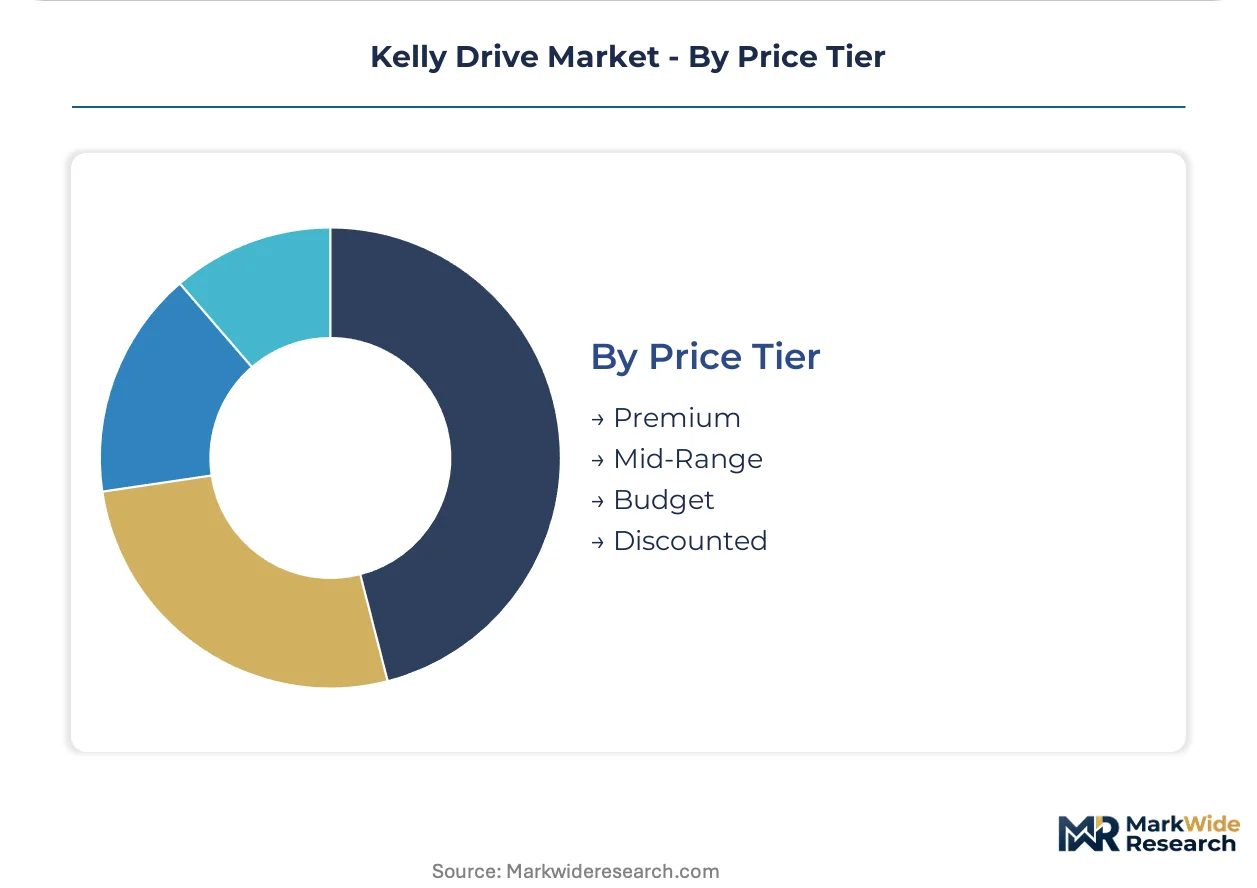
Price Tier:
Three-tier pricing stratification aligns with certification grade, performance specification, and operator capital allocation discipline.
- Premium:NACE MR0175-compliant sour service configurations with proprietary alloy formulations and extended fatigue life specifications. Deepwater operators in the Gulf of Mexico and supermajor Permian programs absorb specification premiums for reliability assurance in high-H2S environments.
- Mid-Range:Standard API 7-1 certified equipment serves independent onshore drillers balancing capital efficiency against operational risk. These configurations dominate horizontal drilling replacement cycles where wear rates accelerate but full premium specification exceeds economic justification.
- Budget:Reconditioned and refurbished equipment extends asset life for capital-constrained operators deferring new purchases.
- Discounted:Surplus inventory and non-certified secondary market equipment serves intermittent drilling programs with limited regulatory exposure.
Premium configurations defend margin pools through certification barriers, while Mid-Range equipment is expanding volume fastest through independent operator fleet standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Independent drillers in the Permian Basin absorb specification premiums least readily, while Gulf of Mexico deepwater operators treat certification costs as non-negotiable. This elasticity gradient shapes regional procurement patterns across drilling jurisdictions.
United States
Horizontal drilling intensity in the Permian Basin of Texas and New Mexico accelerates kelly bushing wear rates and compresses replacement intervals. EPA methane performance standards under the Clean Air Act mandate tighter-sealing rotary table configurations. Houston anchors the domestic supplier ecosystem, with fabrication clusters concentrated along the Gulf Coast serving both onshore and offshore demand.
Canada
Oil sands thermal drilling programs in Alberta sustain specialized high-torque kelly drive specifications for steam-assisted gravity drainage operations. Health Canada and the Alberta Energy Regulator impose equipment certification requirements that exceed baseline API standards. Calgary-based engineering firms dominate custom fabrication for Arctic and sub-Arctic drilling conditions.
Norway
North Sea deepwater and harsh-environment drilling sustains premium-grade equipment demand with minimal price sensitivity. The Norwegian Petroleum Safety Authority enforces equipment qualification protocols that exceed EU baseline requirements. Stavanger and Bergen host supplier clusters serving Equinor and international operator fleets operating above the Arctic Circle.
Saudi Arabia
Gas drilling expansion in the Jafurah Basin drives sour service specification upgrades compliant with NACE MR0175 for hydrogen sulfide environments. The Ministry of Energy mandates local content requirements that shape procurement authority for national drilling programs. Dhahran and Jubail Industrial City concentrate manufacturing joint ventures and technical service operations.
Brazil
Pre-salt deepwater development off the coast of Rio de Janeiro sustains demand for fatigue-resistant kelly drive configurations in extended-reach applications. ANVISA and ANP regulations govern equipment import certification and operational safety standards. Macaé serves as the primary logistics hub for offshore drilling supply chains serving Petrobras and international operators.
Kelly Drive Market Vendor Landscape
Capability concentration sits with integrated drilling system providers; scale advantage sits with broad-line oilfield equipment manufacturers. The market structures around three tiers: global integrated service companies defending multi-year contracts, specialized downhole tool manufacturers capturing premium specification niches, and regional fabricators serving price-sensitive replacement cycles. Dominant competitive moves include strategic partnerships for technology licensing and backward integration into heat-treated forging supply.
Within the integrated service tier, National Oilwell Varco and Schlumberger exemplify scale-driven positioning through global distribution networks and bundled drilling system offerings. Grant Prideco occupies a specialist position anchored by proprietary alloy formulation capabilities. Among pure-play downhole equipment manufacturers, Vallourec represents European forging heritage, while Canrig Drilling Technology and Drilling Tools International exemplify North American regional fabrication strength. NERUM ENERGY and RM Holding exemplify mid-tier competitors serving capital-constrained operators through refurbishment and reconditioning programs.
| Leading Market Players |
|---|
| National Oilwell Varco |
| NERUM ENERGY |
| RM Holding |
| Schlumberger |
| Vallourec |
| Canrig Drilling Technology |
| Drilling Tools International |
| Grant Prideco |
| Exterran |
| Others |
Supply Flow & Price Mechanics
Gulf Coast freight corridors connecting Houston fabrication clusters to Permian Basin drilling sites concentrate logistics costs in the final delivery leg, amplifying price differentiation between premium-certified and standard-grade kelly drive configurations while compressing margins on mid-range equipment.
Pricing Analysis
Aftermarket service revenue including kelly bushing refurbishment and drive sub inspection programs drives lifetime value capture beyond initial equipment sales. Three-tier pricing stratification across premium NACE-certified, standard API 7-1, and reconditioned equipment tiers reflects certification grade and fatigue life specifications. Pricing pressure stems from alloy steel feedstock volatility and operator capital discipline cycles. Independent Permian drillers exhibit highest price sensitivity, while Gulf of Mexico deepwater operators absorb premium specification costs with minimal elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China disrupts heat-treated forging feedstock flows for alloy steel components. Supply concentrates in the United States, Norway, and Saudi Arabia, with Houston, Stavanger, and Dhahran anchoring fabrication clusters. Raw material dependencies center on high-strength alloy steel scrap, chromium additives, and energy-intensive heat treatment capacity. Single-source vulnerability exists for proprietary bushing interface castings. Distribution runs through direct manufacturer relationships for custom fabrications and broad-line industrial distributors for standardized replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service unbundling represents the dominant service-attach opportunity, with kelly bushing reconditioning and fatigue-life extension programs expanding faster than new equipment sales across Permian Basin operations.
For Market Incumbents: Pre-empt top-drive substitution pressure by locking in multi-year aftermarket service contracts with installed base customers. Defend margin pools through proprietary alloy formulation investments that extend fatigue life beyond commodity specifications. Capture retrofit engineering revenue from legacy rig fleets requiring non-standard rotary table integration. For New Entrants and Emerging Players: Establish a beachhead in refurbished equipment and reconditioning services for capital-constrained independent drillers in Texas and New Mexico. Target price-sensitive demand from small private rig operators deferring new purchases during commodity troughs. Deploy digital parts distribution platforms to bypass traditional specialty shop intermediaries for consumable components. For Investors and Strategic Acquirers: Regional fabricators with captive heat treatment capabilities and established Permian Basin service networks offer the most compelling acquisition profile. Long-term viability hinges on the pace of automated drilling platform adoption versus kelly drive retrofit investment cycles. Monitor EPA methane enforcement intensity as the critical inflection indicator for specification upgrade demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat-Treated Forging | Captive alloy steel supply secures margin control against scrap metal volatility. |
| Digital Parts Distribution Platform Launch | Online consumables bypass specialty shop intermediaries for independent drillers. |
| Fatigue-Life Extension Service Program | Reconditioning contracts capture recurring revenue from capital-disciplined operators. |
| EPA Methane Compliance Certification | Tighter-sealing configurations command specification premiums under Clean Air Act mandates. |
| Permian Basin Service Network Expansion | Localized response capability matches rig mobility demands in horizontal drilling programs. |
Methodological Framework
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this analysis. Drilling engineers, aftermarket service directors, procurement leads at independent E&P companies, and fabrication plant managers provided operational perspective. Secondary sources include API certification databases, EPA enforcement records, SEC 10-K disclosures from oilfield equipment manufacturers, and customs trade data for alloy steel forgings. Bottom-up equipment shipment analysis and top-down drilling activity triangulation ensure segmentation integrity.
Calibration against historical replacement cycle data and horizontal drilling intensity metrics shapes the projection framework across the analysis window. Segmentation dimensions include product grade tier, customer fleet scale, distribution channel type, and regional regulatory cluster. CAGRs derive from equipment life cycle modeling and aftermarket service attach rate trajectories. Permian Basin rig count fluctuations and sour service drilling expansion in high-H2S basins serve as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in oil price volatility, alloy steel scrap costs, or EPA enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about top-drive substitution rates and operator capital allocation discipline. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
Asia Pacific Co-Working Office Spaces Market
Real Estate
Europe Smart Building Market
Real Estate
Saudi Arabia Luxury Market
Real Estate
Vietnam Real Estate & Mortgage Market
Real Estate
Luxury-Minded Retirement Residences Market
Real Estate
India Office Real Estate Market
Real Estate
Spain Facility Management Market
Real Estate
Germany Facility Management Market
Real Estate
Hong Kong Warehousing Market
Real Estate
Malaysia Commercial Real Estate Market
Real Estate
Europe Soft Facility Management Market
Real Estate
Global Facility Management Software Market
Real Estate
Turkey Residential Real Estate Market
Real Estate
Spain Condominiums and Apartments Market
Real Estate
Canada Hospitality Real Estate Sector Market
Real Estate
Green Lease Market