
 Global HVAC Software Market | 2026-2036
Global HVAC Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global HVAC Software Market Foresight
Cloud infrastructure is rebalancing legacy on-premise deployment economics across HVAC software procurement. Honeywell International Inc. leverages its building automation heritage to anchor enterprise contracts in North America. Siemens AG competes through deep integration of predictive maintenance modules with industrial IoT architectures. Schneider Electric SE differentiates via edge-computing energy management platforms that reduce latency for real-time building optimization.
HVAC software encompasses digital platforms that monitor, control, and optimize heating, ventilation, and air conditioning systems through sensor networks, algorithms, and user interfaces, typically operating across temperature setpoints, airflow rates, and energy consumption thresholds to maintain indoor environmental quality while minimizing operational expenditure. Building automation and energy management solutions occupy the largest margin pools given their integration complexity and recurring licensing structures, while predictive maintenance and fault detection represent the fastest-expanding categories as asset-heavy facilities prioritize uptime over reactive service calls. Indoor air quality modules are maturing rapidly in educational institutions and healthcare-adjacent commercial buildings where ventilation standards have tightened.
The EPA enforces refrigerant management protocols under Section 608 of the Clean Air Act that force software vendors to embed leak detection and compliance reporting into platform architectures, while the EU F-Gas Regulation and CE marking requirements shape product access across European member states. Japan's METI building efficiency standards and the EU Green Deal national renovation targets collectively expand addressable demand for software-enabled retrofit planning. Stakeholders must weigh cloud migration timelines against cybersecurity exposure as operational technology networks converge with enterprise IT infrastructure.
Market Dynamics
Cloud migration is compressing deployment cycles for HVAC software as facility managers abandon capital-intensive on-premise infrastructure for subscription-based energy management platforms. This shift is redistributing vendor economics toward recurring revenue pools and forcing incumbents to rearchitect legacy building automation systems.
Growth Catalysts
- EU F-Gas Regulation:Mandatory refrigerant leak detection and reporting obligations are embedding software compliance modules into building automation procurement specifications across member states.
- Educational institutions:Post-pandemic ventilation standards in schools and universities are accelerating adoption of indoor air quality monitoring platforms with real-time occupancy-based airflow control.
- Retrofit cycles:Aging commercial building stock in Germany, Japan, and the United States is generating demand for software-enabled energy audit and retrofit planning tools.
Market Restraints
- Semiconductor supply concentration:Edge computing hardware dependencies on Taiwan and South Korean chip fabrication are creating procurement bottlenecks for IoT sensor networks.
- Natural gas price volatility:Input cost swings for heating systems are compressing facility capital budgets and delaying software upgrade timelines.
- Cybersecurity compliance friction:Convergence of operational technology networks with enterprise IT infrastructure is extending sales cycles as buyers evaluate NIST framework adherence.
Strategic Opportunities
- India's Smart Cities Mission:Urban infrastructure digitization programs are creating first-mover advantages for cloud-native building energy management platforms in commercial real estate.
- Digital twin convergence:Integration of BIM models with live sensor telemetry is enabling predictive thermal modeling for large-format healthcare and laboratory facilities.
- Japan's METI building efficiency standards:Mandatory energy disclosure requirements for commercial structures above 2,000 square meters are mandating software-based consumption tracking.
Industry Challenges
- OT-IT integration complexity:BACnet and Modbus legacy protocol translation into cloud-native architectures requires specialized systems engineering talent that vendors struggle to source.
- Certification timeline compression:CE marking and UL certification for AI-driven fault detection algorithms are extending product launch windows by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global HVAC Software Market |
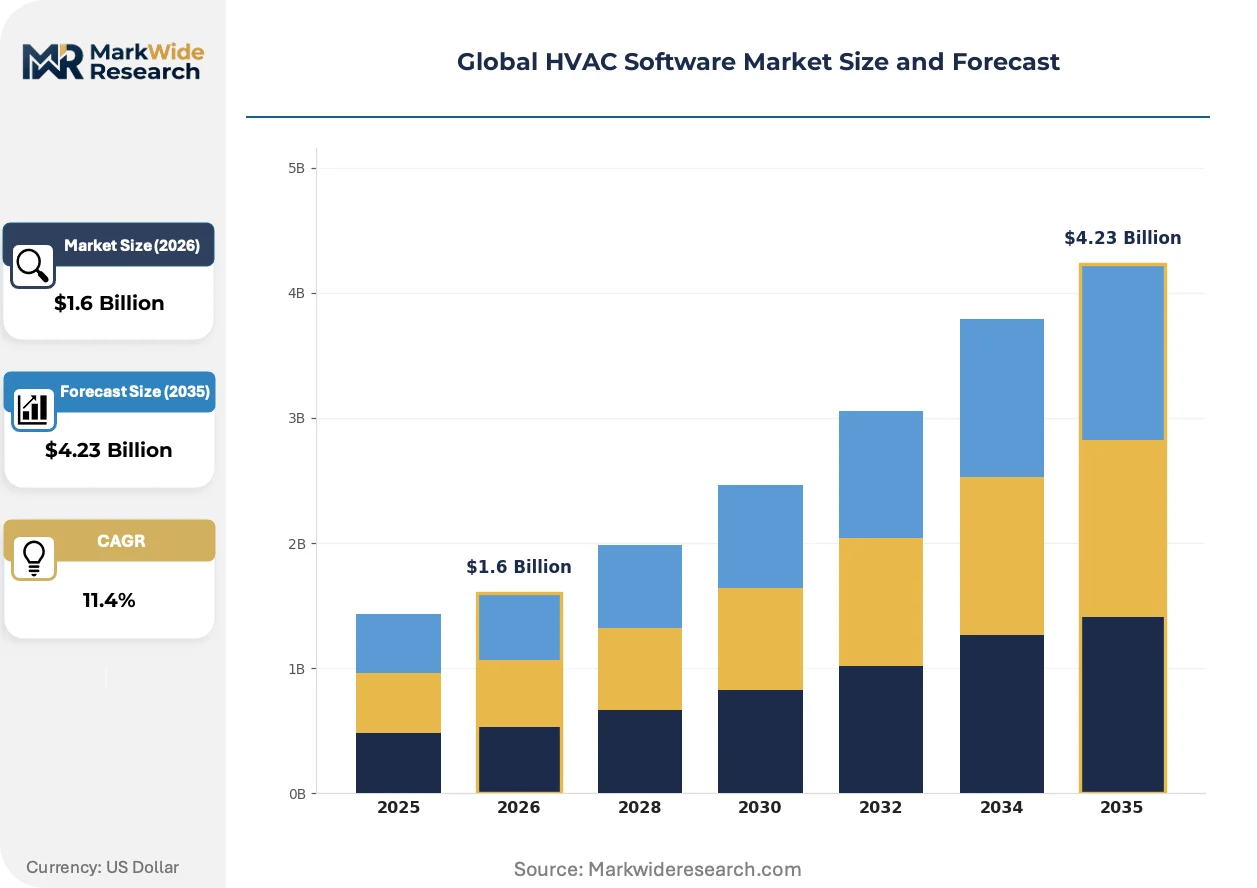
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge, SaaS Solution Type: Building Automation, Energy Management, Predictive Maintenance, Fault Detection, Indoor Air Quality Application: Commercial Buildings, Industrial Facilities, Data Centers, Educational Institutions, Government Facilities End User: Facility Managers, HVAC Contractors, Energy Consultants, Property Owners, Maintenance Teams |
| Companies Covered | Honeywell International Inc., Johnson Controls International plc, Siemens AG, Carrier Global Corporation, Trane Technologies plc, Lennox International Inc., Mitsubishi Electric Corporation, Daikin Industries Ltd., Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global HVAC Software Market Shifts & Advancements
Edge computing architectures are redistributing processing loads away from centralized cloud servers toward building-level hardware. This migration is compressing latency for real-time HVAC optimization while creating new competitive battlegrounds around on-premise versus hybrid deployment models.
Machine learning inference at the edge is decentralizing control logic for multi-zone climate systems. Hospital networks and pharmaceutical manufacturing facilities are deploying these architectures fastest, driven by uptime requirements that cannot tolerate cloud connectivity interruptions. The structural consequence is fragmenting vendor market power away from platform monopolists toward specialized edge hardware suppliers.
The EPA's Section 608 refrigerant management protocols are embedding automated leak detection into software procurement minimums. Equipment manufacturers must now certify that their platforms generate audit-ready compliance documentation or face exclusion from federal building contracts. Commercial refrigeration and cold chain logistics operators in the United States are absorbing these compliance costs earliest.
Facility managers are unbundling after-sales service contracts from initial software licenses, treating predictive maintenance as a separate procurement category. Third-party service integrators are capturing margin pools that incumbent vendors previously monopolized through bundled offerings. This pattern is most pronounced in German and Japanese industrial real estate portfolios where multi-vendor environments complicate single-source service dependencies.
Global HVAC Software Market Segmentation
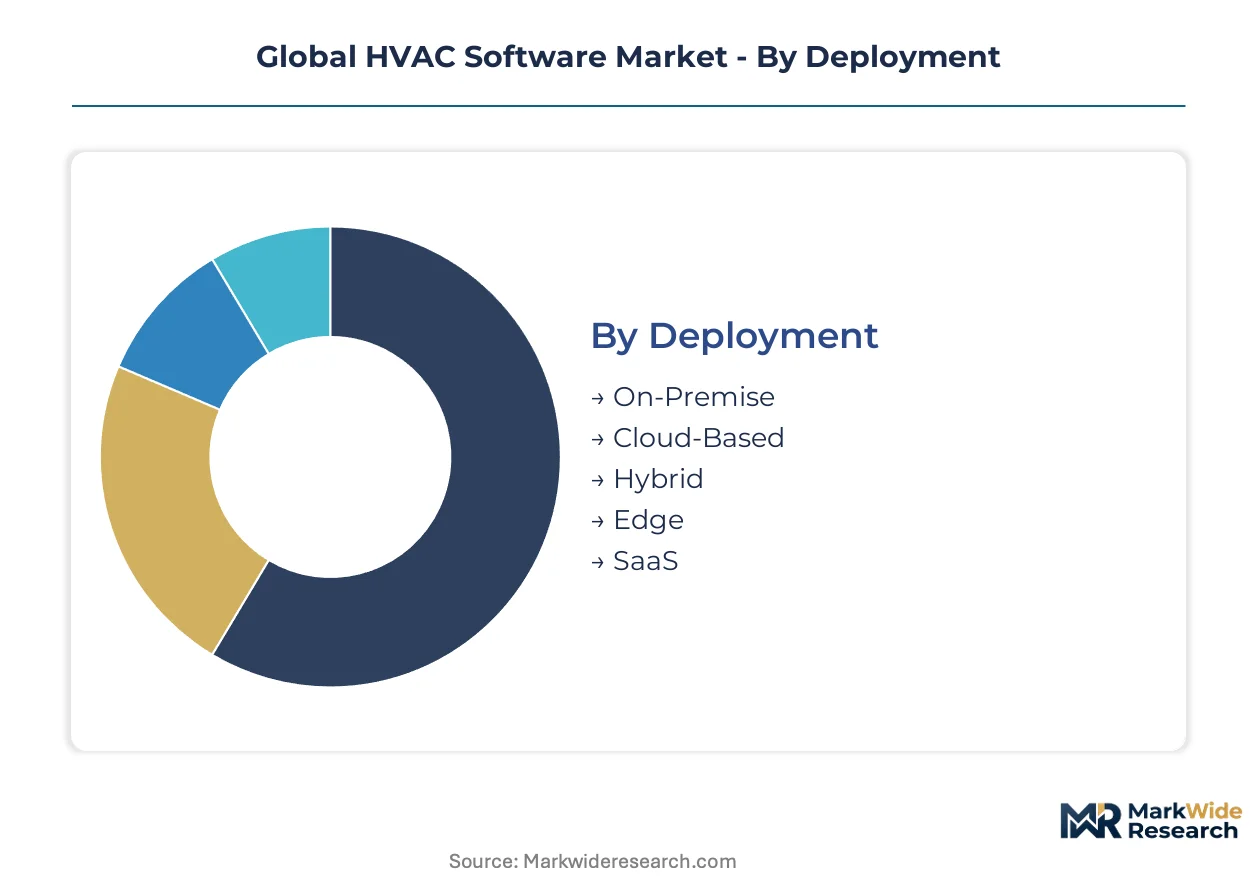
HVAC software segmentation reflects divergent buyer priorities across deployment complexity, operational scale, and compliance exposure. Procurement patterns split between legacy infrastructure retrofits and greenfield cloud-native installations, with each axis commanding distinct vendor capabilities and pricing structures.
Deployment:
Deployment architecture determines latency, cybersecurity exposure, and total cost of ownership for building automation networks. Cloud migration is compressing implementation timelines while edge computing addresses connectivity-critical environments.
- Cloud-Based:Centralized processing platforms eliminate on-site server maintenance and enable remote portfolio management. Demand concentrates in United States commercial real estate where facility managers prioritize capital expenditure reduction over latency sensitivity. Subscription economics are displacing perpetual licenses in mid-market building portfolios.
- Edge:On-premise compute nodes process sensor telemetry locally, eliminating cloud dependency for real-time control loops. Hospital networks and pharmaceutical manufacturing facilities in Germany and Japan deploy these architectures fastest, driven by uptime requirements that cannot tolerate connectivity interruptions. Hardware certification under EU CE marking and Japan's Electrical Appliance and Material Safety Law extends procurement cycles.
- On-Premise:Legacy server installations persist in government facilities with strict data sovereignty mandates.
- Hybrid:Split architectures balance local control with cloud analytics for multi-site industrial operators.
- SaaS:Pure software subscriptions abstract infrastructure entirely, appealing to small commercial property owners without IT departments.
Mature deployment sits with On-Premise. Newer deployment is concentrated in Cloud-Based.
Solution Type:
Functional modules align with buyer maturity stages, from basic environmental control through predictive asset optimization. Margin pools concentrate where software integrates with physical infrastructure and generates measurable operational savings.
- Building Automation:Integrated control platforms coordinate HVAC, lighting, and security systems through unified user interfaces. Large-format commercial buildings in the United States absorb these solutions earliest, driven by LEED certification requirements and utility demand-response incentives. BACnet protocol translation into cloud-native architectures creates implementation friction.
- Predictive Maintenance:Machine learning models analyze vibration, temperature, and power signatures to forecast equipment failures before functional degradation. Industrial facilities in Germany prioritize these capabilities to minimize unplanned downtime in continuous manufacturing processes. EU F-Gas Regulation leak detection mandates are embedding compliance modules into procurement specifications.
- Energy Management:Consumption analytics and optimization algorithms reduce operational expenditure through automated setpoint adjustments and load scheduling.
- Fault Detection:Real-time diagnostics identify performance anomalies and degradation patterns across distributed equipment fleets.
- Indoor Air Quality:Ventilation monitoring and occupancy-based airflow control address post-pandemic standards in educational institutions.
Revenue concentration favors Building Automation. Steepest expansion trajectory belongs to Predictive Maintenance.
Application:
Facility type dictates sensor density, uptime requirements, and regulatory exposure, shaping software feature priorities and sales cycle duration. Data centers and healthcare facilities command premium pricing for mission-critical reliability guarantees.
- Commercial Buildings:Office towers and retail portfolios prioritize energy cost reduction and tenant comfort optimization. Property managers in Japan's major metropolitan areas deploy these solutions to comply with METI mandatory energy disclosure requirements for structures above 2,000 square meters.
- Data Centers:Precision cooling control and redundant environmental monitoring protect server infrastructure from thermal damage. Hyperscale operators in the United States drive demand for real-time optimization that minimizes power usage effectiveness ratios.
- Industrial Facilities:Process-critical HVAC maintains manufacturing environment stability.
- Educational Institutions:Post-pandemic ventilation standards accelerate indoor air quality platform adoption.
- Government Facilities:Federal procurement mandates under EPA Section 608 require embedded refrigerant compliance documentation.
Deployment scale peaks in Commercial Buildings. Regulatory tailwinds are strongest in Data Centers.
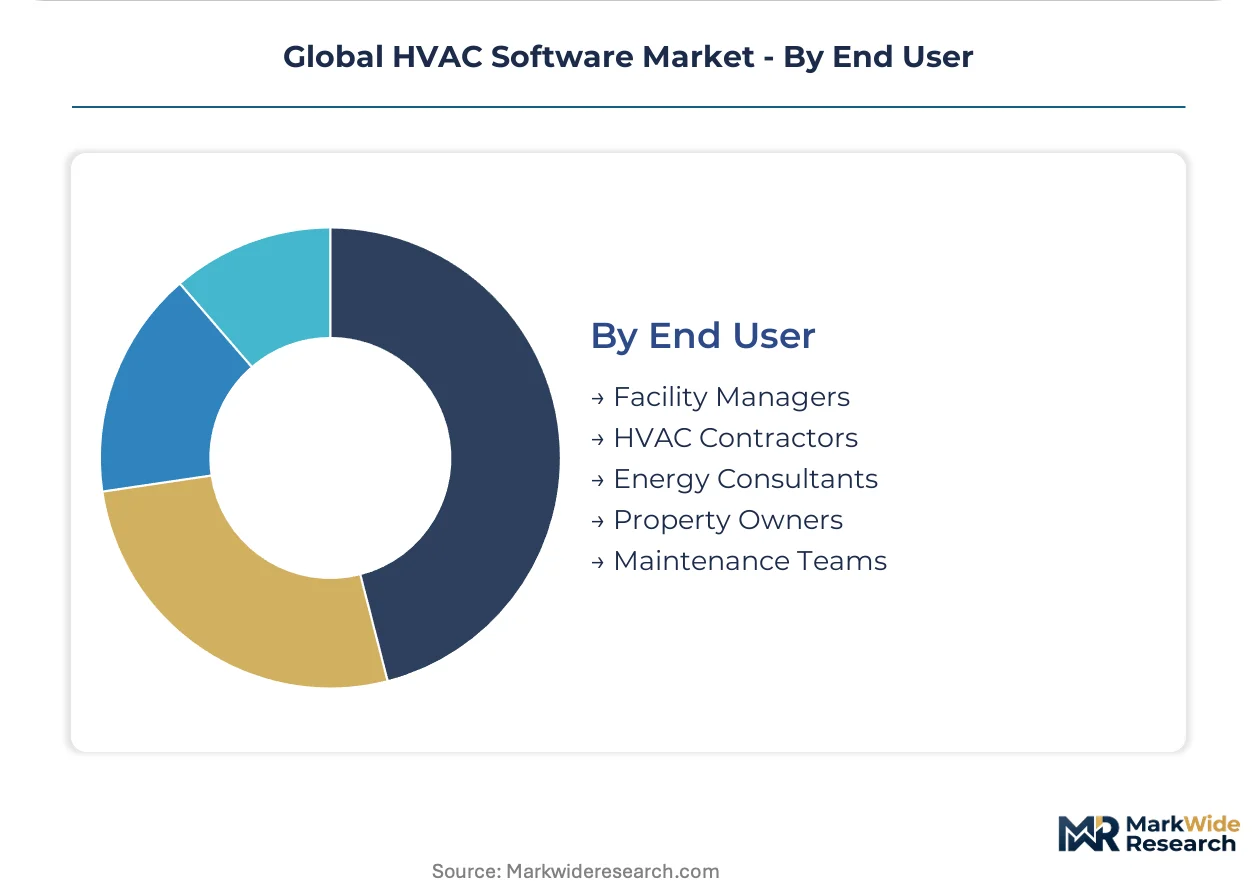
End User:
Buyer sophistication and procurement authority vary sharply across organizational roles, fragmenting vendor sales approaches and channel strategies. Direct enterprise sales, contractor networks, and consultant-led specifications compete for influence.
- Facility Managers:Building operations professionals with direct budget authority over energy and maintenance expenditures. Portfolio-scale operators in Germany's commercial real estate sector consolidate vendor relationships to simplify multi-site service coordination.
- Energy Consultants:Third-party advisors specify software platforms during retrofit planning and compliance certification. These actors capture margin pools that incumbent vendors previously monopolized through bundled service contracts.
- HVAC Contractors:Installation and service providers influence initial equipment and software selection.
- Property Owners:Asset-level decision-makers prioritize capital efficiency and tenant retention metrics.
- Maintenance Teams:Reactive service personnel adopt predictive tools as work order management systems integrate with mobile platforms.
Procurement authority concentrates with Facility Managers. Consultant influence is expanding fastest in retrofit-heavy markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility managers in the United States, Germany, and Japan command the deepest procurement budgets for cloud-based energy management platforms, while retrofit cycles and smart city investments concentrate software demand in these three markets.
United States
Commercial real estate portfolios and hyperscale data center operators drive cloud-native platform adoption. EPA Section 608 refrigerant management protocols mandate automated leak detection documentation for federal building contracts. Dallas-Fort Worth and Phoenix industrial corridors absorb edge-computing HVAC architectures fastest for thermal resilience.
Germany
Industrial manufacturing facilities prioritize predictive maintenance modules to minimize unplanned downtime in continuous processes. EU F-Gas Regulation leak detection obligations embed compliance software into building automation procurement specifications. The Rhine-Ruhr metropolitan region concentrates retrofit planning tool demand from aging commercial building stock.
Japan
Hospital networks and pharmaceutical manufacturing deploy edge architectures for uptime-critical environmental control. METI building efficiency standards mandate software-based energy consumption tracking for commercial structures above 2,000 square meters. Tokyo and Osaka metropolitan areas lead smart city integration of HVAC software with building energy management systems.
India
Urban infrastructure digitization programs under the Smart Cities Mission create first-mover advantages for cloud-native platforms in commercial real estate. Bureau of Indian Standards energy efficiency codes shape procurement specifications for new construction. Bengaluru and Hyderabad technology corridors attract portfolio-scale facility management software deployments.
United Kingdom
Educational institutions accelerate indoor air quality platform adoption following post-pandemic ventilation standard revisions. The EU Green Deal national renovation targets expand addressable demand for software-enabled retrofit planning across commercial building stock. London's commercial property sector consolidates multi-site vendor relationships for simplified service coordination.
Global HVAC Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with diversified industrial conglomerates anchoring enterprise contracts while pure-play software vendors capture mid-market subscription growth. The vendor base organizes around three strategic archetypes: building automation heritage players leveraging installed base relationships, cloud-native challengers attacking subscription economics, and industrial IoT integrators bundling predictive maintenance with sensor hardware. M&A activity concentrates on edge-computing capability acquisition and geographic expansion into India's smart city programs.
Within the building automation heritage tier, Honeywell International Inc. and Johnson Controls International plc exemplify incumbents converting legacy control system relationships into recurring software revenue pools. Siemens AG occupies a position bridging industrial IoT architectures with predictive maintenance modules. These three entities represent how diversified industrial technology portfolios create defensive moats against cloud-native disruption.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Johnson Controls International plc |
| Siemens AG |
| Carrier Global Corporation |
| Trane Technologies plc |
| Lennox International Inc. |
| Mitsubishi Electric Corporation |
| Daikin Industries Ltd. |
| Schneider Electric SE |
| Others |
Supply & Pricing Matrix
Copper and aluminum price indices on the London Metal Exchange cascade through HVAC software supply chains into three-tier pricing structures across premium, standard, and economy levels. Taiwan and South Korean semiconductor fabrication costs transmit directly into edge-computing hardware premiums, while cloud-native SaaS tiers absorb commodity volatility through subscription smoothing.
Pricing Analysis
Volume concentration in mid-market commercial real estate compresses margins, while enterprise data center contracts sustain premium pricing through uptime guarantees. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade—UL-listed fault detection commands 40% premiums over uncertified alternatives—and by after-sales service bundling. Cost compression in economy tiers intensifies because facility managers unbundle predictive maintenance from initial licenses. Small commercial property owners without IT departments exhibit highest price sensitivity; hyperscale data center operators prioritize latency guarantees over cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for integrated building automation platforms, while value-added resellers serve mid-market retrofit projects. Semiconductor supply concentrates in Taiwan, South Korea, and the United States for IoT sensor networks. Edge computing hardware draws from Taiwanese chip fabrication, German industrial control components, and Chinese sensor assemblies. Single-source vulnerability in 7nm chip fabrication creates procurement bottlenecks for real-time optimization nodes. Distribution runs through systems integrators and HVAC contractors who influence software specification during equipment replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
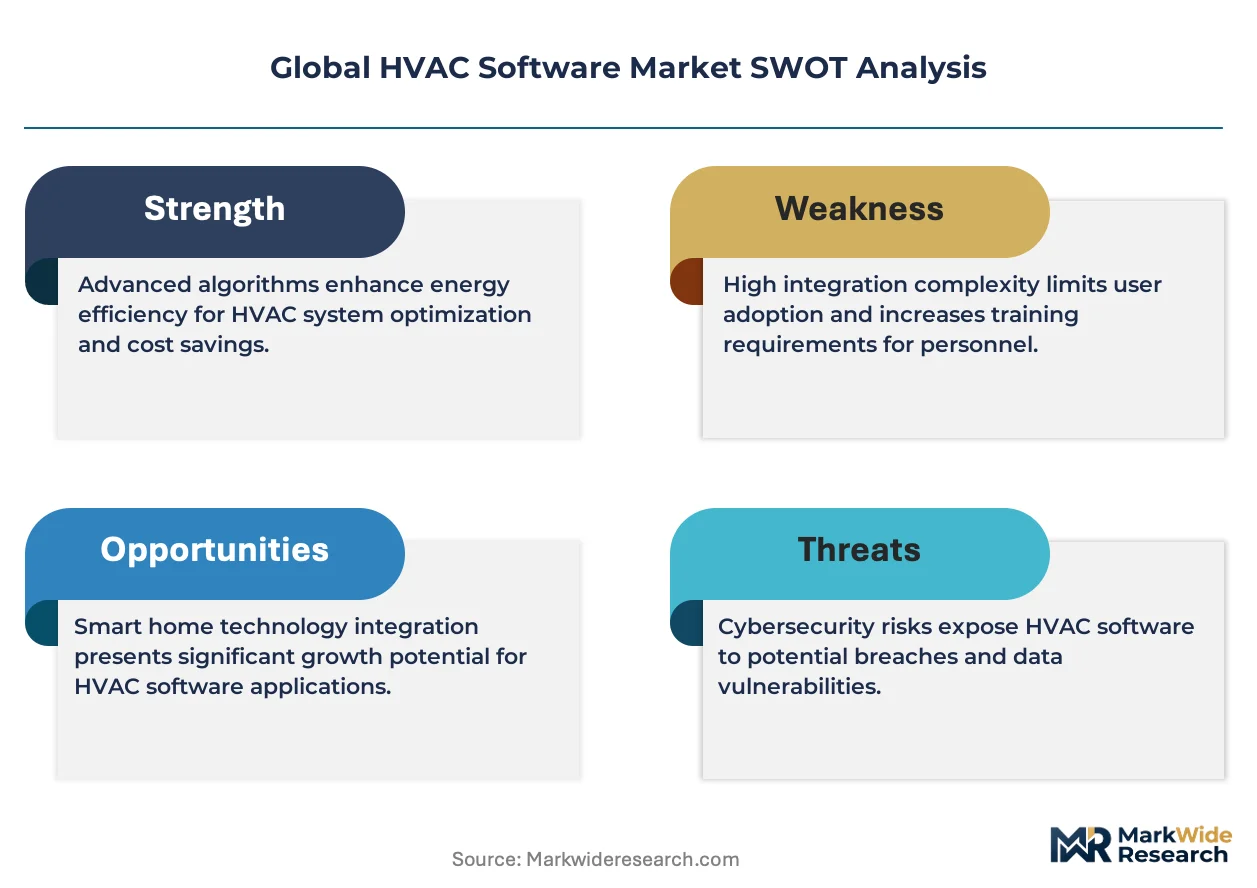
This market operates as a cost-of-compliance arena where EPA Section 608 refrigerant management protocols erect barrier-to-entry moats for vendors with embedded leak detection capabilities.
For Market Incumbents: Cement defensive positions by acquiring edge-computing specialists to address hospital network uptime requirements that cloud-native challengers cannot satisfy. Deepen backward integration into sensor hardware to capture margin pools that third-party service integrators are unbundling from software licenses. Cloud-native entrants threaten mid-market subscription revenue through faster deployment cycles. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany opens a window for compliance-native platforms without legacy BACnet protocol translation burdens. Target India's Smart Cities Mission commercial real estate for first-mover cloud-native deployments. Pursue consultant-led specification channels in UK educational institutions where post-pandemic ventilation standards accelerate procurement. For Investors and Strategic Acquirers: Distressed-cycle entries favor edge-computing hardware specialists with CE marking and Japan's Electrical Appliance and Material Safety Law certifications already secured. Long-term viability hinges on convergence with digital twin architectures for healthcare and laboratory facilities. Watch for AI-driven fault detection algorithm certification timeline compression as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Capability Acquisition | Hospital networks in Germany and Japan prioritize uptime guarantees that cloud architectures cannot deliver. |
| Regulatory Compliance Module Development | EPA Section 608 and EU F-Gas Regulation embed software into federal building contract specifications. |
| Predictive Maintenance Unbundling | Facility managers in German industrial real estate treat maintenance as separate procurement category. |
| Digital Twin Platform Integration | BIM model convergence with live sensor telemetry enables predictive thermal modeling for laboratory facilities. |
| Smart City Geographic Expansion | India's Smart Cities Mission creates first-mover advantages for cloud-native building energy management platforms. |
Research Methodology
Document review covered regulatory filings from EPA and EU ECHA, trade data from customs databases, and SEC disclosures from building automation conglomerates, complemented by interviews with facility managers, energy consultants, HVAC contractors, and platform engineers. Primary fieldwork included discussions with procurement leads at commercial real estate portfolios and technical directors at industrial IoT integrators. Secondary validation drew from BACnet protocol documentation, METI building efficiency standard revisions, and smart city program announcements. Bottom-up deployment model estimates triangulated against top-down market size benchmarks.
Output generation deployed segmentation across deployment architecture, solution type, application vertical, and end-user role, with geographic adoption patterns modeled throughout the forecast period. CAGRs derived from fitted growth curves against retrofit cycle timing and regulatory mandate enforcement schedules. Key inputs included cloud migration timelines, semiconductor supply constraints, and cybersecurity compliance friction in OT-IT convergence.
The model assumes a particular technology adoption path; alternative pathways for edge computing decentralization would alter the outlook if hospital networks accelerate on-premise deployments faster than projected. Forecasts reflect base-case assumptions around regulatory enforcement continuity and supply chain normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Audit Management Software Market
Software & Services
In-Memory Data Grids Software Market
Software & Services
Global Time and Attendance Management Software Market
Software & Services
Global Diagram Software Market
Software & Services
Mobile Backend As a Service (Mbaas) Market
Software & Services
UI Design Software Market
Software & Services
Global Headless CMS Software Market
Software & Services
Europe Database Management Software Market
Software & Services
Content Distribution Software Market
Software & Services
Europe Workforce Management Software Market
Software & Services
Saas for Spa Management Market
Software & Services
Exploration and Production Accounting System Software Market
Software & Services
Spain HR Payroll Software Market
Software & Services
Global Screen and Script Writing Software Market
Software & Services
Channel Management Software Market
Software & Services
Drone Mapping Software Market