
 Germany Sports Nutrition Market | 2026-2036
Germany Sports Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Sports Nutrition Market Foresight
Modular bundling of single-serve sachets with subscription boxes is broadening buyer choice across casual and committed athlete segments. Glanbia plc leverages its dairy protein supply chain to anchor premium powder positioning in German retail. Squeezy Sports Nutrition GmbH competes through gel and bar specialization calibrated to endurance sports demand. PepsiCo Inc extends its beverage distribution muscle into ready-to-drink protein lines stocked in REWE and Edeka outlets.
Germany sports nutrition encompasses formulated consumables—protein isolates, creatine monohydrate, carbohydrate-electrolyte blends, and micronutrient stacks—engineered to support muscle protein synthesis, glycogen replenishment, or recovery acceleration, typically manufactured via spray-drying, extrusion, or cold-pressed bar forming. Protein powders occupy the largest margin pool due to whey and plant-protein ingredient premiums, while energy bars show the fastest structural growth as on-the-go consumption displaces sit-down shaker preparation. Online retail channels now capture the most dynamic volume expansion, though specialty stores retain higher basket values through staff-guided supplement stacking.
BfR (German Federal Institute for Risk Assessment) evaluates novel ingredient safety, while the EU Health Claims Regulation restricts permissible marketing language on muscle-building and recovery promises. KBA has no direct role here; instead, the German Food and Feed Code (LFGB) governs product purity and labeling enforcement by federal state authorities. Stakeholders must monitor pending EU-wide harmonization of caffeine limits in pre-workout formulations and adapt formulation pipelines accordingly.
Market Dynamics
The EU Novel Food Regulation is restructuring ingredient approval pathways, forcing German manufacturers to front-load safety dossiers before launching functional supplements and compressing time-to-market for innovative formulations.
Growth Catalysts
- Fitness Enthusiast Demand:Amateur athletes in Bavaria and North Rhine-Westphalia drive protein powder and energy bar consumption through high gym density and organized sports participation.
- LFGB Compliance Infrastructure:Germany's established enforcement framework under the Food and Feed Code provides clarity on purity standards, reducing regulatory uncertainty for domestic producers.
- Spray-Drying Technology:Advanced manufacturing processes enable whey isolate production with superior solubility, supporting premium positioning in retail channels.
Market Restraints
- Whey Protein Input Volatility:Dairy commodity price swings tied to European milk supply cycles compress margin predictability for powder manufacturers.
- EU Health Claims Regulation:Restricted marketing language on muscle-building promises limits differentiation and forces reliance on ingredient branding rather than outcome messaging.
- Plant Protein Taste Limitations:Pea and rice protein off-notes require expensive flavor masking systems that erode cost advantages versus animal-derived alternatives.
Strategic Opportunities
- Subscription Box Channels:Modular single-serve sachet bundling opens casual athlete segments previously unreachable through bulk powder formats.
- Pre-Workout Caffeine Harmonization:Pending EU-wide caffeine limit standardization creates first-mover advantage for compliant formulation pipelines.
- Cold-Pressed Bar Forming:Clean-label production methods converge with endurance sports demand for minimally processed carbohydrate-electrolyte delivery systems.
Industry Challenges
- Novel Food Dossier Expertise:Shortage of toxicologists capable of assembling BfR-compliant safety packages delays ingredient launches by 18-24 months.
- Legacy Retail Integration:REWE and Edeka shelf-space negotiations require specialized trade marketing functions distinct from direct-to-consumer operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Sports Nutrition Market |
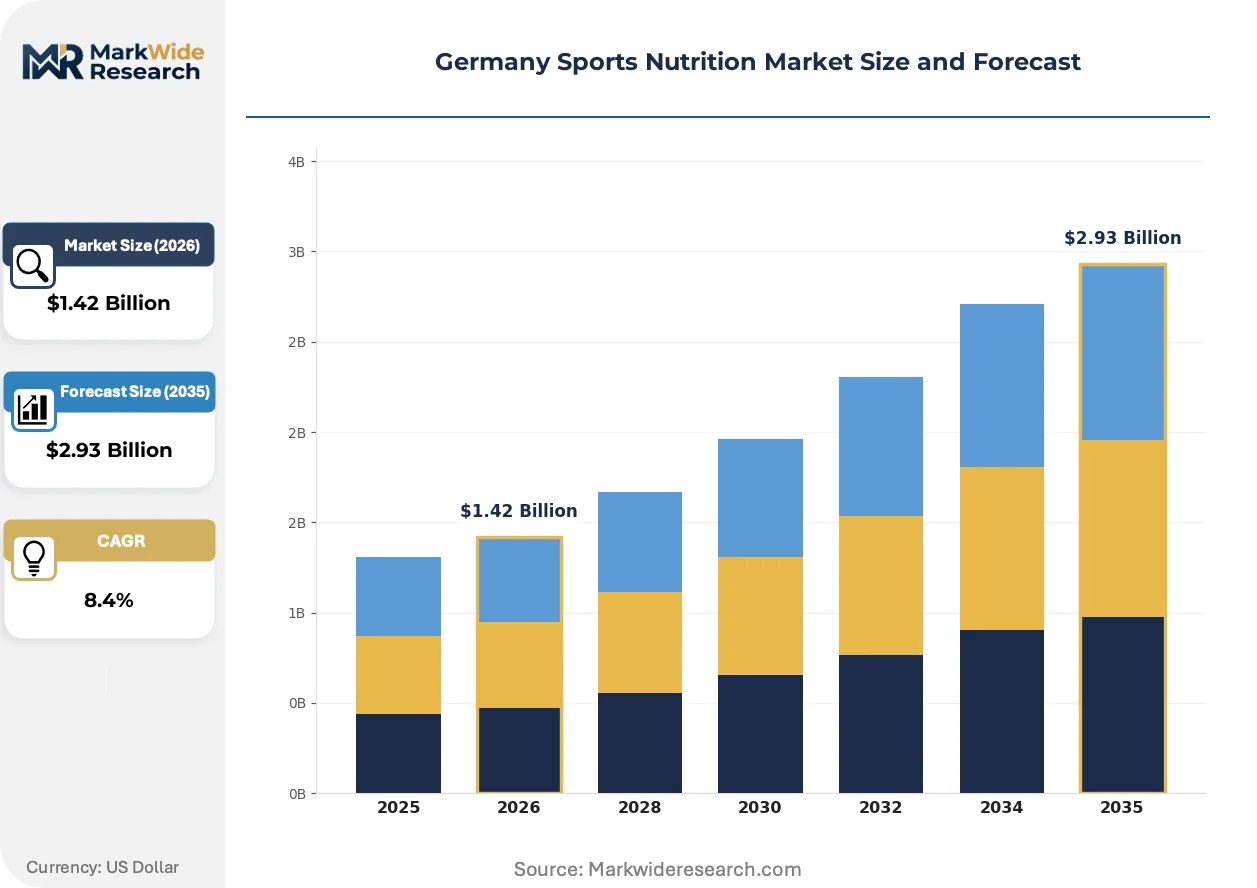
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.93 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Powders, Energy Bars, Meal Replacements, Creatine Supplements End User: Athletes, Fitness Enthusiasts, Recreational Users, Bodybuilders Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Gyms Form: Powder, Bar, Liquid, Capsule |
| Companies Covered | Abbott Laboratories, Clif Bar Company, Glanbia plc, Shop Apotheke, MusclePharm Corporation, PepsiCo Inc, Squeezy Sports Nutrition GmbH, Body Attack Sports Nutrition, Nestle SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Sports Nutrition Market Shifts & Advancements
Formulation science and distribution architecture are converging to reshape how German consumers access performance nutrition, with three distinct vectors altering competitive positioning.
Precision fermentation-derived dairy proteins are overtaking conventional whey isolates in premium positioning. Clean-label athletes in urban centers adopt these bio-identical proteins despite 40-60% price premiums. The technology is compressing reliance on traditional dairy supply chains and enabling allergen-free claims previously unattainable.
BfR's evolving stance on adaptogenic ingredients is tightening safety evaluation timelines for botanical pre-workout additives. Manufacturers must now submit extended toxicity data before market entry, compressing formulation pipelines. The endurance sports segment is responding by pivoting toward mineral-electrolyte stacks with established safety profiles.
Amateur athletes now unbundle supplement purchasing across multiple channels rather than relying on single-source specialty retailers. Online marketplaces capture volume for repeat powder purchases while brick-and-mortar stores retain guided stacking consultations for newcomers. Bavaria's metropolitan clusters exhibit the most pronounced channel fragmentation, with buyers maintaining active carts across three or more platforms simultaneously.
Germany Sports Nutrition Market Segmentation
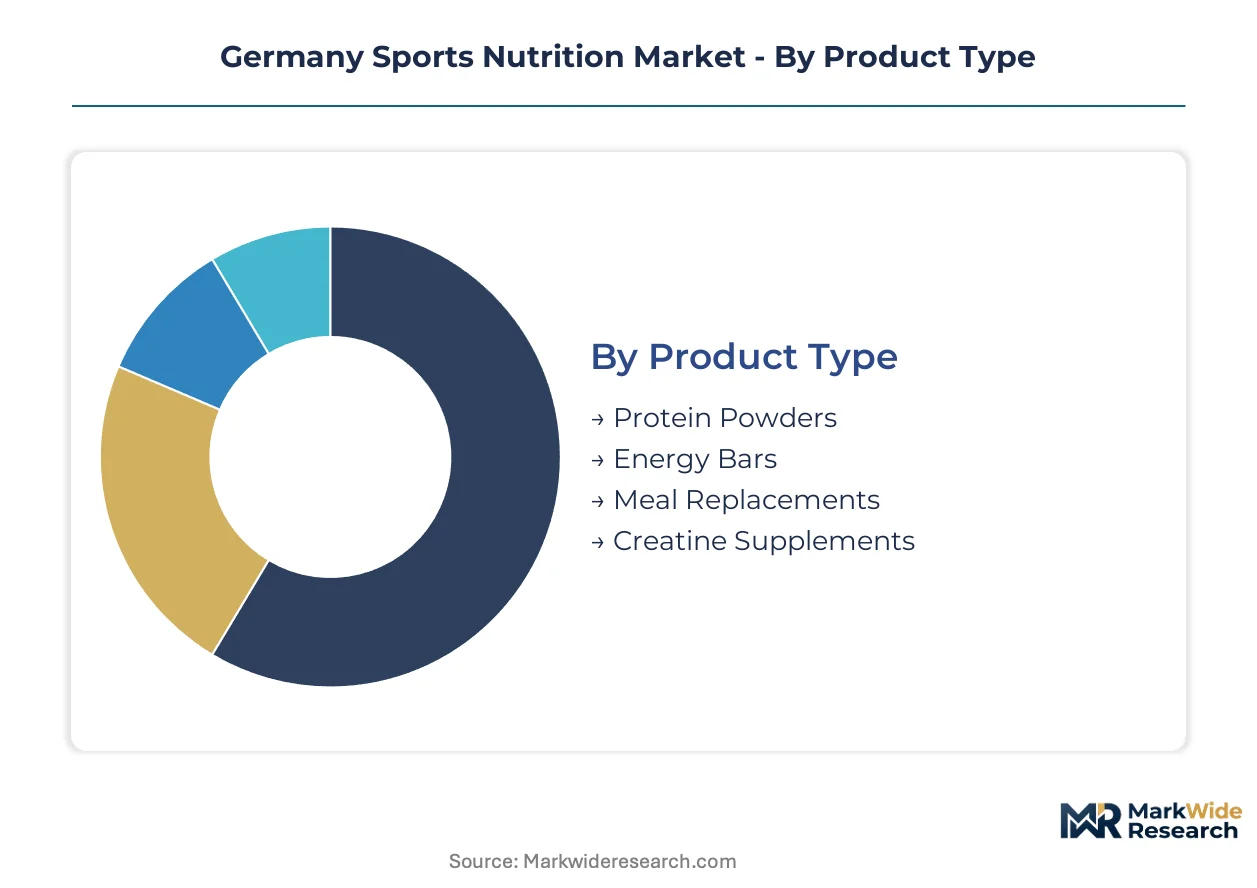
German sports nutrition segmentation reflects divergent athlete maturity levels and channel preferences. Product form and purchase location determine margin capture more than demographic labels alone. Manufacturers must calibrate formulation complexity and packaging format against each segment's technical sophistication.
Product Type:
Standardization dominates mass-market formats while premium tiers embrace ingredient customization and novel delivery systems.
- Protein Powders:Whey isolates and plant-based blends engineered through spray-drying achieve superior solubility. Bavarian gym clusters absorb the highest volumes as amateur athletes prioritize post-workout muscle protein synthesis. Dairy commodity volatility compresses margin predictability for domestic manufacturers.
- Energy Bars:Cold-pressed and extruded formats displace sit-down shaker preparation among time-constrained consumers. North Rhine-Westphalia's endurance sports communities drive demand for carbohydrate-electrolyte delivery with clean-label positioning. Flavor masking costs for plant protein bases erode cost advantages versus animal-derived alternatives.
- Meal Replacements:Micronutrient-fortified powders and RTD beverages target weight management protocols.
- Creatine Supplements:Monohydrate and buffered variants support phosphocreatine replenishment for high-intensity training blocks.
Most installed capacity flows through Protein Powders. Expansion is steepest in Energy Bars.
End User:
Volume concentrates in committed athlete segments while casual participants drive format experimentation and channel fragmentation.
- Fitness Enthusiasts:Amateur athletes with structured training schedules purchase across powder, bar, and liquid formats. Bavaria and North Rhine-Westphalia exhibit highest per-capita consumption through dense gym infrastructure and organized sports participation. Subscription box adoption is broadening reach into previously underpenetrated households.
- Bodybuilders:Competitive and recreational physique athletes demand precise macronutrient tracking and supplement stacking guidance. Specialty store consultations in metropolitan clusters support complex pre-workout and recovery protocols. BfR-compliant novel ingredient access differentiates premium positioning.
- Athletes:Organized sports participants with coaching support follow periodized nutrition programming.
- Recreational Users:Occasional gym visitors and wellness-focused consumers prioritize convenience and taste over performance claims.
Revenue per user peaks with Bodybuilders. User base expansion is climbing the fastest among Fitness Enthusiasts.
Distribution Channel:
Channel selection determines margin structure and customer acquisition cost through divergent service intensity requirements.
- Online Retail:Direct-to-consumer platforms and marketplaces capture repeat powder purchases with lowest per-unit acquisition cost. Bavaria's metropolitan clusters exhibit the most pronounced channel fragmentation, with buyers maintaining active carts across three or more platforms. Modular single-serve sachet bundling opens casual athlete segments unreachable through bulk formats.
- Specialty Stores:Staff-guided supplement stacking commands premium basket values for newcomers navigating complex product matrices. REWE and Edeka negotiations require specialized trade marketing functions distinct from digital operations. In-store expertise justifies margin premiums over mass retail.
- Supermarkets:REWE and Edeka outlets stock ready-to-drink lines leveraging beverage distribution infrastructure.
- Gyms:Point-of-workout placement captures impulse purchases and brand trial among captive audiences.
Volume share is concentrating fastest in Online Retail. Margin per transaction remains highest in Specialty Stores.
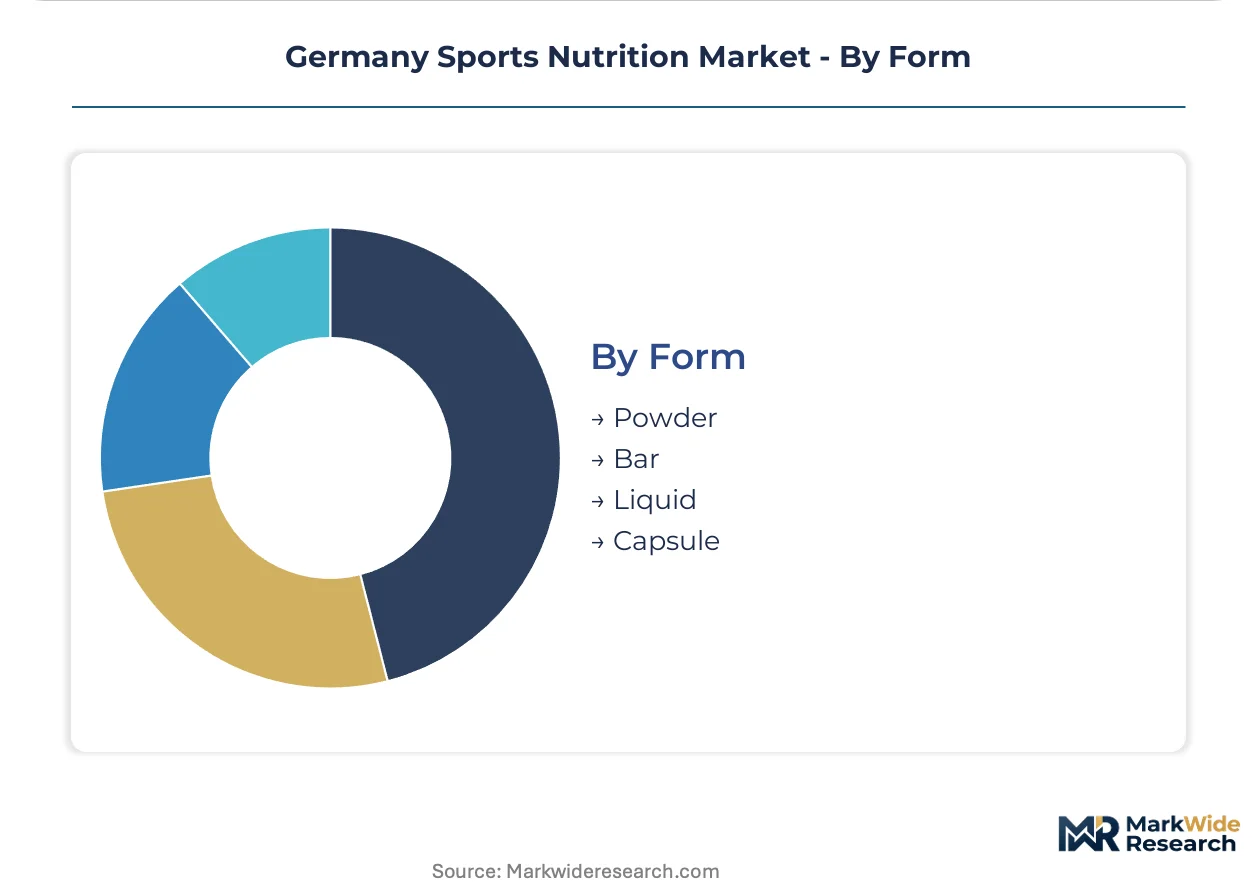
Form:
Manufacturing process selection locks in capital intensity and clean-label positioning simultaneously.
- Powder:Spray-dried isolates and concentrates dominate production scale with established supply chain infrastructure. Precision fermentation-derived alternatives are overtaking conventional whey in premium urban positioning despite substantial price premiums. Allergen-free claims expand addressable market beyond lactose-intolerant consumers.
- Bar:Extrusion and cold-pressed forming enable minimally processed carbohydrate-electrolyte delivery. Endurance sports demand in North Rhine-Westphalia favors portable formats over shaker preparation. Manufacturing flexibility supports rapid flavor rotation and limited-edition releases.
- Liquid:Ready-to-drink protein leverages beverage distribution muscle into mainstream retail placement.
- Capsule:Pre-workout and micronutrient stacks offer precise dosing for advanced supplement protocols.
Production asset base centers on Powder. Capacity addition is accelerating most quickly in Bar formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German sports nutrition manufacturing traces its industrial roots to Bavaria's dairy processing heritage and North Rhine-Westphalia's chemical engineering tradition. These twin foundations established the country's dominance in protein isolation and functional ingredient formulation. Regional specialization now concentrates capacity across five distinct sub-markets.
Bavaria
Munich and Nuremberg anchor Germany's highest gym density per capita, driving protein powder consumption through amateur athlete demand. The Bavarian State Ministry for Health and Food Safety enforces LFGB compliance with particular rigor on dairy-derived supplements. Ingolstadt's precision fermentation startups are overtaking conventional whey suppliers in premium urban positioning.
North Rhine-Westphalia
Cologne and Düsseldorf host endurance sports communities that favor carbohydrate-electrolyte gels and cold-pressed energy bars. The Ministry of Labour, Health and Social Affairs of North Rhine-Westphalia coordinates with BfR on novel ingredient safety evaluations. Dortmund's manufacturing corridor specializes in spray-dried isolate production with superior solubility specifications.
Baden-Württemberg
Stuttgart's fitness enthusiast population demonstrates the strongest subscription box adoption rates for modular single-serve sachets. The Regional Council Stuttgart oversees food purity enforcement under delegated federal authority. Mannheim's chemical parks supply flavor masking systems for plant protein bases.
Hesse
Frankfurt's metropolitan cluster exhibits the most pronounced channel fragmentation, with buyers maintaining active carts across three or more platforms simultaneously. The Hessian Ministry for Social Affairs and Integration monitors EU Health Claims Regulation compliance in marketing materials. Darmstadt's ingredient suppliers specialize in micronutrient premixes for meal replacement formulations.
Berlin-Brandenburg
Berlin's wellness-focused consumers prioritize convenience and taste over performance claims, expanding the recreational user segment. The Berlin Senate Department for Health implements caffeine limit surveillance in pre-workout formulations pending EU harmonization. Potsdam's logistics hubs service direct-to-consumer powder shipments throughout eastern Germany.
Germany Sports Nutrition Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and channel access. Dairy-derived protein specialists command ingredient branding premiums while beverage distribution networks capture mass-market ready-to-drink volume. Three archetypes dominate: integrated dairy processors with captive whey supply, endurance sports gel specialists with calibrated carbohydrate-electrolyte expertise, and multinational beverage distributors leveraging retail shelf-space negotiations. Competitive moves concentrate on subscription box channel development and precision fermentation technology licensing.
Within the integrated dairy processor tier, Glanbia plc exemplifies supply chain anchoring through its whey isolate positioning. PepsiCo Inc represents beverage distribution muscle extending into protein-enhanced ready-to-drink lines. Squeezy Sports Nutrition GmbH occupies the endurance sports specialist position with gel and bar calibration expertise. These three entities collectively illustrate how German market access depends on divergent capability combinations rather than scale alone.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Clif Bar Company |
| Glanbia plc |
| Shop Apotheke |
| MusclePharm Corporation |
| PepsiCo Inc |
| Squeezy Sports Nutrition GmbH |
| Body Attack Sports Nutrition |
| Nestle SA |
| Others |
Supply & Pricing Matrix
Amateur athletes in Bavaria and North Rhine-Westphalia anchor demand concentration, enabling manufacturers to deploy subscription-based pricing with modular single-serve sachet bundling that captures casual participants while preserving premium powder margins for committed users.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the German market, with precision fermentation-derived proteins commanding substantial premiums over conventional whey isolates. Price differentiation rests on ingredient sourcing transparency and BfR novel food compliance status. Cost compression in the standard tier is intensifying because dairy commodity volatility squeezes domestic manufacturers. Recreational users in Berlin-Brandenburg exhibit highest price sensitivity, while bodybuilders in metropolitan specialty store clusters accept substantial premiums for staff-guided stacking protocols.
Supply Chain Analysis
Whey protein concentrate supply rests on Irish and Dutch dairy processing infrastructure, with precision fermentation inputs drawing from German and Danish biotech facilities. Plant protein bases—pea isolates from France and rice protein from Spain—require expensive Mannheim-sourced flavor masking systems. Single-source vulnerability concentrates in novel ingredient toxicology dossier preparation, where qualified BfR-compliant assessors remain scarce. Distribution runs through REWE and Edeka beverage networks for ready-to-drink lines, while direct-to-consumer platforms capture powder repeat purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
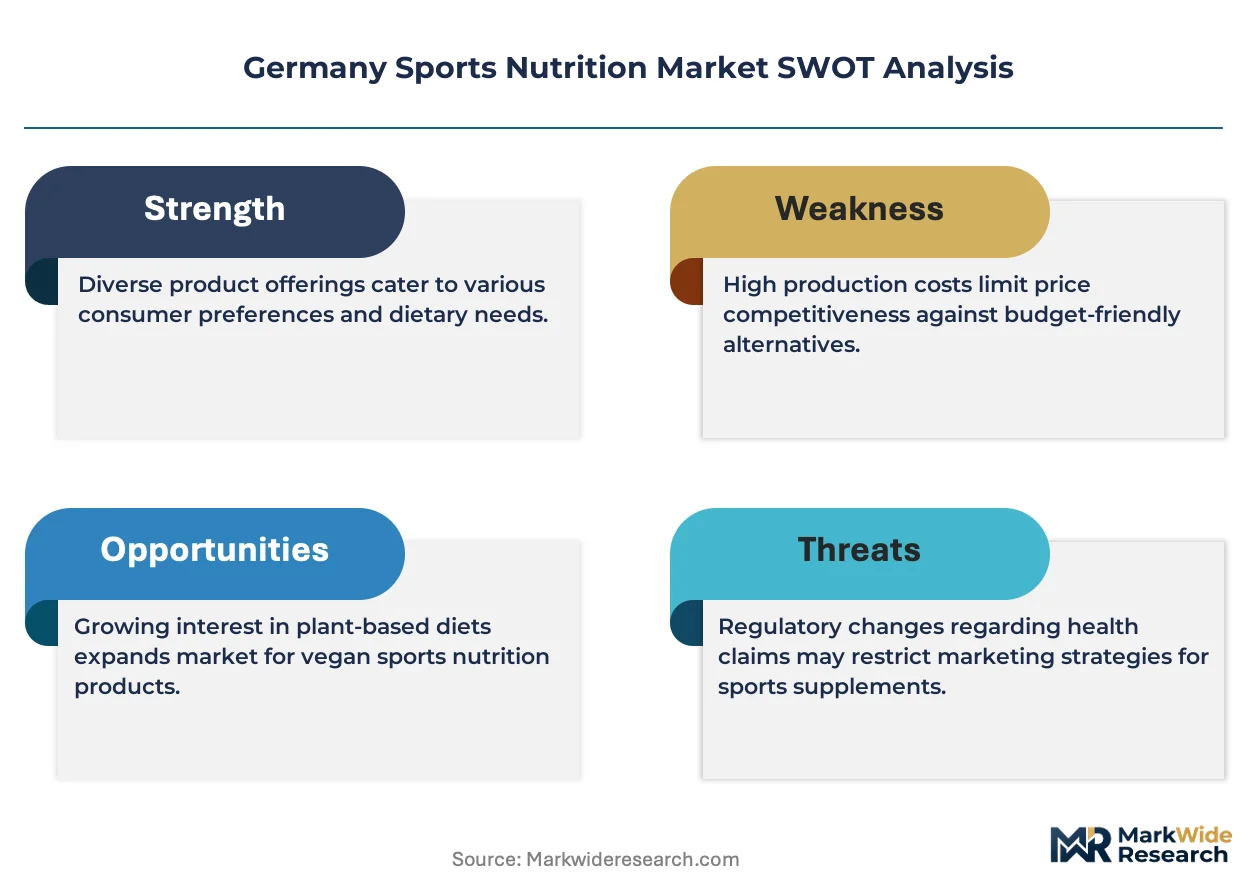
The German sports nutrition market functions as a regulatory-arbitrage play, where domestic LFGB enforcement clarity reduces compliance cost uncertainty versus jurisdictions with fragmented federal-state food safety oversight.
For Market Incumbents: To counter precision fermentation startups overtaking conventional whey positioning, Glanbia plc and integrated dairy processors should secure captive supply contracts with Ingolstadt biotech facilities while expanding BfR dossier preparation capabilities in-house to compress novel ingredient launch timelines. For New Entrants and Emerging Players: Precision fermentation technology licensing offers entry into premium urban positioning without legacy dairy supply chain dependence. White-space targets include subscription box sachet bundling for Baden-Württemberg fitness enthusiasts and clean-label cold-pressed bar formats for North Rhine-Westphalia endurance communities, with direct-to-consumer platforms as the preferred go-to-market angle. For Investors and Strategic Acquirers: Beverage multinationals are the most active acquirer in this space, seeking ready-to-drink distribution synergies. Long-term viability hinges on EU-wide caffeine limit harmonization completion and adaptogenic ingredient safety clearance trajectories. Acquisition target archetypes include endurance sports gel specialists with calibrated carbohydrate-electrolyte expertise and precision fermentation technology licensors. The signal to watch is BfR staffing expansion for novel food evaluation capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Licensing | Enables allergen-free protein claims without traditional dairy supply chain exposure. |
| Subscription Box Channel Development | Captures casual athlete segments unreachable through bulk powder retail formats. |
| BfR Dossier Capability Buildout | Compresses novel ingredient launch timelines by 18-24 months versus outsourced preparation. |
| Cold-Pressed Bar Manufacturing Expansion | Aligns production capacity with clean-label endurance sports demand in North Rhine-Westphalia. |
| REWE and Edeka Trade Marketing Investment | Secures shelf-space for ready-to-drink lines leveraging existing beverage distribution infrastructure. |
Research Methodology
Multiple input streams — primary interviews with sports nutrition brand managers, supplement formulation scientists, and REWE category buyers; secondary validation through BfR safety assessment filings, EU Novel Food Regulation databases, and LFGB enforcement records; customs and trade data on whey protein concentrate flows — were reconciled through bottom-up segment sizing and top-down market reconciliation.
Historical consumption patterns were cross-referenced against panel input from Bavarian gym operators and North Rhine-Westphalia endurance sports retailers. The analytical framework modeled product type, end user maturity tier, distribution channel, and manufacturing process form across the projection horizon. CAGRs were derived from segment-level trajectory blending, with inputs including spray-drying capacity utilization rates and precision fermentation technology adoption curves.
The model holds under stable EU regulatory harmonization timelines; deviation in BfR staffing levels or dairy commodity price volatility would shift launch cadence and margin projections. A small set of named triggers — EU caffeine limit finalization, novel food dossier approval velocity, and subscription box churn rates — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Caloric Supplements Market
Sports Nutrition
Middle East and Africa Sports Nutrition Market
Sports Nutrition
UK Sports Nutrition Market
Sports Nutrition
Active Nutrition Market
Sports Nutrition
Caloric Test Market
Sports Nutrition
Europe Weight Management Supplement Market
Sports Nutrition
Pre-Workout Supplements Market
Sports Nutrition
China Sports Drink Market
Sports Nutrition
Androstenedione Market
Sports Nutrition
Europe Protein Based Sports Drinks Market
Sports Nutrition
Global Ketone Supplements Market
Sports Nutrition
Arginine Supplement Market
Sports Nutrition
Weight Management Products Market
Sports Nutrition
Creatine Monohydrate Market
Sports Nutrition
North America Sports Nutrition Market
Sports Nutrition
United Kingdom Sports Drink Market