
 Caloric Test Market | 2026-2036
Caloric Test Market Size, Share, and Industry Trends Forecast 2026-2036
Caloric Test Market Outlook
ISO 13485 certification is rotating toward a decisive gatekeeping role for caloric test device manufacturers seeking market access in regulated jurisdictions. Natus Medical Incorporated leverages its vertically integrated manufacturing footprint across North American and European distribution channels. Interacoustics A/S anchors its competitive stance through deep specialization in audiometric and vestibular diagnostic platforms. Micromedical Technologies, Inc. differentiates by sustaining concentrated R&D investment in portable caloric stimulation systems.
Caloric testing employs thermal or air-based stimulation of the external auditory canal to induce nystagmus, with electronystagmography or videonystagmography recording eye movement responses at precision thresholds of 0.5 to 2 degrees per second. The procedure serves primarily to isolate peripheral vestibular lesions, distinguish central from peripheral vertigo origins, and quantify unilateral or bilateral vestibular hypofunction in clinical settings. Diagnostic systems command the largest revenue pool among product types, reflecting bundled hardware-software configurations that lock in recurring calibration and maintenance service contracts. ENT clinics represent the fastest-growing end-user channel, driven by ambulatory care migration and specialist consolidation in urban healthcare networks. Vestibular disorders maintain the dominant application share, though neurological research applications are gaining traction as academic medical centers expand protocol-driven studies.
FDA 510(k) premarket notification requirements and EU MDR technical documentation obligations shape device development timelines and commercialization costs for manufacturers targeting transatlantic markets. Japan's PMDA and South Korea's MFDS impose additional clinical evidence standards that filter market entrants and elevate quality benchmarks for approved systems. Stakeholders must monitor evolving notified body capacity constraints under MDR implementation and calibrate regulatory submission strategies accordingly.
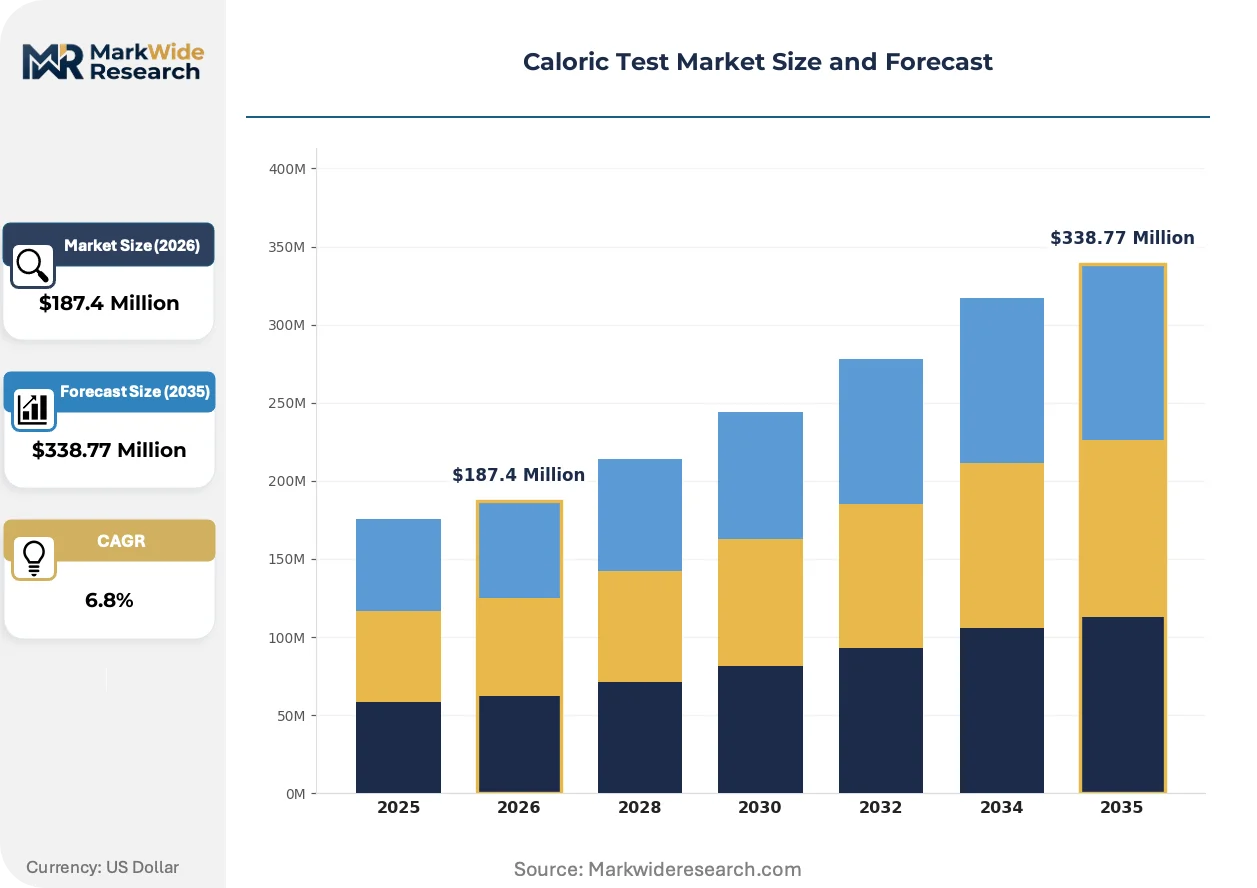
Market Dynamics
ISO 13485 certification under EU MDR and FDA 510(k) pathways is compressing commercialization timelines and elevating capital requirements for caloric test device manufacturers seeking transatlantic market access.
Growth Catalysts
- EU MDR technical documentation:Stricter CE marking requirements under the EU Medical Device Regulation are filtering low-quality competitors and elevating price realizations for certified manufacturers.
- Ambulatory ENT clinics:Specialist consolidation in urban healthcare networks across Germany and the United States is expanding point-of-care diagnostic capacity for vertigo assessment.
- Videonystagmography precision thresholds:Advances in eye-tracking sensitivity to 0.5 degrees per second are improving diagnostic confidence and protocol standardization in vestibular laboratories.
Market Restraints
- Notified body capacity constraints:EU MDR implementation bottlenecks are extending certification timelines by 12-18 months for novel caloric stimulation systems.
- Single-source thermal probe suppliers:Concentrated manufacturing of precision temperature-controlled delivery systems in select European jurisdictions creates supply vulnerability.
- Air calorimetry substitution:Non-thermal alternatives for vestibular assessment are capturing protocol share in pediatric and sensitive-patient populations.
Strategic Opportunities
- South Korea MFDS pathway:Streamlined approval processes for Class II diagnostic devices are opening accelerated market entry for compliant manufacturers.
- Neurological research protocols:Academic medical centers in Japan and the United Kingdom are expanding protocol-driven studies beyond clinical vertigo diagnosis.
- Portable system convergence:Integration of wireless data transmission with tablet-based visualization is enabling remote vestibular assessment in rural healthcare networks.
Industry Challenges
- Electronystagmography technician certification:Specialized training requirements for precise electrode placement and artifact interpretation are constraining workforce scalability.
- Legacy system interoperability:Integration of modern air-based caloric stimulators with hospital information systems requires customized middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caloric Test Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Caloric Testing Equipment, Diagnostic Systems, Reference Standards, Analyzers Application: Vestibular Disorders, Balance Assessment, Hearing Evaluation, Neurological Research End User: Hospitals, Diagnostic Laboratories, Research Institutions, ENT Clinics Service Type: Consultation Services, Training & Support, Maintenance Services, Calibration Services |
| Companies Covered | Natus Medical Incorporated, Micromedical Technologies, Inc., Interacoustics A/S, Beijing Jingjing Medical Equipment Co., Ltd., Neurosoft Ltd., GN Otometrics, Intelligent Hearing Systems, Otopront Medical GmbH, Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caloric Test Market Strategic Shifts
Device architecture is pivoting toward portability and connectivity, while regulatory frameworks on both sides of the Atlantic are hardening quality benchmarks and reshaping competitive qualification.
Wireless caloric stimulators with integrated temperature feedback loops are replacing tethered thermal irrigation systems in outpatient settings. ENT clinics in Germany and the United States are adopting these platforms to reduce patient preparation time and enable bedside assessment. The form factor is miniaturizing from cart-based laboratory equipment to handheld units that fit ambulatory care workflows.
FDA 510(k) premarket notification requirements are tightening clinical evidence standards for novel stimulation modalities. Manufacturers must now submit comparative effectiveness data against predicate devices, extending development timelines and documentation costs. Class II diagnostic device submissions for air-based systems face particular scrutiny in the United States.
Service contract unbundling is separating hardware procurement from calibration and maintenance agreements. Hospital-based vestibular laboratories in Japan and South Korea are negotiating standalone software subscriptions and remote diagnostic support. This purchasing pattern shift is most pronounced in academic medical centers with centralized biomedical engineering departments.
Caloric Test Market Segmentation
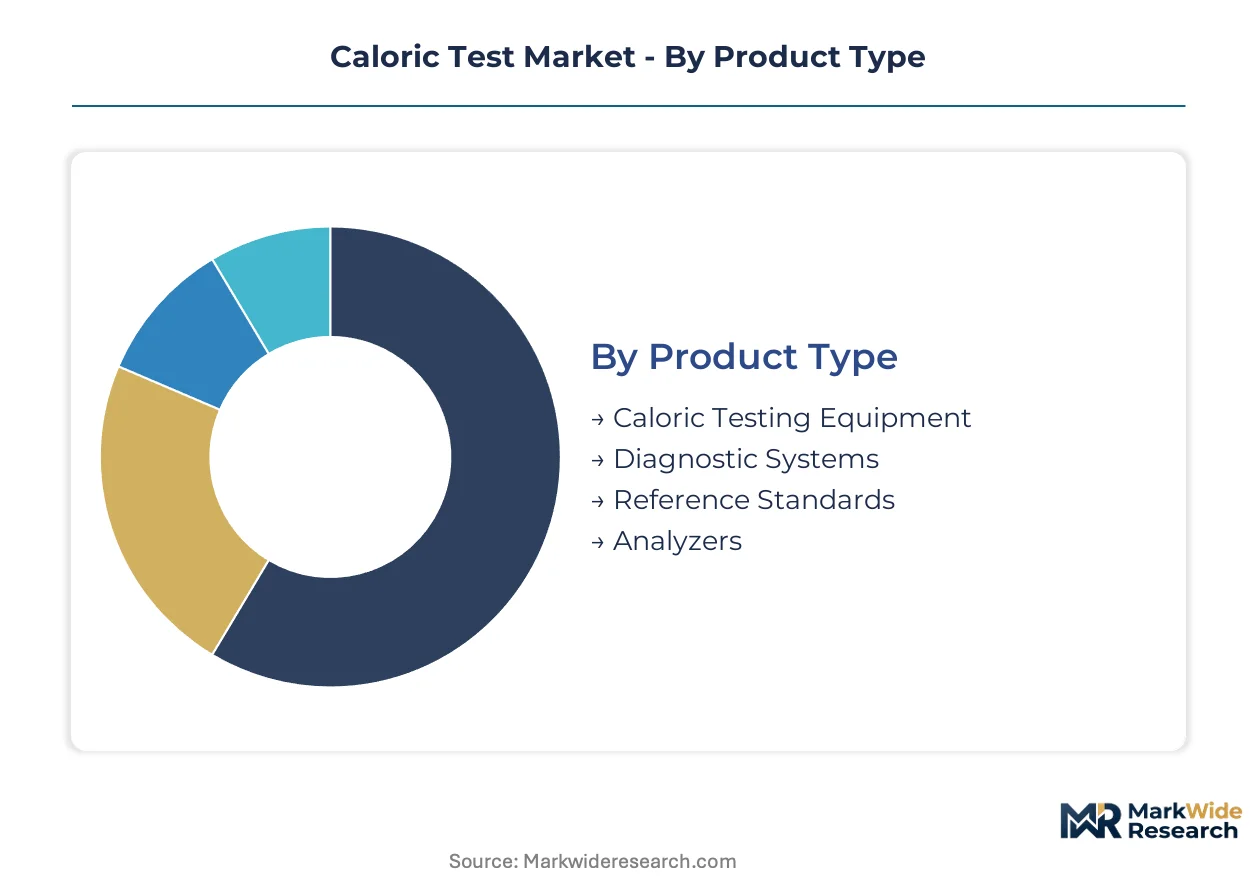
Caloric test market segmentation reveals divergent vulnerability to air calorimetry substitution and videonystagmography displacement across hardware, service, and end-use categories. Equipment manufacturers and service providers must align portfolio investments with segments showing durable protocol integration versus those facing rapid modality erosion.
Product Type:
Diagnostic systems face the most acute substitution pressure from compact air-based stimulators, while reference standards maintain defensive positioning through regulatory tethering to calibration protocols.
- Diagnostic Systems:Bundled hardware-software configurations integrate electronystagmography or videonystagmography recording with thermal irrigation modules. Demand concentrates in hospital-based vestibular laboratories across Japan and South Korea, where bundled service contracts lock in recurring revenue streams and resist unbundling pressures from procurement departments.
- Caloric Testing Equipment:Standalone thermal stimulators and irrigation systems deliver precision temperature-controlled water or air to the external auditory canal. ENT clinics in Germany and the United States are expanding adoption of portable variants, though tethered laboratory systems retain dominance in academic medical centers with centralized biomedical engineering support.
- Analyzers:Signal processing units interpret nystagmus recordings at precision thresholds down to 0.5 degrees per second.
- Reference Standards:Certified calibration devices maintain traceability to national metrology institutes for temperature and flow accuracy verification.
Diagnostic systems anchor the volume base while caloric testing equipment gains share at the steepest rate.
Application:
Margin structures vary sharply across clinical versus research applications, with vestibular disorder diagnosis commanding premium pricing and neurological research showing volume elasticity tied to grant funding cycles.
- Vestibular Disorders:Primary clinical application isolates peripheral vestibular lesions and quantifies unilateral or bilateral hypofunction through standardized caloric irrigation protocols. Demand concentrates in ENT clinics across urban healthcare networks in the United States and Germany, where ambulatory care migration and specialist consolidation expand point-of-care diagnostic capacity.
- Neurological Research:Protocol-driven studies at academic medical centers in Japan and the United Kingdom apply caloric stimulation to investigate central nervous system pathways beyond traditional vertigo diagnosis. MFDS and PMDA clinical evidence standards filter market entrants and elevate quality benchmarks for approved research-grade systems.
- Balance Assessment:Complementary testing within comprehensive fall-risk evaluation protocols.
- Hearing Evaluation:Adjunct diagnostic procedure within audiological workups for suspected cochleovestibular pathologies.
Vestibular disorders dominate revenue contribution while neurological research climbs the fastest.
End User:
Procurement authority and service integration requirements create distinct customer archetypes, with hospitals prioritizing system interoperability and ENT clinics emphasizing workflow efficiency.
- ENT Clinics:Ambulatory specialist practices require compact, portable systems with reduced patient preparation time. Urban healthcare networks in Germany and the United States are consolidating independent practices into multi-site groups, standardizing equipment procurement across pooled purchasing organizations.
- Hospitals:Integrated delivery networks demand middleware compatibility with hospital information systems and centralized biomedical engineering support for maintenance contracts. Vestibular laboratories in Japan and South Korea negotiate standalone software subscriptions and remote diagnostic support.
- Diagnostic Laboratories:Independent testing facilities serving referring physician networks.
- Research Institutions:Academic medical centers with protocol-driven study requirements and grant-dependent capital expenditure cycles.
Hospitals anchor the volume base while ENT clinics expand most quickly.
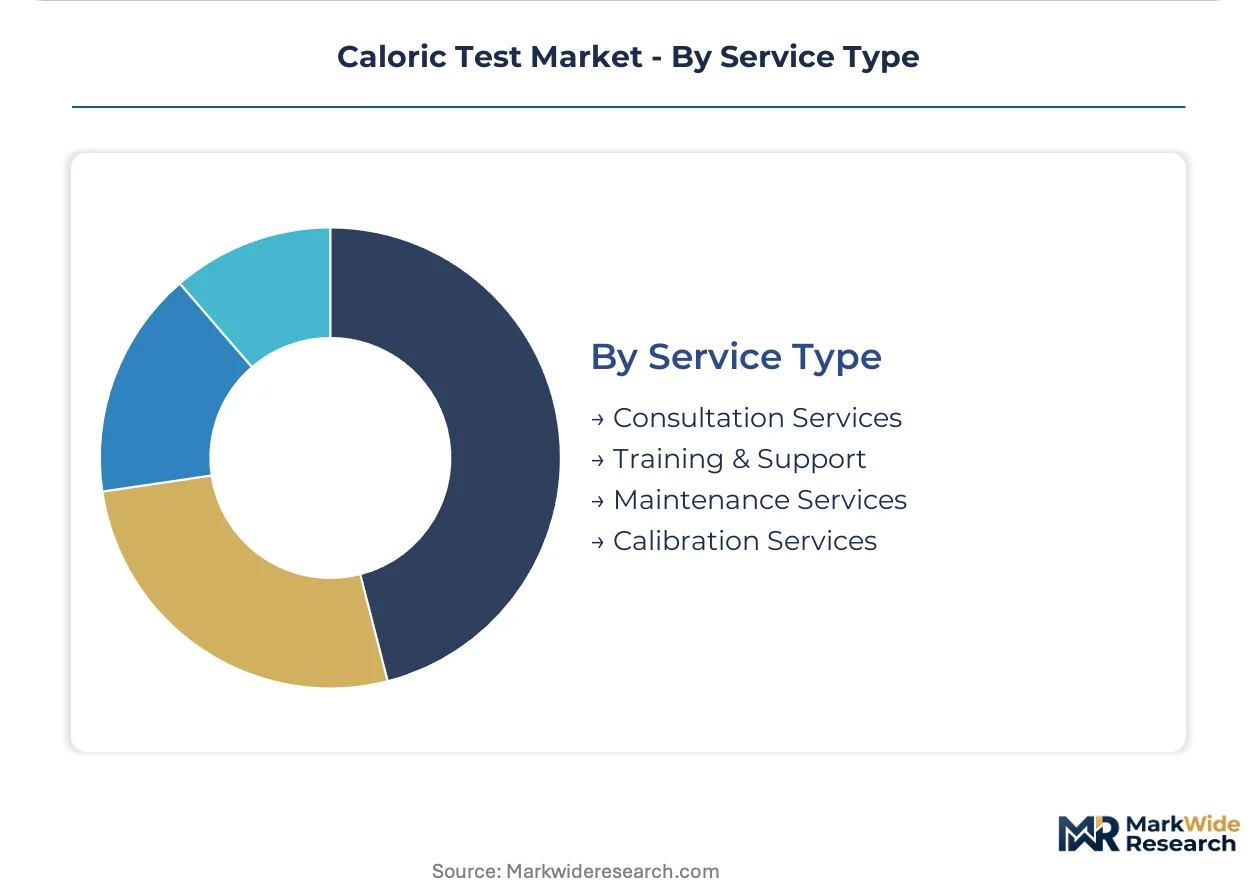
Service Type:
Unbundling trends separate hardware procurement from recurring service agreements, with calibration and maintenance contracts facing margin pressure from in-house biomedical engineering capabilities.
- Maintenance Services:Preventive and corrective service contracts for thermal probe replacement, irrigation line integrity, and temperature control module verification. Hospital-based vestibular laboratories in Japan with centralized biomedical engineering departments are insourcing routine maintenance, compressing third-party service margins.
- Calibration Services:Traceable verification of temperature accuracy, flow rate, and timing precision against reference standards. EU MDR technical documentation obligations and FDA 510(k) quality system requirements mandate documented calibration intervals, sustaining demand despite unbundling pressures.
- Training & Support:Technician certification programs for electronystagmography electrode placement and artifact interpretation.
- Consultation Services:Clinical protocol optimization and workflow design for new laboratory installations.
Calibration services anchor the volume base while maintenance services face the steepest share erosion from in-house capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways in the United States and CE marking obligations under EU MDR are compressing commercialization timelines for caloric test device manufacturers seeking transatlantic market access. Japan's PMDA and South Korea's MFDS impose parallel clinical evidence standards that filter market entrants and elevate quality benchmarks for approved systems.
United States
ENT clinics across urban healthcare networks are consolidating into multi-site specialist groups, standardizing equipment procurement through pooled purchasing organizations. FDA 510(k) premarket notification requirements for Class II diagnostic devices mandate comparative effectiveness data against predicate devices. Hospital-based vestibular laboratories in Greater Boston and the Pacific Northwest negotiate standalone software subscriptions and remote diagnostic support.
Germany
Ambulatory care migration and specialist consolidation in urban healthcare networks are expanding point-of-care diagnostic capacity for vertigo assessment. CE marking under EU MDR technical documentation obligations shapes device development timelines and commercialization costs for manufacturers targeting European markets. ENT clinics in Bavaria and North Rhine-Westphalia are adopting portable caloric stimulation systems to reduce patient preparation time.
Japan
Academic medical centers are expanding protocol-driven studies beyond clinical vertigo diagnosis into neurological research applications. PMDA clinical evidence standards for medical devices filter market entrants and elevate quality benchmarks for approved research-grade systems. Vestibular laboratories in Tokyo and Osaka maintain demand for bundled hardware-software configurations with recurring calibration contracts.
South Korea
Streamlined MFDS approval processes for Class II diagnostic devices are opening accelerated market entry for compliant manufacturers. Hospital procurement departments are negotiating service contract unbundling, separating hardware procurement from calibration and maintenance agreements. Seoul-based vestibular laboratories are insourcing routine maintenance, compressing third-party service margins.
United Kingdom
Academic medical centers are applying caloric stimulation to investigate central nervous system pathways beyond traditional vertigo diagnosis. EU MDR implementation bottlenecks are extending certification timelines for novel caloric stimulation systems entering the British market. Research institutions in London and the Midlands are expanding grant-dependent capital expenditure cycles for protocol-driven studies.
Caloric Test Market Competitive Environment
Player mix skews toward vertically integrated diagnostic platform specialists and portable system innovators. The vendor base concentrates around manufacturers with captive audiometric and vestibular diagnostic expertise. Two strategic archetypes dominate: integrated platform providers bundling hardware-software-service configurations, and portability-focused specialists miniaturizing form factors for ambulatory workflows. Competitive moves center on regulatory pre-clearance investments and service contract unbundling resistance.
Among North American and European platform providers, Natus Medical Incorporated and Interacoustics A/S exemplify the integrated diagnostic archetype, occupying positions that leverage vertically integrated manufacturing footprints across transatlantic distribution channels. Micromedical Technologies, Inc. represents the portable innovation vector, sitting within a specialization tier concentrated on wireless data transmission and tablet-based visualization for remote vestibular assessment. Beijing Jingjing Medical Equipment Co., Ltd. anchors the Asia-Pacific manufacturing cluster, reflecting regional production gravity for precision temperature-controlled delivery systems.
| Leading Market Players |
|---|
| Natus Medical Incorporated |
| Micromedical Technologies, Inc. |
| Interacoustics A/S |
| Beijing Jingjing Medical Equipment Co., Ltd. |
| Neurosoft Ltd. |
| GN Otometrics |
| Intelligent Hearing Systems |
| Otopront Medical GmbH |
| Medtronic plc |
| Others |
Value Chain & Pricing Dynamics
Air calorimetry substitution for thermal irrigation systems is redrawing supply geography toward compact electronics manufacturers in East Asia while compressing pricing premiums historically commanded by precision temperature-controlled water delivery modules.
Pricing Analysis
Certification level creates the primary spread across ISO 13485, FDA 510(k)-cleared, and CE-marked tiers under EU MDR. Three-tier pricing structure across premium, standard, and economy levels bundles hardware-software configurations with calibration service contracts at the top tier. Cost compression in standard-tier diagnostic systems intensifies because ENT clinics in Germany and the United States negotiate unbundled procurement. Hospital-based vestibular laboratories in Japan show least price sensitivity due to centralized biomedical engineering budgets.
Supply Chain Analysis
Precision temperature sensor fabrication in Germany, Switzerland, and Japan anchors component availability for thermal probe assemblies. Manufacturing draws from specialized thermistor substrates, medical-grade silicone tubing, and microprocessor-controlled flow valves. Single-source vulnerability concentrates in European suppliers of calibrated thermal delivery modules. Distribution runs through regional medical device distributors with ISO 13485-certified warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service contract unbundling has accelerated faster than hardware shipment growth, making aftermarket calibration and remote diagnostic support the decisive margin layer for sustainable revenue architecture.
For Market Incumbents: Compound defensive positioning by integrating backward into precision temperature sensor production and expanding captive calibration laboratory networks across North America and Europe. Air calorimetry substitution threatens thermal irrigation margins, requiring certification investment in wireless stimulation platforms to preserve hospital system relationships.
For New Entrants and Emerging Players: South Korea's MFDS streamlined pathway for Class II diagnostic devices offers fastest regulatory traction against EU MDR bottlenecks. Target portable system convergence for rural healthcare networks in the United States and Germany where incumbent service coverage remains sparse. Lead with tablet-based visualization and wireless data transmission as the primary go-to-market wedge.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated diagnostic platform specialists with captive audiometric expertise. Five-to-ten-year viability hinges on recurring service attach rates exceeding hardware replacement cycles. Watch notified body capacity constraints under EU MDR as the inflection signal for acquisition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | CE marking under tightened notified body standards filters low-quality competitors and elevates price realizations. |
| Portable System Wireless Integration | Tablet-based visualization enables remote vestibular assessment in rural German and US healthcare networks. |
| Calibration Service Laboratory Expansion | Standalone software subscriptions lock in recurring revenue from hospital-based vestibular laboratories in Japan. |
| MFDS Regulatory Fast-Track Utilization | Streamlined South Korean approval accelerates market entry against EU MDR timeline compression. |
| Neurological Research Protocol Development | Academic medical centers in the United Kingdom and Japan expand grant-dependent capital expenditure cycles. |
Study Parameters
The analysis maps diagnostic systems, caloric testing equipment, analyzers, and reference standards, each validated through biomedical engineers, ENT clinic procurement officers, hospital purchasing committee members, and regulatory affairs specialists at notified bodies. Primary interview data triangulates against FDA 510(k) premarket notification databases, EU MDR technical documentation filings, PMDA and MFDS device registration records, and hospital procurement contract repositories. Bottom-up unit economics and top-down market sizing converge through iterative validation.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions include product type, application, end user, and service type with geographic regulatory cluster overlays. CAGRs derive from modeled unit shipments and realized pricing by tier. Industry-specific inputs incorporate notified body capacity constraints, air calorimetry substitution rates, and ENT clinic consolidation patterns.
Decision-makers should treat outputs as directional under stable regulatory enforcement and ambulatory care migration assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EU MDR implementation bottlenecks and thermal probe supply concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Active Nutrition Market
Sports Nutrition
Brazil Sports Nutrition Market
Sports Nutrition
L-Carnitine Supplements Market
Sports Nutrition
Creatine Market
Sports Nutrition
South America Sports Nutrition Market
Sports Nutrition
Creatine Monohydrate Market
Sports Nutrition
Europe Protein Bar Market
Sports Nutrition
GCC Sports Nutrition Market
Sports Nutrition
Weight Management Supplements Market
Sports Nutrition
United States Weight Management Market
Sports Nutrition
Global Gummy Supplements Market
Sports Nutrition
Taurine Supplements Market
Sports Nutrition
North America Sports Nutrition Market
Sports Nutrition
B2B Sports Nutrition Market
Sports Nutrition
GLA Supplements Market
Sports Nutrition
Sports Hydration Market