
 Japan Mortgage/Loan Brokers Market | 2026-2036
Japan Mortgage/Loan Brokers Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Mortgage/Loan Brokers Market Insights
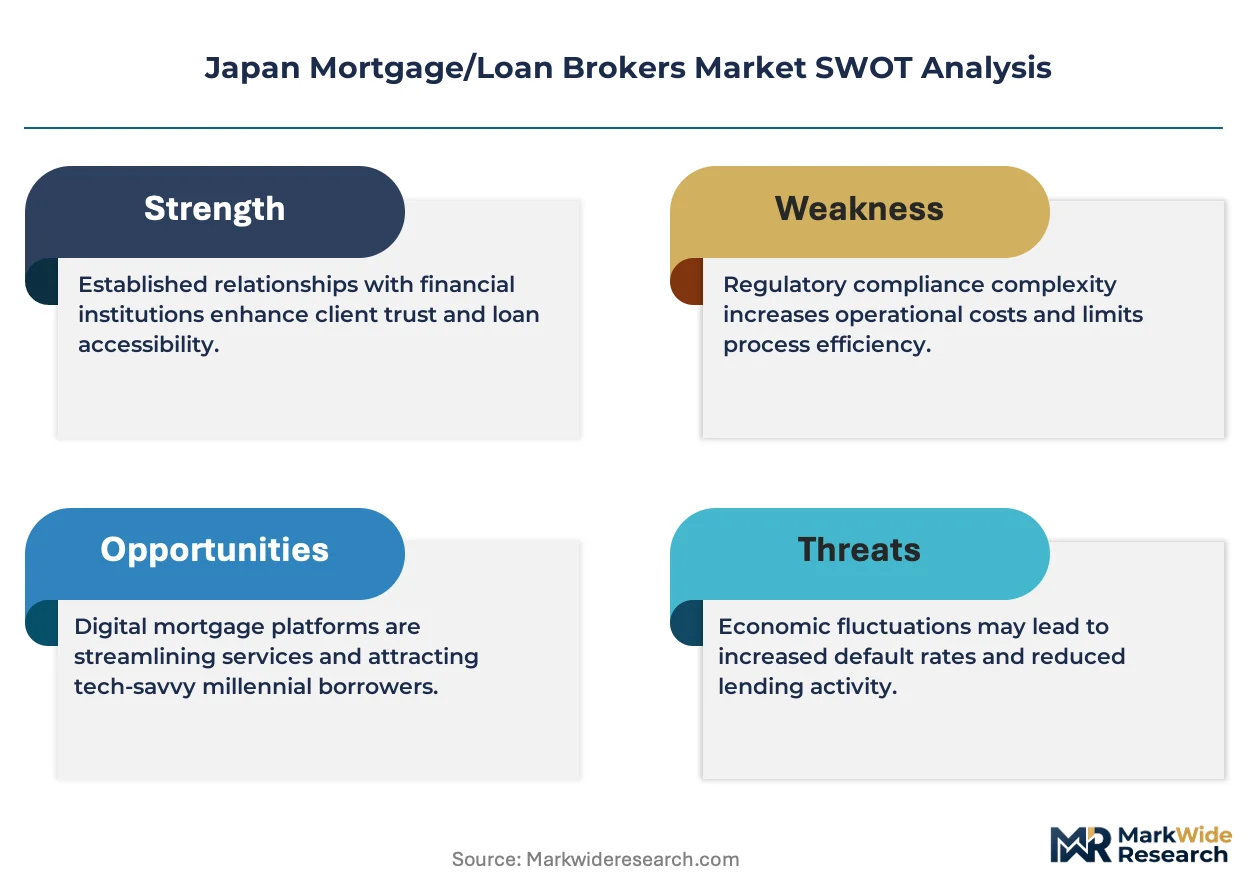
The capital-intensity divergence between megabank platforms and fintech entrants is reorganizing competitive dynamics in Japan's mortgage intermediation sector. MUFG Bank leverages its nationwide branch infrastructure to sustain dominant origination volumes. SBI Mortgage competes through digital-first application pipelines that reduce processing friction for tech-savvy borrowers.
Mortgage and loan brokers in Japan function as licensed intermediaries connecting borrowers with institutional lenders, earning commission-based compensation typically calculated as a percentage of loan principal. These entities manage documentation verification, rate comparison across multiple lenders, and regulatory compliance throughout the underwriting sequence. Home loans anchor the service type mix, reflecting persistent demand from first-time buyers navigating Japan's complex collateral valuation protocols. Fixed-rate products dominate the loan type category, as borrowers seek payment predictability following the Bank of Japan's policy pivot away from prolonged negative rates.
The Financial Services Agency (FSA) governs broker licensing and consumer protection standards, while the Japan Housing Finance Agency establishes secondary market liquidity for fixed-rate mortgages. METI coordinates broader housing policy that indirectly shapes broker demand through construction stimulus and energy-efficiency retrofit programs. Stakeholders must monitor how FSA disclosure rule adjustments and regional bank consolidation alter commission structures and borrower access patterns.
Market Dynamics
The Bank of Japan's exit from negative interest rate policy is restructuring refinancing demand patterns across Japan's mortgage intermediation sector. Borrowers are accelerating rate-lock decisions while regional banks consolidate branch networks, compressing traditional broker access points in secondary cities.
Growth Catalysts
- FSA Disclosure Rule Adjustments:Enhanced transparency mandates from Japan's Financial Services Agency are elevating broker value propositions as borrowers seek clarity on fee structures and rate comparisons across institutional lenders.
- Urban Density in Kanto:Sustained property turnover velocity in Tokyo and surrounding prefectures generates recurring commission opportunities for intermediaries managing complex collateral valuation sequences.
- Energy-Efficiency Retrofit Programs:METI-coordinated construction stimulus channels renovation financing through licensed brokers, expanding addressable loan volume beyond pure home purchase transactions.
Market Restraints
- Regional Bank Consolidation:Shrinking branch networks in Tohoku and Shikoku reduce physical touchpoints where brokers traditionally sourced borrower referrals and documentation verification services.
- Fixed-Rate Product Dominance:Borrower preference for payment predictability following the BOJ policy pivot narrows commission elasticity, as flat-rate structures replace percentage-based fee negotiations.
- Digital Platform Substitution:Direct-to-consumer mortgage comparison engines from megabank subsidiaries bypass traditional broker intermediation for tech-savvy demographics in Osaka and Nagoya.
Strategic Opportunities
- Hokkaido Secondary Cities:Underpenetrated broker presence in Sapporo and surrounding municipalities offers first-mover positioning as remote work patterns expand property demand outside Kanto concentration.
- Cross-Selling Integration:Convergence of mortgage origination with home insurance and property tax advisory services creates bundled revenue streams for licensed intermediaries.
- Digital-First Application Pipelines:Mobile document submission and AI-powered rate matching reduce processing friction, attracting younger first-time buyers who prioritize speed over branch-based consultation.
Industry Challenges
- Licensed Originator Shortages:The Financial Services Agency's examination requirements for broker certification create talent pipeline constraints, particularly in rural prefectures where training infrastructure is sparse.
- Legacy System Integration:Regional lenders' outdated underwriting platforms require manual data re-entry by brokers, inflating operational costs and extending closing timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Mortgage/Loan Brokers Market |
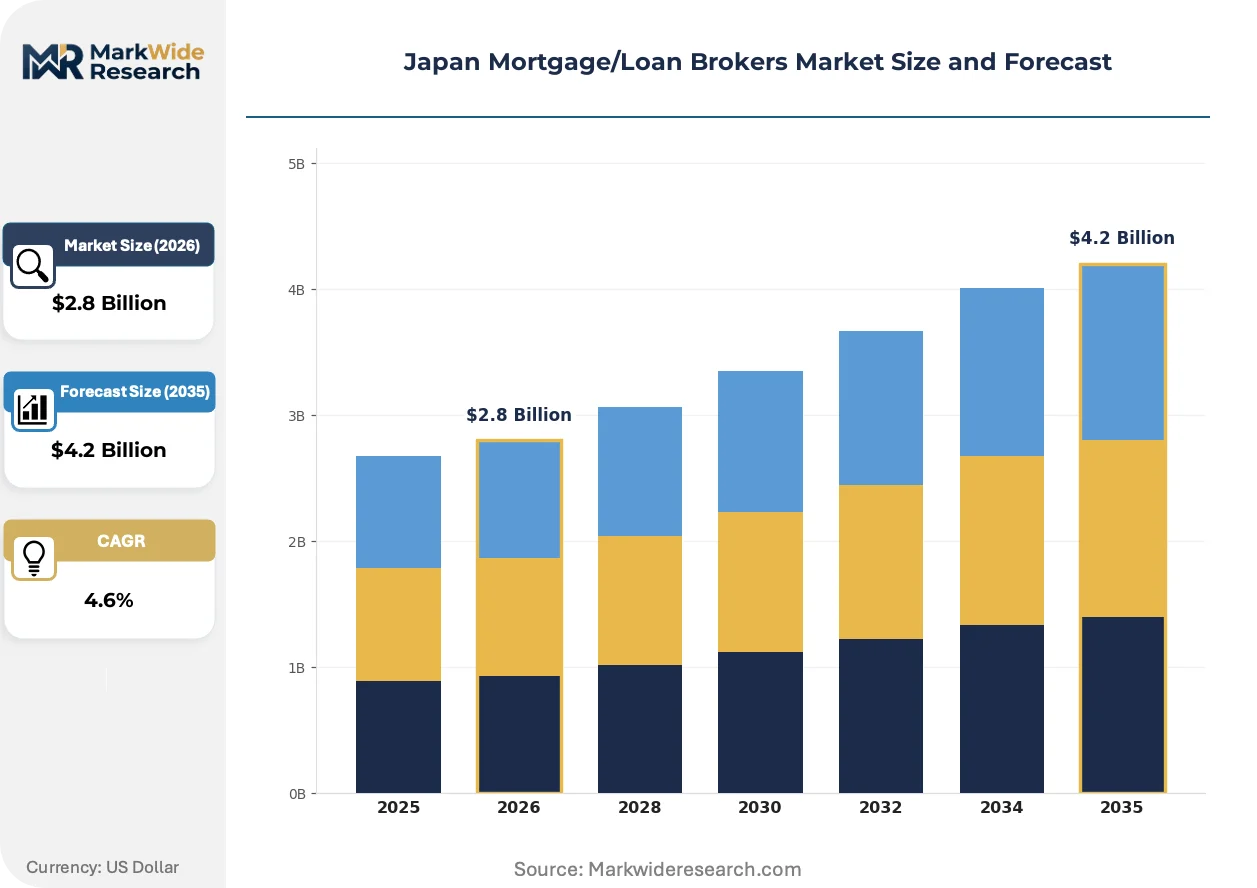
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Home Loans, Commercial Loans, Refinancing, Debt Consolidation Client Type: First-Time Buyers, Real Estate Investors, Homeowners, Businesses Loan Type: Fixed Rate, Adjustable Rate, Interest Only, Business Loans Process Stage: Application, Approval, Funding, Post-Closing |
| Companies Covered | MUFG Bank, Mizuho Bank, Sumitomo Mitsui Banking Corporation, Sony Bank, SBI Mortgage, Aruhi Corporation, Suruga Bank, Japan Housing Finance Agency, Orix, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Mortgage/Loan Brokers Market Trends and Innovations
Digital origination platforms are fragmenting Japan's mortgage distribution architecture, separating high-touch advisory services from automated rate-matching utilities. This technological shift is compressing traditional commission structures while elevating specialized consultation value.
API-based lender connectivity is bifurcating the broker technology stack. These interfaces enable real-time rate synchronization across multiple institutional sources. Tech-savvy intermediaries in Tokyo and Osaka are adopting these tools to compress borrower decision cycles. The market is bifurcating between API-enabled speed specialists and relationship-dependent generalists.
METI's housing policy coordination with the Japan Housing Finance Agency is tightening secondary market liquidity standards for fixed-rate products. This regulatory alignment elevates documentation precision requirements for broker-submitted applications. Kanto-based intermediaries are investing in compliance automation to maintain agency eligibility.
First-time buyer preferences are rotating toward mobile-first consultation models. Branch-dependent brokers in regional prefectures are losing share to digital-native competitors offering evening and weekend application access. This behavioral shift is most visible among Tokyo metropolitan area borrowers under age 40.
Japan Mortgage/Loan Brokers Market Segmentation
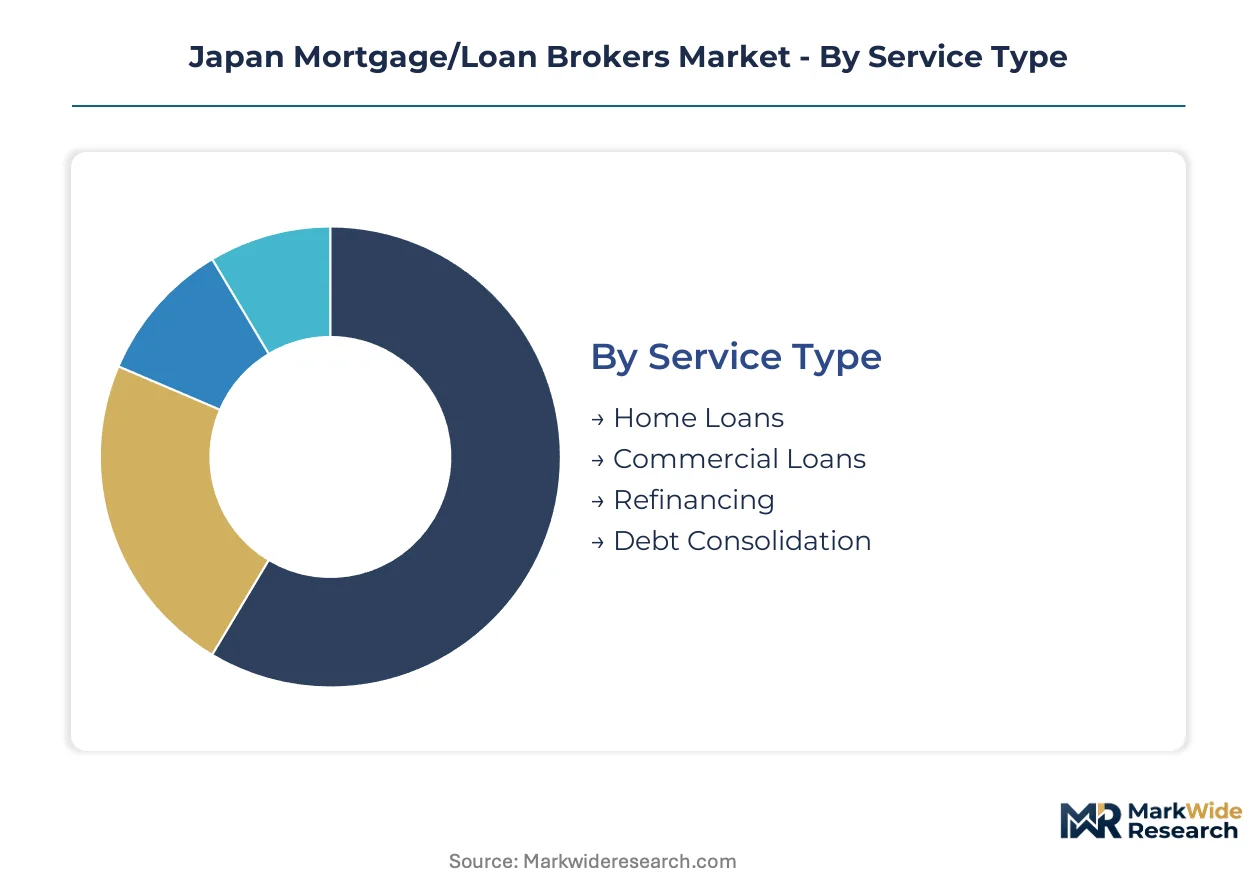
Broker specialization across service types and client profiles determines commission durability in Japan's mortgage intermediation sector. Segmentation reveals where digital substitution threatens traditional advisory models and where complex documentation requirements preserve human intermediary value.
Service Type:
Home loan mediation faces the most intense digital platform substitution as direct-to-consumer comparison engines erode traditional commission structures.
- Home Loans:Collateral valuation coordination and documentation verification for residential property purchases dominate broker revenue. First-time buyers in Tokyo's 23 wards rely on intermediaries to navigate the Japan Housing Finance Agency's fixed-rate qualification requirements amid complex income verification protocols.
- Commercial Loans:Property acquisition financing for small-to-medium enterprises involves layered covenant negotiations and cross-collateral structuring that automated platforms cannot replicate. Osaka-based brokers command premium fees for navigating regional bank consortium arrangements in Kansai industrial zones.
- Refinancing:Rate-lock advisory services generate transaction volume following the Bank of Japan's policy pivot away from negative rates.
- Debt Consolidation:Multiple liability restructuring for overleveraged households requires FSA-compliant disclosure management.
Home Loans retains volume leadership; Refinancing holds the steepest expansion curve as rate volatility accelerates borrower decision-making.
Client Type:
Commission elasticity varies sharply across borrower sophistication levels, with institutional clients demanding flat-fee structures while retail segments accept percentage-based pricing.
- First-Time Buyers:Younger demographics under 40 in the Tokyo metropolitan area prioritize mobile-first application pipelines over branch consultation. SBI Mortgage's digital platforms capture this segment through AI-powered rate matching that compresses decision cycles.
- Real Estate Investors:Portfolio leverage optimization across multiple properties demands sophisticated tax structuring and depreciation coordination. Kanto-based intermediaries bundle mortgage origination with property tax advisory services for this high-value segment.
- Homeowners:Existing property holders seeking renovation financing through METI energy-efficiency retrofit programs.
- Businesses:Corporate entity borrowing for commercial real estate acquisition.
First-Time Buyers generates the highest transaction velocity; Real Estate Investors delivers the strongest margin contribution per engagement.
Loan Type:
Product architecture determines documentation complexity and therefore broker involvement depth across the underwriting sequence.
- Fixed Rate:Long-term payment predictability products dominate origination volume following the Bank of Japan's exit from negative interest rate policy. Borrowers lock rates through the Japan Housing Finance Agency's Flat 35 program, requiring precise eligibility documentation that brokers coordinate.
- Adjustable Rate:Short-term fixed products with periodic reset provisions attract rate-sensitive borrowers in Osaka and Nagoya. Megabank subsidiaries bypass traditional intermediation for this segment through direct digital origination.
- Interest Only:Cash-flow-optimized structures for investors with alternative liquidity sources.
- Business Loans:Commercial entity borrowing with covenant monitoring requirements.
Fixed Rate commands the dominant share of broker-mediated volume; Adjustable Rate faces the most aggressive platform substitution pressure.
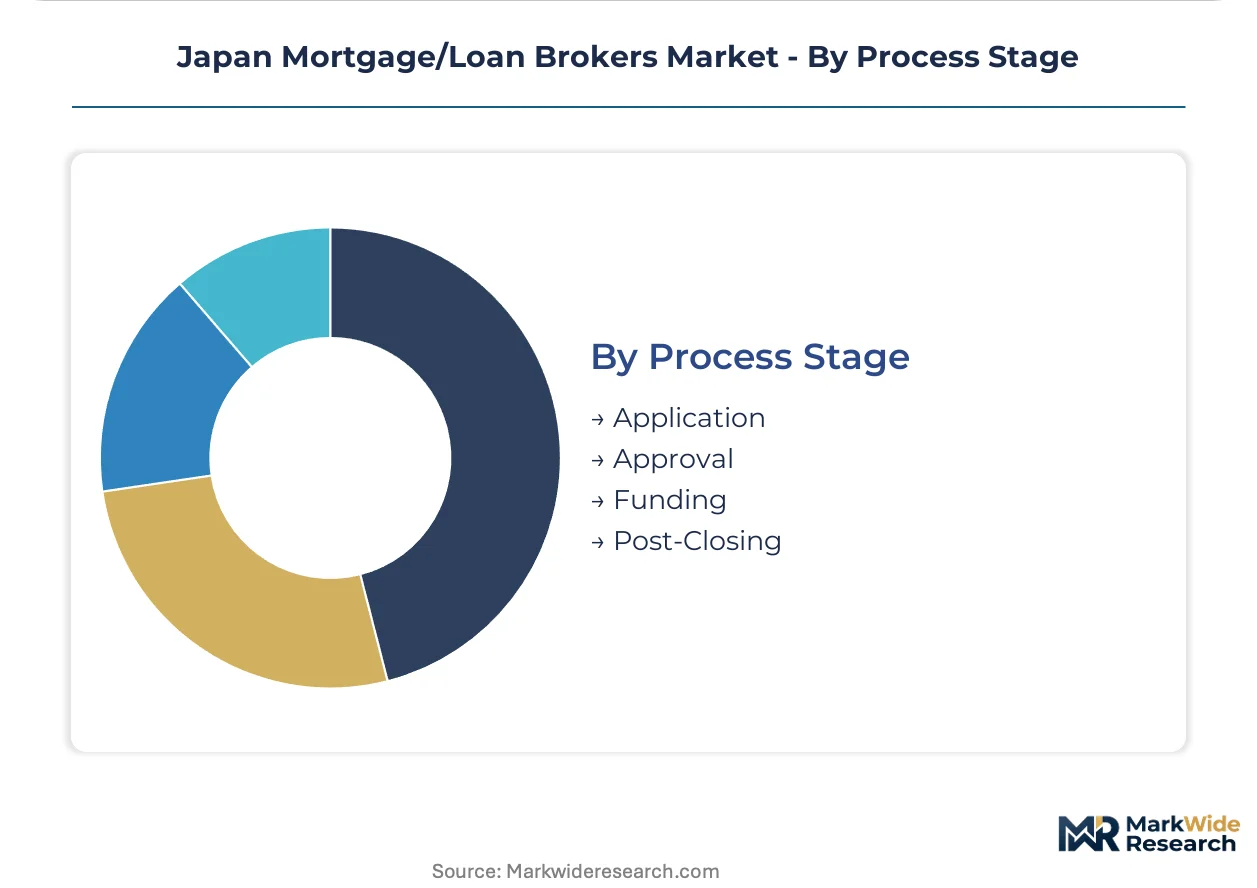
Process Stage:
Automation potential concentrates in post-origination servicing while front-end advisory retains human intermediary value.
- Application:Initial documentation collection and lender matching represents the highest automation risk as API-based rate synchronization tools proliferate among Tokyo-based digital entrants. Regional brokers in Tohoku defend this stage through relationship-dependent generalist positioning.
- Approval:Underwriting coordination and condition satisfaction management requires persistent lender negotiation that technology cannot displace. FSA disclosure rule adjustments elevate compliance precision demands at this stage.
- Funding:Closing coordination and disbursement timing optimization.
- Post-Closing:Ongoing servicing handoff and escrow management.
Application attracts the most technology investment; Approval sustains the strongest broker fee retention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Japan's prefectural landscape. Tokyo metropolitan borrowers exhibit the lowest price sensitivity, accepting flat-rate commission structures for speed and documentation expertise. Rural Tohoku and Shikoku markets retain higher elasticity, where branch proximity and relationship banking still govern intermediary selection.
Kanto/Tokyo
Property turnover velocity in the 23 wards sustains the highest broker density nationwide. First-time buyers under 40 drive mobile-first adoption, compressing decision cycles through digital application pipelines. The Financial Services Agency's disclosure mandates elevate compliance costs, favoring scaled intermediaries with automated documentation systems over sole practitioners.
Kansai/Osaka
Commercial loan mediation commands premium fees in this industrial corridor, where SME property acquisition requires cross-collateral structuring. Regional bank consortium arrangements dominate construction financing, preserving human intermediary value against platform substitution. Osaka-based brokers bundle mortgage origination with property tax advisory for investor portfolios.
Chubu/Nagoya
Automotive supply chain executives generate concentrated demand for jumbo mortgage products with complex income verification. The Japan Housing Finance Agency's Flat 35 program penetration runs below Kanto levels, creating advisory opportunity around eligibility navigation. Megabank digital subsidiaries capture adjustable-rate segments, pressuring traditional commission structures.
Hokkaido
Remote work migration from Tokyo has expanded Sapporo's property demand without proportional broker presence growth. METI energy-efficiency retrofit programs channel renovation financing through licensed intermediaries, offsetting pure purchase transaction decline. Training infrastructure scarcity constrains licensed originator supply, inflating service premiums.
Kyushu
Fukuoka's startup ecosystem attracts younger first-time buyers with non-standard employment documentation, requiring specialized underwriting coordination. Regional bank consolidation in Nagasaki and Kagoshima compresses physical touchpoints where brokers sourced referrals. FSA examination requirements create persistent talent pipeline constraints across the island.
Japan Mortgage/Loan Brokers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Japan's mortgage intermediation sector. The market structure bifurcates between nationwide megabank platforms with captive origination volume and specialized digital entrants competing on processing friction reduction. Three archetypes dominate: branch-dependent relationship generalists, API-enabled speed specialists, and hybrid advisory-technology platforms. M&A activity concentrates among regional bank consolidations, while strategic partnerships between fintech intermediaries and non-bank lenders reshape distribution economics.
Within the megabank tier, MUFG Bank, Mizuho Bank, and Sumitomo Mitsui Banking Corporation occupy positions defined by nationwide branch infrastructure and captive deposit bases. These institutions represent the relationship-dependent generalist archetype, defending market presence through physical proximity and cross-selling integration. SBI Mortgage exemplifies the digital-native specialist model, competing through automated rate matching and mobile document submission. The competitive dynamic between these archetypes concentrates commission pressure on mid-scale regional brokers lacking either technological differentiation or branch density.
| Leading Market Players |
|---|
| MUFG Bank |
| Mizuho Bank |
| Sumitomo Mitsui Banking Corporation |
| Sony Bank |
| SBI Mortgage |
| Aruhi Corporation |
| Suruga Bank |
| Japan Housing Finance Agency |
| Orix |
| Others |
Pricing and Supply Chain Analysis
Flat-rate commission structures lock in both borrower access and fee visibility for Japan's mortgage intermediaries, with the Financial Services Agency's disclosure mandates cementing percentage-to-fixed transitions across Kanto-based operations. This contract evolution compresses margin elasticity while elevating scale advantages for platforms with automated documentation systems.
Pricing Analysis
Post-closing servicing revenue drives lifetime value for broker platforms as recurring advisory fees extend beyond origination. Three-tier pricing structure across premium advisory, standard mediation, and economy digital-matching levels segments borrower sophistication. Cost compression in the economy tier intensifies because megabank subsidiaries deploy direct-to-consumer comparison engines. First-time buyers under 40 in Tokyo exhibit the lowest price sensitivity, accepting flat-rate structures for speed, while rural Tohoku borrowers retain higher elasticity tied to branch proximity.
Supply Chain Analysis
Documentation processing lead times stretch across legacy regional lender platforms, inflating operational costs for intermediaries managing manual data re-entry. Talent supply concentrates in Tokyo and Osaka, where FSA examination infrastructure supports licensed originator pipelines. Raw material inputs for broker operations include compliance automation software, API connectivity licenses, and cloud-based document management systems. Single-source vulnerability runs through the Japan Housing Finance Agency's Flat 35 program eligibility systems. Distribution runs through hybrid digital-branch networks, with Kanto intermediaries prioritizing mobile-first pipelines and regional players defending physical touchpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's mortgage intermediation sector offers fragmentation opportunity as the Bank of Japan's policy pivot splits borrower preferences between rate-lock certainty and adjustable-rate flexibility, creating specialized niches for speed-focused and advisory-heavy platforms.
For Market Incumbents: Shield core origination volume in Tokyo's 23 wards by accelerating compliance automation investments ahead of FSA disclosure rule adjustments. Consolidate regional broker networks in Kansai to capture commercial loan mediation premiums, countering digital platform substitution from SBI Mortgage's AI-powered rate matching.
For New Entrants and Emerging Players: Licensed originator shortages in Hokkaido and Kyushu expose service-layer gaps where incumbents under-serve remote work migrants and non-standard employment borrowers. Target Sapporo's expanding property demand with evening and weekend digital access, penetrating the first-time buyer segment through mobile document submission pipelines.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors hybrid advisory-technology platforms with automated documentation systems and cross-selling integration capabilities. Long-term viability rests on capturing recurring servicing revenue beyond origination. Monitor FSA examination requirement modifications as the inflection signal for talent pipeline expansion or constraint.
| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Automation Investment | FSA disclosure mandates elevate documentation precision requirements for Flat 35 program eligibility. |
| API-Based Lender Connectivity | Real-time rate synchronization across MUFG, Mizuho, and regional bank sources compresses borrower decision cycles. |
| Cross-Selling Integration | Convergence of mortgage origination with home insurance and property tax advisory creates bundled revenue streams. |
| Digital-First Application Pipeline | Mobile document submission attracts Tokyo metropolitan first-time buyers under 40 who prioritize speed. |
| Regional Network Consolidation | Acquisition of Tohoku and Shikoku brokers defends physical touchpoints against branch network compression. |
Research Methodology
A standing panel of mortgage brokerage principals, regional bank lending officers, FSA regulatory specialists, and Japan Housing Finance Agency program administrators provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation from Bank of Japan policy bulletins, Financial Services Agency disclosure rule filings, METI housing stimulus documentation, and prefectural property transaction registries. Bottom-up transaction volume estimates and top-down macroeconomic indicators underwent triangulation to reconcile segment-level outputs.
Consistency checks against external benchmarks validated projections across the analysis window. The analytical framework modeled segmentation dimensions including service type, client profile, loan product architecture, and process stage automation potential. CAGRs derived from historical origination trends and policy-shift scenario modeling incorporated Bank of Japan rate trajectory assumptions and regional bank consolidation patterns as industry-specific inputs.
Forecasts assume regulatory continuity in FSA licensing regimes and METI housing policy coordination; material disclosure rule adjustments or secondary market liquidity standard revisions would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Car Finance Market
Loans and Leasing
Factoring Market
Loans and Leasing
Alternative Lending Market
Loans and Leasing
Europe Home Mortgage Finance Market
Loans and Leasing
Indonesia Mortgage/Loan Brokers Market
Loans and Leasing
Micro Lending Market
Loans and Leasing
Germany Auto Loan Market
Loans and Leasing
India Home Loan Market
Loans and Leasing
Alternative Lending Platform Market
Loans and Leasing
Brazil Car Loan Market
Loans and Leasing
E-Scooter Financing Market
Loans and Leasing
Brazil Home Loan Market
Loans and Leasing
Asia-Pacific Mortgage/Loan Brokers Market
Loans and Leasing
Automotive Finance Market
Loans and Leasing
North America Used Car Financing Market
Loans and Leasing
Loan Management Software Market