
 Electric Lawn Mower Market | 2026-2036
Electric Lawn Mower Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Lawn Mower Market Intelligence
China's battery cell manufacturing expansion is rewriting supply economics for outdoor power equipment. Greenworks leverages its parent company's cell production to control input costs across North American distribution. Toro anchors its commercial lineup with professional-grade lithium-ion platforms for municipal buyers. EGO Power+ differentiates through proprietary 56V architecture that extends runtime benchmarks against competing voltage platforms.
An electric lawn mower converts stored electrical energy from rechargeable batteries into rotational cutting force via brushless or brushed DC motors, typically operating at blade speeds between 2,800 and 3,300 RPM for clean grass severance. Residential end users represent the largest installed base, though landscape contractors generate premium pricing pools due to durability requirements and fleet standardization needs. Robotic product types capture the fastest expansion trajectory as boundary-wire and GPS-guided navigation systems mature for unattended maintenance cycles. Lithium-ion battery chemistry dominates new unit sales while lead-acid configurations persist in price-sensitive entry segments.
EPA Phase 3 emission regulations for small spark-ignition engines and California Air Resources Board (CARB) zero-emission equipment mandates are accelerating manufacturer portfolio transitions away from gasoline powertrains. The EU Green Deal and F-Gas Regulation constrain refrigerant and lubricant chemistries used in battery thermal management systems, adding compliance layers for exporters. Stakeholders must monitor municipal procurement rulemaking in Germany and Australia, where public-sector fleet electrification timelines will determine volume allocation between residential and commercial product configurations.
Market Dynamics
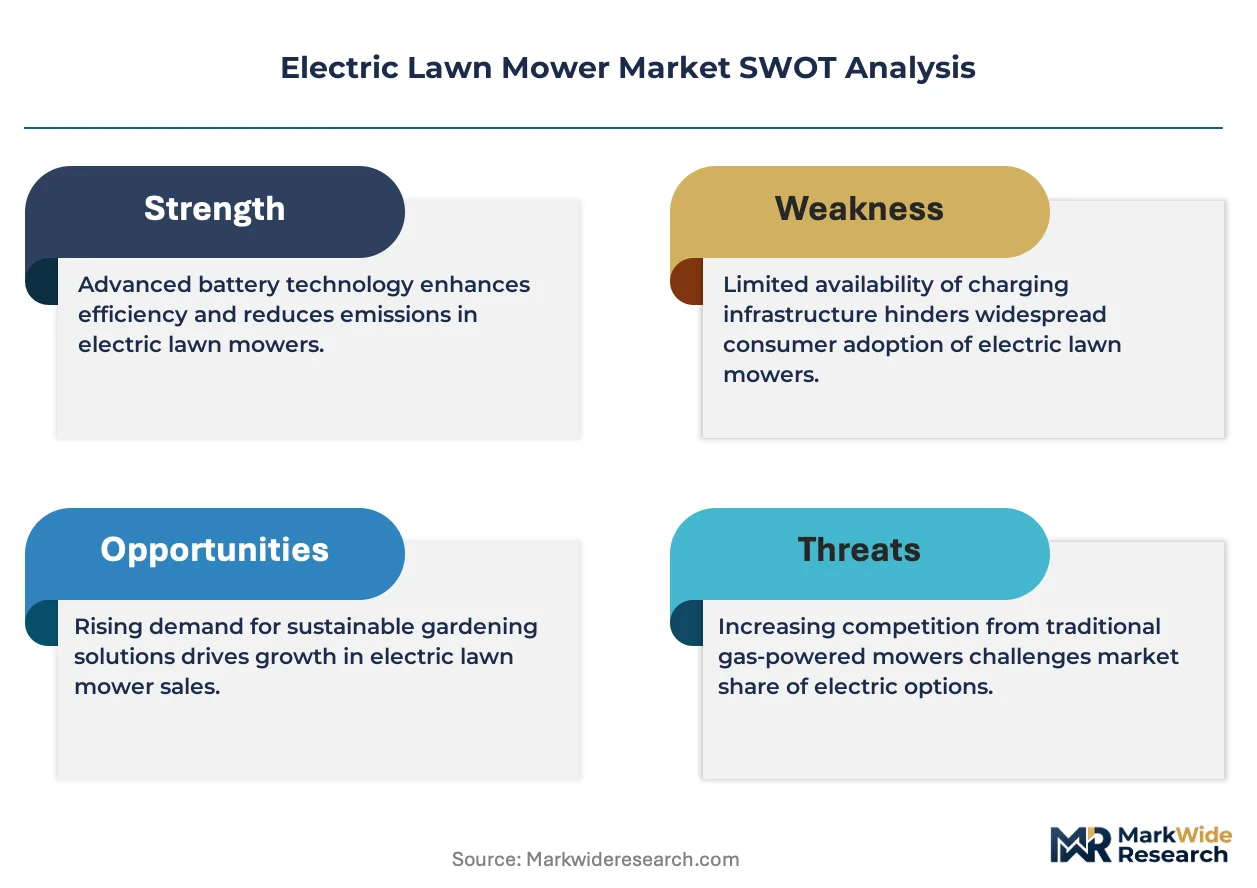
EPA Phase 3 emission standards and CARB zero-emission mandates are forcing manufacturers to abandon small gasoline engines entirely, while China's battery cell production concentration is rewriting cost structures for outdoor power equipment supply chains.
Growth Catalysts
- CARB Zero-Emission Mandate:California's prohibition on gas-powered lawn equipment creates guaranteed replacement demand across the largest US state market, pulling forward electrification timelines for national product portfolios.
- Lithium-Ion Energy Density Gains:Cell chemistry improvements extend runtime benchmarks to 90+ minutes, eliminating the primary performance objection from suburban homeowners with quarter-acre lots.
- Municipal Fleet Electrification:Cities in Germany and Australia are embedding electric maintenance equipment into public procurement specifications, opening institutional volume channels previously dominated by commercial gas contracts.
Market Restraints
- Cell Supply Concentration:Cathode active material refining clusters in China's Hunan and Fujian provinces create geographic single-point vulnerability for non-integrated OEMs.
- Replacement Battery Cost Structure:Pack-level pricing remains at 35-40% of total unit cost, compressing margin recovery for manufacturers without captive cell production.
- Runtime Anxiety in Commercial Use:Landscape contractors operating 8-hour maintenance windows face productivity losses from mid-day charging requirements that gas refueling eliminates.
Strategic Opportunities
- Robotic Navigation Convergence:GPS-RTK and computer vision integration enables unattended perimeter mowing for golf courses and corporate campuses, shifting revenue from equipment sales to subscription maintenance contracts.
- Australian Municipal Procurement:State-level fleet electrification commitments in Victoria and New South Wales outpace supplier readiness, creating first-mover advantage for compliant product configurations.
- Swappable Battery Standardization:Interoperable pack architectures across tool categories let contractors consolidate charging infrastructure, reducing total cost of ownership and locking fleet purchasing decisions.
Industry Challenges
- Brushless Motor Controller Firmware:Specialized embedded systems engineering talent concentrates in Shenzhen and Taipei, forcing Western OEMs into costly cross-border hiring or IP licensing arrangements.
- IP-67 Ingress Certification Timelines:Extended validation cycles for outdoor-rated battery enclosures delay product launches by 8-12 months against aggressive regulatory deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Lawn Mower Market |
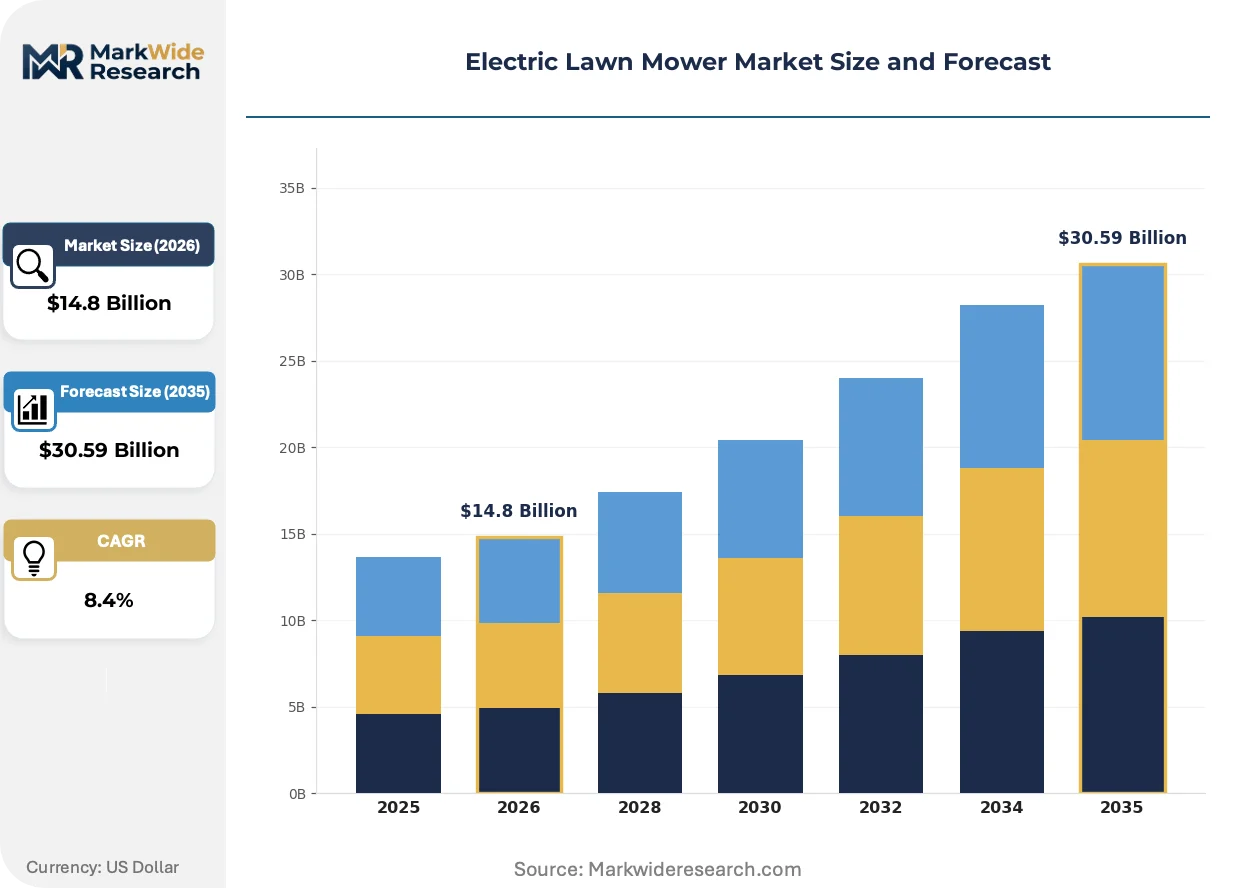
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Propelled, Push, Robotic, Riding End User: Residential, Commercial, Government, Landscape Contractors Cutting Width: Small, Medium, Large, Extra Large Battery Type: Lithium-Ion, Lead-Acid, NiCad, Others |
| Companies Covered | RYOBI, Greenworks, EGO Power+, Bosch, Troy-Bilt, Snapper, Toro, John Deere, Milwaukee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Lawn Mower Market Strategic Shifts & Innovations
Boundary-wire elimination and autonomous navigation are compressing the distinction between residential convenience products and commercial fleet equipment, while regulatory deadlines in multiple geographies synchronize manufacturer R&D roadmaps.
Sensor fusion combining ultrasonic obstacle detection with RTK-GPS positioning is virtualizing the physical perimeter infrastructure that previously constrained robotic mower deployment. Golf course superintendents in Florida and Arizona are piloting wire-free installations across 50+ acre properties. The technology is virtualizing site preparation costs that formerly represented 15-20% of total robotic system investment.
The EU F-Gas Regulation constrains refrigerant chemistries permitted in battery thermal management systems for equipment exported to European markets. Manufacturers must reformulate cooling loops or absorb compliance testing costs for dual-SKU production. Commercial product lines targeting German municipal buyers face the tightest formulation deadlines under the 2027 phase-down schedule.
Landscape contractors are consolidating vendor relationships around single-battery platforms that power mowers, blowers, and string trimmers interchangeably. Equipment distributors in Texas and Georgia report 60% of commercial buyers now prioritize ecosystem compatibility over individual tool performance specifications. This pattern concentrates purchasing power with manufacturers offering the broadest 56V or 80V tool portfolios.
Electric Lawn Mower Market Segmentation
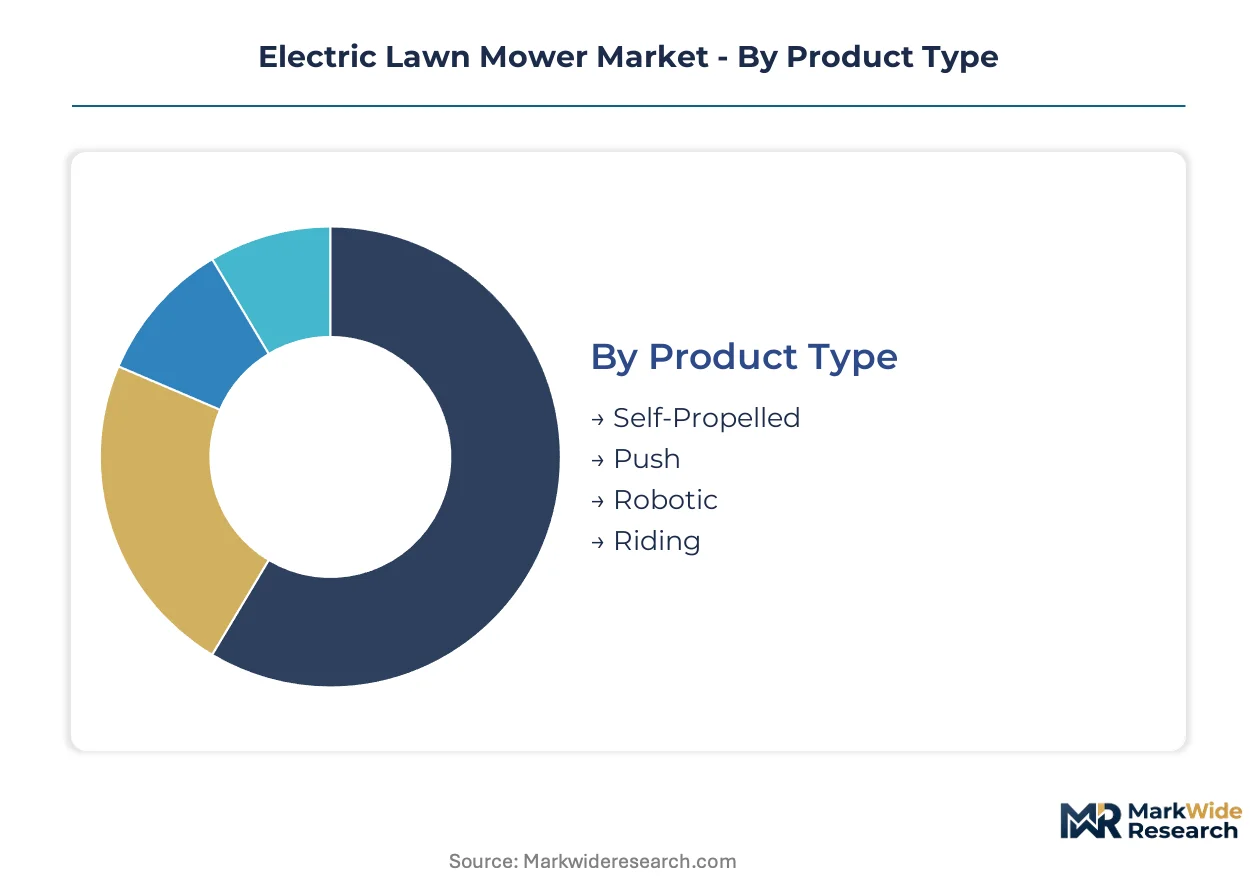
Product configuration and powertrain architecture fragment the competitive landscape into distinct performance tiers. Each dimension—mobility design, end-use intensity, deck sizing, and cell chemistry—creates separate margin pools and supply chain requirements.
Product Type:
Self-propelled units serve the suburban homeowner segment with powered drive systems that reduce physical exertion across uneven terrain.
- Self-Propelled:Rear-wheel or all-wheel drive configurations dominate quarter-acre residential installations. Demand clusters in US suburban counties where CARB compliance deadlines accelerate replacement cycles ahead of gas equipment bans.
- Push:Manual-propulsion designs retain cost-sensitive entry positioning. German municipal procurement specifications exclude these units from professional fleet contracts due to productivity constraints.
- Robotic:GPS-RTK and computer vision navigation eliminate perimeter wire installation. Golf course superintendents in Florida pilot wire-free deployments across 50+ acre properties, compressing site preparation costs.
- Riding:Zero-turn and lawn tractor formats address acreage above one hectare. Australian landscape contractors in Victoria specify these for commercial maintenance contracts requiring continuous runtime.
The dominant share belongs to Self-Propelled, while Robotic is closing the gap fastest.
End User:
Customer type determines durability specifications, fleet standardization needs, and procurement channel access.
- Residential:Homeowners with lots under 0.4 hectares drive volume concentration. Runtime anxiety diminishes as lithium-ion energy density extends benchmarks past 90 minutes.
- Commercial:Property management firms and corporate campuses demand swappable battery architectures. Texas equipment distributors report 60% of buyers prioritize ecosystem compatibility across mowers, blowers, and trimmers.
- Government:Municipal procurement in Germany embeds electrification timelines into public landscaping contracts. EU F-Gas Regulation adds compliance layers for battery thermal management systems.
- Landscape Contractors:Fleet operators face productivity losses from mid-day charging requirements. Swappable pack standardization reduces total cost of ownership for 8-hour maintenance windows.
Residential commands the largest installed base, though Landscape Contractors generate premium pricing pools.
Cutting Width:
Deck dimension correlates directly with application scale and motor power requirements.
- Small:Sub-16 inch decks target urban row houses and confined yards. Australian state electrification commitments in New South Wales outpace supplier readiness for compact configurations.
- Medium:16-20 inch formats balance maneuverability with coverage efficiency. US suburban homeowners represent the core demand concentration.
- Large:20-30 inch spans serve estate properties and institutional grounds. German municipal buyers specify these for park maintenance under Green Deal procurement rules.
- Extra Large:30+ inch decks require riding platforms or wide-area walk-behind designs. Commercial golf courses in Arizona deploy these for fairway cutting.
Medium decks retain the highest shipment volumes, while Extra Large formats expand most quickly in commercial channels.
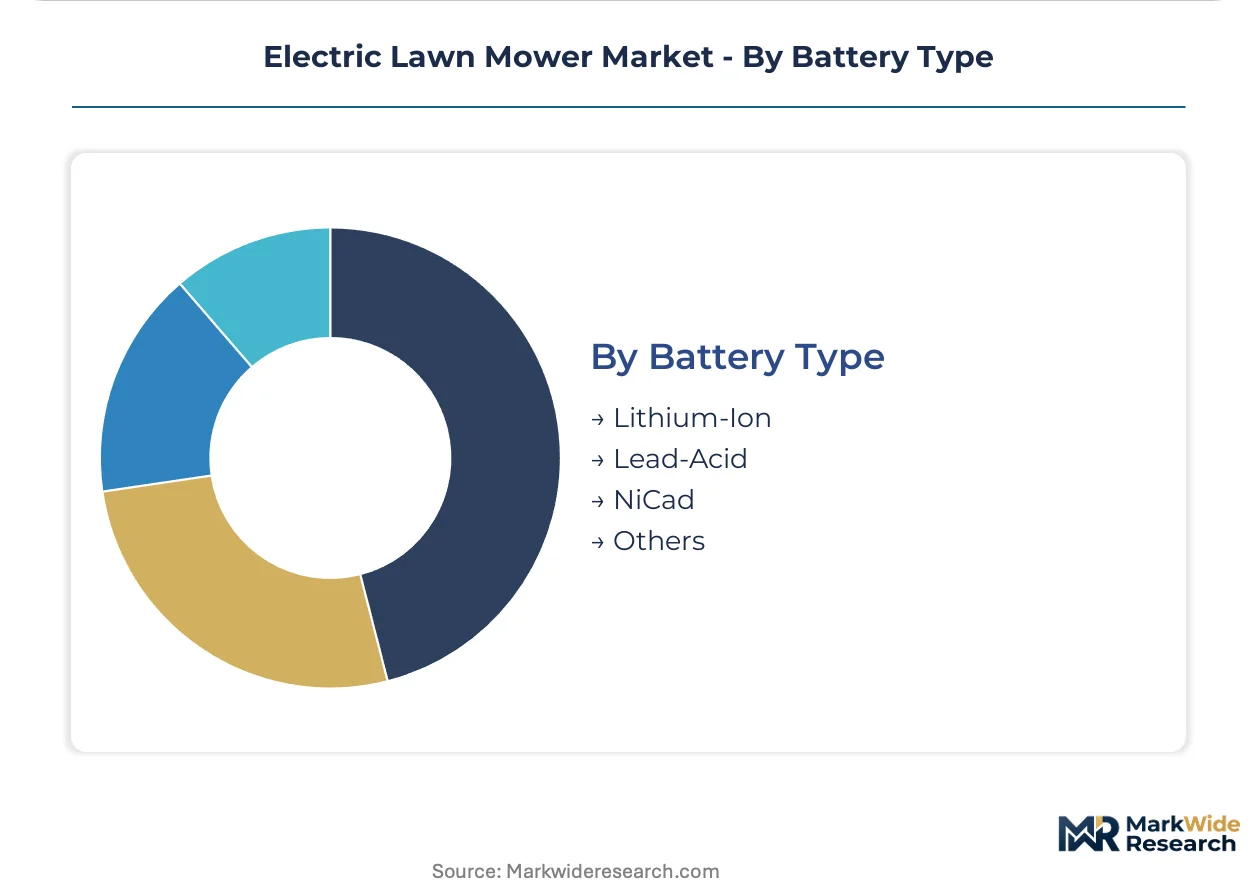
Battery Type:
Cell chemistry determines energy density, cycle life, and thermal management complexity.
- Lithium-Ion:NMC and LFP chemistries dominate new unit sales with superior energy-to-weight ratios. China's Hunan and Fujian cathode refining clusters create geographic supply concentration.
- Lead-Acid:Flooded and AGM configurations persist in price-sensitive entry segments. Australian retail channels stock these for budget-conscious residential buyers.
- NiCad:Nickel-cadmium cells retain niche presence in legacy tool ecosystems. Memory effect limitations restrict adoption in professional applications.
- Others:Emerging solid-state and sodium-ion prototypes target next-generation platforms. EPA Phase 3 emission standards accelerate R&D investment away from gas powertrains entirely.
Lithium-Ion holds decisive technology leadership, while Others category prototypes gain development traction fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Phase 3 emission standards and CARB zero-emission mandates anchor the United States as the dominant geography, with regulatory spillover reshaping procurement patterns across suburban counties and municipal fleets.
United States
California's prohibition on gas-powered lawn equipment pulls forward electrification timelines for national product portfolios. EPA Phase 3 standards force manufacturers to abandon small gasoline engines entirely. Suburban counties in Texas and Georgia concentrate replacement demand as equipment distributors report ecosystem compatibility priorities among commercial buyers.
Germany
Municipal procurement specifications embed electrification timelines into public landscaping contracts under EU Green Deal frameworks. The F-Gas Regulation constrains refrigerant chemistries in battery thermal management systems for exporters. Industrial clusters in Bavaria and North Rhine-Westphalia host landscape contractor fleets standardizing around swappable battery architectures.
Australia
State-level fleet electrification commitments in Victoria and New South Wales outpace supplier readiness for compliant product configurations. The country's national environmental regulator enforces emissions benchmarks for maintenance equipment in public contracts. Sydney and Melbourne metropolitan councils pilot electric fleet deployments for park maintenance operations.
China
Cathode active material refining clusters in Hunan and Fujian provinces create geographic supply concentration for lithium-ion cell production. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate battery manufacturing capacity expansion. Shenzhen and Taipei engineering talent pools concentrate brushless motor controller firmware development.
United Kingdom
London borough councils mandate zero-emission maintenance equipment for municipal groundskeeping contracts. REACH and RoHS compliance layers add testing costs for battery pack exporters serving European markets. Southeast England landscaping firms consolidate vendor relationships around single-battery platforms for mowers and handheld tools.
Electric Lawn Mower Market Key Industry Players
Battery-integrated specialists and diversified outdoor power equipment manufacturers split the market between captive cell production advantages and distribution scale economies. The competitive structure concentrates around three archetypes: vertically integrated cell producers controlling input costs, tool-ecosystem builders locking fleet purchasing through platform compatibility, and commercial-grade specialists targeting municipal procurement channels. Dominant competitive moves include backward integration into battery cell supply and strategic partnerships for navigation software licensing.
Among North American equipment builders, Greenworks and EGO Power+ occupy positions reflecting distinct voltage platform strategies, while Toro anchors the commercial-tier segment. These three exemplify how cell supply access and professional-grade positioning differentiate competitive standing. Greenworks leverages parent-company battery production for cost control. EGO Power+ represents proprietary high-voltage architecture specialization. Toro sits within municipal and landscape contractor procurement channels.
| Leading Market Players |
|---|
| RYOBI |
| Greenworks |
| EGO Power+ |
| Bosch |
| Troy-Bilt |
| Snapper |
| Toro |
| John Deere |
| Milwaukee |
| Others |
Cost & Logistics Intelligence
Hunan and Fujian provinces anchor cathode active material refining capacity that feeds lithium-ion cell production across outdoor power equipment. This geographic concentration grants integrated OEMs cost advantages that compress pack-level pricing for non-captive manufacturers, reshaping margin structures across residential and commercial tiers.
Pricing Analysis
North American retail channels command 15-25% premiums over Australian distribution for equivalent lithium-ion platforms, reflecting tariff-layered import costs and after-sales service bundling. Three-tier pricing structure across premium, standard, and economy levels separates brushless motor systems from brushed DC entry units from lead-acid legacy configurations. Cost compression in the economy tier is intensifying because Chinese cell manufacturers are expanding export-oriented capacity. Residential homeowners exhibit highest price sensitivity, while landscape contractors prioritize ecosystem compatibility over unit economics.
Supply Chain Analysis
Export-control regimes limiting semiconductor fabrication equipment flows to Chinese fabs have not yet constrained battery cell production, though cathode precursor chemistry IP remains restricted. China, South Korea, and Japan concentrate lithium-ion cell supply for outdoor power applications. NMC cathode powders, electrolyte formulations, and battery management system ICs constitute critical input dependencies. Single-source vulnerability clusters in Hunan province refining operations for high-nickel cathode materials. Distribution runs through big-box retail chains in the United States, specialized equipment dealers in Germany, and municipal procurement portals in Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based fleet management software for robotic mowers expands faster than hardware unit sales, converting capital expenditure into recurring revenue streams for equipment vendors and service integrators.
For Market Incumbents: Insulate margin structures by securing captive cell supply agreements or backward integration into cathode material processing, as replacement battery pricing pressure from Chinese integrated competitors threatens aftermarket profitability. Accelerate IP-67 certification investment to compress validation timelines against CARB and EU Green Deal deadlines. Channel control through exclusive dealer networks in Texas and Georgia defends against ecosystem-switching by landscape contractors consolidating vendor relationships. For New Entrants and Emerging Players: Municipal procurement white space in Victoria and New South Wales represents the most penetrable entry point, as Australian state electrification commitments outpace incumbent supplier readiness for compliant riding and wide-deck configurations. Mid-market commercial campuses in the US Southeast seeking wire-free robotic navigation pilot programs offer second-mover advantage where boundary-wire installation costs previously blocked adoption. Go-to-market execution should anchor on direct municipal sales teams rather than retail channel builds. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because EPA Phase 3 and CARB zero-emission mandates guarantee replacement demand cyclicality decoupled from discretionary consumer spending. Acquisition targets should concentrate on brushless motor controller firmware specialists with Shenzhen or Taipei engineering talent pools, or robotic navigation software platforms with RTK-GPS integration capabilities. The signal to watch is municipal procurement rulemaking velocity in Germany and Australia, where public-sector fleet electrification timeline acceleration would pull forward volume allocation to commercial-grade configurations.| Strategic Initiative | Industry Significance |
|---|---|
| Swappable Battery Platform Standardization | Interoperable 56V and 80V architectures lock landscape contractor fleet purchasing decisions across tool categories. |
| Robotic Navigation Software Licensing | RTK-GPS and computer vision partnerships compress site preparation costs for golf course and corporate campus deployments. |
| Cathode Material Backward Integration | In-house NMC and LFP processing secures margin recovery against China's Hunan and Fujian supply concentration. |
| Municipal Procurement Channel Development | Direct sales capabilities in Germany and Australia capture public-sector fleet electrification volume ahead of retail competitors. |
| Battery Thermal Management Reformulation | EU F-Gas Regulation compliance for refrigerant chemistries maintains European market access under 2027 phase-down schedules. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with equipment OEM product managers, municipal procurement officers, landscape contractor fleet operators, and battery cell supply chain directors; and secondary validation through EPA regulatory filings, CARB zero-emission equipment databases, EU Green Deal implementation documents, and customs trade data for lithium-ion battery exports. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across voltage platform, end-user segment, and regional regulatory cluster dimensions.
Forecast inputs considered lithium-ion energy density improvement curves, municipal fleet electrification commitment timelines, and robotic navigation technology adoption rates across the projection horizon. Segmentation modeling captured product type, end user intensity, cutting width tier, and cell chemistry variations. CAGRs derived from regression analysis of historical replacement cycles overlaid with regulatory mandate acceleration effects. Industry-specific inputs included brushless motor controller firmware development capacity constraints and IP-67 ingress certification timeline distributions.
Practitioners should monitor CARB rulemaking expansion to additional states, EU F-Gas Regulation enforcement stringency, and Chinese cathode material export license developments for early signals of forecast revision triggers. Material shifts in municipal procurement electrification timelines or lithium-ion cell supply chain geopolitical access would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
United Kingdom Homeware Market
Home & Garden
North America Flower Pots and Planters Market
Home & Garden
Global Motorized and Smart Awnings Market
Home & Garden
Aquarium LED Lighting Market
Home & Garden
Hedge Trimmer Market
Home & Garden
Christmas Decorations Market
Home & Garden
Japan Flower Pots Market
Home & Garden
Global Hot Tub Market
Home & Garden
Landscaping Services Market
Home & Garden
Europe Robotic Lawn Mower Market
Home & Garden
Wine Racks Market
Home & Garden
United States Landscaping Market
Home & Garden
Garage Organization and Storage Market
Home & Garden
Landscaping Products Market
Home & Garden
North America Floral Gifting Market
Home & Garden
Lawn and Garden Water Equipment Market