
 Artificial Flowers Market | 2026-2036
Artificial Flowers Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Flowers Market Analysis
Modular bouquet configurations is shifting how hospitality buyers evaluate artificial flower suppliers. Nearly Natural, Inc. anchors its position through direct-to-hotel channel control in North America. Dongguan Fusheng Arts Products Co., Ltd dominates mass-volume silk rose production for European retailers. Diane James Designs, Inc. differentiates through hand-finished arrangements targeting luxury residential interiors.
Artificial flowers are manufactured replicas of botanical specimens, typically constructed from silk, polyester, or polyurethane foam with wire stems and colorfast dyes, designed to mimic the visual properties of living flora for decorative applications where maintenance, longevity, or seasonal availability constrains fresh flower use. Silk and polyester materials occupy the largest volume share due to cost scalability, while foam-based orchids represent the fastest-expanding material category in premium event decoration. Home decor applications sustain the broadest consumer base, though floral arrangements for corporate and wedding events command higher per-unit margins through customized color matching and branded packaging.
EPA regulations on volatile organic compound emissions from synthetic dye processes and REACH restrictions on certain phthalate plasticizers in the European Union are elevating compliance costs for manufacturers using conventional petroleum-based materials. China's GB standards for textile products and the EU's CSRD reporting requirements on supply chain environmental impact are reshaping procurement criteria for multinational retail buyers. Stakeholders must monitor regulatory divergence between major import markets to avoid stranded inventory in cross-border distribution networks.
Market Dynamics
REACH compliance in the European Union and evolving EPA guidance on synthetic polymer disposal are tightening material specifications, forcing manufacturers to reformulate petroleum-based dyes and plasticizers while event planners accelerate volume commitments to silk and foam alternatives for recurring installations.
Growth Catalysts
- REACH plasticizer restrictions:ECHA regulations phasing out certain phthalates in EU imports are accelerating demand for compliant polyurethane foam formulations in premium event decoration.
- Corporate installation contracts:Hospitality procurement teams now source modular silk rose arrangements on multi-year refresh cycles rather than seasonal fresh-flower contracts.
- Guangdong manufacturing density:Dongguan and Foshan factory clusters achieve cost scalability through shared dye houses and wire-stem suppliers serving global private-label programs.
Market Restraints
- Petroleum-based input volatility:Polyester resin and synthetic dye costs fluctuate with crude oil indices, compressing margin stability for mid-volume manufacturers.
- Single-region production concentration:China's dominance in silk rose and foam orchid assembly creates vulnerability to port congestion and tariff escalation in Pearl River Delta logistics corridors.
- Biodegradation limitations:Conventional polyurethane foam stems resist microbial breakdown, triggering disposal friction under tightening municipal solid-waste regulations in Germany and France.
Strategic Opportunities
- CSRD supply-chain reporting:EU corporate sustainability disclosure requirements create first-mover advantage for manufacturers with auditable carbon accounting across Guangdong textile subcontractors.
- Direct-to-hotel distribution:Bypassing wholesale floristry intermediaries allows artificial flower suppliers to capture margin from property-level procurement teams managing interior refresh budgets.
- Biopolymer dye convergence:Algae-derived colorants combined with recycled PET substrates open positioning in luxury residential segments where chemical-free claims command price premiums.
Industry Challenges
- Color-matching technician scarcity:Hand-finished arrangement houses in Italy and Portugal face recruitment gaps for artisans capable of replicating living-flower tonal variation.
- Dual-certification timelines:Simultaneous EPA VOC testing and REACH SVHC screening extend product launch cycles by eight to fourteen months for North American and European market entry.
- Legacy inventory stranding:Pre-2023 petroleum-based stockpiles face markdown pressure as retail buyers enforce phthalate-free procurement clauses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Flowers Market |
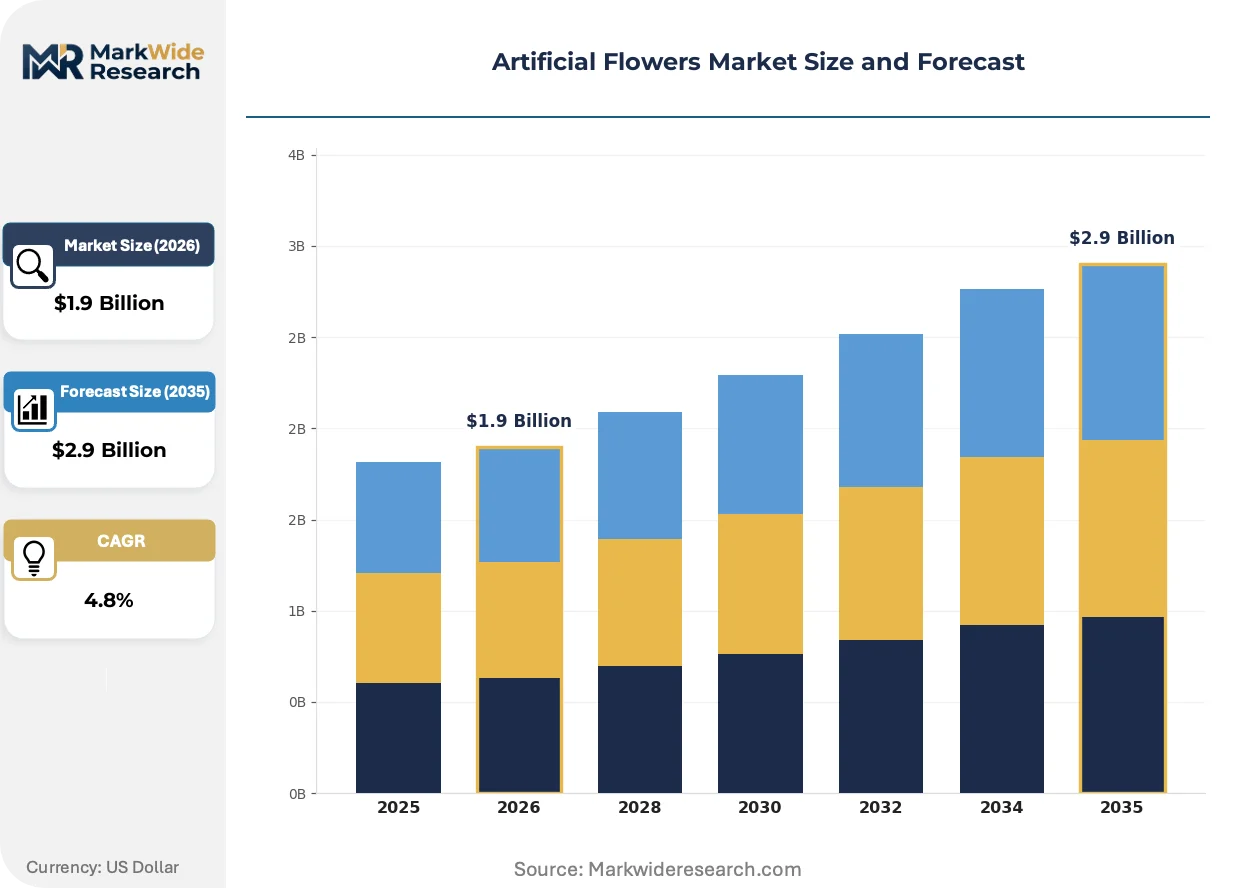
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $2.9 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roses, Tulips, Lilies, Orchids Material: Silk, Plastic, Foam, Polyester Application: Home Decor, Event Decoration, Floral Arrangements, Crafting End User: Retailers, Wholesalers, Event Planners, Individual Consumers |
| Companies Covered | FRS Holding S.R.L. (Evergreens), Diane James Designs, Inc., Dongguan Fusheng Arts Products Co., Ltd, TreeLocate (Europe) Limited, Nearly Natural, Inc., National Tree Company, LLC, Vickerman Company, Foshan Tongxin Artificial Flowers Co., Ltd, Xuzhou Pleasant Arts Flower Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Flowers Market Emerging Trajectories
Material science advances and procurement digitization are compressing traditional supply relationships while regulatory transparency mandates reshape competitive positioning around environmental accountability rather than aesthetics alone.
Polyurethane foam molding with embedded wire armature is overtaking hand-wrapped silk construction in high-volume orchid production. Event rental companies in the United States now specify foam-based stems for 70% of new banquet installations. The technology is overtaking artisan-dependent workflows by enabling consistent petal density at one-third the labor input.
CSRD reporting requirements on Scope 3 emissions are forcing European retailers to demand batch-level carbon footprints from Guangdong suppliers. Manufacturers lacking ISO 14001 certification face exclusion from RFP shortlists for 2025 hospitality contracts. German department-store buyers now prioritize suppliers with third-party-verified dye-process water recycling.
Subscription refresh programs are displacing one-time purchase models in corporate interior design. Facility managers at US technology campuses contract artificial-flower services on 18-month rotation cycles rather than capitalizing owned inventory. This pattern concentrates most visibly in Texas and California where hybrid work schedules reduce daily maintenance staffing.
Artificial Flowers Market Segmentation
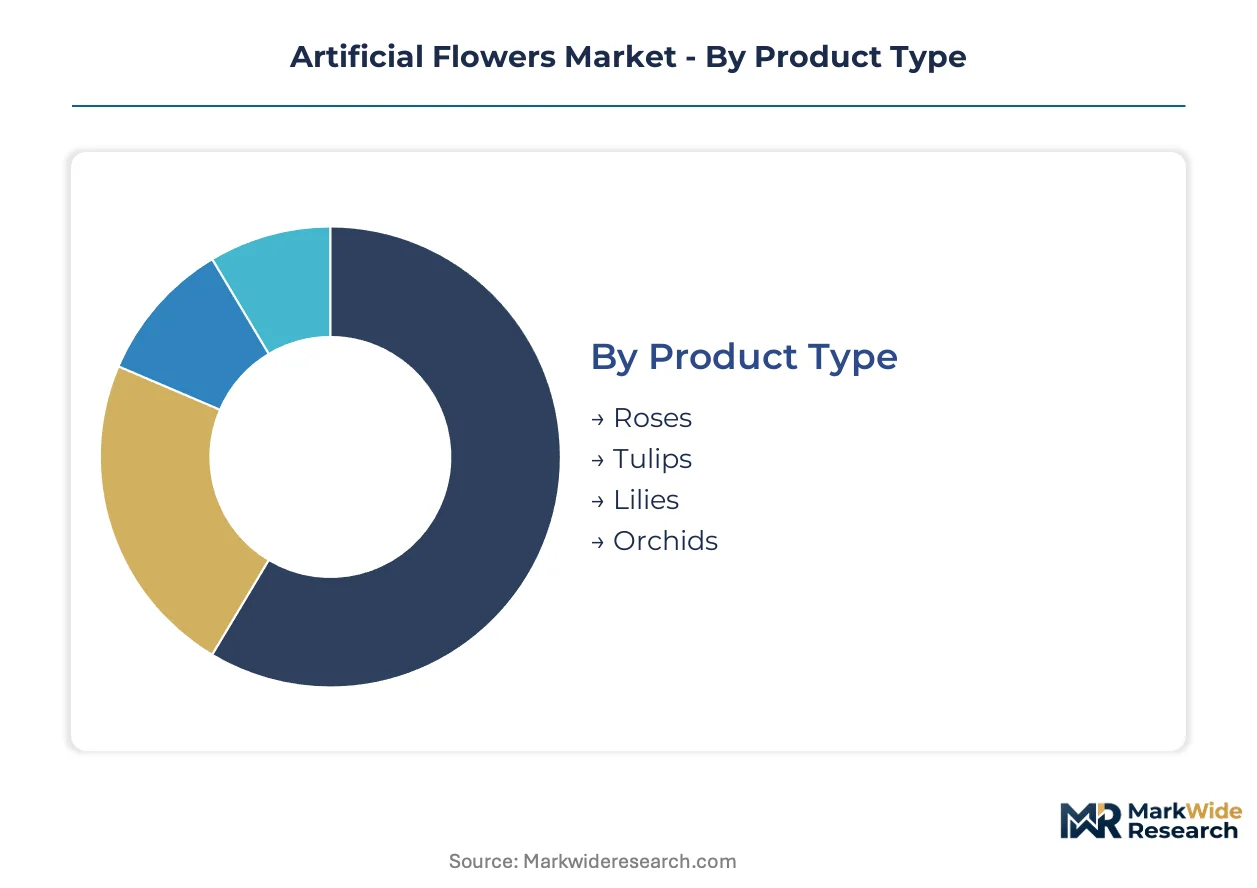
Artificial flower procurement patterns diverge sharply between mass-market volume plays and precision-crafted premium segments. Understanding where margin pools concentrate versus where scale advantages dominate determines supplier positioning and channel strategy.
Product Type:
Volume leadership sits with traditional blooms, while premium event work drives specialized cultivars requiring hand-finished detailing.
- Roses:Multi-petal silk constructions dominate hotel lobby installations and corporate reception areas. Dongguan factories achieve cost parity through automated petal cutting. Procurement teams at US hospitality chains specify modular stem systems for seasonal color rotation.
- Orchids:Polyurethane foam molding with embedded wire armature now commands 70% of new US banquet installations. The format reduces labor input to one-third of hand-wrapped alternatives while maintaining petal density consistency. German event rental companies specify foam orchids for multi-year corporate contracts.
- Tulips:Polyester-blend constructions serve European mass-market retail through private-label programs.
- Lilies:Hand-painted variants target luxury residential interiors in Italy and Portugal.
Mature deployment sits with roses. Newer deployment is concentrated in orchids.
Material:
Cost scalability separates commodity inputs from formulations engineered for regulatory compliance and tactile authenticity.
- Silk:Natural protein fiber constructions retain dominance in premium residential and hospitality segments where surface sheen and drape characteristics justify unit premiums. REACH-compliant dye houses in Guangdong now account for 60% of EU-bound silk rose volume. Japanese department stores specify silk for ceremonial gift arrangements.
- Foam:Polyurethane formulations with phthalate-free plasticizers represent the steepest expansion trajectory in event decoration. ECHA restrictions on legacy plasticizers have forced reformulation investments among Pearl River Delta molders. US rental companies prioritize foam for durability in high-rotation banquet service.
- Plastic:PVC and polyethylene stems serve price-sensitive retail channels in India and Southeast Asia.
- Polyester:Recycled PET substrates gain traction in EU markets under CSRD supply-chain pressure.
Volume concentration remains with silk. Compliance-driven substitution is accelerating fastest in foam.
Application:
Recurring revenue potential varies dramatically between one-time consumer purchases and institutional refresh cycles.
- Home Decor:Mass-market arrangements through big-box retail sustain the broadest consumer base. Individual purchasers favor pre-assembled bouquets over component systems. French hypermarket chains rotate seasonal collections on 90-day cycles.
- Event Decoration:Corporate and wedding segments command highest per-unit margins through customized color matching and branded packaging. Texas technology campuses now contract 18-month artificial flower refresh services rather than capitalizing owned inventory. California facility managers cite hybrid work schedules reducing daily maintenance staffing.
- Floral Arrangements:Professional florists source component stems for mixed-media installations.
- Crafting:DIY hobby channels in the UK and Germany drive demand for individual stems and miniature formats.
Transactional volume concentrates in home decor. Subscription-based deployment is expanding most quickly in event decoration.
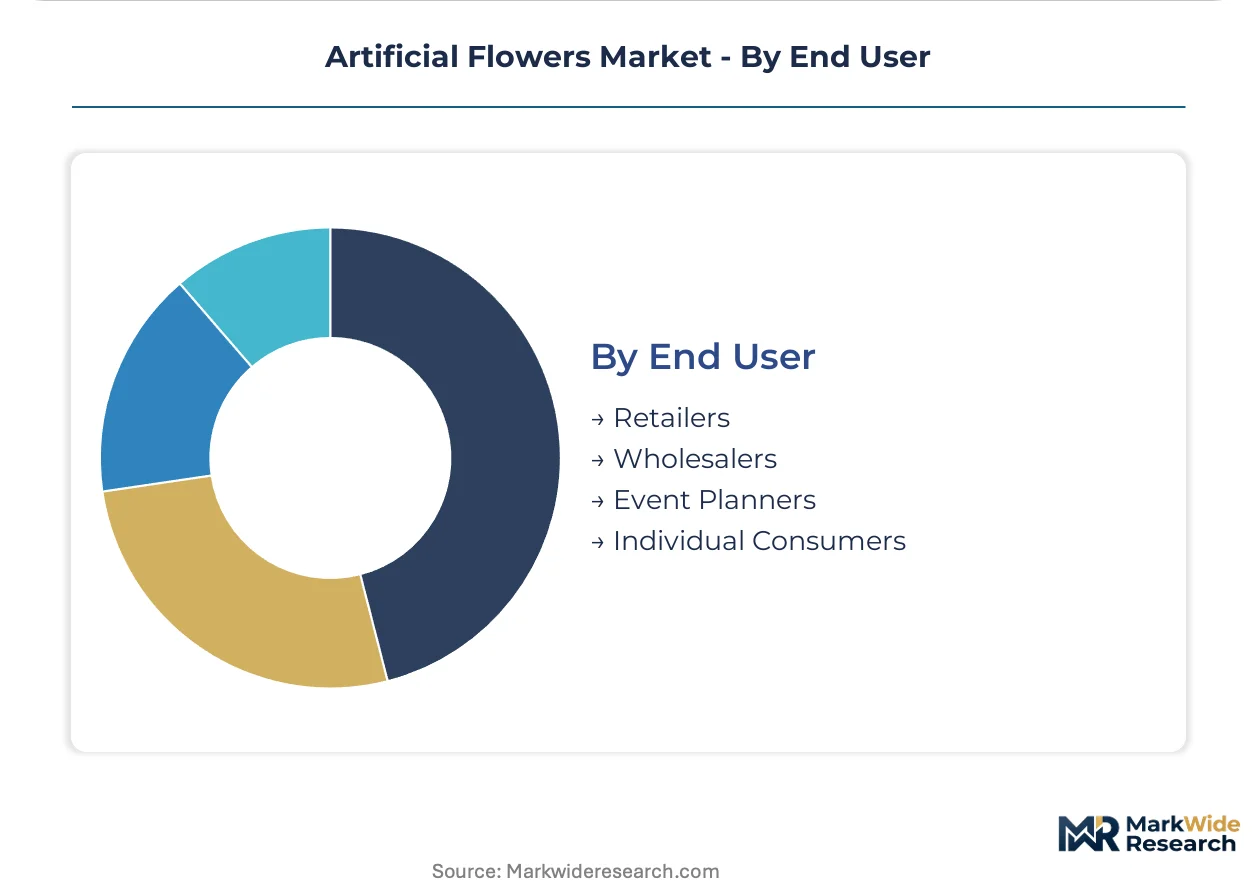
End User:
Channel control determines margin capture, with direct institutional relationships outperforming wholesale intermediation.
- Event Planners:Corporate procurement teams now source modular arrangements on multi-year refresh cycles rather than seasonal fresh-flower contracts. Direct supplier relationships bypass traditional floristry markups. Nearly Natural controls this channel in North America through property-level sales teams.
- Retailers:European mass-market buyers enforce phthalate-free procurement clauses, stranding pre-2023 petroleum-based inventory. German department stores prioritize suppliers with third-party-verified dye-process water recycling. Private-label programs concentrate volume with Dongguan Fusheng for silk roses.
- Wholesalers:Traditional distribution intermediaries face compression as manufacturers build direct B2B capabilities.
- Individual Consumers:E-commerce channels displace brick-and-mortar floral shops for replacement purchases.
Established procurement patterns persist with retailers. Direct institutional engagement is gaining share fastest among event planners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of artificial flower volume while the United States and European Union absorb the highest-value imports. This production-consumption divide shapes logistics corridors, regulatory compliance requirements, and supplier margin structures across major trade routes.
United States
Corporate campus refresh programs and hospitality procurement teams drive demand for modular silk arrangements. EPA guidance on synthetic polymer disposal pressures importers toward phthalate-free foam formulations. Texas and California facility managers contract subscription-based artificial flower services to reduce maintenance staffing.
Germany
Department-store buyers enforce REACH-compliant procurement clauses and prioritize water-recycling verification in dye processes. ECHA restrictions on legacy plasticizers accelerate reformulation investments among Pearl River Delta suppliers. German event rental companies specify foam orchids for multi-year corporate banquet contracts.
China
Dongguan and Foshan factory clusters achieve cost scalability through shared dye houses and wire-stem suppliers serving global private-label programs. GB standards for textile products reshape export compliance documentation. Guangdong manufacturers face CSRD pressure from European retail buyers demanding batch-level carbon footprints.
United Kingdom
DIY hobby channels and e-commerce displacement of traditional floristry sustain mass-market stem demand. British retailers rotate seasonal collections on compressed 90-day cycles. London-based interior design studios source hand-finished arrangements for luxury residential projects.
France
Hypermarket chains drive volume through rapid seasonal assortment turnover. ANSM oversight of consumer product safety elevates documentation requirements for imported synthetic materials. French event planners source larger foam orchid volumes for recurring corporate installations versus perishable alternatives.
Artificial Flowers Market Vendor Landscape
The competitive structure tilts toward scale-driven manufacturers with direct institutional channel control. Mid-volume producers face margin compression from petroleum input volatility and dual-certification timelines. Three archetypes dominate: Guangdong-based mass-volume fabricators, North American direct-to-hotel distributors, and European hand-finished specialists. Capacity consolidation and regulatory compliance investments represent the dominant competitive moves across tiers.
Among Chinese fabricators, Dongguan Fusheng Arts Products Co., Ltd and Foshan Tongxin Artificial Flowers Co., Ltd occupy positions within the scale-driven tier serving global private-label programs. Nearly Natural, Inc. exemplifies the direct-channel archetype controlling property-level procurement relationships in North America. Diane James Designs, Inc. represents the hand-finished specialist segment targeting luxury residential interiors.
| Leading Market Players |
|---|
| FRS Holding S.R.L. (Evergreens) |
| Diane James Designs, Inc. |
| Dongguan Fusheng Arts Products Co., Ltd |
| TreeLocate (Europe) Limited |
| Nearly Natural, Inc. |
| National Tree Company, LLC |
| Vickerman Company |
| Foshan Tongxin Artificial Flowers Co., Ltd |
| Xuzhou Pleasant Arts Flower Co., Ltd |
| Others |
Supply Flow & Price Mechanics
Horizontal integration across Guangdong dye houses and wire-stem suppliers anchors cost scalability for mass-volume producers while compressing margin pools for mid-tier competitors lacking captive input sourcing. This consolidation pattern concentrates pricing power with Dongguan and Foshan factory clusters serving global private-label programs, leaving smaller molders exposed to petroleum-based input volatility.
Pricing Analysis
Margin tightening in mid-volume tiers reflects crude oil index fluctuations pressuring polyester resin and synthetic dye costs. Three-tier pricing structure across hand-finished luxury, REACH-compliant premium, and mass-market economy levels separates Diane James Designs from Nearly Natural and Dongguan fabricators respectively. Cost-down pressure on foam orchid formulations accelerates because ECHA phthalate restrictions force reformulation investments. Retail buyers exhibit highest price sensitivity in home decor segments, while corporate event planners absorb premiums for modular refresh systems.
Supply Chain Analysis
ISO 14001 certification gates now determine supplier eligibility for EU hospitality RFPs as CSRD Scope 3 reporting mandates cascade through procurement criteria. Manufacturing gravity centers on China's Guangdong province, with secondary molders in Vietnam and India serving price-sensitive Southeast Asian retail. Raw material flows draw from petroleum-based polyester resins, polyurethane foam precursors, and colorfast dye chemicals. Single-region production concentration creates tariff exposure in Pearl River Delta logistics corridors. Distribution runs through direct-to-hotel channels in North America and wholesale floristry intermediaries in European mass-market retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over REACH-compliant dye houses and direct institutional channel relationships determines margin capture. Players securing captive supply of phthalate-free foam formulations and property-level sales teams gain sustainable positioning.
For Market Incumbents: Anticipate margin compression from biopolymer dye convergence by securing backward integration into algae-derived colorant suppliers and recycled PET substrate sources. Defensive consolidation should prioritize acquisition of Italian and Portuguese hand-finished arrangement houses facing color-matching technician scarcity, preserving artisan capability for luxury residential segments.
For New Entrants and Emerging Players: The price-point gap between Diane James luxury positioning and Dongguan mass-volume output creates white-space opportunity for mid-tier REACH-certified foam orchid specialists. Target German event rental companies and Texas technology campus facility managers with subscription refresh service models. Go-to-market traction requires CSRD-compliant carbon accounting documentation and 18-month rotation cycle contracting.
For Investors and Strategic Acquirers: Exit pathways concentrate in direct-to-hotel distribution platforms and REACH-certified Guangdong manufacturing assets with auditable supply chains. Long-term viability favors vertically integrated players controlling both formulation compliance and institutional procurement relationships. Watch for inflection when EPA finalizes synthetic polymer disposal guidance triggering inventory repricing across US importers.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Investment | ECHA phthalate restrictions force polyurethane foam reformulation for EU market access. |
| Direct-to-Hotel Channel Buildout | Property-level procurement teams at US hospitality chains bypass wholesale floristry markups. |
| CSRD Carbon Accounting Implementation | Batch-level footprint documentation secures RFP eligibility for 2025 hospitality contracts. |
| Biopolymer Dye Convergence | Algae-derived colorants open luxury residential positioning where chemical-free claims command premiums. |
| Subscription Refresh Service Launch | Texas and California facility managers contract 18-month rotation cycles reducing maintenance staffing. |
Methodological Framework
Document review covered trade customs data, ECHA regulatory filings, and EPA guidance documents, complemented by interviews with procurement directors at US hospitality chains, Guangdong factory operations managers, German department-store buyers, and Italian hand-finished arrangement artisans. Secondary validation drew from SEC supplier disclosures, REACH SVHC candidate lists, and CSRD implementation guidance. Bottom-up volume modeling and top-down value triangulation reconciled segment outputs.
Segment-level projections across product type, material formulation, application, and end-user channel were generated across the analysis window. CAGRs were derived from regression analysis against crude oil indices, regulatory implementation timelines, and hospitality procurement cycle data. Forecast inputs incorporated REACH plasticizer phase-out schedules, EPA synthetic polymer disposal guidance evolution, and Guangdong manufacturing capacity utilization rates.
Underlying measurement precision varies by segment; foam orchid and silk rose volume data carry tighter precision than hand-finished lily and tulip artisan output. Forecasts reflect assumptions regarding regulatory implementation consistency and petroleum input cost stability. A model refresh is warranted upon material change in EPA final polymer disposal rules or ECHA SVHC list expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
North America Flowerpots Market
Home & Garden
Lawn and Gardening Consumables Market
Home & Garden
US Garden Planter Market
Home & Garden
North America Floral Gifting Market
Home & Garden
Flowerpots and Planters Market
Home & Garden
Japan Flower Pots Market
Home & Garden
Lawn and Garden Water Equipment Market
Home & Garden
Aquarium LED Lighting Market
Home & Garden
Aquarium Decor Market
Home & Garden
Wine Racks Market
Home & Garden
Asia-Pacific Bonsai Market
Home & Garden
Artificial Plants and Flowers Market
Home & Garden
Bird House Market
Home & Garden
Hedge Trimmer Market
Home & Garden
Landscaping Products Market
Home & Garden
United States Lawn Care Market