
 Japan Cookware Market | 2026-2036
Japan Cookware Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Cookware Market Insights
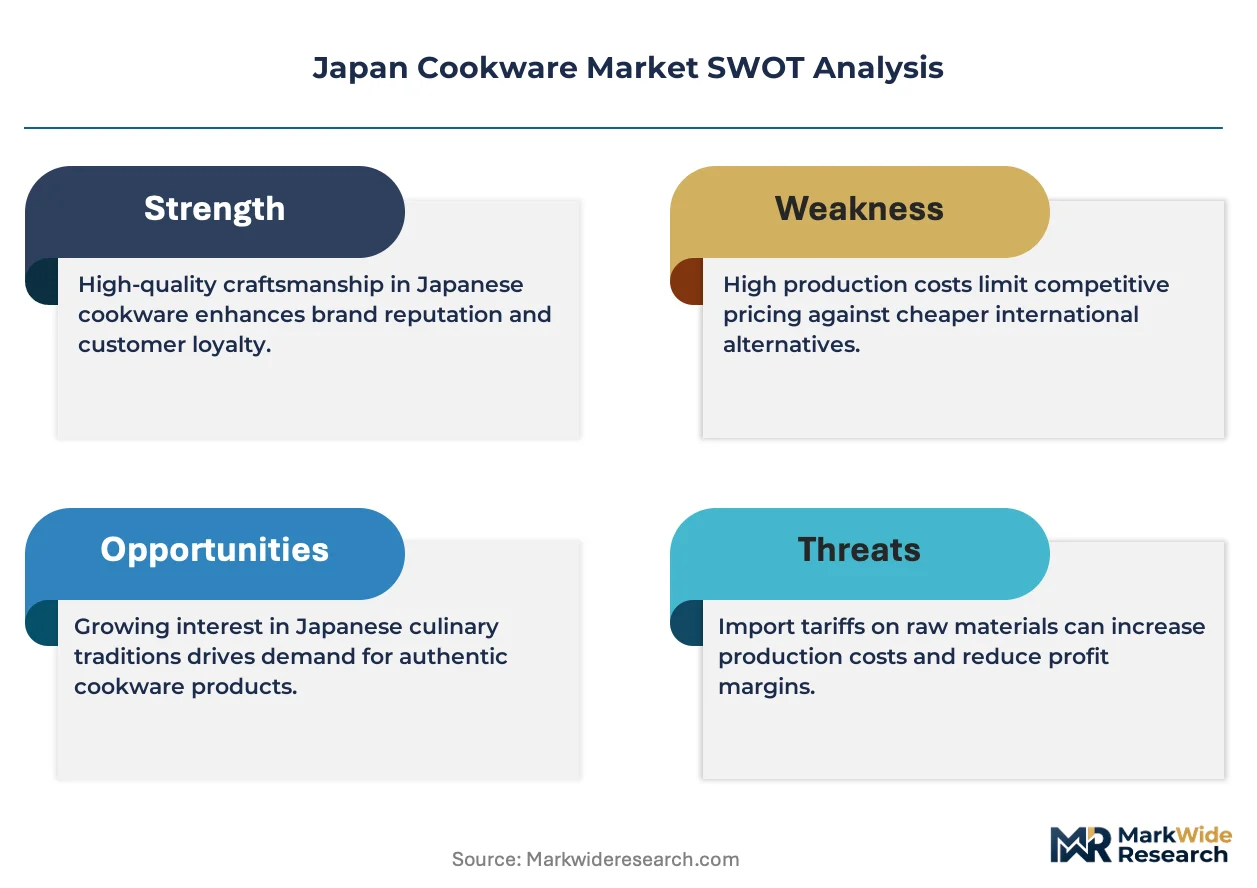
JIS S 2053 certification for metal cookware safety is unwinding the competitive landscape, forcing smaller foundries to upgrade testing protocols or exit. Tiger Corporation leverages vertical integration across its Osaka manufacturing base to control alloy sourcing costs. HARIO Co., Ltd. anchors its position through specialized heat-resistant glass and ceramic product lines that command premium placement in specialty stores.
Japan cookware encompasses vessels and appliances engineered for thermal conductivity, corrosion resistance, and compatibility with induction, gas, and electric heat sources, typically fabricated from stainless steel with copper or aluminum cores, cast iron with enamel coatings, or ceramic-reinforced non-stick surfaces. The primary purpose spans residential meal preparation and commercial foodservice operations requiring precise temperature control and durability under repeated thermal cycling. Stainless steel fry pans and saucepans dominate volume in household channels, while cast iron and ceramic non-stick woks capture margin concentration in restaurant and hotel procurement. Online retail for cookware sets is expanding fastest as direct-to-consumer brands bypass traditional department store markups.
METI enforces energy-efficiency labeling under the Top Runner Program, compelling manufacturers to optimize induction-compatible base designs and reduce standby power in electric cookware. The Food Sanitation Act administered by Japan's Ministry of Health, Labour and Welfare governs heavy-metal migration limits, directly influencing coating formulations and surface treatment choices. Stakeholders must monitor evolving amendments to JIS standards and energy regulations to determine whether backward integration into alloy production or partnership with certified foundries offers superior compliance economics.
Market Dynamics
METI's Top Runner Program is compressing replacement cycles across Japan's cookware base by mandating induction-compatible designs and penalizing standby power inefficiency in electric appliances.
Growth Catalysts
- Tokyo fine-dining procurement:Michelin-starred kitchens are specifying multi-ply stainless steel with copper cores for thermal precision, pulling premium inventory through specialty distribution channels.
- Energy-efficiency mandates:METI's labeling requirements are redirecting manufacturer R&D budgets toward induction base optimization and rapid-heating coil integration.
- Kanto urban density:Compact Tokyo apartments are accelerating turnover for space-efficient, stackable cookware sets with modular lid systems.
Market Restraints
- Nickel price volatility:Stainless steel 304 input costs fluctuate with Indonesian ore export quotas, squeezing margin on mid-tier saucepans and stockpots.
- JIS S 2053 compliance burden:Heavy-metal migration testing protocols require foundries to maintain in-house metallurgical labs or outsource to certified third parties at elevated cost.
- Cast iron supply concentration:Domestic enamel-coating capacity clusters in Osaka and Nagoya, creating geographic vulnerability to logistics disruption.
Strategic Opportunities
- Kyushu regional expansion:Fukuoka's emerging food hall and hotel construction pipeline remains undersupplied with commercial-grade induction wok stations.
- Ceramic-glass hybrid surfaces:Convergence of HARIO's heat-resistant glass expertise with diamond-infused non-stick coatings opens premium residential segments.
- Direct-to-consumer subscription:Online cookware rental and seasonal replacement models bypass department store markups in dense urban corridors.
Industry Challenges
- Alloy metallurgist scarcity:Foundries struggle to recruit technicians capable of calibrating copper-aluminum core bonding for induction compatibility.
- JIS certification timeline:New product approvals require six-to-nine month testing windows, delaying seasonal inventory positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Cookware Market |
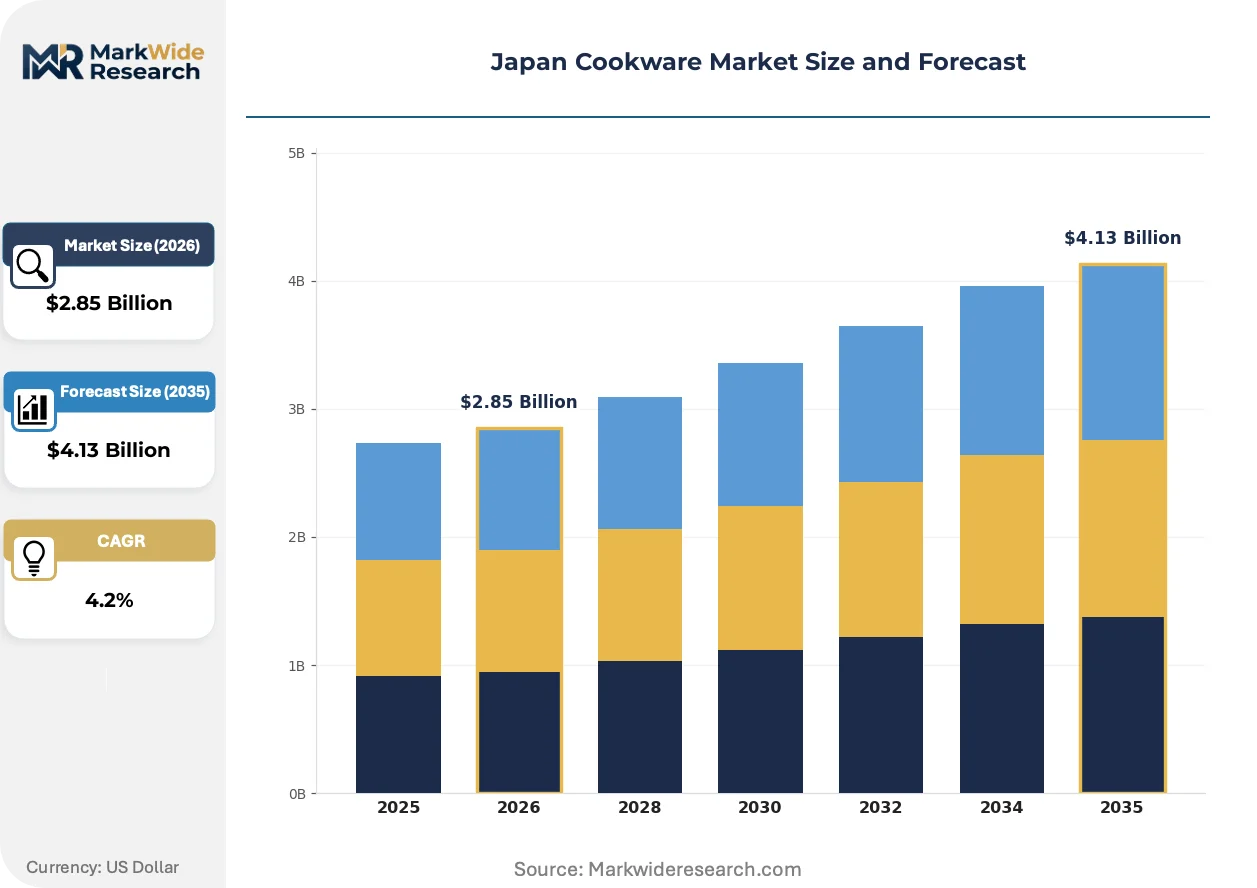
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fry Pans, Saucepans, Cookware Sets, Woks Material: Stainless Steel, Cast Iron, Non-Stick, Ceramic Distribution Channel: Online Retail, Hypermarkets, Specialty Stores, Department Stores End User: Households, Restaurants, Hotels, Catering Services |
| Companies Covered | Noritake Co., Limited, HARIO Co., Ltd., Panasonic Corporation, Tiger Corporation, Zojirushi Corporation, Yoshikawa Metal Industry Co., Ltd., Vermicular, Kyocera Corporation, Mitsubishi Electric Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Cookware Market Trends and Innovations
Material science breakthroughs and regulatory pressure on energy efficiency are converging to remake Japan's cookware competitive landscape around thermal performance metrics and circular design.
Multi-layer composite bases integrating copper cores with ferritic stainless steel exteriors are displacing single-material construction in premium residential and commercial channels. Osaka-based foundries report accelerated adoption among hotel procurement teams seeking faster boil times on induction surfaces. This displacement is compressing demand for traditional aluminum-clad designs in the mid-premium tier.
METI's enforcement of standby power limits under the Top Runner Program is compelling electric cookware manufacturers to redesign control boards and heating element activation logic. The industrial consequence falls heaviest on rice cooker and electric griddle producers, who must absorb component cost increases or sacrifice margin. Smaller appliance specialists are responding by consolidating SKUs and focusing R&D on flagship models that can absorb compliance overhead.
Specialty retailers and department store housewares floors are losing cookware volume to manufacturer-direct online storefronts with virtual fitting tools and induction-compatibility verification. This channel rotation is most visible in Tokyo and Yokohama, where apartment-dwelling millennials research thermal conductivity specifications before purchasing. After-sales service unbundling—warranty registration, care instruction, and replacement part ordering handled entirely through digital portals—is reinforcing the shift away from brick-and-mortar intermediation.
Japan Cookware Market Segmentation
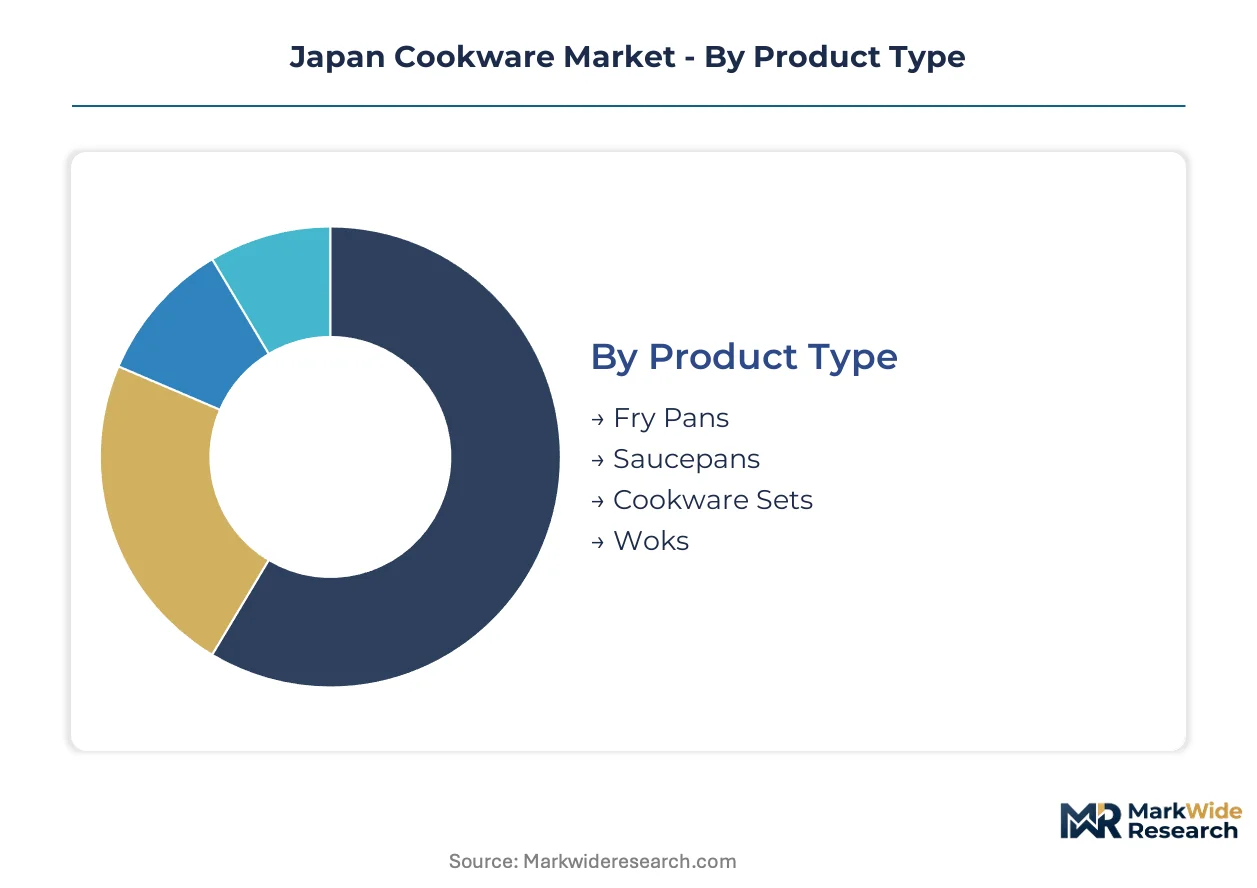
Segmentation in Japan's cookware market reveals how regulatory pressure and channel fragmentation are reshaping profit pools. Material specifications and distribution access now determine competitive positioning more than brand heritage alone.
Product Type:
Margin concentration sits with specialized vessels that command specification premiums from commercial buyers.
- Cookware Sets:Modular stackable configurations with interchangeable lids dominate residential procurement in Tokyo's compact apartments. Kanto urban density drives replacement cycles for space-optimized multi-piece assortments compatible with induction surfaces.
- Woks:Carbon steel and cast iron constructions with induction-compatible bases capture premium placement in Osaka and Nagoya restaurant supply chains. Hotel procurement teams specify rapid-heating designs for banquet operations.
- Fry Pans:Stainless steel 304 constructions with copper cores anchor mid-premium household demand.
- Saucepans:Multi-ply aluminum-core designs serve simmering and sauce reduction tasks across residential channels.
The dominant share belongs to Cookware Sets, while Woks are closing the gap fastest.
Material:
Cost tier stratification separates foundry-capital-intensive metals from coating-dependent surfaces.
- Stainless Steel:Ferritic and austenitic grades with copper-aluminum cores satisfy METI energy-efficiency mandates through superior induction compatibility. Tokyo fine-dining kitchens specify multi-ply constructions for thermal precision under repeated thermal cycling.
- Non-Stick:Ceramic-reinforced and diamond-infused coatings command specialty store placement despite JIS S 2053 heavy-metal migration testing burdens. Direct-to-consumer brands leverage online compatibility verification tools to bypass department store markups.
- Cast Iron:Enamel-coated vessels from Osaka-based foundries serve slow-cooking residential segments.
- Ceramic:Heat-resistant glass-ceramic hybrids from specialized manufacturers target premium gift channels.
Stainless Steel retains volume leadership, though Non-Stick surfaces are expanding most quickly through digital channels.
Distribution Channel:
Customer type fragmentation splits procurement between convenience-seeking households and specification-driven commercial buyers.
- Online Retail:Manufacturer-direct storefronts with virtual fitting tools and induction-compatibility verification are displacing department store intermediation. Tokyo and Yokohama millennials research thermal conductivity specifications before purchasing multi-material portfolios.
- Specialty Stores:Curated heat-resistant glass and ceramic lines from HARIO command premium placement through trained staff consultation. After-sales service unbundling through digital portals reinforces channel loyalty.
- Hypermarkets:Mid-tier stainless steel fry pans and saucepans move through high-volume suburban locations.
- Department Stores:Traditional housewares floors retain gift-oriented cookware set traffic but lose share to direct channels.
Online Retail now leads household penetration, while Specialty Stores defend margin through consultation-dependent segments.
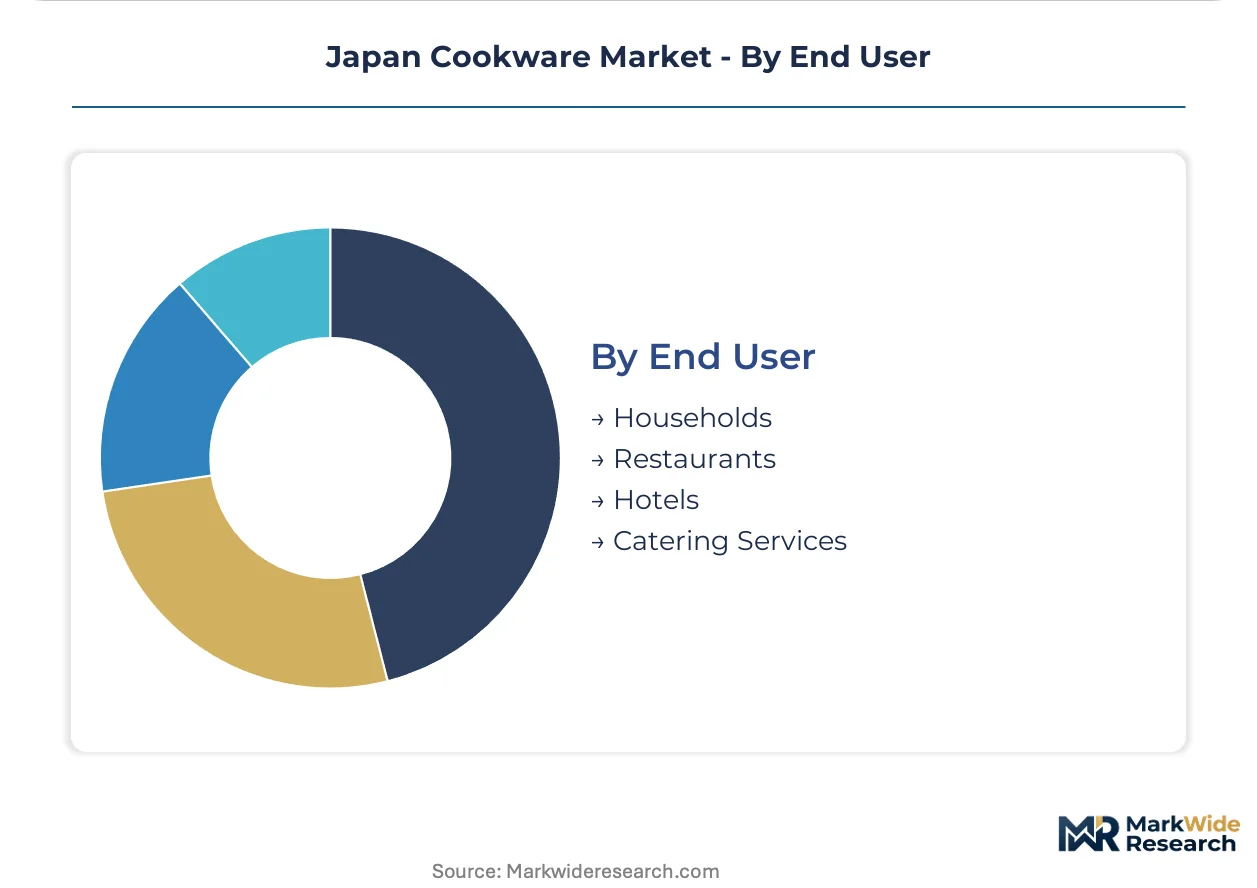
End User:
Application requirements separate thermal-precision commercial specifications from durability-focused residential needs.
- Restaurants:Michelin-starred Tokyo kitchens specify multi-ply copper-core stainless steel for precise temperature control. Procurement runs through specialized distribution channels with metallurgical certification documentation.
- Households:Compact urban dwellings in Kanto accelerate turnover for stackable induction-compatible sets with modular components. Energy-efficiency labeling under METI's Top Runner Program redirects purchase decisions toward rapid-heating designs.
- Hotels:Banquet and room-service operations source commercial-grade induction wok stations from consolidated suppliers.
- Catering Services:Volume operators prioritize durability and replacement part availability over thermal performance specifications.
Restaurants command the highest specification premiums, with Households showing the steepest expansion trajectory through digital channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's Top Runner Program for energy-efficient appliances is compressing replacement cycles across Japan's cookware base. The policy redirects manufacturer investment toward induction-compatible designs and rapid-heating coil integration. Regional demand concentrates in dense urban corridors where compact households and commercial kitchens drive multi-material portfolio turnover.
Kanto/Tokyo
Tokyo's Michelin-starred restaurant sector specifies multi-ply copper-core stainless steel for thermal precision under repeated thermal cycling. METI enforces energy-efficiency labeling that redirects procurement toward induction-compatible base designs. Specialty distribution channels in Ginza and Shibuya serve fine-dining kitchens with metallurgical certification documentation.
Kansai/Osaka
Osaka-based foundries cluster domestic enamel-coating capacity for cast iron vessels serving slow-cooking residential segments. JIS S 2053 heavy-metal migration testing protocols require in-house metallurgical labs or certified third-party outsourcing. The city's manufacturing base supplies hotel banquet operations with commercial-grade induction wok stations.
Chubu/Nagoya
Nagoya's industrial corridor hosts consolidated suppliers of rapid-heating coil systems for electric cookware manufacturers. The Food Sanitation Act governs coating formulations and surface treatment choices for regional producers. Foundries here calibrate copper-aluminum core bonding for induction compatibility across mid-premium tier production.
Kyushu
Fukuoka's emerging food hall and hotel construction pipeline remains undersupplied with commercial-grade induction wok stations. Regional procurement teams seek durable replacement parts availability over thermal performance specifications. Local distributors are expanding inventory for stackable modular cookware sets targeting compact urban apartments.
Hokkaido
Sapporo's tourism-driven restaurant sector sources heat-resistant glass-ceramic hybrids for premium gift channels. Seasonal population fluctuations create uneven demand cycles for replacement cookware inventory. Regional retailers emphasize online compatibility verification tools to bypass department store markups.
Japan Cookware Market Competitive Landscape
Player mix skews toward vertically integrated metal fabricators and specialized ceramic-glass manufacturers. The competitive structure tiers across premium multi-ply specialists, mid-tier stainless steel volume producers, and niche heat-resistant material innovators. Strategic archetypes include Osaka-based foundries controlling alloy sourcing costs, Tokyo-aligned brands serving fine-dining specification channels, and direct-to-consumer digital natives bypassing traditional retail intermediation. Dominant competitive moves center on backward integration into certified foundry capacity and geographic expansion into undersupplied regional corridors.
Among Osaka-based manufacturers, Tiger Corporation exemplifies the vertically integrated archetype through captive supply of alloy inputs across its manufacturing base. HARIO Co., Ltd. occupies a specialist position anchored in heat-resistant glass and ceramic product lines that command premium placement. Panasonic Corporation sits within the diversified industrial conglomerate tier, leveraging appliance ecosystem integration across residential and commercial channels. These three represent distinct competitive vectors: upstream cost control, material specialization, and platform breadth.
| Leading Market Players |
|---|
| Noritake Co., Limited |
| HARIO Co., Ltd. |
| Panasonic Corporation |
| Tiger Corporation |
| Zojirushi Corporation |
| Yoshikawa Metal Industry Co., Ltd. |
| Vermicular |
| Kyocera Corporation |
| Mitsubishi Electric Corporation |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory cycles for nickel-bearing stainless steel feedstock concentrate pricing power among Osaka-based foundries with captive alloy sourcing, while METI energy-efficiency mandates compress margin tolerance for mid-tier producers lacking backward integration into certified metallurgical capacity.
Pricing Analysis
Certification level under JIS S 2053 creates the primary spread between premium multi-ply copper-core vessels and commodity-grade single-ply alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal performance specifications and induction compatibility ratings. Cost compression in mid-tier stainless steel is intensifying because Indonesian ore export quotas generate input volatility. Restaurant procurement teams show the least price sensitivity due to specification mandates from Tokyo's Michelin-starred kitchens, whereas compact urban households in Kanto exhibit acute sensitivity to replacement cycle economics.
Supply Chain Analysis
Strait of Malacca transit vulnerability for Indonesian nickel ore concentrates exposes Japanese foundries to logistics disruption and input cost spikes. Primary metal sourcing draws from Indonesia, China, and domestic scrap reclamation facilities in Osaka and Nagoya. Ceramic coating formulations rest on specialized silicate imports and domestic enamel-processing capacity clustered in Kansai. Single-source vulnerability in copper-aluminum core bonding technology creates procurement risk for rapid-heating induction designs. Distribution runs through manufacturer-direct online storefronts with virtual compatibility verification, displacing traditional department store intermediation in Tokyo and Yokohama corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's cookware market sits in early-cycle expansion as METI's Top Runner Program accelerates replacement demand for induction-compatible portfolios across dense urban households and fine-dining commercial kitchens.
For Market Incumbents: Compound defensive positioning by deepening captive supply of certified alloy inputs and expanding in-house metallurgical testing capacity to compress JIS S 2053 approval timelines. Accelerate SKU consolidation around flagship induction-optimized designs that absorb compliance overhead, while defending specialty store placement through trained consultation services that digital-native entrants cannot replicate. For New Entrants and Emerging Players: Anchor in Kyushu's undersupplied commercial corridor, where Fukuoka's food hall construction pipeline lacks dedicated induction wok station suppliers. Target ceramic-glass hybrid surface innovation by licensing heat-resistant glass expertise from specialized manufacturers, then deploy direct-to-consumer subscription models with seasonal replacement offerings to bypass established retail markups in Kanto urban corridors. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because JIS certification burdens and metallurgist scarcity will force smaller foundries toward exit or acquisition by vertically integrated groups. Monitor nickel price volatility and METI amendment timelines as the critical signal for margin inflection and distressed asset availability across Osaka-Nagoya manufacturing clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Foundry Capacity | Captive JIS S 2053 testing protocols compress approval timelines from nine months toward six. |
| Ceramic-Glass Hybrid Surface Development | HARIO's heat-resistant glass expertise enables premium placement in gift and specialty channels. |
| Direct-to-Consumer Digital Launch | Virtual induction-compatibility tools bypass department store intermediation in Tokyo-Yokohama corridors. |
| Kyushu Regional Distribution Expansion | Fukuoka's food hall pipeline remains undersupplied with commercial-grade induction wok stations. |
| Subscription-Based Replacement Models | Seasonal cookware rental builds recurring revenue from Kanto's compact urban apartment dwellers. |
Research Methodology
Initial hypotheses were tested against primary input from foundry operations managers, restaurant procurement directors, specialty retail buyers, and METI regulatory liaisons and refined through secondary validation against JIS standard documentation, METI Top Runner Program filings, Food Sanitation Act amendments, customs trade records for nickel and copper ore imports, and Osaka-Nagoya industrial cluster surveys. Bottom-up demand modeling across residential and commercial end-use segments was triangulated with top-down value chain analysis.
Variance decomposition across material type, product configuration, distribution channel, and regional demand cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level replacement cycle analysis and regulatory compliance cost absorption curves. Industry-specific forecast inputs included METI energy-efficiency mandate enforcement schedules and fine-dining kitchen specification trends from Tokyo's Michelin-tracked restaurant sector.
Decision-makers should treat outputs as directional under stable nickel ore trade flows and consistent JIS certification timelines; material deviation in Indonesian export policy or METI standard amendments would warrant model refresh. Practitioners should keep alternative scenarios live as alloy price volatility and foundry consolidation dynamics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Global Nap Pod Market
Household Items
UK Digital Showers Market
Household Items
Barbecue Grill Market
Household Items
Kick Bucket Market
Household Items
Global Wet Vacuum Cleaner Market
Household Items
Collapsible Water Bottle Market
Household Items
Gas Hobs Market
Household Items
Silicone Soap Mold Market
Household Items
Sleeping Pillow Market
Household Items
Europe Ice/Cooler Box Market
Household Items
Thermos Bottle Market
Household Items
South Africa Cookware Market
Household Items
Wet Wipes and Toilet Paper Market
Household Items
Knife Set Market
Household Items
Car Air Freshener Market
Household Items
Remote Control Holder Market