
 Sleeping Pillow Market | 2026-2036
Sleeping Pillow Market Size, Share, and Industry Trends Forecast 2026-2036
Sleeping Pillow Market Intelligence
REACH chemical compliance is realigning the cost-of-entry calculus for foam suppliers serving European retailers. Tempur Sealy International leverages its vertically integrated viscoelastic manufacturing to sustain margin control across North American distribution. Nishikawa Sangyo anchors its competitive position through advanced fiber-blowing automation in Japanese domestic production. Hollander Sleep & Decor dominates private-label supply relationships with mass-market retailers through scale-driven logistics networks.
A sleeping pillow is a textile support device engineered to maintain cervical alignment during rest, typically constructed from molded viscoelastic polymers, shredded latex, blown polyester fibers, or sanitized down clusters encased in woven cotton or synthetic ticking. The primary commercial purpose is to deliver ergonomic support that reduces sleep-disordered breathing and musculoskeletal strain for individual consumers and institutional buyers. Memory foam and latex categories command premium positioning due to density-specified durability ratings and certified pressure-relief performance, while polyester fill occupies high-volume economy tiers with shorter replacement cycles. Orthopedic and side-sleeper usage segments concentrate margin pools where loft height and shoulder-cutout engineering justify specialized pricing.
The US Consumer Product Safety Commission enforces flammability standards under 16 CFR Part 1632 that shape foam composition choices for domestic manufacturers. The EU REACH regulation and ECHA restricted substance listings control chemical inputs in imported pillow textiles, while OEKO-TEX Standard 100 certification operates as a de facto market-access filter across German and French retail channels. China's GB 18401 national textile safety standard governs formaldehyde limits and pH requirements for export-oriented production bases. Stakeholders must monitor diverging chemical compliance timelines between jurisdictions to determine regional sourcing strategies and inventory segmentation.
Market Dynamics
EU Ecodesign for Sustainable Products Regulation is forcing material traceability investments across pillow supply chains, compressing margins for polyester-dependent suppliers while advantaging certified natural fiber processors.
Growth Catalysts
- REACH chemical compliance:European retailers now require OEKO-TEX Standard 100 certification as a de facto market-access filter, pulling premium foam formulations into mainstream distribution.
- Direct-to-consumer mattress bundling:US sleep system brands are integrating pillows into bundled purchases, expanding replacement frequency beyond traditional hospitality cycles.
- Viscoelastic density engineering:Molded memory foam with certified pressure-relief ratings is capturing orthopedic and side-sleeper segments through specialized loft configurations.
Market Restraints
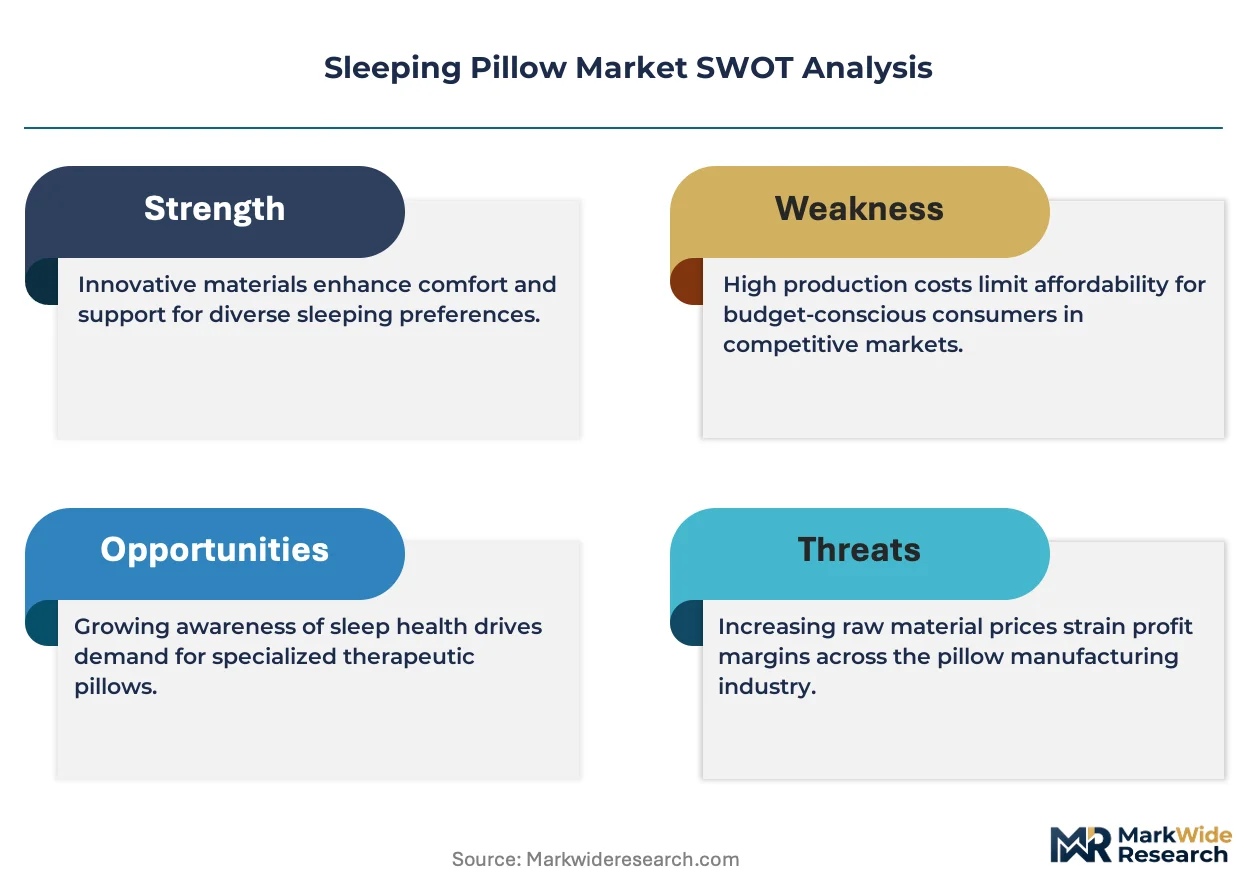
- Polyurethane input volatility:Petrochemical feedstock fluctuations compress margin predictability for viscoelastic foam manufacturers serving price-sensitive economy tiers.
- Down cluster supply concentration:Sanitized feather processing capacity clusters in specific Asian export zones, creating single-source vulnerability for luxury positioning strategies.
- Flammability standard divergence:16 CFR Part 1632 in the United States and GB 18401 in China impose incompatible foam composition requirements, fragmenting inventory segmentation.
Strategic Opportunities
- Japanese domestic automation:Advanced fiber-blowing equipment investments enable mass customization at unit economics competitive with Chinese bulk production.
- Hospitality extended replacement cycles:Premium hotel chains are compressing refresh timelines from 36 to 18 months, creating institutional volume concentration.
- Latex-shredded hybrid formulations:Natural rubber and synthetic blend engineering satisfies EU sustainability mandates while maintaining durability specifications.
Industry Challenges
- Certification timeline compression:OEKO-TEX and REACH documentation requirements extend product development cycles by 4-6 months for new material introductions.
- Legacy ERP integration:Batch-level traceability systems for Ecodesign compliance require retrofitting manufacturing execution software at mid-tier producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sleeping Pillow Market |
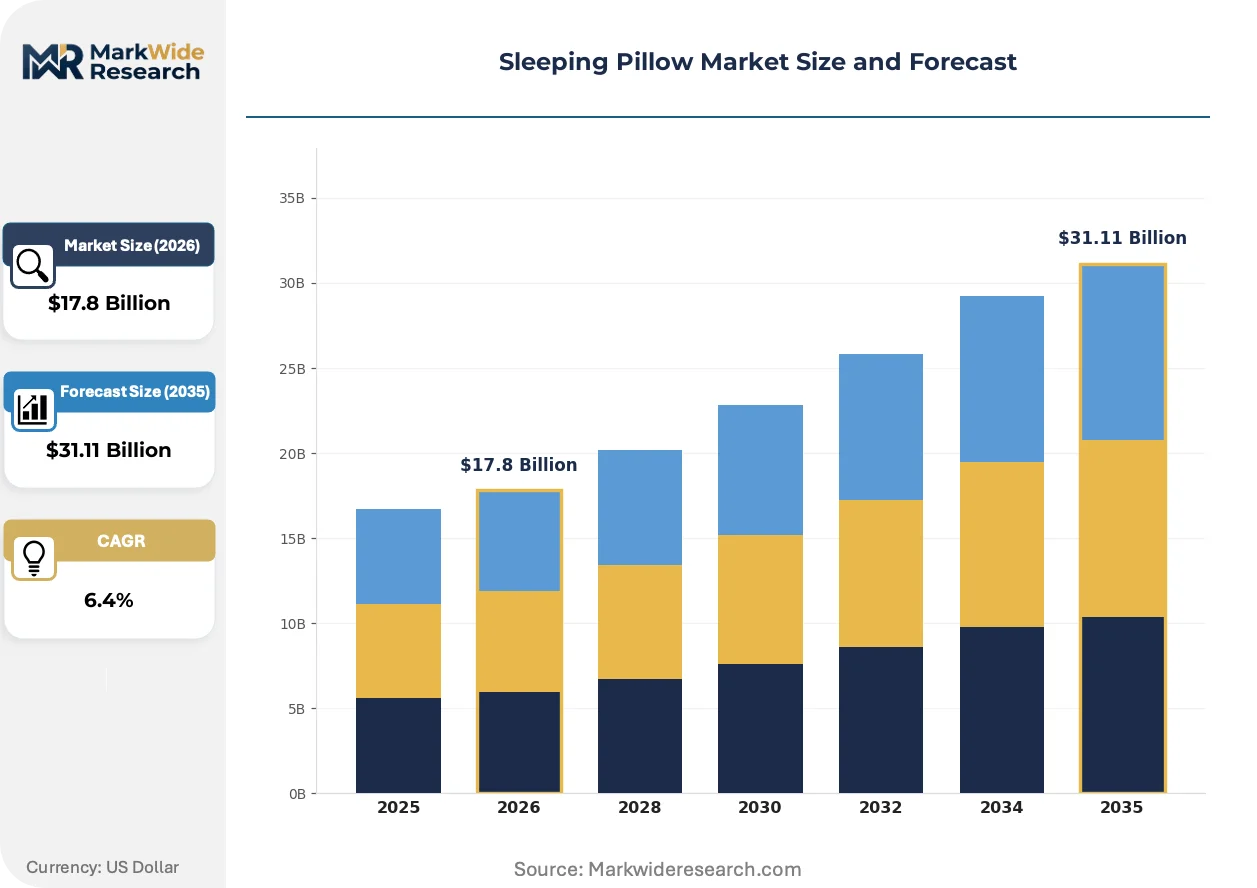
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $31.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Memory Foam, Latex, Polyester, Down Usage: Orthopedic, Side Sleeper, Back Sleeper, Stomach Sleeper Feature: Cooling, Hypoallergenic, Adjustable, Waterproof Distribution Channel: Online Retail, Department Stores, Specialty Stores, Supermarkets |
| Companies Covered | My Pillow, Nishikawa Sangyo, Tempur Sealy International, Luolai Lifestyle, Czech Feather & Down, Hollander Sleep & Decor, Latexco, American Textile Company, Wendre Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sleeping Pillow Market Strategic Shifts & Innovations
Automation and regulatory stringency are converging to reshape competitive positioning in pillow manufacturing, with material traceability and production efficiency becoming inseparable capabilities.
Computer-vision-guided fiber-blowing systems are automating loft consistency control in polyester fill production, enabling Japanese and select European manufacturers to match Asian volume economics while maintaining domestic sourcing claims. Hospitality procurement teams are adopting these systems for private-label programs requiring batch-level documentation.
REACH restricted substance listings and ECHA enforcement protocols are tightening formaldehyde and pH limits for imported textiles, forcing Chinese export-oriented bases to retest legacy inventory and accelerate certified alternative sourcing. German and French retail channels are now rejecting non-compliant shipments at port, compressing supplier response windows.
Direct-to-consumer bundling is displacing standalone pillow retail in the United States, with mattress brands capturing sleep-system attachment rates above 60 percent through subscription-style replacement programs. This channel shift is concentrating margin pools with vertically integrated manufacturers capable of coordinating foam, ticking, and logistics operations under unified quality systems.
Sleeping Pillow Market Segmentation
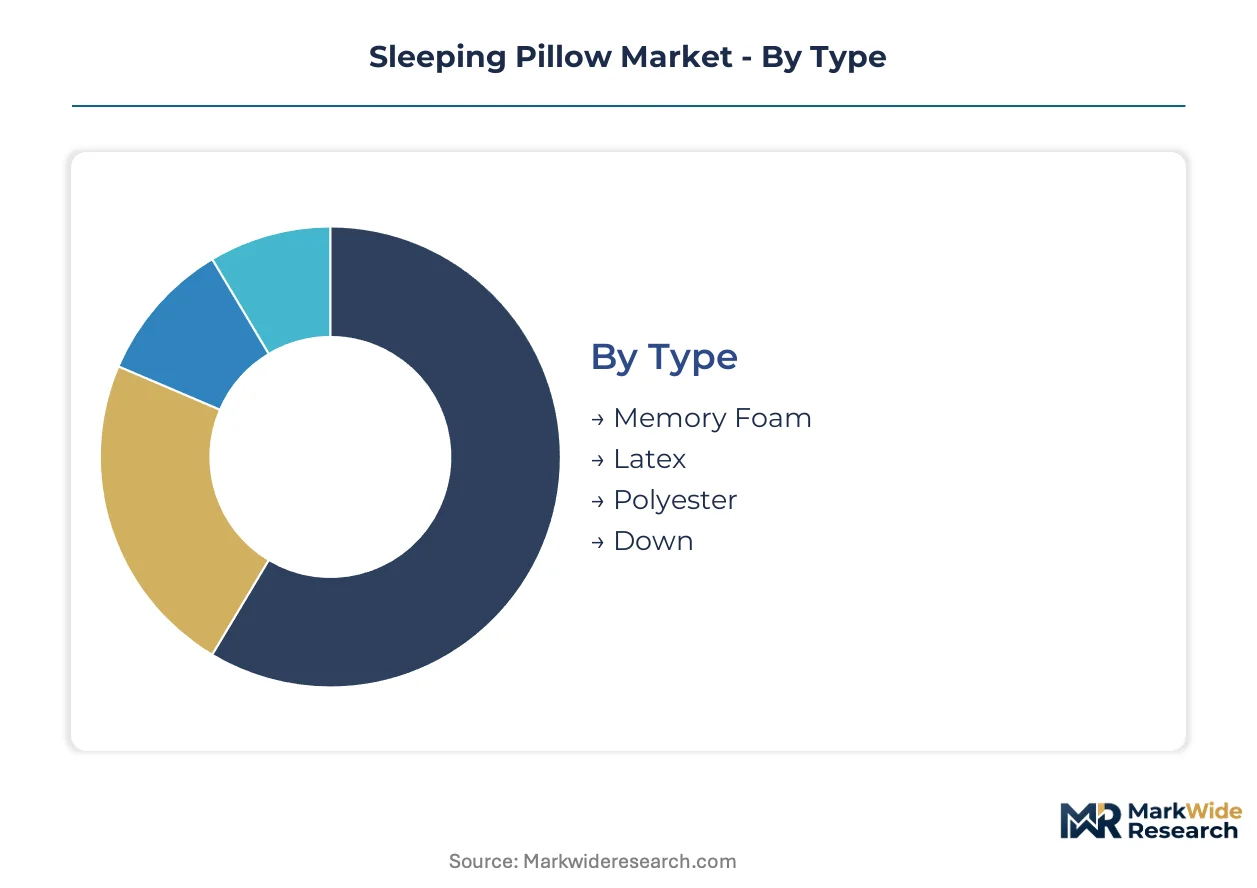
Pillow manufacturers configure production lines around fill chemistry and loft engineering specifications. Segmentation choices determine capital allocation for molding equipment, fiber-blowing automation, and compliance certification timelines.
Type:
Memory foam and latex categories demand the heaviest upfront investment in viscoelastic polymer chemistry and vulcanization presses.
- Memory Foam:Molded viscoelastic polyurethane with density-specified durability ratings between 3-5 pounds per cubic foot. Demand concentrates in US direct-to-consumer mattress bundles where pressure-relief certification justifies premium positioning. REACH chemical compliance and OEKO-TEX Standard 100 certification operate as de facto market-access filters for European distribution.
- Latex:Natural rubber derived from Hevea brasiliensis sap or synthetic styrene-butadiene blends, processed through Dunlop or Talalay vulcanization. EU Ecodesign for Sustainable Products Regulation is tightening material traceability requirements, advantaging certified natural fiber processors over synthetic-dependent suppliers.
- Polyester:Blown polyethylene terephthalate fibers with shorter replacement cycles and economy-tier pricing. Petrochemical feedstock volatility compresses margin predictability for manufacturers serving price-sensitive hospitality procurement.
- Down:Sanitized waterfowl feather clusters with luxury positioning. Supply concentration in specific Asian export zones creates single-source vulnerability for premium hotel chains and specialty retailers.
Polyester absorbs the bulk of installed capacity; memory foam is expanding most quickly.
Usage:
Orthopedic and side-sleeper configurations concentrate margin pools where specialized loft engineering commands pricing premiums.
- Orthopedic:Cervical contour designs with zoned density gradients for spinal alignment. US chiropractic and physical therapy referral channels drive institutional volume concentration.
- Side Sleeper:Elevated loft heights with shoulder-cutout engineering to maintain neutral neck positioning. German and French retail channels reject non-compliant shipments at port, compressing supplier response windows for certified foam formulations.
- Back Sleeper:Medium-loft designs with central cervical depression. Hospitality procurement teams are compressing refresh timelines from 36 to 18 months in premium hotel chains.
- Stomach Sleeper:Low-profile thin constructions to minimize cervical hyperextension. Economy-tier polyester fill dominates this price-sensitive segment with minimal certification overhead.
Side-sleeper configurations capture the steepest margin premiums; orthopedic applications are climbing the fastest on aging-population demographics.
Feature:
Cooling and hypoallergenic attributes require specialized material science investments in phase-change coatings and barrier fabrics.
- Cooling:Gel-infused foams, copper-impregnated textiles, or phase-change material coatings engineered for thermal dissipation. US Consumer Product Safety Commission flammability standards under 16 CFR Part 1632 shape foam composition choices for domestic manufacturers.
- Hypoallergenic:Encased barrier fabrics or synthetic fills engineered to resist dust mite colonization and allergen accumulation. China's GB 18401 national textile safety standard governs formaldehyde limits and pH requirements for export-oriented production bases.
- Adjustable:Zippered compartments or shredded fill designs permitting user-modified loft height. Direct-to-consumer bundling is displacing standalone retail through subscription-style replacement programs.
- Waterproof:Polyurethane laminate barriers for healthcare and hospitality institutional procurement. Incompatible foam composition requirements between US and Chinese standards fragment inventory segmentation for multi-jurisdiction suppliers.
Cooling features dominate premium positioning; hypoallergenic specifications are gaining share fastest on regulatory tightening.
Distribution Channel:
Online retail and specialty stores concentrate margin pools with divergent logistics and merchandising capital requirements.
- Online Retail:Direct-to-consumer platforms with bundled sleep-system attachment rates above 60 percent. Vertically integrated manufacturers coordinate foam, ticking, and logistics operations under unified quality systems.
- Department Stores:Mass-market private-label supply relationships dominated by scale-driven logistics networks. Batch-level traceability systems for Ecodesign compliance require retrofitting manufacturing execution software.
- Specialty Stores:Sleep-focused retailers with tactile merchandising and fitted pillow consultation. Japanese domestic automation investments enable mass customization at unit economics competitive with Chinese bulk production.
- Supermarkets:High-velocity economy-tier polyester fills with minimal specification overhead and compressed replacement cycles.
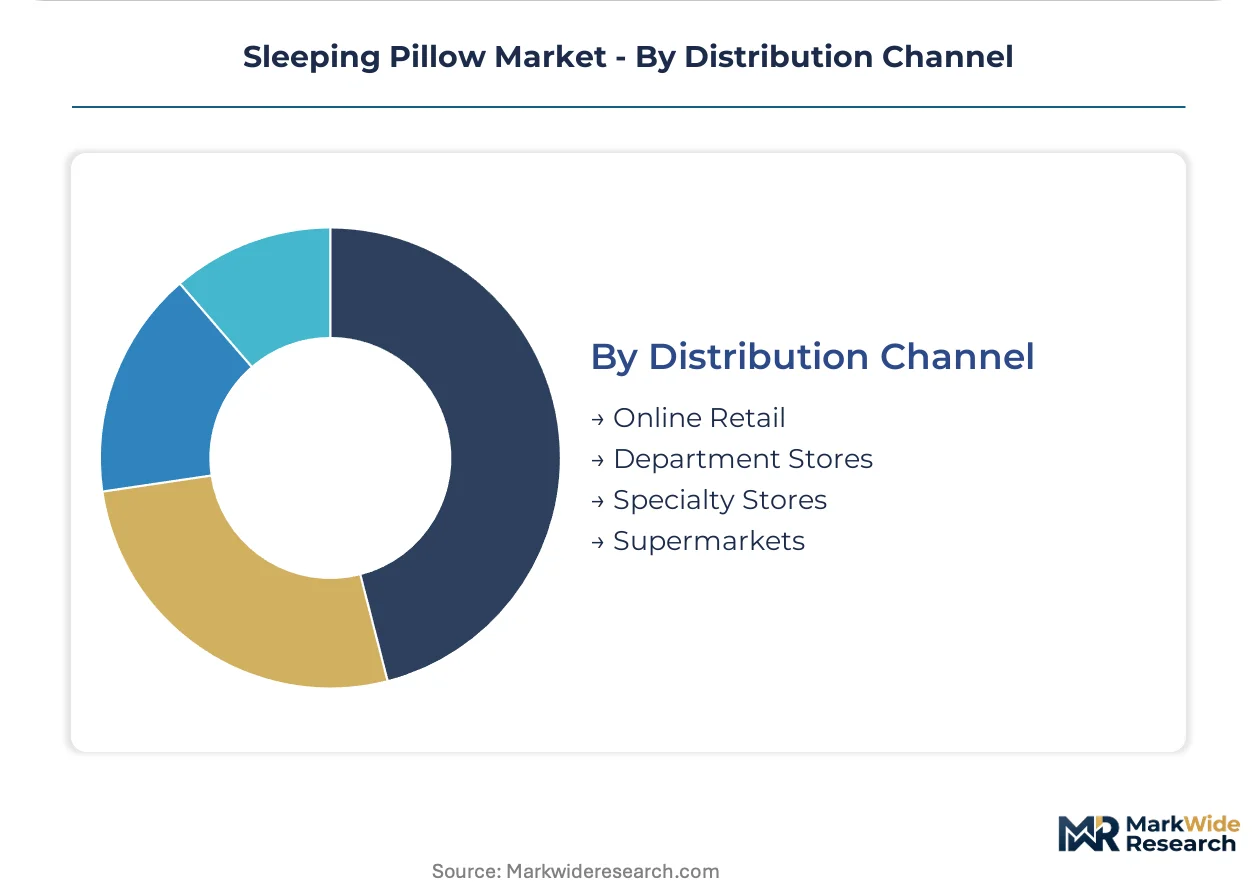
Online retail commands the steepest expansion trajectory; department stores retain the largest transaction volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Shanghai and Shenzhen drive export-oriented pillow manufacturing concentration. Special economic zones across Southeast Asia attract automated fiber-blowing investments. Regulatory divergence between jurisdictions fragments inventory segmentation strategies.
United States
Direct-to-consumer mattress bundling from Casper, Purple, and Tuft & Needle compresses replacement cycles. The Consumer Product Safety Commission enforces 16 CFR Part 1632 flammability standards that shape foam composition choices. North Carolina's textile corridor hosts vertically integrated ticking and foam operations serving hospitality procurement teams.
Germany
REACH chemical compliance and OEKO-TEX Standard 100 certification operate as de facto market-access filters for foam suppliers. The EU Ecodesign for Sustainable Products Regulation tightens material traceability requirements for textile imports. Bavaria's industrial automation sector supplies computer-vision-guided fiber-blowing systems to domestic manufacturers.
China
GB 18401 national textile safety standards govern formaldehyde limits and pH requirements for export-oriented production bases. The dual carbon goals accelerate certified natural fiber processing investments in Jiangsu and Zhejiang provinces. The Yangtze River Delta cluster concentrates sanitized down processing capacity for luxury hotel chains.
Japan
Advanced fiber-blowing automation enables mass customization at unit economics competitive with Chinese bulk production. METI industrial standards govern textile safety and chemical inputs for domestic distribution. Osaka-based Nishikawa Sangyo anchors domestic production through proprietary equipment investments.
India
BIS certification requirements for imported textiles create compliance barriers for uncertified foam suppliers. The PLI scheme for textiles incentivizes domestic fiber and ticking manufacturing scale-up. Tamil Nadu's Coimbatore cluster hosts emerging pillow component suppliers serving Middle East hospitality procurement.
Sleeping Pillow Market Key Industry Players
US producers anchor the premium viscoelastic tier; Asian specialists hold economy-scale polyester and down processing. The vendor base fragments across four strategic archetypes: vertically integrated sleep-system brands, automated domestic manufacturers, private-label logistics operators, and certified natural fiber processors. M&A activity concentrates among mattress brands acquiring ticking and foam capabilities; strategic partnerships link European retailers with compliant Asian component suppliers.
Within the vertically integrated tier, Tempur Sealy International and Nishikawa Sangyo exemplify contrasting geographic approaches to manufacturing control. Hollander Sleep & Decor occupies a position in private-label mass-market supply relationships. Latexco represents the natural rubber processing specialist archetype serving EU sustainability mandates. Czech Feather & Down anchors the sanitized down cluster for luxury hospitality procurement.
| Leading Market Players |
|---|
| My Pillow |
| Nishikawa Sangyo |
| Tempur Sealy International |
| Luolai Lifestyle |
| Czech Feather & Down |
| Hollander Sleep & Decor |
| Latexco |
| American Textile Company |
| Wendre Group |
| Others |
Cost & Logistics Intelligence
EU Ecodesign for Sustainable Products Regulation mandates batch-level material traceability for textile imports, forcing polyester-dependent suppliers to retool documentation systems while certified natural fiber processors capture pricing premiums. This specification shift compresses margins at the economy tier and concentrates margin pools with compliant foam and ticking operations.
Pricing Analysis
Short lead-time premiums now separate hospitality procurement winners from spot-inventory discounters in the pillow market. Three-tier pricing structure across premium, standard, and economy levels stratifies by OEKO-TEX certification grade and viscoelastic density rating. Price differentiation hinges on REACH compliance documentation and domestic sourcing claims. Cost compression in polyester fill is intensifying because petrochemical feedstock volatility erodes contract-margin predictability. Economy-tier hospitality buyers exhibit highest price sensitivity; orthopedic and side-sleeper segments show lowest sensitivity due to certified pressure-relief performance requirements.
Supply Chain Analysis
Certification gating through OEKO-TEX Standard 100 and REACH restricted substance listings now determines supplier viability for European retail access. Production concentrates in China, Vietnam, and India for fiber-blowing and ticking operations, with specialized viscoelastic molding anchored in the United States and Japan. Raw material flows draw from petrochemical feedstocks for polyurethane foam, Hevea brasiliensis latex from Southeast Asian plantations, and sanitized down clusters from Yangtze River Delta processing zones. Single-source vulnerability in Asian feather processing creates supply chain risk for luxury positioning strategies. Distribution runs through direct-to-consumer platforms, mass-market private-label networks, and hospitality procurement consortiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around compliance capabilities, with REACH documentation timelines and Ecodesign traceability investments forcing mid-tier polyester suppliers toward exit or acquisition.
For Market Incumbents: Cement control over certified foam formulation supply by acquiring OEKO-TEX-compliant ticking operations in Portugal or Romania. Tempur Sealy International's captive viscoelastic production model demonstrates how backward integration into polymer chemistry insulates margin from petrochemical volatility. Prioritize automation investments in fiber-blowing equipment to match Japanese unit economics without sacrificing European domestic sourcing claims. For New Entrants and Emerging Players: The gap between premium memory foam bundling and economy polyester hospitality procurement creates white-space opportunity in certified natural latex hybrids. Target German and French retail channels requiring REACH compliance but underserved by existing natural fiber processors. Enter through private-label partnerships with mattress brands seeking EU-sustainable product lines for Ecodesign-aligned merchandising. For Investors and Strategic Acquirers: The window for entry favors automated domestic manufacturers with batch-level traceability systems already deployed. Long-term viability centers on five-to-ten-year compliance moats rather than volume scale. Acquire fiber-blowing specialists with computer-vision quality control and existing OEKO-TEX certification. Watch for inflection when German port authorities begin rejecting non-compliant shipments at volume, accelerating supplier shakeout.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Chemistry | Tempur Sealy's captive viscoelastic production shields margins from petrochemical input volatility. |
| Batch-Level Traceability System Deployment | Ecodesign compliance requires retrofitting manufacturing execution software at mid-tier producers. |
| Direct-to-Consumer Bundling Expansion | Casper and Purple capture sleep-system attachment rates above sixty percent through subscription replacement. |
| Certified Natural Fiber Processing Scale-Up | Latexco's Hevea brasiliensis sourcing satisfies EU sustainability mandates while maintaining durability specs. |
| Computer-Vision Fiber-Blowing Automation | Nishikawa Sangyo's proprietary equipment enables mass customization competitive with Chinese bulk production. |
Research Approach
Multi-period observation of hospitality replacement cycles, REACH enforcement protocols, and direct-to-consumer bundling attachment rates anchored the trend analysis, supplemented by interviews with foam formulation chemists, hospitality procurement directors, private-label category managers, and textile compliance officers. Secondary validation drew from customs trade databases, OEKO-TEX certification registries, SEC filings by publicly traded sleep-system brands, and EU Ecodesign implementation guidance documents. Bottom-up segment sizing triangulated against top-down macroeconomic demand indicators.
Input-output matrices modeled fill chemistry, loft engineering specifications, usage configurations, and distribution channel dynamics across the projection horizon. Segmentation dimensions included viscoelastic density tiers, orthopedic versus standard positioning, cooling feature integration, and online versus institutional procurement channels. CAGRs derived from regression analysis of historical replacement frequency data and regulatory compliance cost trajectories. Forecast inputs incorporated petrochemical price volatility indices and hospitality occupancy recovery patterns.
Underlying measurement precision varies by segment; memory foam and latex categories carry tighter precision than polyester economy tiers due to standardized density ratings and certification documentation. Forecasts reflect assumptions about REACH enforcement consistency and Ecodesign implementation timelines. A model refresh is warranted upon material change in EU port inspection intensity or hospitality procurement consolidation events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Disposable Napkins Market
Household Items
Home Scales Market
Household Items
India Cookware Market
Household Items
Indoor Humidifier Market
Household Items
Portable Humidifiers Market
Household Items
Household Sewing Machines Market
Household Items
Smart Fork Market
Household Items
Global Disposable Toilet Seat Covers Market
Household Items
US Air Fresheners Market
Household Items
Portable Air Humidifier and Dehumidifier Market
Household Items
Scouring Pads Market
Household Items
Robotic Vacuum Cleaner Market
Household Items
Mason Jars and Canning Supplies Market
Household Items
Liquid Hand Soap Market
Household Items
Global Refrigerator Water Filters Market
Household Items
Europe Electric Cordless Lawn and Garden Tools Market