
 Silicone Soap Mold Market | 2026-2036
Silicone Soap Mold Market Size, Share, and Industry Trends Forecast 2026-2036
Silicone Soap Mold Market Insights
3D-printed master pattern technology is narrowing the gap between custom mold prototyping and mass production economics. Shenzhen Silicone Technology Co. Ltd leverages its proximity to electronics manufacturing ecosystems to source precision-machined masters at lower cost. Dow Corning Corporation sustains technology leadership through proprietary platinum-cure formulation libraries developed for medical-grade applications. Matfer Bourgeat anchors European demand through deep distribution into professional culinary and cosmetic supply channels.
Silicone soap molds are flexible, heat-resistant tooling fabricated from platinum-cured or tin-cured polydimethylsiloxane, typically rated for temperatures between minus forty and two hundred thirty degrees Celsius, designed to impart shape and surface texture to molten soap bases during controlled cooling. Custom molds command premium positioning due to design complexity and low order repetition, while square and round standard geometries compete primarily on unit cost and shipping efficiency. Food-grade silicone dominates material selection among commercial producers seeking dual-use certification for cosmetic and culinary applications.
REACH in Europe and FDA food-contact substance regulations in the United States govern platinum catalyst residues and volatile organic compound thresholds, pushing manufacturers toward certified raw material sourcing and third-party testing documentation. China's GB standards for rubber products add a compliance layer for export-oriented factories in Guangdong and Zhejiang provinces. Stakeholders must monitor evolving biocompatibility testing protocols and regional enforcement intensities to anticipate which material grades will face expanded documentation requirements.
Market Dynamics
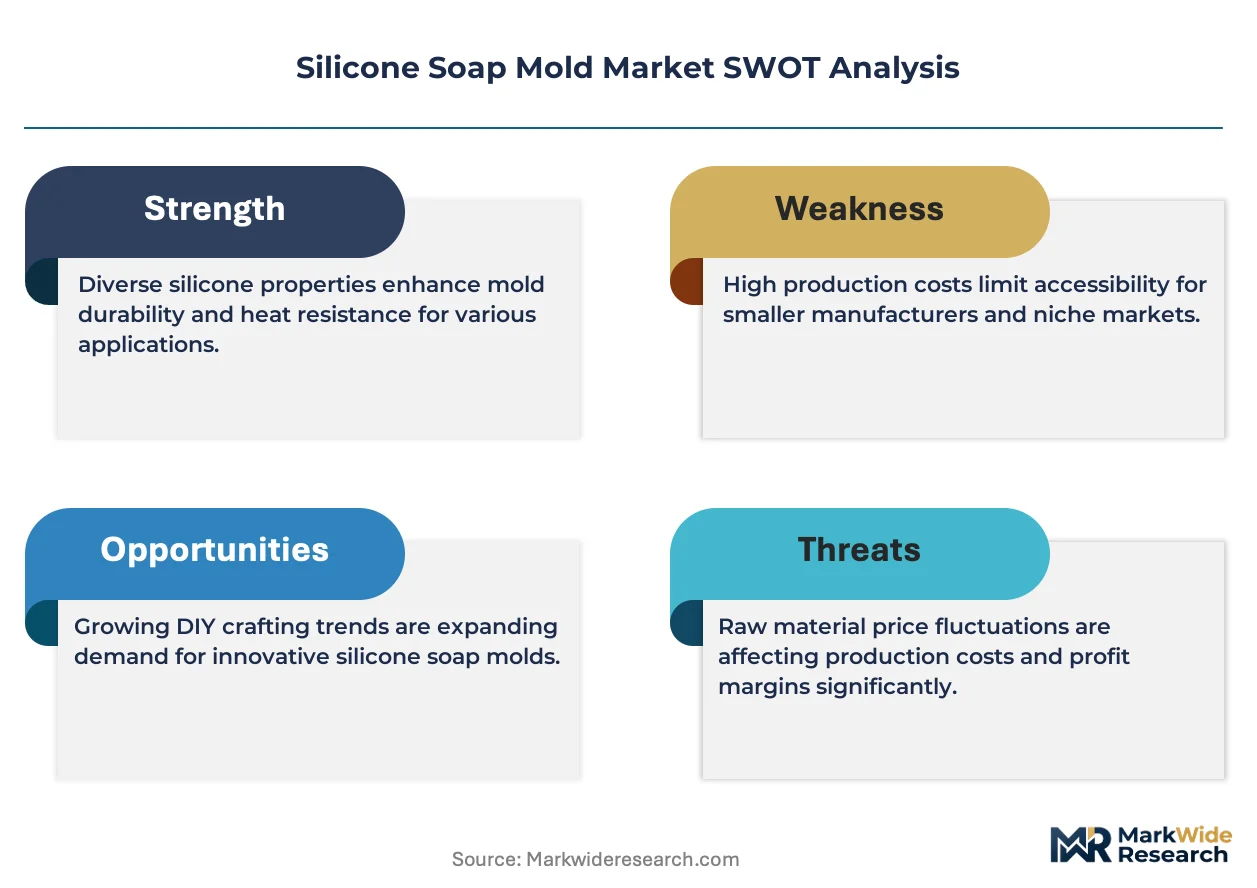
REACH compliance deadlines and FDA food-contact substance notifications are compressing raw material qualification timelines, forcing mold fabricators to consolidate supplier bases and pre-certify platinum-cure formulations before design finalization.
Growth Catalysts
- Artisan soap maker procurement surge:Small-batch cosmetic producers in North America and Western Europe are expanding flexible tooling orders for limited-run designs, creating pull for rapid-turnaround custom masters.
- Platinum-cure formulation advances:Medical-grade silicone crosslinking chemistry is migrating into soap mold production, enabling dual-use certification that satisfies both cosmetic and culinary contact requirements.
- Shenzhen electronics ecosystem spillover:Precision CNC machining capacity originally serving consumer electronics is repurposing to cut aluminum master patterns at cost points unreachable in standalone mold shops.
Market Restraints
- Platinum catalyst cost volatility:Precious metal price swings directly compress margins on food-grade silicone formulations, disproportionately affecting mid-volume producers without forward hedging.
- Guangdong supply concentration risk:Export-oriented mold fabrication clusters in Shenzhen and Wenzhou face disproportionate exposure to shipping rate spikes and port congestion cascades.
- Tin-cure silicone technical ceiling:Condensation-cure chemistry produces shorter mold lifespans and higher volatile organic compound emissions, blocking entry into certified cosmetic applications.
Strategic Opportunities
- India artisan channel underpenetration:Domestic soap-making communities in Maharashtra and Karnataka remain underserved by specialized mold distributors, presenting first-mover positioning for localized design services.
- EU Green Deal regulatory tailwind:Biobased silicone feedstock development funded under circular economy initiatives may unlock premium positioning for molds marketed on renewable content credentials.
- 3D printing-CNC hybrid master production:Converging additive and subtractive workflows are collapsing custom mold prototyping from weeks to days, enabling batch-size-one economics previously reserved for mass production.
Industry Challenges
- Platinum-cure technician scarcity:Formulation chemistry expertise concentrates among medical silicone veterans, forcing mold shops to compete for talent against higher-margin healthcare device manufacturers.
- Multi-jurisdiction certification timeline compression:Simultaneous REACH, FDA, and GB standard documentation requires parallel testing streams that strain quality assurance bandwidth at mid-scale fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicone Soap Mold Market |
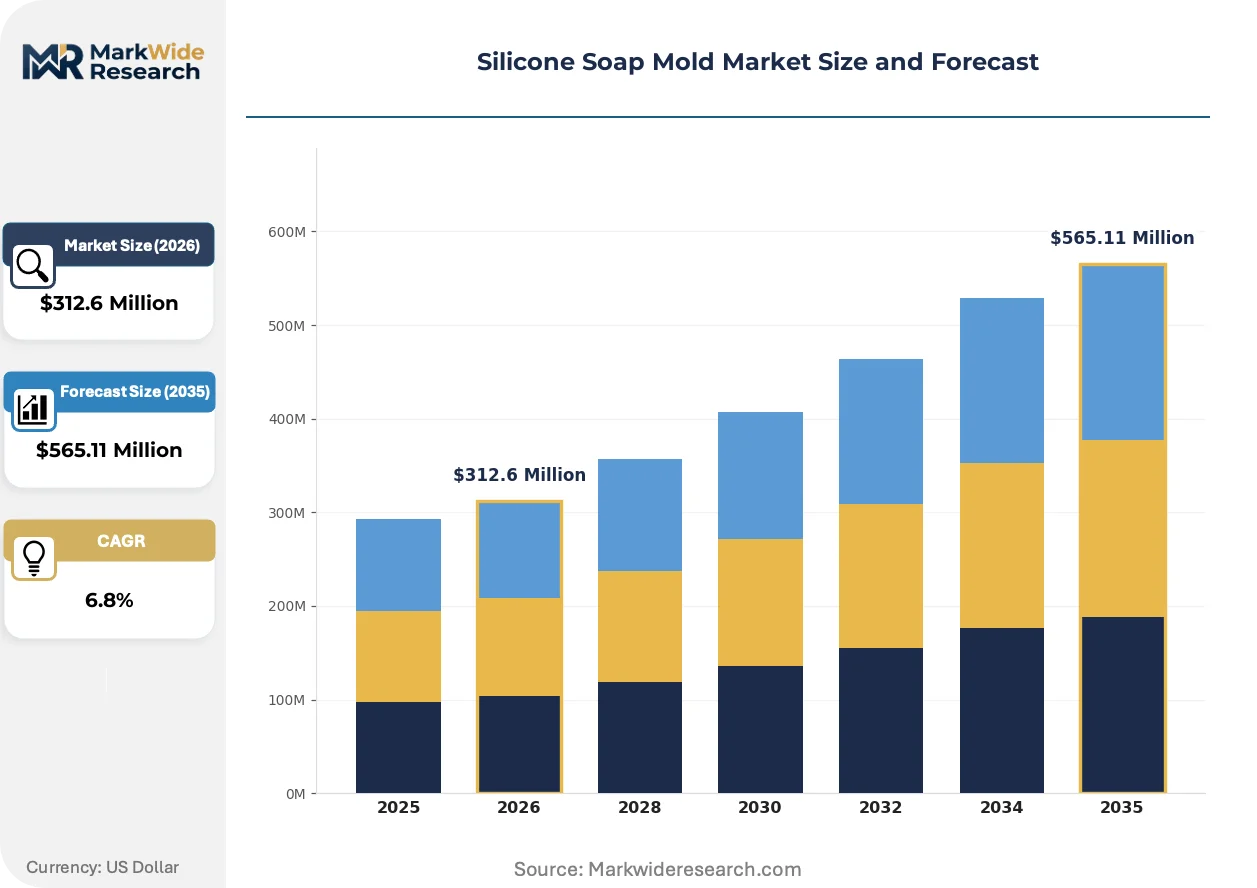
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Square Molds, Round Molds, Luxury Molds, Custom Molds Application: Handcrafted Soaps, Commercial Soaps, Glycerin Soaps, Organic Soaps Material: Food-Grade Silicone, Eco-Friendly Silicone, Reusable Silicone, High-Temperature Silicone Size: Small Molds, Medium Molds, Large Molds, Extra-Large Molds |
| Companies Covered | Matfer Bourgeat, Silicone Mold Factory, Mold Making Solutions, Shenzhen Silicone Technology Co. Ltd, Amaco, Young International, Dow Corning Corporation, Hengshui Xinhua Silicone Rubber Co. Ltd, Wenzhou Comely Silicone Products Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicone Soap Mold Market Trends and Innovations
Digital design-to-production pipelines are collapsing the traditional separation between custom mold prototyping and mass manufacturing economics, while regulatory documentation requirements harden into competitive moats.
3D-printed sacrificial master patterns are digitizing the front end of mold production workflows. Artisan soap makers and small cosmetic brands are adopting desktop resin printing to validate designs before committing to aluminum masters. This technology is digitizing the barrier between hobbyist experimentation and commercial-scale tooling procurement, compressing iteration cycles from months to days.
REACH substance restriction proposals targeting siloxane D4, D5, and D6 are tightening residual monomer thresholds in platinum-cure formulations. European mold importers now require third-party testing documentation traceable to raw material batches. Professional cosmetic supply distributors are responding by pre-qualifying supplier factories against evolving ECHA candidate list expansions.
Direct-to-maker e-commerce channels are fragmenting traditional wholesale distribution for standard geometry molds. Amazon Handmade and specialized craft marketplaces are capturing artisan soap maker volume that previously flowed through regional cosmetic supply houses. This shift is most pronounced in North American and Australian markets where postal logistics support low-weight, high-SKU fulfillment economics.
Silicone Soap Mold Market Segmentation
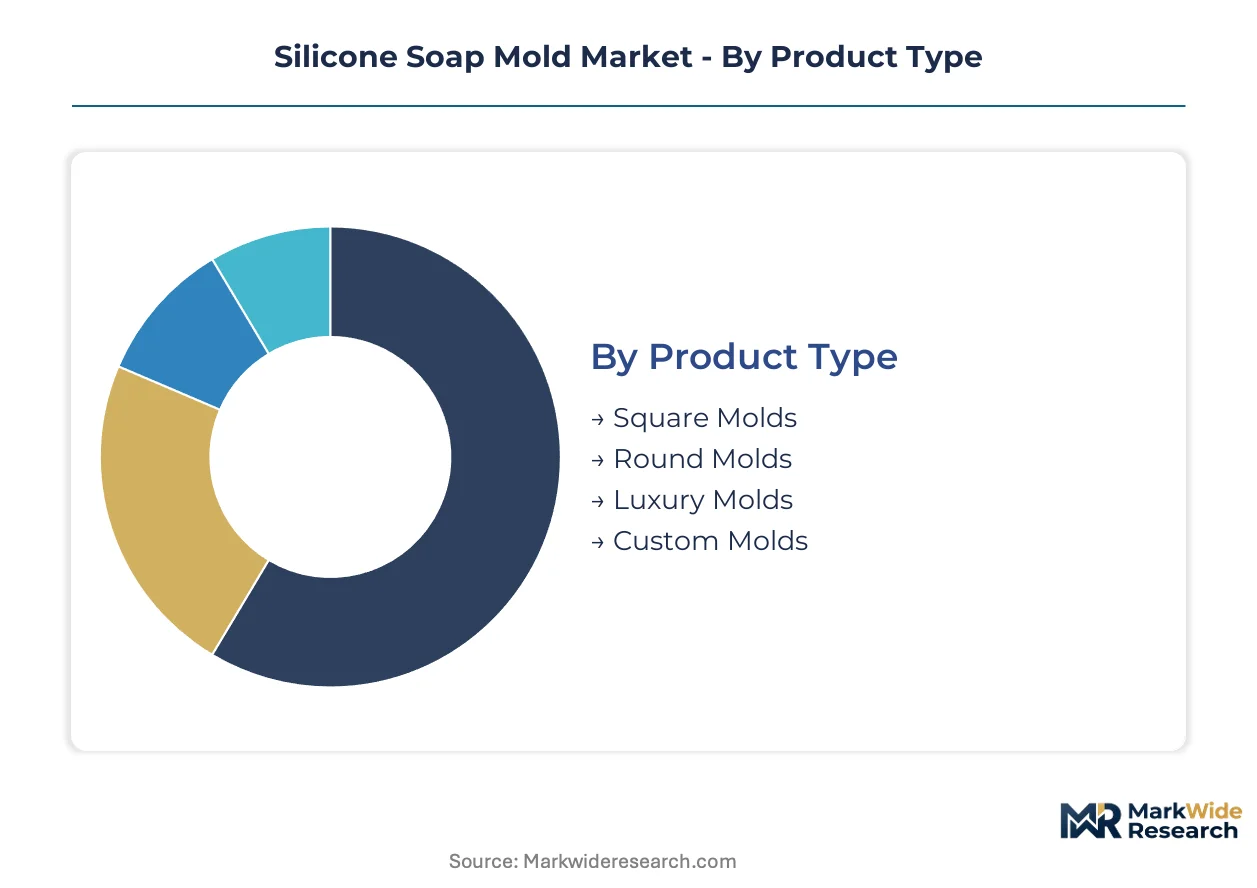
Silicone soap mold procurement patterns diverge sharply across artisan versus commercial channels, with design complexity and certification requirements driving fundamentally different supplier selection criteria. Understanding these segment boundaries reveals where margin pools concentrate and which technical specifications command premium positioning.
Product Type:
After-sales intensity varies dramatically across product types, with custom molds requiring design consultation support while standard geometries compete on fulfillment speed alone.
- Custom Molds:Bespoke tooling fabricated from CNC-machined aluminum masters enables intricate surface textures and proprietary branding elements. Artisan soap makers in Maharashtra and Karnataka are expanding procurement of rapid-turnaround custom masters for limited-run seasonal designs, though platinum-cure formulation costs compress margins at smaller batch sizes.
- Square Molds:Standardized cavity geometries optimize shipping cube efficiency and stackability for commercial producers. Demand concentrates among glycerin soap manufacturers in Guangdong province seeking high-volume, low-unit-cost tooling for export-oriented production.
- Round Molds:Circular cavity designs dominate handcrafted soap channels where aesthetic presentation drives purchasing decisions.
- Luxury Molds:Multi-cavity configurations with polished interior surfaces target premium cosmetic brands requiring flawless demolding.
Custom molds hold the largest share; momentum sits with square molds as commercial producers scale batch sizes.
Application:
Cost tier stratification separates hobbyist-grade tooling from certified commercial equipment, with regulatory documentation requirements widening the price gap.
- Handcrafted Soaps:Small-batch production emphasizes design flexibility and rapid iteration cycles over durability metrics. North American artisan makers are expanding procurement of food-grade silicone molds that satisfy dual-use cosmetic and culinary certification, particularly through direct-to-maker e-commerce channels.
- Commercial Soaps:High-throughput manufacturing prioritizes mold longevity and thermal cycling resistance. Production lines in Zhejiang province are standardizing on platinum-cure formulations to meet FDA food-contact substance notification requirements for export shipments.
- Glycerin Soaps:Transparent base formulations require flawless cavity surfaces to prevent clouding defects.
- Organic Soaps:Certification-compliant tooling must exclude synthetic release agents and tin-cure chemistry residues.
Commercial soaps hold the largest share; handcrafted soaps are climbing the fastest as artisan channels fragment traditional distribution.
Material:
Volume concentration tracks regulatory enforcement intensity, with certified material grades capturing disproportionate share in REACH-governed markets.
- Food-Grade Silicone:Platinum-cured polydimethylsiloxane formulations certified for FDA food-contact substance compliance enable dual cosmetic-culinary applications. European importers are mandating third-party testing documentation traceable to raw material batches as ECHA evaluates D4, D5, and D6 siloxane restrictions.
- Eco-Friendly Silicone:Biobased feedstock development funded under EU Green Deal circular economy initiatives targets renewable content credentials. German cosmetic supply distributors are pre-qualifying suppliers against evolving sustainability disclosure requirements.
- Reusable Silicone:Extended-lifecycle formulations reduce per-batch tooling costs for high-frequency producers.
- High-Temperature Silicone:Thermal stability ratings above 230°C serve specialized hot-process soap manufacturing.
Food-grade silicone holds the largest share; eco-friendly silicone is gaining share fastest on regulatory tailwinds.
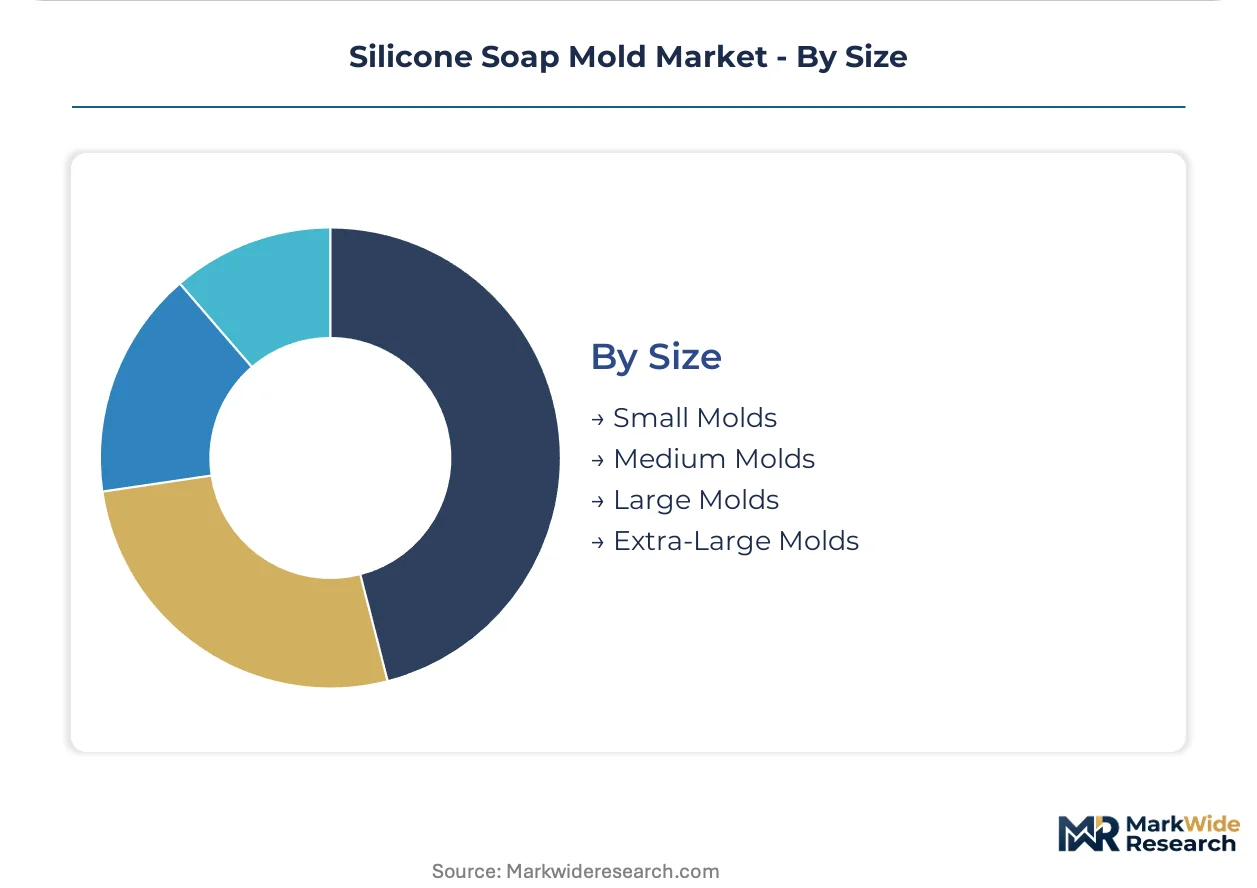
Size:
Customer type fragmentation separates individual makers from contract manufacturers, with order minimums and design services scaling inversely with mold dimensions.
- Small Molds:Single-cavity and low-cavity-count designs dominate hobbyist and entry-level commercial production. Australian craft marketplaces are capturing volume through postal logistics optimized for low-weight, high-SKU fulfillment economics.
- Large Molds:Multi-cavity industrial configurations maximize throughput for commercial soap lines. Production facilities in Shenzhen are integrating precision CNC machining capacity repurposed from consumer electronics ecosystems to cut aluminum masters at cost points unreachable in standalone mold shops.
- Medium Molds:Balanced cavity counts serve growing artisan businesses transitioning to semi-commercial scale.
- Extra-Large Molds:Custom-fabricated tooling for industrial batch production requires specialized handling equipment.
Small molds hold the largest share; large molds show the steepest expansion trajectory as commercial producers consolidate batch operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Artisan soap makers cluster in North America and Western Europe, while commercial production concentrates in Chinese manufacturing hubs. Procurement patterns split between design-flexible custom orders and high-volume standardized tooling.
United States
Direct-to-maker e-commerce channels capture growing artisan volume through Amazon Handmade and specialized craft marketplaces. FDA food-contact substance notifications govern platinum-cure formulation imports, forcing distributors to pre-certify supplier documentation. Production demand centers on small-batch handcrafted soap operations in the Pacific Northwest and Southeast regions.
China
Export-oriented mold fabrication dominates global supply, with Shenzhen and Wenzhou clusters repurposing precision CNC capacity from consumer electronics ecosystems. GB standards for rubber products add compliance documentation layers for Guangdong and Zhejiang province factories. Dual carbon goals under MEE supervision are pressuring tin-cure chemistry transitions toward cleaner platinum-cure alternatives.
Germany
Professional cosmetic supply distributors anchor European demand through deep wholesale networks serving artisan and commercial channels. REACH substance restriction proposals targeting D4, D5, and D6 siloxanes tighten residual monomer thresholds in imported silicone. Bavaria-based distributors are pre-qualifying supplier factories against evolving ECHA candidate list expansions.
India
Domestic soap-making communities in Maharashtra and Karnataka remain underserved by specialized mold distributors, creating first-mover positioning opportunities. BIS standards for rubber products provide national certification frameworks for food-grade silicone imports. Mumbai and Bangalore craft supply retailers are expanding procurement of rapid-turnaround custom masters for limited-run seasonal designs.
Australia
Postal logistics networks support low-weight, high-SKU fulfillment economics for small mold orders through domestic craft marketplaces. TGA biocompatibility guidance influences material selection among cosmetic producers seeking export certification. New South Wales and Victoria-based artisan makers are expanding food-grade silicone procurement for dual-use cosmetic and culinary applications.
Silicone Soap Mold Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement pathways. The vendor base separates into distributors with wholesale network depth, manufacturing-integrated fabricators with captive molding capacity, and design-service specialists offering rapid custom prototyping. Three archetypes dominate: culinary-cosmetic dual-certification holders, electronics-spillover precision machinists, and artisan-channel e-commerce natives. Competitive moves concentrate on geographic expansion into underpenetrated maker communities and portfolio diversification into adjacent silicone tooling categories.
Among China-based fabricators, Shenzhen Silicone Technology Co. Ltd and Wenzhou Comely Silicone Products Co. Ltd occupy positions within the manufacturing-integrated tier, exemplifying the electronics ecosystem spillover pattern. Dow Corning Corporation represents the dual-certification archetype through proprietary formulation libraries. Matfer Bourgeat anchors European channel control through professional culinary and cosmetic supply distribution depth.
| Leading Market Players |
|---|
| Matfer Bourgeat |
| Silicone Mold Factory |
| Mold Making Solutions |
| Shenzhen Silicone Technology Co. Ltd |
| Amaco |
| Young International |
| Dow Corning Corporation |
| Hengshui Xinhua Silicone Rubber Co. Ltd |
| Wenzhou Comely Silicone Products Co. Ltd |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Shenzhen precision machining clusters is compressing master pattern fabrication costs while simultaneously eroding supplier pricing power across export-oriented mold tiers. This utilization dynamic forces mid-volume fabricators toward platinum-cure formulation pre-certification investments that lock in premium positioning, while squeezing margin on standard geometry products competing purely on unit economics.
Pricing Analysis
Cost-plus contracts indexed to platinum group metal spot markets dominate food-grade silicone procurement, with Dow Corning and Shenzhen Silicone Technology leveraging formulation libraries to command certification-based premiums. Price differentiation separates FDA pre-notified dual-use grades from uncertified tin-cure alternatives, while artisan soap makers in Maharashtra and Karnataka exhibit highest sensitivity to landed cost per cavity. Pricing pressure stems from electronics-spillover CNC capacity flooding aluminum master production, eroding historical mold shop premiums.
Supply Chain Analysis
Export control restrictions on precision CNC machine tools from Germany and Japan constrain master pattern production scaling in India and Southeast Asian emerging hubs. Raw material flows center on platinum-cure polydimethylsiloxane from Dow Corning's Midland operations, aluminum billet from Guangdong smelters, and platinum catalyst from South African refiners. Single-source vulnerability concentrates in platinum catalyst supply, with distribution running through professional cosmetic supply distributors in Germany and direct-to-maker e-commerce channels in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise capable of simultaneous REACH, FDA, and GB standard compliance has become the constraining asset, with medical silicone veterans commanding compensation premiums that mid-scale mold shops cannot match. This scarcity pattern rewards early certification investments and penalizes latecomers facing parallel testing timeline compression.
For Market Incumbents: Build regulatory documentation moats by pre-certifying platinum-cure formulations against evolving ECHA D4/D5/D6 restrictions before candidate list expansion. Consolidate supplier bases to compress raw material qualification timelines, and acquire CNC machining capacity in Shenzhen electronics clusters to defend against electronics-spillover cost erosion.
For New Entrants and Emerging Players: Pursue Maharashtra and Karnataka artisan communities through localized rapid-turnaround custom master services, exploiting distributor underpenetration. Target food-grade dual-use certification as the most penetrable tier, leveraging direct-to-maker e-commerce channels to bypass wholesale network barriers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturing-integrated fabricators with captive platinum-cure formulation libraries and established professional supply distributor relationships. Long-term viability favors targets with demonstrated multi-jurisdiction certification bandwidth and Shenzhen electronics ecosystem access. Watch platinum group metal price volatility as the inflection signal forcing margin compression or hedging capability differentiation.
| Strategic Initiative | Industry Significance |
|---|---|
| Platinum-Cure Pre-Certification Investment | REACH and FDA parallel testing creates documentation barriers that block mid-tier competitors from certified cosmetic applications. |
| Shenzhen CNC Capacity Acquisition | Electronics ecosystem spillover enables aluminum master production at cost points unreachable in standalone mold fabrication. |
| India Artisan Channel Localization | Maharashtra and Karnataka soap-making communities remain underserved by specialized mold distributors with rapid-turnaround capability. |
| Direct-to-Maker E-Commerce Expansion | Amazon Handmade and craft marketplaces capture artisan volume that previously flowed through regional cosmetic supply houses. |
| Eco-Friendly Silicone Feedstock Development | EU Green Deal circular economy funding targets biobased credentials that German distributors are pre-qualifying against. |
Research Methodology
Initial hypotheses were tested against primary input from silicone mold fabrication plant managers, artisan soap maker procurement leads, professional cosmetic supply distributors, and platinum-cure formulation chemists, then refined against customs trade data, ECHA regulatory filings, FDA food-contact substance notifications, and SEC 10-K disclosures from material suppliers. Bottom-up unit economics modeling triangulated against top-down market sizing across product type, application, material grade, and size segmentation dimensions.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeling spanning custom versus standard geometries, handcrafted versus commercial end-use, food-grade versus eco-friendly material tiers, and small versus large mold dimensions. CAGRs derived from historical shipment trajectories and forward capacity expansion announcements, incorporating platinum group metal price elasticity and regulatory enforcement intensity as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in shipping rate indices, precious metal spot markets, or regional regulatory enforcement intensity would shift the trajectory. Material shifts in REACH substance restriction implementation timelines or FDA notification processing backlogs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Acrylic Aquarium Market
Household Items
Paper Towel Dispenser Market
Household Items
Flushable Wipes Market
Household Items
Europe Ice/Cooler Box Market
Household Items
Knife Market
Household Items
Automatic Dishwashing Products Market
Household Items
Europe & UK Nonstick Cookware Market
Household Items
Can Opener Market
Household Items
Umbrella Market
Household Items
Coin-Operated Laundries Market
Household Items
Stainless Steel Thermos Cup Market
Household Items
Party Balloon Market
Household Items
Smart Fork Market
Household Items
Toilet Deodorant Market
Household Items
North America Tankless Water Heater Market
Household Items
Command Hooks Market