
 Thermos Bottle Market | 2026-2036
Thermos Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Thermos Bottle Market Analysis
The EU Green Deal is broadening the addressable market for sustainable thermos bottles by mandating recyclability targets across consumer goods. Hydro Flask leverages its position in North American outdoor retail channels with stainless steel specialization. Thermos sustains brand recognition through multi-generational loyalty in Asian household markets. Zojirushi dominates precision vacuum insulation engineering with Japanese manufacturing standards.
A thermos bottle is a double-walled insulated vessel engineered to maintain liquid temperature through vacuum-sealed or foam-filled construction, typically fabricated from 18/8 stainless steel with copper-plated inner walls to minimize thermal radiation loss. Its primary commercial purpose spans portable hydration for commuters, athletes, and outdoor enthusiasts requiring extended temperature retention. Stainless steel variants anchor the premium tier due to durability and food-grade safety credentials, while 500 ml and 750 ml capacity segments capture the bulk of daily commuter and gym usage demand. Travel-oriented usage categories are expanding fastest as post-pandemic mobility patterns normalize and remote workers seek portable beverage solutions.
The US FDA regulates food-contact material safety for thermos bottle linings and seals, while the EU REACH framework restricts hazardous substances in coatings and colorants, directly shaping supplier qualification requirements. China's SAMR enforces GB standards for stainless steel grades used in domestic thermos production, creating a fragmented compliance landscape for exporters. Stakeholders must monitor evolving extended producer responsibility frameworks in Europe and North America, as these will determine which material and packaging configurations retain market access without penalty.
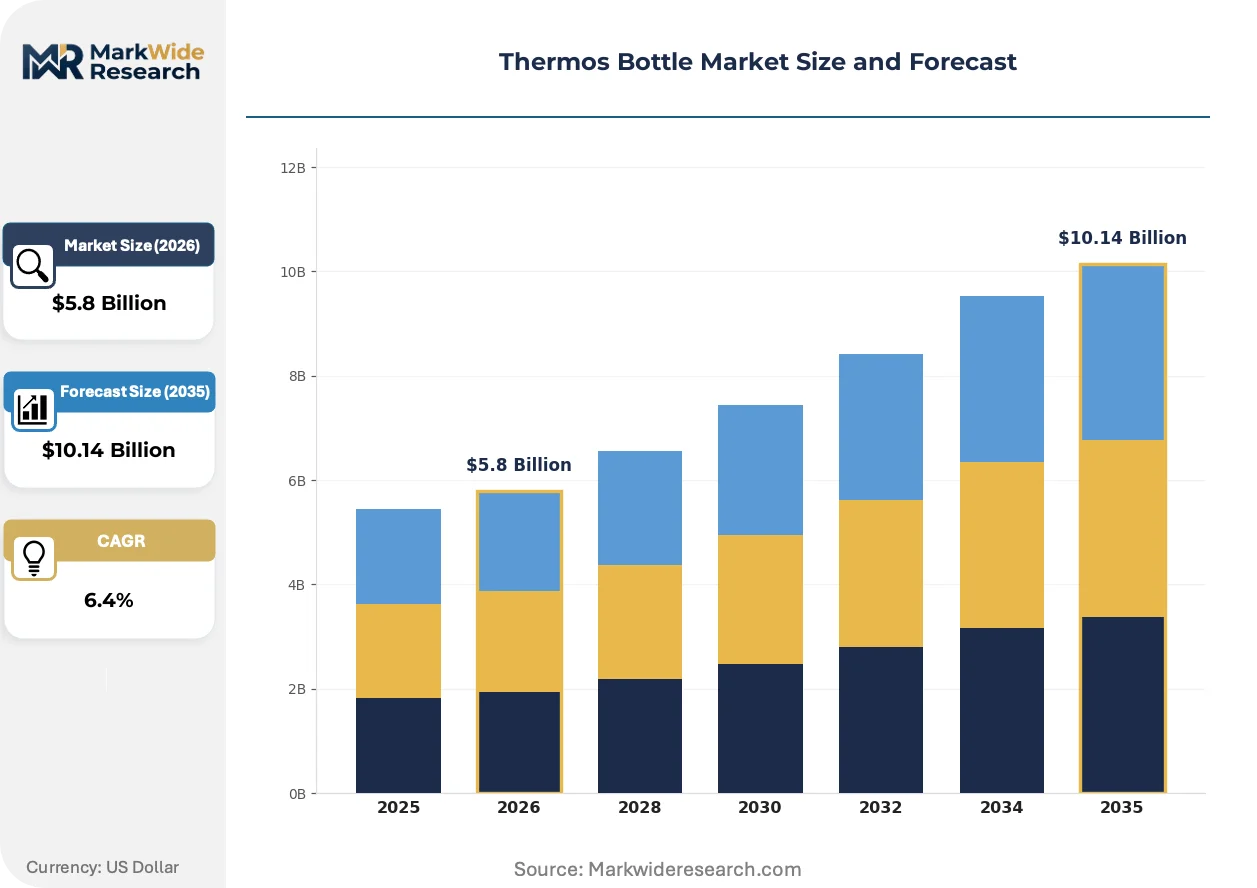
Market Dynamics
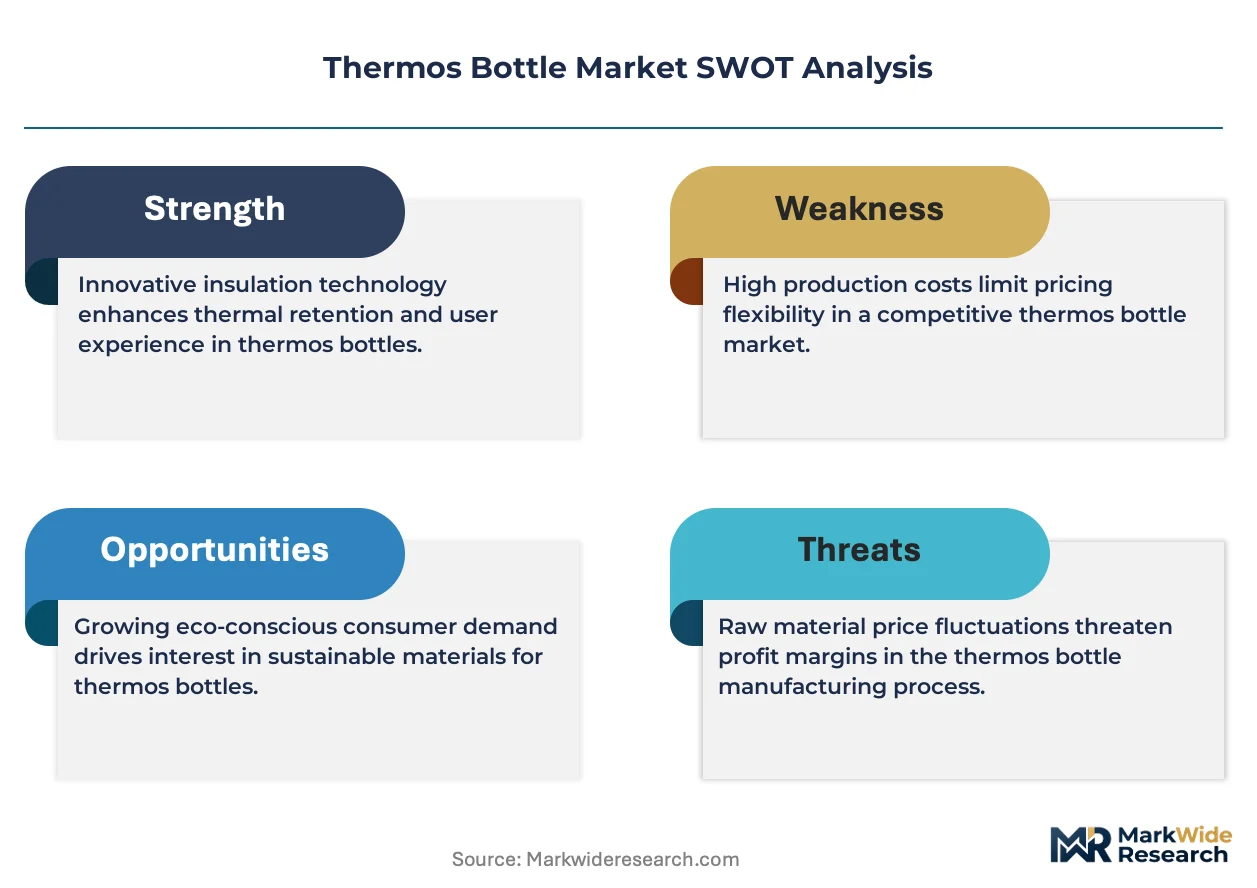
EU Green Deal circular packaging mandates are forcing thermos manufacturers to redesign material stacks and supplier networks, while outdoor recreation demand pulls capacity toward stainless steel vacuum-insulated formats.
Growth Catalysts
- EU Green Deal recyclability mandates:Extended producer responsibility frameworks in Europe are mandating recyclable packaging configurations, expanding addressable market for sustainable stainless steel thermos bottles.
- Outdoor recreation participation:Fitness communities and adventure tourism operators are standardizing vacuum-insulated hydration products for temperature-critical beverage transport.
- Copper-plated vacuum insulation:Japanese precision manufacturing standards are diffusing into mid-tier production, improving thermal retention performance across price bands.
Market Restraints
- Nickel price volatility:18/8 stainless steel input costs fluctuate with nickel futures, compressing margin stability for manufacturers without captive raw material agreements.
- Chinese production concentration:GB-standard stainless steel fabrication clusters in Zhejiang and Guangdong create geographic supply risk for brands without multi-source qualification.
- Silicone seal technical limitations:Food-grade elastomer degradation at temperature extremes constrains warranty periods and replacement part economics.
Strategic Opportunities
- Remote worker mobility patterns:Post-pandemic hybrid employment is creating demand for portable beverage solutions in co-working spaces and transit corridors.
- EU EPR framework expansion:France and Germany are advancing deposit-return schemes for durable drinkware, creating regulatory tailwind for premium thermos adoption.
- Smart hydration convergence:Temperature sensors and Bluetooth connectivity are merging with vacuum insulation, opening premium price tiers in athletic and medical end-uses.
Industry Challenges
- REACH compliance timeline compression:ECHA substance restriction updates require rapid coating reformulation, straining R&D throughput for smaller manufacturers.
- Multi-standard certification burden:Simultaneous FDA, REACH, and SAMR qualification creates redundant testing costs and extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermos Bottle Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Stainless Steel, Glass, Plastic, Aluminum, Copper Capacity: 250 ml, 500 ml, 750 ml, 1000 ml, 1500 ml Usage: Home, Picnic, Office, Gym, Travel Packaging Type: Box, Blister Pack, Plastic Wrap, Carton, Shrink Wrap |
| Companies Covered | Hydro Flask, Ninja, Thermos, CamelBak, Klean Kanteen, Zojirushi, Stanley, Mountop, Yeti, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermos Bottle Market Emerging Trajectories
Material science advances and regulatory pressure on single-use alternatives are converging to elevate thermos bottles from commodity drinkware to engineered thermal systems with embedded sustainability credentials.
Copper-plated 18/8 stainless steel construction is unifying vacuum insulation performance across commuter, athletic, and medical end-use segments. Outdoor retailers and hospital procurement departments are specifying this material stack at accelerating rates. The technology is unifying previously separate premium and standard tiers into a single performance baseline.
REACH substance restrictions on colorants and coatings are forcing reformulation of exterior finishes and interior linings. Manufacturers serving EU markets must qualify alternative ceramic and plant-based coatings to maintain market access. Premium brands with in-house compliance teams are capturing shelf space as smaller competitors exit.
Direct-to-consumer subscription models are displacing traditional retail replenishment cycles for replacement gaskets and lids. Specialty outdoor e-commerce platforms and brand-owned digital channels are capturing repeat purchase revenue previously lost to mass merchants. This pattern is most visible in North American and Australian markets where camping and hiking participation rates drive accessory attach rates.
Thermos Bottle Market Segmentation
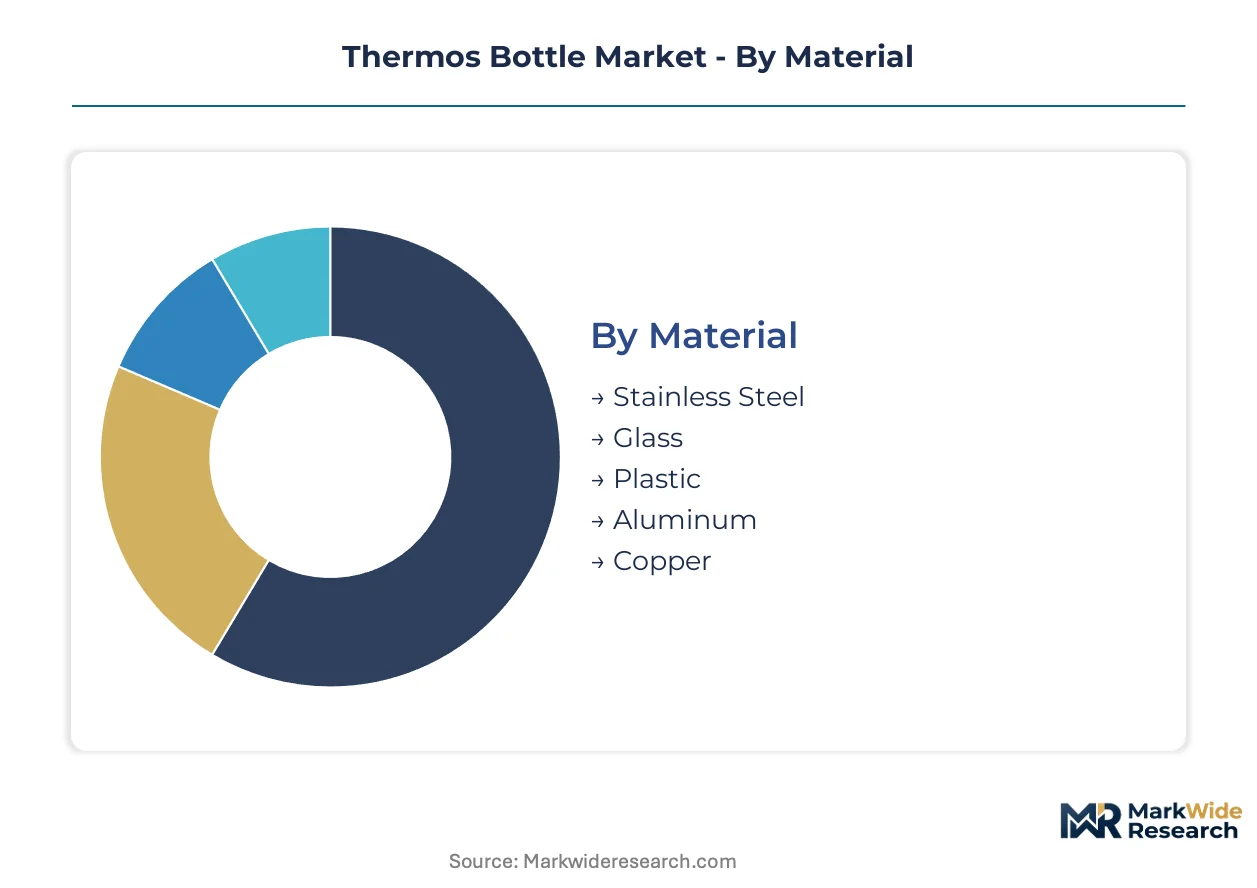
Thermos bottle segmentation reveals how material selection and capacity sizing directly map to replacement frequency and upgrade willingness. Manufacturers calibrate production mixes against these patterns to optimize inventory turns and margin capture across user lifecycles.
Material:
Replacement cycles vary dramatically by material durability, with stainless steel users replacing bottles every 4-7 years versus 1-2 years for plastic variants.
- Stainless Steel:Double-walled 18/8 construction with copper-plated inner walls delivers superior thermal retention and food-grade safety. Demand concentrates in Japanese and South Korean household markets where multi-generational brand loyalty sustains premium pricing. GB-standard fabrication clusters in Zhejiang province supply global brands, though REACH-compliant coating reformulation is raising qualification barriers for EU-bound exports.
- Glass:Borosilicate construction eliminates metallic taste transfer and supports microwave reheating. Adoption clusters in European urban commuter segments where EU Green Deal circularity mandates favor fully recyclable material stacks. Silicone sleeve accessories extend replacement intervals by reducing breakage incidence.
- Plastic:Polypropylene and Tritan copolyester variants dominate entry-level pricing tiers. Demand flows from Southeast Asian mass retail channels and institutional procurement in Indian educational facilities.
- Aluminum:Lightweight single-wall construction serves cycling and trail running enthusiasts requiring minimal carry weight. Powder-coated exteriors accommodate dye-sublimation customization for event merchandise.
- Copper:Solid copper construction appears in Ayurvedic wellness segments and luxury hospitality amenity programs. Antimicrobial properties drive specification in Indian and Middle Eastern premium markets.
Volume placements concentrate in Stainless Steel; the faster expansion belongs to Glass.
Capacity:
Cost tier alignment follows capacity scaling, with manufacturing economies concentrating in mid-range formats where tooling amortization optimizes per-unit economics.
- 250 ml:Compact single-serve sizing suits espresso and tea concentrate transport. Premium positioning in Japanese convenience retail and airline business class amenity kits sustains margin despite lower material input.
- 500 ml:Standard commuter format balances portability against daily hydration requirements. Dominates North American co-working space and urban transit corridor usage patterns.
- 750 ml:Athletic and outdoor standard accommodates extended activity without refill interruption. Copper-plated vacuum insulation diffusion from Japanese manufacturing is elevating thermal performance baselines across this tier.
- 1000 ml:All-day field use format targets construction, agriculture, and expedition segments. Heavier gauge steel requirements raise unit costs and shipping weight penalties.
- 1500 ml:Family and group sizing supports picnic and basecamp scenarios. Niche volume concentrated in Australian and Nordic outdoor retail channels.
Production gravity centers on 500 ml and 750 ml formats; 1000 ml placements are climbing the fastest as hybrid work patterns extend away-from-home hydration windows.
Usage:
Application-driven segmentation determines distribution channel selection and accessory attach rate potential.
- Home:Countertop and tabletop storage formats emphasize aesthetic finish coordination with kitchen environments. Japanese and South Korean markets sustain demand for precision temperature maintenance of specialty teas.
- Picnic:Multi-person capacity and wide-mouth construction facilitate shared beverage service. Seasonal demand concentration in European and North American spring-summer retail cycles.
- Office:Leak-proof certification and slim profile compatibility with vehicle cup holders define procurement specifications. Corporate gifting programs in Indian and Chinese technology sectors drive bulk order flow.
- Gym:Protein shake compatibility and odor-resistant linings differentiate athletic-oriented designs. Direct-to-consumer subscription models for replacement gaskets are displacing traditional retail replenishment in North American and Australian markets.
- Travel:TSA-compliant dimensions and dual-wall insulation for temperature-critical medications represent the fastest-expanding specification set. Post-pandemic mobility normalization is pulling capacity toward this segment.
Margin optimization concentrates in Travel; Gym applications are gaining share fastest through digital channel displacement of mass merchant replenishment.
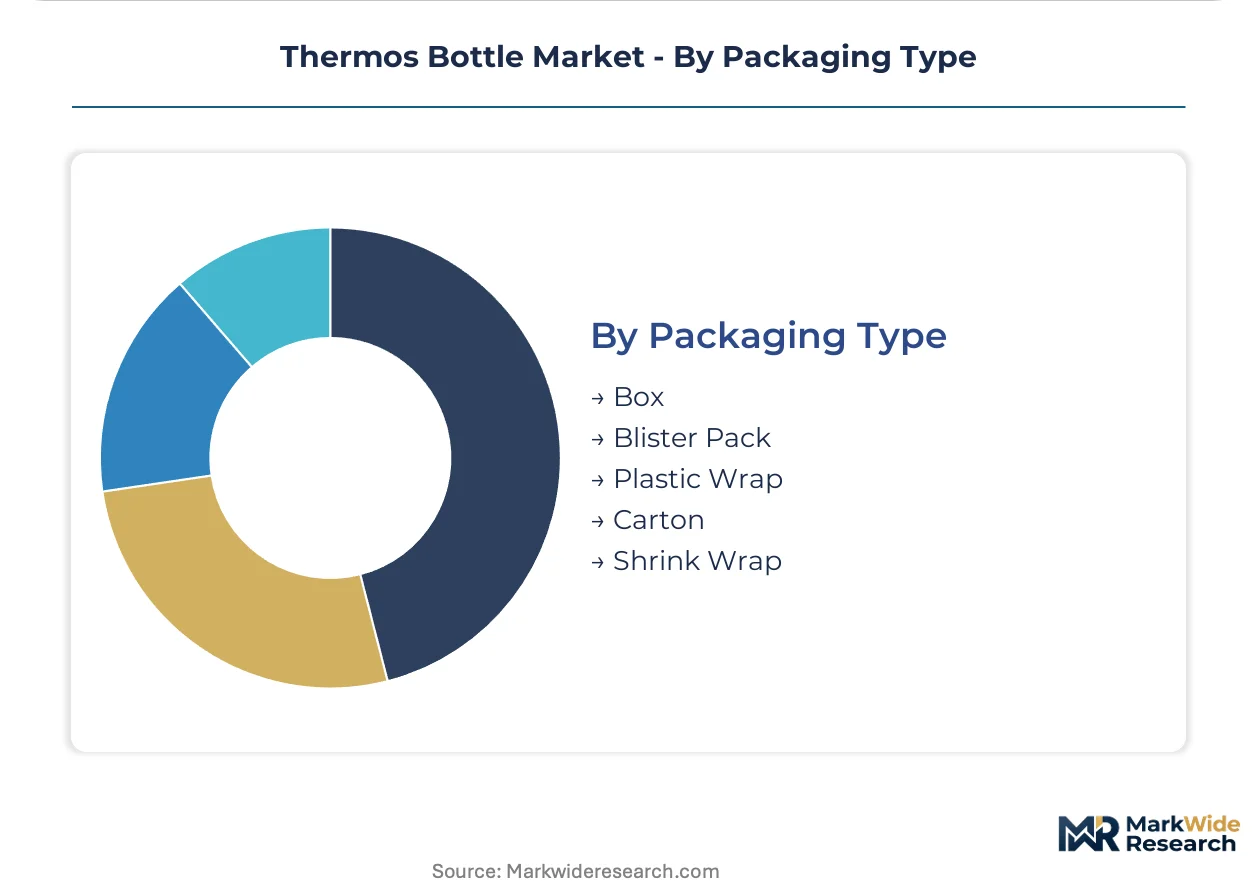
Packaging Type:
Packaging configuration directly determines EU market access under extended producer responsibility frameworks.
- Box:Corrugated construction supports premium unboxing experiences and gift-oriented retail presentation. Dominates North American specialty outdoor and department store channels.
- Blister Pack:Thermoformed clarity enables retail shelf visibility while minimizing cubic volume for air freight. Standard for Southeast Asian hypermarket and electronics store placements.
- Plastic Wrap:Minimal protection format serves palletized bulk shipments to commercial and institutional buyers. Facing regulatory phase-out under France and Germany deposit-return scheme expansions.
- Carton:Recyclable paperboard aligns with EU Green Deal circular packaging mandates. Premium brands with in-house compliance teams are capturing shelf space as smaller competitors exit.
- Shrink Wrap:Polyolefin film provides dust and moisture protection for warehouse club multi-packs. Cost advantage eroding as EPR fees internalize end-of-life disposal costs.
Compliance-driven placements are shifting toward Carton; Blister Pack retains volume leadership in price-sensitive Asian retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang province anchors thermos bottle manufacturing capacity, with Wenzhou and Jinhua industrial corridors hosting GB-standard stainless steel fabrication clusters that supply vacuum-insulated vessels to global brands.
United States
Outdoor recreation participation and remote worker mobility are expanding demand for portable hydration solutions. FDA food-contact material regulations govern stainless steel grades and silicone seal safety for domestic sales. Pacific Northwest retail channels concentrate premium brand distribution, with specialty outdoor merchants driving copper-plated vacuum insulation adoption.
Germany
EU Green Deal circular packaging mandates are accelerating carton-based packaging transitions and deposit-return scheme participation. ECHA REACH substance restrictions require coating reformulation for market access. North Rhine-Westphalia logistics hubs channel compliant stainless steel vessels into European distribution networks.
Japan
Multi-generational brand loyalty sustains premium pricing for precision vacuum insulation in household markets. METI energy efficiency guidelines influence thermal retention performance benchmarking. Osaka-Kobe manufacturing corridors export copper-plated 18/8 stainless steel technology to mid-tier producers across Asia.
China
SAMR GB standards enforcement creates fragmented compliance requirements for domestic versus export-oriented production. Dual carbon policy pressures are reshaping energy-intensive stainless steel processing. Guangdong province assembly clusters integrate Zhejiang-sourced materials for North American and European brand contracts.
South Korea
Urban commuter culture and specialty tea consumption sustain demand for compact precision-insulated formats. National quality certification programs elevate consumer expectations for thermal retention duration. Seoul Capital Area retail density supports rapid product iteration and direct-to-consumer channel experimentation.
Thermos Bottle Market Vendor Landscape
The competitive structure tilts toward brand-anchored specialists with manufacturing scale advantages. Market position stratifies across three tiers: heritage Japanese precision engineers, North American outdoor retail channel capturers, and Chinese contract fabricators serving private label demand. Consolidation pressure operates through geographic expansion into EU-compliant production and technology licensing for smart hydration convergence.
Within the heritage engineering tier, Zojirushi exemplifies multi-generational brand equity built on vacuum insulation precision. Thermos occupies a position as the category-defining name with Asian household market penetration. Hydro Flask represents North American outdoor retail channel specialization with stainless steel focus. These three anchors demonstrate how geographic origin and distribution channel selection shape sustainable competitive position.
| Leading Market Players |
|---|
| Hydro Flask |
| Ninja |
| Thermos |
| CamelBak |
| Klean Kanteen |
| Zojirushi |
| Stanley |
| Mountop |
| Yeti |
| Others |
Supply Flow & Price Mechanics
Nickel futures volatility on the London Metal Exchange cascades through 18/8 stainless steel input costs, compressing margin stability for thermos manufacturers without captive raw material agreements and forcing pricing stratification across premium, standard, and economy tiers.
Pricing Analysis
Thermal retention duration anchors value-based pricing, with copper-plated vacuum insulation commanding premiums against foam-filled alternatives. Three-tier pricing structure across premium, standard, and economy levels separates Zojirushi-grade precision engineering from mid-tier outdoor retail positioning and mass-market private label. Cost compression in the economy tier is intensifying because GB-standard fabrication clusters face REACH-compliant coating reformulation barriers. Institutional procurement in Indian educational facilities exhibits highest price sensitivity; Japanese household markets show least.
Supply Chain Analysis
Regional distribution centers in North Rhine-Westphalia and Pacific Northwest retail hubs channel finished goods through hub-and-spoke patterns into European and North American markets. Manufacturing concentrates in China, Japan, and South Korea, with Zhejiang province fabrication clusters supplying global brand contracts. Raw material flows draw from Indonesian nickel ore, Chilean copper cathode, and Saudi petrochemical feedstocks for silicone seals. Single-source vulnerability concentrates in GB-standard stainless steel qualification. Distribution runs through specialty outdoor retail, direct-to-consumer digital channels, and mass merchant replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thermos bottle market sits in a material-transition phase as copper-plated vacuum insulation displaces legacy foam-filled construction across price bands.
For Market Incumbents: Hedge against nickel price volatility through backward integration into stainless steel processing or long-term offtake agreements with Zhejiang fabrication clusters. Defend margin position by accelerating REACH-compliant coating qualification before ECHA substance restriction updates force competitor exits.
For New Entrants and Emerging Players: Remote workers seeking portable beverage solutions for co-working spaces represent an underserved buyer archetype with limited incumbent lock-in. White-space targets include EU deposit-return scheme participation and smart hydration convergence with temperature sensors. Go-to-market through direct-to-consumer subscription models for replacement gaskets and lids.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier manufacturers with stranded inventory in non-compliant coating formulations across German and French markets. Long-term viability hinges on EU Green Deal circular packaging alignment and smart hydration technology licensing. Watch ECHA substance restriction timelines as inflection indicator for consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Coating Reformulation | ECHA substance restrictions mandate rapid reformulation to maintain EU market access without penalty. |
| Copper-Plated Vacuum Insulation Scale-Up | Japanese precision manufacturing standards diffuse into mid-tier production, elevating thermal retention baselines. |
| Direct-to-Consumer Subscription Launch | Digital channels capture repeat purchase revenue for replacement gaskets previously lost to mass merchants. |
| EU Deposit-Return Scheme Participation | France and Germany regulatory frameworks create tailwind for premium thermos adoption through circular packaging compliance. |
| Smart Hydration Technology Licensing | Bluetooth connectivity and temperature sensors merge with vacuum insulation, opening premium athletic and medical end-uses. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across plant managers at Zhejiang fabrication clusters, procurement leads at North American outdoor retailers, category buyers at German mass merchants, and supply planners at Japanese household brands. Secondary sources included FDA food-contact material registrations, ECHA REACH substance restriction updates, SAMR GB standard enforcement records, and EU Green Deal circular packaging implementation timelines. Bottom-up capacity modeling triangulated against top-down demand segmentation.
Granularity-level framing modeled material-grade thermal performance, capacity-tier distribution economics, and regional regulatory cluster compliance requirements across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by replacement cycle frequency and upgrade willingness patterns. Industry-specific forecast inputs incorporated nickel futures correlation coefficients and outdoor recreation participation indices.
Revisions become necessary when ECHA substance restriction timelines accelerate, nickel futures volatility exceeds historical bands, or EU extended producer responsibility frameworks expand deposit-return scheme coverage. Forecasts reflect documented assumptions around material cost trajectories and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Porcelain Tableware Market
Household Items
US Air Fresheners Market
Household Items
Tablet Tissue Paper Market
Household Items
Chest Freezers Market
Household Items
Command Hooks Market
Household Items
Indoor Humidifier Market
Household Items
Neck Pillows Market
Household Items
Electric Mop Market
Household Items
Portable Vacuum Cleaner Market
Household Items
Soap Tablet Market
Household Items
Middle East and Africa Robotic Vacuum Cleaner Market
Household Items
Deodorizer Bag Market
Household Items
USA Residential Cotton Candy Maker Market
Household Items
Japan Digital Showers Market
Household Items
Netherlands Cookware Market
Household Items
Qatar Gas Hobs Market