
 Wet Wipes and Toilet Paper Market | 2026-2036
Wet Wipes and Toilet Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Wet Wipes and Toilet Paper Market Insights
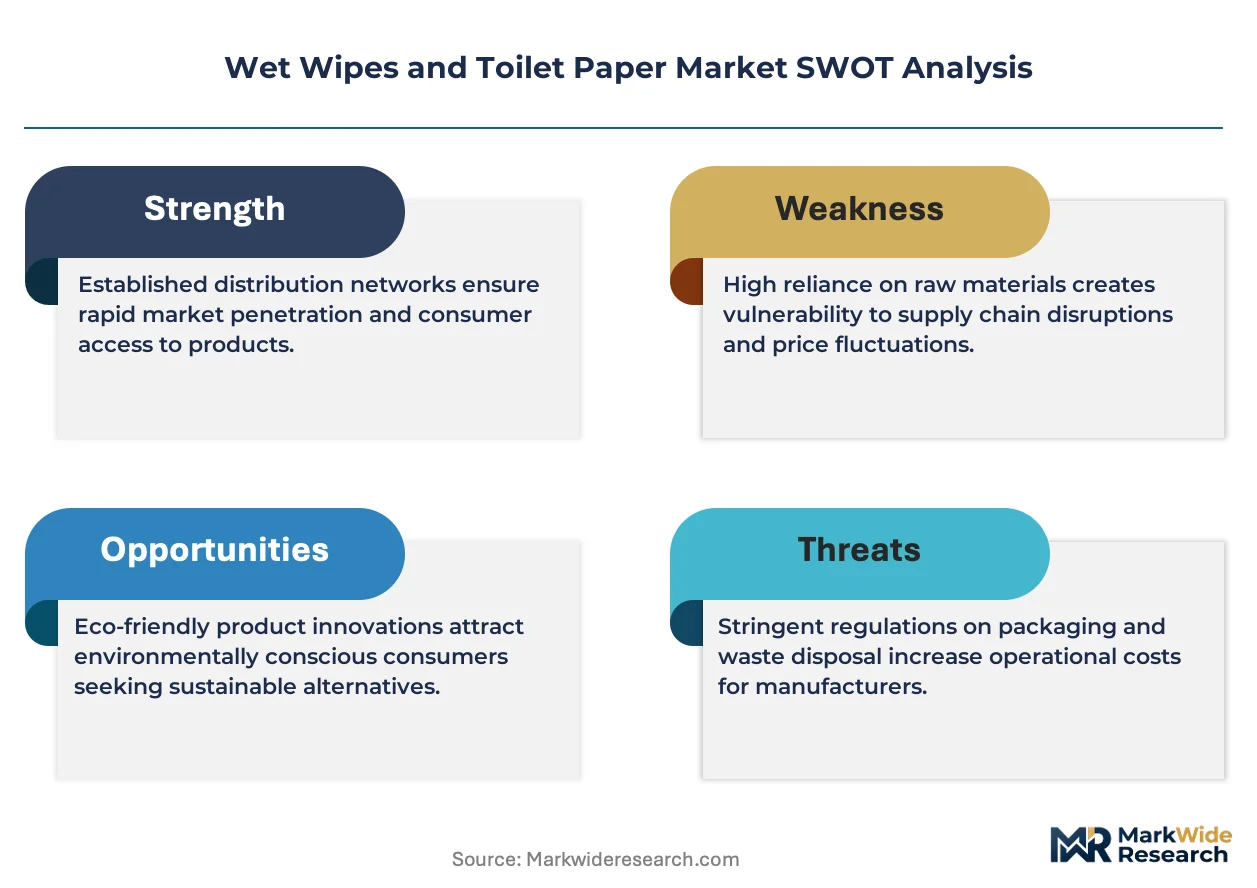
The EU Green Deal is rebalancing fiber sourcing priorities across European supply chains. Procter & Gamble leverages its pulp procurement scale to secure certified sustainable supply agreements. Kimberly-Clark Corporation anchors its competitive position through integrated tissue manufacturing in Scandinavia. Essity AB differentiates via specialized wet-laid nonwoven capacity serving healthcare and hygiene channels.
Wet wipes and toilet paper comprise absorbent disposable products manufactured from wood pulp, bamboo fiber, or synthetic substrates through wet-laid, air-laid, or spunlace processes, designed for personal hygiene, surface cleaning, and medical skin care applications. Toilet paper rolls maintain the largest revenue pool across household and commercial channels, while flushable wipes face technical scrutiny over dispersibility standards. Bamboo-based moist toilet tissue captures premium positioning as brands respond to pulp cost volatility and consumer preference for tree-free alternatives.
EMA packaging guidelines, EU REACH chemical compliance, and national wastewater utility standards in Germany and France collectively determine market access for flushable claims and preservative formulations. FDA oversight of antimicrobial wipe labeling in the United States creates divergent compliance pathways for multinational portfolios. Stakeholders must monitor evolving dispersibility test protocols and regional fiber certification requirements to align R&D investment with enforceable product standards.
Market Dynamics
EU wastewater discharge rules are compressing formulation flexibility for flushable wipes manufacturers while simultaneously opening procurement pathways for compliant suppliers across municipal and healthcare channels.
Growth Catalysts
- Healthcare procurement expansion:German hospitals and long-term care facilities are expanding moist toilet tissue contracts to meet hygiene protocols. Municipal procurement frameworks in France are following this pattern.
- Fiber certification mandates:EU Green Deal packaging waste directives are accelerating certified bamboo and recycled pulp sourcing. Suppliers holding FSC or PEFC chain-of-custody certification gain preferential tender access.
- Composting infrastructure maturation:German municipal composting networks now accept premium moist toilet tissue products. This unlocks premium positioning for biodegradable substrate variants.
Market Restraints
- Wood pulp cost volatility:Softwood pulp futures fluctuate with energy and logistics costs. Manufacturers without long-term fiber supply agreements face margin compression.
- Dispersibility standard fragmentation:INDA/EDANA flushability guidelines in Europe diverge from wastewater utility protocols in France and Germany. Product redesign cycles multiply to satisfy incompatible testing regimes.
- Synthetic substrate substitution:Spunlace polyester wipes face displacement pressure from cellulosic alternatives. Petrochemical feedstock exposure creates regulatory and consumer preference risks.
Strategic Opportunities
- Pharmacy channel expansion:European pharmacy chains are adding dermatologically tested wet wipe SKUs. This channel commands price premiums over mass retail for sensitive-skin formulations.
- Antimicrobial claim differentiation:FDA labeling requirements for antimicrobial wipes in the United States create a compliance moat. European manufacturers meeting these standards can access cross-Atlantic healthcare contracts.
- Wet-laid nonwoven technology convergence:Integration of hydroentanglement with sustainable fiber processing is enabling tree-free product lines at commercial scale. Early adopters capture sustainability-driven procurement tenders.
Industry Challenges
- Preservative formulation compliance:EU REACH chemical restrictions and national wastewater standards in Germany require continuous reformulation. R&D timelines extend as multiple regulatory layers must be satisfied simultaneously.
- Legacy equipment retooling:Converting air-laid production lines to handle bamboo fiber blends demands capital expenditure. Smaller manufacturers face financing constraints for substrate flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wet Wipes and Toilet Paper Market |
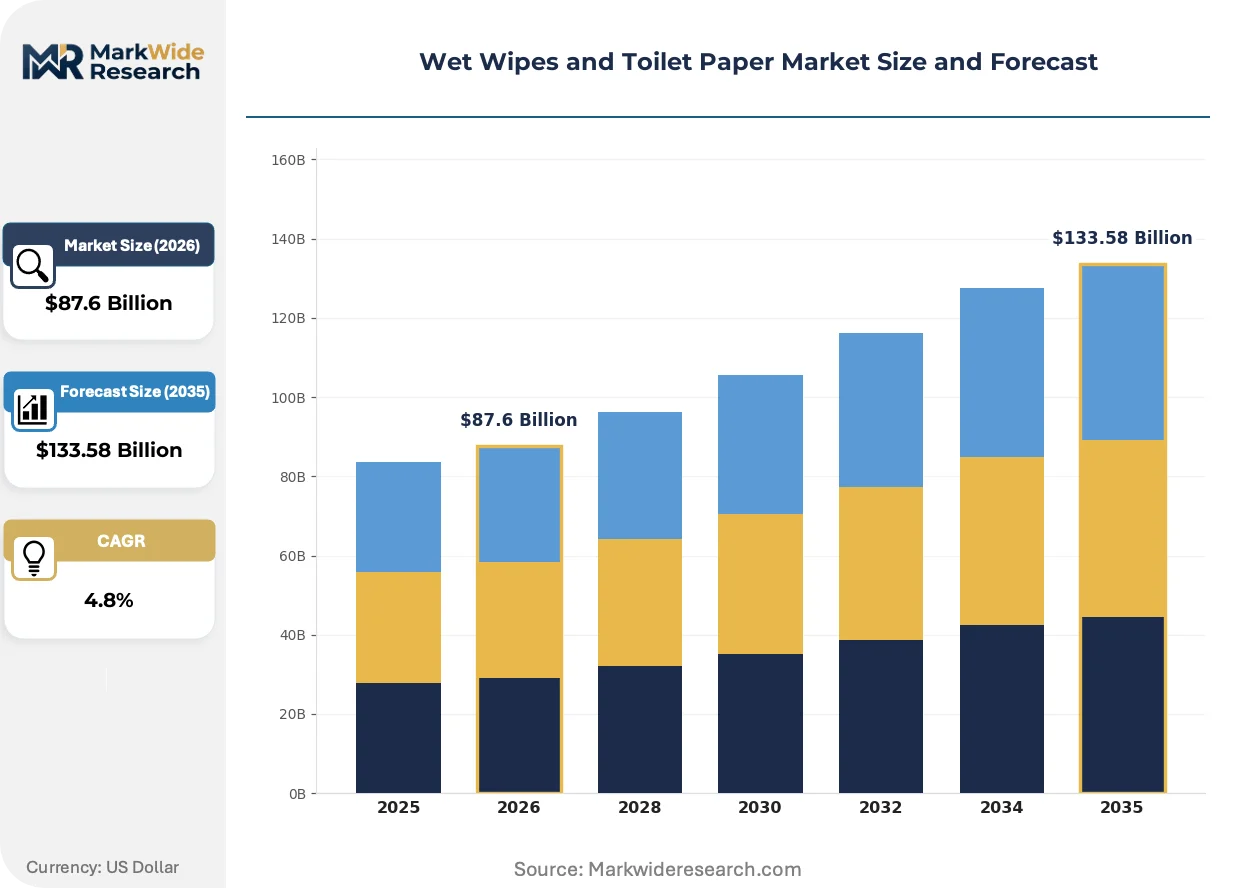
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $133.58 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Wipes, Toilet Paper Rolls, Flushable Wipes, Moist Toilet Tissue Packaging Type: Single Pack, Family Pack, Bulk Pack, Travel Pack End User: Households, Commercial, Healthcare Facilities, Hospitality Material: Pulp, Bamboo, Recycled Fiber, Synthetic |
| Companies Covered | Procter & Gamble, Kimberly-Clark Corporation, Johnson & Johnson, Essity AB, The Clorox Company, Reckitt Benckiser Group, Georgia-Pacific, Hengan International Group, Unicharm Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wet Wipes and Toilet Paper Market Trends and Innovations
Formulation chemistry and substrate engineering are converging to address the tension between performance claims and biodegradability requirements. Manufacturers are racing to satisfy incompatible regulatory frameworks while capturing sustainability premiums.
Bamboo fiber processing is unifying sustainability credentials with performance parity to wood pulp substrates. Premium household brands in Germany are adopting bamboo-based moist toilet tissue at accelerated pace. This substrate shift is compressing the price gap between tree-free and conventional products while enabling flushable claims under stricter dispersibility protocols.
EMA packaging guidelines and EU REACH chemical compliance are tightening preservative selection windows for wet wipe manufacturers. Industrial consequence includes restricted quaternary ammonium compound usage and accelerated phenoxyethanol substitution programs. Healthcare channel suppliers face the most acute reformulation pressure, with German hospital procurement now requiring full ingredient disclosure.
Buyer concentration among European retail consolidators is compressing supplier negotiation leverage and extending payment terms. Private-label manufacturers face the most severe margin pressure as Aldi, Lidl, and Carrefour centralize wet wipe sourcing decisions. France and Germany exhibit the most pronounced retail consolidation effects, with national procurement hubs displacing regional supplier relationships.
Wet Wipes and Toilet Paper Market Segmentation
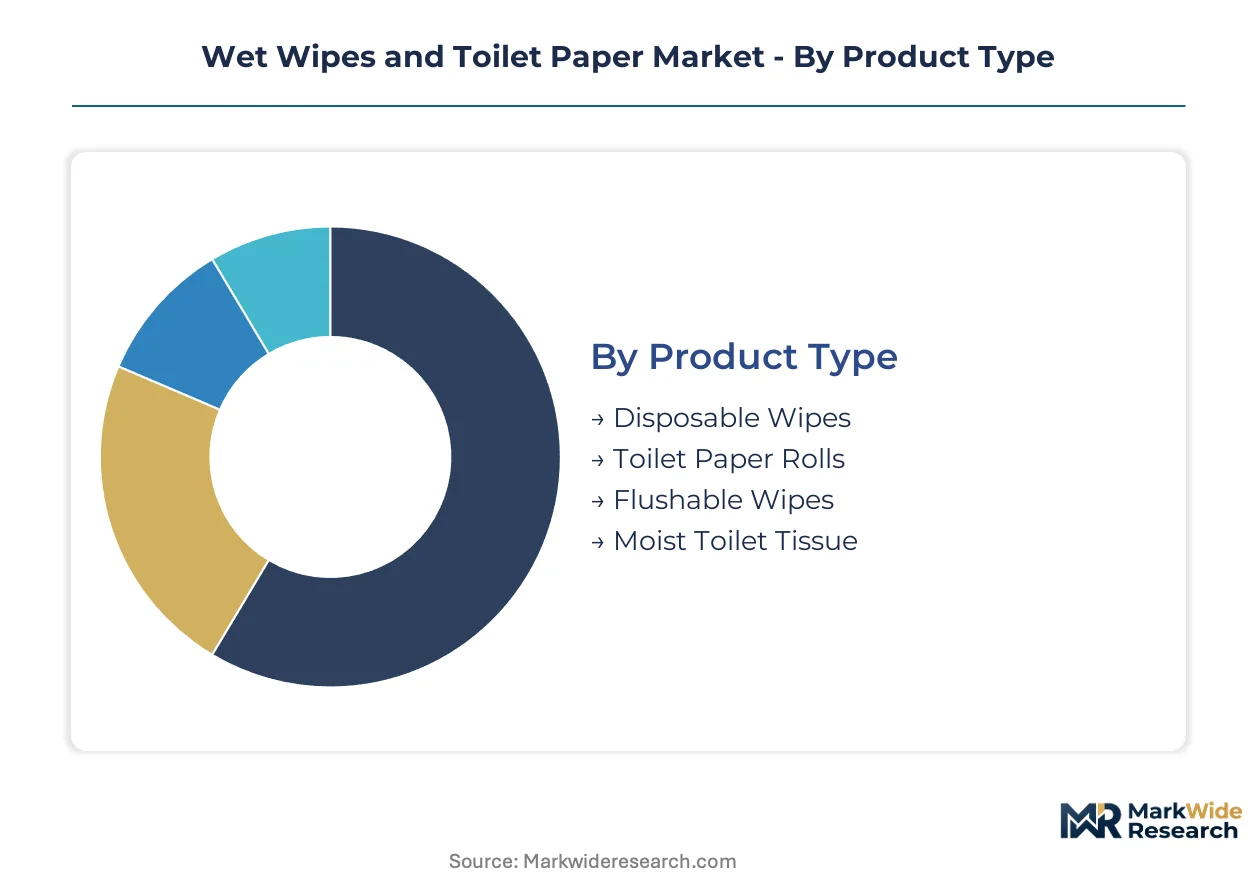
Segmentation in the Wet Wipes and Toilet Paper Market reveals how substrate choices, packaging formats, and procurement channels determine margin structures. Manufacturers configure production lines around specific segment requirements rather than pursuing universal solutions.
Product Type:
Upgrade cycles vary sharply across product categories, with flushable formulations driving the most frequent reformulation investments as wastewater standards tighten.
- Toilet Paper Rolls:Conventional wood pulp-based rolls dominate household procurement volumes across European retail channels. German discounters and French hypermarkets anchor volume contracts for standard and premium tiers, though bamboo variants are capturing shelf space in sustainability-focused assortments.
- Moist Toilet Tissue:Water-impregnated cellulosic substrates with mild preservatives serve consumers seeking enhanced hygiene without full wet wipe functionality. German municipal composting infrastructure now certifies specific biodegradable variants, unlocking premium positioning unavailable in markets lacking organic waste collection systems.
- Disposable Wipes:General-purpose surface and skin cleaning wipes span spunlace and air-laid constructions.
- Flushable Wipes:Dispersibility-tested formulations face divergent technical standards between INDA/EDANA protocols and German wastewater utility requirements.
Toilet Paper Rolls sits at the top of the volume ranking, with Moist Toilet Tissue climbing the fastest.
Packaging Type:
Cost tier positioning determines packaging investment, with bulk formats commanding logistics efficiency and travel packs extracting per-unit premiums through convenience.
- Family Pack:Mid-size multi-roll configurations balance stock-up economics with household storage constraints. French and German retailers promote these SKUs through seasonal campaigns tied to municipal tax rebate periods for sustainable product purchases.
- Bulk Pack:Institutional-scale packaging serves healthcare procurement frameworks and hospitality supply contracts. German hospital purchasing cooperatives negotiate multi-year bulk agreements with full ingredient disclosure requirements under EU Green Deal transparency mandates.
- Single Pack:Individual unit sales concentrate in impulse and pharmacy channels.
- Travel Pack:Compact formats target mobility-oriented consumers with compressed substrate counts.
Bulk Pack holds the largest revenue base, with Travel Pack gaining share fastest among urban demographics.
End User:
Application requirements separate segments, with healthcare procurement imposing the most stringent formulation and certification standards.
- Healthcare Facilities:Hospitals and long-term care facilities demand dermatologically tested, preservative-disclosed products with full supply chain documentation. German procurement frameworks now require REACH compliance certificates and bamboo fiber provenance records for moist toilet tissue contracts.
- Households:Consumer purchasing decisions weigh price-per-sheet against sustainability credentials and flushability claims. French households show elevated willingness to pay for certified compostable substrates where municipal collection infrastructure exists.
- Commercial:Office and institutional buyers prioritize cost control and dispenser compatibility over substrate innovation.
- Hospitality:Hotels and restaurants balance guest experience against operational simplicity in amenity and back-of-house applications.
Households generates the highest absolute volume, with Healthcare Facilities expanding most quickly on reformulation-driven contract renewal cycles.
Material:
Supply concentration shapes competitive access, with certified sustainable fiber commanding procurement priority under EU Green Deal packaging directives.
- Bamboo:Fast-growing grass fiber delivers tree-free sustainability credentials with performance parity to softwood pulp in wet-laid processing. German premium brands have accelerated bamboo moist toilet tissue launches following composting infrastructure certification.
- Recycled Fiber:Post-consumer pulp sourcing satisfies circular economy procurement criteria in French municipal tenders and German retail sustainability programs. Quality consistency challenges limit adoption in healthcare channels requiring substrate purity documentation.
- Pulp:Virgin wood fiber maintains cost and performance leadership in conventional toilet paper rolls.
- Synthetic:Petrochemical-based spunlace substrates face displacement pressure from cellulosic alternatives under tightening wastewater discharge rules.
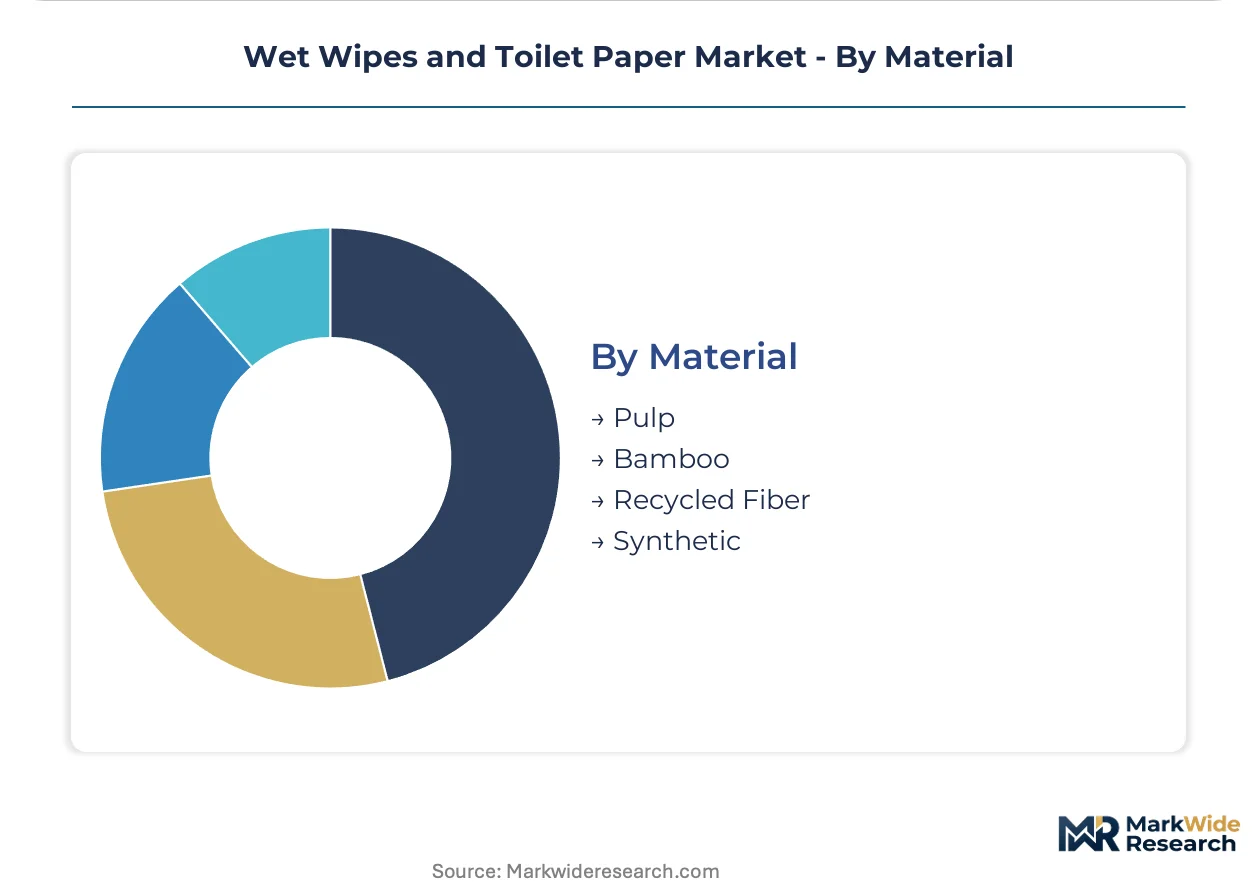
Pulp retains volume leadership, with Bamboo following the steepest expansion trajectory on certification-driven procurement preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The wet wipes and toilet paper industry traces its modern industrial roots to North American pulp processing innovations of the early twentieth century, with subsequent scale concentration in European tissue manufacturing corridors and Asian nonwoven technology hubs.
United States
FDA antimicrobial labeling requirements for healthcare wipes create compliance moats for cross-Atlantic suppliers. EPA wastewater discharge standards in California and New York constrain flushable product formulations. The Southeast pulp processing belt around Georgia anchors virgin fiber supply chains for national tissue brands.
Germany
Municipal composting infrastructure in Bavaria and North Rhine-Westphalia certifies premium moist toilet tissue for organic waste collection. EU Green Deal packaging directives accelerate FSC-certified bamboo procurement tenders. The Rhine-Ruhr industrial corridor concentrates wet-laid nonwoven manufacturing capacity for healthcare channel supply.
China
Dual carbon goals under MEE oversight drive fiber substitution toward bamboo and agricultural residue pulping. GB standards for disposable hygiene products tighten substrate purity documentation for hospital procurement. Yangtze River Delta manufacturing clusters scale spunlace production for export-oriented wet wipe contracts.
France
ANSM chemical safety assessments restrict preservative windows for pharmacy-channel dermatological wipes. National wastewater utility protocols in Île-de-France diverge from INDA/EDANA dispersibility guidelines, forcing product redesign cycles. Auvergne-Rhône-Alpes hosts specialized converters serving private-label retail consolidators.
Japan
METI circular economy roadmaps incentivize post-consumer fiber integration in household tissue products. JIS standards for flushability maintain stricter dispersibility thresholds than European protocols. Kansai manufacturing bases around Osaka supply precision-engineered moist toilet tissue for aging-population hygiene applications.
Wet Wipes and Toilet Paper Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures in the wet wipes and toilet paper market. Integrated pulp-to-retail conglomerates command fiber cost advantages through captive supply chains, while specialized nonwoven converters capture premium positioning through substrate innovation. Three archetypes dominate: scale-driven tissue multinationals with global procurement networks, regional wet-laid specialists serving healthcare channels, and private-label manufacturers supplying retail consolidators. Competitive moves concentrate on backward integration into sustainable fiber sourcing and strategic partnerships with municipal composting operators.
Among North American-based conglomerates, Procter & Gamble and Kimberly-Clark Corporation exemplify scale-driven archetypes with integrated tissue manufacturing footprints. Essity AB represents the European specialist model, anchoring competitive positioning through wet-laid nonwoven capacity concentrated in Scandinavian production bases. These three companies illustrate the structural divergence between fiber-cost leadership and substrate-differentiation strategies.
| Leading Market Players |
|---|
| Procter & Gamble |
| Kimberly-Clark Corporation |
| Johnson & Johnson |
| Essity AB |
| The Clorox Company |
| Reckitt Benckiser Group |
| Georgia-Pacific |
| Hengan International Group |
| Unicharm Corporation |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal packaging waste directives now gate both qualified fiber supply and premium-tier pricing access, as FSC-certified bamboo and recycled pulp sourcing becomes mandatory for contract eligibility while uncertified producers face margin compression in standard-grade toilet paper rolls.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with FSC chain-of-custody documentation commanding 15-20% premia in German healthcare procurement. Price differentiation separates compostable moist toilet tissue from conventional flushable wipes, as municipal certification unlocks shelf space in sustainability-focused assortments. Cost compression in economy-tier private-label SKUs is intensifying because Aldi and Lidl centralization extends payment terms to 90-120 days. Households exhibit highest price sensitivity, while German hospital purchasing cooperatives show least sensitivity due to hygiene protocol mandates.
Supply Chain Analysis
Workforce availability constraints in the Rhine-Ruhr industrial corridor and Scandinavian wet-laid manufacturing bases are elevating automation investment timelines. Supply concentrates in Germany, Sweden, and China, with the Yangtze River Delta anchoring spunlace capacity for export contracts. Raw material dependencies center on softwood pulp futures, bamboo fiber imports, and phenoxyethanol preservative supplies. Single-source vulnerability runs through Indonesian bamboo pulp processors serving European sustainability certifications. Distribution runs through retail consolidator hubs in France and Germany, with pharmacy chains extracting direct-to-shelf access for dermatologically tested SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wet wipes and toilet paper market functions as a stable compounder, with EU wastewater discharge rule tightening driving steady contract renewal cycles across healthcare and municipal procurement channels.
For Market Incumbents: Lock in fiber cost advantages through captive bamboo sourcing agreements in Indonesia and Vietnam, while accelerating wet-laid nonwoven retooling to meet German dispersibility protocols. Synthetic substrate displacement by cellulosic alternatives threatens spunlace-dependent product lines, demanding substrate flexibility investment. For New Entrants and Emerging Players: The mid-tier price gap between premium bamboo-certified moist toilet tissue and economy private-label rolls offers white-space positioning for regional wet-laid specialists. French pharmacy chains represent the most penetrable channel, with dermatological testing partnerships enabling price premia over mass retail. For Investors and Strategic Acquirers: Roll-up economics work for regional wet-laid converters because municipal procurement consolidation favors suppliers with multi-country REACH compliance documentation. Target asset-light designers with established FSC certification and healthcare channel access, watching German hospital purchasing cooperative contract renewal timing as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bamboo Fiber Sourcing | FSC-certified captive supply secures preferential tender access under EU Green Deal mandates. |
| Wet-Laid Nonwoven Capacity Expansion | Hydroentanglement integration enables tree-free product lines at commercial scale for healthcare contracts. |
| Pharmacy Channel Direct Distribution | ANSM-compliant dermatological testing unlocks price premia in French pharmacy chains. |
| Composting Infrastructure Partnership | German municipal organic waste certification differentiates premium moist toilet tissue positioning. |
| REACH Compliance Documentation Investment | Full ingredient disclosure satisfies German hospital procurement frameworks and creates cross-Atlantic FDA access moat. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pulp procurement directors, wet-laid manufacturing plant managers, German hospital purchasing committee members, and pharmacy category buyers with secondary validation through EU ECHA substance restriction databases, FSC chain-of-custody registries, and customs trade records for bamboo fiber imports. Bottom-up capacity assessments and top-down retail audit triangulation anchored volume estimates.
Segment-weighting approaches modeled product type, packaging format, end-user channel, and material substrate dimensions across the analysis window. CAGRs derived from fiber cost trajectory modeling, healthcare procurement contract renewal patterns, and municipal composting infrastructure expansion timelines. Dispersibility test protocol divergence between INDA/EDANA and German wastewater utility standards informed flushable wipes segment assumptions.
Caveats apply where EU REACH chemical restriction expansion, Indonesian bamboo pulp export policy shifts, or German municipal composting certification suspension could materially shift the outlook. Forecasts reflect stated regulatory trajectories and fiber substitution elasticity assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Soap Tablet Market
Household Items
Coffin and Cremation Urn Market
Household Items
India Digital Showers Market
Household Items
Residential Water Purifier Market
Household Items
Titanium Thermos Cup Market
Household Items
United States Commercial Bathroom Products Market
Household Items
Water Purifier Market
Household Items
Ceramic Travel Mug Market
Household Items
Basin, Bowl, and Cup Market
Household Items
Global Residential Robotic Vacuum Cleaner Market
Household Items
Electric Brooms Market
Household Items
Global Electric Scissors Market
Household Items
Drinkware Accessories Market
Household Items
Europe Coin-Operated Laundries Market
Household Items
Laundry Dryer Sheets and Bars Market
Household Items
Industrial Floor Mats Market