
 Japan Beer Market | 2026-2036
Japan Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Beer Market Intelligence
Single-serve and variety-pack configurations are decoupling traditional case-based purchasing, giving consumers flexibility to sample across brands without volume commitment. Kirin Holdings Company leverages its national distribution network to anchor shelf presence in convenience stores. Sapporo Breweries differentiates through premium positioning in on-trade channels. Asahi Group Holdings competes aggressively on price in the standard lager segment while extending its reach into functional low-alcohol lines.
Beer is a fermented alcoholic beverage produced from malted cereals, hops, yeast, and water, typically brewed through mashing, boiling, fermentation, and conditioning processes at controlled temperatures, serving as a mass-market refreshment and social consumption product across licensed venues and retail. Lager dominates volume due to its lighter profile aligning with Japanese palate preferences, while craft beer captures margin pools through localized storytelling and experimental hopping. Distribution channel dynamics show supermarkets sustaining bulk purchases even as online retail builds recurring subscription models among urban millennials.
METI administers Japan's liquor tax framework, which imposes tiered rates based on malt content and alcohol percentage, directly incentivizing brewers to reformulate toward lower-malt happoshu and third-category beers. The National Tax Agency enforces labeling standards including ingredient disclosure and alcohol content precision, while the Food Sanitation Act governs production facility hygiene and import clearance protocols. Stakeholders must monitor how potential tax equalization discussions between standard beer and quasi-beer categories would reshape portfolio allocation and capital deployment across brewing assets.
Market Dynamics
METI's tiered liquor tax framework is the dominant structural force, compelling brewers to reformulate malt content and alcohol percentages to optimize tax exposure across standard beer, happoshu, and third-category segments.
Growth Catalysts
- Low-Alcohol Formulation:Consumer preference shifts in Tokyo and Osaka toward no-alcohol variants are pulling R&D investment into yeast strain optimization and fermentation control technologies.
- Convenience Store Channel Density:Japan's 55,000-plus convenience stores provide refrigerated last-mile access that sustains single-can purchasing frequency and brand experimentation.
- Craft Brewery Localization:Regional cities including Kyoto and Sendai are incubating small-batch producers that capture margin through experiential taproom direct sales.
Market Restraints
- Malted Barley Import Dependency:Japan sources over 90 percent of brewing barley from Australia and Canada, exposing cost structures to currency volatility and climate-driven harvest variance.
- Tax Classification Rigidity:METI's malt-content thresholds create formulation constraints that prevent seamless product migration between tax tiers.
- Aging Demographic Compression:Core lager consumption correlates with shrinking 50-70 year-old cohorts, pressuring volume baselines in rural prefectures.
Strategic Opportunities
- Functional Ingredient Integration:Collagen, fiber, and GABA-infused variants align with Japan's Foods with Function Claims system, opening premium positioning beyond alcohol content differentiation.
- Subscription Direct-to-Consumer Models:Urban millennials in Tokyo's 23 wards are adopting monthly curated variety packs that bypass traditional retail slotting fees.
- Sendai-to-Sapporo Corridor Expansion:Tohoku and Hokkaido regional markets show underpenetrated craft distribution relative to Kanto saturation levels.
Industry Challenges
- Brewmaster Talent Pipeline:Traditional three-year apprenticeship models at major houses are failing to replenish specialized fermentation expertise as veteran brewers retire.
- Legacy System Integration:Regional craft breweries acquiring automated canning lines face workflow friction with existing tank farm configurations and quality control protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Beer Market |
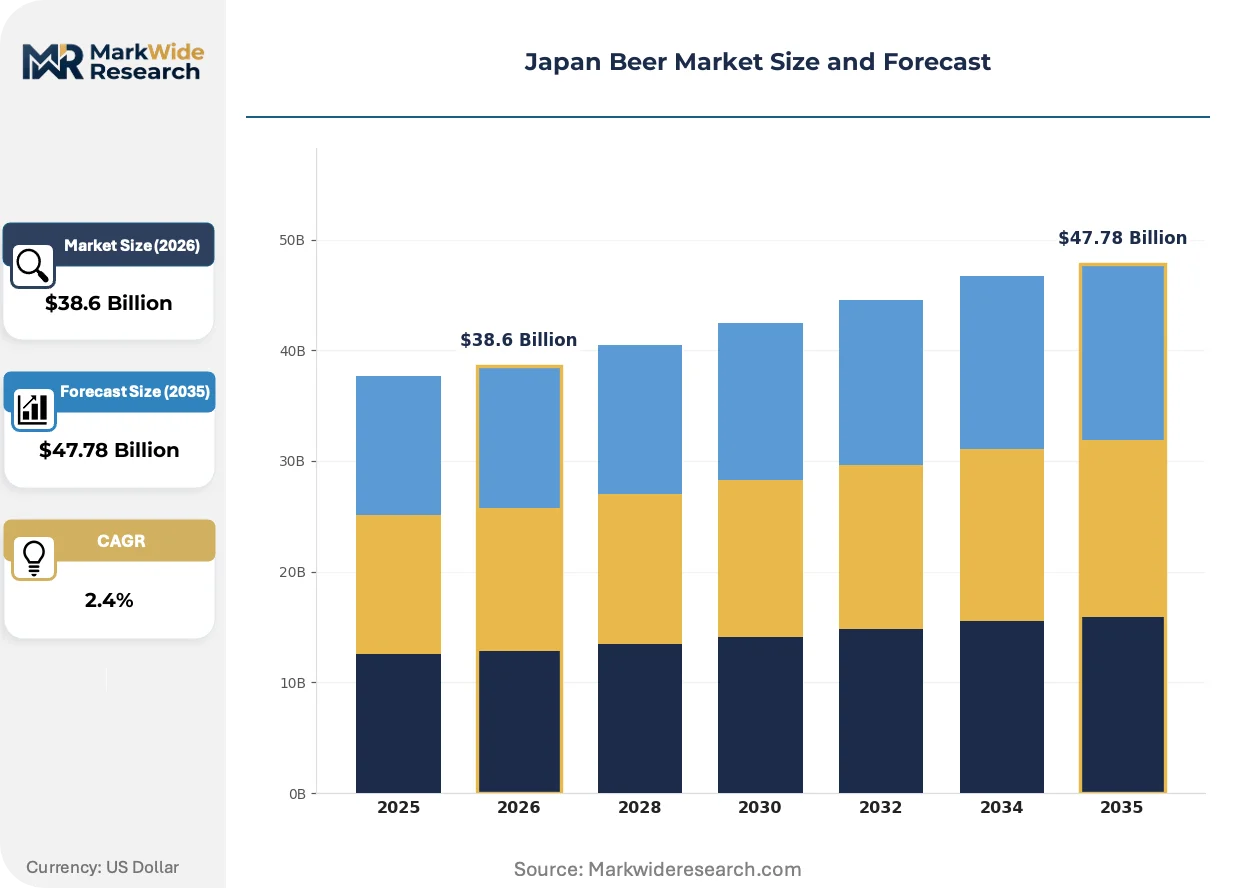
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $47.78 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lager, Ale, Stout, Craft Distribution Channel: Supermarkets, Convenience Stores, Bars, Online Retail Customer Type: Millennials, Gen Z, Working Professionals, Retirees Flavor Profile: Crisp, Fruity, Hoppy, Malty |
| Companies Covered | Sapporo Breweries, AB InBev Japan, Asahi Group Holdings, Echigo Beer, Diageo Japan, Kirin Holdings Company, Heineken Japan, Baird Brewing Company, Suntory Holdings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Beer Market Strategic Shifts & Innovations
Reformulation science and channel fragmentation are converging to reshape how Japanese brewers design, tax-optimize, and deliver beer to increasingly segmented consumption occasions.
Dry hopping and cryogenic hop extract technologies are rewriting flavor architecture possibilities for low-malt products. Premium happoshu lines in Osaka now incorporate aroma hop dosing previously reserved for craft IPA categories. This technical migration is compressing the sensory gap between tax-advantaged quasi-beers and standard lager benchmarks.
METI's ongoing tax equalization review discussions are forcing portfolio rebalancing across all major brewing groups. The potential convergence of standard beer and happoshu rates would eliminate the primary economic rationale for third-category existence. Sapporo and Sendai production facilities are already stress-testing malt-forward formulations that could absorb such regulatory recalibration without margin collapse.
Single-serve procurement from vending machines and convenience stores is displacing traditional case-based household stocking among Tokyo's apartment-dwelling professionals. This behavior shift rewards packaging innovation—slim cans, resealable formats, and temperature-indicating labels—over volume discounting. Kyoto's craft taprooms report that 40 percent of visitors now purchase mixed four-packs rather than committing to brewery-exclusive six-packs.
Japan Beer Market Segmentation
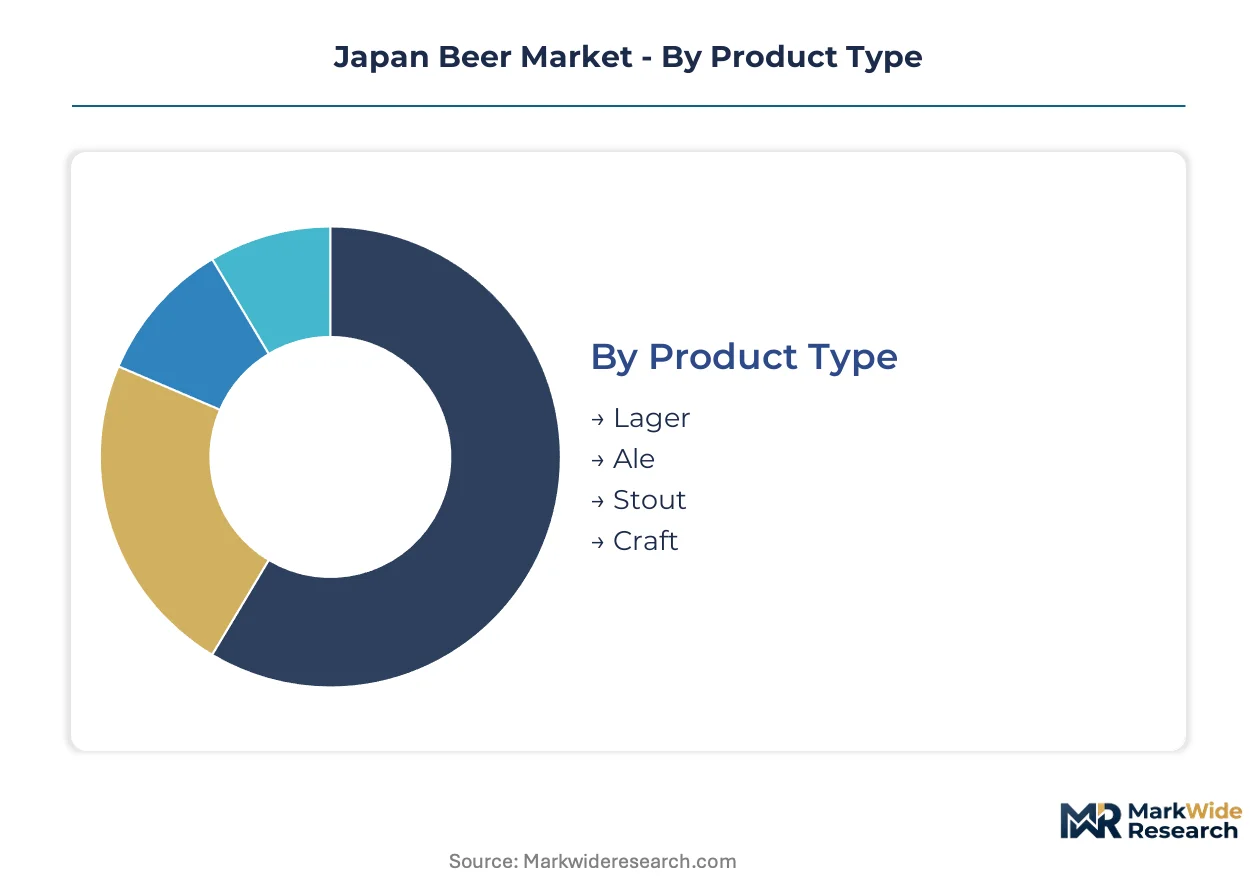
Japan's beer market fragmentation reflects divergent consumption rituals across age cohorts and retail channels. Tax classification tiers and metropolitan density patterns create distinct profit pools that reward precise segment targeting.
Product Type:
Customization spans from mass-produced standardized lagers to hyper-localized craft experimentation, with tax-optimized formulations occupying the middle ground.
- Lager:Bottom-fermented at cold temperatures yielding clean, attenuated profiles. Tokyo and Osaka convenience stores move single-serve volumes driven by after-work consumption rituals among salarymen. METI's malt-content thresholds push brewers toward happoshu-adjacent formulations that preserve lager-like refreshment at lower tax rates.
- Craft:Small-batch production emphasizing regional ingredients and experimental hopping. Kyoto and Sendai taprooms capture margin through direct experiential sales, with consumers paying premiums for localized storytelling and seasonal limited releases. Tax equalization discussions threaten the cost advantage of quasi-beers, potentially redirecting R&D toward authentic malt-forward craft positioning.
- Ale:Top-fermented varieties including pale ales and wheat beers with fruit-forward ester profiles.
- Stout:Dark roasted malt varieties occupying niche winter consumption occasions and dessert pairing contexts.
Leading the category by volume: Lager. Expanding most quickly: Craft.
Distribution Channel:
Channel selection maps directly to purchase frequency and basket size, from bulk household provisioning to impulse single-serve acquisition.
- Convenience Stores:Japan's 55,000-plus refrigerated outlets enable last-mile access with 24-hour availability. Urban millennials in Tokyo's 23 wards favor grab-and-go purchasing that supports brand experimentation without volume commitment. Temperature-indicating labels and slim can formats compete for cooler space against ready-to-drink alternatives.
- Supermarkets:Sustained bulk purchasing venue for household stocking and weekend entertaining. Rural prefectures retain higher case-based purchase frequency as refrigerator capacity and car ownership enable volume transport.
- Bars:On-trade channel where premium positioning and draft freshness command per-unit premiums over retail.
- Online Retail:Subscription models bypass slotting fees while building recurring revenue through curated variety packs.
Channel concentration: Convenience Stores dominate transaction frequency. Steepest expansion trajectory: Online Retail.
Customer Type:
Generational divides in alcohol tolerance, health consciousness, and social consumption settings fragment addressable demand.
- Working Professionals:Core volume driver balancing after-work social rituals with next-day functional requirements. Tokyo and Osaka white-collar cohorts are migrating toward no-alcohol and functional variants that preserve social participation without impairment.
- Millennials:Subscription-adopting urban demographic seeking discovery and variety over brand loyalty. Monthly curated packs from direct-to-consumer platforms align with apartment-scale storage constraints and experimentation preferences.
- Gen Z:Emerging cohort showing reduced per-capita alcohol consumption relative to predecessor generations.
- Retirees:Aging demographic concentrated in rural prefectures with established brand preferences and higher at-home consumption ratios.
Volume leadership: Working Professionals. Gaining share fastest: Millennials.
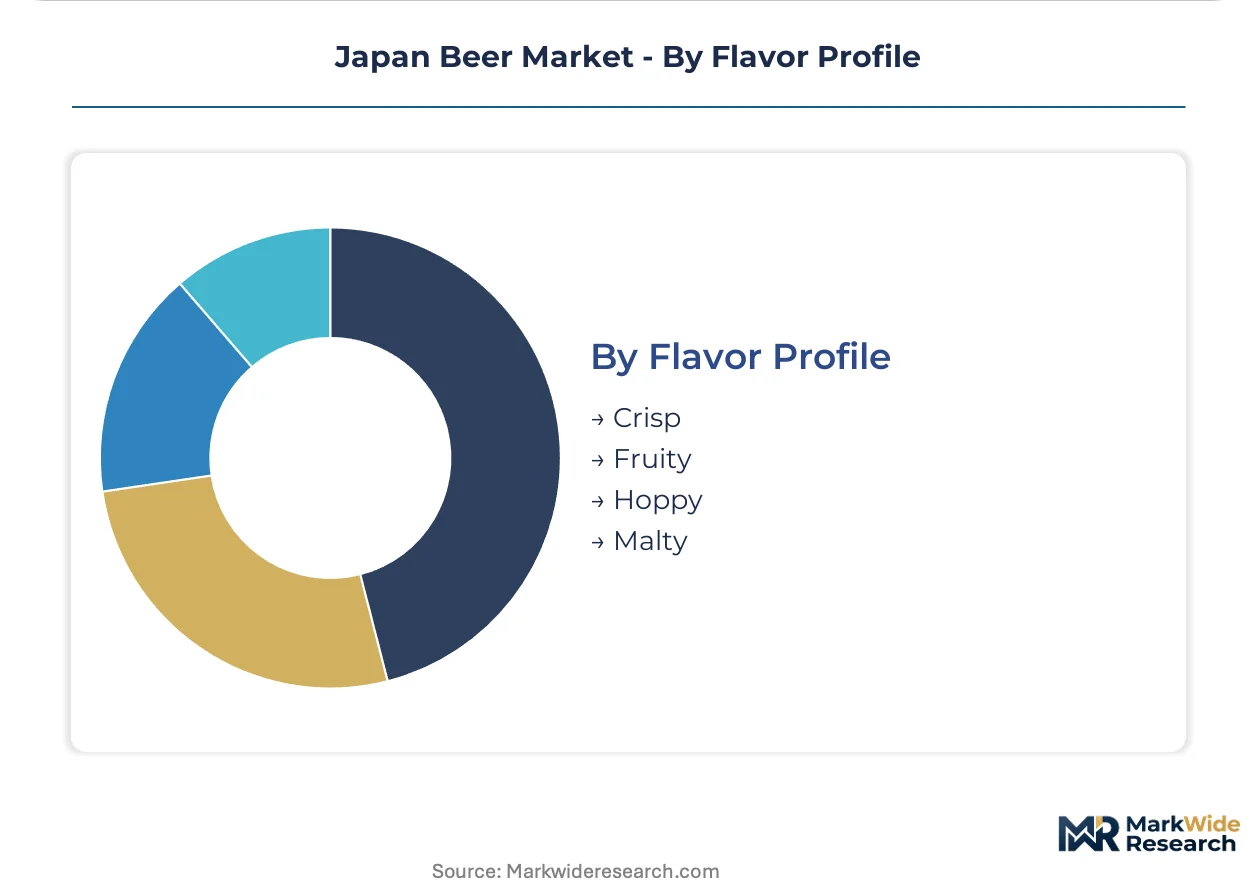
Flavor Profile:
Palate segmentation bridges traditional Japanese preference for attenuated refreshment and emerging appetite for intensity and complexity.
- Crisp:Highly attenuated, low-residual sugar profiles dominating standard lager and happoshu formulations. Aligns with izakaya food pairing requirements and extended session consumption.
- Hoppy:Elevated bitterness and aroma compounds from increased hop dosing. Dry hopping technology migration from craft to premium happoshu lines is compressing sensory differentiation between tax tiers.
- Fruity:Ester-forward profiles from ale yeast strains and fruit adjuncts targeting female demographics and dessert occasions.
- Malty:Residual sweetness and caramel notes from higher kilning temperatures, concentrated in autumn seasonal releases and stout variants.
Preference concentration: Crisp profiles anchor volume. Climbing the fastest: Hoppy expressions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's beer production concentrates in industrial brewing corridors while consumption patterns diverge sharply between dense metropolitan zones and aging rural prefectures. METI's tax classifications have driven manufacturing consolidation around efficiency-optimized facilities, yet demand fragmentation now pulls distribution toward hyperlocal convenience networks and direct-to-consumer channels.
Kanto/Tokyo
Tokyo's 23 wards generate the highest per-capita consumption velocity through convenience store single-serve purchasing among apartment-dwelling professionals. METI labeling standards enforce strict alcohol content precision on all packaged products sold through the capital's 24-hour retail network. Shibuya and Shinjuku clusters incubate subscription-based craft variety pack startups that bypass traditional slotting fees.
Kansai/Osaka
Osaka's working-class consumption culture sustains higher session frequency at izakaya and standing bars compared to Tokyo's after-work rituals. The National Tax Agency's tiered enforcement creates formulation incentives for happoshu-adjacent products dominating Kansai's price-sensitive on-trade. Umeda and Namba districts host experimental taprooms where dry-hopped premium lines compress sensory gaps with craft benchmarks.
Chubu/Nagoya
Chubu's manufacturing belt generates stable industrial demand through factory-adjacent drinking establishments serving shift workers. Food Sanitation Act protocols govern production facility hygiene across Aichi prefecture's brewing assets. Nagoya's Sakae district maintains distinct local brand loyalties that resist Tokyo-Osaka marketing standardization.
Hokkaido
Hokkaido's barley cultivation history supports localized craft positioning around terroir narratives and seasonal ingredient sourcing. The prefecture's harsh winters concentrate consumption in heated indoor venues with extended session durations. Sapporo's brewing heritage anchors tourism-driven experiential retail that converts visitors into direct-ship subscription customers.
Tohoku/Sendai
Sendai's recovery from 2011 demographic disruption has created receptive conditions for craft brewery incubation and regional identity marketing. METI's regional revitalization frameworks channel modest subsidies toward food and beverage entrepreneurship in underpenetrated markets. Miyagi prefecture's brewing clusters exploit distribution gaps relative to Kanto saturation, building direct taproom revenue before retail expansion.
Japan Beer Market Key Industry Players
The competitive structure tilts toward diversified beverage conglomerates with brewing as one vertical among multiple alcohol and soft drink categories. Four major domestic groups anchor volume through national distribution networks spanning convenience stores, supermarkets, and on-trade channels. Strategic archetypes separate scale-driven standard lager producers, premium positioning specialists, and regional craft incubators. Capacity optimization and portfolio diversification toward low-alcohol variants constitute the dominant competitive moves across the landscape.
Within the diversified conglomerate tier, Kirin Holdings Company, Asahi Group Holdings, and Suntory Holdings exemplify multi-beverage platform strategies that cross-subsidize beer R&D through spirits and ready-to-drink revenue pools. These Tokyo-headquartered entities occupy positions where regulatory fluency with METI tax frameworks becomes a structural advantage. Echigo Beer and Baird Brewing Company represent the craft archetype, leveraging localized storytelling and direct experiential sales to capture margin outside standardized retail slotting systems.
| Leading Market Players |
|---|
| Sapporo Breweries |
| AB InBev Japan |
| Asahi Group Holdings |
| Echigo Beer |
| Diageo Japan |
| Kirin Holdings Company |
| Heineken Japan |
| Baird Brewing Company |
| Suntory Holdings |
| Others |
Cost & Logistics Intelligence
Tokyo apartment-dwellers' shift toward single-can convenience store purchasing forces brewers to absorb higher per-unit packaging and last-mile distribution costs, compressing margins on standardized lagers while premium positioning absorbs the differential in craft segments.
Pricing Analysis
Margin tightening in standard lager reflects METI's malt-content tax thresholds that prevent seamless formulation migration between tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by alcohol content and perceived quality grade, with urban millennials showing lowest price sensitivity for craft discovery packs and rural retirees exhibiting highest sensitivity on bulk household purchases. Cost-down pressure on happoshu accelerates because tax equalization discussions threaten the category's primary economic rationale.
Supply Chain Analysis
Regional distribution centers in Tokyo and Osaka operate hub-and-spoke patterns feeding Japan's 55,000-plus convenience store network. Brewing barley draws from Australia and Canada, exposing cost structures to currency volatility and climate-driven harvest variance. Single-source vulnerability concentrates in malted barley import dependency, with over ninety percent sourced from two countries. Distribution runs through temperature-controlled last-mile fleets sustaining refrigerated shelf presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brewmaster talent scarcity constrains craft capacity expansion, propping pricing power for established fermentation expertise holders across the projection horizon.
For Market Incumbents: To counter tax equalization threats, Kirin and Asahi should accelerate backward integration into domestic barley cultivation trials while locking convenience store cooler space through exclusive slim-can format development. For New Entrants and Emerging Players: Enter via Sendai-to-Sapporo corridor craft incubation, targeting underpenetrated Tohoku taproom direct sales before retail expansion, with seasonal limited releases as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors specialized fermentation technology holders and regional craft brands with direct-to-consumer subscription traction, with METI tax reform announcement timing as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Alcohol Formulation Investment | Yeast strain optimization aligns product portfolios with Tokyo professional preferences and METI tax thresholds. |
| Direct-to-Consumer Subscription Launch | Monthly curated packs bypass convenience store slotting fees while building recurring revenue among urban millennials. |
| Regional Craft Brewery Acquisition | Sendai and Kyoto taproom assets capture margin through experiential sales outside standardized retail systems. |
| Functional Ingredient Integration | Collagen and GABA-infused variants qualify for Japan's Foods with Function Claims premium positioning. |
| Domestic Barley Supply Partnership | Hokkaido cultivation contracts reduce Australian and Canadian import dependency exposure. |
Research Approach
Multi-period observation of convenience store transaction velocity, tax tier migration patterns, and craft taproom revenue mix anchored the trend analysis, supplemented by interviews with Kirin and Asahi brand managers, Lawson and Seven-Eleven category buyers, Sendai craft brewery founders, METI regulatory affairs officers, and National Tax Agency enforcement leads. Secondary validation drew from Japan Customs import records, National Tax Agency liquor tax bulletins, Food Sanitation Act facility inspection databases, and Nielsen retail audit data. Bottom-up facility capacity modeling and top-down consumption survey triangulation produced convergent estimates.
Segment-weighting applied product type, distribution channel, customer cohort, and regional density dimensions across the analysis window. CAGRs derived from regression-adjusted historical trend extrapolation incorporating METI tax policy scenario modeling and demographic cohort shift projections. Forecast inputs included barley futures price volatility bands and convenience store channel expansion trajectories.
Revisions become necessary when METI announces tax equalization implementation timelines, Australian or Canadian barley harvest failures materialize, or convenience store channel consolidation alters cooler access economics. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Japan Alcohol E-Commerce Market
Alcoholic Beverages
South Africa Tequila Market
Alcoholic Beverages
Global Spiced/Flavored Rum Market
Alcoholic Beverages
Beer Adjuncts Market
Alcoholic Beverages
Premix Bottled Cocktails Market
Alcoholic Beverages
Global Premium Alcoholic Beverage Market
Alcoholic Beverages
Lager Market
Alcoholic Beverages
Cabernet Sauvignon Market
Alcoholic Beverages
Liquor Flavored Ice Cream Market
Alcoholic Beverages
Citrus Alcohol Market
Alcoholic Beverages
Home Brewing Systems Market
Alcoholic Beverages
American Oak Barrels Market
Alcoholic Beverages
Middle East and Africa Fermented Drinks Market
Alcoholic Beverages
Rum Market
Alcoholic Beverages
Fortified Wine Market
Alcoholic Beverages
Mini Brew Fermenter Market