
 Japan Allulose Market | 2026-2036
Japan Allulose Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Allulose Market Insights
Pharmaceutical-grade allulose specifications is redrawing competitive boundaries in Japan. Ajinomoto Co. Inc. leverages its amino acid fermentation expertise to anchor high-purity production standards. Matsutani Chemical Industry Co. Ltd. sustains decades of rare sugar research to dominate domestic supply channels. Tate & Lyle competes through specialized enzymatic conversion platforms optimized for Japanese formulation requirements.
Allulose is a rare monosaccharide with approximately 70% of sucrose sweetness and negligible caloric content, produced through enzymatic epimerization of fructose using D-psicose 3-epimerase. It functions primarily as a bulking sweetener in reduced-calorie and diabetic-friendly food systems. Powder allulose leads volume due to its stability in baked applications and extended shelf compatibility, while liquid formats gain traction among beverage manufacturers seeking streamlined production integration. The nutraceuticals application segment shows accelerated uptake as FOSHU-eligible products incorporate allulose for glycemic management claims.
PMDA guidelines on novel food ingredients, Japan's Food Sanitation Act administered by the Ministry of Health, Labour and Welfare, and METI's biotechnology promotion frameworks collectively shape market access and purity benchmarks. FOSHU approval requirements drive manufacturers toward documented physiological efficacy data and stringent quality documentation. Stakeholders must monitor evolving standards for rare sugar labeling and assess fermentation capacity expansions against regional demand shifts.
Market Dynamics
FOSHU regulatory acceleration is compressing ingredient approval timelines from years to months, forcing manufacturers to restructure R&D pipelines around documented physiological efficacy rather than traditional sensory testing protocols.
Growth Catalysts
- Enzymatic epimerization advances:D-psicose 3-epimerase efficiency gains are lowering production costs for food-grade allulose. Tate & Lyle's platform refinements enable higher-purity outputs at commercial scale.
- Beverage formulation demand:Zero-calorie drink manufacturers in Osaka and Tokyo are integrating liquid allulose for streamlined production lines. Powder formats follow for bakery applications.
- METI biotechnology promotion:Government funding for rare sugar fermentation infrastructure is expanding domestic production capacity. Grants target glycemic management ingredient development.
Market Restraints
- Fructose feedstock volatility:Corn and beet sugar price fluctuations directly impact allulose manufacturing economics. Japanese importers face currency exposure on raw material purchases.
- PMDA novel food documentation:Extensive safety dossier requirements create multi-year approval pathways for new entrants. Smaller manufacturers lack resources for clinical substantiation.
- Stevia-monk fruit blends:Lower-cost natural sweetener combinations threaten allulose positioning in mass-market beverage segments. Price-sensitive buyers substitute readily.
Strategic Opportunities
- Kyushu fermentation cluster expansion:Underutilized biotech infrastructure in southern Japan offers cost-competitive manufacturing sites. Regional governments provide tax incentives for food-tech relocation.
- Nutraceutical FOSHU eligibility:Blood glucose management claims unlock premium pricing in aging-consumer supplements. Documented efficacy data supports functional food positioning.
- Direct-to-bakery distribution:Bypassing traditional ingredient wholesalers reduces margin compression. Specialty patisseries in Tokyo seek certified low-glycemic inputs.
Industry Challenges
- D-psicose 3-epimerase specialist scarcity:Fermentation biochemists with rare sugar expertise command premium salaries. Universities produce limited graduates in this niche.
- FOSHU certification timeline compression:Accelerated approval demands strain quality documentation teams. Manufacturers must parallel-track clinical studies with production scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Allulose Market |
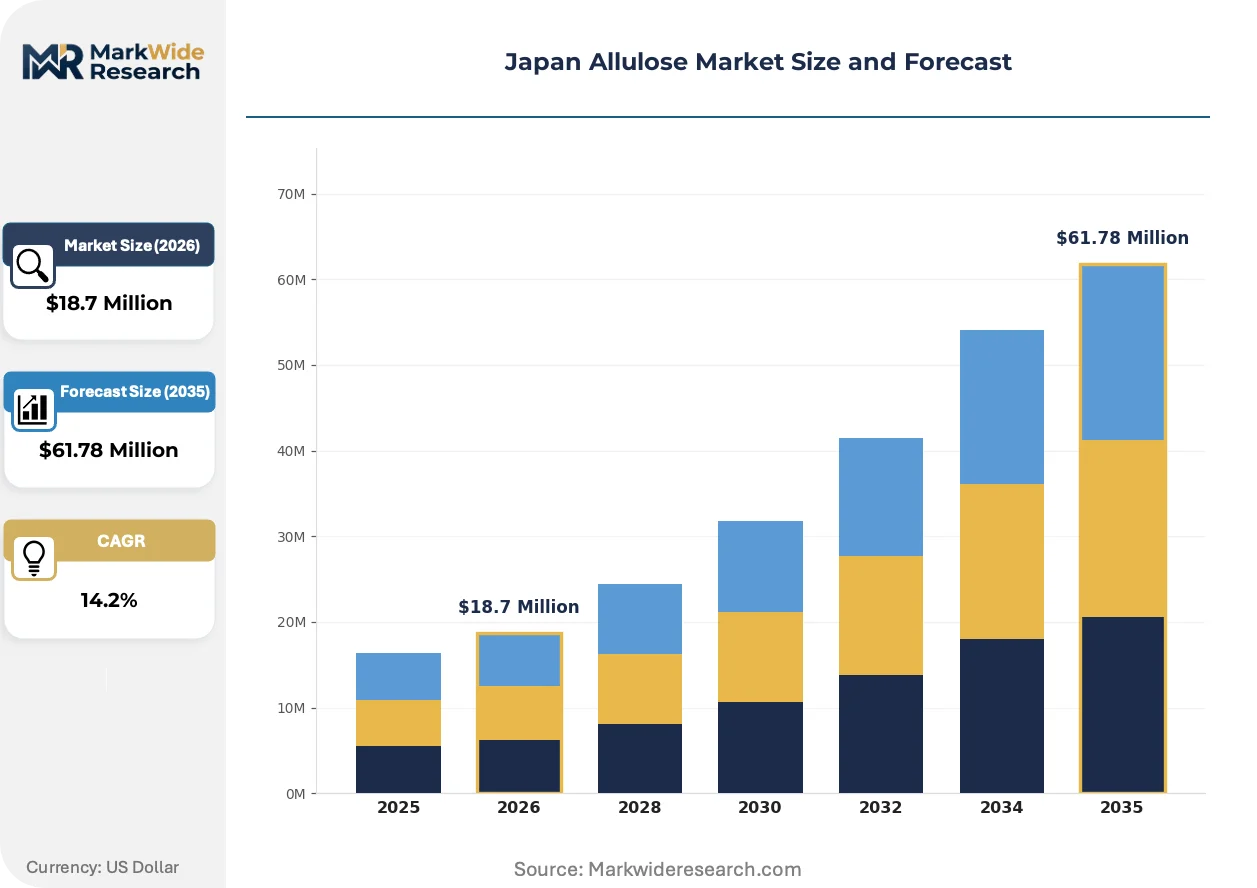
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $61.78 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Granulated, Blends End User: Beverage Manufacturers, Bakeries, Dairy Products, Confectionery Application: Food & Beverages, Nutraceuticals, Personal Care, Pharmaceuticals Distribution Channel: Online Retail, Supermarkets, Health Stores, Food Service |
| Companies Covered | Tate & Lyle, Ajinomoto Co. Inc., Matsutani Chemical Industry Co. Ltd., Nagase & Co. Ltd, Mitsui DM Sugar Holdings Co. Ltd, Samyang Corporation, CJ Cheil Jedang, Mitsubishi Corporation, Ingredion Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Allulose Market Trends and Innovations
Continuous enzymatic conversion systems are replacing batch fermentation as the dominant production paradigm, enabling real-time quality monitoring and reducing downstream purification burdens.
Fixed-bed enzyme reactor technology is supplanting traditional stirred-tank fermentation for allulose manufacturing. Ajinomoto and domestic competitors are retrofitting amino acid production lines with immobilized D-psicose 3-epimerase systems. This shift enables 24-hour continuous processing with 40% lower labor intensity than batch methods.
PMDA's streamlined rare sugar evaluation pathway is shortening novel food ingredient approvals from 36 months to 18 months for substances with prior FOSHU recognition. Manufacturers are front-loading clinical glycemic response studies to exploit this regulatory efficiency. Powder allulose suppliers benefit most from accelerated timeline certainty.
Japanese beverage formulators are consolidating sweetener purchasing around single-source rare sugar contracts rather than multi-ingredient hedging strategies. Kirin and Suntory procurement teams negotiate directly with Matsutani Chemical for dedicated production volumes. This concentration shifts supplier power toward domestic producers with proven FOSHU track records.
Japan Allulose Market Segmentation
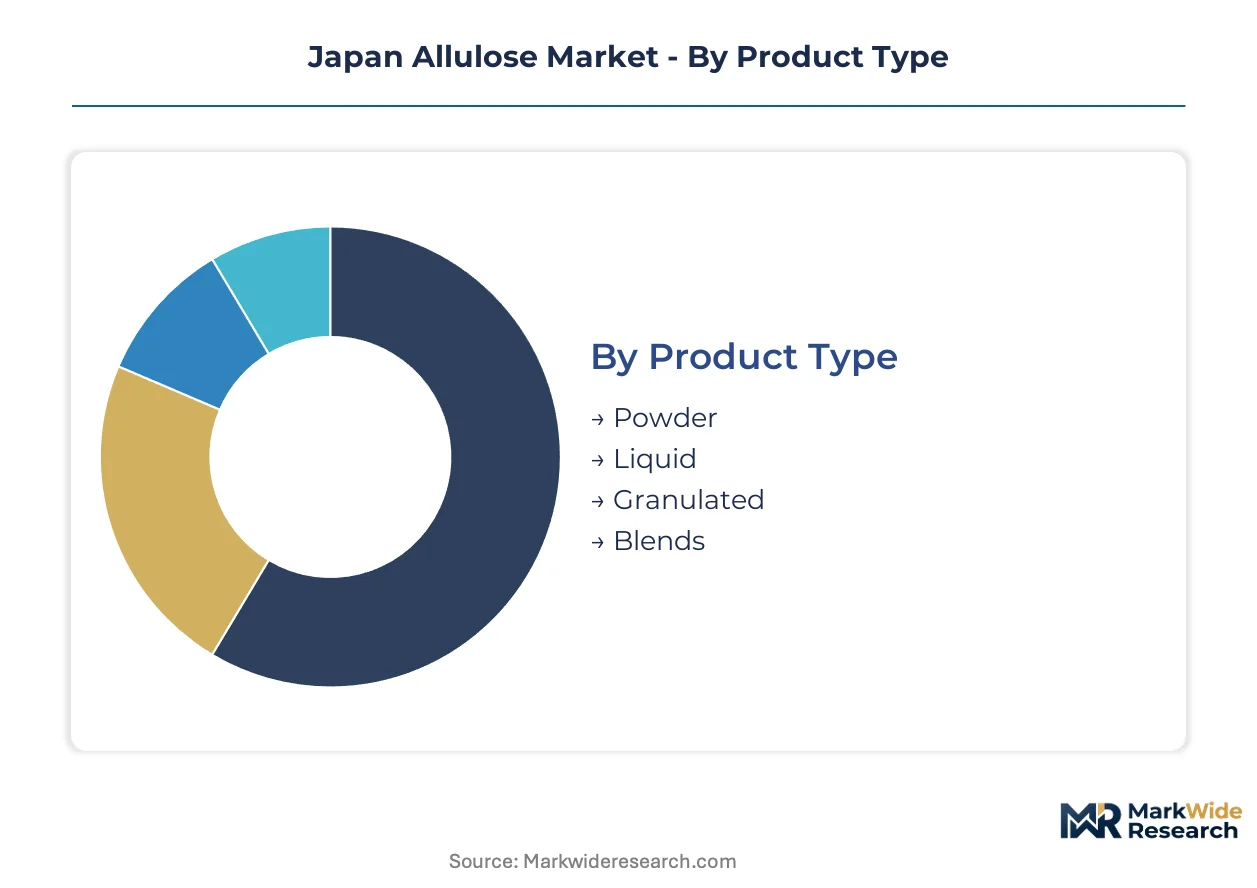
Allulose segmentation in Japan reflects the tension between established supply chains serving traditional food manufacturers and emerging channels targeting functional food innovators. Channel-mix decisions determine which product formats gain shelf space and which applications absorb volume growth.
Product Type:
Powder allulose flows through industrial ingredient distributors to bakeries and confectionery houses, while liquid formats bypass wholesalers for direct beverage manufacturer contracts.
- Powder:Crystalline allulose with 99% purity and 12-month shelf stability anchors bakery and confectionery formulations. Kanto region patisseries specify powder for macaron and sponge cake applications where bulk replacement of sucrose is critical.
- Liquid:Aqueous solutions at 70% solids concentration enable streamlined dosing in beverage production lines. Osaka-based zero-calorie drink manufacturers integrate liquid allulose for reduced handling costs and faster batch turnaround.
- Granulated:Free-flowing crystal structure mimics table sugar pour characteristics for consumer retail packaging. Health stores in Tokyo stock granulated formats for home baking enthusiasts seeking FOSHU-certified ingredients.
- Blends:Pre-mixed combinations with erythritol or monk fruit extract target cost-sensitive mass-market applications. Supermarket private-label lines utilize blends for price-competitive positioning against pure allulose premium SKUs.
Powder dominates installed base. Liquid is where expansion concentrates.
End User:
Cost tier stratification separates premium-positioned nutraceutical buyers from volume-driven beverage manufacturers seeking input cost optimization.
- Beverage Manufacturers:Kirin and Suntory procurement teams negotiate annual volume contracts with rare sugar suppliers. These buyers prioritize supply security and FOSHU documentation over per-kilogram pricing.
- Bakeries:Specialty patisseries in Tokyo's Ginza district source pharmaceutical-grade allulose for diabetic-friendly product lines. Certification requirements drive these buyers toward established domestic suppliers with PMDA-tracked quality systems.
- Dairy Products:Yogurt and ice cream formulators leverage allulose for reduced-calorie claims without compromising freezing point depression. Hokkaido dairy cooperatives trial allulose in functional fermented milk products.
- Confectionery:Traditional wagashi producers in Kyoto adopt allulose for modernized low-glycemic variants of classic sweets. These manufacturers balance heritage positioning with METI-promoted health functionality trends.
Beverage manufacturers absorb the largest procurement volumes. Bakeries command the steepest expansion trajectory.
Application:
Application mix correlates directly with regulatory pathway complexity — FOSHU-eligible categories absorb disproportionate R&D investment.
- Food & Beverages:The foundational application spans zero-calorie soft drinks, reduced-sugar baked goods, and diabetic-friendly confectionery. METI biotechnology promotion grants target this segment for glycemic management ingredient development.
- Nutraceuticals:Blood glucose management supplements represent the highest-margin application with documented physiological efficacy requirements. FOSHU approval unlocks premium pricing for aging-consumer products in Kanto and Kansai regions.
- Personal Care:Limited adoption in oral care and cosmetic formulations where humectant properties provide marginal value. This application remains exploratory with minimal dedicated production allocation.
- Pharmaceuticals:Excipient-grade specifications for tablet binders and syrup bases require PMDA novel food documentation. Smaller manufacturers lack resources for clinical substantiation in this category.
Food and beverages anchor current demand. Nutraceuticals is where margin expansion concentrates.
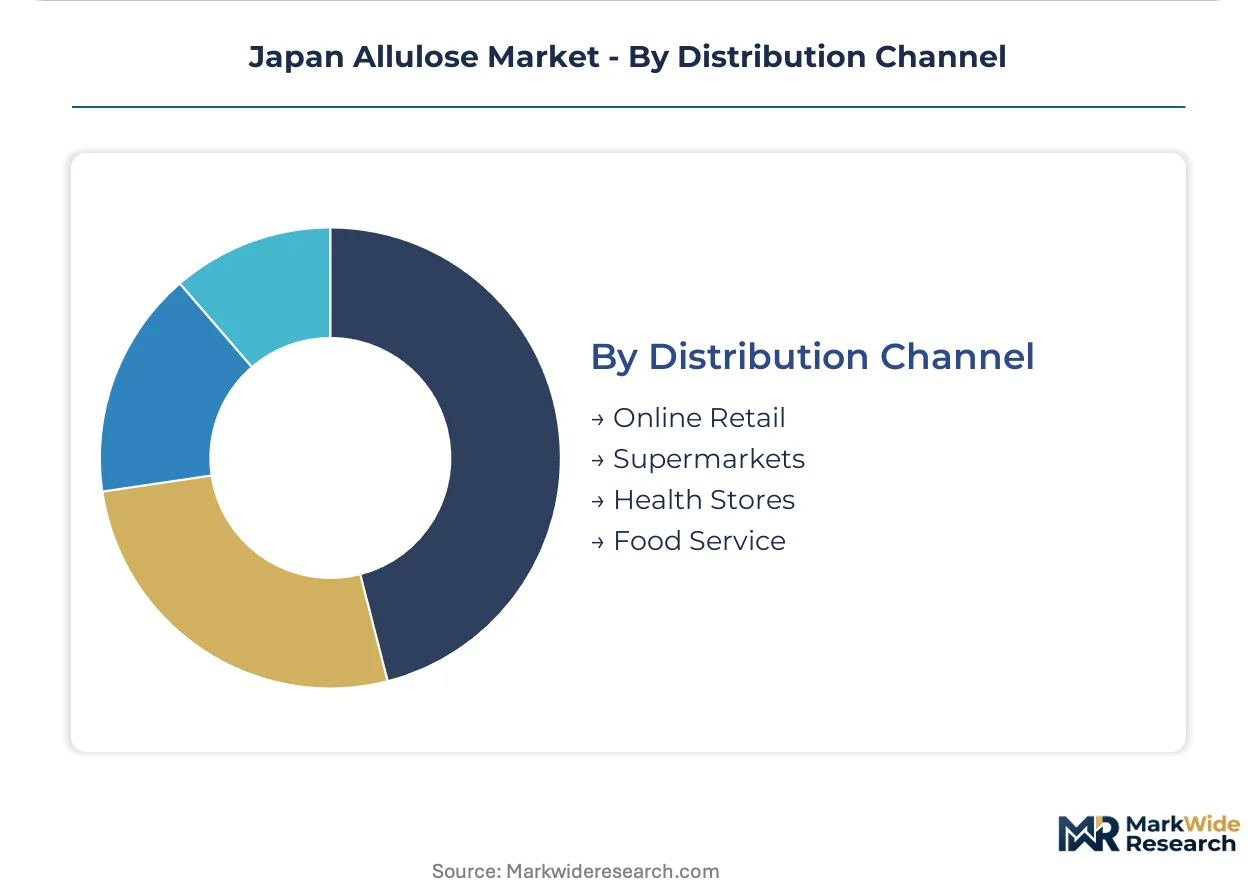
Distribution Channel:
Channel selection reflects customer scale — industrial buyers disintermediate traditional wholesale layers while retail consumers depend on physical presence.
- Online Retail:Direct-to-consumer platforms serve home bakers and small-scale nutraceutical formulators seeking certified low-glycemic inputs. Amazon Japan and Rakuten list granulated allulose from multiple domestic suppliers.
- Supermarkets:Mass retail placement requires volume commitments and promotional investment from ingredient brands. Aeon and Ito-Yokado chains stock blends in health food aisles alongside stevia products.
- Health Stores:Specialty retailers in Tokyo's Omotesando district curate pharmaceutical-grade allulose for discerning functional food consumers. Staff training on glycemic index benefits drives conversion rates.
- Food Service:Restaurant and café procurement teams source liquid allulose for menu items targeting diabetic and weight-conscious diners. Chain operators in Osaka integrate allulose into standardized recipes.
Supermarkets dominate unit volume throughput. Online retail is where customer acquisition concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese allulose production flows primarily to domestic beverage manufacturers in Kanto and Kansai, with limited exports to South Korean nutraceutical formulators seeking FOSHU-equivalent quality documentation.
Kanto
Tokyo's food technology cluster drives powder allulose demand for diabetic-friendly patisserie applications. METI biotechnology promotion grants target glycemic management ingredient development in this corridor. Specialty bakeries in Ginza source pharmaceutical-grade specifications from domestic suppliers with PMDA-tracked quality systems.
Kansai
Osaka-based zero-calorie drink manufacturers absorb liquid allulose volumes for streamlined production integration. The region's beverage procurement teams negotiate annual contracts prioritizing supply security over per-kilogram pricing. Kyoto wagashi producers balance heritage positioning with METI-promoted health functionality trends.
Kyushu
Underutilized fermentation infrastructure in southern Japan offers cost-competitive manufacturing sites for rare sugar production. Regional governments provide tax incentives for food-tech relocation to this biotech corridor. Fukuoka's emerging food ingredient cluster attracts enzymatic conversion platform investments.
Hokkaido
Dairy cooperatives trial allulose in functional fermented milk products targeting glycemic management claims. The prefecture's cold chain infrastructure supports extended shelf stability requirements for nutraceutical distribution. Sapporo-based formulators experiment with freezing point depression properties in reduced-calorie ice cream.
Japan Allulose Market Competitive Landscape
Listed leaders compete with private specialists across enzymatic conversion expertise. The vendor base stratifies between consolidated amino acid fermentation houses and mid-cap rare sugar specialists. Three archetypes dominate: integrated fermentation conglomerates with backward enzyme supply control, dedicated rare sugar research houses with decades of D-psicose epimerase development, and multinational ingredient traders leveraging global feedstock procurement networks. Capacity expansion and FOSHU documentation acceleration represent the dominant competitive moves.
Within the integrated fermentation tier, Ajinomoto Co. Inc. and Matsutani Chemical Industry Co. Ltd. anchor domestic production standards through captive enzymatic platforms. Tate & Lyle occupies a position among multinational specialists adapting global rare sugar expertise to Japanese formulation requirements. These three entities exemplify the tension between domestic purity benchmarks and international scale economics.
| Leading Market Players |
|---|
| Tate & Lyle |
| Ajinomoto Co. Inc. |
| Matsutani Chemical Industry Co. Ltd. |
| Nagase & Co. Ltd |
| Mitsui DM Sugar Holdings Co. Ltd |
| Samyang Corporation |
| CJ Cheil Jedang |
| Mitsubishi Corporation |
| Ingredion Inc |
| Others |
Pricing and Supply Chain Analysis
Enzymatic conversion technology displacing traditional batch fermentation simultaneously relocates production economics toward Kyushu's underutilized biotech infrastructure and compresses price premiums for pharmaceutical-grade allulose specifications. This substitution dynamic rewards domestic suppliers with captive D-psicose 3-epimerase platforms while pressuring importers exposed to fructose feedstock currency volatility.
Pricing Analysis
Batch-to-continuous processing technology-generation pricing gaps separate incumbent fermentation houses from retrofitting specialists, with fixed-bed reactor systems commanding 15-25% premiums over stirred-tank outputs. Three-tier pricing structure across FOSHU-certified pharmaceutical grade, food-grade pure, and economy blends reflects certification depth and documented glycemic efficacy data. Cost compression in economy blends is intensifying because stevia-monk fruit alternatives capture mass-market beverage procurement. Beverage manufacturers exhibit lowest price sensitivity due to supply security priorities, while supermarket private-label buyers drive blend substitution.
Supply Chain Analysis
Strait of Malacca transit vulnerability for fructose feedstocks from Southeast Asian corn and beet sugar sources underwrites inventory positioning strategies across Japanese ports. Domestic production draws from Kyushu fermentation clusters and Kanto enzymatic conversion facilities, with South Korean nutraceutical formulators absorbing limited export volumes. Single-source vulnerability concentrates in D-psicose 3-epimerase enzyme supply controlled by Ajinomoto and Matsutani captive platforms. Distribution runs through industrial ingredient wholesalers to bakeries and direct contracts to beverage manufacturers, bypassing traditional layers for liquid format procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FOSHU regulatory acceleration constitutes a high-growth disruption, compressing approval timelines from 36 months to 18 months and rewarding manufacturers with front-loaded clinical glycemic response documentation.
For Market Incumbents: Secure FOSHU certification pipeline dominance by parallel-tracking clinical studies with production scale-up, defending against emerging enzymatic platform specialists through backward integration into immobilized enzyme reactor technology. Channel control via direct-to-bakery distribution contracts in Tokyo's Ginza district preserves margin position against wholesale disintermediation threats. For New Entrants and Emerging Players: Anchor in Kyushu's tax-incentivized fermentation corridor to exploit underutilized biotech infrastructure and regional government relocation grants, targeting white-space opportunities in nutraceutical blood glucose management supplements where documented efficacy requirements create barrier-protected premium positioning. Direct-to-consumer online retail platforms offer streamlined go-to-market access for granulated formats targeting home baking enthusiasts. For Investors and Strategic Acquirers: PMDA's streamlined rare sugar evaluation pathway reshapes the acquisition landscape toward domestic producers with proven FOSHU track records and captive enzymatic platforms. Long-term viability centers on 5-10 year windows where glycemic management claims penetrate aging-consumer supplements. Acquisition target archetype: mid-cap rare sugar specialists with decades of D-psicose epimerase development and PMDA-tracked quality systems. Signal to watch: METI biotechnology promotion grant allocations for rare sugar fermentation infrastructure expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FOSHU Certification Acceleration | Front-loaded clinical studies exploit PMDA's 18-month approval pathway for rare sugars. |
| Continuous Enzyme Reactor Retrofit | Fixed-bed systems enable 24-hour processing with 40% labor reduction versus batch methods. |
| Kyushu Manufacturing Relocation | Regional tax incentives attract food-tech investment to underutilized fermentation infrastructure. |
| Direct-to-Bakery Distribution | Bypassing wholesalers preserves margins for pharmaceutical-grade powder specifications in Tokyo. |
| Nutraceutical Application Expansion | Blood glucose management claims unlock premium pricing in Kanto and Kansai aging-consumer markets. |
Research Methodology
Operator-level perspectives from fermentation plant managers, FOSHU regulatory affairs specialists, beverage procurement directors at Kirin and Suntory, and Tokyo specialty patisserie owners anchored the qualitative base for this study. Secondary validation drew from METI biotechnology promotion grant disclosures, PMDA novel food ingredient filings, Japan Food Sanitation Act administrative guidance, and customs trade data on fructose feedstock imports. Bottom-up volume estimates from enzymatic conversion capacity installations were triangulated against top-down demand projections from beverage formulation trends and nutraceutical supplement launches.
Sensitivity analysis across feedstock price volatility scenarios, regulatory timeline compression assumptions, and substitution elasticity parameters for stevia-monk fruit alternatives shaped the analytical framework. Segmentation dimensions modeled include product format (powder, liquid, granulated, blends), end-user category (beverage manufacturers, bakeries, dairy, confectionery), application (food and beverages, nutraceuticals), and distribution channel. CAGRs were derived from installed capacity expansion schedules cross-referenced with FOSHU approval velocity and glycemic management claim penetration in aging-population supplements.
Material uncertainties — fructose feedstock currency exposure, PMDA documentation requirement evolution, and D-psicose 3-epimerase specialist labor scarcity — sit outside the modeled envelope. Forecasts reflect assumptions about METI grant continuity and FOSHU pathway stability that could revise projections if biotechnology promotion priorities shift. Practitioners should keep alternative scenarios live as rare sugar labeling standards and South Korean nutraceutical export demand evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Europe B2B Brown Sugar Market
Sweeteners
Corn Syrup Market
Sweeteners
Australia Allulose Market
Sweeteners
Sanding Sugar Market
Sweeteners
Asia-Pacific Sugar Substitute Market
Sweeteners
Citrus Molasses Market
Sweeteners
Invert Sugar Market
Sweeteners
Asia-Pacific Low-Calorie Sweeteners Market
Sweeteners
Vanilla Sugar Market
Sweeteners
South America Sugar Substitutes Market
Sweeteners
South Africa Food Sweetener Market
Sweeteners
Xylose Market
Sweeteners
Mannitol Market
Sweeteners
Short-Chain Fructooligosaccharides (Scfos) Market
Sweeteners
Low-Fat Sugar Market
Sweeteners
United States Xylitol Market