
 Kuwait Vegetables and Fruits Market | 2026-2036
Kuwait Vegetables and Fruits Market Size, Share, and Industry Trends Forecast 2026-2036
Kuwait Vegetables and Fruits Market Insights
Saudi Arabia's controlled-environment agriculture expansion is narrowing the Gulf's historical dependence on European and Asian imports. Al-Othman Trading Company leverages its integrated cold-chain logistics to dominate wholesale distribution across the emirate. The Sultan Center sustains premium positioning through direct sourcing relationships with Lebanese and Egyptian growers. Al Yasra Food anchors its competitive stance via specialized banana ripening facilities and temperature-controlled warehousing.
Kuwait vegetables and fruits constitute fresh and minimally processed edible plant products traded through multi-tier distribution networks, with shelf-life parameters typically ranging from three to fourteen days depending on cultivar, harvest maturity, and post-harvest cooling protocols. These products serve commercial food preparation, retail household consumption, and institutional catering functions within a high-import-dependency economy. Leafy greens and berries command premium margin pools due to perishability and air-freight intensity, while citrus fruits occupies volume leadership through longer storage stability and lower transport costs. Supermarkets and wholesale providers represent the structural backbone of distribution, though online grocery channels are capturing disproportionate growth from digitally native household segments.
Kuwait's Public Authority for Food and Nutrition and the Environment Public Authority jointly govern pesticide residue limits, cold-chain compliance, and plastic packaging reduction mandates that dictate import eligibility and retail presentation standards. The country's national food security strategy and import substitution programs are reshaping procurement patterns toward Gulf Cooperative Council-sourced alternatives and domestic hydroponic ventures. Stakeholders must monitor regulatory adjustments to shelf-life labeling requirements and evolving sustainability criteria that will determine market access for incumbent and new suppliers.
Market Dynamics
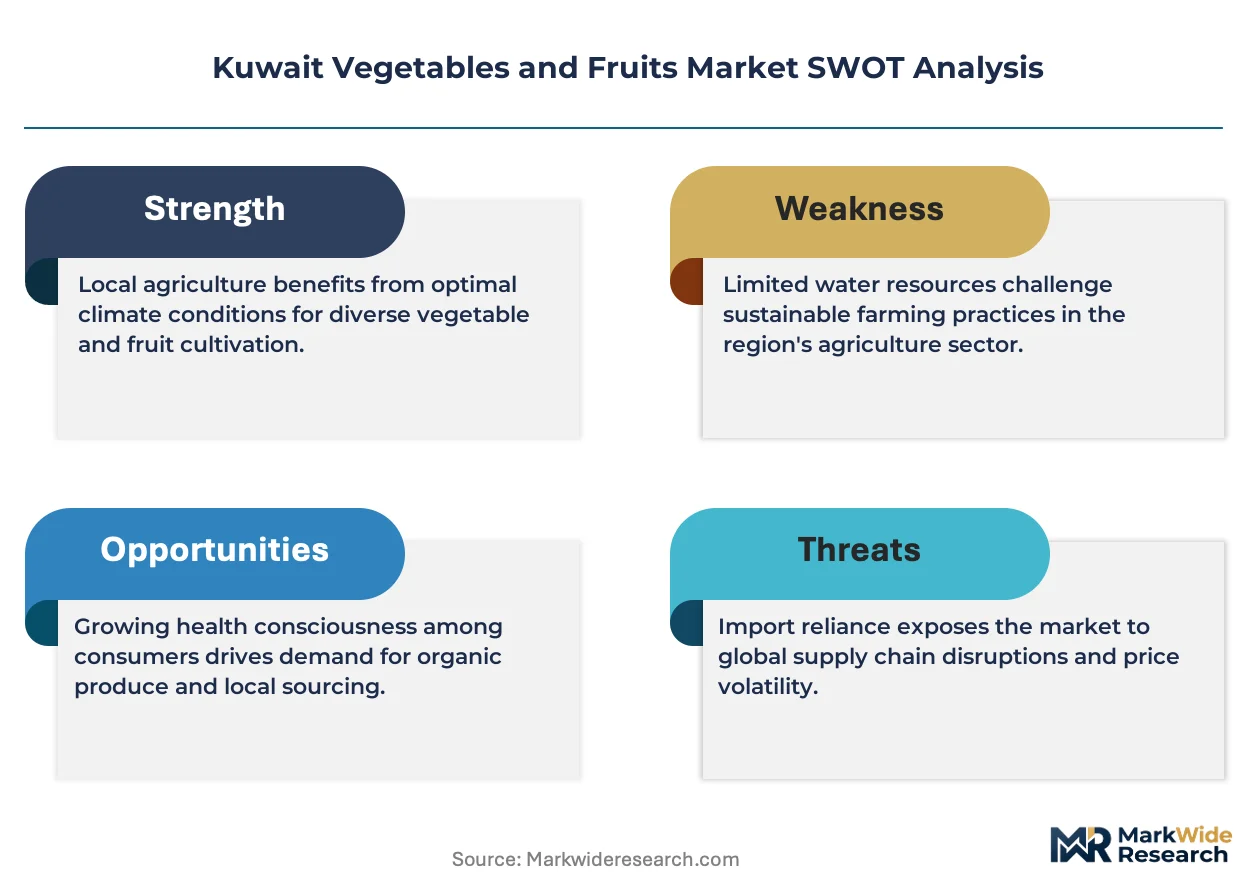
Import dependency and cold-chain fragility dominate Kuwait's vegetables and fruits sector, with the Public Authority for Food and Nutrition tightening residue testing protocols that reshape supplier eligibility and procurement timelines for inbound Mediterranean and South Asian shipments.
Growth Catalysts
- Hydroponic Investment Incentives:Kuwait's national food security strategy channels capital toward domestic controlled-environment agriculture, reducing air-freight exposure for leafy greens and herbs.
- Hotel and Restaurant Procurement:The hospitality sector's expanding fresh produce requirements pull higher-grade imports through specialized wholesale channels serving Kuwait City and Jahra Governorate clusters.
- EU-GCC Trade Alignment:REACH-equivalent safety standards adopted by Gulf Cooperative Council members streamline cross-border sourcing from Saudi Arabian greenhouse operations.
Market Restraints
- Air-Freight Cost Volatility:Jet fuel price swings disproportionately burden berry and asparagus categories that cannot tolerate maritime transit times.
- Single-Point Cold-Chain Failure:Kuwait International Airport's limited temperature-controlled cargo bays concentrate perishability risk during summer peak demand.
- Water Scarcity Constraints:Domestic cultivation faces absolute production ceilings from non-renewable groundwater reserves, capping import substitution potential regardless of capital deployment.
Strategic Opportunities
- Jahra Governorate Logistics Hubs:Underdeveloped warehousing infrastructure in Kuwait's northwestern agricultural zone offers first-mover positioning for integrated ripening and distribution facilities.
- Biodegradable Packaging Mandates:The Environment Public Authority's plastic reduction timeline creates supplier-switching windows for Lebanese and Jordanian exporters with certified compostable materials.
- IoT-Enabled Traceability:Blockchain-tracked provenance systems converge with supermarket private-label expansion, enabling premium positioning through verified pesticide-free claims.
Industry Challenges
- HACCP Certification Bottlenecks:Extended approval timelines for new Egyptian and Indian suppliers strain inventory planning during seasonal transition periods.
- Refrigerated Fleet Scarcity:Shortages of multi-temperature trucking capacity between Shuwaikh Port and retail distribution centers force consolidation delays that compress shelf-life margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kuwait Vegetables and Fruits Market |
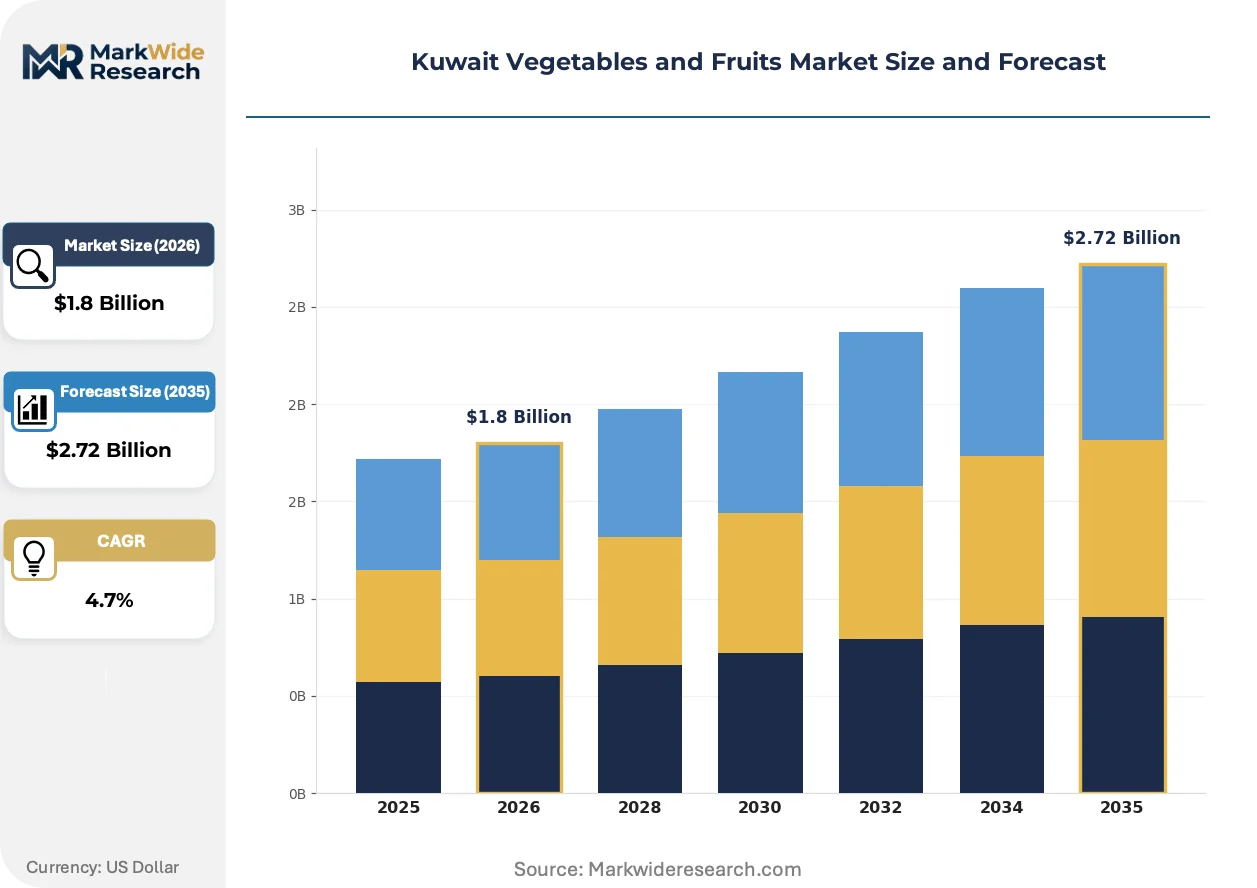
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leafy Greens, Root Vegetables, Berries, Citrus Fruits Distribution Channel: Supermarkets, Local Markets, Online Grocery, Wholesale Providers Customer Type: Households, Restaurants, Catering Services, Juice Shops Packaging Type: Bags, Boxes, Clamshells, Trays |
| Companies Covered | Al-Othman Trading Company, The Sultan Center, Al Yasra Food, Goodlife Gen Trad Food Co., Suma Fruits International (Alghanim Sons Group), Kuwait National Foodstuff Company (KNFC), Food & Fruit Company for Foodstuffs, Al Bustan Co., Al-Khayyat Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kuwait Vegetables and Fruits Market Trends and Innovations
Digital traceability and controlled-environment production methods are restructuring how Kuwait sources, certifies, and delivers fresh produce to price-sensitive yet quality-demanding household segments.
Hyperspectral sorting technology is collapsing quality-assurance timelines at import terminals. The Public Authority for Food and Nutrition has piloted automated residue detection systems that replace 72-hour laboratory holds with real-time clearance. Major supermarket importers now mandate this certification layer for all Lebanese stone fruit and Egyptian strawberry consignments, compressing supplier qualification cycles from months to weeks.
Kuwait's Environment Public Authority enforces plastic packaging reduction mandates that phase out conventional polyethylene wraps for loose produce by 2027. Retailers are responding with cellulose-based alternatives and bulk-display formats that shift handling costs onto consumers. The Sultan Center and cooperative societies in Salmiya and Riggae have deployed self-service weighing stations that eliminate pre-packaging entirely for root vegetables and citrus categories.
Subscription-based produce box models are capturing digitally native households that prioritize convenience over aisle browsing. Q8 Roots and similar ventures aggregate direct farm relationships into weekly delivery schedules, bypassing traditional wholesale markups. This channel shift concentrates most visibly in Kuwait City's Mishref and Salwa districts, where dual-income families demonstrate higher willingness to pre-commit to seasonal variety limitations in exchange for time savings.
Kuwait Vegetables and Fruits Market Segmentation
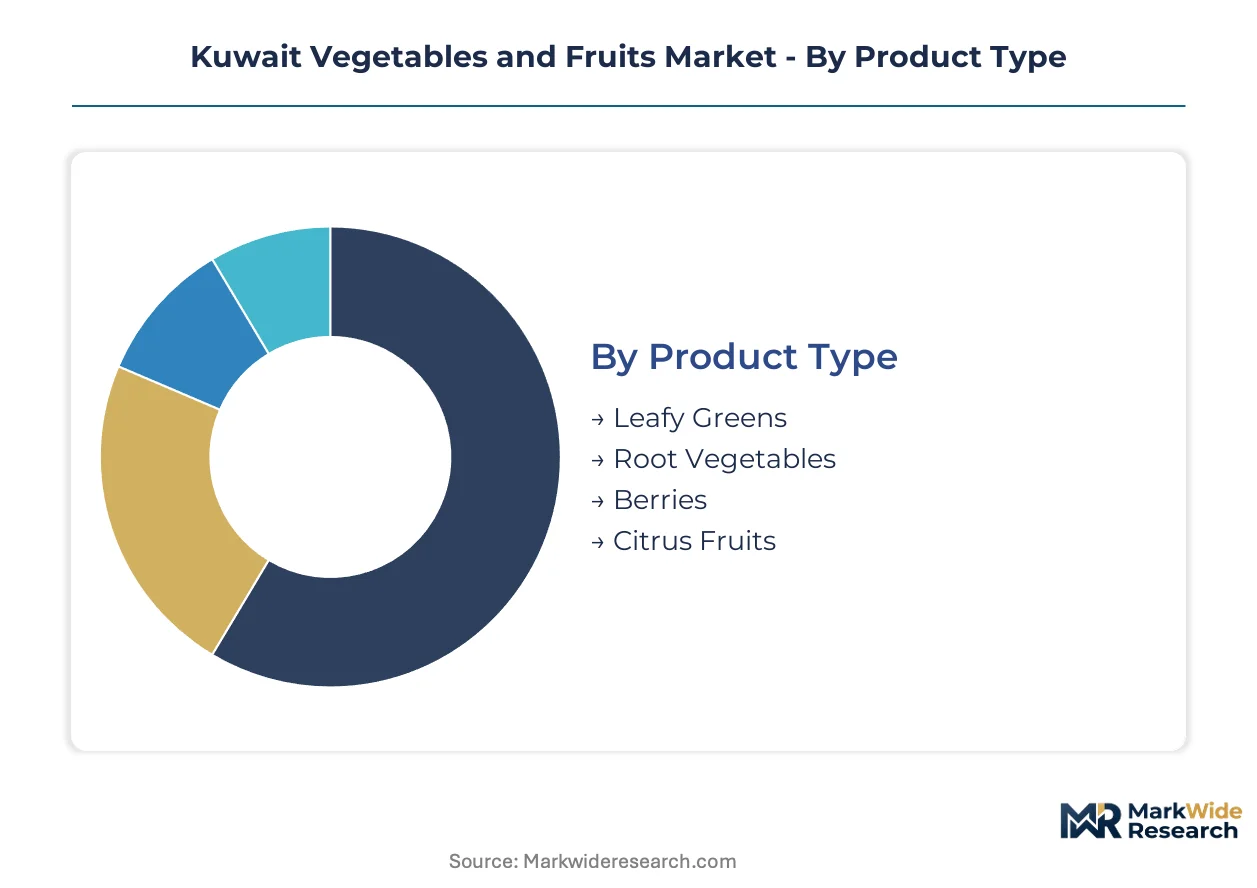
Kuwait's import-dependent produce sector fragments across four distinct dimensions. Each segmentation layer reveals how procurement patterns, shelf-life constraints, and regulatory compliance reshape competitive positioning within the emirate's $1.8 billion market.
Product Type:
Use-case spectrum spans from premium perishables demanding air-freight speed to volume staples tolerating maritime transit.
- Leafy Greens:Lettuce, spinach, and kale cultivars require continuous cold-chain maintenance from harvest through retail display. Demand concentrates in Kuwait City's hotel and restaurant corridors, where the Public Authority for Food and Nutrition's residue testing protocols favor certified hydroponic suppliers from Saudi Arabia.
- Root Vegetables:Carrots, potatoes, and beet varieties offer extended storage stability under controlled humidity. Procurement clusters around Jahra Governorate wholesale hubs serving institutional catering contracts, with Egyptian and Syrian exporters dominating volume leadership through lower transport cost structures.
- Berries:Strawberry, blueberry, and raspberry shipments face acute air-freight cost volatility. Lebanese growers maintain preferential access through direct supermarket relationships.
- Citrus Fruits:Oranges, lemons, and grapefruits occupy volume leadership through maritime container viability. Egyptian and Spanish suppliers compete on price-grade differentiation.
The dominant share belongs to Citrus Fruits, while Leafy Greens is closing the gap fastest.
Distribution Channel:
Cost-tier stratification separates capital-intensive modern retail from fragmented traditional trade.
- Supermarkets:The Sultan Center and cooperative societies deploy temperature-controlled display infrastructure with direct sourcing from Lebanese and Egyptian growers. Private-label expansion is concentrating procurement power among three banner groups controlling shelf-space allocation.
- Online Grocery:Q8 Roots and digital-native platforms aggregate farm-direct relationships into subscription models. Mishref and Salwa districts demonstrate highest penetration among dual-income households prioritizing convenience over aisle browsing.
- Local Markets:Shuwaikh and Riggae traditional souks handle unpackaged bulk transactions with minimal cold-chain investment. Price-sensitive households dominate this channel.
- Wholesale Providers:Al-Othman Trading Company and specialized distributors serve restaurant and hotel procurement through integrated ripening and logistics facilities.
Supermarkets command the largest revenue pool, though Online Grocery is expanding most quickly.
Customer Type:
Application-driven segmentation maps procurement specifications from household freshness standards to commercial food-safety certification.
- Households:Retail consumers prioritize visual quality and convenience packaging over provenance documentation. Salmiya and Riggae cooperative societies have eliminated pre-packaging for root vegetables through self-service weighing stations.
- Restaurants:Fine-dining establishments in Kuwait City demand HACCP-certified supply chains with documented pesticide residue compliance. Extended approval timelines for new Egyptian and Indian suppliers strain inventory planning.
- Catering Services:Institutional contracts emphasize volume consistency and price hedging through seasonal forward contracts.
- Juice Shops:Specialized outlets require blemish-grade citrus and pulp-density specifications distinct from retail quality tiers.
Households generate the highest absolute volume, yet Restaurants are driving the steepest margin expansion.
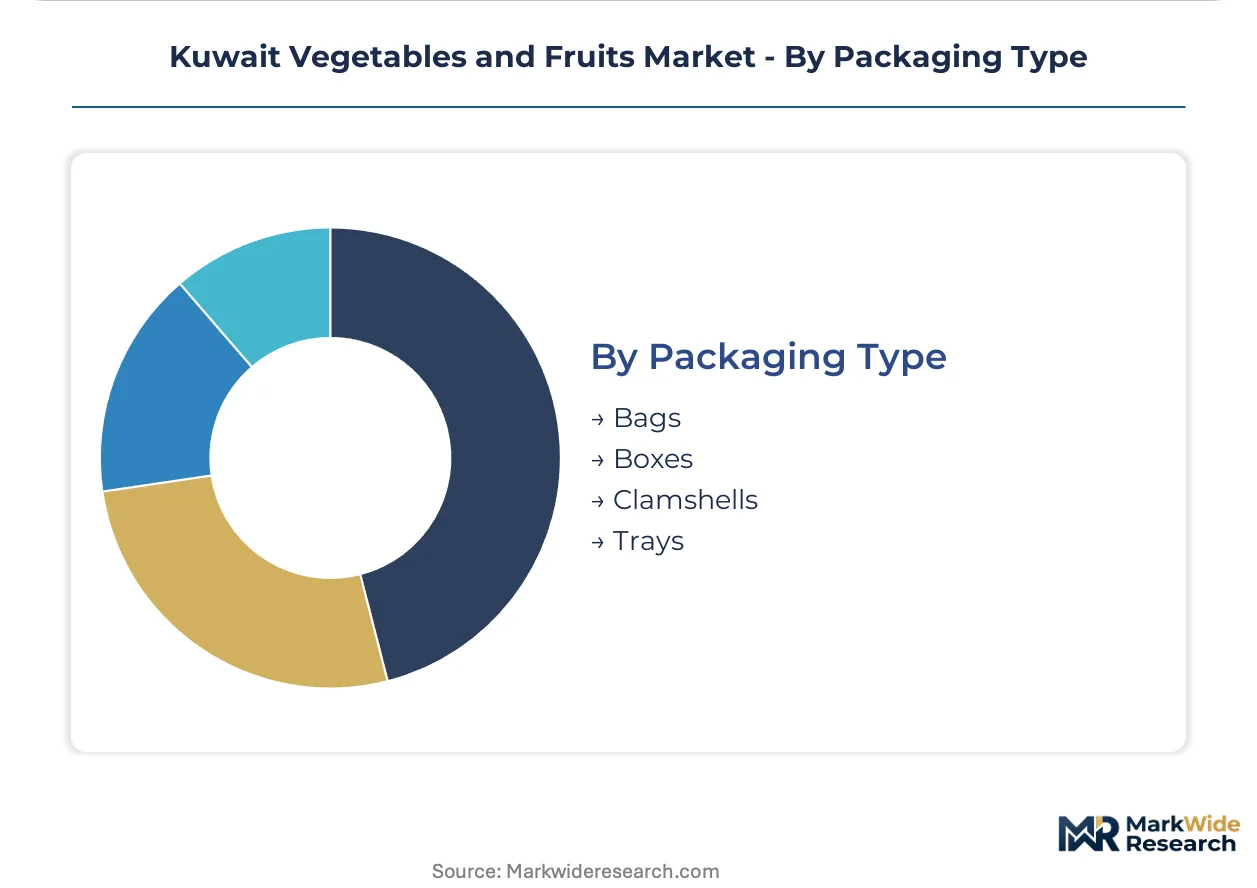
Packaging Type:
Margin structure correlates directly with material cost and regulatory compliance burden under Environment Public Authority mandates.
- Bags:Cellulose-based alternatives are displacing polyethylene wraps for loose produce categories. The 2027 phase-out deadline accelerates supplier-switching windows.
- Boxes:Corrugated fiberboard dominates citrus and root vegetable bulk shipment from Egyptian and Indian origins. Stackability and ventilation specifications vary by maritime versus air-freight modality.
- Clamshells:Rigid PET structures protect berry categories through handling-intensive distribution. Biodegradable substitutes command 15-20% cost premiums.
- Trays:Expanded polystyrene faces outright prohibition under plastic reduction timelines. Pulp-molded alternatives require moisture-barrier coatings for wet produce categories.
Boxes retain the largest installed base, though Bags are gaining share fastest from regulatory displacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fresh produce supply chains concentrate in Gulf Cooperative Council states with controlled-environment agriculture capacity. Kuwait's import dependency creates procurement corridors through Saudi Arabia, UAE, Egypt, and Lebanon. Each neighboring market shapes availability, pricing, and regulatory compliance for inbound shipments.
Saudi Arabia
Riyadh-based greenhouse operators supply hydroponic lettuce and herbs through Al-Qassim and Asir highland farms. The Saudi Food and Drug Authority enforces pesticide residue protocols aligned with Gulf standards. Jeddah Islamic Port's refrigerated terminals handle transshipment volumes bound for Kuwait City wholesale markets.
United Arab Emirates
Dubai's Jebel Ali free zone hosts re-export consolidation for South Asian mangoes and Indian pomegranates. Emirates Authority for Standardization and Metrology governs import documentation harmonization. Al Ain oasis farms supply dates and vegetables through direct trucking routes crossing Saudi territory.
Egypt
Nile Delta citrus growers and Upper Egypt tomato producers dominate maritime container volumes through Alexandria Port. The National Food Safety Authority manages export certification timelines that affect Kuwaiti inventory planning. Cairo-based exporters maintain dedicated cold-chain contracts with Shuwaikh Port handlers.
Lebanon
Bekaa Valley stone fruit and strawberry growers leverage air-freight speed through Beirut-Rafic Hariri International Airport. The Lebanese Ministry of Economy and Trade coordinates seasonal export windows. Tripoli port facilities handle lower-value root vegetable shipments during peak summer demand.
India
Maharashtra onion and Gujarat banana exporters compete on price-grade differentiation for Kuwait's institutional catering contracts. The Food Safety and Standards Authority of India regulates phytosanitary certification. Mumbai's Nhava Sheva port generates maritime transit economics that undercut air-freight alternatives for non-perishables.
Kuwait Vegetables and Fruits Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. Kuwait's vegetables and fruits sector consolidates around three banner groups controlling supermarket shelf-space allocation. Wholesale distributors maintain parallel dominance through integrated ripening and logistics infrastructure. Strategic archetypes include vertically integrated trading houses, direct-sourcing retailers, and specialized ripening operators. Competitive moves center on cold-chain capacity expansion and private-label portfolio diversification.
Within the integrated trading tier, Al-Othman Trading Company and Al Yasra Food exemplify platform dominance through captive warehousing and multi-temperature distribution networks. The Sultan Center occupies a position representing premium retail archetype with direct farm relationships. Goodlife Gen Trad Food Co. and Suma Fruits International sit within specialist importer categories serving hospitality procurement channels. Kuwait National Foodstuff Company anchors the institutional supply vector through government contract relationships.
| Leading Market Players |
|---|
| Al-Othman Trading Company |
| The Sultan Center |
| Al Yasra Food |
| Goodlife Gen Trad Food Co. |
| Suma Fruits International (Alghanim Sons Group) |
| Kuwait National Foodstuff Company (KNFC) |
| Food & Fruit Company for Foodstuffs |
| Al Bustan Co. |
| Al-Khayyat Company |
| Others |
Pricing and Supply Chain Analysis
Shuwaikh Port's temperature-controlled cargo consolidation determines margin distribution across Kuwait's import-dependent produce sector, with limited multi-temperature trucking capacity between maritime terminals and retail distribution centers compressing shelf-life economics for inbound Mediterranean and South Asian shipments.
Pricing Analysis
The Public Authority for Food and Nutrition's residue testing protocols dictate the pricing tier structure across Kuwait's vegetables and fruits sector. Three-tier pricing structure across premium, standard, and economy levels separates HACCP-certified hydroponic lettuce from conventional field-grown alternatives and unpackaged bulk root vegetables. Cost compression in the berry category is intensifying because air-freight fuel volatility disproportionately burdens air-shipped perishables. Households in traditional souk channels demonstrate highest price sensitivity, while fine-dining procurement in Kuwait City shows lowest elasticity for certified supply chains.
Supply Chain Analysis
Phytosanitary export controls limiting flows from Egyptian and Indian origins through extended HACCP approval timelines constrain supplier diversification for Kuwait's institutional buyers. Production clusters in Egypt, Lebanon, and Saudi Arabia feed the emirate's import dependency, with Nile Delta citrus and Bekaa Valley stone fruit dominating maritime and air-freight corridors respectively. Cold-chain inputs draw from refrigerated fleet capacity, temperature-controlled warehousing, and automated residue detection systems. Single-point vulnerability concentrates at Kuwait International Airport's limited climate-controlled cargo bays. Distribution runs through Al-Othman Trading Company's integrated ripening facilities and The Sultan Center's direct farm relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kuwait's vegetables and fruits sector represents an early-cycle expansion story as domestic hydroponic investment accelerates under national food security strategy capital deployment, with controlled-environment agriculture narrowing historical import dependency for leafy greens and herb categories.
For Market Incumbents: Pre-empt margin erosion in the berry segment by securing forward contracts with Lebanese air-freight operators before peak summer demand windows. Al-Othman Trading Company should expand captive ripening capacity in Jahra Governorate logistics hubs to defend against wholesale distributor consolidation. Certification investment in blockchain-tracked provenance systems creates differentiation as supermarket private-label expansion accelerates.
For New Entrants and Emerging Players: Jahra Governorate's underdeveloped warehousing infrastructure offers first-mover positioning for integrated temperature-controlled facilities serving northwestern agricultural zones. Subscription-based produce box models in Mishref and Salwa districts represent the most penetrable segment among dual-income households prioritizing convenience. Farm-direct aggregation partnerships bypass traditional wholesale markups and establish defensible supplier relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a import-substitution infrastructure play because domestic hydroponic capacity expansion aligns with Gulf Cooperative Council food security mandates. Acquisition targets should emphasize controlled-environment agriculture operators with established Saudi Arabian greenhouse operations and Kuwaiti distribution relationships. The signal to watch is Environment Public Authority acceleration of biodegradable packaging mandates that would shift supplier-switching windows toward certified compostable material providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Capacity Expansion | Multi-temperature warehousing at Jahra Governorate hubs reduces perishability risk for inbound Lebanese stone fruit. |
| Direct Farm Relationship Development | Bypassing Egyptian wholesale intermediaries compresses procurement timelines for The Sultan Center's private-label expansion. |
| Biodegradable Packaging Transition | Cellulose-based alternatives align with Environment Public Authority's 2027 polyethylene phase-out mandate for loose produce. |
| IoT-Enabled Traceability Investment | Blockchain-tracked provenance converges with supermarket private-label growth to enable pesticide-free premium positioning. |
| Controlled-Environment Agriculture Scale-Up | Domestic hydroponic lettuce production reduces air-freight exposure under Kuwait's national food security strategy. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with supermarket category buyers, wholesale distribution managers, hotel procurement directors, controlled-environment agriculture facility operators, and Environment Public Authority compliance officers. Secondary validation drew from Kuwait Public Authority for Food and Nutrition regulatory filings, Gulf Cooperative Council trade harmonization protocols, customs import documentation, hospitality sector procurement databases, and supermarket private-label expansion disclosures. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the produce import sector.
Calibration anchored historical volume trajectories to observed import flows through Shuwaikh Port and Kuwait International Airport cargo terminals. Segmentation dimensions spanned product type, distribution channel, customer application, and packaging format across the projection horizon. CAGRs were derived from trend extrapolation adjusted for regulatory intervention timelines and infrastructure investment cycles. Forecast inputs incorporated air-freight fuel cost volatility indices and domestic hydroponic capacity buildout schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Saudi Arabian greenhouse operators or accelerated biodegradable packaging mandate enforcement would shift outcomes. Material shifts in Gulf Cooperative Council trade alignment or Kuwait International Airport cargo capacity expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Global Jalapeno Pepper Market
Fruits and Vegetables
Freeze Dried Bananas Market
Fruits and Vegetables
Fresh Strawberry Market
Fruits and Vegetables
Olive Market
Fruits and Vegetables
Israel Fruits and Vegetables Market
Fruits and Vegetables
Morocco Fruits and Vegetables Market
Fruits and Vegetables
IQF Fruits and Vegetables Market
Fruits and Vegetables
Fruit and Vegetable Pieces and Powders Market
Fruits and Vegetables
Global Shiitake Mushroom Market
Fruits and Vegetables
Freeze-Dried Fruit Powder Market
Fruits and Vegetables
Peach Extract Market
Fruits and Vegetables
Starchy Roots Market
Fruits and Vegetables
Lycopene Market
Fruits and Vegetables
North America Organic Fruits Market
Fruits and Vegetables
North America Olive Market
Fruits and Vegetables
Passion Fruit Extract Market