
 Global Fruit Concentrate Puree Market | 2026-2036
Global Fruit Concentrate Puree Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fruit Concentrate Puree Market Analysis
Beverage manufacturers is realigning procurement priorities toward tropical and berry puree bases for functional and clean-label drink portfolios. Kerry Group leverages its integrated flavor systems to secure long-term supply contracts with multinational beverage brands. AGRANA Beteiligungs-AG anchors Central European fruit processing through its vertically controlled beet and fruit supply chains. Döhler differentiates via customized ingredient blends that combine puree concentrates with natural color and flavor compounds.
Fruit concentrate puree denotes mechanically processed fruit pulp with reduced water content, typically achieving 28-32 degrees Brix for standard concentrates and higher solids for industrial purees, produced through evaporation, aseptic filling, or cold-pressed concentration methods. This intermediate serves as a shelf-stable, standardized raw material enabling consistent flavor, color, and viscosity across batch production cycles. Berry puree and tropical fruit puree command premium positioning within the product type dimension, reflecting constrained raw material windows and complex cold-chain logistics. The beverage industry application segment leads volume absorption, while nutraceuticals represents the fastest-growing application channel as brands fortify puree bases with protein, fiber, and probiotic additions.
FDA enforces juice and puree labeling standards under 21 CFR 101.30, dictating minimum Brix levels and additive disclosure thresholds that govern US market access. EFSA and EU Green Deal frameworks impose pesticide residue ceilings and carbon footprint documentation requirements that reshape Mediterranean and Eastern European sourcing patterns. India's FSSAI mandates microbial load specifications and preservative limits for imported fruit concentrates entering dairy and bakery processing channels. Stakeholders must monitor evolving deforestation-free supply chain regulations and water stress indices in key growing regions to secure cost-competitive, compliant raw material positions.
Market Dynamics
Beverage manufacturers' pivot toward clean-label functional drinks concentrates procurement power among tropical fruit puree suppliers, while EU Green Deal carbon documentation mandates force sourcing network restructuring across Mediterranean and Eastern European processing corridors.
Growth Catalysts
- EU Green Deal sustainability frameworks:Mandatory carbon footprint documentation for imported fruit concentrates drives certified sourcing investments across Spanish, Italian, and Greek supply bases.
- Functional beverage formulation expansion:Protein fortification and probiotic integration into puree-based drinks accelerates demand for high-Brix industrial concentrates in North American and European bottling facilities.
- India FSSAI import standardization:Microbial load specifications for dairy and bakery processing channels formalize quality tiers that premium international suppliers exploit to displace informal domestic processors.
Market Restraints
- Raw material window constraints:Berry and tropical fruit harvest compression to 8-12 week annual cycles forces processors to absorb working capital intensity from extended cold storage requirements.
- Water stress indices in key growing regions:Irrigation-dependent mango and passion fruit cultivation in Maharashtra and Karnataka faces yield volatility from monsoon pattern disruption.
- Aseptic filling equipment capex thresholds:Minimum viable scale for commercial aseptic processing exceeds capital access for mid-tier processors across Southeast Asian supply bases.
Strategic Opportunities
- Underpenetrated nutraceutical applications:Gummy and soft-gel supplement manufacturers in Germany and Switzerland seek fruit puree bases as clean-label alternatives to synthetic colorants and flavor systems.
- Dual carbon policy alignment in China:MIIT energy efficiency mandates for food processing equipment create preference for cold-pressed concentration technologies that reduce thermal energy consumption.
- Direct-to-bakery distribution channels:Industrial-scale patisserie and artisanal bread producers in France and Belgium bypass traditional ingredient distributors to contract directly with puree processors for customized viscosity specifications.
Industry Challenges
- Specialized food engineering talent scarcity:Evaporation technology optimization and aseptic system maintenance require hybrid mechanical-microbiological expertise that outpaces vocational training output in Central European processing hubs.
- Legacy ERP integration with traceability platforms:Batch-level carbon accounting and deforestation-free documentation systems clash with installed manufacturing execution software at established Mediterranean fruit processors.
- Multi-jurisdiction certification timeline compression:Simultaneous pursuit of USDA Organic, EU Organic, and India NPOP accreditations extends product qualification cycles beyond annual harvest windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fruit Concentrate Puree Market |
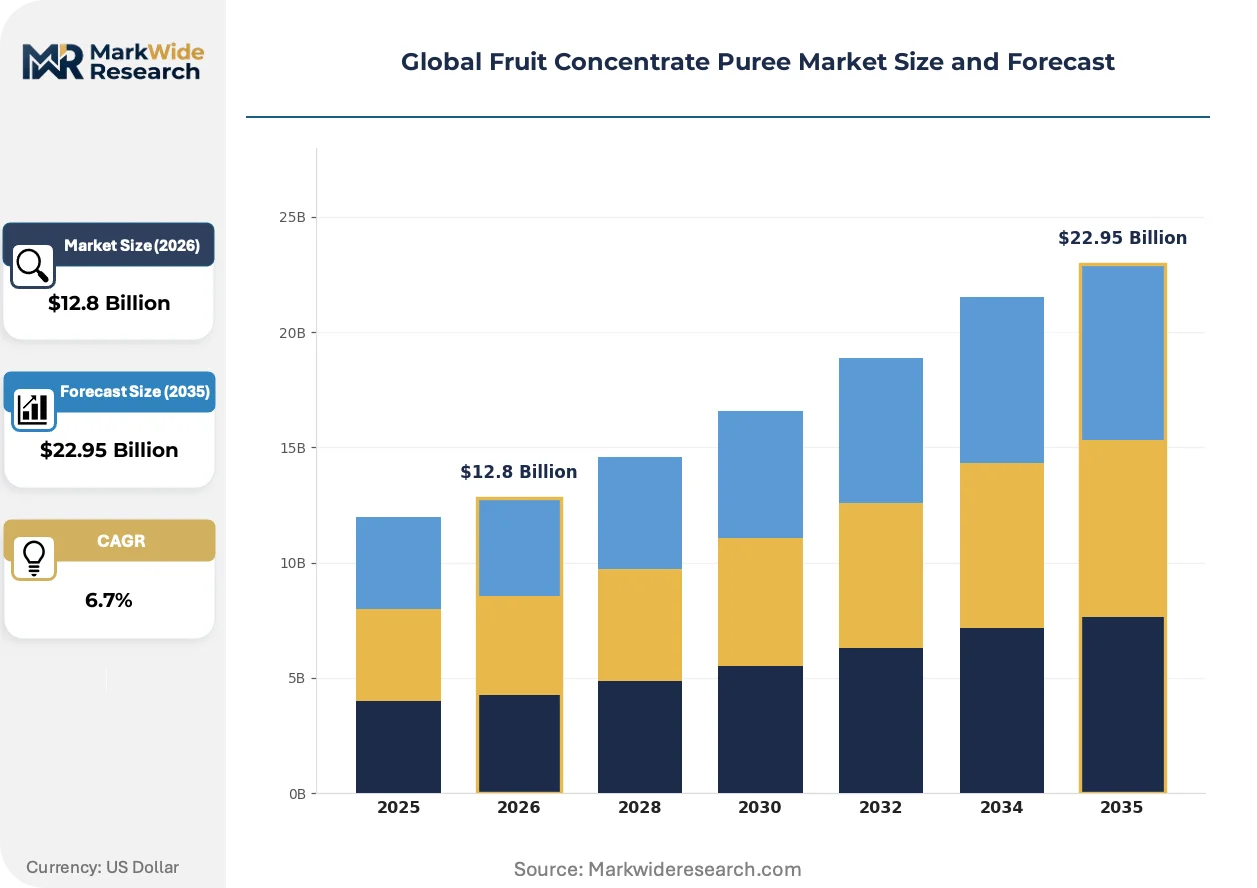
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Berry Puree, Stone Fruit Puree, Tropical Fruit Puree, Citrus Puree End User: Beverage Manufacturers, Bakery Producers, Ice Cream Manufacturers, Dairy Processors Packaging Type: Cartons, Pouches, Tubs, Drums Application: Food Industry, Beverage Industry, Confectionery, Nutraceuticals |
| Companies Covered | Kerry Group, AGRANA Beteiligungs-AG, ADM, Tree Top, Ingredion, Sudzucker, SVZ, SunOpta, Döhler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fruit Concentrate Puree Market Emerging Trajectories
Processing technology automation and regulatory documentation digitization are compressing batch-to-market timelines while procurement centralization among multinational beverage brands reshapes supplier qualification protocols.
Hyperspectral sorting and AI-driven defect detection is automating raw fruit quality assessment at receiving docks, enabling real-time Brix and maturity indexing that bypasses manual sampling delays. Large-scale Brazilian and Mexican mango processors deploy these systems to reduce pre-processing holding times from 72 hours to under 8 hours, compressing working capital cycles and reducing spoilage-driven yield loss.
REACH chemical safety registration and EU Green Deal deforestation-free supply chain regulations impose upstream documentation burdens that favor vertically controlled sourcing networks over spot-market procurement. Mediterranean fruit processors respond by deploying blockchain-anchored traceability platforms that map orchard-to-package provenance for each concentrate batch.
Buyer consolidation among multinational beverage conglomerates concentrates volume contracts with fewer qualified suppliers, displacing fragmented procurement across regional distributors. This pattern concentrates most visibly in North American and Western European markets, where three-tier supplier qualification systems now mandate simultaneous food safety, carbon accounting, and social compliance audits before contract award.
Global Fruit Concentrate Puree Market Segmentation
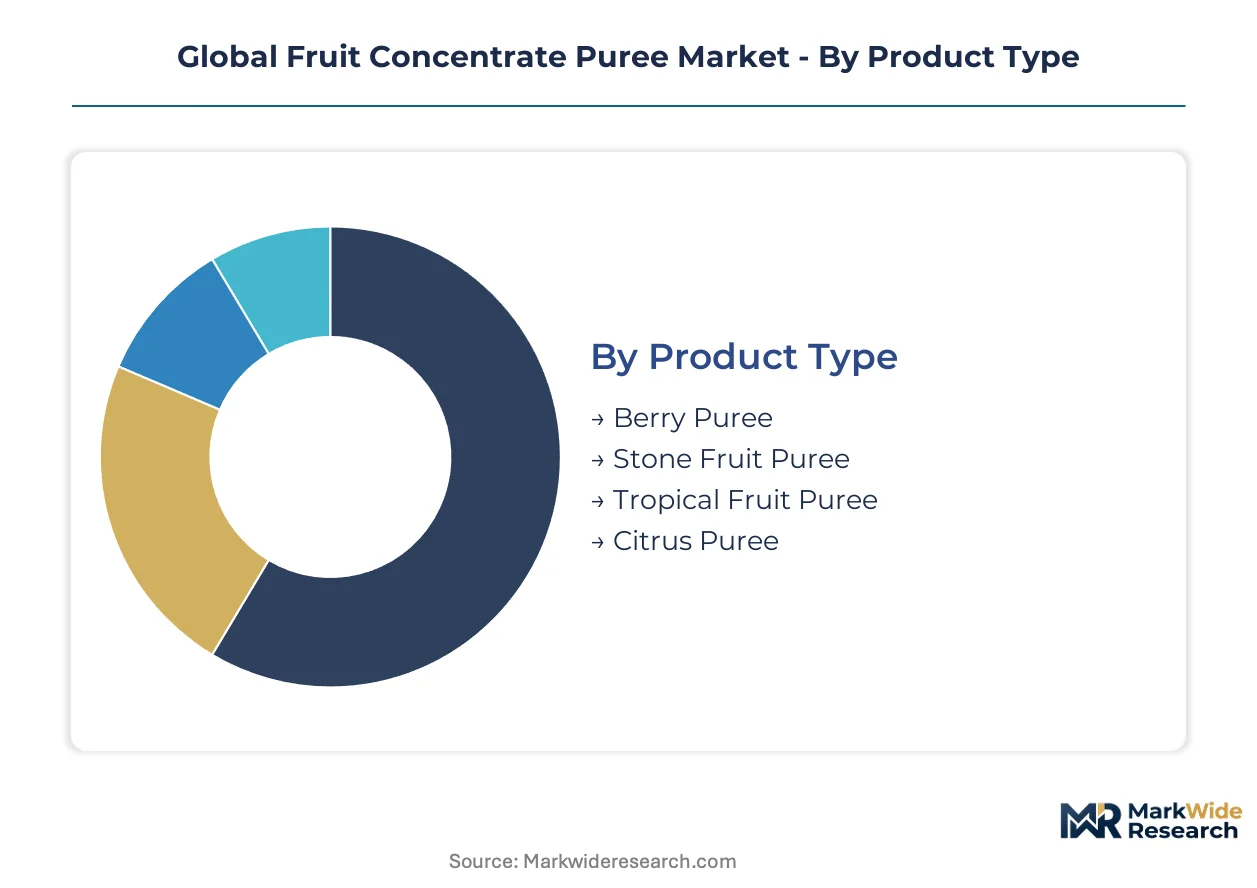
Fruit concentrate puree segmentation reflects divergent technical requirements across processing tiers. Standalone industrial concentrates demand different Brix specifications and aseptic handling than embedded ingredient systems serving finished food formulations.
Product Type:
Integration depth varies sharply: berry and tropical purees function predominantly as standalone bases requiring full cold-chain integrity, while citrus and stone fruit concentrates embed more readily into multi-component processing streams.
- Berry Puree:Achieves 28-32 degrees Brix through vacuum evaporation, retaining anthocyanin stability for color-critical applications. Beverage manufacturers in Germany and Switzerland concentrate procurement here for functional drink portfolios, constrained by compressed harvest windows in Poland and Serbia that force extended cold storage cycles.
- Tropical Fruit Puree:Mango and passion fruit bases reach higher solids content through cold-pressed concentration to preserve volatile aromatics. Indian dairy processors and bakery producers scale industrial volumes, though Maharashtra irrigation stress from monsoon disruption injects raw material volatility.
- Stone Fruit Puree:Peach and apricot concentrates balance acidity profiles for dessert applications.
- Citrus Puree:Orange and mandarin bases serve as cost-efficient acidity modulators across beverage blending operations.
Volume placements concentrate in Tropical Fruit Puree; the faster expansion belongs to Berry Puree.
End User:
Cost tier stratification separates capital-intensive aseptic processors serving multinational beverage brands from mid-scale bakery and dairy operations accepting lower-Brix concentrates with shorter shelf stability.
- Beverage Manufacturers:Demand highest-Brix industrial concentrates with full carbon documentation under EU Green Deal frameworks. These buyers consolidate procurement among vertically controlled suppliers capable of blockchain-anchored traceability from orchard to aseptic fill.
- Bakery Producers:French and Belgian patisserie operations contract directly with processors for customized viscosity specifications, bypassing traditional ingredient distributors to secure batch-to-batch consistency in laminated dough and filling applications.
- Ice Cream Manufacturers:Require fruit bases with controlled water activity to prevent ice crystal formation during thermal shock.
- Dairy Processors:Indian yogurt and cheese producers drive import demand under FSSAI microbial load specifications that formalize quality tiers.
Revenue concentration sits with Beverage Manufacturers; margin expansion favors Bakery Producers.
Packaging Type:
Application context dictates format selection: aseptic cartons and drums serve high-volume industrial users, while pouches and tubs address batch-flexibility needs in artisanal and mid-tier processing environments.
- Drums:Industrial-scale aseptic drums with nitrogen flushing dominate tropical fruit concentrate exports from Brazil and Mexico. Hyperspectral sorting investments at receiving docks compress pre-processing holding times, reducing working capital intensity for large-volume beverage bottlers.
- Pouches:Flexible aseptic pouches gain share among German and Swiss nutraceutical gummy manufacturers seeking clean-label fruit bases as alternatives to synthetic colorants.
- Cartons:Standard brick formats serve regional dairy and bakery distributors with moderate throughput requirements.
- Tubs:Small-batch tubs address artisanal ice cream producers requiring frequent flavor rotation without inventory obsolescence.
Shipment volumes concentrate in Drums; format innovation clusters in Pouches.
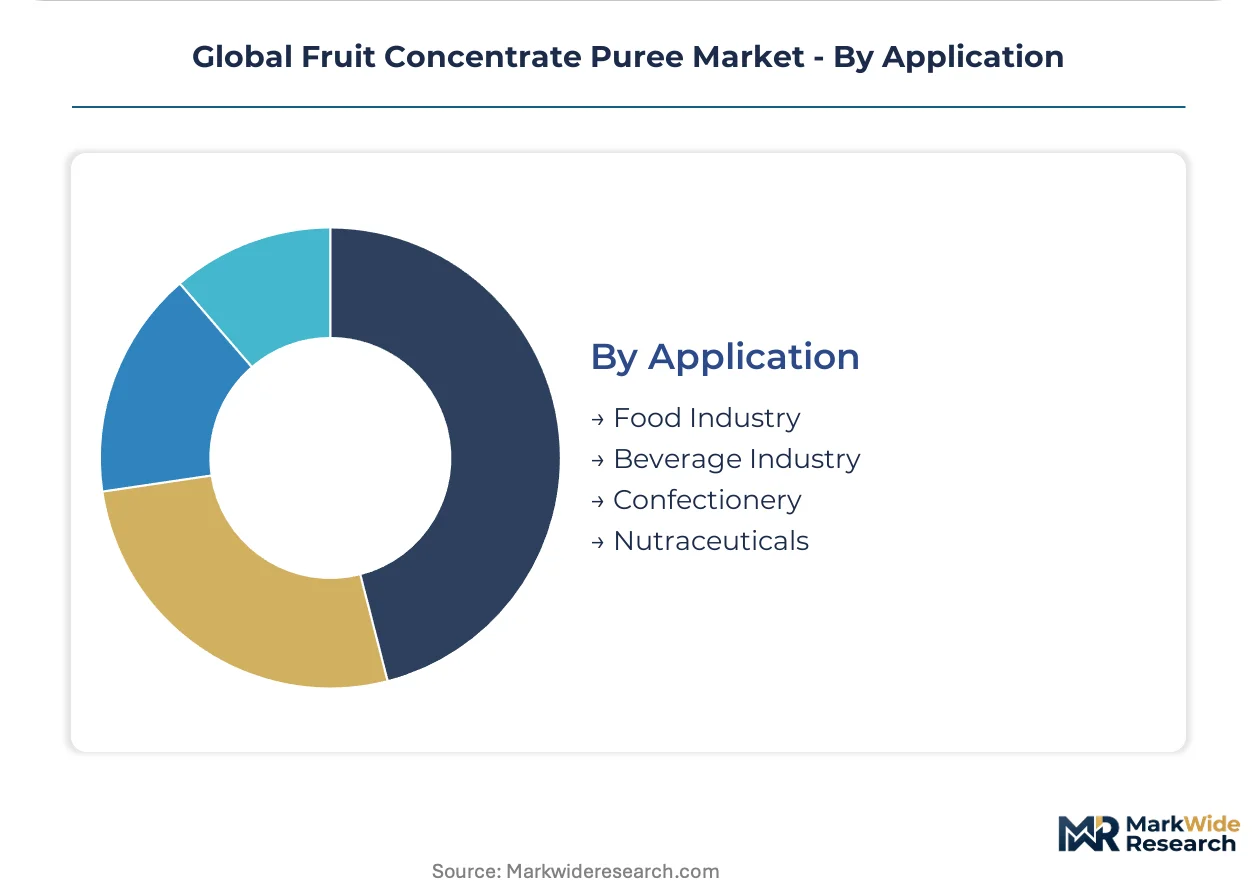
Application:
Supply concentration separates mature food and beverage channels from emerging nutraceutical demand, where protein fortification and probiotic integration command premium positioning.
- Beverage Industry:Absorbs the largest volume share through functional drink formulations combining tropical puree bases with protein and fiber additions. Clean-label mandates from multinational brand procurement offices reshape supplier qualification protocols toward carbon-accounted sourcing.
- Nutraceuticals:Gummy and soft-gel supplement manufacturers in Switzerland and Germany source fruit puree bases to displace synthetic flavor systems. EFSA novel food approvals and REACH chemical safety registrations impose upstream documentation burdens that favor established processors with regulatory affairs capacity.
- Food Industry:Sauces, dressings, and prepared meals incorporate lower-Brix concentrates for viscosity control.
- Confectionery:Fruit jellies and centers demand precise pH buffering to achieve target gel strength.
Volume placements concentrate in Beverage Industry; the steepest expansion trajectory belongs to Nutraceuticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing capacity clusters in tropical growing belts while formulation demand concentrates in temperate manufacturing corridors. The United States, Germany, India, Brazil, and France illustrate this geographic split between raw material supply and value-added consumption.
United States
Beverage manufacturers in California and the Pacific Northwest drive tropical puree procurement for functional drink portfolios. FDA juice labeling standards under 21 CFR 101.30 govern Brix specifications and additive disclosure thresholds. Seattle-area bottling facilities consolidate supplier qualification around carbon-accounted sourcing protocols.
Germany
Gummy and soft-gel nutraceutical manufacturers in Bavaria and Baden-Württemberg source berry puree bases as clean-label alternatives to synthetic inputs. REACH chemical safety registration and EU Green Deal deforestation-free mandates reshape upstream documentation requirements. Munich-based processing hubs deploy blockchain-anchored traceability platforms for orchard-to-package provenance mapping.
India
Dairy processors in Maharashtra and bakery producers in Karnataka scale industrial tropical puree volumes for yogurt and laminated dough applications. FSSAI microbial load specifications and preservative limits for imported concentrates formalize quality tiers that displace informal domestic processors. Mumbai-Ahmedabad corridor distribution networks bypass traditional ingredient wholesalers for direct processor contracts.
Brazil
Mango and passion fruit processors in São Paulo and Minas Gerais deploy hyperspectral sorting systems to compress pre-processing holding times from 72 hours to under 8 hours. ANVISA food safety protocols align with EU Green Deal carbon documentation requirements for export-oriented supply chains. Campinas industrial parks anchor aseptic filling capacity serving North American beverage bottlers.
France
Artisanal patisserie operations in Île-de-France and industrial bakeries in Hauts-de-France contract directly with puree processors for customized viscosity specifications in filling and laminated dough applications. EFSA pesticide residue ceilings and EU organic certification frameworks filter supplier pools. Paris basin distribution channels prioritize batch-flexibility formats over bulk industrial packaging.
Global Fruit Concentrate Puree Market Vendor Landscape
Top-tier vendors anchor multinational supply contracts, while mid-scale regional processors fill spot-market gaps. The vendor base stratifies across three capability tiers: integrated flavor houses with captive fruit processing, standalone concentrate specialists with aseptic infrastructure, and commodity traders without manufacturing assets. Dominant competitive moves include backward integration into orchard operations and technology licensing for cold-pressed concentration systems.
Among European-integrated ingredient houses, Kerry Group and AGRANA Beteiligungs-AG exemplify the vertically controlled archetype, while Döhler occupies a position within the customized blend specialist tier. Kerry Group leverages integrated flavor systems for long-term beverage contracts. AGRANA anchors Central European processing through controlled beet and fruit supply chains. Döhler differentiates via ingredient blends combining puree concentrates with natural color and flavor compounds.
| Leading Market Players |
|---|
| Kerry Group |
| AGRANA Beteiligungs-AG |
| ADM |
| Tree Top |
| Ingredion |
| Sudzucker |
| SVZ |
| SunOpta |
| Döhler |
| Others |
Supply Flow & Price Mechanics
Multinational beverage procurement offices mandating simultaneous carbon accounting, food safety, and social compliance audits before contract award force processors to absorb qualification costs that stratify pricing across certified and uncertified supply tiers. EU Green Deal deforestation-free documentation requirements and FDA juice labeling standards under 21 CFR 101.30 impose tiered compliance burdens that concentrate pricing power among vertically controlled suppliers capable of blockchain-anchored traceability.
Pricing Analysis
Short lead-time premiums for aseptic tropical puree concentrates compress spot-market discounts for extended cold-storage inventory held past optimal release windows. Three-tier pricing structure across premium, standard, and economy levels separates EU Organic and India NPOP dual-certified batches from single-certification and uncertified concentrates. Cost compression in mid-tier standard grades is intensifying because Maharashtra irrigation stress and monsoon pattern disruption inject raw material volatility into mango and passion fruit bases. Beverage manufacturers with consolidated volume contracts exhibit lowest price sensitivity; artisanal bakery producers in France and Belgium negotiating customized viscosity specifications face highest budget constraint.
Supply Chain Analysis
Specialized food engineering talent scarcity in Central European processing hubs—particularly evaporation technology optimization and aseptic system maintenance expertise—constrains capacity expansion at established Mediterranean fruit processors. Supply concentration centers on Brazil, India, and Mexico for tropical fruit puree, with Poland and Serbia anchoring berry concentrate production. Raw material dependencies rest on irrigation-dependent mango cultivation, cold-chain logistics infrastructure, and aseptic filling equipment. Single-source vulnerability from compressed 8-12 week harvest windows forces extended cold storage cycles. Distribution runs through direct processor-to-bakery channels in France and Belgium alongside traditional ingredient distributors serving mid-tier dairy operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aseptic filling equipment capex thresholds exceeding capital access for mid-tier Southeast Asian processors prop pricing for qualified supply, creating durable margin protection for incumbents with installed capacity. Raw material window constraints and multi-jurisdiction certification timeline compression extend product qualification cycles beyond annual harvest windows, reinforcing supply scarcity.
For Market Incumbents: Anchor backward integration into orchard operations in Maharashtra and Karnataka to secure irrigation-stressed mango supply against yield volatility from monsoon pattern disruption. Invest in cold-pressed concentration technology licensing to align with MIIT energy efficiency mandates in China while defending margin position against emerging spot-market traders without manufacturing assets. For New Entrants and Emerging Players: Capture underpenetrated nutraceutical applications in Germany and Switzerland where gummy and soft-gel supplement manufacturers seek clean-label fruit puree bases as alternatives to synthetic colorants. Target direct-to-bakery distribution channels in France and Belgium with batch-flexibility pouch formats that bypass traditional ingredient distributors for customized viscosity specifications. For Investors and Strategic Acquirers: The window for entry favors processors with installed aseptic infrastructure and dual carbon policy alignment capability across EU Green Deal and China MIIT frameworks. Long-term viability rests on acquisition of mid-scale regional processors with blockchain-anchored traceability platforms and existing EU Organic certification. Watch hyperspectral sorting and AI-driven defect detection adoption rates as inflection indicator for working capital efficiency compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Operations | Captive supply of Maharashtra and Karnataka mango bases insulates against irrigation stress yield volatility. |
| Cold-Pressed Concentration Technology Licensing | MIIT energy efficiency mandate alignment reduces thermal energy consumption for China market access. |
| Blockchain-Anchored Traceability Platform Deployment | EU Green Deal deforestation-free documentation satisfies multinational beverage procurement audit requirements. |
| Direct-to-Bakery Distribution Channel Development | Customized viscosity specifications for French and Belgian patisserie operations bypass distributor margins. |
| Dual Certification Investment (EU Organic, India NPOP) | Quality tier formalization under FSSAI microbial load specifications displaces informal domestic processors. |
Methodological Framework
Independent corroboration across beverage procurement executives, dairy processing plant managers, aseptic equipment engineers, and bakery R&D directors underwrites the qualitative findings on specification evolution and supplier qualification protocols. Secondary validation draws from FDA juice labeling standards filings, EU Green Deal framework documentation, FSSAI import standardization records, and customs trade data on tropical concentrate movements. Bottom-up volume modeling across product type, end user, and packaging format dimensions triangulates with top-down macroeconomic anchoring.
Historical reference periods spanning pre-pandemic baseline, supply chain disruption phase, and post-stabilization recovery anchor the forecast window across the analysis window. Segmentation dimensions modeled include product type integration depth, end-user cost tier stratification, packaging format application context, and geographic regulatory cluster. CAGRs derive from compound annual progression of segment-level volume and value outputs. Industry-specific forecast inputs incorporate water stress indices in key growing regions and aseptic filling capacity utilization rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to monsoon pattern disruption in Maharashtra and Karnataka, EU Green Deal carbon documentation mandate enforcement intensity, and multi-jurisdiction certification timeline compression effects. Forecasts reflect documented assumptions on procurement centralization trajectories and technology automation adoption curves. Material deviation in irrigation-dependent yield volatility or blockchain traceability platform deployment rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Yacon Fruit Extract Market
Fruits and Vegetables
Red Berries Market
Fruits and Vegetables
Butterfly Pea Flowers Market
Fruits and Vegetables
Brined Vegetable Market
Fruits and Vegetables
Global Shiitake Mushroom Market
Fruits and Vegetables
Egypt Fruits and Vegetables Market
Fruits and Vegetables
Freeze Dried Bananas Market
Fruits and Vegetables
Mung Beans Market
Fruits and Vegetables
North Africa Fruits and Vegetables Processing Market
Fruits and Vegetables
Fruit Puree Market
Fruits and Vegetables
Global Maqui Berries Market
Fruits and Vegetables
Fruit and Vegetable Cleaners Market
Fruits and Vegetables
Global Fresh Berries Market
Fruits and Vegetables
Acai Berry Market
Fruits and Vegetables
Middle East and Africa Shiitake Mushroom Market
Fruits and Vegetables
Global Papaya Puree Market