
 Spain Automotive LED Lighting Market | 2026-2036
Spain Automotive LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Automotive LED Lighting Market Insights
Spain is narrowing its reliance on imported LED modules through expanded domestic assembly lines in Catalonia and the Basque Country. Marelli Holdings Co Ltd leverages its Martorell-adjacent operations to supply SEAT and Volkswagen Group plants with localized headlamp assemblies. HELLA GmbH & Co KGaA (FORVIA) sustains engineering partnerships with Spanish Tier-1 suppliers for adaptive lighting calibration. KOITO MANUFACTURING CO LTD anchors its European distribution through Iberian logistics hubs serving Mediterranean OEM networks.
Automotive LED lighting denotes solid-state illumination systems employing semiconductor diodes with luminous efficacy exceeding 100 lumens per watt, fabricated through epitaxial gallium nitride deposition on sapphire substrates and packaged with thermal management substrates for vehicular thermal cycling endurance. These systems replace halogen and xenon architectures to reduce energy draw from alternator loads and enable programmable beam patterns for pedestrian detection. Headlights and adaptive technology segments command premium positioning as matrix systems integrate with camera-based traffic sign recognition. Interior lights and standard LED configurations occupy mature volume tiers where cost-per-lumen optimization dominates supplier selection. Electric vehicle applications within the application dimension represent the fastest structural expansion as 800-volt architectures demand low-current illumination to preserve range.
Spain's Directorate General of Industry and Small and Medium-Sized Enterprises enforces EU REACH compliance for LED phosphor materials and RoHS restrictions on hazardous substances in automotive electronics. The country's national type-approval authority aligns with UNECE Regulation 48 for headlamp photometric performance and ECE R128 for LED retrofit modules. Stakeholders must monitor pending EU Green Deal circularity requirements for automotive lighting recyclability and assess whether domestic remanufacturing capabilities can satisfy extended producer responsibility frameworks without disrupting just-in-sequence delivery to Martorell, Zaragoza, and Vigo assembly complexes.
Market Dynamics
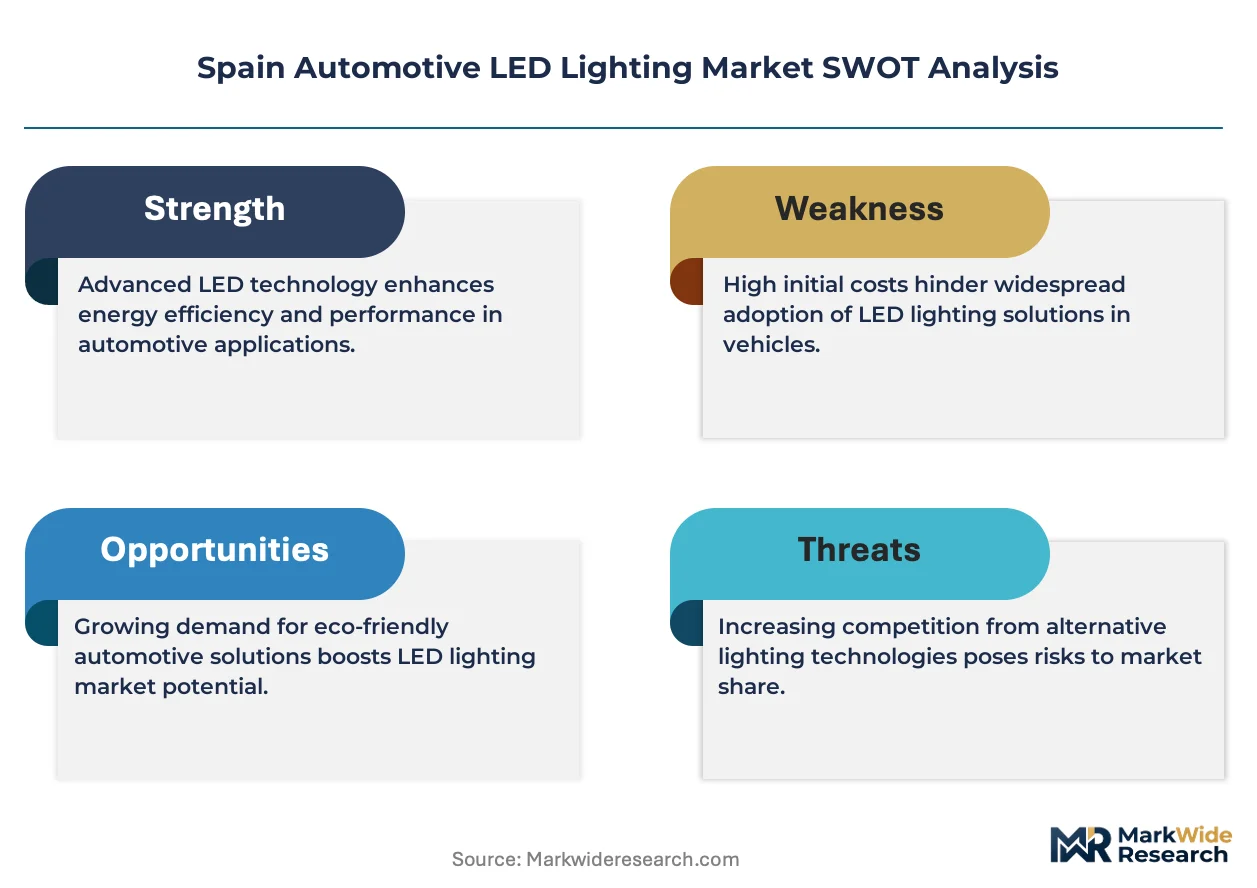
OEM procurement of adaptive headlamp systems for electric vehicle platforms is accelerating across Spanish assembly plants, compressing supplier qualification timelines and favoring localized LED module production over imported alternatives.
Growth Catalysts
- EU Green Deal circularity mandates:Extended producer responsibility frameworks for automotive lighting recyclability are driving domestic remanufacturing investments in Catalonia and the Basque Country.
- 800-volt electric vehicle architectures:Low-current LED illumination preserves battery range, creating specification pull from SEAT and Volkswagen Group assembly lines in Martorell.
- Basque Country automotive cluster concentration:Vitoria-Gasteiz and Bilbao manufacturing corridors generate dense supplier ecosystems that reduce logistics costs for just-in-sequence delivery.
Market Restraints
- Gallium nitride substrate cost volatility:Epitaxial deposition materials for high-efficacy LEDs face price pressure from concentrated Asian supply sources.
- UNECE Regulation 48 compliance friction:Spain's national type-approval authority enforces stringent headlamp photometric performance testing that extends product development cycles.
- Phosphor material substitution risk:Quantum dot emitters threaten conventional LED phosphor architectures in premium adaptive headlamp segments.
Strategic Opportunities
- Andalusia underpenetration:Seville and Málaga automotive corridors lack dense LED supplier presence, creating white space for logistics hub establishment.
- Camera-based traffic sign recognition convergence:Matrix LED systems integrating with ADAS sensor fusion represent emerging specification territory for Tier-1 suppliers.
- RoHS hazardous substance restrictions:ECHA enforcement of electronics substance bans favors Spanish assemblers with established compliance documentation.
Industry Challenges
- Thermal management engineering scarcity:Vehicular thermal cycling endurance design requires specialized semiconductor packaging expertise that outpaces Spanish technical education output.
- ECE R128 retrofit module certification timelines:LED aftermarket approval protocols create working capital strain for smaller Spanish lighting specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Automotive LED Lighting Market |
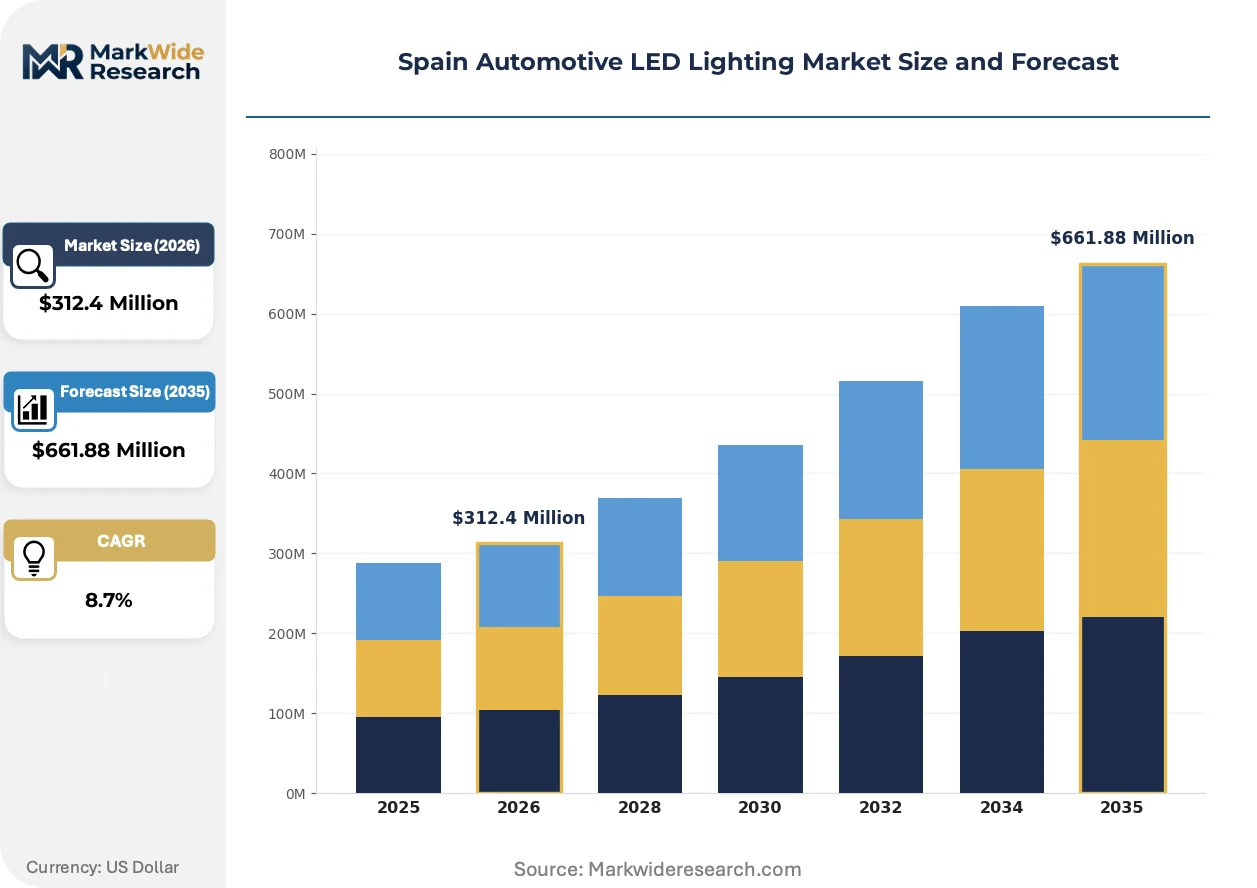
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headlights, Taillights, Interior Lights, Fog Lights Technology: Standard, Adaptive, Matrix, Laser End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Application: Passenger Cars, Commercial Vehicles, Electric Vehicles, Luxury Vehicles |
| Companies Covered | Marelli Holdings Co Ltd, KOITO MANUFACTURING CO LTD, HELLA GmbH & Co KGaA (FORVIA), Valeo SE, Uno Minda Limited, OSRAM GmbH, Stanley Electric Co Ltd, ams OSRAM AG, GRUPO ANTOLIN IRAUSA S A, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Automotive LED Lighting Market Trends and Innovations
Precision LED architectures are displacing conventional illumination across Spanish OEM platforms as regulatory alignment protocols and electric vehicle range preservation create simultaneous specification pressure.
Matrix beam technology is migrating from premium passenger vehicles to mid-range electric platforms. SEAT's Martorell assembly complex specifications now require programmable beam patterns for pedestrian detection across volume-tier nameplates. This migration from luxury segmentation to mass-market deployment compresses supplier margin structures while expanding total addressable module volume.
Spain's General Directorate of Traffic mandates stringent headlamp alignment protocols that favor precision LED architectures over halogen and xenon alternatives. The Directorate's enforcement of UNECE Regulation 48 photometric performance standards creates compliance barriers for non-LED retrofit entrants. Aftermarket distributors in Madrid and Barcelona are consolidating inventory toward certified LED configurations to avoid type-approval rejection rates.
Specification authority is concentrating at OEM platform engineering centers rather than dispersed purchasing departments. Tier-1 suppliers in the Basque Country report direct technical collaboration with Volkswagen Group platform teams on adaptive lighting calibration. This centralization of design-in decisions compresses competitive bidding cycles and rewards engineering-proximate suppliers with preferred supplier status.
Spain Automotive LED Lighting Market Segmentation
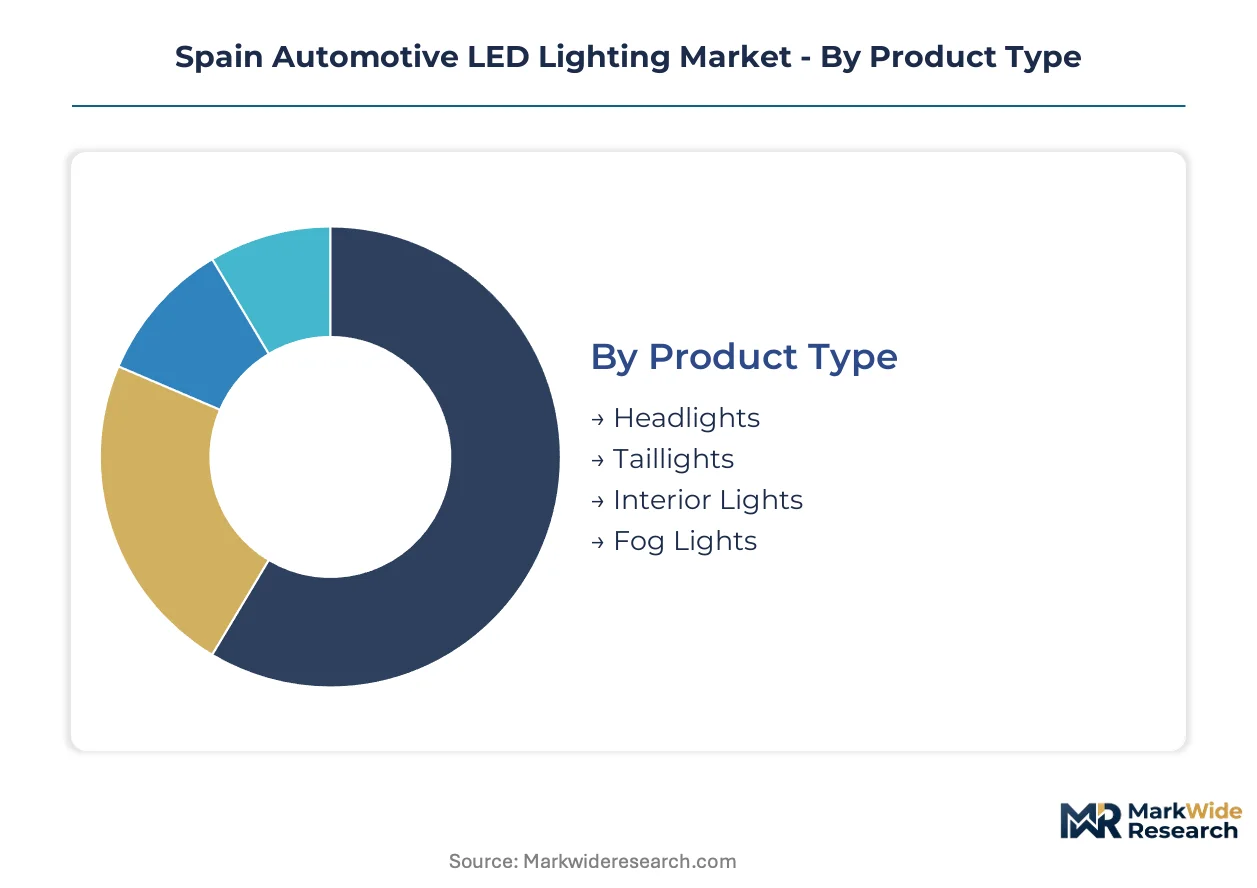
Segmentation reveals how specification authority concentrates in Spain's automotive LED lighting supply base. Tier-1 suppliers calibrate production lines differently for OEM platform engineering versus aftermarket retrofit channels, while electric vehicle architectures impose distinct thermal management requirements across product categories.
Product Type:
After-sales service intensity varies sharply across product categories, with adaptive headlamp systems requiring specialized recalibration equipment that Spanish distributors must maintain.
- Headlights:Matrix LED architectures integrate semiconductor diodes with camera-based pedestrian detection systems. Demand concentrates at SEAT's Martorell assembly complex where Volkswagen Group platform specifications mandate programmable beam patterns for volume-tier nameplates.
- Taillights:Solid-state illumination systems employ gallium nitride epitaxial deposition for luminous efficacy exceeding 100 lumens per watt. Basque Country suppliers near Vitoria-Gasteiz prioritize just-in-sequence delivery to reduce logistics friction for OEM procurement teams.
- Interior Lights:Mature volume tier where cost-per-lumen optimization dominates supplier selection criteria.
- Fog Lights:Standard LED configurations serving secondary illumination roles with lower thermal cycling endurance requirements.
By volume, Interior Lights leads. By growth pace, Headlights is ahead.
Technology:
Cost tier stratification separates premium adaptive systems from standard configurations, with matrix technology commanding engineering-proximate supplier relationships.
- Adaptive:Dynamic beam adjustment systems respond to traffic sign recognition inputs through ADAS sensor fusion. Spanish Tier-1 suppliers in Bilbao manufacturing corridors report direct technical collaboration with Volkswagen Group platform teams on calibration protocols.
- Matrix:Programmable LED arrays enable selective dimming of individual diodes to avoid oncoming glare. The General Directorate of Traffic's stringent headlamp alignment protocols favor these precision architectures over conventional alternatives.
- Standard:Conventional LED configurations occupying mature market tiers with compressed margin structures.
- Laser:Emerging high-luminance technology facing UNECE Regulation 48 photometric performance compliance friction.
By revenue concentration, Adaptive dominates. By specification momentum, Matrix is expanding most quickly.
End User:
Customer type determines procurement pattern complexity, with OEMs centralizing design-in decisions at platform engineering centers.
- OEMs:Volkswagen Group and SEAT procurement teams compress supplier qualification timelines for electric vehicle platform launches at Martorell, Zaragoza, and Vigo assembly complexes.
- Tier-1 Suppliers:Basque Country engineering partnerships with Marelli Holdings and FORVIA sustain adaptive lighting calibration capabilities.
- Vehicle Assemblers:Final assembly operations dependent on just-in-sequence LED module delivery from localized production.
- Aftermarket Providers:Madrid and Barcelona distributors consolidating inventory toward ECE R128 certified configurations to avoid type-approval rejection rates.
By contract value, OEMs lead. By localization pressure, Tier-1 Suppliers face the steepest capacity expansion requirements.
Application:
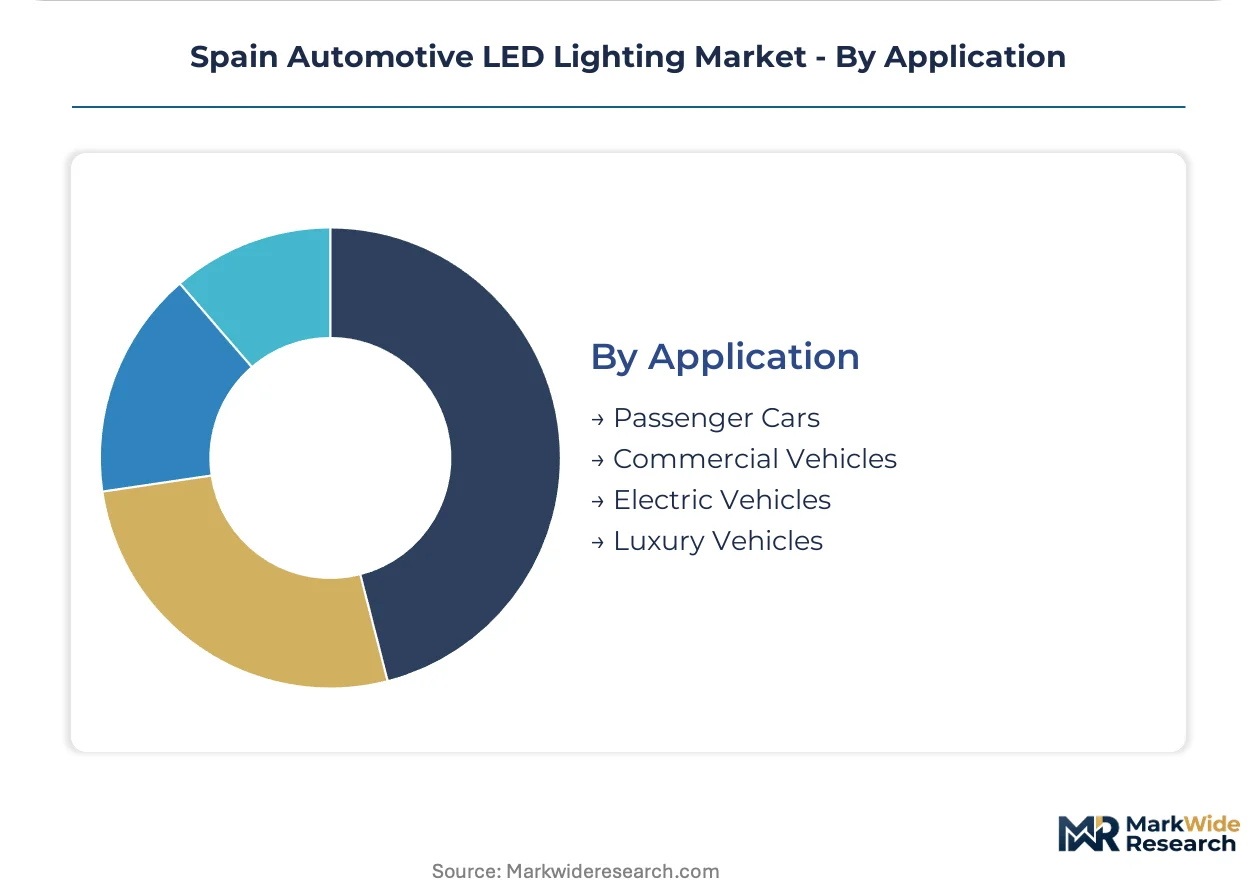
Application maturity separates established passenger car volumes from emerging electric vehicle specifications demanding low-current illumination.
- Electric Vehicles:800-volt architectures require reduced alternator load draw to preserve battery range. SEAT specifications at Martorell now mandate LED illumination across all volume-tier electric nameplates.
- Passenger Cars:Mid-range platforms migrating from halogen to LED configurations under EU Green Deal circularity mandates for automotive lighting recyclability.
- Commercial Vehicles:Fleet operators prioritizing durability metrics and thermal management endurance for heavy-duty cycling.
- Luxury Vehicles:Premium segmentation where matrix beam technology originated before migrating to mass-market deployment.
By installed base, Passenger Cars leads. By specification pull, Electric Vehicles is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Spain's automotive LED lighting market diverge sharply by sub-region, with northern industrial corridors prioritizing OEM-integrated adaptive systems while southern markets concentrate on aftermarket retrofit volumes and compliance-driven standard configurations.
Catalonia
Martorell's Volkswagen Group assembly complex drives specification authority for matrix LED architectures across SEAT's electric vehicle platforms. The region's Generalitat enforces EU REACH compliance for phosphor materials through its Catalan Waste Agency oversight. Barcelona logistics hubs coordinate just-in-sequence delivery to coastal OEM plants while Girona suppliers expand thermal management substrate fabrication.
Basque Country
Vitoria-Gasteiz and Bilbao manufacturing corridors generate Europe's densest automotive supplier ecosystem for adaptive headlamp calibration. ECHA's RoHS enforcement through Spanish customs channels favors established assemblers with documented hazardous substance compliance. Local engineering partnerships with FORVIA and Marelli sustain precision LED architecture production for 800-volt electric vehicle specifications.
Madrid
The capital region concentrates aftermarket distribution networks serving central Iberian retrofit demand. Spain's General Directorate of Traffic maintains its national type-approval authority headquarters here, administering UNECE Regulation 48 photometric testing protocols. Madrid distributors consolidate inventory toward ECE R128 certified configurations to minimize rejection rates at alignment inspection stations.
Andalusia
Seville and Málaga automotive corridors remain underpenetrated by LED supplier presence relative to northern industrial density. The Junta de Andalucía's regional competitiveness programs incentivize logistics hub establishment for Mediterranean OEM networks. Cádiz port infrastructure offers alternative entry points for gallium nitride substrate imports facing Asian supply volatility.
Valencia
Ford's Almussafes assembly operations and growing electric vehicle component investments reshape local procurement patterns. The region's port authority facilitates Iberian distribution for Asian LED module suppliers seeking European market access. Castellón's ceramics industry provides adjacent thermal management substrate fabrication capabilities for automotive semiconductor packaging.
Spain Automotive LED Lighting Market Competitive Landscape
Capability concentration sits with Tier-1 engineering-proximate suppliers; scale advantage sits with diversified multinational electronics conglomerates. The market structures around three archetypes: integrated automotive lighting specialists with platform engineering relationships, diversified semiconductor manufacturers leveraging cross-sector LED expertise, and regional assembly specialists serving just-in-sequence logistics requirements. Competitive dynamics center on M&A activity consolidating adaptive calibration capabilities and capacity expansion targeting 800-volt electric vehicle platform launches.
Among the named players, Marelli Holdings Co Ltd and HELLA GmbH & Co KGaA (FORVIA) exemplify the engineering-proximate Tier-1 archetype through their Martorell-adjacent and Basque Country operations. KOITO MANUFACTURING CO LTD represents the Asian-anchored multinational model, leveraging Iberian logistics hubs for Mediterranean market access. These three occupy positions spanning the capability-scale spectrum without dominating any single segment exclusively.
| Leading Market Players |
|---|
| Marelli Holdings Co Ltd |
| KOITO MANUFACTURING CO LTD |
| HELLA GmbH & Co KGaA (FORVIA) |
| Valeo SE |
| Uno Minda Limited |
| OSRAM GmbH |
| Stanley Electric Co Ltd |
| ams OSRAM AG |
| GRUPO ANTOLIN IRAUSA S A |
| Others |
Pricing and Supply Chain Analysis
Gallium nitride substrate cost volatility from concentrated Asian supply sources compresses margin structures across both premium adaptive systems and standard LED configurations while simultaneously forcing procurement teams toward multi-source qualification timelines that reshape inventory holding patterns. This input-cost uncertainty propagates through tiered pricing spreads that separate matrix-equipped platforms from economy-tier retrofits.
Pricing Analysis
Basque Country suppliers command 15-25% premia over Madrid aftermarket distributors for equivalent lumen-output modules due to just-in-sequence logistics integration with Martorell assembly lines. Pricing stratifies across premium adaptive-matrix tiers, mid-range standard LED configurations, and economy retrofit segments based on thermal management substrate quality and UNECE Regulation 48 certification status. Cost compression in standard interior lighting is intensifying because SEAT procurement teams are consolidating supplier panels for volume-tier electric nameplates. Tier-1 engineering partnerships show least price sensitivity; aftermarket distributors in Barcelona and Madrid exhibit highest sensitivity to ECE R128 certification cost pass-through.
Supply Chain Analysis
Epitaxial gallium nitride deposition draws from Taiwanese and South Korean wafer fabrication capacity, with sapphire substrate finishing concentrated in China and Japan. Spanish LED module assemblers source phosphor materials from Chinese chemical processors and thermal management substrates from German ceramics specialists. Single-source vulnerability sits with gallium nitride epitaxy equipment where two Asian vendors dominate global installation base. Distribution runs through Barcelona and Valencia port complexes for Iberian OEM networks, with Basque Country corridors maintaining direct pipeline feeds to Vitoria-Gasteiz and Bilbao manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision semiconductor packaging expertise for vehicular thermal cycling endurance represents the critical capability gap constraining Spanish supplier expansion, with technical education output lagging platform engineering demand from Volkswagen Group and SEAT procurement teams.
For Market Incumbents: Entrench adaptive calibration capabilities through captive engineering partnerships with Basque Country technical universities while consolidating phosphor material supply contracts ahead of EU Green Deal circularity mandate enforcement. Quantum dot emitter substitution in premium headlamp segments threatens conventional LED architectures; backward integration into thermal management substrate fabrication preserves margin control against gallium nitride cost volatility. For New Entrants and Emerging Players: Andalusia's underpenetrated Seville and Málaga corridors offer white-space logistics hub establishment with Junta de Andalucía competitiveness program support. Target aftermarket retrofit certification services where ECE R128 approval timelines create working capital strain for smaller Madrid and Barcelona distributors. Camera-based traffic sign recognition integration with matrix LED systems represents the most penetrable specification territory for engineering-proximate entrants lacking incumbent platform relationships. For Investors and Strategic Acquirers: The market sits at a supplier consolidation phase that favors adaptive calibration capability acquisition over greenfield capacity builds. Long-term viability across the projection horizon rests on 800-volt electric vehicle platform content-per-vehicle expansion rather than legacy passenger car retrofit replacement cycles. Acquisition target archetype: Tier-1 suppliers with documented UNECE Regulation 48 compliance portfolios and established just-in-sequence relationships with Martorell or Vitoria-Gasteiz assembly complexes. Monitor SEAT electric nameplate launch cadence as the inflection signal for capacity utilization rates across Basque Country supplier ecosystems.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Calibration Capability Acquisition | Consolidates engineering-proximate supplier status with Volkswagen Group platform teams. |
| Phosphor Material Supply Contracting | Secures feedstock continuity ahead of ECHA REACH enforcement on hazardous substance restrictions. |
| Thermal Management Substrate Fabrication | Captures margin pool from gallium nitride epitaxy cost volatility through backward integration. |
| Andalusia Logistics Hub Establishment | Reduces delivery friction for Mediterranean OEM networks outside Basque Country density. |
| Camera-ADAS Integration Development | Positions for matrix LED specification pull from traffic sign recognition convergence trends. |
Research Methodology
A standing panel of OEM platform engineers, Tier-1 supplier procurement directors, aftermarket distributor operations managers, and thermal management substrate fabricators provided ongoing calibration across the study period. Primary interview data combined with secondary validation from UNECE Regulation 48 type-approval documentation, Spanish Directorate General of Traffic enforcement records, IHS Markit vehicle production databases, and EU REACH compliance filings. Bottom-up module shipment estimates triangulated against top-down electric vehicle platform content assumptions.
Scenario-bracketing around gallium nitride substrate cost trajectories and EU Green Deal circularity implementation timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product category, technology tier, end-user channel, and propulsion architecture. CAGRs derived from slope-intercept calibration against historical platform launch cadences and electric vehicle adoption curves. Forecast inputs incorporated 800-volt architecture penetration rates and adaptive headlamp specification pull from pedestrian detection regulatory pressure.
Practitioners should monitor gallium nitride epitaxy equipment lead time extensions and ECHA enforcement intensity on RoHS hazardous substance restrictions for early signals of supply constraint or compliance cost pass-through. Forecasts reflect assumptions on SEAT electric nameplate volume ramps and Basque Country supplier ecosystem capacity expansion schedules. Cross-checking against IHS Markit European vehicle registration data and Spanish automotive production statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Germany Smart Home Market
Others
Dry-Cleaning and Laundry Services Market
Others
Military Wearable Market
Others
Caster Wheels Market
Others
AI In Government And Public Services Market
Others
Liquid-Cooled Heat Sink Market
Others
Transportation Lighting Market
Others
Magnetic Stripe Readers Market
Others
Embedded Computer Market
Others
Profilometer Market
Others
Nanomedicine for Drug Delivery Market
Others
Asia Pacific Video Conferencing Hardware Market
Others
Latin America Video Conferencing Hardware Market
Others
Cloud-Based Streaming Services Market
Others
Europe Tablet PC Market
Others
Football Sportswear Market