
 Global Mobile Gambling Market | 2026-2036
Global Mobile Gambling Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Gambling Market Outlook
Bundled wagering packages that combine sports betting, casino access, and live dealer streams into single-app subscriptions is expanding consumer stickiness across operator platforms. Flutter Entertainment leverages its portfolio breadth to anchor cross-selling opportunities between sportsbook and casino verticals. DraftKings competes through daily fantasy sports integration that funnels users into broader gambling products. Entain plc sustains geographic diversification across regulated European, Latin American, and US state markets.
Mobile gambling denotes wagering activities conducted through handheld devices using native applications or browser-based platforms, typically requiring real-time data encryption, geolocation verification, and payment gateway integration to ensure transactional integrity and regulatory compliance. The primary commercial purpose centers on converting leisure time into monetized betting engagement through frictionless user interfaces and personalized promotional algorithms. Sports Betting commands the largest revenue pool among game type segments, while Live Casino represents the fastest-growing category as streaming latency improvements enable real-time dealer interaction. iOS platforms capture premium user segments with higher average deposit values, whereas Android dominates total install volume across price-sensitive demographics in Asia and Latin America.
The UK Gambling Commission, state-level gaming regulators across the United States, and Brazil's national lottery operator Secretaria de Prêmios e Apostas collectively determine market access through licensing density, advertising restrictions, and responsible gambling mandate enforcement. GDPR in Europe and emerging data localization requirements in India further constrain how operators manage customer identity verification and behavioral analytics. Stakeholders must monitor regulatory divergence between permissive licensing regimes and tightening advertising prohibitions when allocating capital across geographic expansion targets.
Market Dynamics
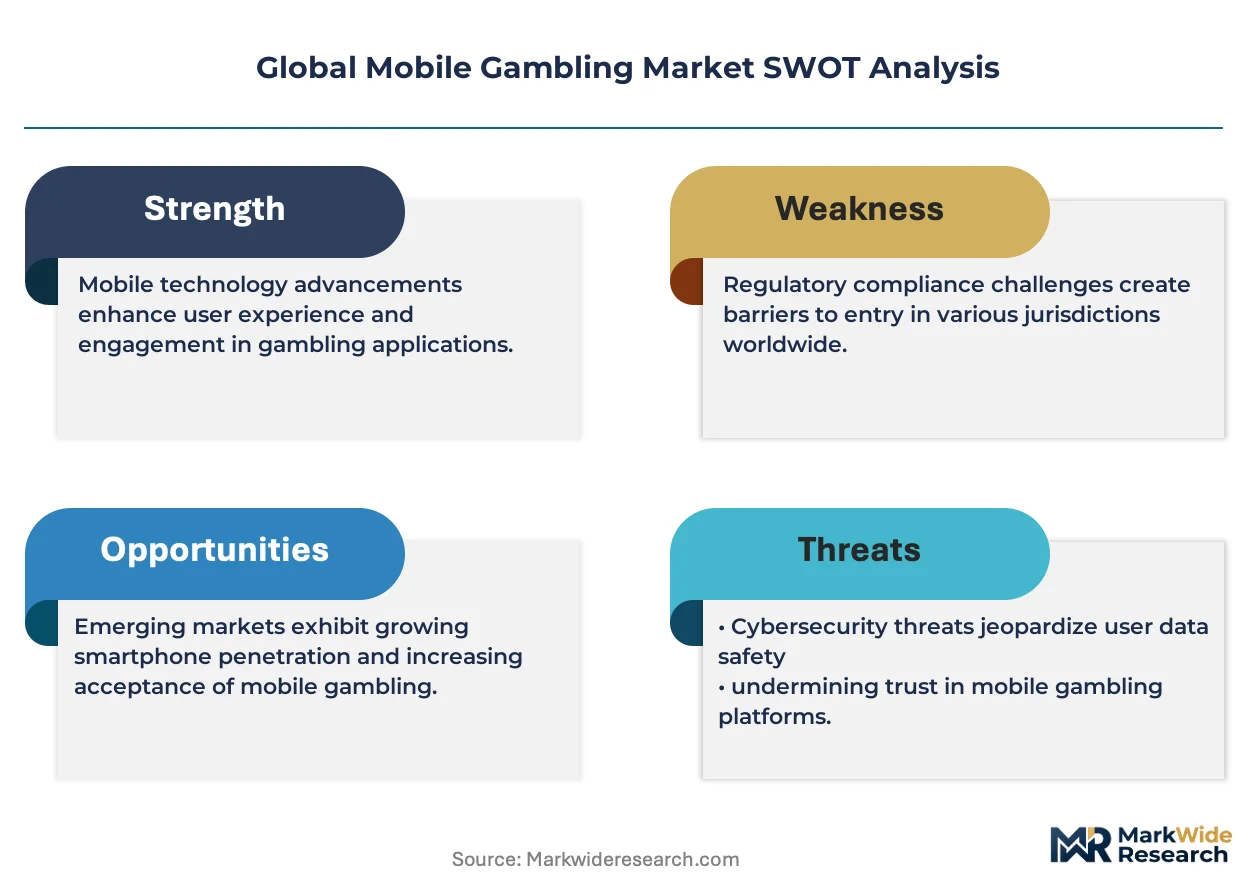
Regulatory fragmentation between permissive licensing regimes and tightening advertising prohibitions is forcing operators to architect multi-jurisdictional compliance stacks, diverting capital from product development toward legal infrastructure and geolocation verification systems.
Growth Catalysts
- Brazil's Secretaria de Prêmios e Apostas liberalization:Federal sports betting framework enacted in 2023 permits international operators to secure domestic licenses, unlocking Latin America's largest addressable population of mobile-first users.
- 5G network latency reduction:Sub-20 millisecond streaming speeds enable real-time live dealer casino experiences previously constrained by buffering interruptions, expanding addressable wallet share from casual bettors to high-frequency table game players.
- India's UPI payment rail integration:Unified Payments Interface protocols allow instant rupee-denominated deposits without credit card intermediaries, reducing customer acquisition friction in a previously cash-dominated wagering culture.
Market Restraints
- GDPR-KYC data localization conflict:European privacy mandates restrict cross-border transfer of biometric verification data, forcing redundant identity infrastructure builds in each member state and inflating per-user compliance costs.
- Apple App Store commission structure:30% in-app purchase fees on iOS gambling transactions compress net gaming revenue margins, incentivizing operators to push users toward direct browser-based deposits with inferior retention metrics.
- Android device fragmentation:Thousands of unpatched OS versions across Southeast Asian markets create security vulnerability surfaces that fraud detection systems must address through expensive device fingerprinting layers.
Strategic Opportunities
- United Arab Emirates tourism corridor:Ras Al Khaimah's emerging integrated resort licensing creates first-mover positioning for luxury-focused mobile platforms targeting high-net-worth visitors from restrictive neighboring jurisdictions.
- Artificial reality convergence:AR headset wagering overlays on live sporting events merge physical stadium attendance with real-time proposition betting, opening experiential gambling formats unattainable through flat-screen interfaces.
- Affiliate-to-operator vertical integration:Direct acquisition of content publishers and tipster platforms reduces customer acquisition cost dependence on opaque programmatic advertising networks subject to regulatory blacklists.
Industry Challenges
- Responsible gambling algorithmic auditing:Regulators in the United Kingdom and Netherlands mandate explainable AI for behavioral intervention triggers, requiring data science teams to reconstruct black-box machine learning models for compliance documentation.
- Multi-state tax engine complexity:United States operators must calculate withholding obligations across 30-plus jurisdictions with divergent treatment of promotional credits, parlay outcomes, and non-resident winnings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Gambling Market |
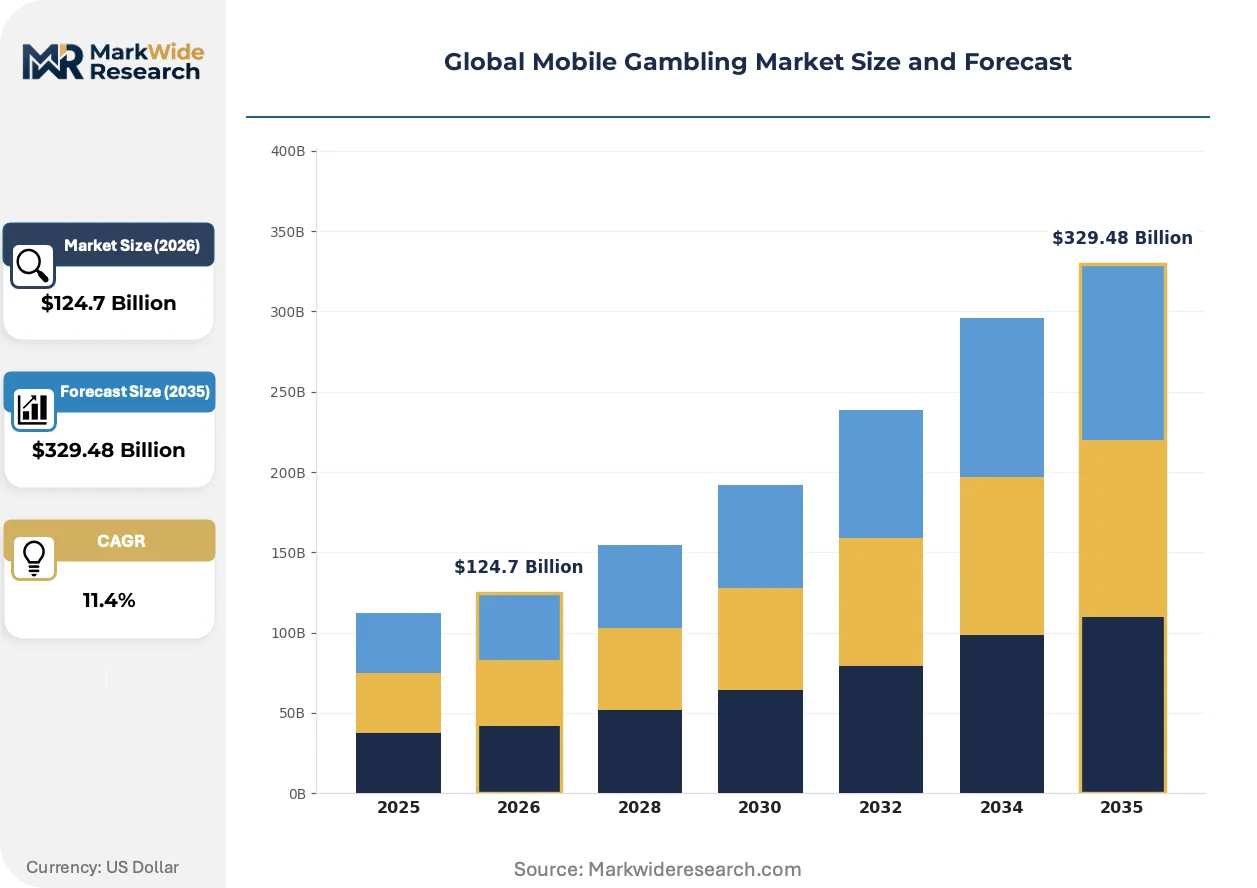
| Market Size in 2026 | $124.7 Billion |
| Market Size in 2035 | $329.48 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform: iOS, Android, Windows, Others Game Type: Slots, Poker, Sports Betting, Live Casino End User: Casual Gamers, High Rollers, Regular Players, New Users Monetization Model: Freemium, Subscription, Pay-to-Play, Ad-Supported |
| Companies Covered | Flutter Entertainment, Entain plc, Bet365 Group Ltd, DraftKings Inc., Betsson AB, 888 Holdings plc, Playtech plc, MGM Resorts International, Caesars Entertainment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Gambling Market Strategic Shifts
Streaming infrastructure investments and wallet architecture unification are compressing the gap between sportsbook and casino product silos, enabling single-session cross-vertical engagement that extends lifetime value metrics.
Edge computing nodes deployed within cellular carrier networks are expanding into sub-second wager settlement for in-play sports markets. Tier-one operators in the United Kingdom and Australia have adopted these distributed processing architectures to circumvent latency bottlenecks from centralized cloud data centers. The technology is expanding into micro-betting formats on individual pitch outcomes and player performance metrics previously excluded from real-time pricing.
GDPR's Article 22 restrictions on automated decision-making have triggered manual review workflows for high-velocity deposit limit adjustments and account suspension triggers. European operators now maintain dedicated responsible gambling adjudication teams that override algorithmic recommendations, adding 15-20% to operational headcount. The regulatory shift most affects VIP retention programs that previously relied on predictive churn models for personalized reinvestment offers.
Bettor acquisition through social media influencer partnerships is displacing traditional television advertising in jurisdictions with strict wagering commercial prohibitions. Short-form video platforms host tipster personalities who embed affiliate tracking links within ostensibly educational content, funneling followers toward operator registrations. This channel migration concentrates marketing spend in Brazil, Nigeria, and India where platform moderation of gambling content remains inconsistent.
Global Mobile Gambling Market Segmentation
Mobile gambling operators architect platform-specific compliance stacks and game-type monetization strategies to capture divergent user cohorts. Segmentation discipline separates high-frequency sports bettors from casual casino players, enabling targeted retention algorithms and jurisdiction-appropriate product bundling.
Platform:
iOS commands premium deposit values through affluent user bases, while Android dominates install volume across emerging markets where device price sensitivity shapes acquisition economics.
- iOS:Apple's closed ecosystem enforces stricter gambling app review protocols, filtering out non-compliant operators and concentrating revenue among licensed tier-one platforms. Deposit averages run higher in the United Kingdom, Japan, and Australia where discretionary income supports premium wagering behavior. Geolocation verification integrates natively with Core Location frameworks, reducing compliance infrastructure costs for operators.
- Android:Fragmented OS distribution across Southeast Asian and Latin American markets demands extensive device fingerprinting for fraud prevention. Google's Play Store gambling policies vary by country, forcing sideloading distribution in jurisdictions without official storefront approval. Lower customer acquisition costs in Brazil and India offset higher support burdens from diverse hardware configurations.
- Windows:Negligible mobile market share relegates this platform to legacy desktop migration paths for established European operators.
- Others:Proprietary OS environments in China and specialized gaming devices capture niche segments outside mainstream Western distribution channels.
Mature deployment sits with iOS. Newer deployment is concentrated in Android.
Game Type:
Revenue concentration follows engagement frequency, with real-time sports markets and immersive live dealer formats commanding disproportionate operator investment.
- Sports Betting:In-play wagering on football, cricket, and basketball drives session frequency through micro-betting on individual events. Edge computing nodes within cellular networks now support sub-second settlement latency previously unattainable through centralized cloud architecture. Demand concentrates in the United Kingdom, Australia, and Brazil where sporting culture intersects with permissive regulatory frameworks.
- Live Casino:Real-time dealer streaming via 5G networks has eliminated buffering interruptions that previously constrained table game migration from physical venues. Studio infrastructure investments cluster in Latvia, the Philippines, and Georgia where labor costs and regulatory permissiveness support 24/7 multilingual operations. This vertical is climbing the fastest as streaming technology matures.
- Slots:Algorithmic random number generation and progressive jackpot mechanics sustain casual player retention through variable reward scheduling optimized for mobile session lengths.
- Poker:Skill-based tournament formats attract dedicated player pools with higher lifetime value but require substantial liquidity depth to maintain game integrity.
Established revenue bases anchor Sports Betting. Technology-driven expansion is reshaping Live Casino.
End User:
Behavioral segmentation separates monetization strategies between high-volume low-margin casual acquisition and concentrated VIP relationship management.
- High Rollers:Dedicated account managers and personalized reinvestment offers sustain deposit volumes that subsidize broader customer acquisition economics. GDPR Article 22 restrictions on automated decision-making now mandate manual adjudication for deposit limit adjustments, inflating operational headcount for VIP programs. Concentration is heaviest in the United Arab Emirates, Singapore, and Monaco where tourism corridors funnel affluent visitors.
- Regular Players:Predictable weekly wagering patterns enable algorithmic churn prediction and targeted promotional interventions through push notification ecosystems. Cross-vertical engagement between sportsbook and casino products extends session duration metrics in mature European markets.
- Casual Gamers:Freemium-to-paid conversion funnels and social casino mechanics lower barrier-to-entry for price-sensitive demographics in India and Nigeria.
- New Users:Onboarding flows emphasize identity verification speed and first-deposit bonus clarity to minimize abandonment at KYC friction points.
Profitability concentrates with High Rollers. Volume expansion is accelerating among Casual Gamers.
Monetization Model:
Payment rail integration and regulatory advertising restrictions are displacing traditional subscription approaches toward transaction-based revenue capture.
- Pay-to-Play:Direct real-money wagering remains the dominant revenue architecture, with India's UPI integration and Brazil's Pix instant payment protocols reducing deposit friction previously imposed by credit card intermediaries. Tax engine complexity across United States state jurisdictions forces operators to maintain separate withholding calculation stacks.
- Freemium:Virtual currency accumulation with optional real-money unlocks navigates advertising prohibition jurisdictions where direct gambling promotion faces regulatory blacklists. Social casino mechanics sustain engagement in markets awaiting formal licensing liberalization.
- Subscription:Bundled access packages combining multiple verticals attract price-sensitive users in saturated European markets with established regulatory clarity.
- Ad-Supported:Programmatic inventory monetization captures non-paying user attention in emerging markets where payment infrastructure remains underdeveloped.
Established revenue architecture centers on Pay-to-Play. Regulatory adaptation is expanding Freemium deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ras Al Khaimah's integrated resort licensing zone is funneling capital toward luxury-focused mobile platforms targeting high-net-worth visitors from restrictive neighboring jurisdictions. The United Arab Emirates, Brazil, and India's regulatory openings are redrawing licensing density maps. Established European markets face tightening advertising prohibitions that compress acquisition economics.
United States
State-by-state licensing expansion and tribal gaming compacts are fragmenting market access across 30-plus jurisdictions. The Department of Justice's Wire Act interpretations and individual state gaming boards determine operational permissions. New Jersey's Atlantic City corridor and Nevada's Las Vegas cluster anchor platform development centers for multi-state tax engine architectures.
Brazil
Secretaria de Prêmios e Apostas federal sports betting liberalization unlocks Latin America's largest mobile-first user population. Pix instant payment protocol integration eliminates credit card friction for real-money deposits. São Paulo's fintech corridor hosts operator localization teams adapting KYC workflows to Portuguese-language verification standards.
United Kingdom
Gambling Commission mandates on responsible gambling algorithmic auditing and advertising restrictions are elevating compliance infrastructure costs. GDPR Article 22 restrictions on automated decision-making force manual adjudication workflows for VIP programs. London's regulatory technology cluster supplies geolocation verification and behavioral analytics services to tier-one operators.
India
UPI payment rail integration enables instant rupee-denominated deposits without intermediary friction. State-level gambling law divergence between Sikkim, Nagaland, and Maharashtra creates jurisdictional arbitrage opportunities. Bangalore's technology parks host platform development teams optimizing Android fragmentation across thousands of unpatched device versions.
United Arab Emirates
Ras Al Khaimah's emerging integrated resort licensing creates first-mover positioning for luxury-focused mobile platforms. Federal-level restrictions in Dubai and Abu Dhabi funnel affluent visitors toward permissive northern emirate corridors. Dubai's hospitality technology cluster supplies multilingual customer acquisition infrastructure targeting tourism-driven wagering.
Global Mobile Gambling Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across licensing-heavy jurisdictions where regulatory compliance stacks determine market access. Tier-one operators maintain multi-jurisdictional legal infrastructure while mid-tier platforms concentrate on single-market dominance. Three archetypes dominate: horizontally integrated entertainment conglomerates, sportsbook-native platforms with casino cross-sell capabilities, and technology suppliers licensing platform infrastructure. M&A activity concentrates on affiliate-to-operator vertical integration and geographic license portfolio expansion.
Within the diversified entertainment conglomerate tier, Flutter Entertainment and MGM Resorts International exemplify portfolio breadth strategies spanning sportsbook, casino, and hospitality verticals. DraftKings Inc. occupies a position as a sportsbook-native platform with daily fantasy sports integration capabilities. These three entities represent contrasting approaches to customer acquisition economics and cross-vertical retention architecture.
| Leading Market Players |
|---|
| Flutter Entertainment |
| Entain plc |
| Bet365 Group Ltd |
| DraftKings Inc. |
| Betsson AB |
| 888 Holdings plc |
| Playtech plc |
| MGM Resorts International |
| Caesars Entertainment |
| Others |
Value Chain & Pricing Dynamics
Platform certification divergence between iOS App Store compliance and Android sideloading distribution creates tiered infrastructure cost structures that propagate through operator margin profiles and vendor selection priorities. Premium-tier operators absorbing Apple's 30% commission burden maintain pricing power through affluent user bases, while economy-tier platforms distributing via direct APK downloads compete on deposit minimums and promotional intensity.
Pricing Analysis
Short lead-time deployment premiums dominate operator procurement decisions, with certified iOS compliance stacks commanding substantial uplifts over browser-based alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects geolocation verification sophistication, payment rail integration depth, and responsible gambling algorithmic audit readiness. Cost compression in economy-tier white-label platforms is intensifying because Android fragmentation demands expensive device fingerprinting layers. Casual gamers in Southeast Asia exhibit highest price sensitivity, while VIP programs in the United Arab Emirates show minimal elasticity to deposit threshold adjustments.
Supply Chain Analysis
UK Gambling Commission certification and state-level US gaming board approvals function as primary gating mechanisms for platform technology vendors. Geographic concentration clusters in the United Kingdom, Malta, and Gibraltar where regulatory technology clusters feed compliance infrastructure to tier-one operators. Raw material dependencies center on streaming bandwidth contracts, payment processor APIs, and geolocation verification services. Single-source vulnerability runs through Apple's App Store review protocols, which can suspend distribution without recourse. Distribution runs through direct operator procurement of modular compliance stacks rather than integrated platform licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around regulatory compliance scale, with GDPR-KYC data localization conflicts and multi-jurisdictional tax engine complexity forcing sub-scale operators toward exit or acquisition.
For Market Incumbents: Hedge against Apple App Store commission compression by accelerating browser-based platform development with native-app-equivalent retention mechanics. Deepen upstream control over affiliate content publishers to reduce dependence on programmatic advertising networks facing regulatory blacklists in Brazil and Nigeria. Prioritize certification investment in emerging UAE integrated resort licensing before competitor platform saturation.
For New Entrants and Emerging Players: The mid-market pricing gap between premium iOS-native platforms and economy Android sideloading offers white-space positioning for hybrid deployment models. Target India's UPI-integrated market segment where payment infrastructure maturation outpaces formal licensing clarity, enabling freemium-to-paid conversion funnels. Pursue tipster platform acquisition as primary go-to-market angle to circumvent television advertising prohibitions.
For Investors and Strategic Acquirers: Re-rating potential sits with sportsbook-native platforms with proven casino cross-sell capabilities given live casino vertical expansion and 5G latency reduction enabling real-time dealer streaming. Long-term viability favors operators with multi-jurisdictional license portfolios spanning at least three regulatory clusters. Watch Brazil's Secretaria de Prêmios e Apostas enforcement consistency as inflection indicator for Latin American market access premiumization.
| Strategic Initiative | Industry Significance |
|---|---|
| Affiliate-to-Operator Vertical Integration | Direct acquisition of tipster platforms reduces customer acquisition cost dependence in advertising-restricted jurisdictions. |
| Edge Computing Node Deployment | Sub-second wager settlement via cellular carrier network integration enables micro-betting formats previously excluded from real-time pricing. |
| Multi-Jurisdictional Tax Engine Buildout | United States state-level withholding calculation stacks determine operational economics across 30-plus divergent regulatory frameworks. |
| AR Headset Wagering Platform Development | Stadium attendance overlay technology merges physical event presence with real-time proposition betting engagement. |
| Responsible Gambling Algorithmic Audit Investment | GDPR Article 22 compliance for explainable AI behavioral intervention triggers mandates dedicated adjudication team infrastructure. |
Study Parameters
Document review covered UK Gambling Commission enforcement actions, state gaming board licensing databases, and SEC operator filings, complemented by interviews with platform technology executives, regulatory compliance officers, payment processor product leads, and affiliate network operators. Secondary validation drew from App Store review guideline archives, GDPR adjudication records, and telecommunications infrastructure deployment disclosures. Bottom-up segmentation modeling and top-down market sizing triangulated volume estimates across platform, game type, and monetization model dimensions.
Cross-referencing historical operator revenue disclosures against panel input from compliance technology vendors established baseline growth trajectories across the projection horizon. Segmentation dimensions modeled include platform ecosystem, game type vertical, end user behavioral cohort, and monetization model architecture. CAGRs were derived from fitted trend analysis incorporating 5G network rollout timelines, regulatory liberalization schedules, and payment rail integration milestones. Forecast inputs incorporated UPI transaction volume growth in India and Pix adoption curves in Brazil.
Underlying measurement precision varies by segment; established European markets with mature regulatory reporting carry tighter precision than emerging jurisdictions with informal market estimation. Forecasts reflect assumptions regarding enforcement consistency, technology deployment timelines, and competitive entry patterns. A model refresh is warranted upon material change in federal sports betting framework adoption across Latin America or Apple App Store commission structure revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Fiber to the X (Fttx) Tester Market
Others
South Korea Smart Home Market
Others
Fenoxanil Market
Others
Dried Fruit Extracts Market
Others
United States Air Furnaces Market
Others
Europe Postal Services Market
Others
Bicycle Panniers Market
Others
Aircraft Lighting Market
Others
Healthcare Bioconvergence Market
Others
Digital Signage Media Player Market
Others
Asia Pacific Video Conferencing Hardware Market
Others
Solar Animal Repeller Market
Others
Global Bio-Based Chemicals Market
Others
Smart Home Solutions Market
Others
Shear Testing Equipment Market
Others
Global Automotive LED Lighting Market