
 Financial Services Application Market | 2026-2036
Financial Services Application Market Size, Share, and Industry Trends Forecast 2026-2036
Financial Services Application Market Analysis
Subscription-based project finance and asset-light SaaS licensing is reshaping competitive entry in financial services software, lowering capital barriers for fintech challengers and mid-tier vendors. Microsoft Corporation leverages its Azure cloud infrastructure to anchor enterprise banking deployments across North America and Europe. Fiserv, Inc. specializes in payment processing integration, competing through dense correspondent banking relationships. Temenos AG dominates core banking modernization in emerging markets, sustaining growth via modular deployment options.
Financial services applications constitute software systems engineered for transaction processing, risk calculation, regulatory reporting, and customer interface management, typically built on distributed architectures with sub-second latency requirements and AES-256 encryption standards. These platforms serve commercial and institutional users by automating clearing, settlement, lending workflows, and compliance verification. Payment Processing Solutions leads product type revenue due to persistent merchant acquiring volume and real-time rail expansion, while Fraud Detection Systems represents the fastest-growing category as behavioral biometrics and machine learning models displace rule-based engines. Cloud-based installation modes capture expanding share as retail banks and credit unions exit datacenter ownership, though hybrid solutions retain dominance among investment firms with latency-sensitive trading operations.
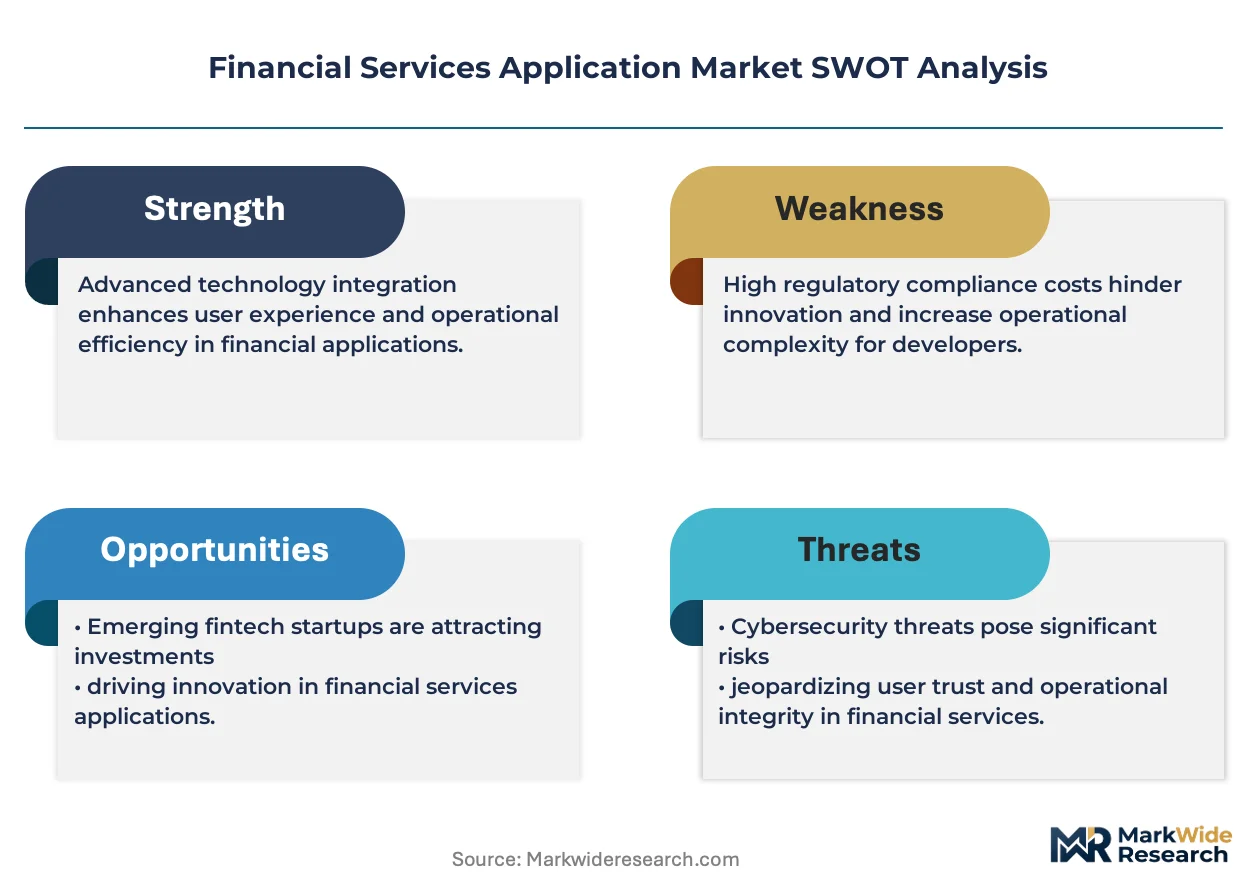
The SEC, EU AI Act, and RBI impose divergent compliance architectures that fragment product development roadmaps and inflate certification costs for cross-border vendors. Basel III operational risk frameworks and PCI-DSS standards further dictate encryption, access control, and audit trail specifications that software must embed natively. Stakeholders must monitor how divergent national AI governance regimes fragment platform standardization and force region-specific engineering bets.
Market Dynamics
Cloud-native core banking platforms are compressing deployment timelines from years to months, forcing incumbent vendors to modularize architectures or cede ground to API-first challengers. This infrastructure shift rewrites procurement criteria, risk assessment frameworks, and long-term vendor relationships across retail and institutional banking.
Growth Catalysts
- Real-time payment rails:FedNow in the United States and SEPA Instant across the European Union mandate sub-second settlement infrastructure, driving wholesale replacement of batch-processing legacy systems.
- EU AI Act compliance deadlines:Banks operating across member states must embed audit-ready algorithmic decision trails by 2025, accelerating procurement of explainable ML platforms for credit underwriting and fraud detection.
- Behavioral biometrics adoption:Device fingerprinting and keystroke dynamics are displacing SMS-based two-factor authentication as primary customer verification layers in mobile banking applications.
Market Restraints
- Specialized engineering talent scarcity:Cloud-native financial infrastructure requires rare combinations of distributed systems expertise and regulatory domain knowledge, inflating compensation costs and extending hiring cycles.
- Datacenter exit friction:Investment banks with co-located trading engines face latency penalties when migrating from owned hardware to public cloud, preserving hybrid complexity.
- Fragmented AI governance:Divergent national implementations of the EU AI Act, pending US federal frameworks, and China's algorithmic recommendation regulations force parallel compliance engineering tracks.
Strategic Opportunities
- India's digital public infrastructure:Account Aggregator frameworks and UPI stack expansion create openings for modular lending and wealthtech applications targeting underbanked segments.
- Embedded finance convergence:Banking-as-a-Service APIs combined with generative AI interfaces enable non-financial platforms to offer contextual credit and insurance products.
- CSRD disclosure mandates:European corporate sustainability reporting requirements generate demand for carbon footprint tracking modules integrated directly into treasury and risk management suites.
Industry Challenges
- Core system migration complexity:Decades-old COBOL-based deposit engines resist decomposition, forcing expensive strangler-fig architectural patterns that extend project risk windows.
- Model risk management certification:SR 11-7 and equivalent ECB guidance require documented validation pipelines for every production ML model, consuming data science bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Financial Services Application Market |
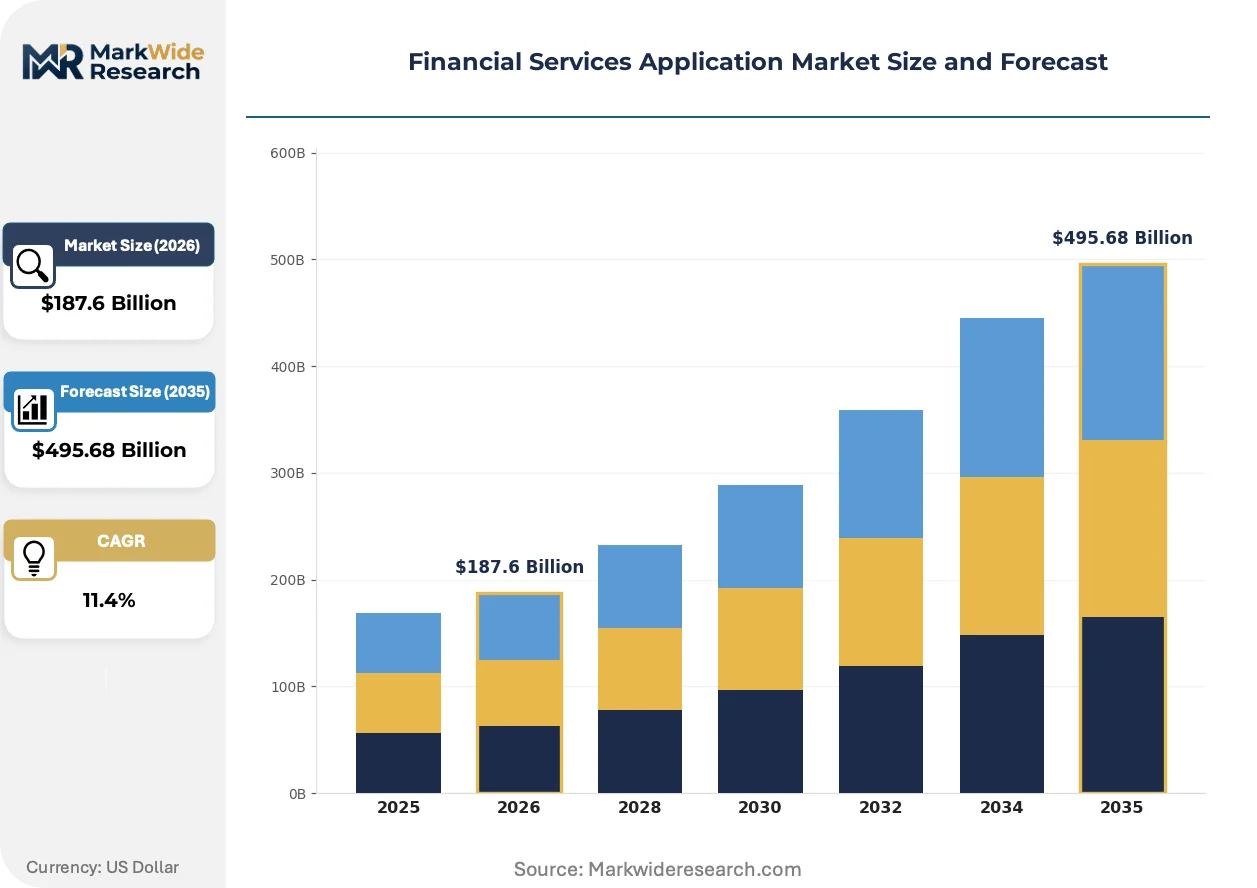
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $495.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Banking, Wealth Management Software, Payment Processing Solutions, Fraud Detection Systems End User: Retail Banks, Investment Firms, Credit Unions, Insurance Companies Installation: On-premise, Cloud-based, Hybrid Solutions, Legacy Systems Service Type: Consulting Services, Support Services, Managed Services, Custom Development |
| Companies Covered | Microsoft Corporation, Fidelity National Information Services (FIS), Fiserv, Inc., SAP SE, Oracle Corporation, Accenture plc, International Business Machines Corporation, Infosys Limited, Temenos AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Financial Services Application Market Emerging Trajectories
Distributed ledger infrastructure is virtualizing settlement layers previously anchored to physical clearinghouses, while regulatory pressure on algorithmic transparency accelerates investment in interpretable AI architectures.
Containerized microservices orchestration is virtualizing monolithic core banking functions into independently deployable components. Tier-two banks and credit unions are adopting Kubernetes-based platforms at the fastest clip, lured by reduced vendor lock-in and granular scaling. This decomposition is virtualizing the traditional core banking procurement model, compressing contract values and fragmenting supplier relationships across specialized API providers.
The EU AI Act's risk-tiered classification system imposes mandatory conformity assessments on high-risk credit scoring and fraud detection algorithms. Vendors must now embed technical documentation, human oversight protocols, and accuracy testing into product design from inception. Retail banks with cross-border European operations face the steepest compliance engineering burden, diverting R&D resources from feature expansion to audit readiness.
Corporate treasury departments are unbundling monolithic ERP banking modules in favor of best-of-breed API marketplaces. CFOs at mid-market manufacturers now procure cash forecasting, FX hedging, and liquidity management tools from separate specialists rather than single-suite providers. This pattern is most pronounced in Germany and the Netherlands, where open banking infrastructure maturity supports seamless multi-vendor orchestration.
Financial Services Application Market Segmentation
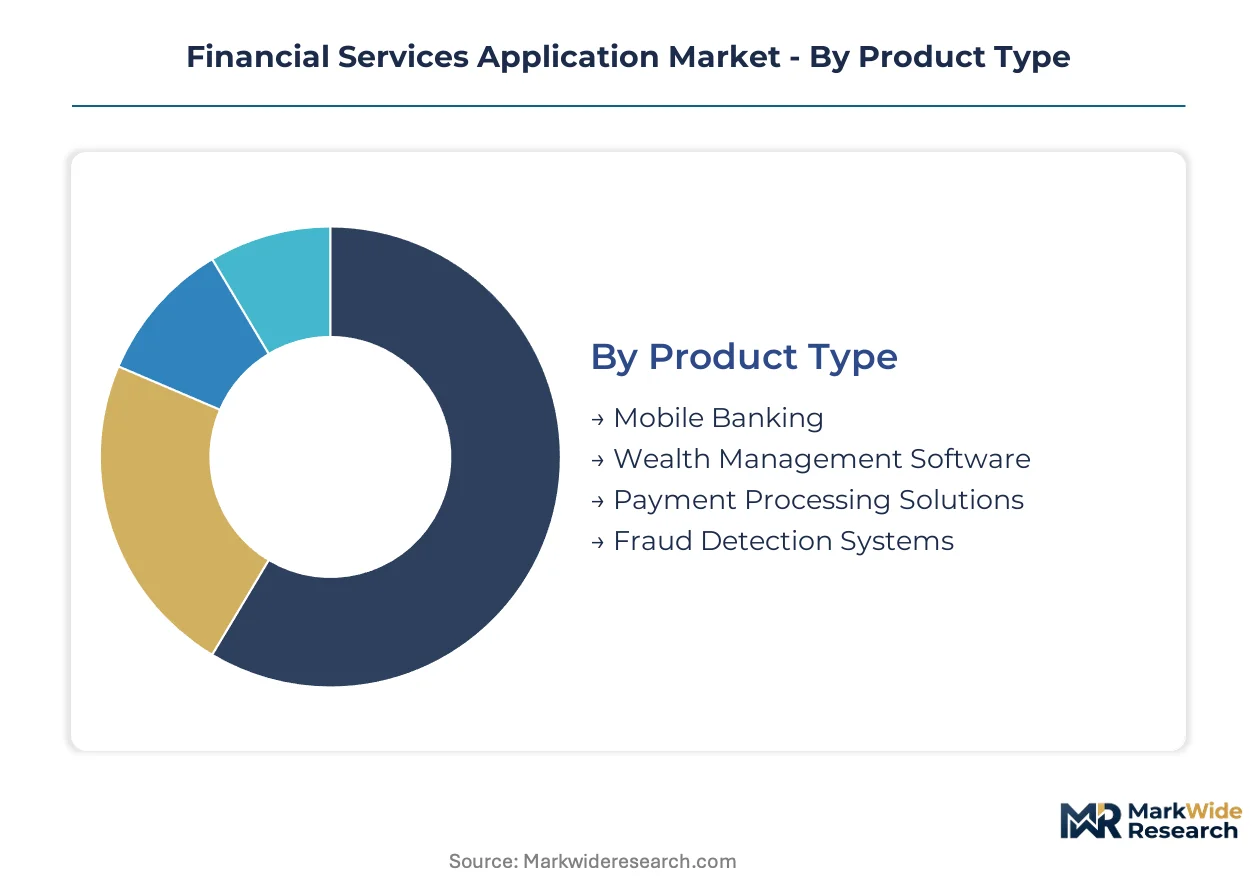
Segmentation in financial services applications reveals how procurement priorities diverge across infrastructure maturity, regulatory exposure, and customer interaction intensity. Vendors must architect modular pricing and deployment models that map to these distinct operational contexts rather than forcing uniform platform adoption.
Product Type:
After-sales service intensity varies sharply across product categories, with real-time transaction systems demanding 24/7 operational support while analytical modules require periodic model retraining and validation services.
- Payment Processing Solutions:These platforms handle merchant acquiring, real-time rail integration, and settlement orchestration with sub-second latency requirements. Demand concentrates among retail banks in the United States modernizing for FedNow compliance, driven by merchant volume growth and legacy batch system replacement mandates.
- Fraud Detection Systems:Behavioral biometrics engines and machine learning scoring models displace rule-based detection architectures. European banks under EU AI Act deadlines represent the fastest-expanding customer base, compelled by mandatory algorithmic audit trails and explainability requirements.
- Mobile Banking:Customer-facing applications with native iOS and Android deployments.
- Wealth Management Software:Portfolio analytics and advisory workflow platforms for high-net-worth segments.
Payment Processing Solutions holds the largest share; momentum sits with Fraud Detection Systems.
End User:
Cost tier stratification separates institutional buyers with dedicated compliance engineering teams from mid-market institutions purchasing through managed service arrangements.
- Retail Banks:Full-service deposit and lending institutions with the broadest functional requirements and highest regulatory touchpoints. Cloud-native core replacement projects concentrate among regional banks in Germany and the Netherlands, driven by open banking infrastructure maturity and API marketplace adoption.
- Investment Firms:Broker-dealers and asset managers with latency-sensitive trading operations. Hybrid infrastructure retention dominates in the United States and United Kingdom due to co-location requirements and market data feed proximity constraints.
- Credit Unions:Member-owned financial cooperatives with constrained IT budgets.
- Insurance Companies:Underwriting and claims platforms with actuarial system integration needs.
Retail Banks command the largest addressable base; Investment Firms show the steepest expansion trajectory for specialized risk analytics.
Installation:
Volume concentration patterns reflect datacenter ownership economics and workload latency sensitivity across trading versus retail banking functions.
- Cloud-based:Containerized deployments on AWS, Azure, or GCP with Kubernetes orchestration. Tier-two banks and credit unions in India and Brazil are adopting fastest, attracted by granular scaling and reduced vendor lock-in.
- Hybrid Solutions:Split architectures with sensitive data on-premise and customer channels in cloud. Investment banks in London and New York maintain this model to preserve microsecond advantages in execution infrastructure.
- On-premise:Dedicated hardware installations with full operational control.
- Legacy Systems:COBOL-based mainframe environments resisting decomposition.
Cloud-based captures expanding share; Hybrid Solutions retain dominance where latency penalties prohibit full migration.
Service Type:
Customer type differentiation separates institutions with captive engineering capabilities from those outsourcing entire platform lifecycle management.
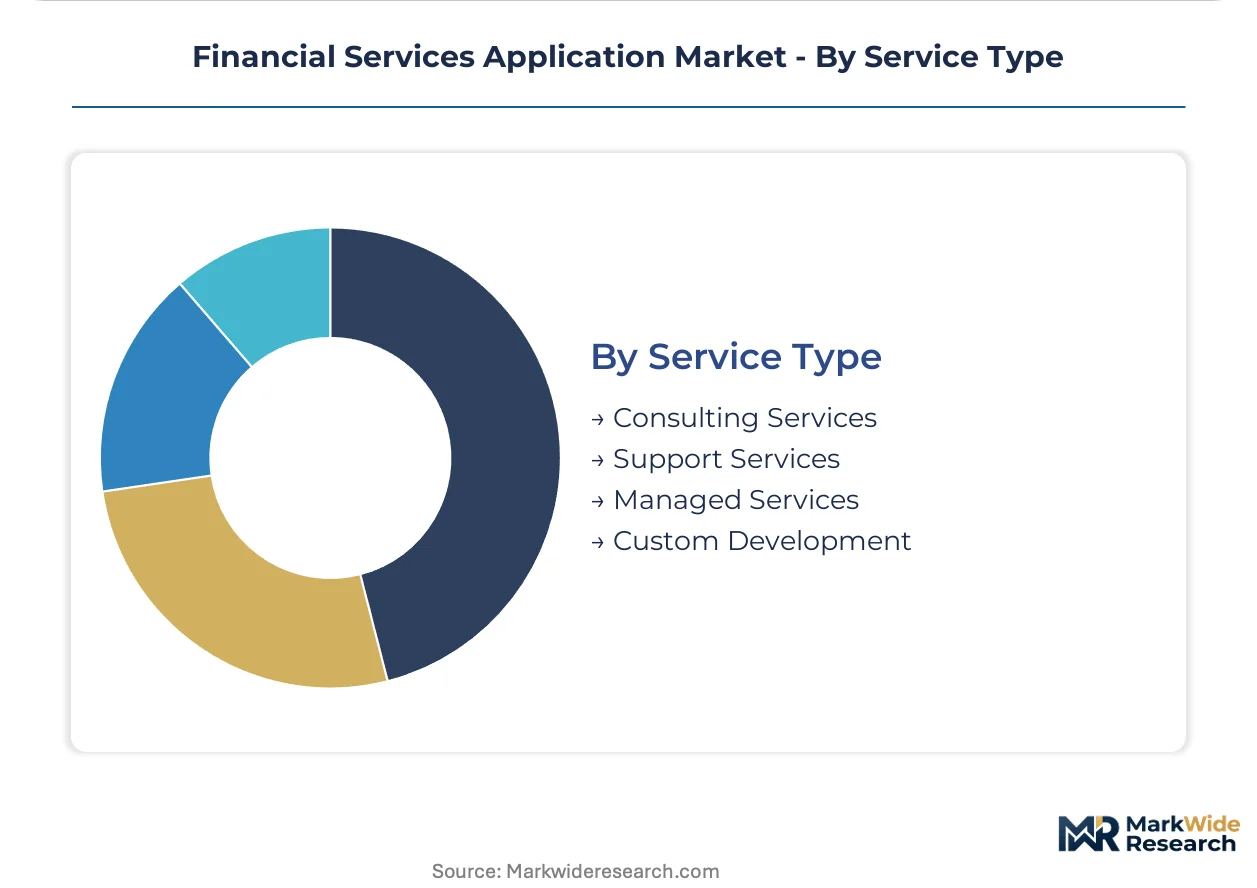
- Managed Services:Full operational responsibility including infrastructure monitoring, security patching, and regulatory update implementation. Mid-tier retail banks across Spain and Italy prefer this model to compensate for specialized talent scarcity.
- Consulting Services:Strategic advisory for core system migration and compliance architecture design. Demand clusters among North American institutions navigating SEC disclosure modernization and Basel III operational risk framework implementation.
- Support Services:Break-fix and maintenance contracts for installed platforms.
- Custom Development:Bespoke feature engineering for proprietary workflow requirements.
Managed Services holds the largest share; Consulting Services is gaining share fastest amid migration complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border software licensing flows concentrate outbound from the United States and inbound to European and Asian banking centers, with regulatory divergence acting as the primary trade friction mechanism rather than tariffs or currency risk.
United States
FedNow real-time payment infrastructure mandates and SEC disclosure modernization are driving core system replacement cycles among regional banks. The Office of the Comptroller of the Currency has accelerated fintech charter approvals, expanding the addressable vendor base. New York and Charlotte banking clusters host the densest concentration of procurement decision-makers for enterprise-class platforms.
Germany
Open banking infrastructure maturity and corporate treasury unbundling trends favor API-first vendors over integrated suite providers. BaFin implementation of EU AI Act conformity assessments imposes documentation burdens on credit scoring algorithm deployments. Frankfurt and Munich financial centers anchor demand for hybrid cloud solutions serving latency-sensitive trading operations.
India
Account Aggregator framework expansion and UPI stack growth create modular lending application opportunities targeting underbanked segments. RBI guidelines on cloud data localization and digital lending compliance reshape vendor qualification criteria. Mumbai and Bangalore fintech corridors concentrate engineering talent and venture capital deployment for indigenous platform development.
United Kingdom
Post-Brexit regulatory divergence from EU frameworks forces parallel compliance engineering tracks for cross-border banking operations. The Financial Conduct Authority's operational resilience mandates accelerate legacy infrastructure replacement timelines. London's investment banking cluster preserves hybrid infrastructure dominance due to co-location requirements and microsecond execution sensitivity.
Brazil
Pix instant payment system adoption and open finance regulatory phases expand addressable market for payment processing and lending workflow platforms. Banco Central do Brasil's sandbox frameworks lower entry barriers for foreign software vendors. São Paulo's financial district concentrates both incumbent bank technology procurement and emerging fintech platform demand.
Financial Services Application Market Vendor Landscape
On the supply side, the industry is consolidating around cloud-native platform providers while fragmenting across specialized API vendors, creating a tiered structure with divergent margin profiles. Incumbent full-suite vendors face compression from modular challengers offering discrete payment, fraud, or core banking components. Two strategic archetypes dominate: hyperscale cloud infrastructure anchors and regulatory domain specialists. Competitive moves concentrate on M&A absorption of API-first challengers and strategic partnerships embedding finance functionality into non-financial platforms.
Among North American technology conglomerates, Microsoft Corporation exemplifies the hyperscale infrastructure anchor archetype through Azure cloud banking deployments. Fiserv, Inc. occupies a position within payment processing specialization, while Temenos AG represents the modular core banking modernization approach targeting emerging market tier-two institutions. These three entities collectively illustrate the competitive tension between integrated platform breadth and targeted functional depth.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Fidelity National Information Services (FIS) |
| Fiserv, Inc. |
| SAP SE |
| Oracle Corporation |
| Accenture plc |
| International Business Machines Corporation |
| Infosys Limited |
| Temenos AG |
| Others |
Supply Flow & Price Mechanics
Bangalore's cloud engineering talent density feeds directly into SaaS vendor pricing power across enterprise banking contracts. Indian development centers anchor cost structures for global fintech platforms, compressing margins for European and North American pure-play competitors while enabling aggressive subscription-tier expansion.
Pricing Analysis
Retail banks anchor pricing stratification across premium, standard, and economy deployment tiers. Subscription-based SaaS licensing with usage-scaled tiers dominates, with differentiation resting on FedNow compliance certification and API integration depth. Cost compression in mid-market segments intensifies as Kubernetes-native challengers displace legacy per-seat models. Tier-two credit unions exhibit highest price sensitivity; investment banks with co-location requirements show lowest.
Supply Chain Analysis
Upstream cloud infrastructure feeds from hyperscale data centers concentrated in the United States, Ireland, and Singapore. Distributed computing hardware, encryption modules, and regulatory compliance software draw from specialized vendors across Taiwan, Germany, and Israel. Single-source vulnerability in EU-located AI audit tooling creates exposure as EU AI Act deadlines approach. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory jurisdictions creates specialized vendor niches as banks abandon monolithic suite procurement. Modular API-first architectures reward targeted functional depth over platform breadth.
For Market Incumbents: Pre-empt core banking displacement by acquiring Kubernetes-native challengers before they scale beyond sub-$50 million ARR. Defensive consolidation must address API marketplace unbundling in German and Dutch corporate treasury segments. Backward integration into behavioral biometrics engines preserves fraud detection margin pools against pure-play ML vendors. For New Entrants and Emerging Players: Build out India-focused Account Aggregator lending modules before domestic platforms achieve regulatory lock-in. India's underbanked SME credit scoring represents the most penetrable white-space. Embedded finance partnerships with non-financial platforms offer the strongest go-to-market angle for bypassing incumbent procurement cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fraud detection vendors with EU AI Act conformity pre-certification. Long-term viability favors regulatory domain specialists over horizontal cloud infrastructure plays. Watch FedNow adoption velocity among U.S. regional banks as the primary inflection signal for payment processing platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Absorbing API-first challengers secures Kubernetes talent and FedNow-ready codebases. |
| Platform Integration | Embedding fraud detection into Azure banking deployments captures Microsoft ecosystem procurement. |
| Strategic Partnership | Banking-as-a-Service alliances with retail platforms expand addressable merchant acquiring volume. |
| Regulatory Pre-Certification | EU AI Act conformity assessment investment accelerates European bank procurement cycles. |
| Geographic Expansion | India development center buildout reduces engineering costs for global SaaS delivery. |
Methodological Framework
A spread of perspectives from CTOs at tier-two banks, cloud platform engineers, regulatory compliance officers, and fintech product managers converged on the working assumptions. Primary interview data combined with secondary validation from SEC filings, ECB supervisory disclosures, RBI circulars, and hyperscaler capex reports. Bottom-up deployment estimates triangulated against top-down banking IT spend forecasts.
Demand-supply balance across cloud infrastructure availability and specialized engineering talent shaped the analytical framework. Segmentation modeled deployment model, institution size tier, functional module, regional regulatory cluster, and integration complexity. CAGRs derived from trend extrapolation with cross-validation against historical banking software procurement cycles. FedNow adoption curves and EU AI Act implementation timelines served as industry-specific forecast inputs.
Stress conditions across interest rate volatility, regulatory deadline delays, and cloud egress cost inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about bank modernization budget persistence and compliance-driven procurement urgency. Cross-checking against disclosed banking technology vendor contract values is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Intellectual Property Valuation Market
Financial Services
Back-Office Outsourcing in Financial Services Market
Financial Services
Financial Advisory Services Market
Financial Services
United Kingdom E-Brokerage Market
Financial Services
Global Product Cost Management Market
Financial Services
E-KYC Market
Financial Services
BFSI A2P SMS Market
Financial Services
Commodity Services Market
Financial Services
Solar Powered ATM Market
Financial Services
South Korea Financial Services Software Market
Financial Services
North America B2B Legal Services Market
Financial Services
India Payroll Services Market
Financial Services
Canada Credit Cards Market
Financial Services
Europe E-Invoicing Market
Financial Services
Debt Settlement Solution Market
Financial Services
Middle East Financial Consulting Software Market