
 North America B2B Legal Services Market | 2026-2036
North America B2B Legal Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America B2B Legal Services Market Insights
Mid-market enterprise legal procurement is pivoting toward consolidated panel arrangements that reduce vendor counts while expanding scope per retained firm. Kirkland & Ellis dominates private equity sponsor representation through its leveraged finance and fund formation depth. Latham & Watkins extends its position across emerging company capital markets and climate-related transactional advisory. Jones Day anchors its competitive stance through a decentralized partnership model that sustains geographic proximity to industrial clients across the Great Lakes and Gulf Coast manufacturing corridors.
North America B2B legal services encompass advisory, transactional, and dispute-resolution counsel delivered on a business-to-business basis, encompassing contract drafting with precision to governing law clauses and jurisdictional specifications, due diligence protocols for M&A closings, and regulatory interpretation for compliance programs. Corporate law engagements command the largest fee pool among service types, reflecting sustained capital markets activity and private equity transaction velocity. Intellectual property work registers the fastest structural expansion as technology sector clients prosecute patent portfolios and defend against NPE assertions across Eastern District of Texas and Western District of Wisconsin dockets.
SEC disclosure rules and Canadian securities administrators' guidance shape demand for public company governance counsel, while U.S. Department of Justice antitrust enforcement priorities redirect merger control work toward extended Second Request timelines. State bar ethics opinions on artificial intelligence tool adoption create compliance complexity that drives advisory spend at the intersection of professional responsibility and operational efficiency. Stakeholders must monitor how state-level unauthorized practice of law enforcement evolves in response to technology-enabled service delivery models that challenge traditional jurisdictional boundaries.
Market Dynamics
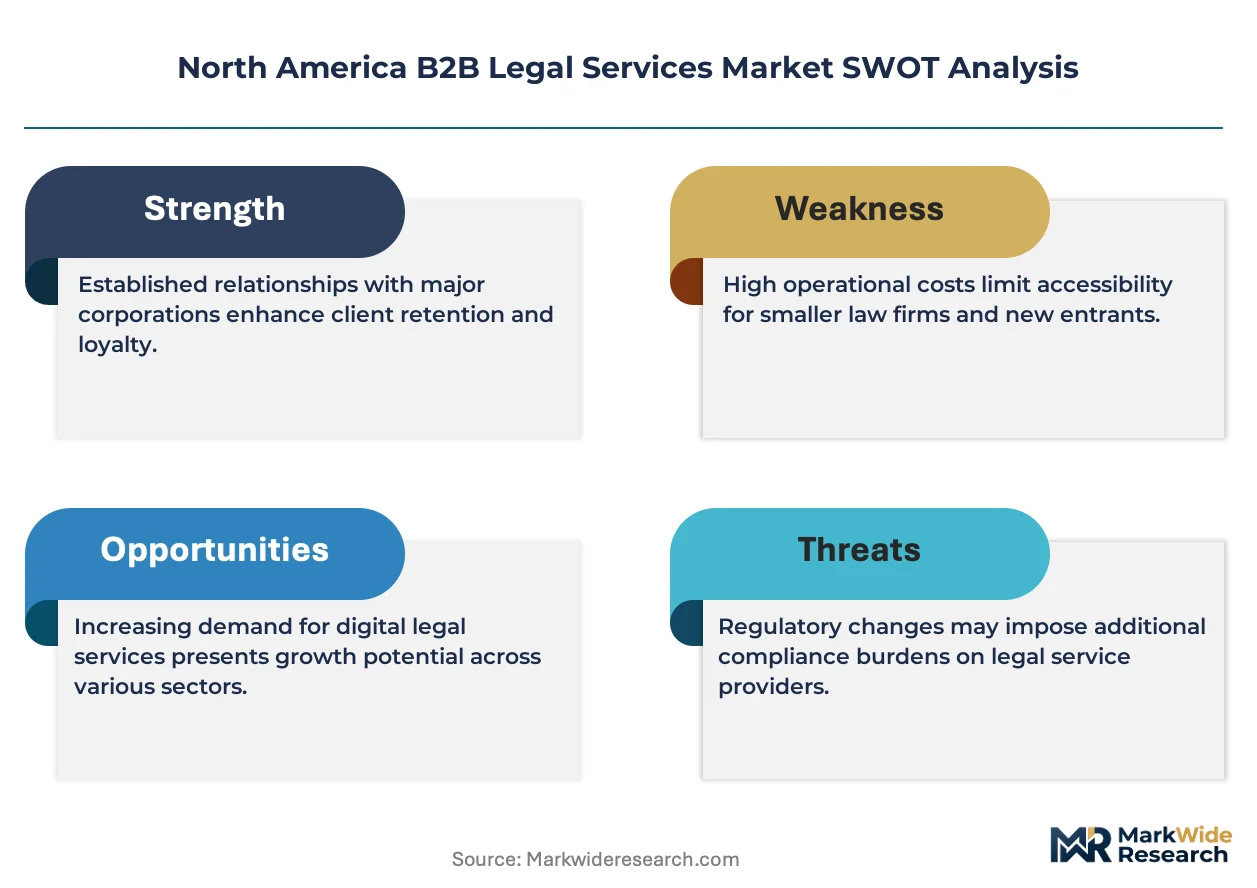
Artificial intelligence contract review platforms are compressing discovery timelines and forcing law firms to reconfigure staffing ratios, while mid-market enterprises consolidate vendor panels to reduce costs amid heightened SEC disclosure obligations.
Growth Catalysts
- SEC disclosure rule expansion:Mid-market companies face intensified reporting mandates that drive enterprise procurement of regulatory compliance counsel across capital markets and M&A advisory segments.
- Canadian privacy authority mandates:Cross-border data governance requirements from provincial and federal regulators generate sustained advisory volume for technology sector clients managing transnational data flows.
- Artificial intelligence tool adoption:State bar ethics opinions on AI-assisted legal research create compliance complexity that expands advisory spend at the intersection of professional responsibility and operational efficiency.
Market Restraints
- Partner compensation inflation:Talent competition at leveraged finance and fund formation practices drives cost structures upward, compressing margin for fixed-fee engagements.
- Unauthorized practice enforcement:State-level regulatory friction threatens technology-enabled service delivery models that challenge traditional jurisdictional boundaries for remote counsel provision.
- Alternative legal service providers:Document automation platforms and managed legal services substitutes capture commoditized work at price points below traditional firm rates.
Strategic Opportunities
- Climate-related transactional advisory:Emerging company capital markets and sustainability-linked financing structures create white space for counsel with energy transition expertise.
- Second Request timeline extension:DOJ antitrust enforcement priorities redirect merger control work toward extended regulatory review processes that expand advisory hours.
- Intellectual property portfolio prosecution:Technology sector patent filings and NPE defense work in Eastern District of Texas and Western District of Wisconsin dockets represent underpenetrated growth corridors.
Industry Challenges
- Associate retention and pipeline development:Junior lawyer attrition accelerates as alternative career paths in technology and finance compete for talent with traditional partnership tracks.
- Legacy system integration with AI platforms:Knowledge management infrastructure requires capital-intensive reconfiguration to support machine learning document analysis without compromising client confidentiality protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America B2B Legal Services Market |
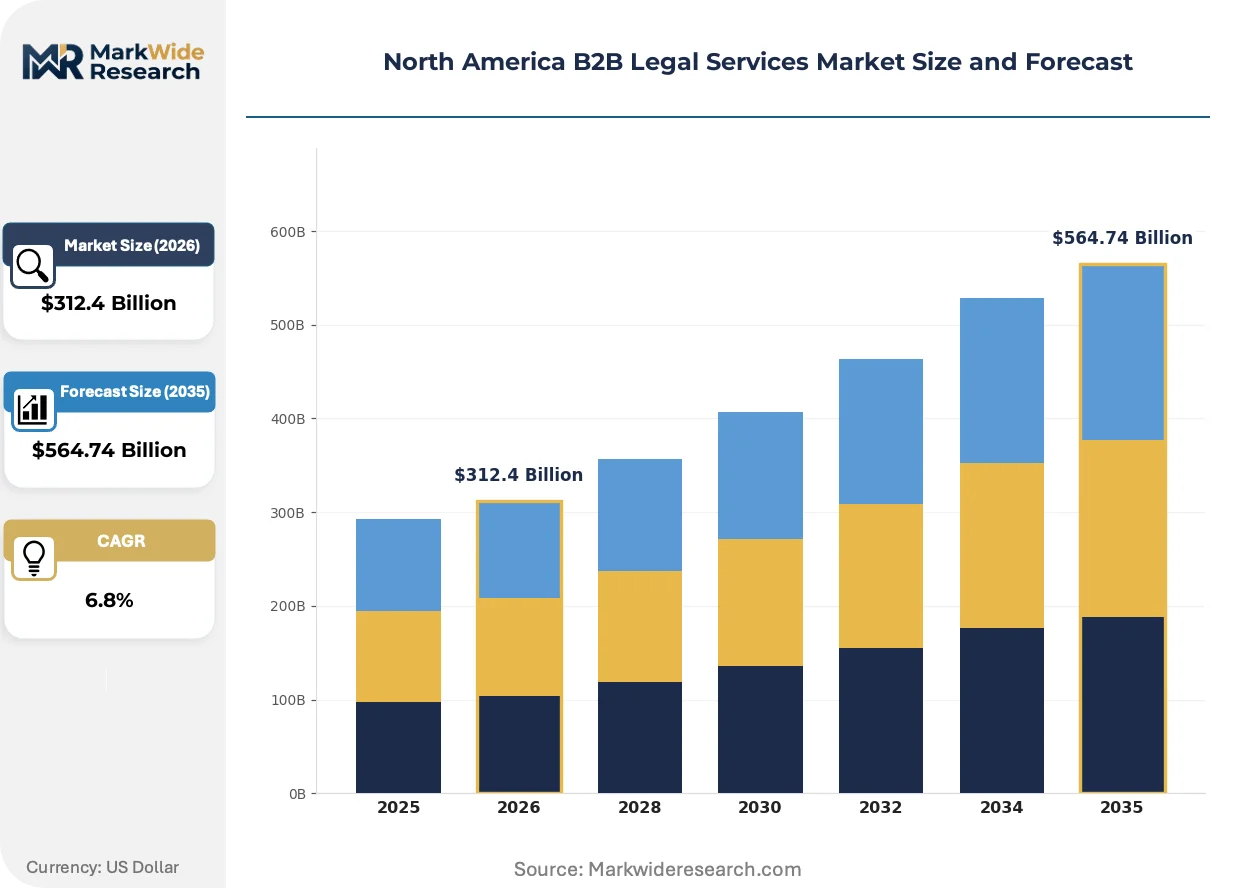
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $564.74 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Litigation, Corporate Law, Intellectual Property, Employment Law Client Type: Startups, Enterprises, Nonprofits, Government Agencies Industry Vertical: Technology, Healthcare, Finance, Retail Engagement Model: Retainer, Hourly Billing, Fixed Fee, Contingency |
| Companies Covered | Jones Day, Baker McKenzie, Simpson Thacher & Bartlett, Latham & Watkins, Kirkland & Ellis, Sidley Austin, Hogan Lovells, Skadden, Arps, Slate, Meagher & Flom, White & Case, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America B2B Legal Services Market Trends and Innovations
Technology-enabled delivery models are reshaping competitive positioning across the North America B2B legal services landscape, with artificial intelligence, regulatory complexity, and procurement transformation converging to redefine value creation.
Natural language processing contract analysis tools are expanding into due diligence and lease abstraction workflows at mid-market enterprises and private equity sponsors. Technology sector legal departments and fund formation practices adopt these platforms at accelerating pace to compress closing timelines. The technology is expanding into areas previously staffed by junior associates, forcing firms to retrain talent toward higher-value advisory functions.
DOJ antitrust enforcement priorities and Canadian securities administrators' guidance are extending merger control timelines and public company governance obligations. These regulatory frameworks redirect transaction structuring toward extended Second Request preparation and cross-border disclosure harmonization. U.S. technology sector engagements and cross-border M&A involving Canadian targets face the most pronounced compliance burden expansion.
Corporate legal departments are consolidating outside counsel panels from twenty-plus firms to five-to-seven preferred providers with expanded scope mandates. This concentration disrupts the traditional hourly billing relationship and replaces it with alternative fee arrangements tied to matter outcomes. The pattern is most visible among Fortune 500 industrials and mid-market private equity sponsors across the Great Lakes and Gulf Coast manufacturing corridors.
North America B2B Legal Services Market Segmentation
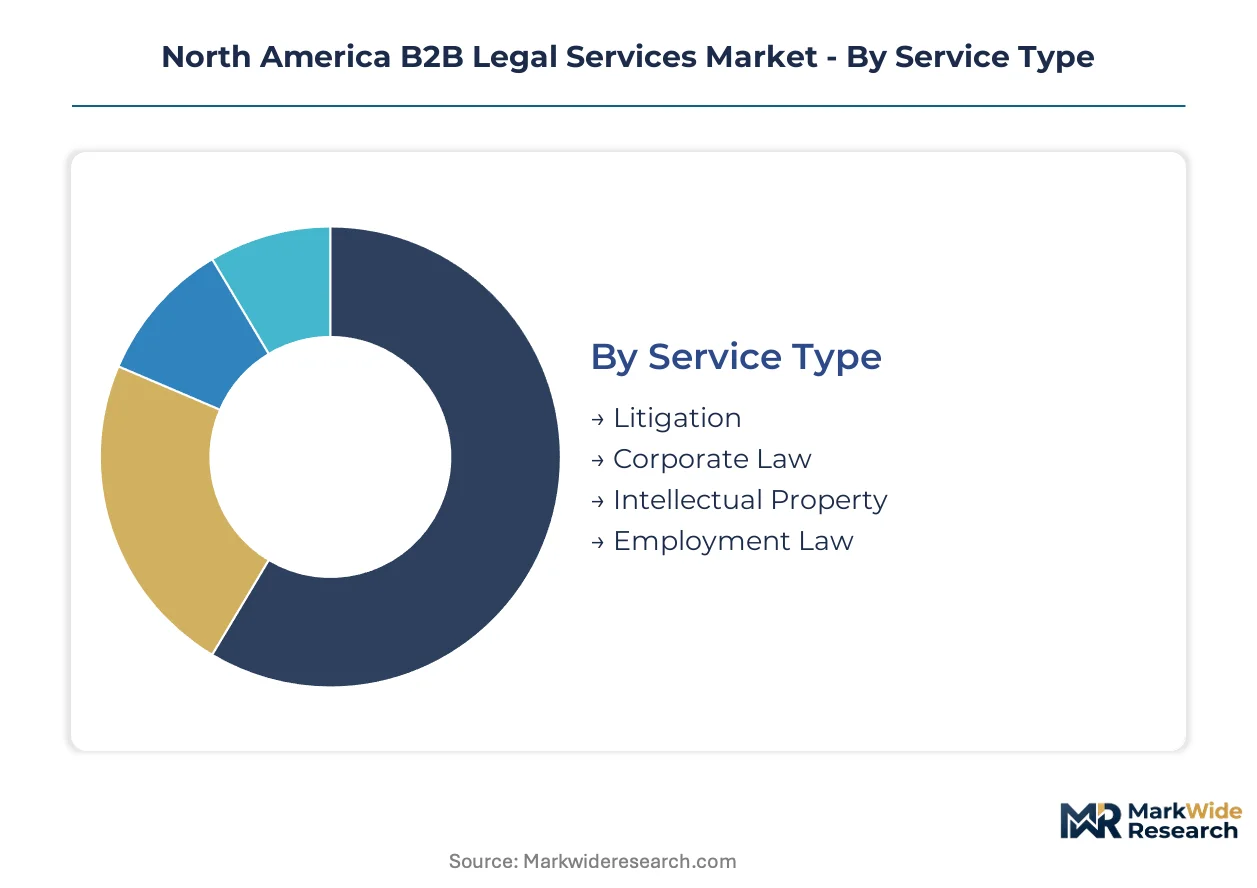
North America B2B legal services segmentation reveals how procurement patterns diverge across service complexity, client sophistication, and regulatory exposure. Understanding these divides clarifies where pricing power concentrates and which delivery models face substitution pressure.
Service Type:
Capital intensity varies sharply across legal disciplines, with litigation and corporate law demanding the heaviest partner-level investment and proprietary knowledge management infrastructure.
- Litigation:Discovery-intensive practice requiring document review platforms, expert witness networks, and appellate specialist benches. Demand concentrates in U.S. technology sector patent disputes and SEC enforcement defense, driven by Eastern District of Texas venue rules and DOJ white-collar priorities.
- Corporate Law:Transactional advisory spanning M&A execution, capital markets issuance, and fund formation. Private equity sponsors across the Great Lakes and Gulf Coast manufacturing corridors sustain the largest fee pool, with leveraged finance work commanding premium partner rates.
- Intellectual Property:Patent prosecution and NPE defense workflows.
- Employment Law:Compliance counseling and class action defense.
Most installed capacity flows through Corporate Law. Expansion is steepest in Intellectual Property.
Client Type:
Cost tier stratification separates price-sensitive buyers from those purchasing outcome certainty and regulatory insulation.
- Startups:Venture-backed emerging companies purchasing founder-friendly formation documents, SAFE financing templates, and scaled counsel through deferred fee arrangements. Demand clusters in U.S. technology hubs and Canadian innovation corridors, constrained by runway-limited legal budgets and preference for fixed-fee predictability.
- Enterprises:Fortune 500 and mid-market industrials with consolidated panel arrangements. These buyers across Great Lakes manufacturing belts and Texas energy corridors drive alternative fee structure adoption, substituting hourly billing for matter-outcome pricing.
- Nonprofits:Mission-driven organizations seeking tax-exempt compliance and governance advisory.
- Government Agencies:Federal and provincial procurement of specialized regulatory counsel.
Enterprises command the deepest relationship investment. Startups are gaining share fastest through venture ecosystem density.
Industry Vertical:
Application-specific regulatory complexity determines advisory pricing and partner specialization depth.
- Technology:Cross-border data governance mandates from Canadian privacy authorities and U.S. federal agencies generate sustained advisory volume. Patent prosecution, open-source licensing, and cybersecurity incident response dominate spend.
- Healthcare:HIPAA compliance, FDA regulatory strategy, and fraud defense. U.S. hospital systems and Canadian provincial health authorities procure specialized counsel for reimbursement disputes and clinical trial contracting.
- Finance:SEC disclosure obligations and CFPB enforcement defense.
- Retail:Consumer protection compliance and supply chain contracting.
Technology verticals absorb the most sophisticated advisory. Healthcare is climbing the fastest on regulatory burden expansion.
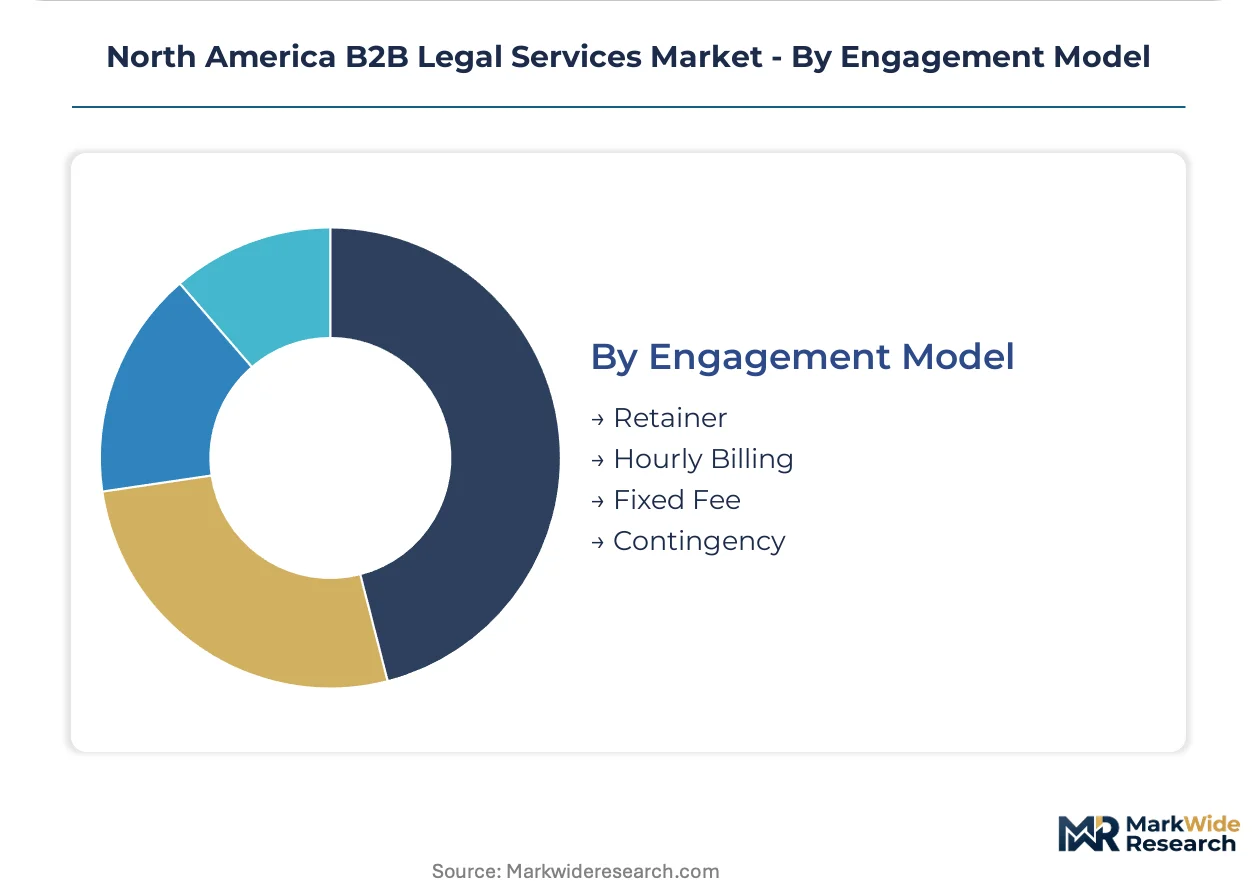
Engagement Model:
Margin structure and cash flow timing differentiate how legal services are procured and delivered.
- Retainer:Relationship-based arrangements providing priority access and predictable cost baselines. Mid-market private equity sponsors and Fortune 500 industrials across the Great Lakes favor this model for fund formation and portfolio company work.
- Hourly Billing:Traditional time-and-materials pricing facing compression from procurement departments and alternative fee pressure.
- Fixed Fee:Outcome-defined pricing for discrete matters like M&A closings and patent filings.
- Contingency:Plaintiff-side and defense arrangements tied to matter resolution.
Retainer relationships anchor firm profitability. Fixed Fee is expanding most quickly as procurement departments consolidate panels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Partner-level talent pools concentrate in coastal metropolitan corridors, with lateral hiring markets tightening across the Great Lakes and Texas energy belts. Canadian regulatory expertise commands premium positioning in cross-border mandates.
United States
SEC disclosure obligations and DOJ antitrust enforcement priorities drive sustained demand for capital markets and merger control counsel. The Sarbanes-Oxley Act and Dodd-Frank provisions shape compliance program architecture for public company clients. New York and Washington DC anchor the largest advisory clusters, with Silicon Valley technology sector engagements expanding fastest on patent prosecution and data governance mandates.
Canada
Provincial privacy commissioners and federal Competition Bureau investigations generate cross-border advisory volume for technology and healthcare clients. The Personal Information Protection and Electronic Documents Act and provincial securities administrators' guidance create compliance complexity for transnational data flows. Toronto and Montreal concentrate the deepest bilingual regulatory expertise, with Calgary energy sector practices sustaining fund formation work.
Mexico
Nearshoring manufacturing investments and USMCA compliance requirements expand transactional advisory needs for automotive and electronics supply chain clients. The Federal Economic Competition Commission and National Institute of Industrial Property shape merger control and intellectual property strategy. Mexico City and Nuevo León anchor corporate law practices, with Bajío Region industrial corridors driving employment and commercial contracting work.
North America B2B Legal Services Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across service lines, creating tiered competitive dynamics. The vendor base organizes around three strategic archetypes: full-service global firms with leveraged finance depth, boutique specialists in regulatory niches, and technology-enabled alternative providers capturing commoditized workflows. M&A activity concentrates on adding cybersecurity and climate advisory capabilities, while strategic partnerships with contract automation platforms reshape delivery economics.
Within the full-service tier, Kirkland & Ellis, Latham & Watkins, and Jones Day exemplify divergent organizational models for market positioning. Kirkland & Ellis occupies a position defined by private equity sponsor concentration and fund formation specialization. Latham & Watkins represents the geographically distributed partnership structure with emerging company capital markets depth. Jones Day anchors competitive stance through decentralized partnership governance sustaining proximity to industrial clients across manufacturing corridors.
| Leading Market Players |
|---|
| Jones Day |
| Baker McKenzie |
| Simpson Thacher & Bartlett |
| Latham & Watkins |
| Kirkland & Ellis |
| Sidley Austin |
| Hogan Lovells |
| Skadden, Arps, Slate, Meagher & Flom |
| White & Case |
| Others |
Pricing and Supply Chain Analysis
Leveraged finance associate pools in Manhattan and Washington DC drive labor-cost differentials that widen pricing-tier spreads between white-shoe partnerships and regional mid-market competitors. Partner compensation inflation at elite fund formation practices compresses margins for fixed-fee engagements while alternative legal service providers capture commoditized work below traditional rate floors.
Pricing Analysis
The bundled-vs-unbundled service split distinguishes full-service retainer relationships from discrete matter pricing. Three-tier pricing structure across premium, standard, and economy levels reflects partner specialization depth and jurisdictional complexity. Cost compression in discovery-intensive litigation intensifies because artificial intelligence contract review platforms displace junior associate hours. Startups exhibit the highest price sensitivity due to runway-constrained budgets, while private equity sponsors prioritize outcome certainty over rate minimization.
Supply Chain Analysis
Domestic-content mandates in Canadian provincial bar admissions and US state unauthorized practice enforcement reshape sourcing for cross-border advisory capacity. Talent supply concentrates in the United States, Canada, and United Kingdom legal education pipelines. Raw material dependencies include bar-certified associate labor, proprietary knowledge management infrastructure, and expert witness networks. Single-source vulnerability runs through partnership-track retention pipelines. Distribution runs through relationship-based retainer arrangements and panel consolidation frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America B2B legal services market functions as a stable compounder where regulatory complexity generates recurring advisory demand regardless of economic cyclicality.
For Market Incumbents: Cement dominance in private equity sponsor relationships through fund formation depth and portfolio company coverage expansion. Deepen vertical integration into contract automation platforms to defend against alternative legal service provider substitution. Prioritize cybersecurity and climate advisory capability acquisition as white-space defense.
For New Entrants and Emerging Players: Capture mid-market enterprise panel consolidation opportunities by offering fixed-fee predictability for M&A closings and patent prosecution. The most penetrable segment lies in technology sector startups seeking founder-friendly formation documents and deferred fee arrangements. Pursue geographic expansion into Great Lakes manufacturing corridors where incumbent proximity advantages have eroded.
For Investors and Strategic Acquirers: Private equity firms with legal services portfolio experience are the most active acquirer in this space, targeting boutique specialists with regulatory niche depth. Long-term viability rests on sustained regulatory burden expansion across SEC disclosure and cross-border data governance mandates. Monitor state bar ethics opinions on artificial intelligence adoption as the critical inflection signal for technology-enabled delivery model legitimacy.
| Strategic Initiative | Industry Significance |
|---|---|
| Artificial Intelligence Platform Integration | Natural language processing tools compress discovery timelines and reconfigure associate staffing ratios. |
| Climate Advisory Practice Buildout | Sustainability-linked financing structures create white space for energy transition expertise. |
| Cross-Border Regulatory Capability Acquisition | Canadian privacy authority mandates and SEC disclosure rules demand harmonized compliance counsel. |
| Alternative Fee Structure Expansion | Outcome-based pricing aligns with enterprise procurement department panel consolidation priorities. |
| Intellectual Property Prosecution Scaling | Eastern District of Texas and Western District of Wisconsin patent dockets represent underpenetrated corridors. |
Research Methodology
Direct dialogue with managing partners, general counsel at Fortune 500 industrials, private equity legal operations heads, and state bar ethics committee members grounded qualitative findings. Secondary validation drew from SEC filing disclosures, Canadian securities administrators' guidance documents, state bar ethics opinions, and law firm financial transparency reports. Bottom-up matter volume estimates and top-down addressable market sizing underwent cross-referencing for triangulation integrity.
Segmentation outputs across service type, client sophistication tier, industry vertical, and engagement model structure the analytical framework. CAGRs derive from regression analysis against historical fee growth patterns and regulatory event frequency. Forecast inputs incorporate DOJ antitrust enforcement priority shifts and technology sector patent filing velocity.
Partner compensation inflation acceleration, alternative legal service provider capability maturation, and state-level unauthorized practice enforcement evolution are the dominant revision risks. Forecasts reflect documented assumptions regarding regulatory burden trajectory and technology adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Back-Office Outsourcing in Financial Services Market
Financial Services
Canada Credit Cards Market
Financial Services
Multivendor ATM Software Market
Financial Services
Currency Exchange Software Market
Financial Services
Peer-To-Peer (P2P) Market
Financial Services
Latin America Factoring Services Market
Financial Services
Global Treasury Management System (TMS) Market
Financial Services
Financial Auditing Professional Services Market
Financial Services
Pawn Shop Market
Financial Services
Global Product Cost Management Market
Financial Services
Banknote Counters Market
Financial Services
Spain E-Brokerage Market
Financial Services
Banking Cloud Services Market
Financial Services
CFD Trading Affiliate Programs Market
Financial Services
Source to Pay Market
Financial Services
Financial Services Application Market