
 High End Furnitures Market | 2026-2036
High End Furnitures Market Size, Share, and Industry Trends Forecast 2026-2036
High End Furnitures Market Insights
Sustainable timber is consolidating its position as the dominant material substrate across premium seating and case goods, displacing conventional hardwoods burdened by certification gaps and supply inconsistency. Restoration Hardware (RH) leverages captive sourcing from European mills to secure FSC-certified oak and walnut at scale. Roche Bobois anchors its competitive stance through Paris-based ateliers that maintain hand-finishing protocols for leather upholstery. Bernhardt competes on domestic manufacturing flexibility, operating North Carolina facilities that reduce lead times for custom orders.
High end furnitures denote precision-crafted interior fixtures engineered to exacting dimensional tolerances, typically employing kiln-dried hardwood frames, eight-way hand-tied spring suspension, and top-grain leather or performance fabric coverings rated for residential and contract durability. The primary commercial purpose centers on delivering aesthetic distinction alongside functional longevity in luxury environments. Sofas command the largest margin pool within product type categories due to upholstery complexity and customization premiums. Wood materials sustain dominant volume share across residential channels, while metal and glass compositions lead growth in modern design style segments targeting commercial and hospitality end users. The hospitality end user category represents the fastest-expanding demand vertical, driven by boutique hotel development and experiential retail concepts.
EPA formaldehyde emission standards and California Air Resources Board (CARB) Phase 2 compliance requirements shape product specifications for wood-based materials sold in the United States. ECHA REACH restrictions on chromium VI in leather tanning processes directly affect European supply chains and sourcing decisions for upholstered components. ISO 9001 quality management certification functions as a baseline market access threshold for contract hospitality procurement. Stakeholders must monitor evolving chemical disclosure mandates across multiple jurisdictions and assess how material certification requirements will reshape supplier qualification criteria.
Market Dynamics
REACH chemical disclosure mandates in Europe and EPA formaldehyde standards in the United States are forcing material requalification across upholstered goods and wood substrates, compressing supplier lead times and elevating certification costs for manufacturers serving multiple jurisdictions.
Growth Catalysts
- Boutique Hospitality Development:Experiential retail concepts and design-forward hotel chains in Dubai and Miami are expanding procurement of bespoke seating and case goods, creating sustained demand for artisanal production capacity.
- ECHA REACH Restrictions:Chromium VI limitations in leather tanning processes are accelerating supplier consolidation toward certified tanneries with disclosed chemical chains, advantaging early-compliant manufacturers.
- FSC-Certified Oak Sourcing:Captive mill relationships with European forestry operations are securing volume commitments for kiln-dried hardwood frames, reducing exposure to certification gap risks in conventional supply channels.
Market Restraints
- Input Cost Volatility:Premium walnut and teak prices fluctuate with tropical hardwood harvest restrictions in Southeast Asian source markets, compressing margin predictability for case goods producers.
- Supply Concentration Risk:Italian and French atelier capacity for hand-finishing leather upholstery remains geographically concentrated, creating bottleneck exposure for brands dependent on Paris-based craft labor pools.
- Substitution Threat:High-performance engineered composites and thermally modified softwoods are capturing share in modern design segments where aesthetic tolerance for non-traditional materials has expanded.
Strategic Opportunities
- China Tier-One Penetration:Affluent consumers in Shanghai and Beijing are prioritizing designer craftsmanship, creating whitespace for brands establishing direct retail presence outside established wholesale channels.
- ISO 9001 Contract Hospitality:Quality management certification is becoming a baseline procurement threshold for hotel operators, creating competitive separation for manufacturers with documented process controls.
- Digital Configuration Platforms:Real-time customization interfaces are converging with North Carolina manufacturing flexibility, enabling compressed lead times for made-to-order residential specifications.
Industry Challenges
- Eight-Way Hand-Tying Skill Gap:Traditional spring suspension craft is aging out of the workforce faster than training programs replenish qualified upholsterers, constraining production scaling for premium seating.
- CARB Phase 2 Compliance Timelines:California Air Resources Board emission testing protocols require extended product validation cycles, delaying market entry for new wood substrate formulations.
- Multi-Jurisdiction Disclosure Burden:Divergent chemical reporting requirements across EPA, ECHA, and emerging state-level mandates are fragmenting product specification management and increasing compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High End Furnitures Market |
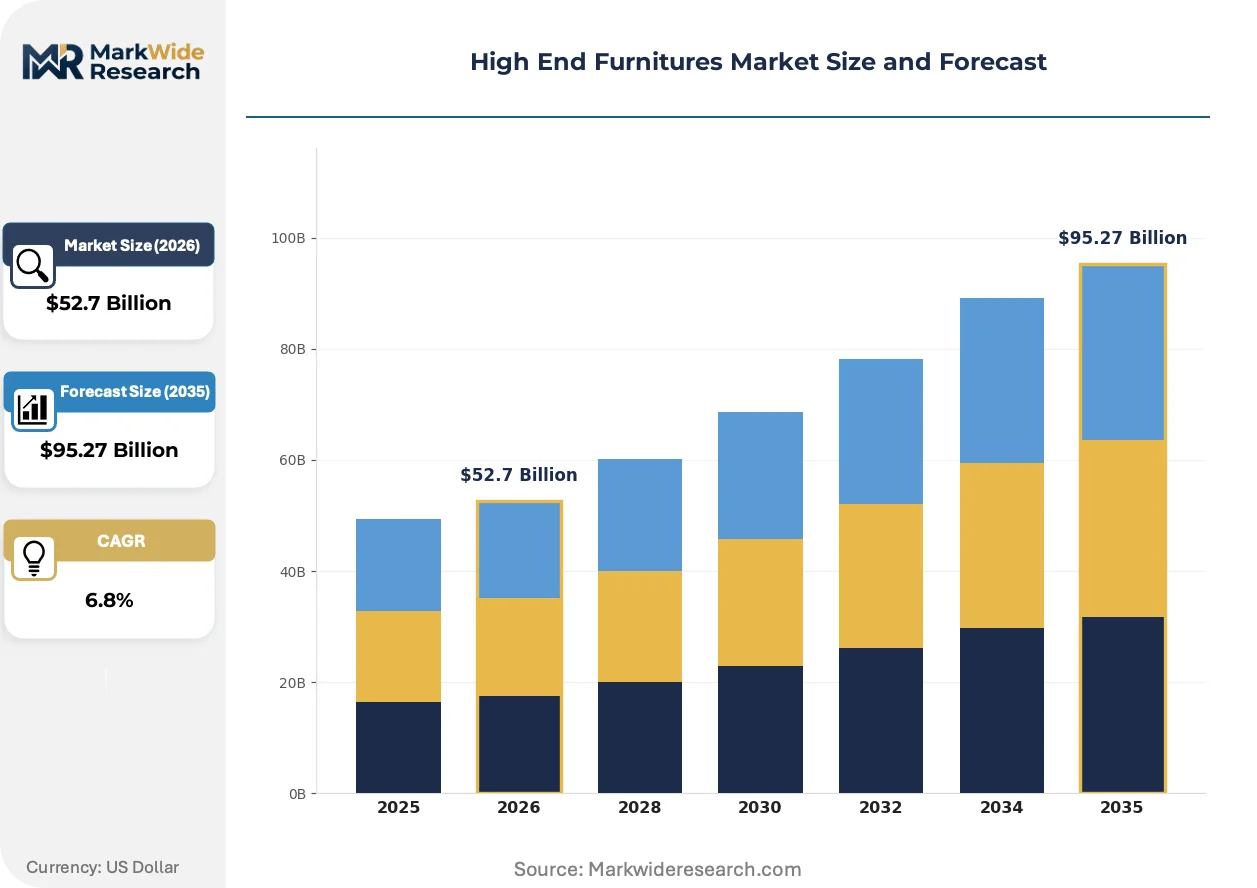
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chairs, Tables, Sofas, Cabinets Material: Wood, Leather, Metal, Glass Design Style: Modern, Vintage, Minimalist, Rustic End User: Residential, Commercial, Hospitality, Office |
| Companies Covered | Restoration Hardware (RH), Roche Bobois, Century Furniture, Bernhardt, Baker Furniture, Knoll, Mitchell Gold + Bob Williams, Arhaus, Brown Jordan International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High End Furnitures Market Trends and Innovations
Material science advances and regulatory stringency are compressing traditional production timelines while elevating transparency requirements across the value chain, reshaping how manufacturers qualify suppliers and engage end-users.
Thermally modified ash and acetylated wood treatments are overtaking conventional tropical hardwoods in exterior and high-humidity interior applications. Hospitality developers in coastal markets are specifying these substrates for poolside and spa environments where dimensional stability matters. The shift is overtaking established teak supply relationships and redirecting procurement toward Nordic and North American modified-wood producers with disclosed chemical processes.
ECHA REACH Annex XVII expansions now mandate substance-of-very-high-concern disclosure throughout upholstery supply chains. European manufacturers are requalifying foam suppliers and textile finishers to maintain market access. Upholstered goods sold in Germany and France face the most immediate compliance pressure, with brands accelerating leather sourcing transitions to vegetable-tanned alternatives ahead of enforcement deadlines.
Direct-to-consumer configuration tools are fragmenting traditional wholesale relationships in residential channels. Affluent buyers in China's tier-one cities now expect real-time visualization of custom dimensions and fabric selections. This behavioral shift is most visible in Shanghai's luxury retail corridors, where showroom footprints are shrinking in favor of digital-first engagement with centralized North American manufacturing fulfillment.
High End Furnitures Market Segmentation
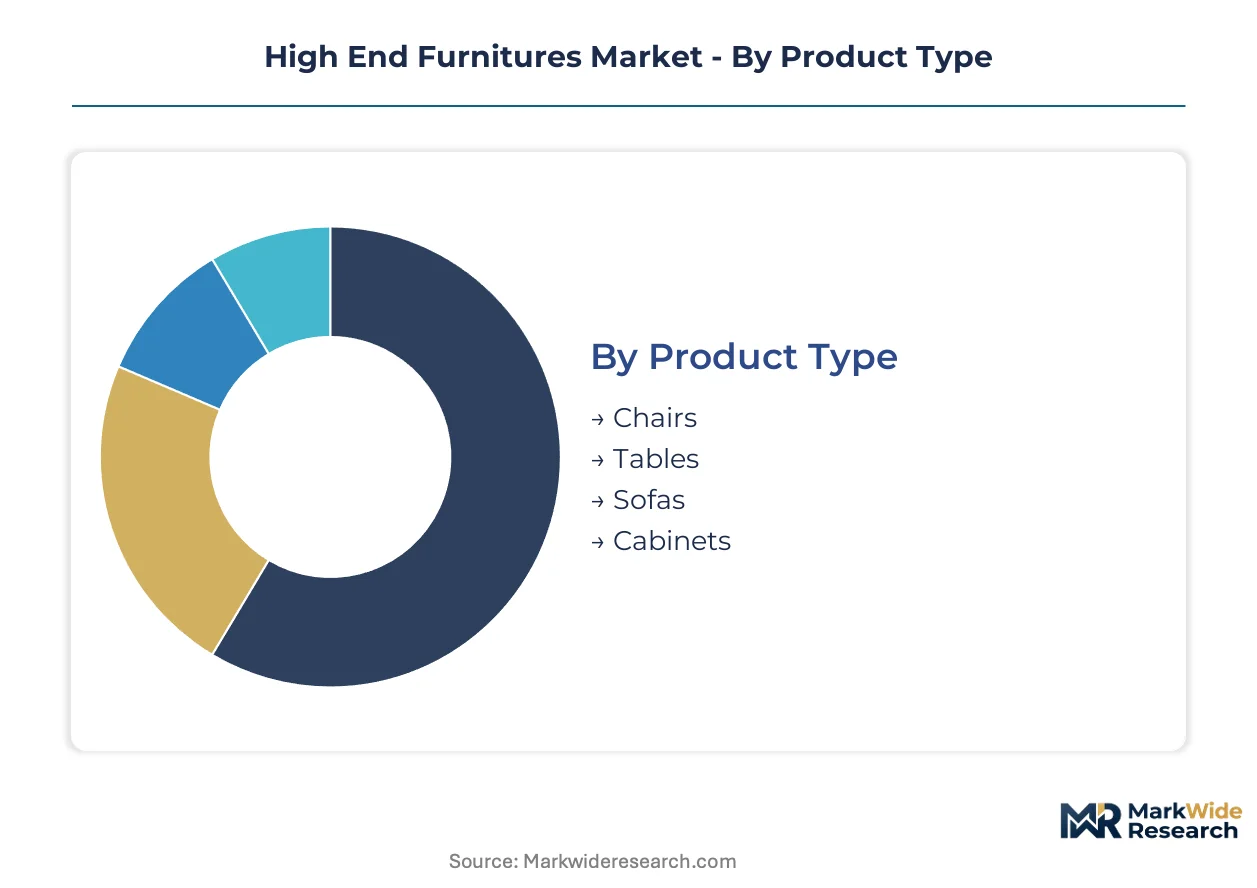
High end furnitures manufacturers configure production lines around distinct specification clusters that dictate material sourcing, craft labor allocation, and certification pathways. Segment boundaries determine which regulatory frameworks apply and where margin concentration pools form across residential contract and hospitality procurement channels.
Product Type:
Supply concentration for premium seating and storage systems shapes competitive positioning across artisanal production networks.
- Sofas:Kiln-dried hardwood frames with eight-way hand-tied spring suspension command the largest margin pool due to upholstery complexity and customization premiums. Demand concentrates in Dubai and Miami where luxury residential developers specify bespoke dimensions for penthouse installations.
- Cabinets:Precision-milled case goods with dovetail joinery and hand-rubbed finishes anchor dining and bedroom collections. China's tier-one cities drive specification volume as affluent consumers prioritize visible storage craftsmanship in open-plan layouts.
- Chairs:Dining and accent seating with sculpted frames and performance fabric coverings.
- Tables:Conference and dining surfaces employing book-matched veneer patterns and metal base integrations.
Today's leader: Sofas. Tomorrow's challenger: Cabinets.
Material:
Cost tier differentiation separates certified sustainable substrates from conventional supply channels burdened by regulatory gaps.
- Wood:FSC-certified oak and walnut sustain dominant volume share across residential channels, with kiln-dried hardwood frames setting structural durability benchmarks. REACH chemical disclosure mandates in Europe and EPA formaldehyde standards in the United States are forcing material requalification across upholstered goods and wood substrates.
- Leather:Top-grain and full-grain hides with hand-finishing protocols define upholstery luxury positioning. ECHA REACH restrictions on chromium VI in leather tanning processes are accelerating supplier consolidation toward certified tanneries with disclosed chemical chains.
- Metal:Powder-coated steel and brass extrusions for modern frame constructions.
- Glass:Tempered and laminated surfaces for contemporary tabletops and display systems.
Certified wood commands current volume leadership. Leather faces the steepest compliance-driven transformation.
Design Style:
Application context determines which aesthetic codes dominate procurement specifications across contract and residential channels.
- Modern:Clean lines and material honesty drive metal and glass compositions that lead growth in commercial and hospitality end uses. Boutique hotel developers in experiential retail corridors specify these forms for lobby and amenity spaces.
- Minimalist:Reduced visual mass and functional purity attract urban residential buyers in Shanghai and Beijing seeking spatial efficiency.
- Vintage:Referential forms with patinated finishes and reproduced hardware details.
- Rustic:Reclaimed timber and hand-forged metal accents for lodge and resort environments.
Modern styling captures hospitality momentum. Minimalist approaches are gaining share fastest in Asia-Pacific residential specification.
End User:
Customer type segmentation reveals where ISO 9001 certification and contract durability ratings create market access barriers.
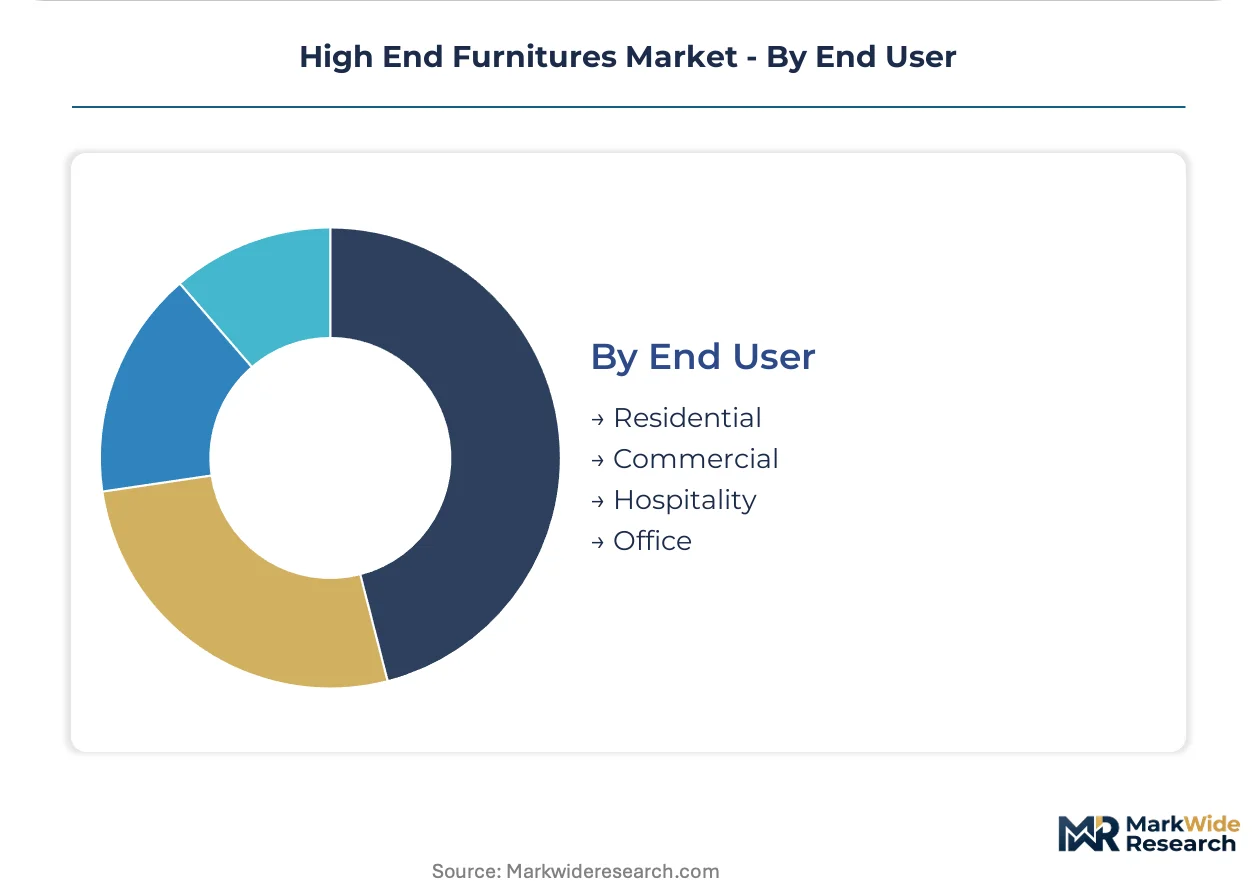
- Hospitality:Boutique hotel development and experiential retail concepts represent the fastest-expanding demand vertical. Design-forward chains in Dubai and Miami are expanding procurement of bespoke seating and case goods, creating sustained demand for artisanal production capacity with documented process controls.
- Residential:Affluent consumers in China's tier-one cities prioritize designer craftsmanship, driving whitespace for brands establishing direct retail presence outside established wholesale channels.
- Commercial:Corporate lobbies and executive suites requiring fire-rated upholstery and commercial-grade frame warranties.
- Office:Private office and conference room furnishings with ergonomic adjustability and technology integration.
Hospitality procurement sets the steepest growth trajectory. Residential channels retain the deepest volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Carolina's manufacturing corridor anchors artisanal upholstery capacity serving residential and contract channels. Boutique hospitality developers in Miami and Dubai are expanding procurement of bespoke seating and case goods. REACH chemical disclosure mandates in Europe and EPA formaldehyde standards in the United States are forcing material requalification across upholstered goods and wood substrates.
United States
Luxury residential developers in Miami and Los Angeles are driving specification volume for penthouse installations with bespoke dimensions. EPA formaldehyde emission standards and California Air Resources Board Phase 2 compliance requirements shape product specifications for wood-based materials. North Carolina manufacturing facilities reduce lead times for custom orders through domestic production flexibility.
China
Affluent consumers in Shanghai and Beijing are prioritizing designer craftsmanship, creating whitespace for brands establishing direct retail presence. The country's national environmental regulator enforces stricter chemical disclosure protocols for imported upholstered goods. Yangtze River Delta manufacturing clusters are expanding capacity for kiln-dried hardwood frame production serving domestic and export markets.
Germany
REACH Annex XVII expansions now mandate substance-of-very-high-concern disclosure throughout upholstery supply chains. ECHA restrictions on chromium VI in leather tanning processes are accelerating supplier consolidation toward certified tanneries. Bavarian craft workshops maintain hand-finishing protocols for leather upholstery serving contract hospitality procurement.
France
Paris-based ateliers anchor competitive positioning through maintained hand-finishing protocols for premium leather goods. ECHA REACH restrictions on chromium VI are driving sourcing transitions to vegetable-tanned alternatives ahead of enforcement deadlines. Île-de-France design houses concentrate specification influence for luxury residential and boutique hotel developments across European markets.
United Arab Emirates
Boutique hotel development and experiential retail concepts in Dubai represent the fastest-expanding demand vertical for artisanal production capacity. The country's national standards body aligns with emerging chemical disclosure mandates for imported furnishings. Dubai Design District clusters are attracting European and North American brands establishing regional showrooms and specification offices.
High End Furnitures Market Competitive Landscape
Global majors compete with regional champions across material sourcing and craft labor access. The vendor base organizes around three tiers: vertically integrated holding companies with captive mill relationships, Paris-based atelier networks preserving hand-finishing protocols, and North Carolina manufacturers competing on domestic production flexibility. Two dominant competitive moves are reshaping positioning: strategic partnerships with FSC-certified European forestry operations securing volume commitments, and geographic expansion into China's tier-one cities through direct retail presence outside established wholesale channels.
Among North Carolina-based manufacturers, Bernhardt occupies a position exemplifying domestic manufacturing flexibility with reduced lead times for custom residential orders. Within the European atelier tier, Roche Bobois represents the Paris-based craft labor model maintaining hand-finishing protocols for leather upholstery. At the scale-driven end, Restoration Hardware anchors vertically integrated sourcing through captive mill relationships securing FSC-certified oak and walnut at volume.
| Leading Market Players |
|---|
| Restoration Hardware (RH) |
| Roche Bobois |
| Century Furniture |
| Bernhardt |
| Baker Furniture |
| Knoll |
| Mitchell Gold + Bob Williams |
| Arhaus |
| Brown Jordan International |
| Others |
Pricing and Supply Chain Analysis
Captive mill relationships with European forestry operations anchor both supply security and pricing power for kiln-dried hardwood frames. Restoration Hardware's backward integration into FSC-certified oak sourcing insulates margin pools from certification gap risks that plague conventional procurement channels serving luxury residential developers in Miami and Dubai.
Pricing Analysis
Input-cost pass-through from tropical hardwood harvest restrictions in Southeast Asian source markets is compressing margin predictability for case goods producers. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified oak frames from conventional hardwoods and engineered composites. Pricing pressure stems from REACH chemical disclosure mandates elevating certification overhead for European market access. Boutique hospitality developers in Dubai exhibit the least price sensitivity due to experiential retail positioning, while mid-market residential channels in China's tier-two cities face acute cost compression.
Supply Chain Analysis
Dual-sourcing requirements from hotel operators now mandate multi-supplier qualification for leather upholstery and wood substrates alike. Manufacturing gravity draws from Italy, France, and North Carolina for hand-finishing protocols, domestic production flexibility, and artisanal craft labor pools. Raw material dependencies center on FSC-certified oak, top-grain leather hides, and kiln-dried hardwood frames. Single-source vulnerability concentrates in Paris-based atelier capacity for eight-way hand-tied spring suspension. Distribution runs through direct retail showrooms in Shanghai and Beijing alongside traditional wholesale channels serving contract hospitality procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high end furnitures market reads as a late-cycle quality story justified by affluent consumers in China's tier-one cities prioritizing designer craftsmanship over mass-market alternatives. This demand-shift toward premium specifications rewards manufacturers with documented process controls and certified supply chains.
For Market Incumbents: Anticipate substitution threats from high-performance engineered composites by deepening captive sourcing relationships with European forestry operations. Invest in ISO 9001 certification ahead of contract hospitality procurement thresholds. Secure Paris-based craft labor pools through apprenticeship programs addressing the eight-way hand-tying skill gap before workforce aging constrains production scaling. For New Entrants and Emerging Players: Capture whitespace in China's tier-one cities through digital-first engagement models with centralized North American manufacturing fulfillment. Target Shanghai and Beijing residential channels where direct retail presence outside established wholesale channels remains underdeveloped. Lead with real-time customization interfaces converging with compressed lead time capabilities. For Investors and Strategic Acquirers: Roll-up economics work for North Carolina-based manufacturers with domestic production flexibility because fragmented craft labor access creates scarcity value for scaled operators. Five-to-ten year viability hinges on multi-jurisdiction compliance infrastructure. Monitor ECHA REACH enforcement timelines as the inflection indicator for supplier consolidation velocity across European upholstery supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Sourcing Partnership | FSC-certified European mill relationships secure volume commitments for kiln-dried hardwood frames. |
| Digital Configuration Platform | Real-time customization interfaces compress lead times for made-to-order residential specifications. |
| ISO 9001 Certification Investment | Quality management documentation unlocks contract hospitality procurement from boutique hotel chains. |
| Vegetable-Tanned Leather Transition | ECHA REACH chromium VI restrictions accelerate sourcing shifts ahead of enforcement deadlines. |
| China Direct Retail Expansion | Showroom footprints in Shanghai and Beijing bypass wholesale margin extraction from established channels. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged furniture manufacturing executives, leather tannery procurement leads, boutique hotel development directors, North Carolina craft workshop supervisors, and China's tier-one city retail operators. Secondary validation drew from EPA emission standard filings, ECHA REACH substance databases, FSC chain-of-custody audits, and customs trade records for tropical hardwood imports. Bottom-up production capacity estimates and top-down demand segmentation triangulated volume and value outputs.
Comparable-period anchoring linked historical reference frames to forward projection horizons across the analysis window. Segmentation modeling incorporated product type, material certification tier, design style application, and end-user channel dynamics. CAGRs derived from trend extrapolation against substitution elasticity parameters for engineered composites. Forecast inputs included artisanal craft labor replenishment rates and multi-jurisdiction chemical disclosure mandate implementation timelines.
Regulatory enforcement delays, tropical hardwood harvest restriction expansions, and boutique hospitality development financing conditions are the dominant revision risks. Deviation in ECHA REACH substance-of-very-high-concern disclosure scope would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Global Furniture Fittings Market
Furniture
Metal Furniture Market
Furniture
Europe School Furniture Market
Furniture
HORECA Furniture Market
Furniture
Japan Home Furniture Market
Furniture
US Sustainable Furniture Market
Furniture
Canada Home Furniture Market
Furniture
Children Furniture Market
Furniture
GCC Multifunctional Furniture Market
Furniture
Europe High-End Furniture Market
Furniture
UAE Luxury Furniture Market
Furniture
United Kingdom Kitchen Furniture Market
Furniture
Europe Upholstered Furniture Market
Furniture
Global Furniture Market
Furniture
Global Multifunctional Furniture Market
Furniture
Kids Table and Chair Market