
 Global Lipid Testing Market | 2026-2036
Global Lipid Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lipid Testing Market Intelligence
Project finance for decentralized diagnostic networks is tilting competitive dynamics toward asset-light operators that can scale without capital-intensive lab buildouts. Quest Diagnostics leverages its national logistics footprint to sustain same-day lipid panel turnaround across non-urban catchments. Thermo Fisher Scientific anchors its position through captive reagent supply chains that limit third-party dependency. Abbott Laboratories differentiates via handheld analyzer platforms that occupy the point-of-care channel with minimal technician training requirements.
Lipid testing comprises quantitative biochemical analysis of blood-derived cholesterol fractions, triglycerides, and lipoprotein subclasses using enzymatic, spectroscopic, or chromatographic methods with clinical decision thresholds typically set at LDL-C greater than 190 mg/dL for high-risk stratification. The enzymatic assay segment dominates routine clinical volume due to cost efficiency and CLIA compatibility, while mass spectrometry applications expand in research settings where lipoprotein particle quantification demands higher analytical resolution. Among end users, clinical laboratories control the majority value pool through high-throughput automation, whereas preventive care facilities represent the fastest-growing channel as employer wellness programs and direct-to-consumer screening models gain traction.
The FDA regulates in vitro diagnostic devices under 21 CFR Part 820 quality system requirements, while CLIA establishes personnel and proficiency standards that shape laboratory accreditation and test complexity classification. The EU In Vitro Diagnostic Regulation transitions legacy CE-marked assays toward strengthened clinical evidence requirements, compressing timelines for market access renewals across European member states. ISO 15189 medical laboratory accreditation frameworks in Japan and South Korea harmonize cross-border quality benchmarks for reference laboratories serving regional clinical trial networks. Stakeholders must monitor evolving payer coverage determinations for advanced lipid phenotyping versus standard panel reimbursement to align R&D portfolios with commercially viable test menus.
Market Dynamics
Point-of-care lipid testing is compressing the diagnostic value chain as hospital emergency departments demand sub-15-minute turnaround times for cardiac triage panels. This velocity requirement is restructuring procurement patterns toward handheld analyzer platforms and CLIA-waived test cartridges that bypass centralized laboratory workflows.
Growth Catalysts
- Medicare preventive screening expansion:The United States reimbursement framework for cardiovascular risk assessment is widening eligible patient populations and driving volume in physician office laboratories.
- Enzymatic assay automation:High-throughput clinical laboratories are integrating robotic liquid handling systems that reduce per-test labor costs and enable 24-hour processing windows.
- Employer wellness program mandates:Large self-insured employers in Germany and Japan are contracting direct-to-consumer lipid screening as a condition of premium tiering.
Market Restraints
- Reagent supply concentration:Captive enzyme production for HDL-C and LDL-C assays concentrates among three European chemical suppliers, creating input vulnerability.
- Mass spectrometry capital intensity:Lipoprotein particle quantification requires $300,000-plus instrument platforms that limit adoption to academic medical centers.
- EU IVDR transition friction:The In Vitro Diagnostic Regulation's strengthened clinical evidence requirements are compressing timelines for legacy assay renewals across European member states.
Strategic Opportunities
- Direct-to-consumer channel formation:Pharmacy retail chains in the United Kingdom are deploying self-service lipid kiosks with telemedicine result consultation.
- At-home fingerstick integration:Consumer diagnostics platforms are converging with smartphone-connected photometric readers for cholesterol panel quantification.
- India preventive health mandates:Corporate health screening obligations under expanding insurance regulations are creating volume for decentralized testing networks.
Industry Challenges
- CLIA personnel certification bottlenecks:Moderate-complexity testing site expansion is constrained by qualified laboratory director availability in rural catchments.
- LIS integration complexity:Point-of-care analyzers require HL7 FHIR-compliant middleware development to synchronize with legacy hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lipid Testing Market |
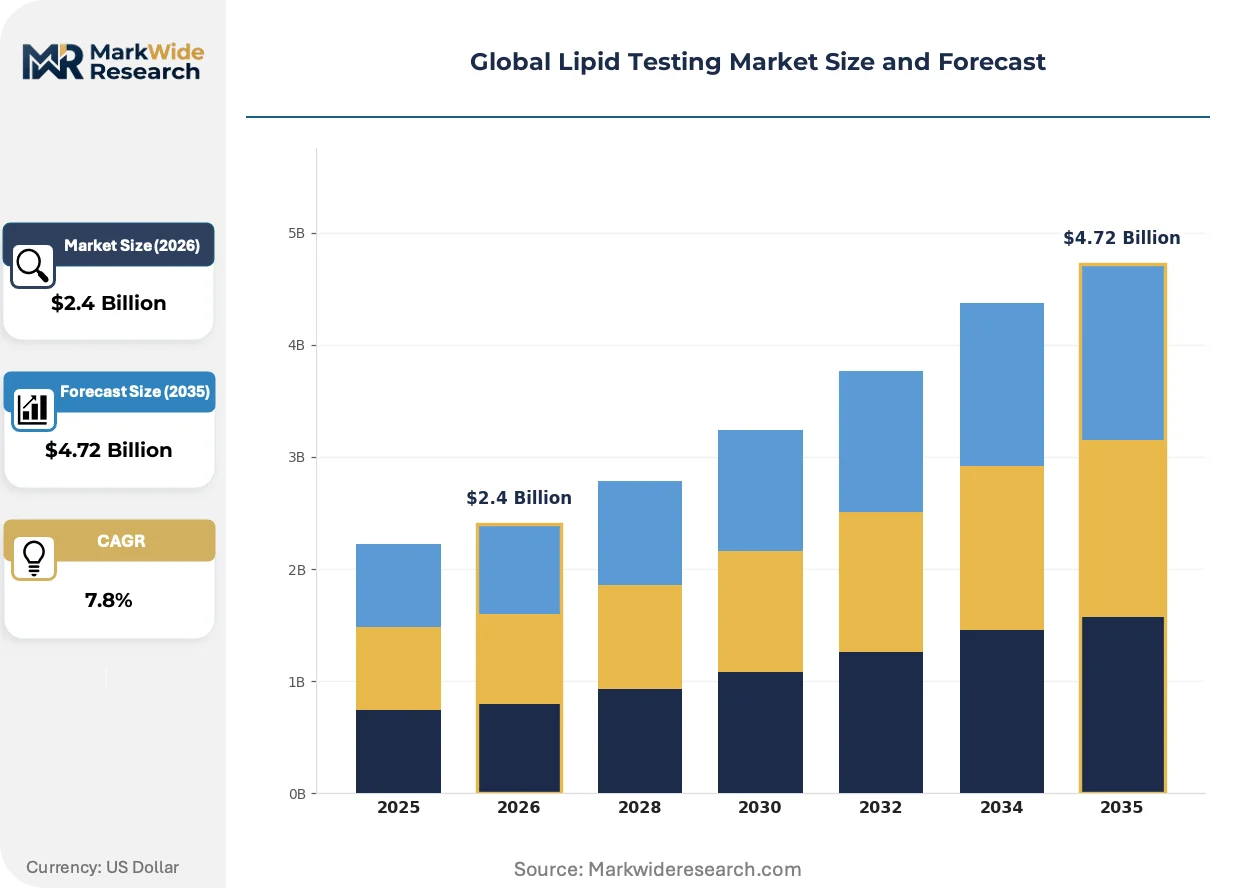
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Lipid Panel, LDL Cholesterol Test, HDL Cholesterol Test, Triglycerides Test, Total Cholesterol Test Technology: Enzymatic Assay, Nuclear Magnetic Resonance, Mass Spectrometry, Colorimetric Assay, Fluorescence Spectroscopy Application: Cardiovascular Risk Assessment, Diabetes Management, Obesity Monitoring, Metabolic Syndrome Detection, Nutritional Evaluation End User: Clinical Laboratories, Diagnostic Centers, Research Institutes, Preventive Care Facilities, Blood Banks |
| Companies Covered | Abbott Laboratories, Quest Diagnostics, F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific Inc., Beckman Coulter Inc., Randox Laboratories Ltd., Siemens Healthcare GmbH, Bio-Rad Laboratories Inc., Nova Biomedical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lipid Testing Market Strategic Shifts & Innovations
Lipid testing modalities are bifurcating between velocity-optimized point-of-care platforms and resolution-optimized research-grade systems. This divergence is fragmenting vendor R&D portfolios and creating distinct competitive arenas with incompatible technical specifications.
Nuclear magnetic resonance spectroscopy is migrating from research laboratories into specialty clinical reference settings for lipoprotein subclass quantification. Cardiology practices in the United States are adopting NMR-derived particle number metrics for residual risk stratification. The technology is migrating from academic publication into guideline-influenced clinical decision-making, compressing the validation timeline for novel biomarkers.
The FDA's CLIA waiver expansion for moderate-complexity tests is broadening test site eligibility beyond hospital laboratories. This regulatory pathway is enabling pharmacy chains and urgent care networks to offer lipid panels without full laboratory accreditation. The United States preventive care infrastructure is responding with point-of-care device procurement programs that bypass traditional laboratory service agreements.
Employer-sponsored screening contracts are consolidating procurement authority among benefits administrators rather than individual physicians. Large self-insured plans in the United States are negotiating direct pricing with diagnostic platforms and disintermediating hospital outreach laboratories. This purchasing concentration is most visible in manufacturing and logistics sectors with distributed workforces requiring mobile testing deployment.
Global Lipid Testing Market Segmentation
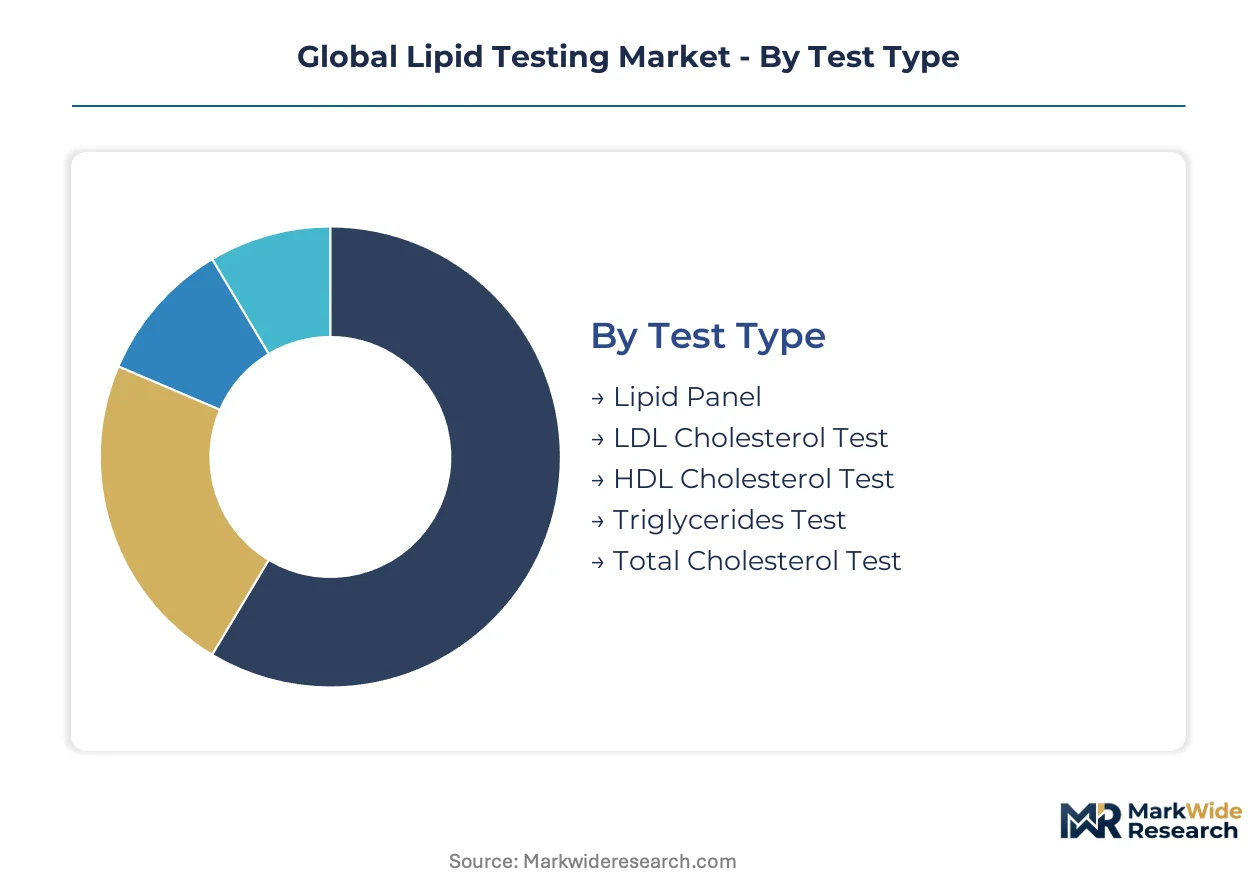
Lipid testing market segmentation reveals distinct technology maturity curves and channel economics that shape vendor R&D allocation. Test type and end-user configuration determine reimbursement pathways, while technology choice governs capital deployment intensity.
Test Type:
Application volume concentrates in preventive screening protocols and acute cardiac triage workflows.
- Lipid Panel:Comprehensive quantification of total cholesterol, LDL-C, HDL-C, and triglycerides in a single analytical run. Hospital emergency departments in the United States drive procurement for sub-15-minute turnaround requirements under Medicare reimbursement frameworks.
- LDL Cholesterol Test:Direct measurement of low-density lipoprotein cholesterol using selective detergent or homogeneous assay methods. Cardiology practices in Germany specify this test for residual risk stratification in statin-treated patients with discordant non-HDL metrics.
- HDL Cholesterol Test:Quantification of high-density lipoprotein cholesterol via selective precipitation or direct enzymatic clearance.
- Triglycerides Test:Enzymatic hydrolysis and colorimetric detection of serum triglyceride concentration.
- Total Cholesterol Test:Single-analyte screening assay deployed in employer wellness programs and pharmacy retail kiosks.
Lipid panels command the established base. The steepest expansion runs through LDL cholesterol direct measurement assays.
Technology:
Capital intensity and analytical resolution define competitive positioning across the technology spectrum.
- Enzymatic Assay:Clinical chemistry platforms using cholesterol esterase and oxidase cascade reactions with spectrophotometric endpoint detection. High-throughput laboratories in Japan deploy these systems for 24-hour processing windows under ISO 15189 accreditation frameworks.
- Nuclear Magnetic Resonance:Spectroscopic quantification of lipoprotein particle size and subclass distribution. Academic medical centers in the United States adopt NMR platforms for guideline-influenced residual risk assessment.
- Mass Spectrometry:Chromatographic separation with tandem mass detection for research-grade lipoprotein phenotyping.
- Colorimetric Assay:Simplified photometric detection for point-of-care and resource-limited settings.
- Fluorescence Spectroscopy:Enhanced sensitivity detection for low-volume sample analysis in pediatric and geriatric populations.
Enzymatic assays anchor routine clinical volume. NMR spectroscopy gains share fastest in specialty reference settings.
Application:
Clinical utility and reimbursement coding determine addressable market size per application segment.
- Cardiovascular Risk Assessment:Population-level screening and individual risk stratification using Framingham or pooled cohort equations. Physician office laboratories in the United States process volume under expanded Medicare preventive service codes.
- Diabetes Management:Integrated lipid monitoring alongside HbA1c for diabetic dyslipidemia surveillance. Endocrinology clinics in India specify quarterly lipid panels under corporate health screening mandates.
- Obesity Monitoring:Bariatric surgery preoperative evaluation and postoperative metabolic tracking.
- Metabolic Syndrome Detection:Multi-criteria screening combining lipid abnormalities with glucose and blood pressure thresholds.
- Nutritional Evaluation:Lifestyle intervention monitoring in employer wellness and direct-to-consumer channels.
Cardiovascular risk assessment generates the dominant procedure volume. Diabetes-integrated monitoring climbs the fastest as comorbidity management protocols tighten.
End User:
Channel economics and accreditation requirements fragment procurement authority across site types.
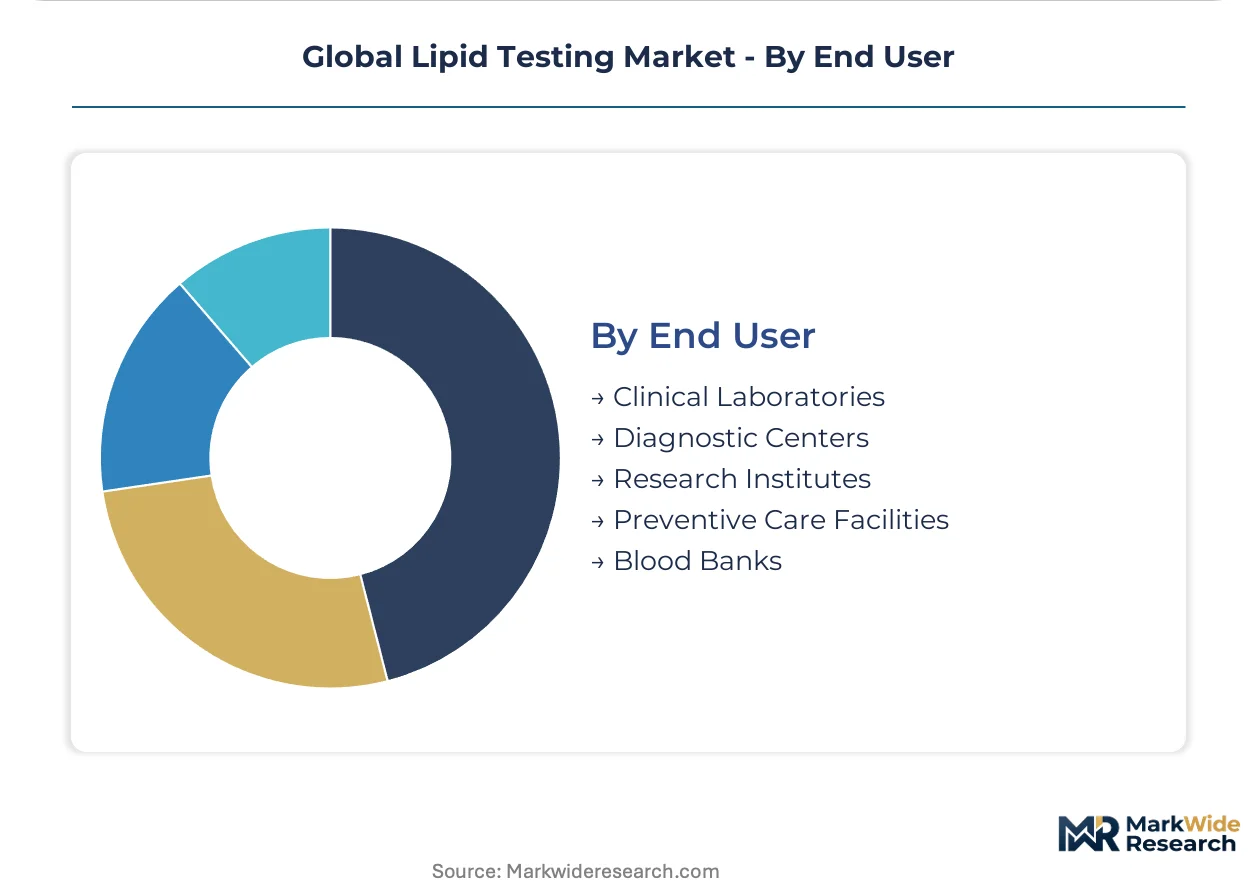
- Clinical Laboratories:High-throughput automated platforms serving hospital systems and outpatient networks. National laboratory chains in the United States sustain same-day turnaround across non-urban catchments through centralized logistics infrastructure.
- Diagnostic Centers:Decentralized testing sites with moderate-complexity CLIA certification. Urgent care networks in the United Kingdom deploy these facilities for employer contract fulfillment.
- Research Institutes:Academic and pharmaceutical trial laboratories requiring advanced lipoprotein phenotyping.
- Preventive Care Facilities:Employer on-site clinics and wellness program contractors.
- Blood Banks:Donor screening and component qualification testing.
Clinical laboratories retain the volume concentration. Preventive care facilities expand most quickly as benefits administrators consolidate procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The lipid testing trade flows through distinct national regulatory corridors, with reagent and instrument exports clustering in jurisdictions with harmonized quality certifications. Import dependence concentrates in markets where decentralized testing infrastructure outpaces domestic manufacturing capacity.
United States
Medicare preventive screening expansions drive volume in physician office laboratories and urgent care networks. The FDA's CLIA waiver pathway for moderate-complexity tests enables pharmacy chains to offer lipid panels without full laboratory accreditation. The Boston-Cambridge corridor anchors NMR spectroscopy adoption for residual risk stratification in cardiology practices.
Germany
Self-insured employer mandates for workforce lipid screening create procurement concentration among benefits administrators. The EU In Vitro Diagnostic Regulation compresses timelines for legacy assay renewals across member states. The Rhine-Ruhr industrial belt hosts centralized clinical laboratories processing high-throughput enzymatic panels for regional hospital networks.
Japan
ISO 15189 accreditation frameworks harmonize quality benchmarks for reference laboratories serving regional clinical trial networks. METI guidelines shape point-of-care device procurement for corporate health screening programs. The Kanto region around Tokyo sustains 24-hour automated processing windows under stringent proficiency standards.
India
Corporate health screening obligations under expanding insurance regulations generate volume for decentralized testing networks. CDSCO oversight of in vitro diagnostic imports shapes supply chain configuration for enzyme reagents. The Mumbai-Pune corridor concentrates diagnostic center expansion serving manufacturing sector wellness mandates.
United Kingdom
Pharmacy retail chains deploy self-service lipid kiosks with telemedicine result consultation for direct-to-consumer channels. NHS England coverage determinations for advanced lipid phenotyping versus standard panels influence R&D portfolio alignment. The Greater London area anchors employer-sponsored screening contract consolidation among benefits administrators.
Global Lipid Testing Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in reagent and consumable supply. The lipid testing vendor base organizes around three archetypes: multinational diagnostics conglomerates with captive logistics networks, specialized clinical chemistry firms with enzyme production capabilities, and point-of-care device manufacturers with handheld analyzer platforms. Consolidation pressure runs through strategic partnerships between instrument makers and reagent suppliers, while geographic expansion targets preventive care facilities in employer wellness channels.
Among the multinational tier, Abbott Laboratories and Quest Diagnostics exemplify divergent scale strategies. Abbott Laboratories occupies a position within the point-of-care channel through handheld analyzer platforms requiring minimal technician training. Quest Diagnostics anchors the centralized laboratory vector, leveraging logistics infrastructure to sustain turnaround advantages across distributed catchments. Thermo Fisher Scientific sits within the reagent supply archetype, limiting third-party dependency through captive production chains. These three entities represent the dominant competitive anchors shaping procurement patterns across hospital, physician office, and direct-to-consumer channels.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Quest Diagnostics |
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific Inc. |
| Beckman Coulter Inc. |
| Randox Laboratories Ltd. |
| Siemens Healthcare GmbH |
| Bio-Rad Laboratories Inc. |
| Nova Biomedical Corporation |
| Others |
Cost & Logistics Intelligence
The Rhine-Alpine freight corridor links enzyme reagent production in Germany to clinical laboratory networks across Western Europe, with transport cost volatility feeding directly into both supply concentration among three European chemical suppliers and downstream price stratification between high-throughput hospital systems and decentralized point-of-care sites.
Pricing Analysis
Hospital laboratory procurement teams anchor contract-based long-term offtake structures for enzymatic assay reagents, with price differentiation driven by ISO 15189 certification tier and annual test volume commitments. Cost compression in the point-of-care segment is intensifying because CLIA-waived cartridge manufacturers compete for pharmacy chain shelf space. Self-insured employers exhibit the lowest price sensitivity due to wellness program budget insulation, while independent diagnostic centers face acute margin pressure from Medicare reimbursement rate compression.
Supply Chain Analysis
Upstreamesterase and oxidase feedstocks draw from biochemical manufacturing clusters in Germany, the Netherlands, and Switzerland, with cholesterol esterase production resting on porcine pancreas sourcing and recombinant microbial fermentation inputs. Single-source vulnerability concentrates in lipoprotein-specific detergent formulations for direct LDL-C measurement. Distribution runs through captive reagent supply chains at Thermo Fisher Scientific and third-party chemical distributors serving mid-size clinical laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lipid testing market is positioned for cyclical recovery as Medicare preventive screening expansions normalize post-pandemic testing backlogs and employer wellness mandates institutionalize annual cardiovascular risk assessment protocols.
For Market Incumbents: Insulate reagent margins through backward integration into enzyme production capabilities, particularly for HDL-C and LDL-C assay components where European chemical supplier concentration creates input vulnerability. Secure CLIA-waived cartridge supply agreements with urgent care networks before pharmacy retail chains consolidate procurement authority under benefits administrators. For New Entrants and Emerging Players: Pursue white-space opportunities in at-home fingerstick integration with smartphone-connected photometric readers, where consumer diagnostics platforms remain underdeveloped relative to clinical laboratory saturation. Target India's corporate health screening obligations under expanding insurance regulations, deploying decentralized testing networks through diagnostic center partnerships rather than capital-intensive laboratory buildouts. For Investors and Strategic Acquirers: The EU IVDR transition reshapes the acquisition landscape by compressing timelines for legacy assay renewals and elevating clinical evidence requirements that favor established players with regulatory affairs infrastructure. Focus on point-of-care device manufacturers with handheld analyzer platforms and existing FDA 510(k) clearances, monitoring CDSCO import oversight changes as a signal for Indian market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Waiver Pathway Expansion | Enables pharmacy chains to offer lipid panels without full laboratory accreditation under FDA oversight. |
| Reagent Supply Chain Captive Integration | Limits third-party dependency for enzyme production and insulates against European supplier concentration. |
| Point-of-Care Device Miniaturization | Reduces technician training requirements and accelerates deployment in urgent care networks. |
| Employer Wellness Contract Direct Negotiation | Disintermediates hospital outreach laboratories and consolidates procurement authority among benefits administrators. |
| NMR Spectroscopy Clinical Validation | Migrates lipoprotein particle quantification from academic settings into guideline-influenced cardiology practice. |
Research Approach
A spread of perspectives from clinical laboratory directors, point-of-care device product managers, hospital purchasing committee members, and reagent supply chain managers converged on the working assumptions, validated against FDA 510(k) filings, CMS Medicare reimbursement databases, EU IVDR technical documentation, and ISO 15189 accreditation records through bottom-up and top-down triangulation.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by test type, technology platform, end-user channel, and regional regulatory cluster. CAGRs were derived from volume trajectory analysis and pricing elasticity assessments, incorporating enzymatic assay automation adoption curves and NMR spectroscopy penetration rates in academic medical centers as industry-specific forecast inputs.
Sensitivities concentrate around Medicare reimbursement rate revisions, EU IVDR transition timelines, and CLIA personnel certification availability in rural catchments. Forecasts reflect assumptions about preventive screening expansion continuity and employer wellness program durability. Material shifts in FDA CLIA waiver policy or CDSCO import regulations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Global Dairy Testing Market
Food Safety Testing
Global Inline Metal Detector Market
Food Safety Testing
Meat Species Identification Kits Market
Food Safety Testing
Global Bacteriological Testing Market
Food Safety Testing
Mycotoxin Testing Market
Food Safety Testing
Global Food Authenticity Testing Market
Food Safety Testing
UAE Product Testing Lab Services Market
Food Safety Testing
Fruit & Vegetable Wash Market
Food Safety Testing
Food Traceability Solutions Market
Food Safety Testing
Global Meat Speciation Testing Market
Food Safety Testing
Animal Feed Safety Testing Equipment Market
Food Safety Testing
Food Testing Kits Market
Food Safety Testing
Food Allergens and Intolerance Testing Market
Food Safety Testing
Italy Food Safety Testing Market
Food Safety Testing
High-Throughput Food Allergen Screening Test Instruments Market
Food Safety Testing
Inline Beverage Gas and Microbial Load Monitoring Test Systems Market