
 Bottled Water Testing Equipment Market | 2026-2036
Bottled Water Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Bottled Water Testing Equipment Market Analysis
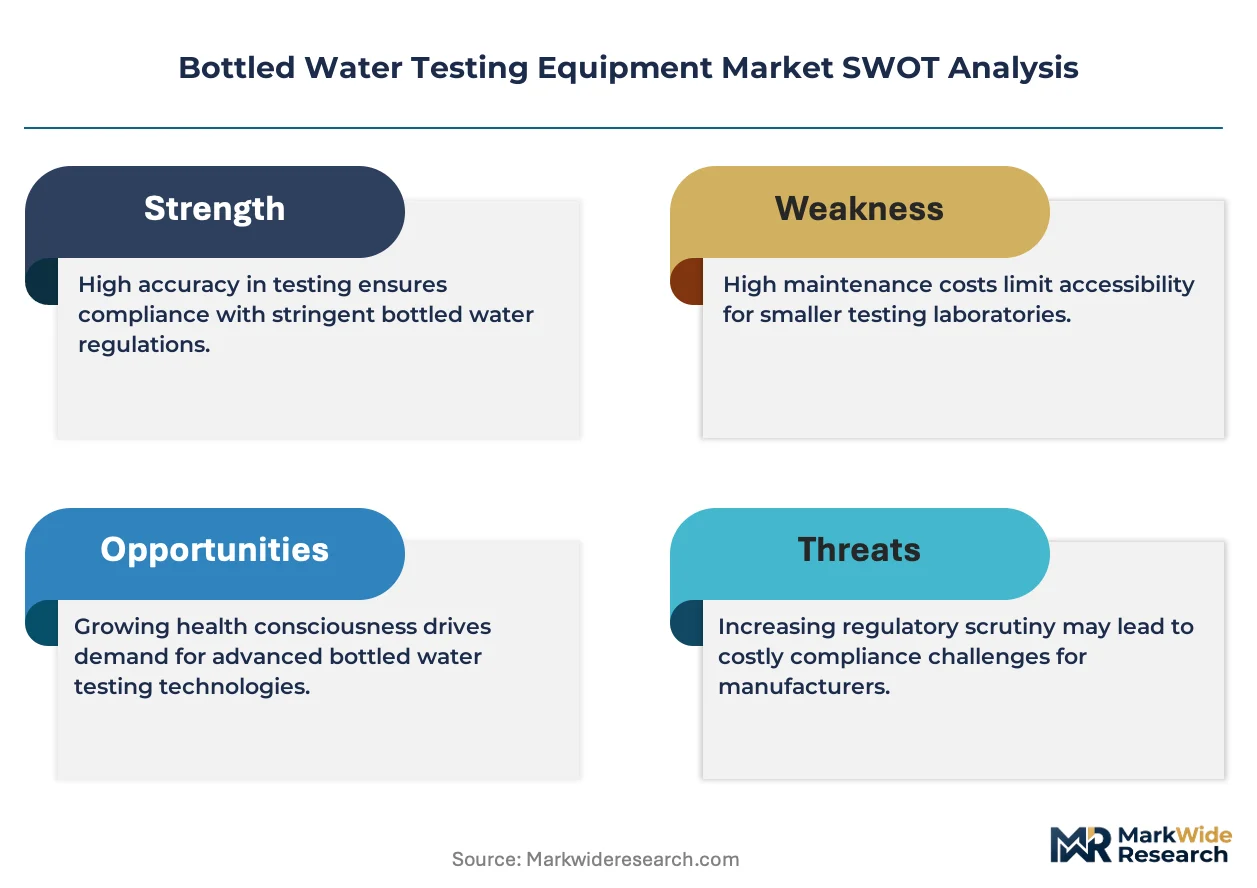
Quality control labs are unwinding reliance on beverage manufacturers' in-house testing, as third-party verification gains share across the bottled water supply chain. Thermo Fisher Scientific leverages its chromatography portfolio to anchor high-throughput contaminant screening workflows. Waters Corporation sustains dominance in mass spectrometry detection for trace pharmaceutical residues. Metrohm AG specializes in electrochemical titration systems that beverage producers deploy for rapid mineral content verification.
Bottled water testing equipment comprises analytical instrumentation designed to detect microbiological, chemical, and physical contaminants in packaged drinking water, with sensitivity thresholds typically reaching parts-per-billion for heavy metals and single-colony-forming-unit detection for pathogens. Laboratory equipment occupies the largest installed base due to regulatory mandate for centralized verification, while portable test kits represent the fastest-expanding category as field audits intensify under decentralized quality programs. Chromatography systems command premium positioning because multi-residue pesticide analysis requires separation precision that optical methods cannot replicate.
The US FDA enforces bottled water quality standards under 21 CFR 165.110, while the EPA administers contaminant monitoring protocols that directly shape equipment specification requirements for domestic producers. EU Drinking Water Directive recasts and REACH compliance obligations in Europe force manufacturers to validate detection capabilities against expanding chemical candidate lists. Stakeholders must weigh capital allocation between laboratory centralization and distributed sensor networks as enforcement patterns diverge across regulatory jurisdictions.
Market Dynamics
Automated microbiological detection systems are compressing turnaround times from days to hours, forcing quality control labs to retire legacy culture-based methods or surrender contract volume to faster competitors.
Growth Catalysts
- EU Drinking Water Directive recast:The expanded chemical candidate list mandates validation against emerging contaminants, compelling German and French laboratories to upgrade chromatography capacity.
- Portable electrochemical sensors:Field audit intensification under decentralized quality programs is accelerating deployment of handheld mineral verification units at bottling plants.
- Third-party verification mandates:Retailers and foodservice distributors now require independent testing documentation, diverting volume from in-house laboratories to external service providers.
Market Restraints
- Helium supply volatility:Gas chromatography systems depend on helium carrier gas, and price spikes from Qatar and US export constraints squeeze operating margins for pesticide residue screening.
- Reference material scarcity:Certified reference standards for novel per- and polyfluoroalkyl substances remain unavailable, blocking validation of detection protocols required by EPA monitoring rules.
- Optical method limitations:UV-Vis spectroscopy cannot achieve parts-per-billion sensitivity for heavy metals, forcing capital-intensive upgrades to atomic absorption or ICP-MS platforms.
Strategic Opportunities
- India packaged water expansion:FSSAI enforcement of IS 14543 standards in tier-2 cities creates instrumentation demand where laboratory infrastructure remains underdeveloped.
- Real-time sensor networks:Integration of IoT-enabled turbidity and conductivity probes with cloud-based quality management systems enables continuous monitoring at remote bottling sites.
- REACH compliance services:European beverage exporters require documentation support for substance registration, opening recurring revenue streams for testing laboratories beyond equipment sales.
Industry Challenges
- Metrologist recruitment bottlenecks:Specialized expertise in mass spectrometry method development commands premium salaries, constraining laboratory expansion timelines.
- ISO 17025 accreditation delays:Backlogs at national accreditation bodies extend certification timelines, freezing contract eligibility for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bottled Water Testing Equipment Market |
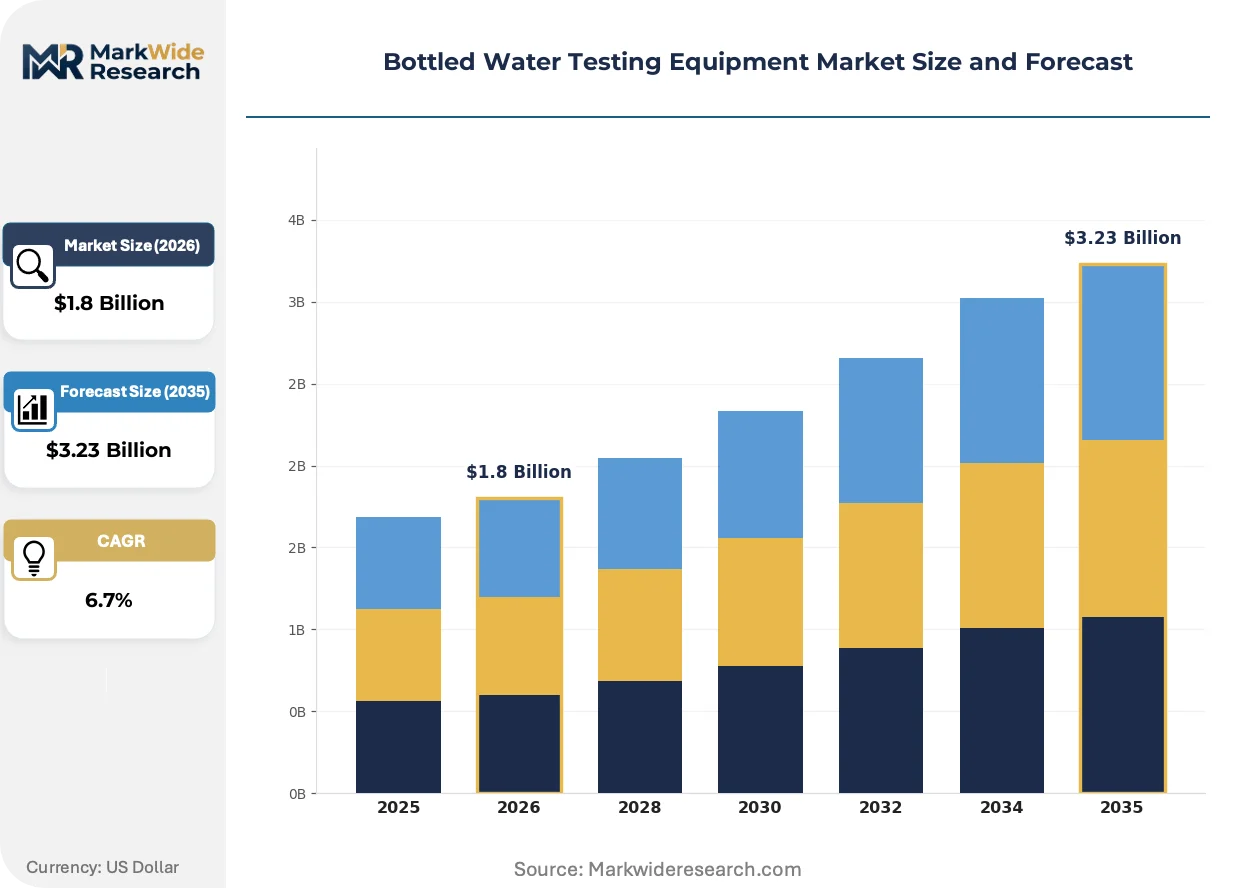
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Test Kits, Laboratory Equipment, Water Quality Sensors, Analyzers Technology: Electrochemical, Optical, Spectroscopy, Chromatography End User: Beverage Manufacturers, Quality Control Labs, Environmental Agencies, Research Institutions Application: Contaminant Detection, Quality Assurance, Regulatory Compliance, Research & Development |
| Companies Covered | Thermo Fisher Scientific Inc., Agilent Technologies Inc., Waters Corporation, Bio-Rad Laboratories Inc., Shimadzu Corporation, PerkinElmer Inc., Merck KGaA, Mettler-Toledo International Inc., Metrohm AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bottled Water Testing Equipment Market Emerging Trajectories
Digital PCR platforms are fragmenting the microbiological testing value chain, enabling direct pathogen quantification without enrichment culture steps and threatening incumbent optical detection suppliers.
Raman spectroscopy handheld units are decomposing the centralized laboratory model for mineral content verification. Mid-sized bottlers in Italy and Spain now deploy these devices at receiving docks to validate supplier certificates of analysis within minutes rather than days. The technology is decomposing the traditional separation between production-floor quality checks and laboratory confirmation, compressing decision cycles and reducing sample logistics costs.
EPA Safe Drinking Water Act amendments are tightening monitoring frequencies for disinfection byproducts. Municipal water suppliers serving as source inputs for bottled water producers must now document quarterly rather than annual testing, cascading equipment procurement requirements to contract laboratories. California and Texas bottlers face the steepest compliance ramps, driving demand for automated sample preparation systems.
Service unbundling is fragmenting traditional equipment procurement patterns. German and Austrian quality control laboratories now lease chromatography systems with embedded consumables and method support, converting capital expenditure to operational budgets. This shift concentrates vendor relationships with full-service providers and marginalizes pure-hardware distributors unable to deliver application expertise.
Bottled Water Testing Equipment Market Segmentation
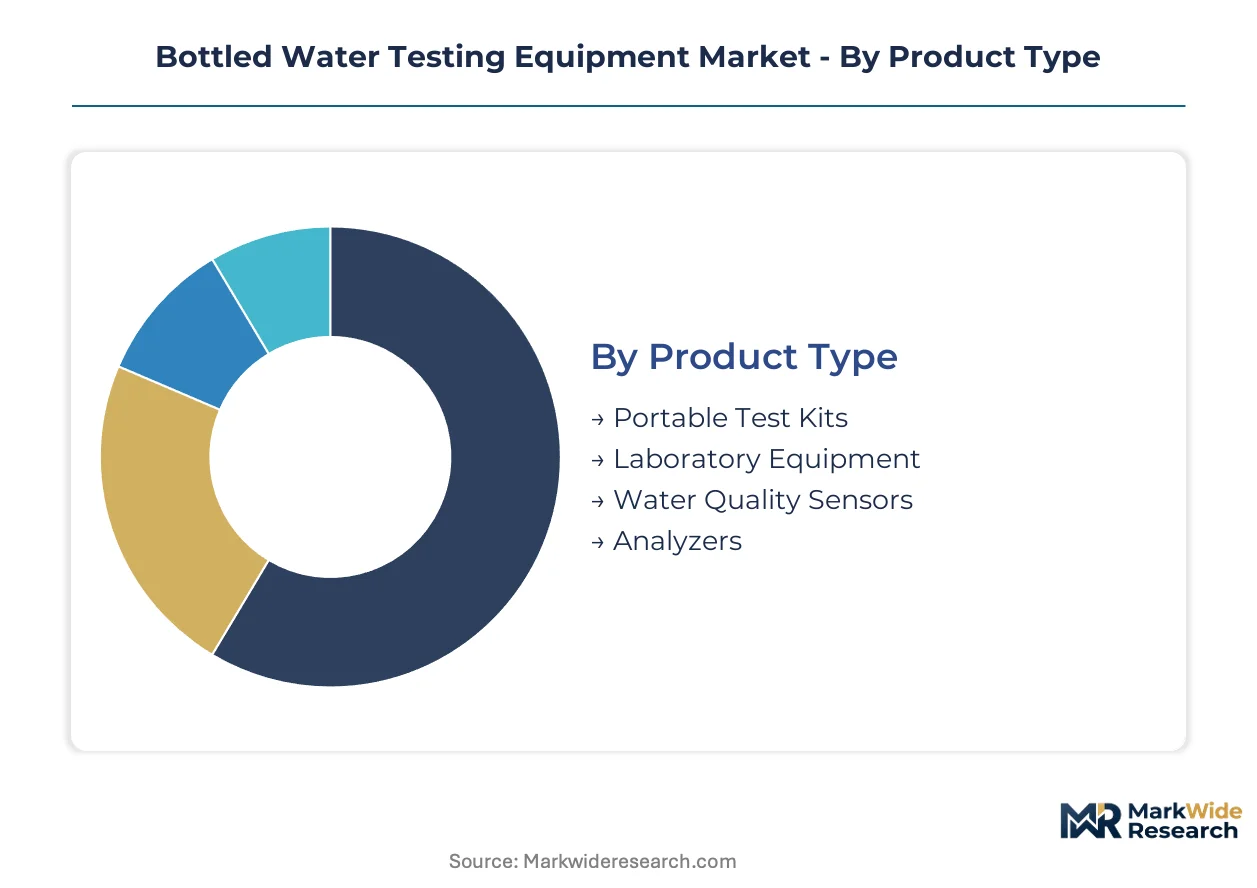
Equipment segmentation in bottled water testing reflects divergent capital deployment strategies between centralized laboratories and distributed production facilities. Margin pools concentrate where regulatory complexity intersects with high-throughput requirements.
Product Type:
Laboratory equipment commands premium pricing through validation workflows that centralized facilities cannot circumvent, while portable formats capture volume expansion in field audit protocols.
- Laboratory Equipment:Chromatography systems, mass spectrometers, and automated microbiology platforms occupy fixed installations where ISO 17025 accreditation mandates centralized confirmation. German quality control laboratories anchor demand as EU Drinking Water Directive enforcement tightens mineral water verification requirements. Capital intensity and method validation timelines protect incumbent positions.
- Portable Test Kits:Handheld electrochemical sensors and colorimetric assay kits enable rapid mineral content screening at bottling plant receiving docks. Italian and Spanish mid-sized producers deploy these units to compress supplier certificate validation from days to minutes. Field audit intensification under decentralized quality programs accelerates procurement.
- Water Quality Sensors:IoT-enabled turbidity and conductivity probes integrate with cloud-based quality management for continuous remote monitoring.
- Analyzers:Benchtop multi-parameter instruments serve smaller laboratories balancing throughput constraints against capital budgets.
Laboratory equipment holds the dominant share, while portable test kits are gaining share fastest.
Technology:
Technology selection tracks contaminant specificity requirements, with separation-based methods securing pricing power where optical detection thresholds prove inadequate.
- Chromatography:Gas and liquid chromatography systems achieve multi-residue pesticide separation precision that regulatory mandates require. Helium carrier gas dependency exposes operating margins to Qatar supply volatility, yet no alternative method matches detection specificity for trace pharmaceutical residues.
- Spectroscopy:Atomic absorption and ICP-MS platforms deliver parts-per-billion heavy metal sensitivity where UV-Vis methods fail. California and Texas bottlers drive procurement as EPA Safe Drinking Water Act amendments tighten disinfection byproduct monitoring frequencies.
- Electrochemical:Titration and potentiometric systems verify mineral content through rapid ion-selective measurement.
- Optical:Digital PCR and fluorescence-based platforms target pathogen detection with throughput advantages over culture-based alternatives.
Chromatography retains the largest revenue base, though spectroscopy is climbing the fastest on heavy metal compliance ramps.
End User:
Customer concentration shifts as third-party verification mandates redirect testing volume from beverage manufacturers toward independent service providers.
- Quality Control Labs:Independent testing facilities capture contract volume as retailers and foodservice distributors demand documentation beyond in-house capabilities. German instrumentation clusters concentrate here, serving both domestic mineral water traditions and export certification requirements.
- Beverage Manufacturers:In-house laboratories face capital efficiency pressures as service unbundling converts equipment procurement to operational leases.
- Environmental Agencies:Municipal water suppliers serving as bottled water source inputs require expanded monitoring under amended EPA protocols.
- Research Institutions:Academic and government laboratories develop validation methods for emerging contaminant classes.
Quality control labs command the dominant position, while environmental agencies are expanding most quickly on source water monitoring mandates.
Application:
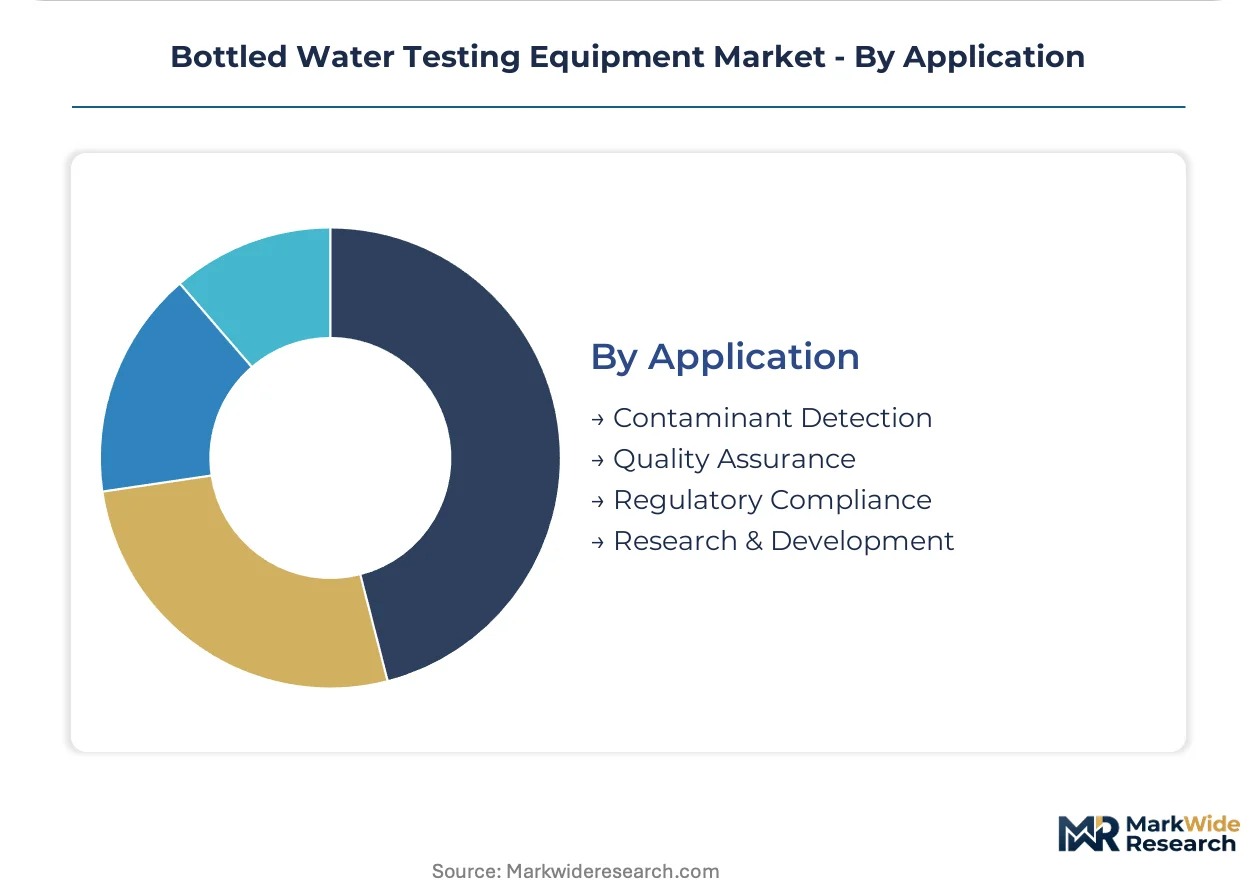
Application prioritization reflects enforcement sequencing, with compliance documentation preceding research investment in capital allocation hierarchies.
- Regulatory Compliance:Documentation requirements for FDA 21 CFR 165.110 and EU Drinking Water Directive recast anchor equipment specification. Automated sample preparation systems see steepest demand in jurisdictions with tightened monitoring frequencies.
- Contaminant Detection:Per- and polyfluoroalkyl substance protocols stall where certified reference standards remain unavailable.
- Quality Assurance:Real-time sensor networks enable continuous verification beyond batch sampling limitations.
- Research & Development:Method development for emerging chemical candidates occupies specialized laboratories ahead of regulatory adoption.
Regulatory compliance absorbs the dominant investment share, while quality assurance is expanding most quickly on continuous monitoring adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German mineral water exports flow across EU borders and into North American markets, driving instrumentation demand at both production sites and destination-country verification laboratories. Trade corridors link Italian bottling clusters to Middle Eastern retail distributors, requiring dual-jurisdiction compliance documentation.
United States
California and Texas bottlers face the steepest compliance ramps under amended EPA Safe Drinking Water Act monitoring frequencies for disinfection byproducts. FDA enforcement of 21 CFR 165.110 drives automated sample preparation procurement at contract laboratories in Los Angeles and Houston metropolitan clusters.
Germany
Mineral water traditions and EU Drinking Water Directive recast enforcement create dense instrumentation demand in Bavarian quality control laboratories. REACH compliance obligations force exporters to validate detection capabilities against expanding chemical candidate lists, concentrating chromatography system deployment around Munich and Stuttgart industrial zones.
India
FSSAI enforcement of IS 14543 standards in tier-2 cities generates instrumentation demand where laboratory infrastructure remains underdeveloped. Packaged water expansion in Maharashtra and Gujarat drives portable electrochemical sensor procurement for rapid mineral verification at bottling plant receiving docks.
Italy
Mid-sized producers deploy Raman spectroscopy handheld units at receiving docks to validate supplier certificates within minutes. Field audit intensification under decentralized quality programs accelerates procurement in Lombardy and Emilia-Romagna mineral water production clusters.
Spain
Decentralized quality programs and retailer third-party verification mandates redirect testing volume from in-house beverage manufacturer laboratories to independent service providers. Barcelona and Madrid metropolitan areas concentrate quality control laboratory accreditation activity under ISO 17025 protocols.
Bottled Water Testing Equipment Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and application expertise dimensions, producing a tiered structure where scale advantages meet specialized method development capabilities. Thermo Fisher Scientific and Agilent Technologies occupy positions with broad analytical portfolios, while Metrohm AG and Merck KGaA occupy narrower electrochemical and reagent niches. Strategic moves concentrate on service unbundling conversions from capital expenditure to operational lease models, and geographic expansion into underdeveloped laboratory infrastructure markets.
Among diversified analytical instrumentation conglomerates, Thermo Fisher Scientific Inc. and Agilent Technologies Inc. exemplify the full-service archetype bundling hardware with embedded consumables and method support. Waters Corporation occupies a position representing mass spectrometry specialization for trace contaminant detection. These three anchors demonstrate how vendor relationships concentrate with providers capable of delivering application expertise alongside equipment platforms.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Agilent Technologies Inc. |
| Waters Corporation |
| Bio-Rad Laboratories Inc. |
| Shimadzu Corporation |
| PerkinElmer Inc. |
| Merck KGaA |
| Mettler-Toledo International Inc. |
| Metrohm AG |
| Others |
Supply Flow & Price Mechanics
Helium-to-hydrogen carrier gas substitution in gas chromatography systems simultaneously redraws procurement geography toward Eastern European hydrogen suppliers and compresses operating margins for laboratories locked into legacy helium contracts. This input transition reshapes vendor pricing power as equipment manufacturers bundle hydrogen-ready retrofit kits into service agreements.
Pricing Analysis
Next-generation digital PCR platforms command 40-60% premiums over prior-generation culture-based microbiology systems, while automated sample preparation modules sit in a mid-tier pricing band. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17025-accredited laboratories from in-house beverage manufacturer labs and field audit portable kits. Cost compression in chromatography consumables is intensifying because service unbundling converts capital expenditure to operational leases. Quality control laboratories exhibit lowest price sensitivity due to regulatory non-negotiability, while tier-2 Indian bottlers face acute budget constraints.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for German and Dutch quality control laboratories sourcing Japanese mass spectrometry components. Manufacturing concentrates in Germany, Japan, and the United States for precision optical and separation systems. Supply chains draw from specialized quartz manufacturers in Heraeus, rare earth element processors in China, and precision machining clusters in Switzerland. Single-source vulnerability around helium extraction in Qatar and Algeria threatens chromatography system operability. Distribution runs through authorized distributor networks with embedded application engineering support rather than pure hardware resale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bottled water testing equipment sits in an early-cycle expansion phase as decentralized quality programs and real-time sensor networks penetrate mid-sized producer facilities previously reliant on centralized laboratory outsourcing.
For Market Incumbents: Consolidate service bundling capabilities to capture lease-model conversions from capital-intensive laboratories. Acquire portable electrochemical sensor specialists in Italy and Spain before regional champions emerge. Digital PCR platforms threaten incumbent optical detection suppliers with enrichment-free pathogen quantification.
For New Entrants and Emerging Players: Lead with cloud-integrated IoT turbidity and conductivity probes targeting Indian tier-2 cities where FSSAI enforcement outpaces laboratory infrastructure development. White-space concentrates in real-time quality assurance subscriptions for remote bottling sites. Partner with existing chromatography distributors for rapid channel access rather than building direct sales.
For Investors and Strategic Acquirers: The market sits at a technology-substitution phase that favors application-software-over-hardware specialists and full-service lease providers. Long-term viability favors vendors with recurring consumables revenue and method validation expertise rather than pure equipment manufacturers. Watch EPA Safe Drinking Water Act amendment timing as inflection indicator for automated sample preparation demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Service Unbundling Conversion | Transforms capital expenditure to operational budgets, concentrating vendor relationships with full-service providers in Germany. |
| Portable Sensor Geographic Expansion | Captures FSSAI-driven demand in Indian tier-2 cities where laboratory infrastructure remains underdeveloped. |
| Digital PCR Platform Development | Displaces culture-based microbiology with direct pathogen quantification, threatening incumbent optical detection suppliers. |
| Helium Independence Investment | Mitigates Qatar supply volatility through hydrogen carrier gas retrofit programs for gas chromatography systems. |
| REACH Compliance Service Layer | Opens recurring revenue streams for European beverage exporters requiring substance registration documentation support. |
Methodological Framework
Operator-level perspectives from quality control laboratory directors, beverage manufacturer quality assurance heads, chromatography application specialists, and FSSAI enforcement officers anchored the qualitative base. Primary interviews combined with secondary validation from EPA enforcement guidance documents, EU Drinking Water Directive recast texts, FDA 21 CFR 165.110 filings, and ISO 17025 accreditation body records. Bottom-up equipment procurement tracking across German, Italian, Spanish, Indian, and United States facilities triangulated against top-down vendor shipment data.
Sensitivity analysis tested forecast robustness across helium price volatility scenarios, regulatory amendment timing variations, and technology substitution rates. Segmentation dimensions modeled include product type, technology platform, end-user category, and application purpose across the projection horizon. CAGRs derived from equipment replacement cycle analysis, regulatory mandate sequencing, and penetration rate assumptions for portable versus laboratory formats. Industry-specific inputs incorporated FSSAI tier-2 city enforcement schedules and EU Drinking Water Directive recast implementation timelines.
Forecasts assume regulatory continuity in EPA Safe Drinking Water Act enforcement, EU Drinking Water Directive recast adoption, and FSSAI IS 14543 implementation; material policy shifts would require re-modeling. Specific risks include helium export restriction escalations, ISO 17025 accreditation body backlogs freezing contract eligibility, and certified reference material scarcity blocking PFAS detection protocol validation. Recalibration cycles align with material shifts in regulatory amendment schedules, technology substitution milestones, and geographic enforcement pattern changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Mycotoxin Testing Market
Food Safety Testing
Food Pathogen Testing Market
Food Safety Testing
Global Lipid Testing Market
Food Safety Testing
Edible Oil Adulteration Testing Chemicals Market
Food Safety Testing
Water Activity Instrumentation Market
Food Safety Testing
Screening Equipment Market
Food Safety Testing
Europe Food Safety Testing Market
Food Safety Testing
Water Quality Testing Market
Food Safety Testing
US Consumer Product Safety Testing Market
Food Safety Testing
Food Traceability Market
Food Safety Testing
Meat Testing Market
Food Safety Testing
Residual Lactose Analyzer Market
Food Safety Testing
Food Tester Market
Food Safety Testing
Food and Beverage Protective Cultures Market
Food Safety Testing
Italy Food Safety Testing Market
Food Safety Testing
Dairy Testing Services Market