
 Xylose Absorption Tests Market | 2026-2036
Xylose Absorption Tests Market Size, Share, and Industry Trends Forecast 2026-2036
Xylose Absorption Tests Market Analytics
Hospital procurement consolidation is decoupling from independent laboratory purchasing patterns across North America. Bristol-Myers Squibb Company leverages its therapeutic diagnostics alignment to sustain hospital system partnerships. Sigma-Aldrich Corporation anchors research-grade reagent supply chains for academic medical centers. Pfizer Inc competes through its distribution scale in specialty diagnostic channels.
Xylose absorption tests measure intestinal permeability and carbohydrate absorption capacity using a standardized D-xylose load protocol with timed blood or urine specimen collection, primarily identifying malabsorption syndromes and mucosal damage in clinical settings. Blood test formats command the largest share due to established clinical workflows, while enzymatic assays lead technology adoption for their specificity in quantifying xylose metabolites. Diagnostic kits represent the fastest-expanding segment as point-of-care platforms reduce laboratory turnaround times for celiac disease screening.
The FDA oversees clinical laboratory improvement amendment compliance for test accuracy and personnel certification, while the EMA's in vitro diagnostic regulation shapes market access requirements for European manufacturers. ISO 15189 accreditation standards govern quality management in medical laboratories performing these assays. Stakeholders must monitor evolving immunoassay platform interoperability and reimbursement coding revisions for malabsorption diagnostics.
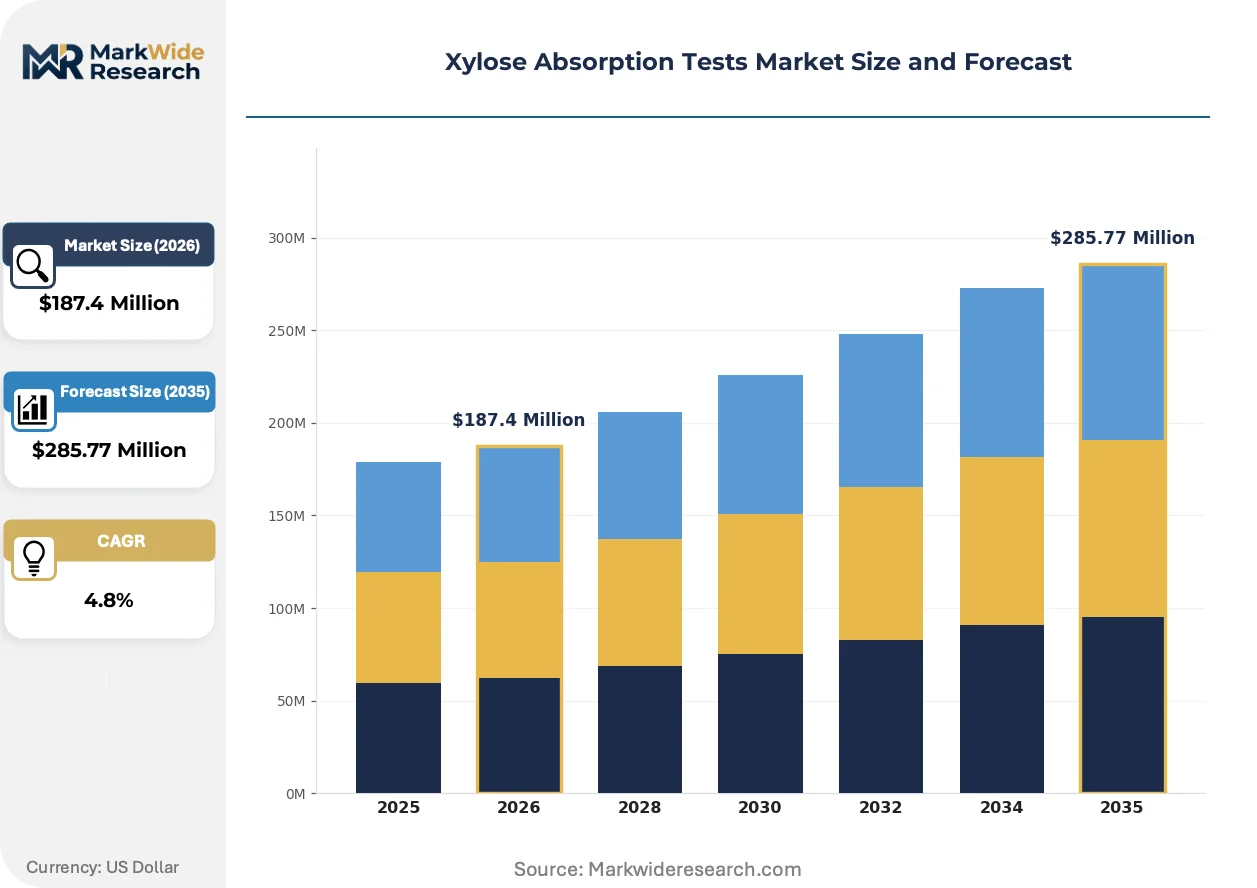
Market Dynamics
Hospital procurement consolidation is decoupling from independent laboratory purchasing patterns, creating divergent pricing and service expectations across the Xylose Absorption Tests Market. This structural split is forcing manufacturers to maintain dual commercial infrastructures.
Growth Catalysts
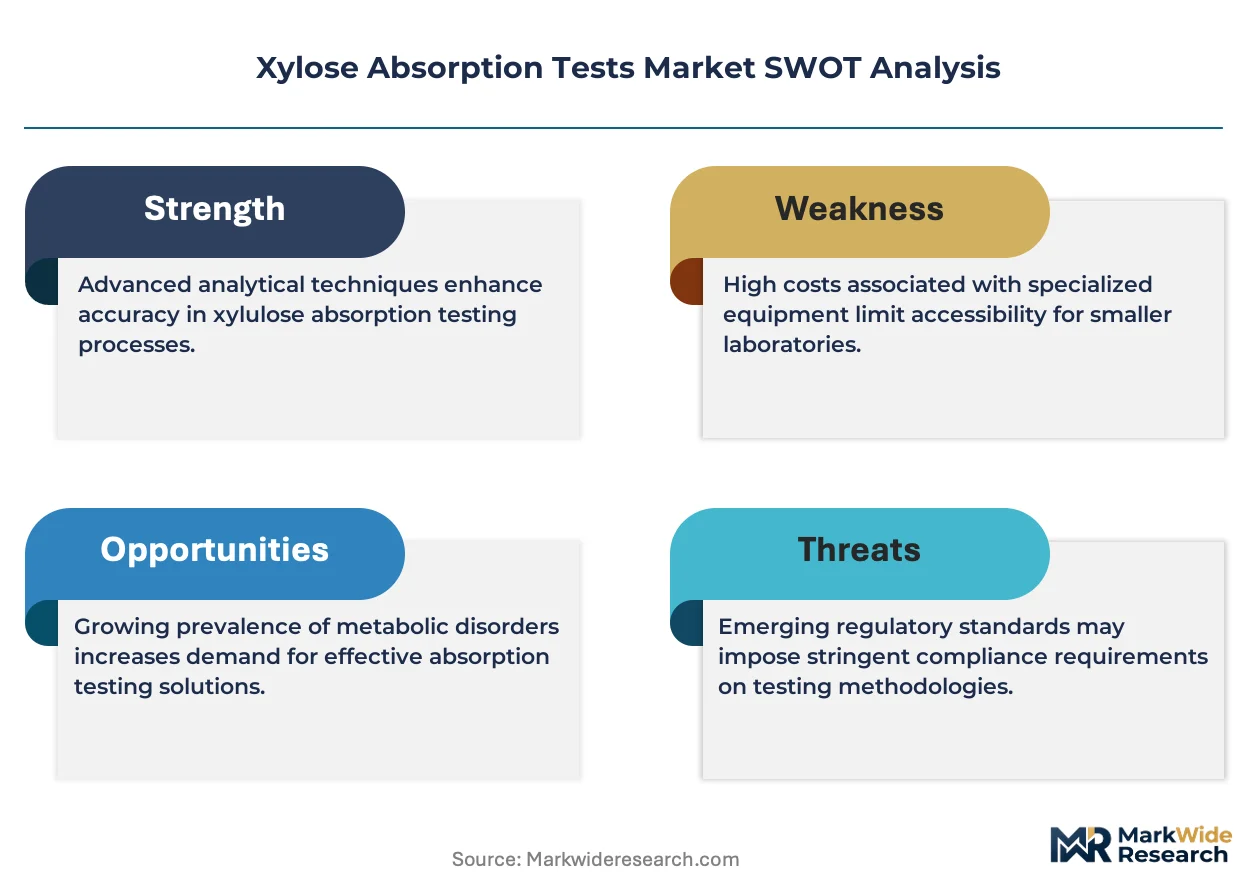
- FDA Clinical Laboratory Improvement Amendments:These quality benchmarks for assay validation are elevating standards that differentiate compliant suppliers from marginal operators.
- Enzymatic assay specificity:Superior quantification of xylose metabolites is pulling adoption away from less precise colorimetric methods in academic medical centers.
- Gastroenterology clinic expansion:Non-invasive diagnostic preferences are accelerating test volumes as celiac disease screening protocols standardize.
Market Restraints
- Reagent supply concentration:Research-grade chemical sourcing clusters with Sigma-Aldrich Corporation and limited alternative suppliers create vulnerability.
- Lactose breath test substitution:Hydrogen breath testing for carbohydrate malabsorption competes directly on patient convenience and single-visit completion.
- ISO 15189 accreditation costs:Medical laboratory quality management certification imposes capital and personnel burdens that filter smaller competitors.
Strategic Opportunities
- Point-of-care platform convergence:Lateral flow and handheld reader technologies are opening ambulatory settings previously reserved for centralized laboratories.
- EMA In Vitro Diagnostic Regulation alignment:European market access requirements are creating first-mover advantages for manufacturers achieving MDR compliance early.
- Pediatric malabsorption screening:Underpenetrated neonatal and early childhood protocols present volume expansion beyond adult gastroenterology.
Industry Challenges
- Cross-platform immunoassay interoperability:Analyzer-specific reagent formats fragment laboratory workflows and complicate inventory management.
- Reimbursement coding revision cycles:CPT and HCPCS updates for malabsorption diagnostics create revenue recognition uncertainty during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Xylose Absorption Tests Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Blood Test, Urine Test, Stool Test, Diagnostic Kit Application: Digestive Disorders, Malabsorption Syndromes, Celiac Disease, Research Studies End User: Clinics, Hospitals, Laboratories, Research Institutions Technology: Enzymatic Assays, Chromatographic Methods, Immunoassays, Spectrophotometry |
| Companies Covered | Bristol-Myers Squibb Company, Tokyo Chemical Industry, Boston Scientific Corporation, Laughlin Industries Inc, Penta International Corporation, Pfizer Inc, Mylan Pharmaceuticals, Synerzine, Inc, Sigma-Aldrich Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Xylose Absorption Tests Market Evolving Landscape
Diagnostic workflow compression is reshaping how xylose absorption testing reaches patients. Laboratories and manufacturers are racing to eliminate pre-analytical delays while preserving analytical integrity.
Microfluidic cartridge systems are overtaking traditional batch enzymatic processing in high-volume hospital laboratories. These platforms reduce technician hands-on time and specimen aliquoting errors. Reference labs in integrated health networks are deploying them fastest, compressing turnaround from hours to under thirty minutes.
REACH chemical registration requirements in Europe are tightening reagent import documentation and substance volume tracking. Manufacturers must now maintain dual formulation registries for EU and non-EU markets. Diagnostic kit suppliers with European manufacturing footprints are absorbing compliance costs faster than importers.
Direct-to-physician distribution is displacing traditional laboratory supply intermediaries in specialty diagnostic channels. Gastroenterology practices now expect manufacturer field support for assay validation and quality control troubleshooting. This pattern concentrates in the United States where practice management corporations negotiate centralized purchasing agreements.
Xylose Absorption Tests Market Segmentation
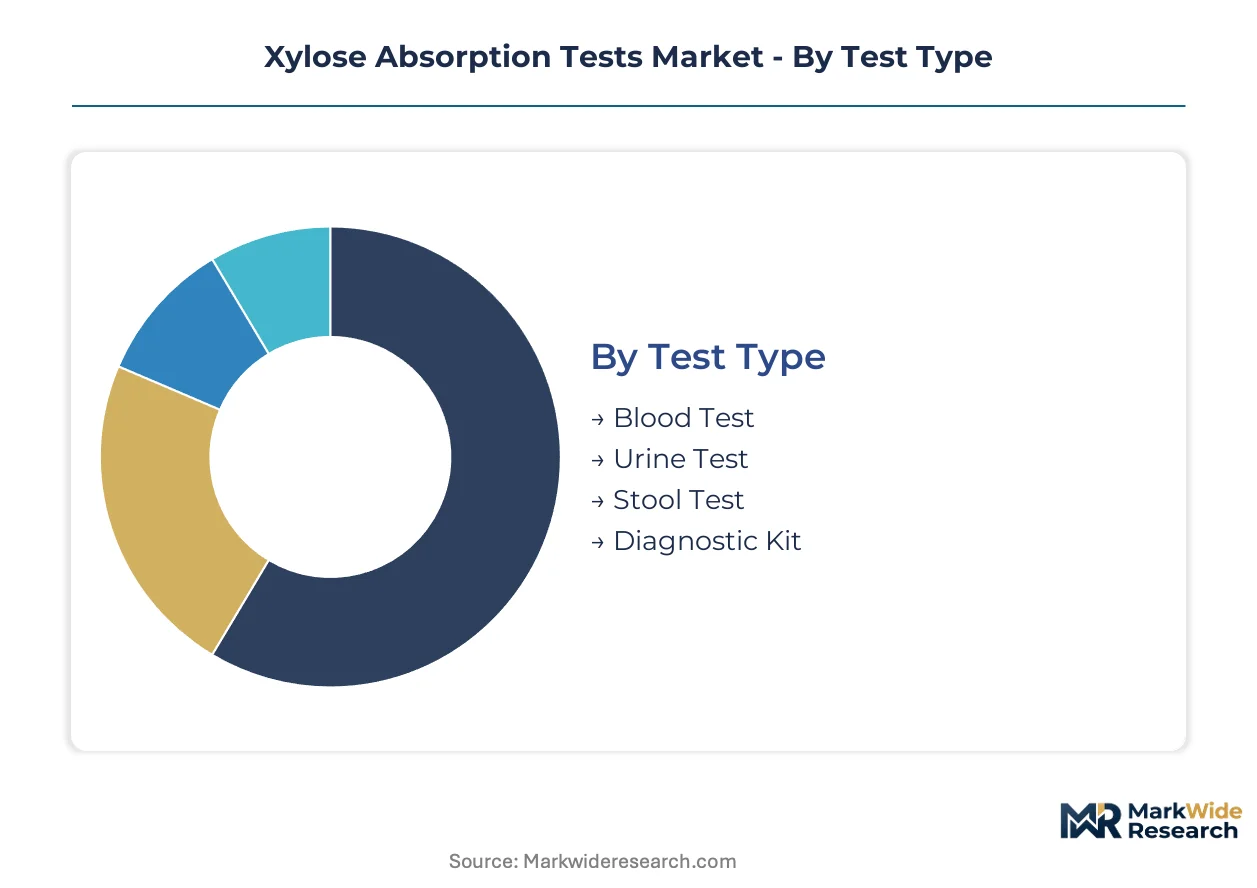
Xylose absorption testing fragments across four distinct category axes. Test format, clinical application, care setting, and analytical technology each create separate purchasing logics that manufacturers must navigate simultaneously.
Test Type:
Buyer differentiation hinges on specimen handling capabilities and turnaround requirements rather than clinical sensitivity alone.
- Blood Test:Serum quantification via venipuncture at baseline and two-hour intervals remains the reference standard for mucosal function assessment. Hospital laboratories in the United States anchor demand here, driven by standardized malabsorption screening protocols within integrated health networks.
- Diagnostic Kit:Pre-configured reagent packs with calibrated standards compress setup time for low-volume operators. Gastroenterology clinics expanding celiac disease screening programs are pulling adoption fastest as point-of-care platforms reduce laboratory turnaround times.
- Urine Test:Five-hour urine collection with oral D-xylose load offers non-invasive alternative for pediatric and geriatric populations.
- Stool Test:Fecal xylose detection serves research protocols and secondary confirmation where blood draws are contraindicated.
Volume sits with blood-based workflows; growth tilts toward diagnostic kit formats.
Application:
Clinical utility concentrates where differential diagnosis complexity justifies specialized carbohydrate absorption assessment.
- Malabsorption Syndromes:Small intestinal bacterial overgrowth and tropical sprue investigations rely on xylose testing for mucosal integrity quantification. Academic medical centers maintain highest test volumes, supported by Sigma-Aldrich Corporation research-grade reagent supply chains.
- Celiac Disease:Seronegative case confirmation and post-diagnostic monitoring drive repeat testing cycles. Gastroenterology clinic expansion across North America is accelerating protocol standardization for this indication.
- Digestive Disorders:Functional dyspepsia and irritable bowel syndrome workups employ xylose testing to exclude organic pathology.
- Research Studies:Drug absorption kinetics and barrier function modeling utilize standardized D-xylose protocols in pharmaceutical development settings.
Malabsorption syndromes command procedure volume; celiac disease applications are expanding most quickly.
End User:
Purchasing authority splits between centralized procurement offices and specialty practice managers.
- Hospitals:Integrated health networks negotiate system-wide contracts for high-throughput enzymatic processing. Bristol-Myers Squibb Company leverages therapeutic diagnostics alignment to sustain these partnerships.
- Clinics:Independent gastroenterology practices prioritize single-visit completion and rapid result turnaround. Direct-to-physician distribution is displacing traditional laboratory supply intermediaries in this channel.
- Laboratories:Reference labs and hospital-affiliated facilities manage regulatory compliance burden for CLIA-waived and moderate-complexity testing.
- Research Institutions:Academic medical centers demand batch consistency documentation and lot-to-lot validation for longitudinal studies.
Hospitals dominate absolute volume; clinics represent the steepest expansion trajectory.
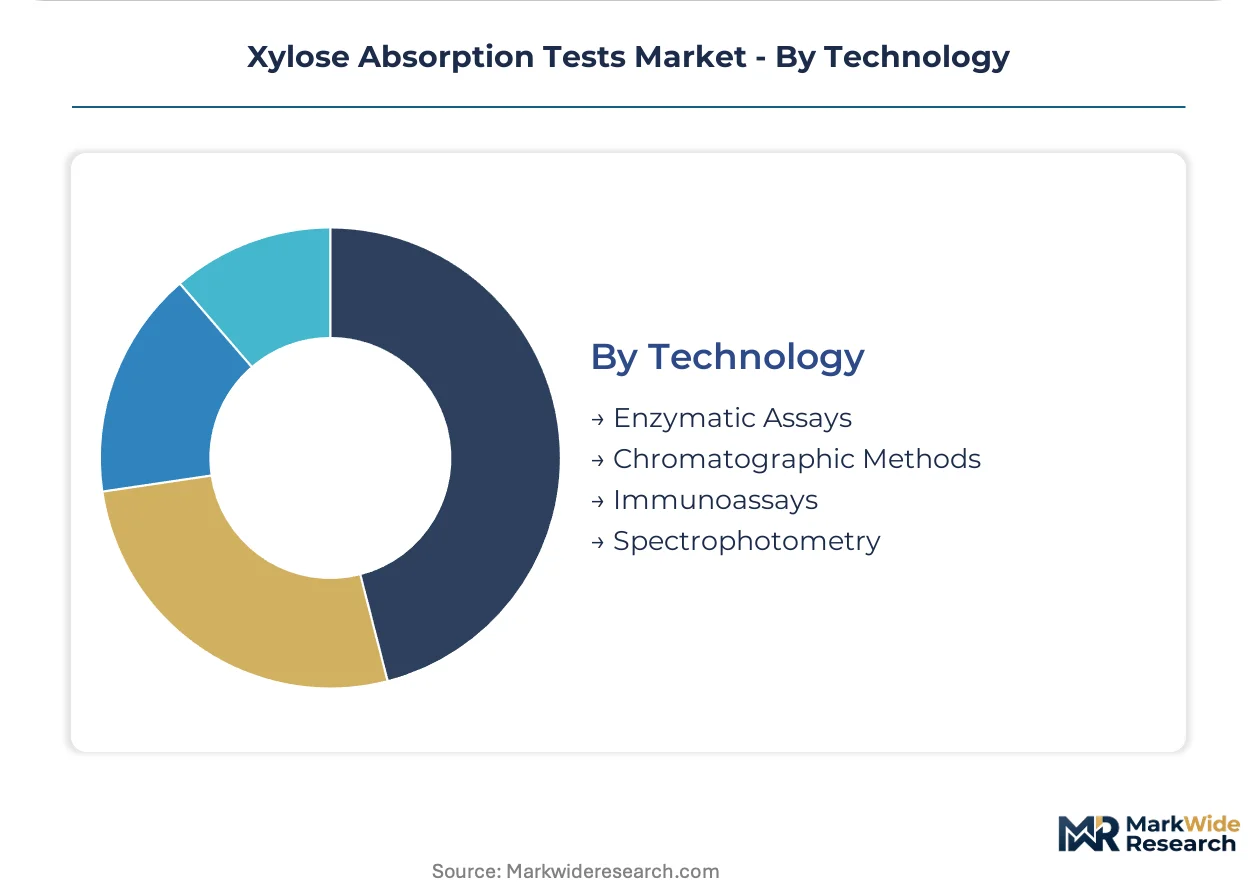
Technology:
Analytical specificity requirements separate premium-positioned platforms from cost-optimized alternatives.
- Enzymatic Assays:Xylose oxidase-based quantification delivers metabolite-specific detection with minimal interference from other pentoses. Academic medical centers are pulling adoption away from less precise colorimetric methods.
- Chromatographic Methods:HPLC and GC-MS separations serve reference laboratories requiring definitive identification and simultaneous multi-analyte profiling.
- Immunoassays:Antibody-based detection platforms face cross-platform interoperability challenges that fragment laboratory workflows.
- Spectrophotometry:Phloroglucinol colorimetric methods retain utility in resource-constrained settings despite lower analytical specificity.
Enzymatic assays hold installed base dominance; chromatographic methods are gaining share fastest in high-complexity reference laboratories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health networks concentrate the highest test volumes through standardized malabsorption screening protocols. Germany and Japan anchor European and Asian demand through academic medical center networks. Emerging markets in India and Brazil are expanding diagnostic access as gastroenterology infrastructure develops.
United States
FDA Clinical Laboratory Improvement Amendments enforce quality benchmarks that differentiate compliant assay suppliers from marginal operators. Integrated health networks in the Midwest and Southeast negotiate system-wide contracts for high-throughput enzymatic processing. The Mayo Clinic and Cleveland Clinic anchor reference laboratory standardization efforts across their respective regional footprints.
Germany
EMA In Vitro Diagnostic Regulation alignment creates first-mover advantages for manufacturers achieving MDR compliance early. REACH chemical registration requirements tighten reagent import documentation and substance volume tracking. The Rhine-Ruhr metropolitan region concentrates diagnostic kit manufacturing with dual formulation registries for EU and non-EU markets.
Japan
PMDA oversight of in vitro diagnostics shapes quality management expectations for medical laboratories performing xylose assays. METI industrial policy supports point-of-care platform development through targeted R&D subsidies. The Kansai region around Osaka hosts specialized reagent suppliers serving academic medical centers with batch consistency documentation requirements.
India
CDSCO regulatory pathways for diagnostic kits are streamlining as the domestic gastroenterology clinic network expands into tier-2 cities. The country's national pharmaceutical regulator maintains vigilance over assay import quality through enhanced port inspections. Maharashtra and Karnataka states concentrate new diagnostic infrastructure investment around Mumbai and Bangalore metropolitan clusters.
Brazil
ANVISA diagnostic registration timelines create market access friction that favors established suppliers with regulatory affairs capabilities. Hydrogen breath testing for carbohydrate malabsorption competes directly on patient convenience in São Paulo's private clinic network. The Southeast region anchors demand as gastroenterology practice management corporations consolidate purchasing authority.
Xylose Absorption Tests Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue point-of-care platform convergence and pediatric screening specialization. The vendor base splits between therapeutic-aligned pharmaceutical conglomerates and independent diagnostic reagent specialists. Three archetypes dominate: integrated health network contractors, academic medical center suppliers, and direct-to-physician distributors. Competitive moves concentrate on M&A for regulatory compliance capabilities and capacity expansion for enzymatic assay production.
Within the therapeutic-diagnostics alignment tier, Bristol-Myers Squibb Company and Pfizer Inc exemplify pharmaceutical conglomerates leveraging hospital system partnerships. Sigma-Aldrich Corporation anchors the research-grade reagent supply archetype for academic medical centers with batch validation requirements. Tokyo Chemical Industry occupies a position among specialty chemical suppliers serving diagnostic kit manufacturers with substance volume tracking compliance.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Tokyo Chemical Industry |
| Boston Scientific Corporation |
| Laughlin Industries Inc |
| Penta International Corporation |
| Pfizer Inc |
| Mylan Pharmaceuticals |
| Synerzine, Inc |
| Sigma-Aldrich Corporation |
| Others |
Value Network & Pricing Analysis
Microfluidic cartridge adoption in high-volume hospital laboratories simultaneously compresses per-test processing costs and concentrates reagent procurement power among integrated health networks. This technological shift tightens margins for standalone diagnostic kit suppliers while rewarding manufacturers with captive enzymatic assay production capabilities.
Pricing Analysis
High-throughput hospital contracts trade margin for volume commitment, while independent gastroenterology clinics retain price sensitivity for single-visit completion formats. Three-tier pricing structure across premium enzymatic assays, standard colorimetric methods, and economy spectrophotometry reflects certification grade and turnaround time differentiation. Cost compression in the standard tier intensifies as point-of-care platforms eliminate laboratory intermediation. Academic medical centers prove least price-sensitive due to batch validation requirements and research-grade reagent specifications.
Supply Chain Analysis
Return flows for expired diagnostic kits and recalibrated standards flow back through manufacturer field service teams rather than traditional distribution channels. Reagent manufacturing concentrates in Germany, the United States, and Japan, with substance volume tracking compliance anchoring production location decisions. Xylose oxidase enzymes, calibrated reference standards, and microfluidic substrates constitute critical input dependencies. Single-source vulnerability sits with research-grade chemical suppliers serving batch consistency documentation requirements. Distribution runs through direct-to-physician channels in specialty gastroenterology practices and centralized procurement offices in integrated health networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA Clinical Laboratory Improvement Amendments erect a cost-of-compliance barrier that filters marginal operators and entrenches validated suppliers with quality management infrastructure. This regulatory moat rewards early movers who absorbed personnel certification and assay validation capital burdens.
For Market Incumbents: To counter hydrogen breath test substitution in celiac disease screening, incumbents should deepen point-of-care platform integration and secure exclusive distribution agreements with practice management corporations. Backward integration into xylose oxidase enzyme production reduces exposure to Sigma-Aldrich Corporation supply concentration.
For New Entrants and Emerging Players: Begin with pediatric malabsorption screening protocols, where underpenetrated neonatal testing volumes offer white-space expansion beyond saturated adult gastroenterology. Ambulatory surgery centers represent a secondary target with compressed turnaround requirements and limited incumbent relationships. A go-to-market angle emphasizing CLIA-waived assay simplicity bypasses hospital laboratory consolidation.
For Investors and Strategic Acquirers: Exit pathways concentrate in therapeutic-diagnostics alignment acquisitions by pharmaceutical conglomerates seeking hospital system access. Long-term viability hinges on EMA MDR compliance completion ahead of European market access deadlines. Monitor reimbursement coding revisions for malabsorption diagnostics as an inflection signal for revenue recognition stability.
| Strategic Initiative | Industry Significance |
|---|---|
| Point-of-Care Platform Development | Lateral flow handheld readers open ambulatory settings previously reserved for centralized laboratories. |
| Enzymatic Assay Capacity Expansion | Xylose oxidase production scale-up reduces dependency on concentrated research-grade reagent suppliers. |
| EMA MDR Compliance Pathway | Early MDR certification creates first-mover advantages in European diagnostic kit market access. |
| Direct-to-Physician Distribution Buildout | Manufacturer field support for assay validation displaces traditional laboratory supply intermediaries. |
| Pediatric Screening Protocol Partnership | Neonatal malabsorption test standardization expands volume beyond adult gastroenterology saturation. |
Research Methodology
Document review covered FDA 510(k) filings, EMA MDR technical documentation, hospital procurement databases, and GPO contracts, complemented by interviews with laboratory directors, gastroenterology practice managers, regulatory affairs specialists, and diagnostic reagent procurement leads. Secondary sources integrated CLIA waiver databases, CMS Medicare reimbursement schedules, and ISO 15189 accreditation records. Bottom-up test volume modeling and top-down market sizing triangulated against manufacturer revenue disclosures.
Segment-level projections across test format, clinical application, care setting, and analytical technology generated volume and value estimates over the projection horizon. CAGRs derived from historical procedure growth rates, test price trajectories, and gastroenterology clinic expansion patterns. Forecast inputs incorporated enzymatic assay adoption curves and point-of-care platform penetration assumptions by care setting.
Underlying measurement precision varies by segment; blood test and hospital end-user categories carry tighter precision than emerging diagnostic kit and clinic segments due to established reporting infrastructure. Forecasts reflect assumptions about regulatory timeline stability and reimbursement coding continuity. Practitioners should monitor FDA CLIA amendment revisions and EMA MDR enforcement intensity for early signals of compliance cost recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Global Inline Metal Detector Market
Food Safety Testing
Allergen Testing Market
Food Safety Testing
Salmonella Testing Market
Food Safety Testing
Food Safety Testing Services Market
Food Safety Testing
Gum Content Tester Market
Food Safety Testing
Genetically Modified Food Safety Testing Market
Food Safety Testing
US Food Safety Testing Market
Food Safety Testing
Italy Food Safety Testing Market
Food Safety Testing
Food Traceability Market
Food Safety Testing
Animal Feed Safety Testing Equipment Market
Food Safety Testing
Adulteration Tester Market
Food Safety Testing
Beverage Tester Market
Food Safety Testing
Food Allergen Testing Market
Food Safety Testing
Food Tester Market
Food Safety Testing
Meat Speciation Testing Service Market
Food Safety Testing
UAE Product Testing Lab Services Market