
 Food Testing, Inspection, and Certification Market | 2026-2036
Food Testing, Inspection, and Certification Market Size, Share, and Industry Trends Forecast 2026-2036
Food Testing, Inspection, and Certification Market Insights
Qualified microbiology technician availability is collapsing across contract laboratories, forcing service providers to automate workflows or raise wages to retain talent. SGS leverages its multi-continent laboratory network to sustain testing throughput despite regional labor shortages. Eurofins Scientific anchors its competitive position through R&D intensity in rapid pathogen detection methods. Bureau Veritas differentiates by controlling specialized seafood and aquaculture certification protocols in Asia-Pacific markets.
Food testing, inspection, and certification encompasses the analytical verification, physical audit, and standards-based accreditation of agricultural and processed food products for safety, authenticity, and regulatory compliance, employing techniques such as PCR amplification for pathogen DNA detection at sensitivity thresholds below 10 CFU per gram. Its primary commercial purpose is to enable cross-border trade, protect public health, and verify label claims across complex, multi-tier supply chains. Microbiological testing leads service revenue as recurring pathogen screening mandates from retailers and regulators generate stable volume, while certification services capture disproportionate margin due to brand-dependent trust premiums and multi-year accreditation cycles. Rapid testing technology is displacing traditional culture-based methods in factory settings where same-shift release decisions compress turnaround requirements.
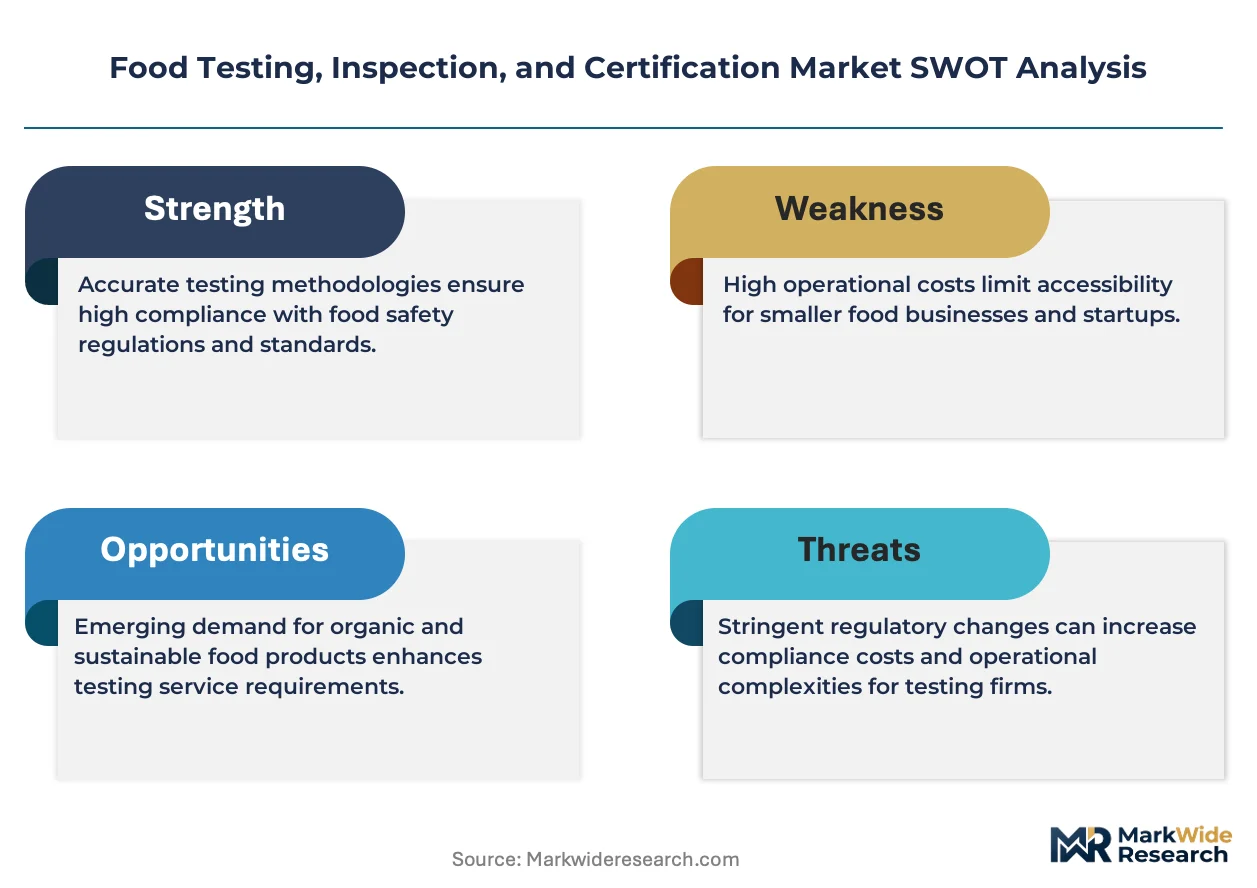
The FDA Food Safety Modernization Act and EU regulations including REACH contaminant thresholds and the EU Green Deal sustainable food frameworks are elevating testing stringency, directly expanding mandatory analytical scope and audit frequency for importers and domestic producers alike. China's SAMR and GB standards enforcement is tightening parallel to Western regimes, creating convergent compliance burdens for multinational food manufacturers sourcing across multiple jurisdictions. Stakeholders must monitor divergence between regional maximum residue limits and emerging requirements for climate-impact verification that could reshape certification scope beyond traditional safety parameters.
Market Dynamics
Contract laboratories face acute pressure from collapsing microbiology technician availability, forcing automation investments or wage escalation to maintain testing throughput under tightening FDA and EU contaminant thresholds.
Growth Catalysts
- EU Green Deal frameworks:Sustainable food verification mandates expand certification scope beyond safety into climate-impact documentation, creating new revenue streams for accredited bodies serving European importers.
- PCR amplification methods:Pathogen DNA detection at sub-10 CFU per gram sensitivity enables same-shift release decisions, compressing turnaround times for processed food manufacturers.
- China import verification:SAMR enforcement of GB standards intensifies parallel compliance burdens for multinational manufacturers sourcing across multiple jurisdictions.
Market Restraints
- Skilled technician scarcity:Qualified microbiology labor availability constraints limit laboratory expansion regardless of capital deployment, particularly acute in Germany and United States metropolitan clusters.
- Equipment amortization cycles:Rapid testing instrumentation requires replacement every 4-6 years, straining mid-tier service providers against larger multi-continent networks.
- REACH residue limit divergence:Misalignment between EU maximum thresholds and FDA tolerances forces dual testing protocols for cross-Atlantic suppliers.
Strategic Opportunities
- Seafood aquaculture certification:Asia-Pacific specialized protocol control offers margin expansion as regional production volumes climb and export eligibility hinges on accredited verification.
- Blockchain-PCR convergence:Immutable chain-of-custody documentation paired with rapid pathogen detection creates differentiated offerings for high-value supply chains.
- India FSSAI alignment:Domestic food safety authority tightening presents entry potential for international certification bodies establishing local accreditation partnerships.
Industry Challenges
- Laboratory information management integration:Legacy ERP systems at food manufacturers resist seamless data exchange with external testing platforms, delaying result transmission.
- Multi-jurisdiction audit scheduling:Coordinating simultaneous inspections across FDA, EFSA, and SAMR requirements strains manufacturer compliance calendars and extends certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Testing, Inspection, and Certification Market |
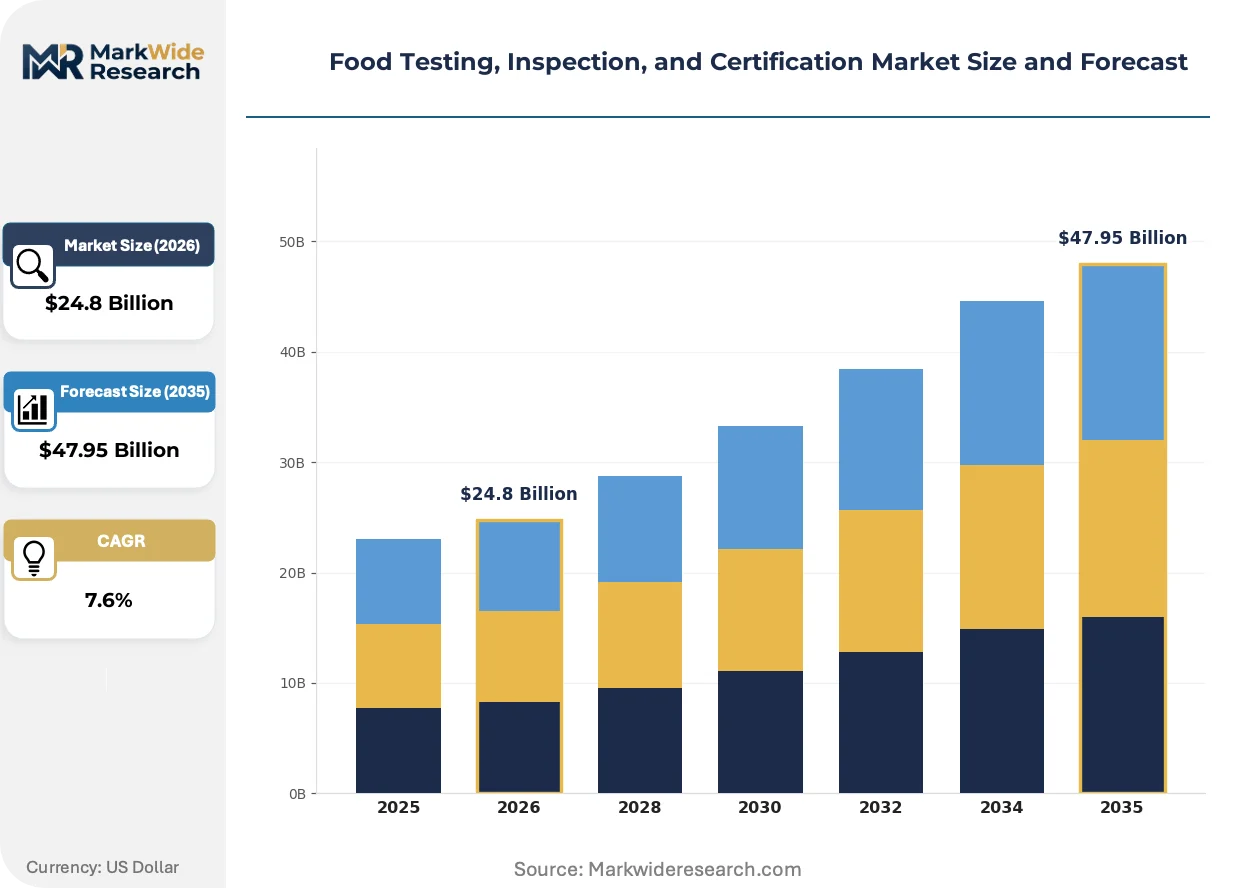
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $47.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Microbiological Testing, Chemical Analysis, Sensory Evaluation, Certification Services Product Type: Meat, Dairy, Seafood, Processed Foods End User: Food Manufacturers, Retailers, Importers, Regulatory Agencies Technology: PCR Testing, Mass Spectrometry, Chromatography, Rapid Testing |
| Companies Covered | SGS, Eurofins Scientific, Intertek Group plc, Bureau Veritas, DEKRA, TÜV SÜD, NSF International, Applus+, UL LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Testing, Inspection, and Certification Market Trends and Innovations
Rapid molecular diagnostics and digital traceability systems are compressing traditional culture-based workflows while regulatory scope expands beyond safety into sustainability verification.
Next-generation sequencing platforms are fragmenting the dominance of conventional PCR methods in high-throughput contract laboratories. Large processed food manufacturers in the United States and Germany are deploying these systems for metagenomic screening of raw ingredient lots. The technology is fragmenting service provider market structure by enabling smaller laboratories to compete on sensitivity metrics previously requiring capital-intensive infrastructure.
EU Green Deal sustainable food frameworks are mandating climate-impact documentation alongside traditional safety certification. Food exporters to European markets must now verify carbon footprint and water usage across agricultural inputs. Processed food manufacturers and ingredient suppliers are responding by integrating life-cycle assessment data into existing quality management systems.
Retailer-driven audit consolidation is compressing supplier testing burdens as Walmart, Carrefour, and Tesco harmonize private standards. Third-party certification bodies are displacing redundant customer-specific audits with unified protocols accepted across multiple retail banners. This concentration is most visible in North American and Western European produce and protein supply chains where buyer power enables standardization enforcement.
Food Testing, Inspection, and Certification Market Segmentation
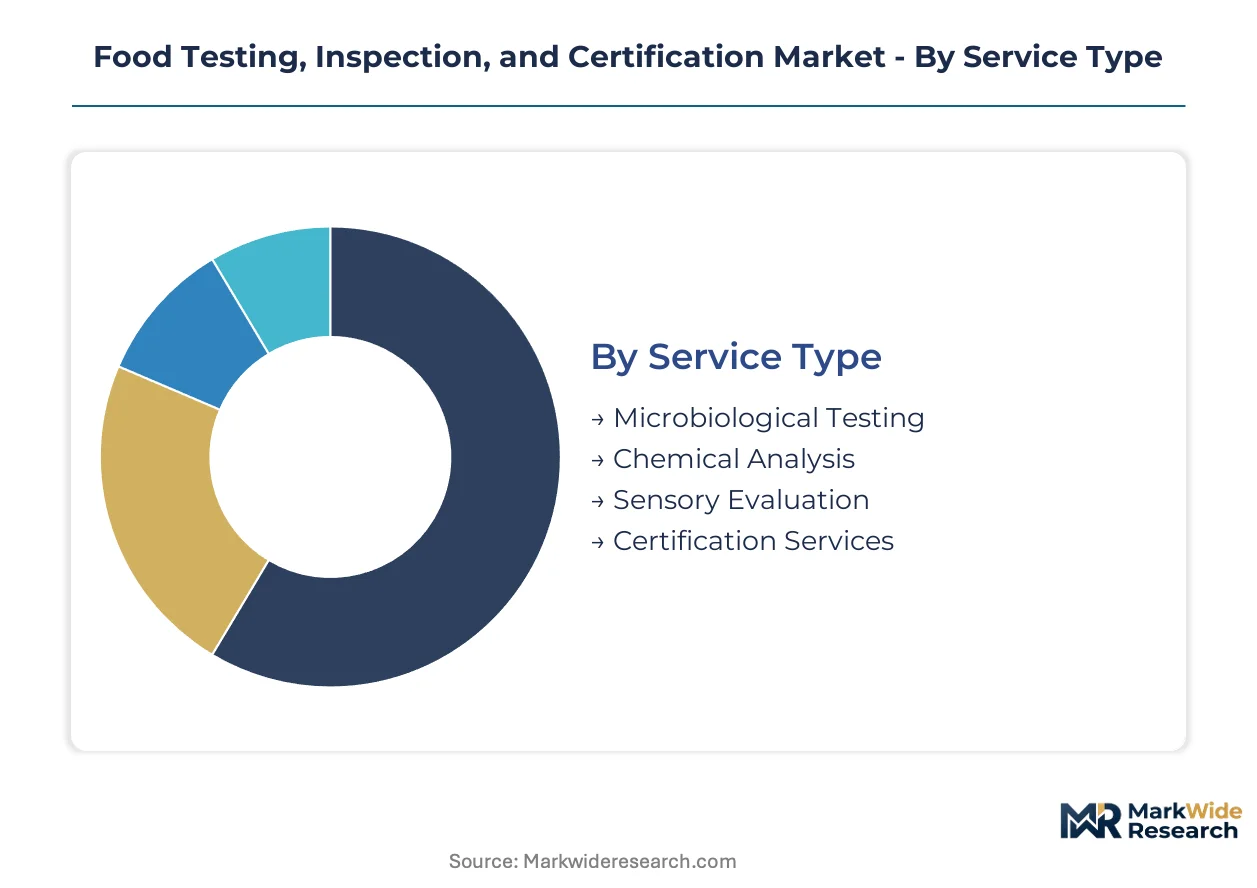
Segmentation in food testing, inspection, and certification reveals distinct margin architectures across service modalities and technology platforms. Understanding where value concentrates helps stakeholders allocate capital toward accreditation-heavy or rapid-turnaround segments.
Service Type:
Margin pools concentrate in recurring certification cycles and high-frequency microbiological screening mandates from retail buyers.
- Microbiological Testing:Pathogen detection via culture-based and molecular methods for Salmonella, Listeria, and E. coli verification. Demand clusters at processed food manufacturers in Germany and the United States facing compressed release timelines under FDA and EFSA thresholds.
- Chemical Analysis:Residue quantification for pesticides, veterinary drugs, and heavy metals using chromatographic and spectrometric techniques. Laboratories in China serving export-oriented seafood processors absorb volume as SAMR tightens GB standard enforcement for cross-border shipments.
- Sensory Evaluation:Organoleptic assessment for flavor, texture, and appearance consistency in premium product lines.
- Certification Services:Third-party accreditation for organic, non-GMO, and sustainability claims with multi-year audit cycles.
The dominant share belongs to Microbiological Testing, while Certification Services is closing the gap fastest.
Product Type:
Testing intensity varies sharply by perishability and regulatory scrutiny, with animal proteins commanding premium analytical spend.
- Meat:Species authentication and pathogen screening across beef, pork, and poultry supply chains. USDA and EFSA residue monitoring programs drive volume at slaughterhouse laboratories in the United States and Germany.
- Seafood:Histamine detection, fraud verification, and aquaculture certification for export eligibility. Asia-Pacific processing hubs in Vietnam and Indonesia anchor demand as EU import controls tighten.
- Dairy:Antibiotic residue testing and compositional analysis for fluid milk and cheese production.
- Processed Foods:Label claim verification and contaminant screening for ready-to-eat categories.
Meat captures the largest revenue pool, though Seafood is expanding most quickly on aquaculture certification growth.
End User:
Procurement authority shifts testing volume toward retail-driven consolidation and import gatekeeping functions.
- Food Manufacturers:In-house and contract laboratory spending for HACCP validation and lot release decisions. Large processors in the United States deploy rapid PCR systems for same-shift clearance under FSMA preventive controls.
- Retailers:Private standard enforcement and supplier audit harmonization across Walmart, Carrefour, and Tesco banners. Third-party certification displaces redundant customer-specific protocols in North American and Western European produce chains.
- Importers:Border verification and documentation for customs clearance under divergent national regimes.
- Regulatory Agencies:Surveillance sampling and enforcement testing for public health protection.
Food Manufacturers retain the dominant procurement position, yet Retailers are gaining share fastest through audit consolidation.
Technology:
Capital deployment favors platforms compressing turnaround time while maintaining detection sensitivity below regulatory thresholds.
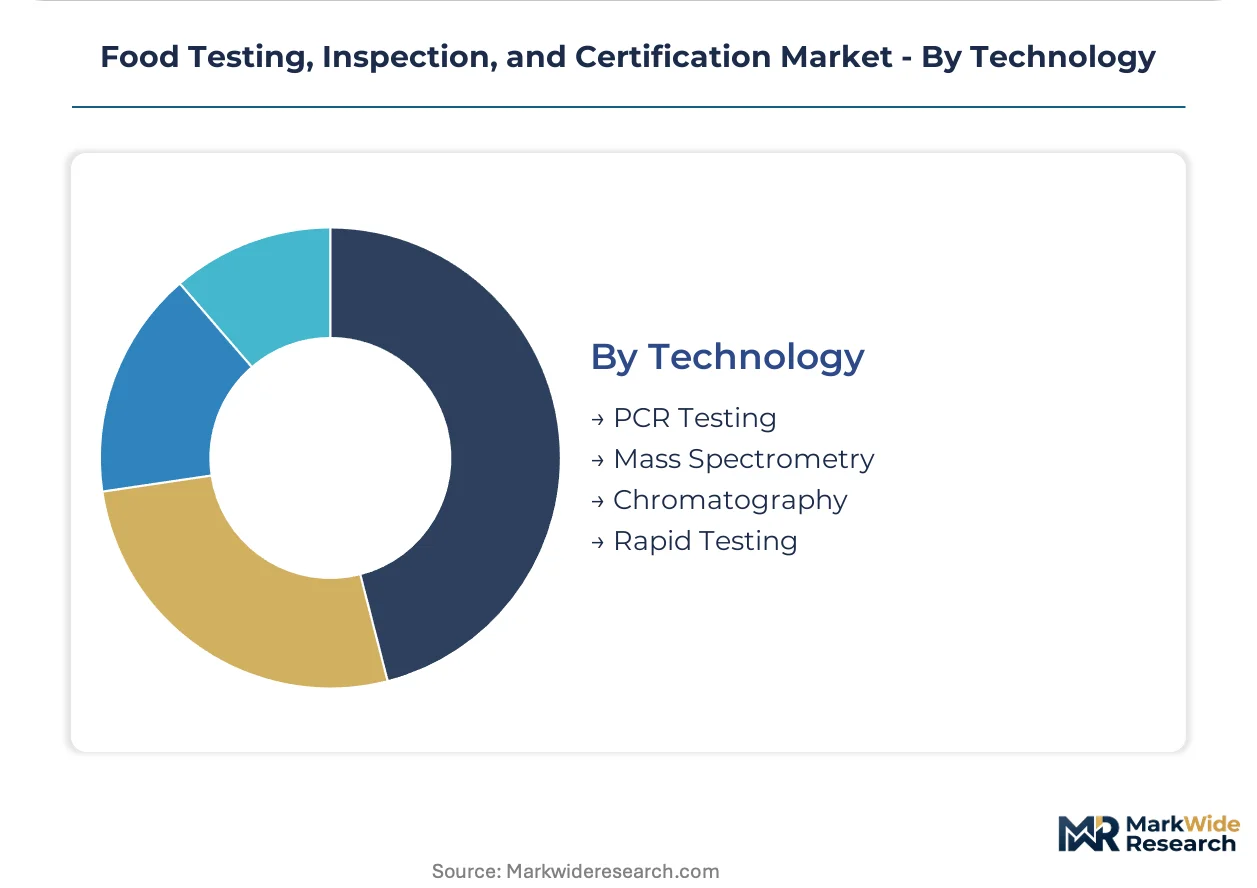
- PCR Testing:DNA amplification for pathogen identification at sub-10 CFU per gram sensitivity. Factory-floor deployment in German meat processing plants enables same-shift release decisions previously requiring overnight culture incubation.
- Rapid Testing:Lateral flow and immunoassay formats for presumptive screening without laboratory infrastructure. Small and mid-tier processors in India adopt these systems as FSSAI alignment raises domestic compliance burdens.
- Mass Spectrometry:High-resolution molecular identification for chemical residue and authenticity verification.
- Chromatography:Separation-based quantification for pesticide and veterinary drug residue analysis.
PCR Testing holds the installed base lead, while Rapid Testing is climbing the fastest on decentralization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets. Germany and the United States prioritize rapid pathogen screening for factory-floor release decisions. China concentrates on import verification and export certification for seafood and processed goods.
United States
Processed food manufacturers in Chicago and Omaha deploy PCR systems for same-shift lot clearance under FSMA preventive controls. FDA enforcement of stricter contaminant thresholds elevates testing frequency at slaughterhouse laboratories. The USDA residue monitoring program drives volume across Nebraska and Iowa meat processing corridors.
Germany
EFSA-mandated residue limits and REACH compliance burdens concentrate analytical demand at contract laboratories in Munich and Hamburg. Meat processors in Lower Saxony adopt rapid molecular diagnostics to compress turnaround times. The country's central position in EU food trade amplifies certification requirements for cross-border ingredient shipments.
China
SAMR enforcement of GB standards intensifies testing at export-oriented seafood processors in Qingdao and Dalian. Domestic dairy and infant formula manufacturers absorb volume following food safety scandals. The dual compliance burden—meeting both GB standards and EU import thresholds—shapes procurement patterns in Yangtze River Delta food manufacturing clusters.
India
FSSAI alignment with Codex standards raises domestic compliance burdens for processed food manufacturers in Maharashtra and Gujarat. Rapid testing adoption accelerates among mid-tier processors lacking in-house laboratory infrastructure. Mumbai and Ahmedabad anchor demand as retail consolidation forces supplier harmonization of safety documentation.
Vietnam
Seafood export eligibility hinges on EU-accredited verification as Brussels tightens import controls on aquaculture products. Processing hubs in Mekong Delta provinces absorb certification spending for pangasius and shrimp value chains. Bureau Veritas and SGS maintain specialized protocol control over regional aquaculture audit networks.
Food Testing, Inspection, and Certification Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in food testing, inspection, and certification. The upper tier commands multi-continent laboratory networks that sustain throughput despite regional technician shortages. Mid-tier specialists compete on seafood, organic, or rapid diagnostics niches. Dominant competitive moves include automation investments to offset labor constraints and geographic expansion into Asia-Pacific aquaculture certification.
Among Swiss and French integrated leaders, SGS and Bureau Veritas exemplify the network-scale archetype through multi-continent laboratory footprints. Eurofins Scientific anchors the R&D-intensive tier with emphasis on rapid pathogen detection methods. These three occupy positions where capital deployment and accreditation breadth create defensive moats against mid-tier challengers facing equipment amortization pressures.
| Leading Market Players |
|---|
| SGS |
| Eurofins Scientific |
| Intertek Group plc |
| Bureau Veritas |
| DEKRA |
| TÜV SÜD |
| NSF International |
| Applus+ |
| UL LLC |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at multi-continent laboratory networks shapes both supply concentration and price floors for food testing services. Large integrated providers in Germany and the United States leverage scale economies to absorb equipment amortization cycles that strain mid-tier competitors, compressing margins at regional laboratories while sustaining premium pricing for accredited certification protocols.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between processed food manufacturers and testing providers, locking in volume commitments that insulate pricing from spot-market volatility. Three-tier pricing structure across premium, standard, and economy levels separates rush-turnaround PCR diagnostics from routine culture-based screening and basic documentation services. Pricing pressure stems from equipment replacement cycles every 4-6 years that strain capital reserves at mid-tier laboratories. Large multinational food manufacturers in the United States exhibit lowest price sensitivity due to FSMA compliance mandates, while mid-tier processors in India face acute cost constraints as FSSAI alignment raises domestic testing burdens.
Supply Chain Analysis
Strait of Malacca transit underwrites chemical reagent supply security for Asia-Pacific laboratories serving seafood export certification. Germany, the United States, and China anchor global supply for rapid testing instrumentation and molecular diagnostic platforms. Reagent manufacturing draws from specialty chemical producers in Switzerland and Japan, while plastic consumables feed from precision molders in South Korea and Taiwan. Single-source vulnerability concentrates in reference standard production for pesticide residue quantification, where European suppliers control certified reference material archives. Distribution runs through direct sales forces for large account relationships and regional distributors serving mid-tier processors lacking centralized procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PCR amplification at sub-10 CFU sensitivity and EU Green Deal sustainability mandates are disrupting competitive positioning across food testing services, compressing turnaround timelines while expanding analytical scope beyond traditional safety parameters.
For Market Incumbents: Fortify laboratory network density in Asia-Pacific aquaculture corridors where Bureau Veritas and SGS currently control specialized certification protocols. Automate culture-based workflows to offset collapsing microbiology technician availability in Germany and United States metropolitan clusters. Invest in blockchain-traceability integration to defend margin position against rapid-testing entrants targeting factory-floor decentralization. For New Entrants and Emerging Players: Anchor in India FSSAI alignment opportunities where mid-tier processors lack in-house laboratory infrastructure and rapid testing adoption accelerates. Target seafood aquaculture certification in Vietnam and Indonesia where EU import control tightening creates accreditation demand unmet by local providers. Pursue white-label PCR platform partnerships with equipment manufacturers to bypass capital-intensive instrument ownership. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among certification bodies with multi-year audit cycles and retailer-mandated accreditation lock-in. Long-term viability favors providers controlling specialized protocols in high-growth protein segments. Monitor blockchain-traceability adoption rates as inflection indicator for technology-enabled differentiation premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Investment | Laboratory robotics deployment offsets technician scarcity in United States and Germany contract networks. |
| Asia-Pacific Certification Expansion | Specialized aquaculture protocol control captures margin from EU-bound seafood export eligibility requirements. |
| Rapid Testing Platform Launch | Factory-floor PCR deployment enables same-shift release decisions for FSMA-compliant meat processors. |
| Sustainability Verification Integration | EU Green Deal climate-impact documentation expands service scope beyond traditional safety testing. |
| Blockchain Traceability Partnership | Immutable chain-of-custody documentation differentiates offerings for high-value supply chain clients. |
Research Methodology
Initial hypotheses were tested against primary input from laboratory operations directors, regulatory affairs managers at processed food manufacturers, certification body audit coordinators, and retail buyer quality assurance leads, then refined through secondary validation. FDA warning letter databases, EFSA scientific opinions, SAMR GB standard filings, and customs trade records provided external triangulation. Bottom-up service revenue estimates from contract laboratory networks were reconciled with top-down market sizing from accreditation body membership data.
Variance decomposition across service type, technology platform, and geographic regulatory cluster shaped the analytical framework. Segmentation dimensions modeled include microbiological versus chemical testing modality, PCR versus rapid versus culture-based technology tier, and meat-seafood-dairy-processed food product category. CAGRs were derived from installed base growth curves for rapid testing instrumentation and regulatory mandate expansion timelines. Equipment replacement cycles and technician wage escalation trajectories informed cost-structure projections.
Decision-makers should treat outputs as directional under assumptions of sustained FDA and EFSA enforcement intensity; material deviation in regulatory stringency would warrant model refresh. Practitioners should keep alternative scenarios live as EU-China regulatory convergence patterns and blockchain-traceability adoption rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Food Authentication Testing Market
Food Safety Testing
Food Allergen Testing Market
Food Safety Testing
Global Food Diagnostics Market
Food Safety Testing
Dairy Testing Services Market
Food Safety Testing
Genetically Modified Food Safety Testing Market
Food Safety Testing
Shelf-Life Testing Market
Food Safety Testing
Europe Food Safety Testing Market
Food Safety Testing
North America Food Safety Testing Market
Food Safety Testing
Mycotoxin Testing Market
Food Safety Testing
Food Traceability Solutions Market
Food Safety Testing
Food Testing Kits Market
Food Safety Testing
Global Food Authenticity Testing Market
Food Safety Testing
Screening Equipment Market
Food Safety Testing
Fresh Food Residue Testing Market
Food Safety Testing
Bottled Water Testing Equipment Market
Food Safety Testing
Global Dairy Testing Market