
 Vitamin Test Market | 2026-2036
Vitamin Test Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamin Test Market Analysis
Liquid chromatography-tandem mass spectrometry (LC-MS/MS) is repositioning immunoassay-based vitamin testing by delivering superior specificity for fat-soluble vitamin panels. Abbott Laboratories leverages its point-of-care diagnostics footprint to anchor vitamin D testing in primary care settings. Thermo Fisher Scientific Inc. competes through reagent standardization programs that reduce inter-laboratory variability. Bio-Rad Laboratories specializes in quality control materials that sustain laboratory accreditation standards.
Vitamin testing comprises analytical procedures that quantify micronutrient concentrations in biological specimens, typically employing chromatographic, immunoassay, or spectrophotometric methods with detection thresholds ranging from nanograms to micrograms per milliliter. These assays serve clinical diagnosis of deficiency states, nutritional status monitoring, and wellness screening applications across healthcare and consumer segments. Serum analysis dominates routine clinical workflows due to established reference ranges and reimbursement alignment, while home testing kits represent the fastest-expanding delivery mode as consumers bypass traditional laboratory channels. Point-of-care testing captures concentrated margin pools in physician office laboratories seeking same-day diagnostic turnaround.
FDA 510(k) clearance requirements shape device commercialization timelines and clinical validity standards for vitamin test manufacturers seeking US market access. The Clinical Laboratory Improvement Amendments (CLIA) framework governs laboratory certification tiers and directly determines which testing sites may perform moderately complex vitamin assays. Stakeholders must monitor evolving CMS reimbursement codes for nutritional testing panels, as coverage decisions will determine whether expanded vitamin screening penetrates standard preventive care protocols or remains confined to self-pay wellness markets.
Market Dynamics
LC-MS/MS technology is compressing turnaround times for fat-soluble vitamin panels while simultaneously raising capital requirements for laboratory infrastructure upgrades.
Growth Catalysts
- CLIA Laboratory Certification:The Clinical Laboratory Improvement Amendments framework in the United States permits moderately complex vitamin assays in physician office laboratories, expanding point-of-care access beyond hospital networks.
- Employer Wellness Programs:Large US corporations now subsidize routine micronutrient screening as a preventive health benefit, creating institutional demand independent of diagnostic necessity.
- Functional Medicine Practices:These clinics order comprehensive vitamin panels as baseline assessments, normalizing frequent retesting protocols among health-conscious patient cohorts.
Market Restraints
- Reference Material Costs:Certified reference standards for vitamins D and B12 carry premium pricing, elevating per-test material costs for smaller diagnostic laboratories.
- Reimbursement Compression:CMS coverage decisions for nutritional testing panels remain restrictive, confining expanded screening to self-pay wellness markets outside standard preventive care protocols.
- Inter-Laboratory Variability:Immunoassay methods produce discordant results between testing sites, undermining physician confidence in vitamin D status assessments.
Strategic Opportunities
- At-Home Testing Channels:Direct-to-consumer distribution bypasses traditional laboratory networks, capturing margin pools previously allocated to collection site fees.
- FDA 510(k) Pathway Optimization:Streamlined clearance timelines for vitamin testing devices accelerate commercialization for manufacturers with predicate device strategies.
- Multi-Vitamin Panel Integration:Chromatographic platforms now enable simultaneous quantification of fat-soluble and water-soluble vitamins from single specimen aliquots.
Industry Challenges
- Mass Spectrometry Expertise Scarcity:LC-MS/MS operation requires specialized analytical chemists, constraining deployment in community hospital laboratories.
- Quality Control Material Sourcing:Third-party proficiency testing programs for vitamin assays face limited supplier options, complicating accreditation maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamin Test Market |
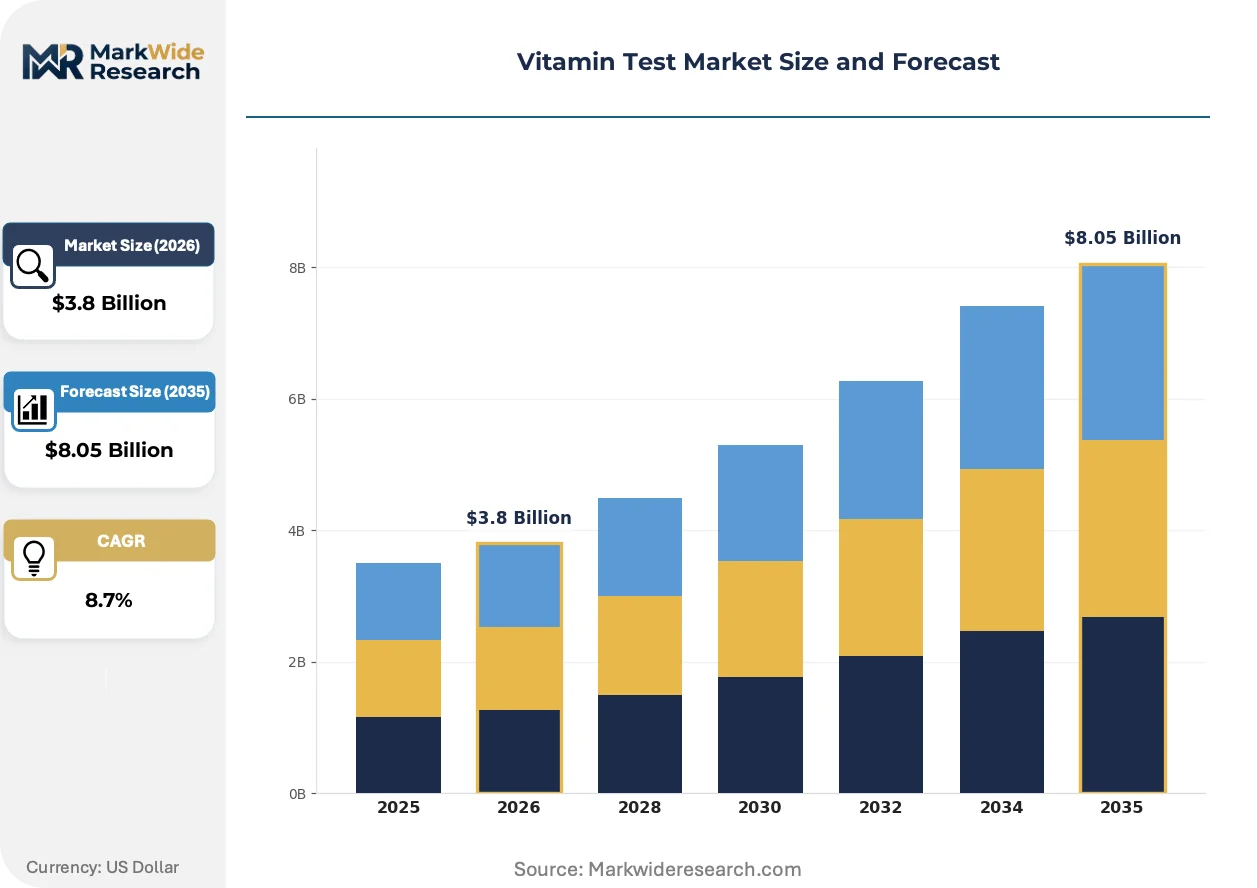
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Serum Analysis, Urine Analysis, Hair Mineral Analysis, Blood Spot Testing Application: Nutrition Assessment, Deficiency Diagnosis, Wellness Screening, Clinical Research End User: Diagnostic Laboratories, Wellness Clinics, Research Institutes, Nutritional Counselors Delivery Mode: Point-of-Care Testing, Laboratory-Based Testing, Home Testing Kits, Mobile Testing Services |
| Companies Covered | F. Hoffmann-La Roche Ltd, Bio-Rad Laboratories, Abbott Laboratories, Thermo Fisher Scientific Inc., Roche Diagnostics, DiaSorin S.p.A, Quest Diagnostics, Orgentec Diagnostika GmbH, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamin Test Market Emerging Trajectories
Diagnostic workflows are fragmenting across multiple access points as specimen collection decentralizes from centralized laboratories toward consumer-controlled environments.
Robotic sample preparation systems are automating liquid-liquid extraction and derivatization steps for vitamin D metabolite quantification. High-throughput clinical laboratories in the United States are deploying these platforms to offset technologist staffing constraints. This automation is compressing batch processing timelines from hours to minutes while reducing solvent consumption and human error rates.
Europe's In Vitro Diagnostic Regulation (IVDR) is recalibrating clinical validity documentation requirements for vitamin test manufacturers seeking CE marking. The expanded notified body oversight is extending technical file preparation timelines by twelve to eighteen months for novel assay formats. Manufacturers are responding by prioritizing predicate device pathways and consolidating product portfolios to focus on highest-volume vitamin D and B12 assays.
Consumer purchasing patterns are shifting toward subscription-based testing models that deliver quarterly vitamin panels through mail-order specimen collection kits. This channel disintermediation is eroding traditional laboratory referral networks while capturing recurring revenue streams. The United States exhibits the most pronounced behavioral shift, where direct-to-consumer brands now compete with established diagnostic service providers for routine nutritional screening volume.
Vitamin Test Market Segmentation
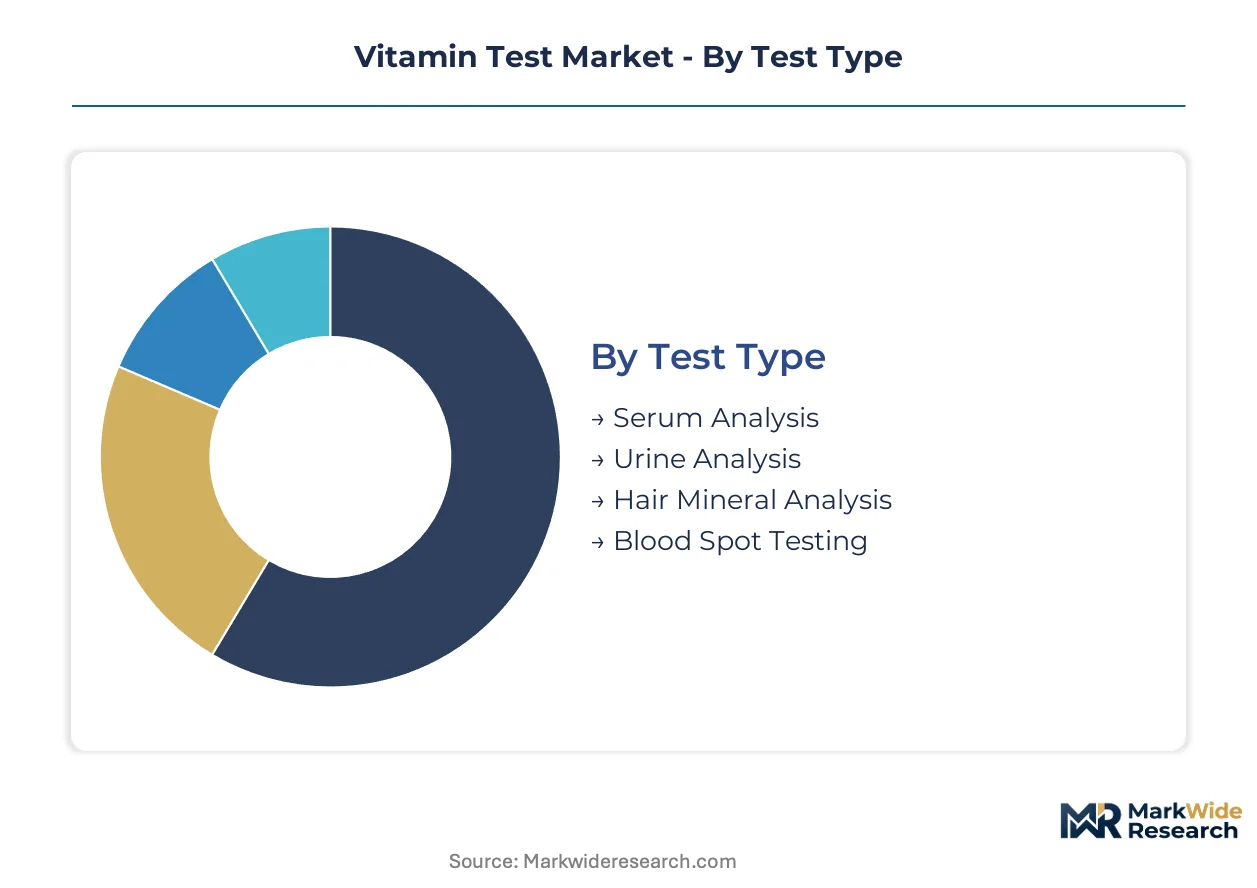
Vitamin test segmentation reveals how specimen type, clinical setting, and distribution channel reshape procurement economics. Laboratories and consumers select testing modalities based on turnaround requirements, reimbursement pathways, and analytical specificity needs.
Test Type:
Specimen chemistry and collection logistics determine analytical sensitivity thresholds and workflow integration.
- Serum Analysis:Liquid-phase specimen processing enables quantitative measurement of circulating vitamin concentrations with established reference intervals. Hospital laboratories in the United States rely on serum protocols for vitamin D and B12 assessments due to CLIA alignment and Medicare reimbursement codes.
- Blood Spot Testing:Dried matrix collection eliminates cold-chain logistics and reduces phlebotomy requirements. Direct-to-consumer brands in the United States deploy blood spot formats for home collection kits targeting wellness subscribers seeking quarterly retesting convenience.
- Urine Analysis:Non-invasive collection suits water-soluble vitamin excretion studies and metabolic assessment panels.
- Hair Mineral Analysis:Keratin-incorporated minerals provide retrospective exposure timelines for research applications.
Serum analysis leads on scale; blood spot testing leads on momentum.
Application:
Clinical intent separates reimbursed diagnostic workflows from self-pay wellness expenditure.
- Deficiency Diagnosis:Symptom-driven testing protocols identify clinically significant insufficiency states requiring therapeutic intervention. Endocrinology practices in the United States order vitamin D panels for patients presenting with fatigue or bone density concerns, triggering insurance coverage under diagnostic necessity criteria.
- Wellness Screening:Asymptomatic population testing captures health-conscious consumers outside traditional care pathways. Employer wellness programs in the United States subsidize comprehensive micronutrient panels as preventive benefits, creating institutional demand independent of clinical indication.
- Nutrition Assessment:Baseline status evaluation supports dietary counseling and supplementation planning.
- Clinical Research:Standardized biomarker quantification enables trial endpoint validation and pharmacokinetic studies.
Deficiency diagnosis commands reimbursement depth; wellness screening expands volume fastest.
End User:
Facility certification tiers and patient access models concentrate purchasing authority across distinct operational scales.
- Diagnostic Laboratories:High-throughput processing centers with CLIA moderate or high complexity certification dominate vitamin D and B12 volume. Quest Diagnostics and Labcorp processing sites in the United States standardize LC-MS/MS protocols to reduce inter-laboratory variability and maintain accreditation compliance.
- Wellness Clinics:Functional medicine practices normalize frequent retesting protocols among affluent patient cohorts seeking optimization rather than disease management. These clinics in California and Texas order comprehensive panels quarterly, bypassing insurance constraints through self-pay arrangements.
- Research Institutes:Academic medical centers and contract research organizations require validated biomarker data for nutritional intervention trials.
- Nutritional Counselors:Independent practitioners leverage point-of-care devices to deliver immediate feedback during client consultations.
Diagnostic laboratories anchor procurement volume; wellness clinics drive panel expansion.
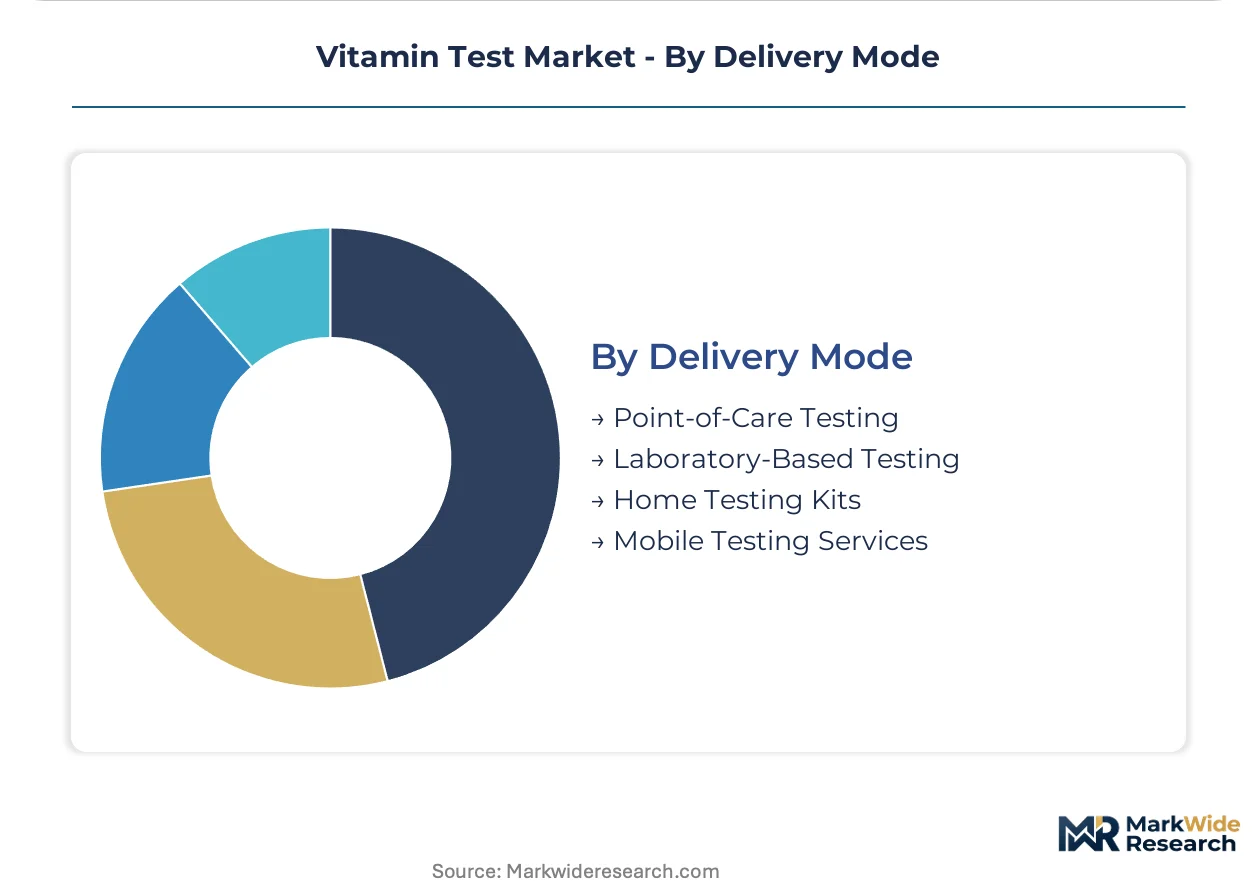
Delivery Mode:
Physical proximity to specimen collection and result reporting compresses or extends commercialization timelines.
- Home Testing Kits:Direct-to-consumer distribution bypasses laboratory networks and captures margin pools previously allocated to collection site fees. Everlywell and similar brands in the United States have established subscription models delivering quarterly vitamin panels through mail-order logistics.
- Point-of-Care Testing:Physician office laboratories with waived or moderate complexity CLIA certification deliver same-day diagnostic turnaround. Primary care clinics in the United States deploy Abbott's point-of-care vitamin D devices to reduce referral delays and capture reimbursement at the point of service.
- Laboratory-Based Testing:Centralized processing maintains analytical gold standards for complex chromatographic assays.
- Mobile Testing Services:On-site collection units serve employer wellness events and rural access gaps.
Laboratory-based testing retains analytical authority; home testing kits capture margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic laboratory clusters in the United States concentrate vitamin testing infrastructure and drive protocol standardization across North America and Europe.
United States
Employer wellness programs and functional medicine practices generate institutional demand for routine micronutrient screening outside traditional diagnostic pathways. FDA 510(k) clearance pathways compress commercialization timelines for at-home testing devices seeking market access. Laboratory networks in California and Texas process high volumes of vitamin D and B12 panels through CLIA-certified facilities.
Germany
Specialized diagnostic laboratories adopt LC-MS/MS platforms to reduce inter-laboratory variability in fat-soluble vitamin quantification. The EU In Vitro Diagnostic Regulation (IVDR) extends technical file preparation timelines for novel assay formats seeking CE marking. Industrial clusters in Bavaria and North Rhine-Westphalia host proficiency testing providers serving Central European accreditation networks.
United Kingdom
National Health Service pathology networks standardize vitamin D testing protocols to manage seasonal deficiency screening demand. The Medicines and Healthcare products Regulatory Agency (MHRA) oversees post-Brexit device registration requirements for IVD manufacturers. London-based reference laboratories supply quality control materials to private diagnostic chains across Southeast England.
Japan
Aging demographics drive demand for nutritional status monitoring in preventive geriatric care protocols. The Pharmaceuticals and Medical Devices Agency (PMDA) evaluates clinical validity documentation for vitamin assay systems seeking market approval. Diagnostic equipment distributors in the Kanto region around Tokyo anchor point-of-care device deployment to physician office laboratories.
India
Rising prevalence of vitamin D deficiency in urban populations expands diagnostic testing volume in metropolitan healthcare networks. The Central Drugs Standard Control Organization (CDSCO) regulates IVD import and manufacturing licensing for domestic market access. Laboratory chains in Maharashtra and Karnataka deploy automated immunoassay platforms to serve employer health screening contracts.
Vitamin Test Market Vendor Landscape
Global majors compete with regional champions across technology platforms and distribution channels, producing a tiered structure where scale-driven conglomerates anchor high-throughput laboratory supply while specialized reagent manufacturers capture niche quality control segments. Three archetypes dominate: diversified life science conglomerates with chromatography and immunoassay portfolios; point-of-care device specialists leveraging waived complexity CLIA certifications; and reference material suppliers sustaining laboratory accreditation compliance. Competitive moves concentrate on predicate device strategies for regulatory clearance acceleration and reagent standardization programs that reduce inter-laboratory variability.
Among diversified diagnostics conglomerates, F. Hoffmann-La Roche Ltd and Abbott Laboratories occupy positions spanning centralized laboratory systems and decentralized point-of-care deployment. Thermo Fisher Scientific Inc. exemplifies the analytical platform archetype, supplying chromatography infrastructure and reagent standardization programs to high-throughput processing centers. These three entities represent distinct competitive vectors: Roche anchors European laboratory automation, Abbott captures US primary care point-of-service workflows, and Thermo Fisher supplies the analytical backbone for mass spectrometry migration.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Bio-Rad Laboratories |
| Abbott Laboratories |
| Thermo Fisher Scientific Inc. |
| Roche Diagnostics |
| DiaSorin S.p.A |
| Quest Diagnostics |
| Orgentec Diagnostika GmbH |
| Siemens AG |
| Others |
Supply Flow & Price Mechanics
Backward integration into reference material production anchors pricing power for vitamin test manufacturers serving CLIA-certified laboratories. Captive supply of certified vitamin D and B12 standards insulates larger diagnostic conglomerates from third-party pricing volatility while compressing margins for smaller competitors dependent on external sourcing.
Pricing Analysis
Input-cost pass-through from certified reference materials and chromatography reagents shapes pricing stratification across laboratory tiers. Three-tier pricing structure across premium, standard, and economy levels separates LC-MS/MS panels from automated immunoassay workflows and basic point-of-care devices. Cost compression in the economy tier is intensifying because direct-to-consumer brands bypass traditional laboratory fee structures. Employer wellness programs exhibit the lowest price sensitivity due to institutional procurement budgets, while independent nutritional counselors face acute margin pressure.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Japan anchor warehouse-distribution layer efficiency for reagent and device logistics. Manufacturing concentration for mass spectrometry instrumentation rests on Germany, the United States, and Singapore, while reference material production draws from the United States and the United Kingdom. Single-source vulnerability in isotope-labeled internal standards creates supply chain risk for LC-MS/MS laboratories. Distribution runs through diagnostic distributor networks serving hospital systems and physician office laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vitamin test market functions as a regulatory compounder where FDA 510(k) clearance milestones for at-home devices accelerate commercialization timelines and expand addressable demand beyond traditional diagnostic channels.
For Market Incumbents: Hedge against direct-to-consumer disintermediation by acquiring predicate device portfolios that compress regulatory timelines for point-of-care expansion. Consolidate reference material production capabilities to defend margin position against reagent cost inflation. Channel control through exclusive distribution agreements with Quest Diagnostics and Labcorp processing networks sustains volume anchoring.
For New Entrants and Emerging Players: Employer wellness program procurement managers represent an underserved buyer archetype with institutional budgets and recurring testing mandates. White-space concentration sits in subscription-based home testing models bypassing physician intermediaries. Target functional medicine practices in Texas and California through direct sales forces rather than distributor intermediaries.
For Investors and Strategic Acquirers: Roll-up economics work for point-of-care device specialists because CLIA certification scarcity creates regional moats around physician office laboratory access. Five-to-ten-year viability hinges on predicate device portfolios and waived complexity assay menus. The signal to watch is CMS reimbursement expansion for nutritional screening panels.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market access for at-home vitamin D testing devices through predicate pathway leverage. |
| Reagent Standardization Program | Thermo Fisher's approach reduces inter-laboratory variability and sustains CLIA accreditation compliance. |
| Hospital System Partnership | Abbott's primary care deployment captures same-day diagnostic reimbursement at point of service. |
| CE Marking Pathway | IVDR compliance timelines extend technical file preparation for European market entry. |
| Software Companion Development | Direct-to-consumer brands integrate result interpretation platforms to reduce physician consultation dependency. |
Methodological Framework
Direct dialogue with diagnostic laboratory directors, CLIA compliance officers, functional medicine practitioners, and reference material procurement managers grounded qualitative findings. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement databases, Clinical Laboratory Improvement Amendments guidance documents, and proficiency testing program records. Bottom-up and top-down triangulation reconciled assay volume estimates with reagent consumption patterns across the analysis window.
Bottom-up modeling segmented vitamin test demand by specimen type, delivery mode, and end-user facility certification tier. Top-down constraints incorporated macro healthcare expenditure patterns and preventive screening penetration rates. CAGR derivation weighted historical CLIA laboratory expansion rates against projected employer wellness program adoption curves. Key inputs included LC-MS/MS platform deployment timelines and direct-to-consumer subscription renewal rates.
Inputs from FDA clearance databases and CMS coverage determinations were available through the study window; gaps in private insurer nutritional testing policy introduce uncertainty bands around wellness screening volume projections. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and reimbursement expansion trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Food Authentication Testing Market
Food Safety Testing
Food and Beverage Protective Cultures Market
Food Safety Testing
Testing, Inspection, and Certification in Consumer Goods and Retail Market
Food Safety Testing
Mycotoxin Testing Market
Food Safety Testing
Global Food Authenticity Testing Market
Food Safety Testing
Meat Speciation Testing Service Market
Food Safety Testing
High-Throughput Food Allergen Screening Test Instruments Market
Food Safety Testing
Edible Oil Adulteration Testing Chemicals Market
Food Safety Testing
Food Testing Services Market
Food Safety Testing
UAE Product Testing Lab Services Market
Food Safety Testing
US Food Safety Testing Market
Food Safety Testing
Europe Food Safety Testing Market
Food Safety Testing
Carbohydrates Testing Services Market
Food Safety Testing
Shelf-Life Testing Market
Food Safety Testing
Water Activity Meter Market
Food Safety Testing
Dairy Testing Services Market