
 Salt Meter Market | 2026-2036
Salt Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Salt Meter Market Outlook
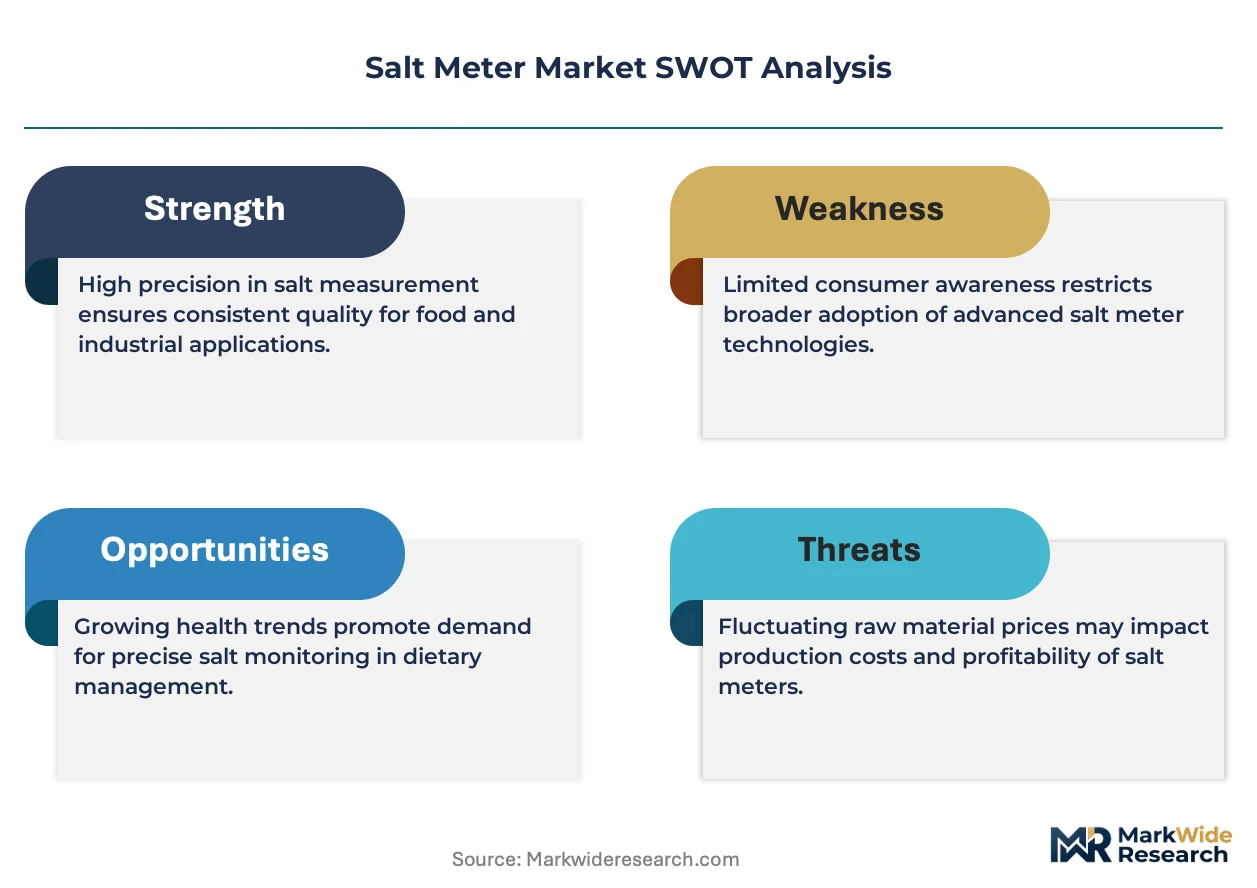
IP67-rated and ATEX-certified specification tiers is redrawing competitive boundaries in the salt meter landscape. Hanna Instruments leverages its coastal manufacturing footprint in Romania to sustain cost-competitive portable meter production. Metrohm anchors its position through high-precision electrochemical titration systems that dominate Swiss pharmaceutical quality labs. Thermo Fisher Scientific differentiates via deep integration with laboratory information management systems across North American research campuses.
A salt meter is an analytical instrument that measures sodium chloride concentration or total dissolved solids through conductivity, ion-selective electrode response, or refractive index detection, typically operating across ranges from 0.01 ppm to saturation with temperature compensation algorithms. Its primary commercial purpose is ensuring formulation consistency in food brining operations and detecting boiler feedwater contamination before scaling damages industrial heat exchangers. Portable meters lead unit shipments due to field deployment in environmental monitoring, while benchtop configurations command margin pools in pharmaceutical quality control laboratories where 21 CFR Part 11 compliance adds validation overhead. Electrochemical technology occupies the largest installed base, though optical methods are gaining traction in chemical manufacturing for non-contact measurement of corrosive process streams.
The EPA enforces salinity discharge limits under the Clean Water Act National Pollutant Discharge Elimination System, compelling water treatment utilities to install continuous monitoring equipment or face permit revocation. ISO 7888 and ASTM D1125 establish conductivity measurement protocols that manufacturers must validate for laboratory meter certification in regulated industries. FDA hazard analysis requirements for food processing facilities mandate documented salt concentration verification at critical control points, directly driving benchtop meter procurement in commercial bakeries and cured meat operations. Stakeholders must weigh the capital efficiency of smart meter connectivity against the cybersecurity exposure of cloud-based calibration management before committing to next-generation platform architectures.
Market Dynamics
The EU Green Deal's industrial discharge standards are compressing upgrade cycles for salinity monitoring equipment, forcing water treatment utilities and chemical manufacturers to replace legacy conductivity meters with continuous monitoring systems before permit deadlines.
Growth Catalysts
- Food Safety Mandates:FDA hazard analysis requirements for commercial bakeries and cured meat operations mandate documented salt concentration verification at critical control points, directly driving benchtop meter procurement.
- EPA Enforcement:The Clean Water Act National Pollutant Discharge Elimination System compels water treatment utilities to install continuous monitoring equipment or face permit revocation.
- Process Automation:Chemical manufacturing corridors in Germany are expanding inline conductivity sensing for real-time brine and process stream quality control.
Market Restraints
- Electrode Supply Concentration:Specialized ion-selective membrane production concentrates among limited suppliers in Japan and Switzerland, creating input bottlenecks for electrochemical meter manufacturers.
- Validation Overhead:21 CFR Part 11 compliance requirements for pharmaceutical laboratories add 18-24 month validation timelines to benchtop meter deployments, compressing near-term revenue recognition.
- Optical Substitution:Refractive index sensors are displacing contact-based conductivity methods in corrosive chemical process streams, threatening electrochemical technology's installed base.
Strategic Opportunities
- Smart Meter Connectivity:Cloud-based calibration management platforms enable recurring service revenue streams, though stakeholders must weigh cybersecurity exposure against capital efficiency gains.
- Environmental Monitoring Expansion:Coastal water quality programs in Australia and field salinity mapping in agricultural regions present underpenetrated demand for portable meter deployments.
- ATEX-Certified Tiers:Hazardous area certification requirements in EU chemical plants create premium pricing tiers for explosion-proof portable meters serving refinery and petrochemical maintenance crews.
Industry Challenges
- Electrochemical Expertise Scarcity:Ion-selective electrode maintenance and calibration require specialized analytical chemistry skills that field service organizations struggle to recruit and retain.
- Legacy System Integration:Laboratory information management system connectivity demands vary across North American research campuses, forcing meter vendors to support multiple data protocol configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Salt Meter Market |
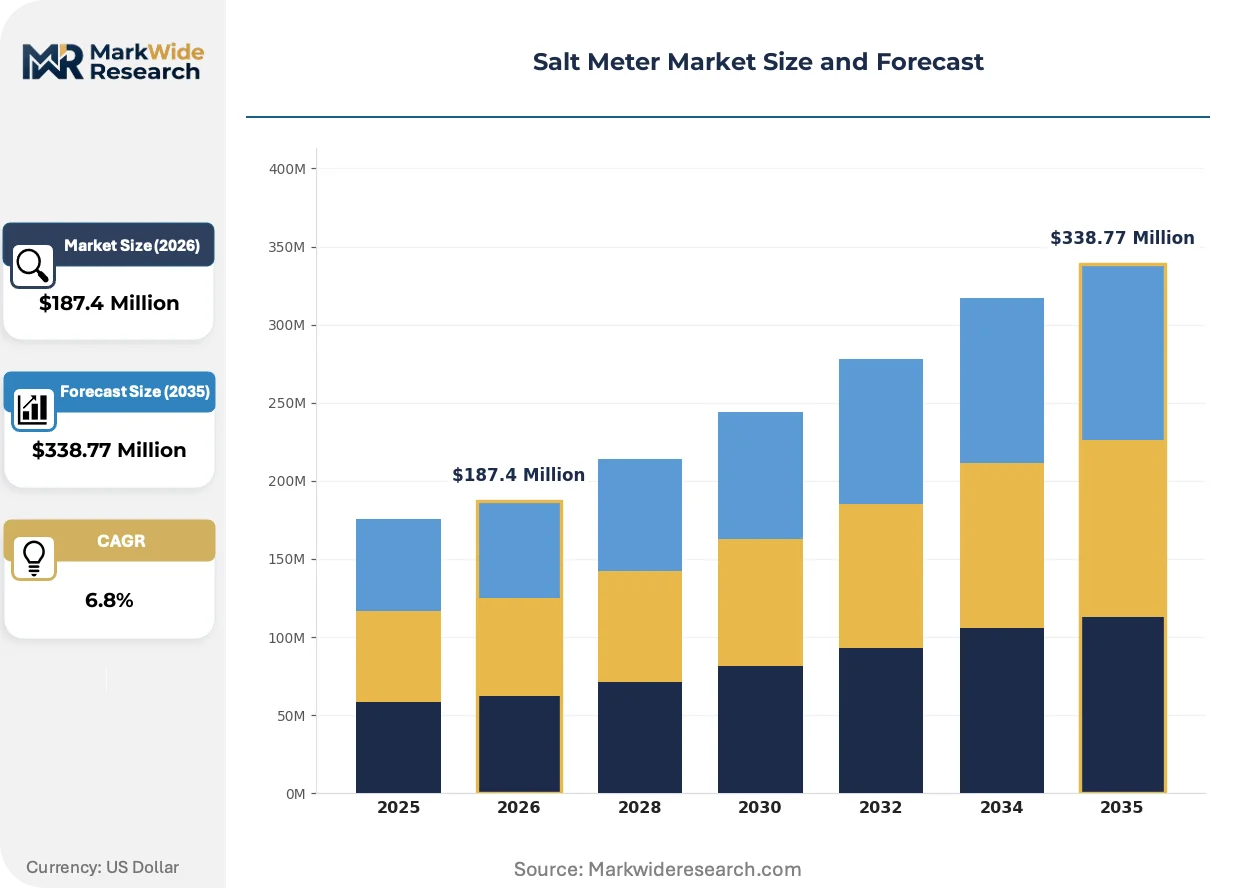
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Meters, Benchtop Meters, Laboratory Meters, Smart Meters End User: Food Processing, Chemical Manufacturing, Water Treatment, Laboratory Testing Technology: Conductivity, Ion-Specific, Optical, Electrochemical Application: Quality Control, Research, Environmental Monitoring, Industrial Processes |
| Companies Covered | Thermo Fisher Scientific, Mettler Toledo, Hanna Instruments, YSI (Xylem), Metrohm, Horiba, Oakton, Extech Instruments, Lovibond, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Salt Meter Market Strategic Shifts
Sensor architecture is converging with wireless telemetry and edge computing, compressing the form-factor and connectivity gap between portable field instruments and laboratory-grade benchtop systems.
Microfabricated solid-state conductivity sensors are miniaturizing the traditional electrode assembly into chip-scale packages. Environmental monitoring agencies and agricultural extension services are adopting these reduced-footprint devices for drone-mounted and distributed sensor network deployments. This form-factor compression is miniaturizing the addressable market boundary between portable and benchtop configurations, enabling new deployment geometries previously constrained by probe dimensions.
REACH substance restrictions on mercury-containing reference electrodes are forcing electrochemical meter manufacturers to accelerate silver-silver chloride and solid-state reference designs. The industrial consequence is a 12-18 month redesign cycle for legacy product lines serving European pharmaceutical and food processing laboratories. German chemical manufacturers and Swiss quality control facilities are most affected, with procurement teams now requiring RoHS-compliant documentation for all new meter acquisitions.
Calibration-as-a-service models are displacing traditional equipment ownership in North American municipal water utilities. Third-party metrology providers now perform on-site conductivity cell verification and certificate generation, unbundling the after-sales service relationship from original equipment manufacturers. This service unbundling is most visible in California and Texas water districts facing EPA audit pressure and seeking to outsource compliance documentation liability.
Salt Meter Market Segmentation
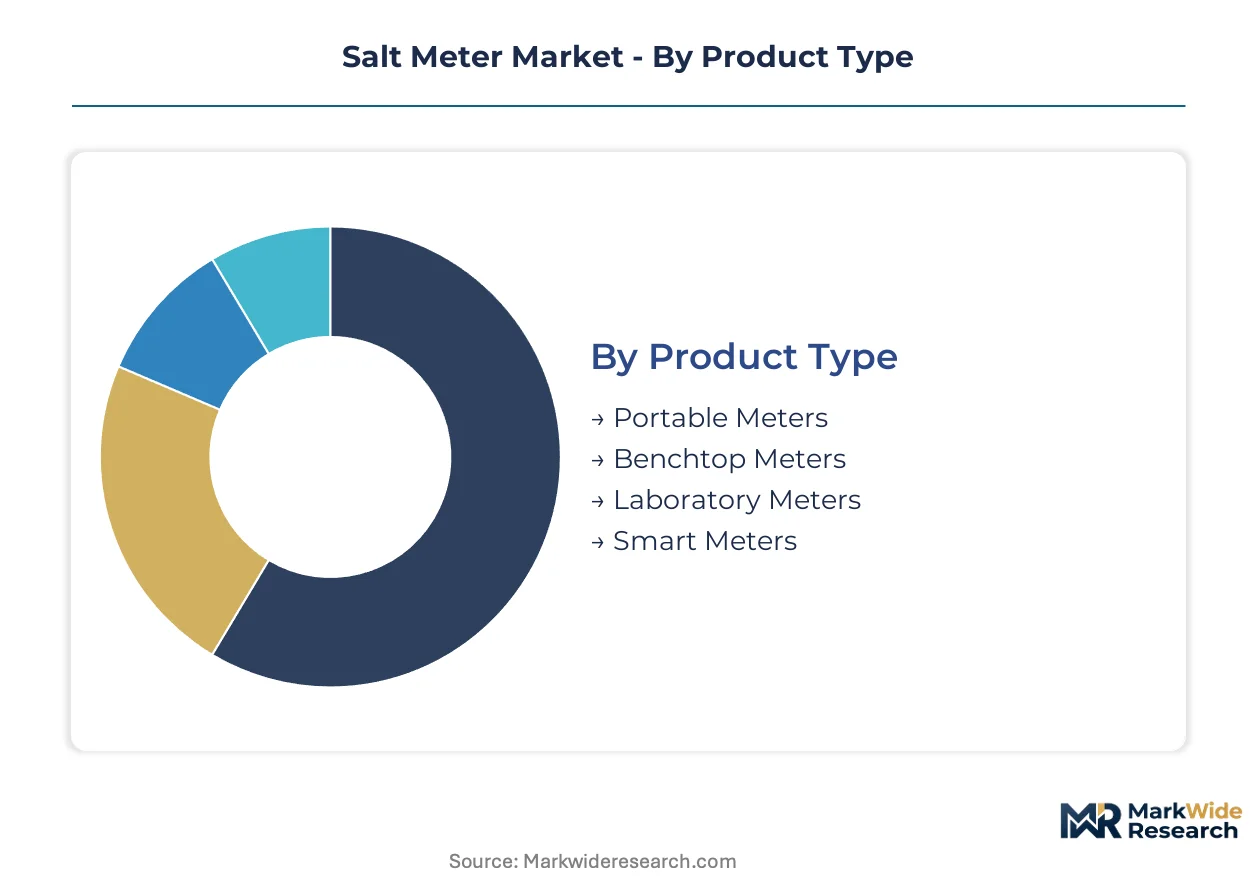
Salt meter procurement patterns diverge sharply between field-deployable instruments and laboratory-grade systems, with certification requirements and connectivity features determining margin capture across each tier. Understanding where volume concentrates versus where pricing power accumulates enables vendors to align R&D investment with actual purchase decision drivers.
Product Type:
Margin pools concentrate in configurations that balance portability with validation-ready documentation capabilities, particularly where regulatory audit trails are mandatory.
- Portable Meters:Handheld conductivity and TDS units with IP67 sealing and automatic temperature compensation serve environmental monitoring crews and food processing floor technicians. Demand clusters in Australia's coastal water quality programs and Germany's chemical corridor maintenance operations, where ATEX certification commands premium positioning for refinery deployment.
- Benchtop Meters:Laboratory-grade instruments with 21 CFR Part 11 compliant software and LIMS integration dominate pharmaceutical quality control and commercial bakery critical control point verification. FDA hazard analysis documentation requirements drive replacement cycles in US cured meat operations and Swiss pharmaceutical facilities.
- Laboratory Meters:High-precision electrochemical titration systems with multi-parameter capability serve research campuses and reference laboratories requiring traceable calibration chains.
- Smart Meters:Cloud-connected devices with edge computing architecture enable remote calibration management and predictive maintenance alerts for distributed water utility networks.
Benchtop meters hold installed capacity. Smart meters are rotating up the share rankings.
End User:
Application intensity varies by sector compliance burden and process criticality, with food safety mandates creating the most predictable procurement timelines.
- Food Processing:Commercial bakeries and cured meat operations require documented salt concentration verification at HACCP critical control points, driving benchtop meter standardization. USDA-FSIS inspection protocols and FDA hazard analysis requirements create non-negotiable replacement demand.
- Water Treatment:Municipal utilities and industrial discharge facilities install continuous monitoring systems to meet EPA NPDES permit conditions and EU Green Deal discharge standards. California and Texas districts increasingly outsource calibration verification to third-party metrology providers.
- Chemical Manufacturing:BASF and Evonik operations in Germany's chemical corridor deploy inline conductivity sensing for real-time brine and process stream quality control.
- Laboratory Testing:Academic research campuses and contract testing facilities require multi-method flexibility and LIMS connectivity across diverse sample matrices.
Water treatment holds installed capacity. Food processing is rotating up the share rankings.
Technology:
Measurement modality selection hinges on sample corrosivity, required detection limits, and maintenance expertise availability in the deployment environment.
- Electrochemical:Ion-selective electrode systems with silver-silver chloride reference designs dominate pharmaceutical and food laboratory installed bases. REACH substance restrictions on mercury-containing electrodes are forcing 12-18 month redesign cycles for European product lines.
- Conductivity:Four-cell and toroidal conductivity sensors provide the workhorse measurement approach for water treatment and industrial process applications, with microfabricated solid-state variants enabling drone-mounted environmental deployments.
- Optical:Refractive index sensors enable non-contact measurement of corrosive chemical process streams, threatening electrochemical technology's position in harsh manufacturing environments.
- Ion-Specific:Targeted sodium and chloride selective electrodes offer interference-resistant measurement for complex matrices in research and specialty chemical applications.
Electrochemical holds installed capacity. Optical is rotating up the share rankings.
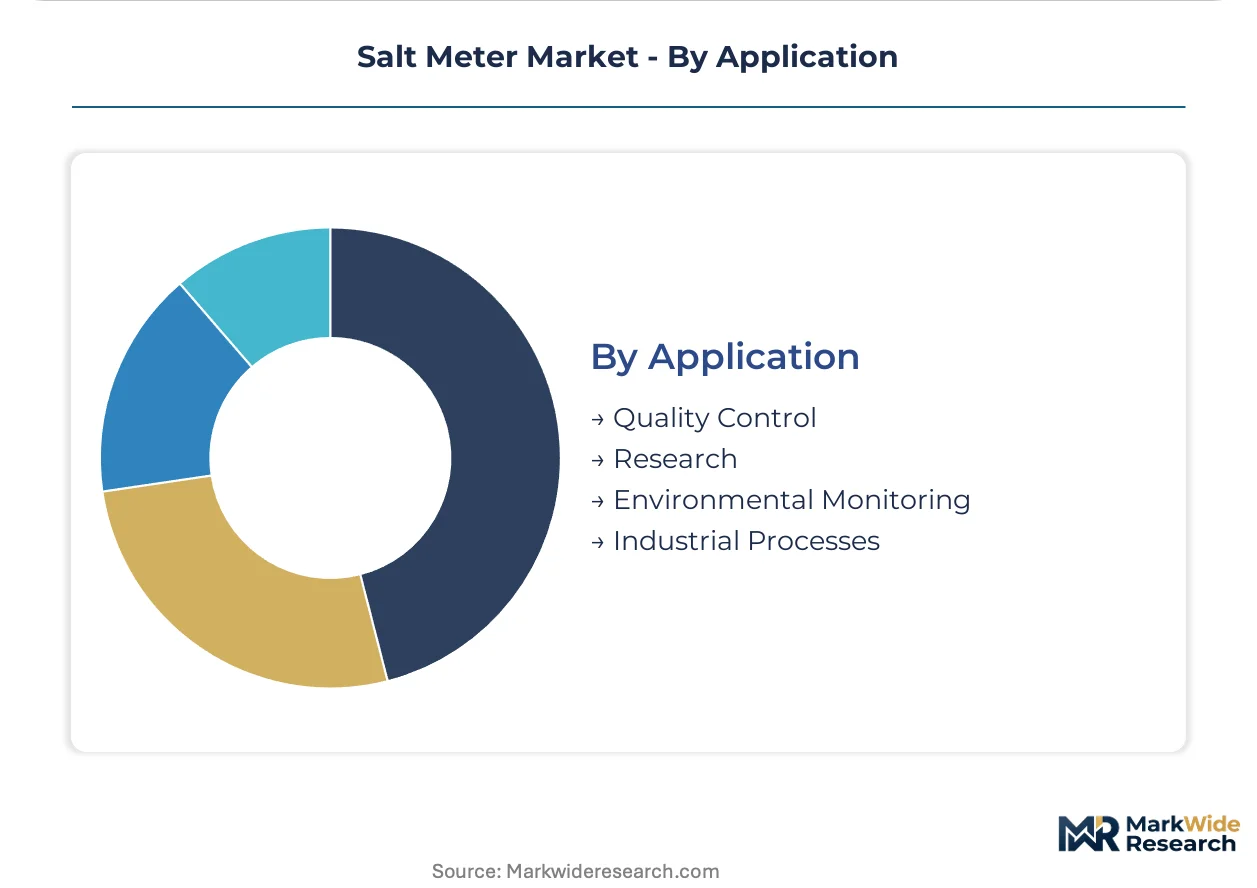
Application:
Use case differentiation determines whether procurement prioritizes speed, precision, or regulatory defensibility in instrument specification.
- Quality Control:Inline and at-line measurement systems with automated pass-fail alarming dominate food brining operations and chemical process streams where formulation consistency directly impacts yield.
- Environmental Monitoring:Portable and distributed sensor networks for coastal water quality and agricultural salinity mapping are expanding most quickly, driven by Australian government monitoring programs and precision agriculture adoption.
- Industrial Processes:Continuous conductivity monitoring protects boiler feedwater systems and heat exchangers from scaling damage in power generation and manufacturing facilities.
- Research:Multi-parameter flexibility and method development capabilities serve academic and government laboratory investigation requirements.
Quality control holds installed capacity. Environmental monitoring is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized ion-selective membrane production concentrates among limited suppliers in Japan and Switzerland, creating input bottlenecks that shape regional deployment patterns. Germany's chemical corridor and Swiss pharmaceutical clusters anchor European demand for high-precision instrumentation.
United States
EPA enforcement of Clean Water Act NPDES permits compels municipal utilities in California and Texas to install continuous salinity monitoring or face revocation. FDA hazard analysis requirements drive benchtop meter standardization in commercial bakeries and cured meat operations across the Midwest and Southeast.
Germany
BASF and Evonik operations in the chemical corridor deploy inline conductivity sensing for real-time brine quality control. EU Green Deal discharge standards compress upgrade cycles for legacy equipment, forcing water treatment facilities toward continuous monitoring systems before permit deadlines.
Switzerland
Pharmaceutical quality laboratories in Basel and Geneva require 21 CFR Part 11 compliant benchtop systems with traceable calibration chains. REACH substance restrictions on mercury-containing reference electrodes accelerate silver-silver chloride redesign cycles for electrochemical product lines.
Australia
Coastal water quality programs and agricultural salinity mapping expand portable meter deployment in New South Wales and Queensland. Government monitoring initiatives and precision agriculture adoption create underpenetrated demand for field-deployable environmental instrumentation.
Japan
Specialized ion-selective membrane manufacturing concentrates among precision materials suppliers serving domestic electrochemical meter producers. METI industrial standards and domestic pharmaceutical quality requirements sustain demand for high-reliability laboratory-grade systems in Osaka and Tokyo research clusters.
Salt Meter Market Competitive Environment
Concentration sits with diversified analytical instrumentation conglomerates and specialized electrochemical equipment manufacturers. The vendor base spans three tiers: multinational laboratory technology providers with LIMS integration capabilities, mid-scale portable instrument specialists leveraging coastal manufacturing footprints, and regional electrochemical component suppliers facing membrane input constraints. Strategic moves center on cloud-based calibration service unbundling and hazardous area certification tiering for refinery and petrochemical maintenance segments.
Within the multinational tier, Thermo Fisher Scientific and Mettler Toledo exemplify laboratory-grade system providers with North American and Swiss origins respectively. Hanna Instruments occupies a position among portable instrument specialists. Metrohm represents the precision electrochemical titration archetype anchored in Swiss pharmaceutical quality control markets.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Mettler Toledo |
| Hanna Instruments |
| YSI (Xylem) |
| Metrohm |
| Horiba |
| Oakton |
| Extech Instruments |
| Lovibond |
| Others |
Value Chain & Pricing Dynamics
Silver-silver chloride reference electrode substitution for mercury-containing designs simultaneously shifts component sourcing toward Japanese and Swiss precision materials suppliers and compresses margin structures for European electrochemical meter manufacturers facing 12-18 month redesign cycles.
Pricing Analysis
EU Green Deal discharge standards dictate the pricing tier structure across salt meter procurement, with ATEX-certified portable units commanding premium positioning against standard IP67 configurations. Three-tier pricing structure across premium, standard, and economy levels separates explosion-proof refinery-grade instruments from laboratory validation-ready systems and basic field conductivity probes. Cost compression in the portable segment is intensifying because Romanian coastal manufacturing footprints enable Hanna Instruments to sustain aggressive positioning. Municipal water utilities exhibit the highest price sensitivity due to budget-constrained procurement cycles, while pharmaceutical quality laboratories show relative inelasticity given 21 CFR Part 11 compliance mandates.
Supply Chain Analysis
Strategic stockpiling of ion-selective membranes dominates procurement behavior among electrochemical meter manufacturers confronting concentrated Japanese and Swiss supplier bases. Component sourcing draws from Japan for specialized membrane substrates, Switzerland for precision reference electrode assemblies, and Romania for cost-optimized portable instrument final assembly. Single-source vulnerability in mercury-free reference electrode chemistry creates exposure to REACH substance restriction enforcement timelines. Distribution runs through authorized analytical instrumentation distributors serving laboratory and industrial end-users, with direct OEM relationships penetrating large water utility accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized electrochemical expertise scarcity constrains field service scalability and shapes competitive moats around vendors with captive calibration capabilities.
For Market Incumbents: Consolidate membrane supply relationships through backward integration into silver-silver chloride reference electrode production or exclusive offtake agreements with Swiss and Japanese materials suppliers. Deepen vertical integration into cloud-based calibration service platforms to capture recurring revenue streams threatened by third-party metrology provider unbundling in California and Texas water districts.
For New Entrants and Emerging Players: Cloud-based calibration management under-service among legacy electrochemical specialists creates entry pathways for SaaS-native instrumentation vendors. Target Australia's coastal water quality programs and agricultural salinity mapping initiatives where government monitoring budgets expand faster than incumbent field service capacity. Lead with drone-compatible microfabricated solid-state sensor form factors that compress deployment geometries beyond traditional probe limitations.
For Investors and Strategic Acquirers: The market sits at a regulatory-forced technology transition phase that favors electrochemical component specialists with mercury-free reference electrode capabilities. Long-term viability hinges on validation-ready benchtop meter positions in pharmaceutical and food safety verticals where compliance documentation creates sticky replacement demand. Watch for EPA NPDES permit deadline clustering as inflection signal for continuous monitoring system procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Silver-Silver Chloride Reference Electrode Transition | REACH compliance redesign cycles force 12-18 month product line overhauls for European laboratory meter suppliers. |
| Cloud-Based Calibration Platform Launch | Third-party metrology unbundling in California and Texas water districts threatens OEM service revenue capture. |
| Microfabricated Solid-State Sensor Development | Drone-mounted environmental deployments in Australian coastal monitoring programs expand addressable form-factor geometries. |
| ATEX Certification Tier Expansion | EU chemical corridor refinery maintenance crews command premium pricing for explosion-proof portable conductivity meters. |
| LIMS Integration Partnership | North American research campus connectivity demands vary across multiple data protocol configurations requiring vendor flexibility. |
Study Parameters
Cross-validation between primary interviews with water utility planning officers, pharmaceutical quality control directors, chemical plant maintenance engineers, and environmental monitoring agency procurement leads anchors the qualitative findings against secondary validation from EPA NPDES permit databases, EU ECHA REACH substance restriction filings, FDA warning letter archives, and ISO 7888 certification records. Bottom-up instrument shipment estimates triangulate against top-down water treatment capital expenditure disclosures and food processing facility HACCP documentation requirements.
Sensitivity analysis around regulatory deadline clustering and membrane supply concentration stress-tests the analytical framework across the projection horizon. Segmentation dimensions span product configuration tier, end-use industry compliance burden, measurement technology modality, and regional regulatory enforcement intensity. CAGRs derive from installed base replacement cycle analysis and greenfield continuous monitoring system penetration curves, with specific weighting for EU Green Deal permit deadline impacts and FDA food safety mandate expansion trajectories.
Underlying assumptions cover stable REACH substance restriction enforcement timelines and consistent EPA NPDES audit intensity, with deviation risk concentrated in optical sensor substitution rates for corrosive chemical process streams. Revision becomes warranted when refractive index sensor cost-performance thresholds cross electrochemical method defensibility boundaries in harsh manufacturing environments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Inline Beverage Gas and Microbial Load Monitoring Test Systems Market
Food Safety Testing
Food Safety Testing Services Market
Food Safety Testing
Water Activity Instrumentation Market
Food Safety Testing
Global Lipid Testing Market
Food Safety Testing
Adulteration Tester Market
Food Safety Testing
High-Throughput Food Allergen Screening Test Instruments Market
Food Safety Testing
Xylose Absorption Tests Market
Food Safety Testing
UK Food Testing Market
Food Safety Testing
Salmonella Testing Market
Food Safety Testing
Food and Beverage Protective Cultures Market
Food Safety Testing
Beverage Tester Market
Food Safety Testing
South Africa Food Safety Testing Market
Food Safety Testing
US Food Allergen Testing Market
Food Safety Testing
Water Quality Testing Market
Food Safety Testing
Food Traceability Solutions Market
Food Safety Testing
Global Inline Metal Detector Market