
 Non-Hormonal Steroid Modulators Market | 2026-2036
Non-Hormonal Steroid Modulators Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Hormonal Steroid Modulators Market Analytics
Plant-derived phytosterol precursors is realigning raw-material economics for non-hormonal steroid modulators, displacing traditional synthetic cholesterol-based feedstocks across oral and injectable formulations. Bristol Myers Squibb Company leverages its biologics manufacturing infrastructure to sustain cost advantages in peptide-based myostatin inhibitor production. Novartis anchors its position through geographic dominance in European specialty distribution channels for clinical-grade SARMs. Amgen differentiates via R&D intensity in next-generation androgen receptor partial agonists with improved tissue selectivity profiles.
Non-hormonal steroid modulators comprise synthetic or naturally derived compounds that bind androgen, glucocorticoid, or related steroid receptors without direct hormone conversion, typically exhibiting tissue-selective anabolic activity with molecular weights between 300 and 600 Daltons and oral bioavailability thresholds exceeding 20 percent. Their primary commercial purpose centers on preserving or augmenting lean muscle mass while minimizing androgenic side effects in therapeutic and performance contexts. Selective androgen receptor modulators dominate current revenue pools due to established prescriber familiarity and broader clinical investigation portfolios, while myostatin inhibitors represent the fastest-growing product category as follistatin-derived peptides advance through late-stage trials for muscular dystrophy indications. The athletes and bodybuilders end-user segment commands premium pricing through direct-to-consumer channels, whereas clinical patients concentrate volume through institutional procurement contracts with hospital systems.
The FDA maintains stringent oversight of SARMs under the Designer Anabolic Steroid Control Act, classifying non-approved compounds as Schedule III controlled substances and restricting compounding pharmacy formulations. The DEA coordinates with the FDA to intercept unapproved SARM imports, while USADA and WADA anti-doping protocols shape legitimate demand by disqualifying competitive athletes using these agents. The FTC supplements this framework by prosecuting dietary supplement manufacturers making unsubstantiated muscle-building claims for products containing undisclosed SARM analogues. Stakeholders must monitor pending legislative amendments that could reclassify certain tissue-selective agents as legitimate prescription therapies rather than controlled substances.
Market Dynamics
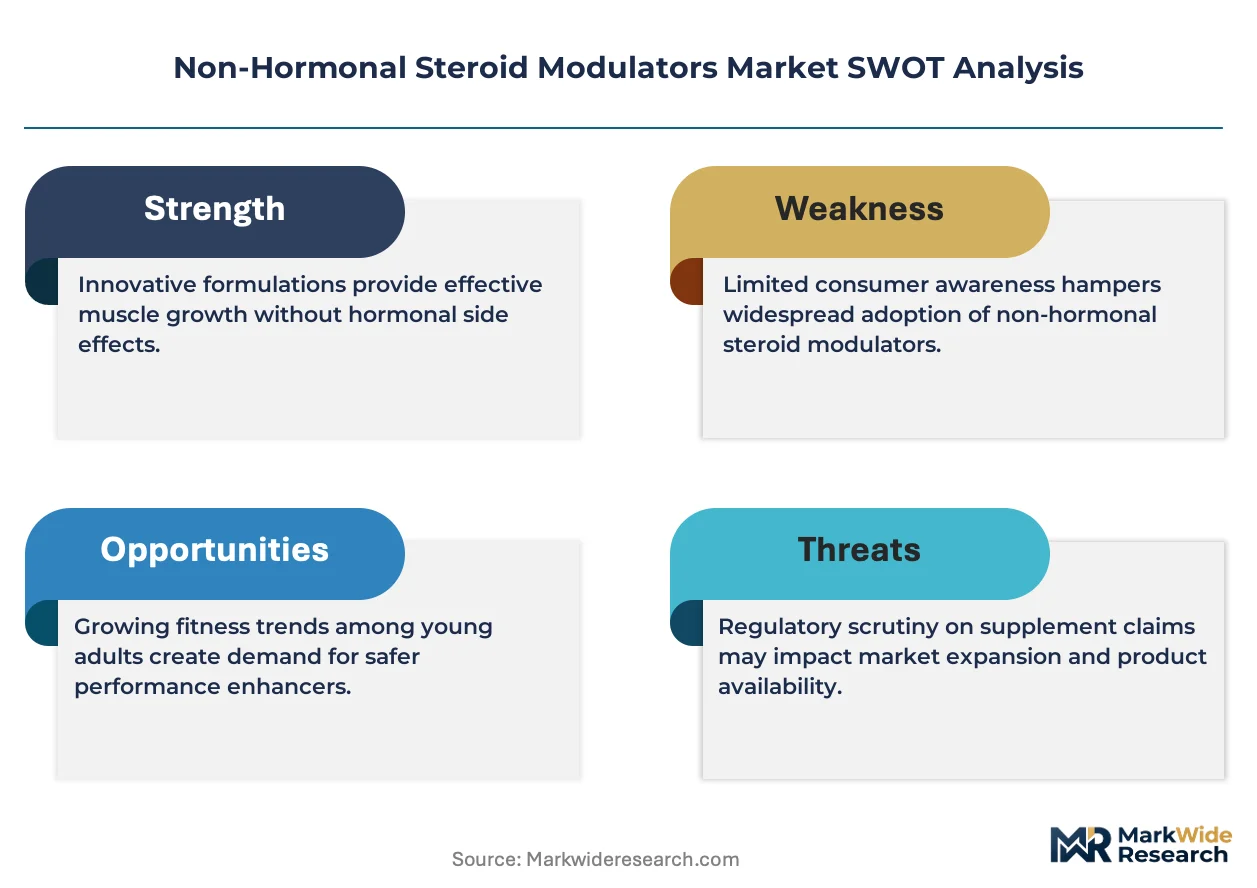
The FDA's evolving enforcement posture under the Designer Anabolic Steroid Control Act is compressing gray-market channels while redirecting demand toward legitimate clinical pathways and compounding pharmacy networks.
Growth Catalysts
- Tissue-selective anabolic agents:Clinical patients drive volume expansion as off-label prescribing patterns shift toward SARMs with improved safety profiles. Hospital procurement contracts concentrate demand through institutional channels.
- Phytosterol precursor technology:Plant-derived feedstocks displace synthetic cholesterol bases in oral and injectable formulations, reducing raw-material cost volatility for manufacturers.
- Specialty pharmacy infrastructure:United States distribution networks expand prescriber access to clinical-grade products, connecting endocrinology practices with compounding facilities.
Market Restraints
- Schedule III controlled substance classification:FDA-DEA coordination restricts interstate commerce of non-approved SARM analogues, limiting formulation flexibility for domestic manufacturers.
- Peptide manufacturing cost structure:Follistatin-derived myostatin inhibitors require biologics-grade production infrastructure, creating capital barriers for mid-scale entrants.
- Import interception protocols:DEA enforcement at ports of entry disrupts raw material supply for unapproved compounds, concentrating risk at international sourcing nodes.
Strategic Opportunities
- Muscular dystrophy therapeutic applications:Late-stage trials for myostatin inhibitors in orphan indications open priority review pathways and extended exclusivity provisions.
- European specialty distribution channels:Geographic expansion through EMA-aligned regulatory frameworks accesses reimbursed prescription markets with established clinical protocols.
- Direct-to-consumer telehealth platforms:Digital prescribing infrastructure connects anti-aging clinics with compounding pharmacies, bypassing traditional hospital procurement.
Industry Challenges
- Androgen receptor pharmacology expertise:Tissue-selective ligand design requires specialized medicinal chemistry talent scarce outside large pharmaceutical R&D organizations.
- Anti-doping protocol compliance:USADA and WADA substance lists create liability exposure for manufacturers whose products reach competitive athletes through diversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Hormonal Steroid Modulators Market |
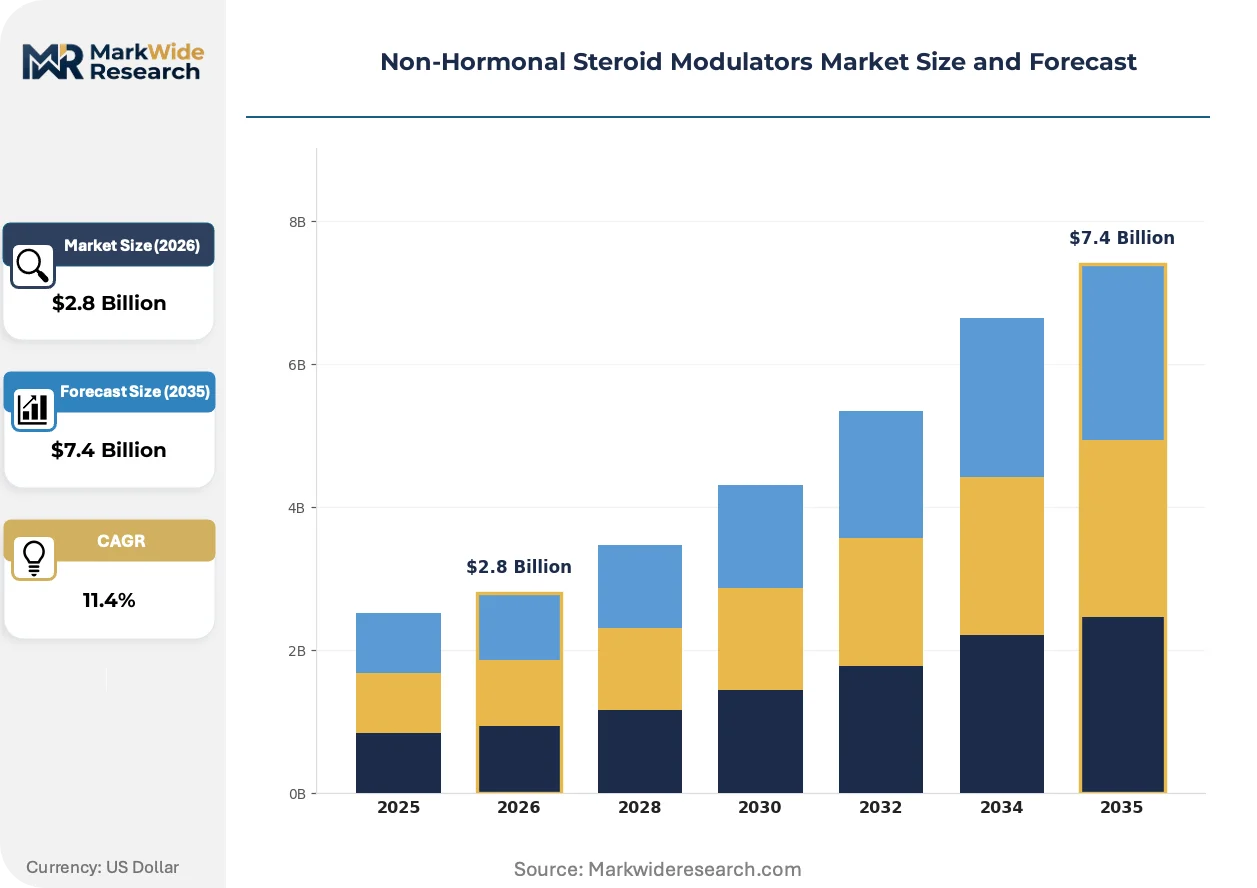
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Selective Androgen Receptor Modulators, Myostatin Inhibitors, Nutritional Supplements, Peptides Application: Muscle Growth, Fat Reduction, Strength Enhancement, Performance Optimization End User: Athletes, Bodybuilders, Fitness Enthusiasts, Clinical Patients Delivery Mode: Oral, Injectable, Topical, Powder |
| Companies Covered | AbbVie, Bristol Myers Squibb Company, Novartis, Amgen, Pfizer, Merck, Sanofi, Genentech, Janssen Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Hormonal Steroid Modulators Market Evolving Landscape
Receptor engineering and manufacturing process intensification are compressing development timelines while regulatory arbitrage between clinical and wellness channels reshapes commercial strategy.
Next-generation androgen receptor partial agonists with improved tissue selectivity profiles are integrating computational docking models into lead optimization workflows. Specialty endocrinology practices adopt these candidates at accelerated enrollment rates for sarcopenia trials. The technology is integrating structure-based design into early-stage discovery, compressing preclinical timelines for oral bioavailable candidates.
REACH registration requirements for novel synthetic steroid scaffolds are tightening substance notification protocols across EU member states. Industrial consequence includes mandatory toxicity dossiers for import quantities exceeding one tonne annually. Clinical-grade SARM manufacturers with existing EMA master file submissions capture first-mover advantage in reimbursed prescription channels.
Prescribing authority consolidation among anti-aging and functional medicine clinics is displacing fragmented direct-to-consumer supplement retail. Specialty telehealth platforms aggregate patient panels across state lines, replacing independent compounding pharmacy relationships with centralized fulfillment contracts. This channel compression is most visible in Florida, Texas, and Arizona where regulatory alignment permits interstate telehealth prescribing.
Non-Hormonal Steroid Modulators Market Segmentation
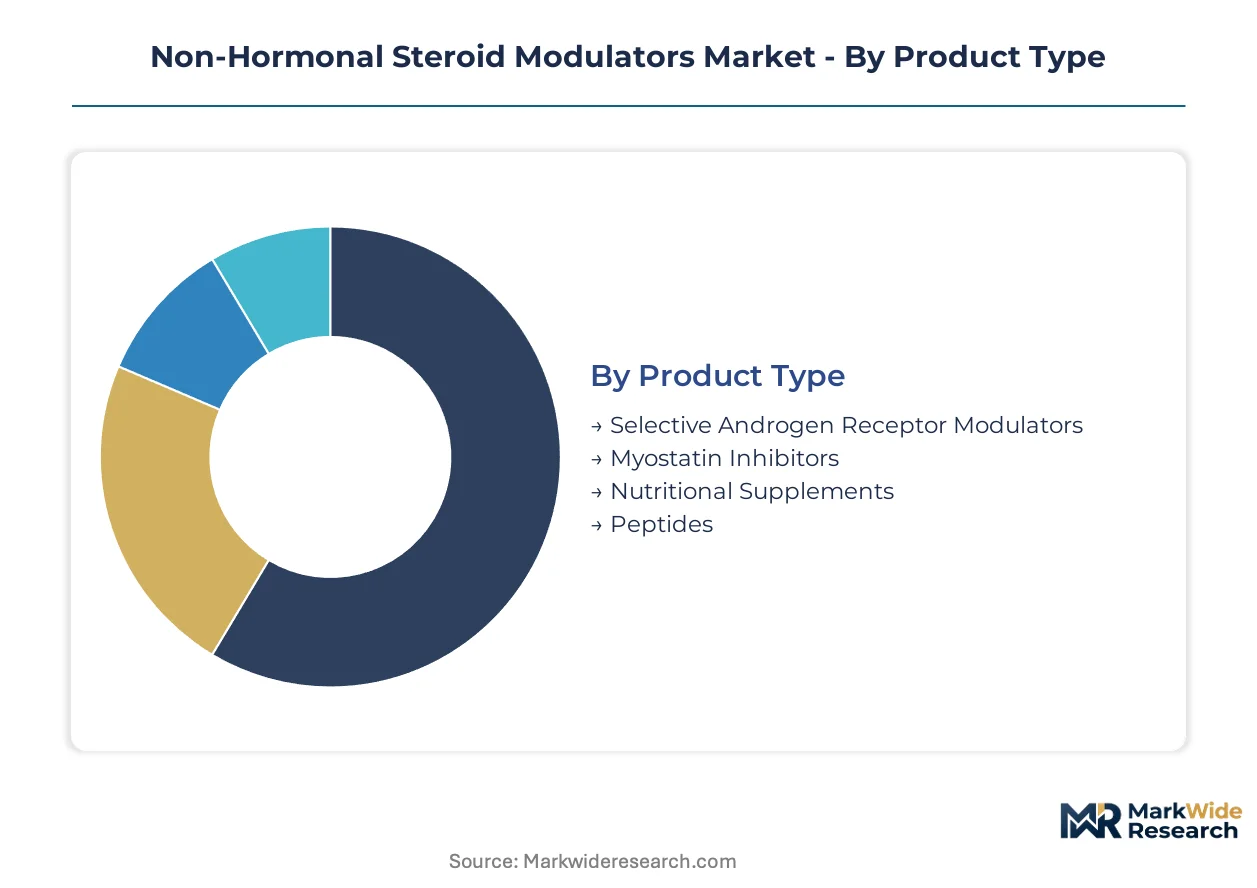
Segmentation in the Non-Hormonal Steroid Modulators Market reveals distinct commercial pathways between regulated clinical channels and discretionary wellness consumption. Product architecture and delivery mode determine regulatory exposure, while end-user identity shapes pricing power and distribution infrastructure requirements.
Product Type:
Standalone therapeutic compounds command premium positioning through prescription networks, whereas nutritional formulations embed within broader supplement portfolios with reduced regulatory scrutiny.
- Selective Androgen Receptor Modulators:Synthetic non-steroidal ligands with molecular weights between 300 and 600 Daltons bind androgen receptors with tissue-selective activation profiles. Hospital procurement contracts in the United States concentrate demand through endocrinology and oncology practices managing sarcopenia and cachexia. The FDA's Schedule III classification under the Designer Anabolic Steroid Control Act restricts interstate commerce to approved investigational protocols.
- Myostatin Inhibitors:Follistatin-derived peptides and antibody constructs block myostatin signaling to promote skeletal muscle hypertrophy. Late-stage trials for muscular dystrophy indications in the United States and European Union are accelerating clinical adoption through orphan drug pathways. Biologics-grade manufacturing infrastructure creates capital barriers that favor established pharmaceutical manufacturers.
- Nutritional Supplements:Plant-derived phytosterol precursors and proprietary blends target fitness enthusiasts through direct-to-consumer channels.
- Peptides:Short-chain amino acid sequences with growth hormone secretagogue activity serve anti-aging clinic protocols.
Selective Androgen Receptor Modulators lead volumes today; Myostatin Inhibitors are gaining share fastest.
Application:
Cost tier differentiation separates reimbursed therapeutic indications from discretionary performance enhancement, with institutional procurement anchoring the premium segment.
- Muscle Growth:Preservation and augmentation of lean body mass drives the primary clinical value proposition for sarcopenia and cancer cachexia management. United States specialty pharmacies fulfill prescriptions through compounding networks serving anti-aging and functional medicine practices. Reimbursement pathways through Medicare Part B concentrate volume in institutional settings.
- Strength Enhancement:Neuromuscular performance improvement targets competitive and recreational athletes through both clinical and gray-market channels. WADA and USADA prohibited substance lists create liability exposure for manufacturers whose products divert into sports applications. European anti-doping agencies coordinate with customs authorities to intercept unapproved peptide imports.
- Fat Reduction:Body recomposition effects appeal to aesthetic medicine and wellness clinic clientele.
- Performance Optimization:Recovery acceleration and endurance metrics attract tactical athlete and first-responder populations.
Muscle Growth anchors current revenue; Strength Enhancement shows the steepest expansion trajectory.
End User:
Customer type determines channel architecture, with clinical patients routing through institutional procurement and fitness-oriented segments activating direct-to-consumer infrastructure.
- Clinical Patients:Individuals with diagnosed sarcopenia, muscular dystrophy, or cancer-related cachexia access products through physician-supervised protocols. Hospital system formularies in the United States concentrate volume through group purchasing organizations negotiating institutional pricing. Off-label prescribing patterns among endocrinologists are shifting toward tissue-selective agents with improved safety profiles relative to traditional anabolic steroids.
- Athletes:Competitive and recreational sports participants drive discretionary demand through premium pricing in direct channels. Anti-doping protocol compliance requirements create market fragmentation between legitimate prescription pathways and prohibited gray-market sourcing. The FTC prosecutes supplement manufacturers making unsubstantiated claims for products containing undisclosed SARM analogues.
- Bodybuilders:Aesthetic-focused consumers prioritize hypertrophy outcomes through specialized gym culture distribution.
- Fitness Enthusiasts:General wellness seekers access lower-potency formulations through mainstream supplement retail.
Clinical Patients concentrate volume through institutional contracts; Athletes command the highest per-unit pricing.
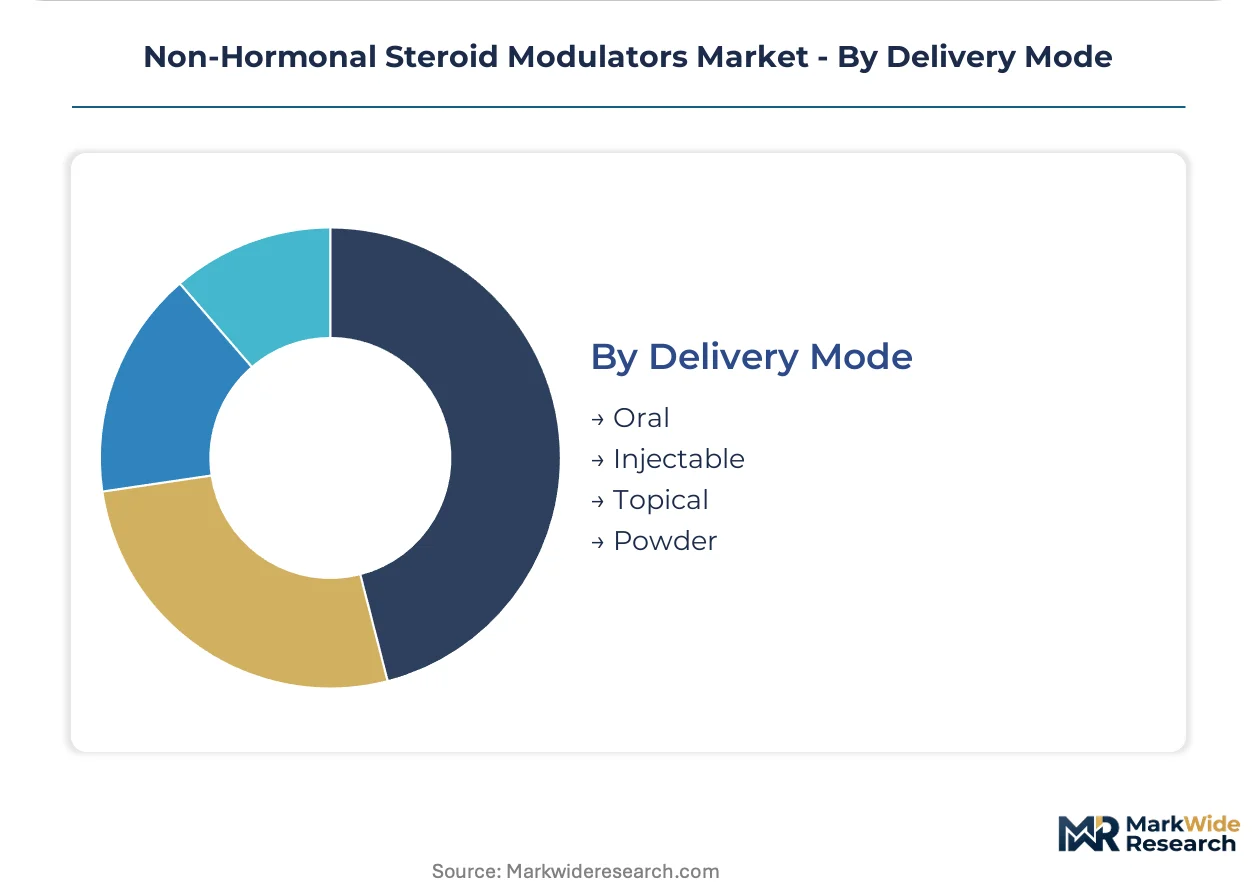
Delivery Mode:
Supply concentration in oral formulation manufacturing reflects patient preference for non-invasive administration, while injectable modalities capture the biologics segment.
- Oral:Tablet and capsule formulations dominate SARM administration due to patient compliance advantages and established pharmaceutical manufacturing infrastructure. United States compounding pharmacies produce customized oral preparations for specialty clinic networks under Section 503A of the Federal Food, Drug, and Cosmetic Act. Bioavailability thresholds exceeding 20 percent determine clinical viability for lead candidates.
- Injectable:Subcutaneous and intramuscular delivery enables peptide-based myostatin inhibitors and depot formulations for extended release. Biologics manufacturing infrastructure requirements concentrate production among contract manufacturing organizations with FDA-approved facilities. Cold chain logistics create distribution complexity that favors regional fulfillment models.
- Topical:Transdermal gels and creams serve hormone replacement therapy adjacent applications with localized absorption profiles.
- Powder:Bulk active pharmaceutical ingredients supply compounding facilities and research institutions.
Oral delivery leads prescription volumes today; Injectable formats are climbing the fastest in the myostatin inhibitor category.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States specialty pharmacy networks anchor commercial distribution for non-hormonal steroid modulators, with compounding facilities clustering in Florida, Texas, and Arizona to serve telehealth-enabled prescriber panels.
United States
FDA enforcement under the Designer Anabolic Steroid Control Act compresses gray-market channels while redirecting demand toward legitimate clinical pathways. The DEA coordinates port-of-entry interception protocols that disrupt raw material supply for unapproved SARM analogues. Boston and San Diego biotech clusters concentrate myostatin inhibitor R&D through contract manufacturing relationships with FDA-approved facilities.
Germany
EMA-aligned regulatory frameworks access reimbursed prescription markets with established clinical protocols for sarcopenia management. REACH registration requirements tighten substance notification protocols for novel synthetic steroid scaffolds exceeding one tonne annual import. The Rhine-Ruhr industrial corridor anchors pharmaceutical manufacturing infrastructure serving European specialty distribution channels.
Switzerland
Swissmedic oversight of clinical-grade peptide manufacturing attracts biologics infrastructure investment from multinational pharmaceutical sponsors. The country's central bank stability supports cross-border licensing transactions for follistatin-derived therapeutic candidates. Basel and Zurich pharmaceutical clusters concentrate contract research organizations managing late-stage muscular dystrophy trials.
Japan
PMDA priority review pathways for orphan indications accelerate myostatin inhibitor development timelines for rare disease populations. METI industrial policy supports domestic biologics manufacturing capacity expansion to reduce import dependency for peptide-based therapeutics. The Kanto region around Tokyo hosts the majority of clinical trial enrollment sites for sarcopenia interventions.
United Kingdom
Medicines and Healthcare products Regulatory Agency alignment with EMA standards preserves market access continuity for EMA master file holders post-Brexit. The MHRA's evolving framework for tissue-selective agents shapes prescriber confidence in specialty endocrinology practices. London and Cambridge life science clusters concentrate early-stage discovery programs for next-generation androgen receptor partial agonists.
Non-Hormonal Steroid Modulators Market Competitive Landscape
Global majors compete with regional champions across regulatory navigation capabilities and biologics manufacturing scale. Market structure tilts toward consolidated pharmaceutical conglomerates with existing FDA enforcement relationships and EMA master file portfolios. Three archetypes dominate: diversified biopharma conglomerates with cachexia therapeutic franchises, mid-cap peptide specialists with muscular dystrophy orphan drug focus, and research-stage biotechs with platform tissue-selectivity technologies. Dominant competitive moves include strategic partnerships with telehealth platforms for prescriber network access and capacity expansion into biologics-grade manufacturing infrastructure.
Within the diversified biopharma tier, Bristol Myers Squibb Company and Novartis exemplify archetypes leveraging existing biologics infrastructure and European specialty distribution dominance respectively. Amgen occupies a position representing R&D-intensive investment in tissue-selectivity improvements. These three anchors illustrate how scale, geographic positioning, and research focus stratify competitive advantage in a market where regulatory compliance and manufacturing quality create steep barriers to mid-scale entry.
| Leading Market Players |
|---|
| AbbVie |
| Bristol Myers Squibb Company |
| Novartis |
| Amgen |
| Pfizer |
| Merck |
| Sanofi |
| Genentech |
| Janssen Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Medicinal chemistry talent concentration in Boston and San Diego biotech clusters drives labor-cost differentials that widen pricing-tier spreads between premium clinical-grade formulations and economy-positioned research compounds.
Pricing Analysis
Input-cost pass-through from phytosterol feedstock volatility shapes contract-based long-term offtake structures for oral SARM manufacturers, while biologics-grade peptide production anchors premium tier pricing. Price differentiation hinges on FDA master file status and EMA registration tier, with certified clinical-grade products commanding substantial premiums over research-use equivalents. Pricing pressure stems from DEA import interception disrupting gray-market supply, forcing cost absorption in unlicensed channels. Hospital procurement managers demonstrate lowest price sensitivity through institutional contracts, whereas compounding pharmacy networks exhibit highest sensitivity to active pharmaceutical ingredient cost swings.
Supply Chain Analysis
Dual-sourcing requirements from FDA-inspected facilities mandate multi-supplier qualification for myostatin inhibitor manufacturers, concentrating biologics production between United States, Switzerland, and Japan. Raw material dependencies center on follistatin-derived peptides, plant-derived phytosterol precursors, and synthetic cholesterol bases. Single-source vulnerability in follistatin supply creates exposure to Swissmedic manufacturing inspection schedules. Distribution runs through specialty pharmacy networks with regional cold chain fulfillment, connecting compounding facilities to prescriber panels across state lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Non-Hormonal Steroid Modulators Market functions as a regulatory compounder where FDA enforcement posture under the Designer Anabolic Steroid Control Act redirects demand toward legitimate clinical channels and expands addressable market for compliant manufacturers.
For Market Incumbents: Hedge against peptide manufacturing cost escalation by securing captive supply of follistatin-derived raw materials through backward integration into biologics-grade production infrastructure. Fortify position against mid-scale entrants by accelerating EMA master file submissions for novel tissue-selective scaffolds before REACH registration thresholds tighten. Channel control through exclusive specialty pharmacy relationships protects margin structure from telehealth platform disintermediation. For New Entrants and Emerging Players: Section 503A of the Federal Food, Drug, and Cosmetic Act in the United States opens a window for compounding-focused entrants to capture volume from anti-aging clinic prescribing authority consolidation. Target muscular dystrophy orphan indications as the most penetrable therapeutic segment, leveraging priority review vouchers and extended exclusivity provisions. Pursue direct-to-consumer telehealth platform partnerships as the primary go-to-market angle, bypassing traditional hospital procurement gatekeepers. For Investors and Strategic Acquirers: Diversified biopharma conglomerates with existing cachexia therapeutic franchises represent the most active acquirer category in this space, seeking tissue-selectivity platform technologies to augment internal pipelines. Platform-stage biotechs with computational docking capabilities and validated lead optimization workflows offer strongest long-term viability within a five-to-ten year development horizon. Watch for FDA reclassification signals regarding tissue-selective agents as the critical inflection indicator for valuation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Master File Submission | Accelerates market access through pre-negotiated regulatory pathways across reimbursed European prescription channels. |
| Orphan Drug Designation Pursuit | Unlocks priority review and extended exclusivity for muscular dystrophy myostatin inhibitors in United States and European Union. |
| Specialty Pharmacy Network Expansion | Connects prescriber panels in Florida, Texas, and Arizona with compounding facilities under Section 503A compliance. |
| Biologics Manufacturing Scale-Up | Addresses capital barriers for follistatin-derived peptide production through FDA-approved contract manufacturing relationships. |
| Telehealth Platform Partnership | Aggregates patient panels across state lines, replacing fragmented independent pharmacy relationships with centralized fulfillment. |
Research Methodology
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with regulatory affairs leads, formulary directors at hospital systems, compounding pharmacy procurement managers, and specialty endocrinology practitioners with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov enrollment data, and CMS Medicare Part B claims databases.
Historical trendline analysis across approved investigational protocols and commercial prescription volumes establishes baseline trajectories, with segmentation modeling across product type, therapeutic indication, delivery mode, and prescriber channel driving volume projections over the analysis window. CAGRs derive from fitted growth curves applied to institutional procurement contract values and direct-to-consumer channel receipts, incorporating PMDA priority review timelines and orphan drug pathway success rates as industry-specific forecast inputs.
Revisions become necessary when FDA reclassification proceedings, DEA enforcement intensity shifts, or EMA substance notification protocol amendments materialize. Deviation in Swissmedic manufacturing inspection schedules for follistatin supply would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Bone and Teeth Supplements Market
Dietary Supplements
Glucosamine Salt Market
Dietary Supplements
Womens Health and Beauty Supplements Market
Dietary Supplements
Fertility Supplements Market
Dietary Supplements
Oral Clinical Nutrition Supplements Market
Dietary Supplements
Melatonin Sleep Supplements Market
Dietary Supplements
Bisglycinate Market
Dietary Supplements
Sleep Supplement Market
Dietary Supplements
Bone and Joint Health Supplements Market
Dietary Supplements
Herbal Medicinal Products Market
Dietary Supplements
Concentrated Angelica Pills Market
Dietary Supplements
Global Oral Electrolyte Solutions Market
Dietary Supplements
Glucosamine Supplements Market
Dietary Supplements
Alpha Lipoic Acid Market
Dietary Supplements
Mediterranean Mood and Stress Support Complexes Market
Dietary Supplements
Cardiovascular Health Supplements Market