
 Battery Resistance Tester Market | 2026-2036
Battery Resistance Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Resistance Tester Market Outlook
Data center operators and EV fleet managers are redrawing procurement priorities for battery resistance testers as predictive maintenance replaces reactive replacement cycles. Fluke Corporation leverages its channel density in North American industrial distribution to sustain service-contract attach rates. Hioki E.E. Corporation anchors premium positioning in Japanese automotive OEM validation labs. Megger Group competes on ruggedized field-portable architectures for utility-scale storage inspections.
A battery resistance tester measures internal ohmic resistance of electrochemical cells using AC injection or DC pulse methods, typically resolving micro-ohm deviations to predict thermal runaway risk and capacity fade. Digital technology segments command margin pools through software-defined measurement algorithms and cloud-connected degradation trending. Microprocessor-controlled portable units represent the fastest-growing product type as technician workflows shift from bench-bound diagnostics to at-cell field verification. Bench top systems retain dominance in battery manufacturing quality control where automated throughput and traceability to IEC 62660 standards remain non-negotiable.
FDA device-quality frameworks indirectly shape medical battery tester specifications, while EPA hazardous waste rules govern disposal protocols for lead-acid diagnostic units. China's SAMR enforces GB/T standards for new energy vehicle battery testing equipment market access. The EU AI Act and Battery Regulation together compel tester manufacturers to embed algorithmic transparency and passport-ready data formats. Stakeholders must decide whether to build in-house calibration networks or outsource metrology to accredited laboratories as regulatory granularity tightens.
Market Dynamics
EU Battery Regulation passport requirements and China's GB/T certification mandates are forcing tester manufacturers to embed traceable data architectures and algorithmic transparency into hardware platforms.
Growth Catalysts
- Second-life battery certification:China's SAMR enforces internal resistance thresholds for repurposed lithium-ion cells, creating mandatory replacement demand for diagnostic-grade equipment in recycling facilities.
- Data center predictive maintenance:Hyperscale operators now require micro-ohm resolution testing as standard practice for UPS battery string monitoring, shifting procurement from reactive to scheduled verification cycles.
- AC injection method advancement:Software-defined measurement algorithms enable cloud-connected degradation trending, expanding attach rates for subscription-based calibration and firmware update services.
Market Restraints
- Precision component supply concentration:High-stability current shunts and 24-bit ADC modules concentrate among Japanese and German specialty component suppliers, exposing lead time volatility.
- Metrology outsourcing dependency:Accredited laboratory calibration networks remain thin outside Germany, Japan, and South Korea, forcing field technicians to ship units overseas for IEC 17025 traceability.
- Bench-top system displacement pressure:Portable microprocessor-controlled units capture technician preference for at-cell verification, compressing capital equipment budgets for fixed manufacturing line installations.
Strategic Opportunities
- India battery manufacturing clusters:PLI scheme subsidies for cell and pack production create greenfield demand for automated throughput systems with BIS certification alignment.
- Medical device battery testing:FDA device-quality frameworks indirectly shape specifications for implantable power source validation, opening specialized niche segments with premium margin structures.
- AI Act algorithmic transparency:EU regulatory mandates compel embedded software documentation, creating first-mover advantage for vendors with pre-integrated compliance modules.
Industry Challenges
- Multi-standard calibration complexity:Technicians must maintain proficiency across IEC 62660, GB/T, and JIS protocols simultaneously as customer bases diversify geographically.
- Legacy system integration friction:Cloud-connected testers face interoperability barriers with established manufacturing execution systems in automotive OEM battery plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Resistance Tester Market |
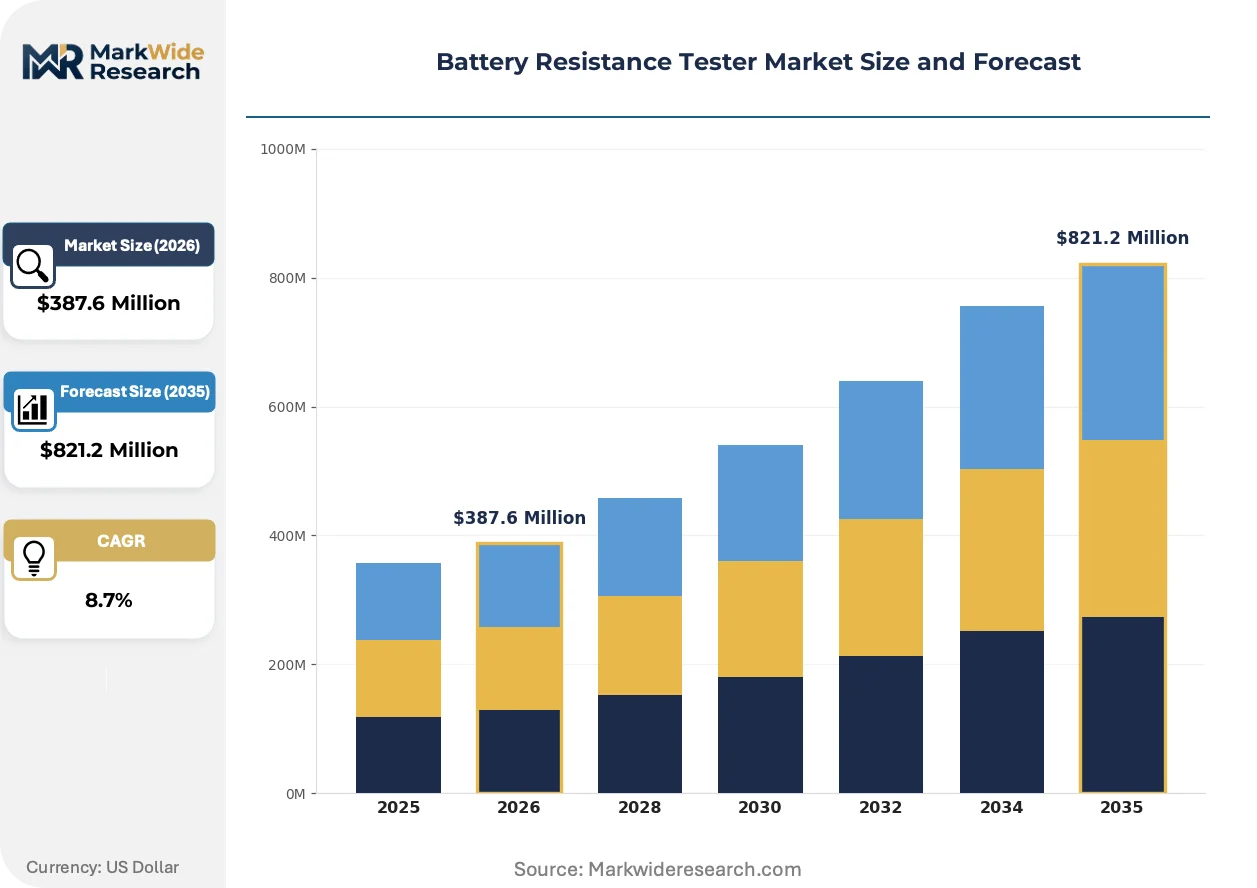
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Digital, Analog, Microprocessor Controlled, Portable End User: Automotive, Electronics, Telecommunications, Industrial Application: Maintenance, Testing, Diagnostics, Quality Control Product Type: Handheld, Bench Top, Automated, Specialty |
| Companies Covered | Hioki E.E. Corporation, Fluke Corporation, Megger Group, Chroma ATE Inc., Arbin Instruments, Cadex Electronics Inc., Keysight Technologies, Eagle Eye Power Solutions, DIGATRON, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Resistance Tester Market Strategic Shifts
Measurement hardware architectures are splitting between cloud-native field portability and automated manufacturing line integration, with software-defined functionality becoming the primary differentiation vector.
AC injection with digital signal processing is bifurcating tester architectures into two performance tiers. Field technicians adopt handheld units with Bluetooth-linked degradation trending apps for utility-scale storage inspections. Manufacturing quality engineers retain bench-bound systems with automated fixture handling and direct MES integration. The technology is compressing price premiums for basic resistance measurement while expanding recurring revenue pools for analytics subscriptions.
EU Battery Regulation passport-ready data formats are mandating embedded traceability modules in new equipment sales. Manufacturers must pre-configure XML output structures and unique identifier generation for second-life certification handoffs. German automotive testing corridors and South Korean battery manufacturing clusters face the steepest compliance timelines, driving accelerated replacement cycles for non-compliant legacy inventory.
Fleet operators now unbundle after-sales service contracts from hardware procurement, selecting calibration and firmware update providers independently of initial equipment vendors. North American industrial distributors respond with multi-brand service portfolios. EV fleet managers in California and Texas lead this behavior shift, compressing traditional vendor lock-in structures and opening channel competition for recurring revenue streams.
Battery Resistance Tester Market Segmentation
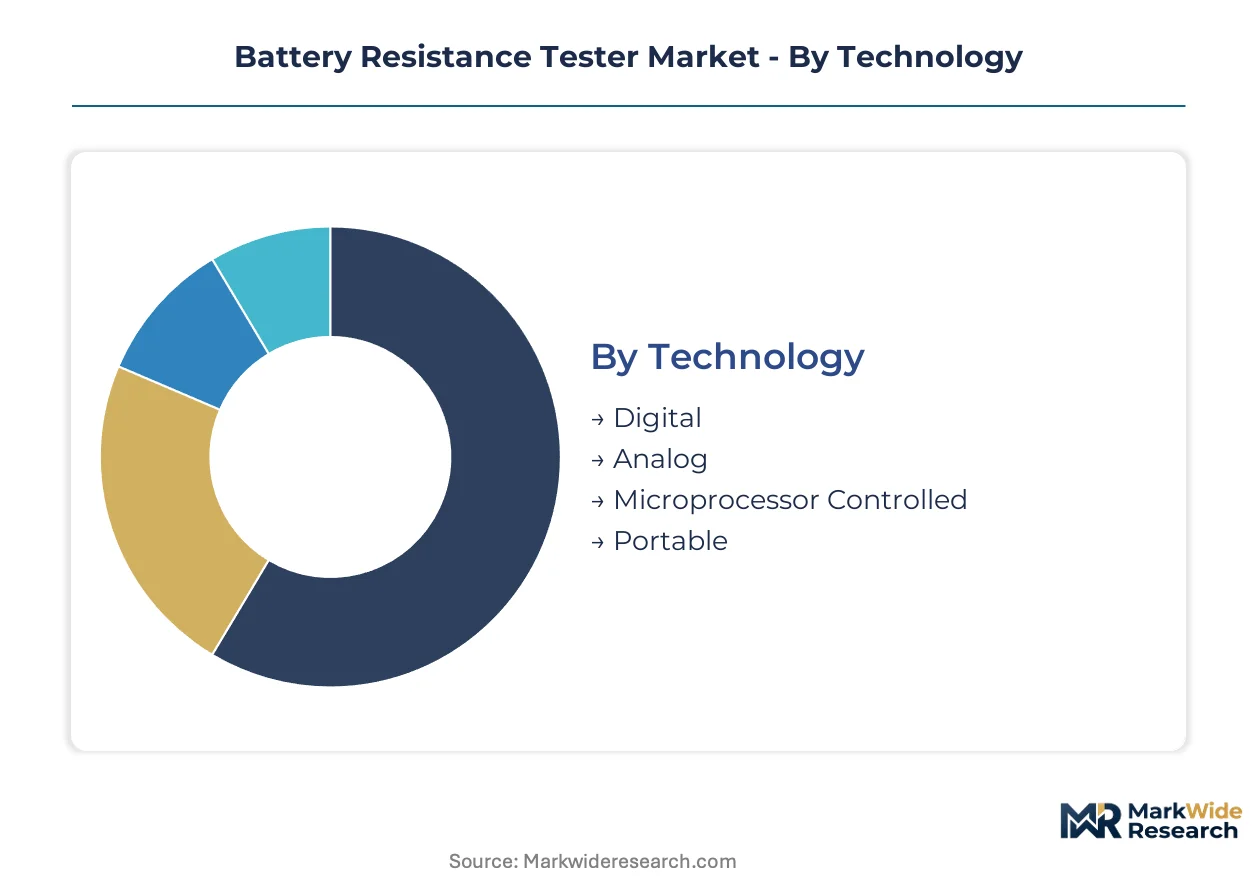
Battery resistance tester procurement patterns diverge sharply across technology tiers and use-case intensity. Segment boundaries are hardening as regulatory mandates in Germany, China, and South Korea force equipment upgrades with traceable data architectures.
Technology:
Digital architectures face substitution pressure from software-defined measurement platforms that embed cloud connectivity and algorithmic transparency modules.
- Digital:Software-defined measurement algorithms enable IEC 62660-traceable resistance trending with automated XML output for EU Battery Regulation passport compliance. German automotive OEM validation labs concentrate procurement here as second-life certification thresholds tighten.
- Microprocessor Controlled:Embedded firmware supports multi-protocol calibration across IEC, GB/T, and JIS standards simultaneously. South Korean battery manufacturing clusters drive demand as cell production capacity expands under SAMR-aligned export requirements.
- Analog:Legacy architectures persist in cost-sensitive maintenance workflows where basic micro-ohm resolution suffices.
- Portable:Bluetooth-linked field units displace bench-bound systems for utility-scale storage inspections and at-cell verification.
Digital platforms anchor the volume base while portable configurations gain share at the steepest rate.
End User:
Cost tier stratification separates diagnostic-grade procurement in automotive validation from standard-grade electronics manufacturing.
- Automotive:OEM battery plants require automated throughput with direct MES integration and passport-ready data formats. EU Battery Regulation timelines in Germany and Czech Republic manufacturing corridors accelerate replacement cycles.
- Industrial:Data center UPS string monitoring demands micro-ohm resolution as hyperscale operators shift from reactive replacement to predictive maintenance cycles.
- Electronics:Consumer device battery validation emphasizes compact bench-top systems for production line throughput.
- Telecommunications:Field technicians prioritize ruggedized handheld units for remote infrastructure battery health verification.
Automotive anchors the volume base while industrial applications expand most quickly.
Application:
Customer type fragmentation splits procurement between scheduled maintenance contracts and capital-intensive quality control installations.
- Quality Control:Automated fixture handling with BIS certification alignment dominates India's PLI-subsidized cell manufacturing greenfield projects.
- Maintenance:Subscription-based calibration services attach to field-portable units as fleet operators unbundle after-sales contracts from hardware.
- Testing:Standardized resistance verification for second-life battery handoffs requires embedded traceability modules.
- Diagnostics:Thermal runaway risk prediction drives lithium-ion cell degradation monitoring adoption.
Quality control anchors the volume base while maintenance services climb the fastest.
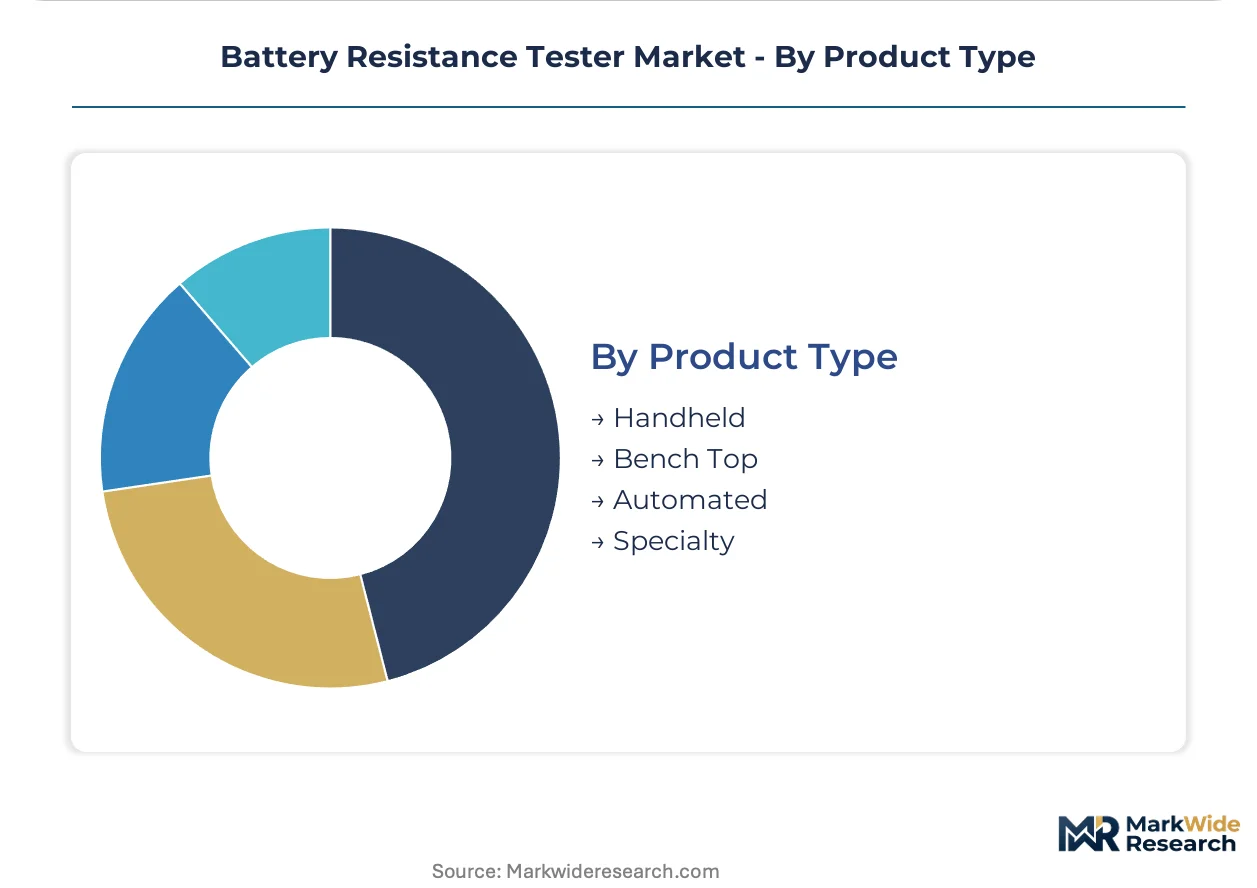
Product Type:
Maturity gradients separate established bench-top manufacturing systems from emerging automated architectures with MES integration.
- Bench Top:Fixed manufacturing line installations retain dominance where IEC 62660 traceability and automated throughput remain non-negotiable for cell certification.
- Automated:Robotic fixture handling with direct manufacturing execution system integration serves high-volume battery plants in South Korea and China.
- Handheld:Field technicians favor Bluetooth-linked degradation trending for utility-scale storage inspections.
- Specialty:FDA device-quality frameworks shape specifications for implantable medical power source validation.
Bench top systems anchor the volume base while automated configurations gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive testing corridors export diagnostic-grade equipment to battery manufacturing clusters across South Korea and China, establishing a trade-flow axis that channels precision metrology expertise into Asia-Pacific cell production facilities.
Germany
Automotive OEM validation labs in Stuttgart and Munich drive procurement of automated throughput systems with EU Battery Regulation passport-ready data formats. The KBA enforces second-life certification thresholds that accelerate replacement cycles for legacy testing inventory. Bavaria's battery testing corridor concentrates manufacturing quality control installations serving export markets.
China
Cell production capacity expansion under SAMR-aligned GB/T standards creates mandatory demand for diagnostic-grade equipment in recycling and repurposing facilities. SAMR enforces internal resistance thresholds for second-life lithium-ion certification. Yangtze River Delta manufacturing clusters absorb automated systems with direct MES integration for high-volume output.
South Korea
Battery manufacturing clusters in Busan-Ulsan and the Seoul Capital Area import German precision metrology while scaling domestic production under export-aligned certification requirements. The MFDS influences medical device battery testing specifications for implantable power sources. Daegu-Gyeongbuk cell plants deploy microprocessor-controlled units for multi-protocol calibration.
United States
Data center UPS string monitoring in Virginia and Texas hyperscale facilities shifts procurement toward predictive maintenance cycles with micro-ohm resolution requirements. The EPA governs disposal protocols for lead-acid diagnostic units while the FDA shapes medical battery tester specifications. California EV fleet operators unbundle after-sales service contracts from hardware procurement.
India
PLI scheme subsidies for cell and pack production generate greenfield demand for automated throughput systems requiring BIS certification alignment. The CEA regulates grid-connected battery testing protocols for utility-scale storage. Gujarat and Tamil Nadu manufacturing corridors concentrate first-wave installations serving domestic automotive electrification programs.
Battery Resistance Tester Market Competitive Environment
Player mix skews toward precision instrumentation specialists with established channel density in industrial distribution networks. Market structure exhibits moderate consolidation around vendors with IEC 17025 traceability capabilities and software-defined measurement platforms. Two strategic archetypes dominate: field-portable ruggedization specialists serving utility inspections, and automated manufacturing integration providers for OEM battery plants. Competitive moves concentrate on calibration network expansion and firmware subscription attach rates.
Within the precision instrumentation tier, Hioki E.E. Corporation and Fluke Corporation exemplify divergent geographic anchoring strategies. Hioki occupies a position associated with Japanese automotive OEM validation lab relationships, while Fluke represents North American industrial distribution channel density. Megger Group sits within the ruggedized field-portable archetype, reflecting utility-scale storage inspection requirements. Chroma ATE Inc. and Arbin Instruments anchor the automated manufacturing integration vector, with company names suggesting Taiwan and US origins respectively.
| Leading Market Players |
|---|
| Hioki E.E. Corporation |
| Fluke Corporation |
| Megger Group |
| Chroma ATE Inc. |
| Arbin Instruments |
| Cadex Electronics Inc. |
| Keysight Technologies |
| Eagle Eye Power Solutions |
| DIGATRON |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day lead times for high-stability current shunts and 24-bit ADC modules concentrate pricing power among Japanese and German specialty component suppliers, compressing margins for downstream tester assemblers while amplifying cost pass-through to automotive OEM validation labs.
Pricing Analysis
Digital-versus-analog pricing gaps separate software-defined measurement platforms from legacy microprocessor-controlled units. Three-tier pricing structure across premium diagnostic-grade, standard industrial-grade, and economy maintenance-grade levels reflects certification alignment to IEC 62660, GB/T, and JIS standards. Price differentiation hinges on embedded traceability modules for EU Battery Regulation compliance and after-sales service bundling. Cost compression in economy tiers intensifies as portable units displace bench-bound systems. Data center operators exhibit lowest price sensitivity due to predictive maintenance ROI calculations, while small-scale electronics manufacturers face acute budget constraints.
Supply Chain Analysis
Japan and Germany anchor production of precision current shunts, high-resolution ADC modules, and calibration-grade reference resistors. China assembles finished tester units and produces battery-specific test fixtures. Component sourcing draws from Taiwan for microprocessor chips and South Korea for display modules. Single-source vulnerability concentrates in 24-bit ADC supply from two Japanese specialty houses. Distribution runs through industrial equipment distributors in North America, direct OEM relationships in Germany, and systems integrators in China's Yangtze River Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward hyperscale data center operators and EV fleet managers as procurement consolidates around predictive maintenance contracts, fragmenting traditional vendor lock-in structures.
For Market Incumbents: Compound calibration network density in South Korea and India before local competitors achieve IEC 17025 accreditation. Deepen backward integration into high-stability current shunt production to offset Japanese supplier lead-time volatility. Defend against portable-unit entrants by embedding MES integration modules that manufacturing quality engineers cannot easily replicate. For New Entrants and Emerging Players: Firmware subscription gaps in North American industrial distribution expose white-space for independent calibration service providers. Target India's PLI-subsidized cell manufacturing corridors with BIS-certified automated throughput systems. Enter through channel partnerships with existing distributors rather than direct OEM sales cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial instrumentation parents where battery tester divisions lack standalone scale. Five-to-ten-year viability hinges on software-defined measurement platform transitions rather than hardware-only architectures. Watch for SAMR enforcement actions on GB/T certification deadlines as inflection signals for equipment replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Network Expansion | IEC 17025-accredited laboratories in India and South Korea capture recurring revenue from SAMR-aligned export requirements. |
| Backward Integration into Precision Components | In-house production of high-stability current shunts reduces dependency on Japanese specialty suppliers. |
| Firmware Subscription Platform Launch | Cloud-connected degradation trending services attach to portable units as fleet operators unbundle hardware procurement. |
| MES Integration Module Development | Direct manufacturing execution system connectivity defends bench-top market share against portable displacement. |
| BIS Certification Alignment | Automated throughput systems with Bureau of Indian Standards approval access PLI-subsidized greenfield cell plants. |
Study Parameters
Cross-validation between primary interviews with battery testing equipment procurement managers, automotive OEM validation engineers, and data center facilities directors anchors the qualitative findings against secondary validation from IEC standards documentation, SAMR regulatory filings, and hyperscaler capex disclosures. Bottom-up triangulation incorporates distributor inventory data and manufacturing capacity announcements. Top-down constraints derive from automotive production forecasts and grid-scale storage deployment pipelines.
Sensitivity analysis across technology adoption curves, regulatory enforcement timelines, and component supply scenarios shapes the analytical framework. Segmentation dimensions span technology tier, product architecture, end-use intensity, and regional certification cluster. CAGRs derive from equipment replacement cycle modeling and greenfield capacity absorption rates. Forecast inputs include second-life battery certification thresholds and predictive maintenance contract penetration curves.
Forecasts assume regulatory continuity in EU Battery Regulation implementation and SAMR GB/T enforcement; material policy shifts would require re-modeling. Specific risks encompass precision component supply disruptions, multi-standard calibration complexity, and legacy system integration friction. Recalibration cycles align with material shifts in automotive electrification programs and data center construction pipelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
VXI Test Equipment Market
Test and Measurement
Hipot Tester Market
Test and Measurement
Gigabit Ethernet Test Equipment Market
Test and Measurement
North America Automated Test Equipment Market
Test and Measurement
Network Tester Market
Test and Measurement
Manufacturing Test Systems Market
Test and Measurement
Battery Pack Immersion Cooling System Performance Test Rigs Market
Test and Measurement
Roughness Tester Market
Test and Measurement
Video Test Equipment Market
Test and Measurement
Solar Measuring Device Market
Test and Measurement
Solar Clamp Meter Market
Test and Measurement
Semiconductor Bond Testing Market
Test and Measurement
Test Rig Market
Test and Measurement
Ultrasonic Pulse Velocity Tester Market
Test and Measurement
Radiation Tester Market
Test and Measurement
Brightness Meter Market