
 North America Crowd Analytics Market | 2026-2036
North America Crowd Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Crowd Analytics Market Insights
Edge computing silicon is restructuring cost structures for on-premise crowd analytics deployments. Cisco Systems, Inc. leverages its networking infrastructure footprint to dominate video data ingestion pipelines. IBM Corporation anchors its position through AI analytics platforms that process multimodal sensor feeds. NEC Corporation specializes in biometric-integrated crowd counting for high-security venues.
Crowd analytics encompasses the real-time collection, processing, and interpretation of human density, flow, and behavior data using computer vision algorithms, thermal sensors, and Wi-Fi/Bluetooth signal detection, typically operating at latencies below 200 milliseconds for safety-critical applications. The technology serves commercial and governmental buyers seeking operational intelligence for space optimization, emergency response, and revenue management. Computer vision currently leads technology adoption but sensor fusion architectures combining thermal and optical inputs are capturing the fastest expansion in margin pools. Application demand concentrates in public safety and smart cities, where municipal procurement cycles favor integrated platform vendors over point solutions.
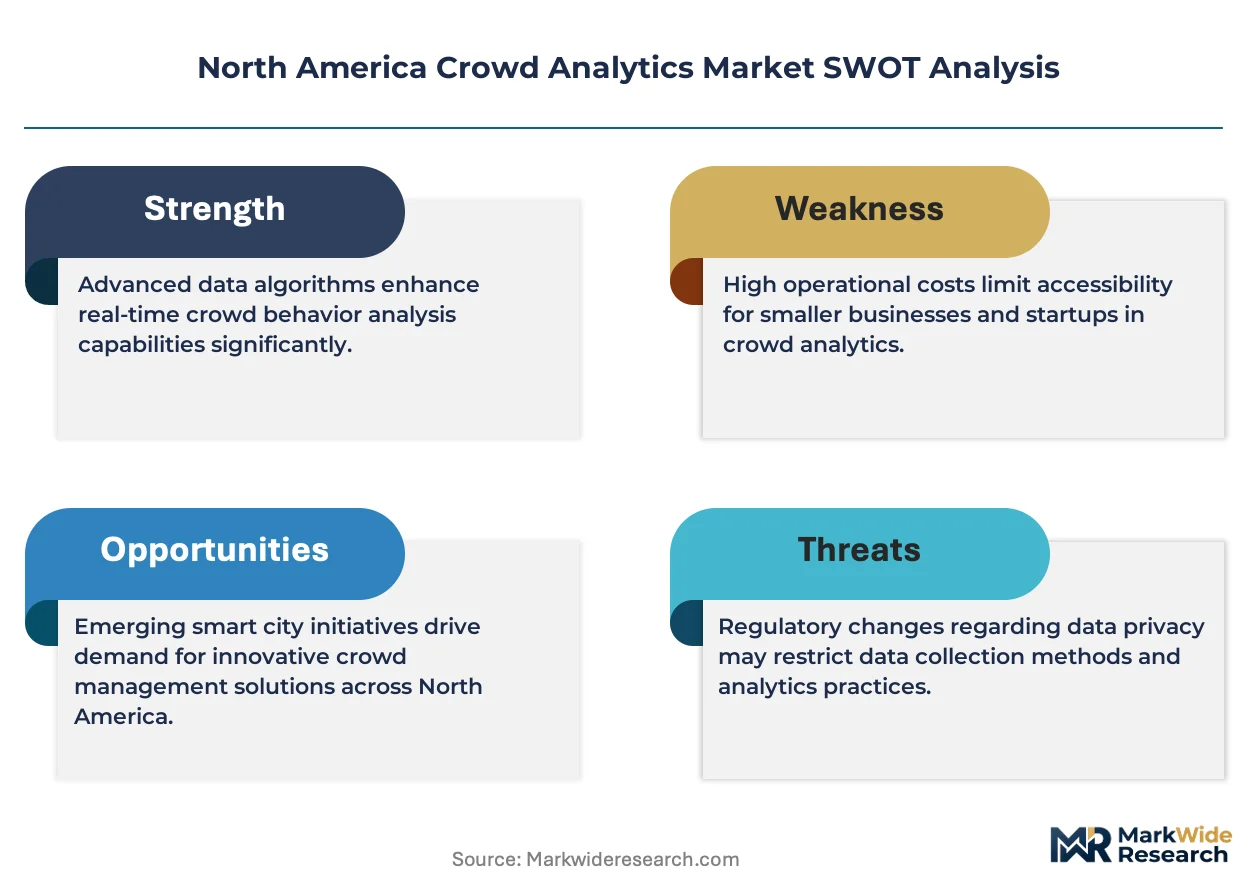
The National Institute of Standards and Technology shapes interoperability requirements for federal transportation grants, while the Federal Communications Commission governs spectrum allocation for crowd-sensing wireless networks. State-level privacy statutes in California and Illinois impose algorithmic audit obligations on biometric crowd analytics vendors. Buyers must evaluate vendor compliance postures against fragmented federal, state, and municipal regulatory layers before committing to multi-year deployment contracts.
Market Dynamics
Edge computing silicon is restructuring cost structures for on-premise crowd analytics deployments. Municipal transportation departments in Chicago and Toronto are accelerating procurement of real-time passenger flow monitoring systems as aging transit infrastructure demands predictive crowd management capabilities.
Growth Catalysts
- Smart city deployments:Municipal governments in Chicago and Toronto are deploying integrated crowd analytics platforms for public safety and transit optimization. Federal transportation grants increasingly require real-time passenger monitoring capabilities.
- NIST interoperability standards:The National Institute of Standards and Technology video sensor standards are reshaping procurement requirements. Federal grant compliance now mandates certified interoperability for multi-vendor sensor networks.
- Wi-Fi/Bluetooth signal detection:Wireless crowd-sensing networks are capturing adoption in high-density venues. The Federal Communications Commission spectrum allocation rules are enabling denser sensor deployments in urban corridors.
Market Restraints
- Algorithmic audit obligations:Illinois Biometric Information Privacy Act and California Consumer Privacy Act impose compliance costs on biometric-integrated crowd counting vendors. Legal exposure limits vendor willingness to deploy facial recognition.
- Sensor hardware concentration:Thermal-optical sensor fusion architectures depend on concentrated Asian semiconductor supply chains. Tariff exposure and logistics bottlenecks create input cost volatility.
- Legacy transit infrastructure:Aging physical plant in the US Northeast corridor requires costly retrofitting for sensor network integration. Capital constraints delay procurement cycles.
Strategic Opportunities
- Underpenetrated Canadian municipalities:Toronto's smart city investments exceed most Canadian peers. Mid-sized Canadian cities lack deployed crowd analytics infrastructure.
- Biometric-venue convergence:High-security venues are integrating NEC-style biometric counting with access control systems. Technology convergence creates premium service tiers.
- State-level privacy frameworks:Illinois and California regulatory precedents are spreading to other states. Early compliance investments position vendors for multi-state procurement eligibility.
Industry Challenges
- Computer vision engineering talent:Sub-200 millisecond latency requirements for safety-critical applications demand specialized edge AI optimization skills. Talent scarcity inflates R&D costs.
- Multi-vendor integration complexity:NIST interoperability mandates do not eliminate friction between proprietary AI analytics platforms and third-party sensor hardware. System integration timelines extend deployment schedules.
- Fragmented municipal procurement:Federal, state, and municipal regulatory layers create inconsistent compliance postures. Vendors must maintain multiple certification tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Crowd Analytics Market |
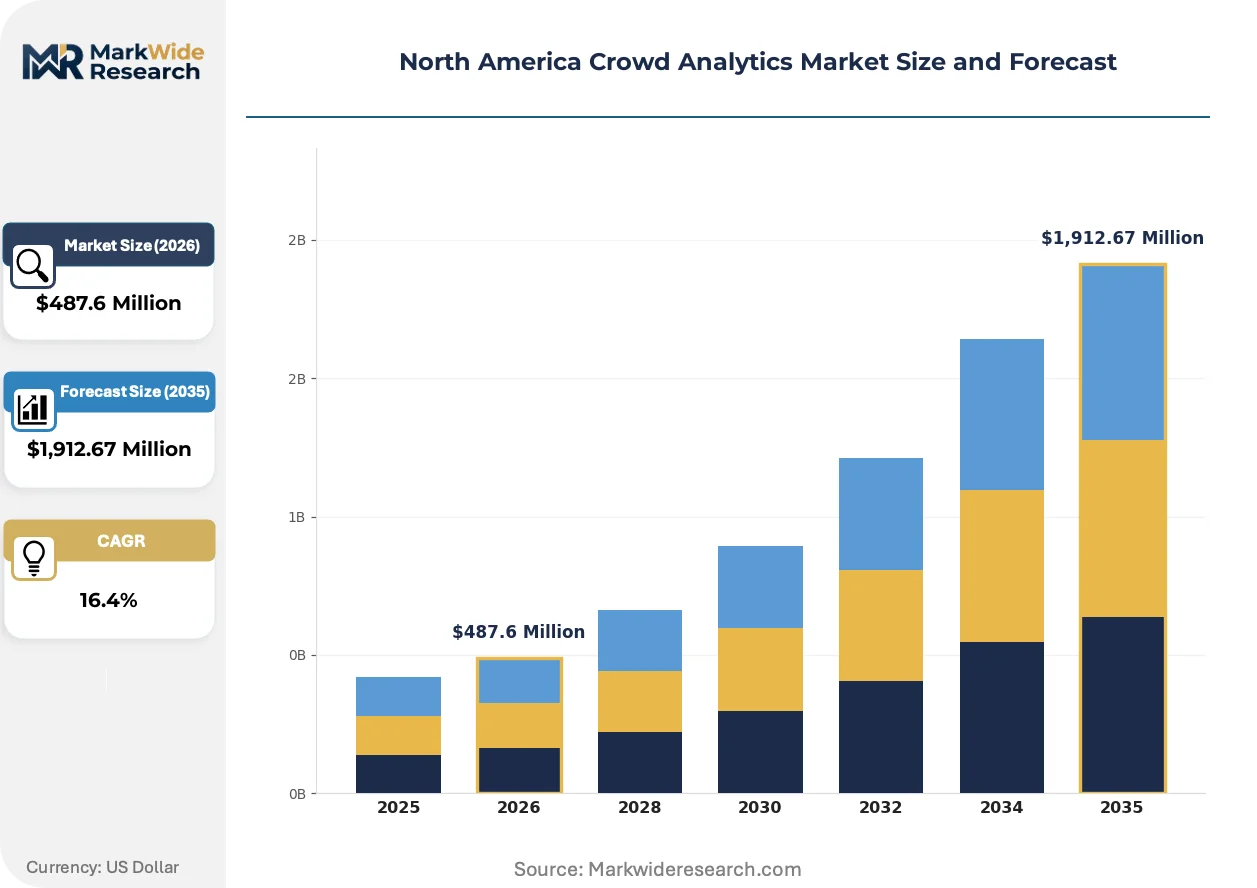
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,912.67 Million |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Computer Vision, Machine Learning, AI Analytics, Sensor Technology Application: Retail Analytics, Public Safety, Event Management, Smart Cities End User: Retailers, Government Agencies, Event Organizers, Transportation Service Type: Consulting, Managed Services, System Integration, Support Services |
| Companies Covered | IBM Corporation, Cisco Systems, Inc., CrowdANALYTIX, Spigit, Inc., AGT International, Sightcorp, Walkbase, Nokia Corporation, NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Crowd Analytics Market Trends and Innovations
Computer vision algorithms are confronting sensor fusion architectures as the dominant technology paradigm. Three active developments are restructuring competitive positioning and buyer value propositions.
Sensor fusion architectures combining thermal and optical inputs are expanding into safety-critical public transit applications. Municipal transportation departments in the US Northeast corridor are adopting these systems for real-time platform crowding alerts. The technology is expanding into predictive maintenance workflows by correlating passenger density with infrastructure stress indicators.
The National Institute of Standards and Technology video sensor interoperability standards are mandating open architecture procurement for federal transportation grants. Vendors must decouple hardware from analytics software to qualify for municipal contracts. Biometric-integrated crowd counting vendors face the steepest compliance reconfiguration as their proprietary systems confront interoperability audits.
Buyer concentration among municipal transportation departments is compressing vendor sales cycles and unbundling after-sales service contracts. Chicago and Toronto procurement offices are demanding separate pricing for hardware, software licensing, and maintenance. This pattern is most visible in the US Northeast corridor where consolidated transit authorities command volume pricing leverage.
North America Crowd Analytics Market Segmentation
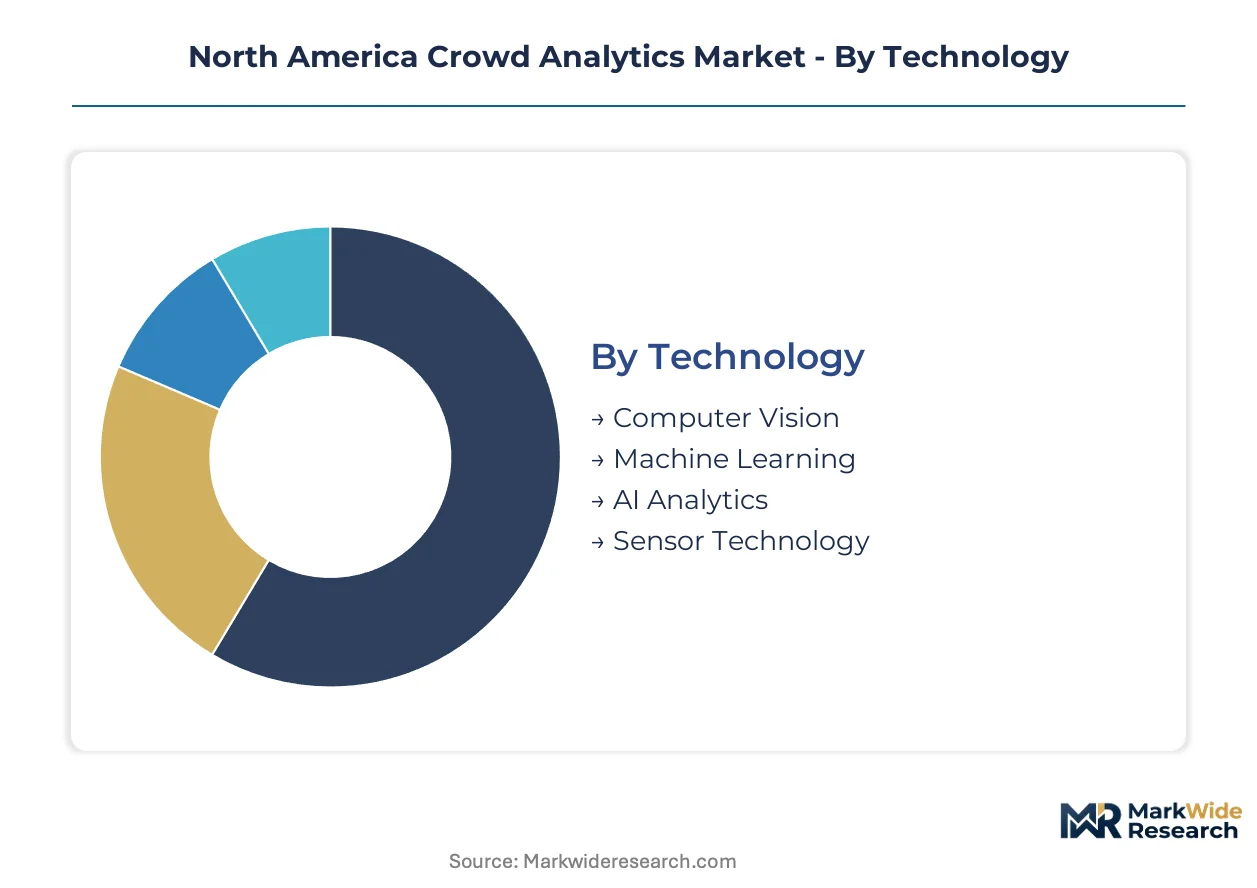
Crowd analytics procurement in North America segments across technology platforms, application domains, and service delivery models. Municipal transportation departments and private venue operators prioritize different capability bundles when evaluating vendor proposals.
Technology:
Upgrade cycles for legacy video analytics infrastructure are accelerating as edge computing silicon reduces on-premise deployment costs. Federal transportation grant compliance now mandates certified interoperability for multi-vendor sensor networks.
- Computer Vision:Optical-based crowd density and flow analysis using fixed and pan-tilt-zoom camera networks. Demand concentrates in Chicago and Toronto municipal transit systems where real-time platform crowding alerts require sub-200 millisecond latency.
- Machine Learning:Predictive algorithms trained on historical crowd patterns to forecast congestion events. The US Northeast corridor transit authorities deploy these systems for aging infrastructure stress correlation with passenger density.
- AI Analytics:Multimodal processing platforms integrating video, thermal, and wireless signal feeds. California and Illinois transit agencies favor these for algorithmic audit compliance under state biometric privacy statutes.
- Sensor Technology:Hardware layer encompassing thermal-optical fusion devices and Wi-Fi/Bluetooth detection arrays. FCC spectrum allocation rules are enabling denser urban corridor deployments.
Volume placements concentrate in Computer Vision; the faster expansion belongs to Sensor Technology.
Application:
Municipal procurement patterns favor integrated platforms over point solutions across safety-critical and revenue-optimization use cases. NIST interoperability standards are reshaping vendor qualification requirements for federal grant eligibility.
- Retail Analytics:Customer journey mapping and conversion funnel optimization for brick-and-mortar operators. Big-box retailers in the US Midwest deploy these for space optimization and staffing allocation.
- Public Safety:Real-time crowd monitoring for emergency response and threat detection. High-security venues integrate NEC-style biometric counting with access control systems for premium service tiers.
- Event Management:Temporary deployment analytics for stadiums, festivals, and convention centers. Toronto's smart city investments exceed most Canadian peers in permanent infrastructure, creating adjacent demand for mobile event systems.
- Smart Cities:Integrated municipal platforms spanning transit, public safety, and urban planning. Chicago's procurement office demands unbundled pricing for hardware, software licensing, and maintenance.
Smart Cities command the largest deployment volumes; Event Management is climbing the fastest as post-pandemic gathering density returns.
End User:
Buyer concentration among consolidated transit authorities compresses vendor sales cycles and fragments after-sales service contracts. State-level privacy frameworks are spreading beyond Illinois and California to reshape multi-state procurement eligibility.
- Retailers:Department stores and grocery chains seeking footfall intelligence and queue management. These buyers prioritize cost-per-sensor metrics over advanced AI capabilities.
- Government Agencies:Federal, state, and municipal departments with fragmented regulatory compliance layers. The National Institute of Standards and Technology shapes interoperability requirements for transportation grant recipients.
- Event Organizers:Temporary venue operators requiring rapid-deployment crowd monitoring. These buyers favor rental and managed service models over capital purchases.
- Transportation:Transit authorities in the US Northeast corridor with aging physical plant requiring sensor network retrofitting. Capital constraints delay procurement cycles despite operational urgency.
Transportation absorbs the highest absolute spending; Retailers are gaining share fastest as loss prevention budgets expand.
Service Type:
Vendor margin structures are shifting as buyers demand separation of hardware, software, and maintenance pricing. Talent scarcity for edge AI optimization skills inflates R&D and implementation costs across delivery models.
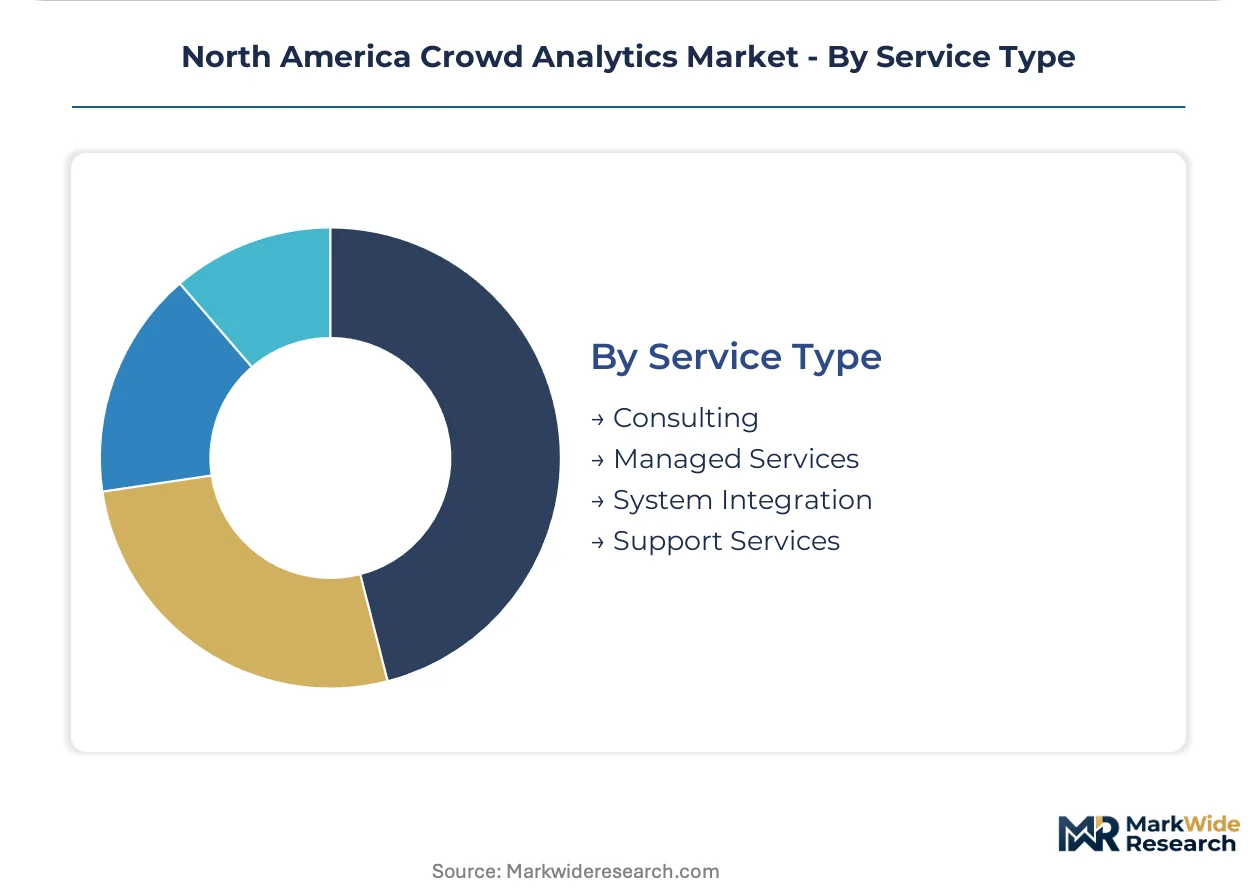
- Consulting:Needs assessment, system design, and regulatory compliance planning. Municipal transportation departments engage these services for NIST interoperability audit preparation.
- Managed Services:Ongoing platform operation and algorithm refinement by vendor personnel. High-security venues favor this model for biometric-integrated crowd counting complexity.
- System Integration:Multi-vendor sensor network deployment and AI platform configuration. NIST mandates do not eliminate friction between proprietary analytics and third-party hardware, extending timelines.
- Support Services:Maintenance, troubleshooting, and software update delivery. Consolidated transit authorities command volume pricing leverage on these contracts.
System Integration captures the steepest expansion trajectory; Support Services maintain the largest revenue base from installed infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States Northeast corridor, where aging transit infrastructure drives procurement urgency. Municipal transportation departments in Chicago and Toronto anchor smart city deployment volumes. Federal transportation grant requirements reshape vendor qualification across the continent.
United States
The Northeast corridor transit authorities deploy real-time passenger flow monitoring for aging infrastructure stress management. The National Institute of Standards and Technology mandates certified interoperability for federal grant eligibility. Chicago's municipal procurement office demands unbundled pricing for hardware, software, and maintenance contracts.
Canada
Toronto's smart city investments exceed most Canadian peers in permanent crowd analytics infrastructure. Health Canada shapes privacy compliance frameworks for biometric-integrated systems. Mid-sized Ontario municipalities lack deployed sensor networks, creating adjacent expansion opportunities for vendors.
Mexico
Mexico City Metro explores pilot deployments for platform crowding alerts in high-density stations. The country's national telecommunications regulator governs spectrum allocation for wireless crowd-sensing networks. Northern border states concentrate manufacturing-linked security deployments at logistics hubs.
North America Crowd Analytics Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors decouple hardware from analytics software to meet NIST interoperability mandates. The market structures around three tiers: networking infrastructure incumbents, AI platform specialists, and biometric-integrated security vendors. Two strategic archetypes define positioning: integrated platform vendors capturing municipal smart city contracts, and point solution specialists serving high-security venue niches. Technology licensing and portfolio diversification represent the dominant competitive moves as vendors adapt to fragmented regulatory compliance layers.
Among networking and AI platform providers, Cisco Systems, Inc. and IBM Corporation exemplify the integrated platform archetype, while NEC Corporation occupies a position within the biometric-integrated security tier. These three companies represent contrasting approaches to the interoperability and privacy compliance requirements reshaping procurement eligibility across municipal transportation departments and high-security venues.
| Leading Market Players |
|---|
| IBM Corporation |
| Cisco Systems, Inc. |
| CrowdANALYTIX |
| Spigit, Inc. |
| AGT International |
| Sightcorp |
| Walkbase |
| Nokia Corporation |
| NEC Corporation |
| Others |
Pricing and Supply Chain Analysis
Edge AI optimization talent scarcity in the US Northeast corridor widens pricing-tier spreads between premium integrated platforms and economy sensor-only deployments. Labor-cost differentials between specialized computer vision engineers and commodity hardware technicians translate directly into vendor margin structures and buyer procurement trade-offs.
Pricing Analysis
Volume placements concentrate in economy-tier sensor hardware while margin pools accrue to premium AI analytics platforms. Pricing stratifies across federal grant-eligible integrated systems, state-compliant biometric-audited tiers, and basic video analytics without audit capabilities. Cost compression in hardware tiers intensifies because Asian semiconductor supply chains face tariff exposure. Municipal transportation departments in Chicago and Toronto command volume pricing leverage as consolidated transit authorities, while mid-sized Canadian cities show highest price sensitivity due to capital constraints.
Supply Chain Analysis
Thermal-optical sensor fusion architectures rest on concentrated Asian semiconductor supply chains, with fabrication capacity centered in Taiwan, South Korea, and Japan. Critical inputs include edge computing silicon, thermal imaging sensors, and Wi-Fi/Bluetooth detection chipsets. Tariff exposure on Chinese-manufactured components creates input cost volatility for hardware vendors. Distribution runs through municipal procurement offices and federal transportation grant administrators, with system integrators capturing downstream value.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America crowd analytics market sits in a technology-transition phase as sensor fusion architectures displace legacy computer vision-only deployments. Edge computing silicon is restructuring cost structures and competitive positioning across vendor tiers.
For Market Incumbents: Acquire specialized edge AI engineering teams to defend against talent scarcity inflating R&D costs. Cisco Systems and IBM Corporation should deepen backward integration into sensor hardware to reduce multi-vendor integration friction. NEC Corporation must invest in NIST interoperability certification to preserve federal grant eligibility as biometric-integrated systems face audit mandates. For New Entrants and Emerging Players: Enter via underpenetrated mid-sized Canadian municipalities where Toronto's smart city investments have not yet spread. Target event management applications with rental and managed service models rather than capital sales. Position around Illinois and California algorithmic audit compliance as a go-to-market wedge for multi-state procurement eligibility. For Investors and Strategic Acquirers: Re-rating potential sits with biometric-integrated security vendors given spreading state-level privacy frameworks creating compliance moats. Long-term viability favors vendors with captive edge computing silicon relationships or in-house thermal-optical fusion capabilities. Watch NIST interoperability audit pass rates as an inflection indicator for federal grant market share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Launch | Thermal-optical integration captures safety-critical transit applications requiring sub-200 millisecond latency. |
| NIST Interoperability Certification | Federal transportation grant compliance mandates open architecture procurement for municipal contracts. |
| Biometric Audit Compliance Investment | Illinois BIPA and California CCPA algorithmic obligations reshape vendor qualification requirements. |
| Edge Computing Silicon Partnership | On-premise deployment cost structures restructure around specialized AI optimization chip supply. |
| Managed Service Model Expansion | Event organizers and high-security venues favor rental models over capital purchases. |
Research Methodology
Document review covered municipal procurement databases, federal transportation grant filings, and NIST technical standards, complemented by interviews with transit authority technology officers, smart city procurement managers, edge AI platform engineers, and system integration specialists. Secondary validation drew from FCC spectrum allocation records, state privacy statute filings, and vendor SEC disclosures. Bottom-up sensor deployment counts and top-down municipal IT spending estimates were triangulated to anchor market sizing.
Historical deployment trajectories were cross-referenced against expert panel inputs on procurement cycle timing and interoperability adoption curves. The forecast framework modeled technology platform transitions, application domain shifts between public safety and smart cities, service delivery model evolution, and regional regulatory clustering. CAGRs were derived from segment-level growth rate blending across the projection horizon, with edge computing cost curves and federal grant allocation patterns as primary inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under tariff escalation scenarios or accelerated state privacy framework proliferation. Projections reflect assumptions about NIST standard adoption timelines and semiconductor supply chain stability. A small set of named triggers—FCC spectrum reallocation, Illinois BIPA litigation outcomes, and Northeast corridor infrastructure funding authorization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Embedded Analytics Software Market
Analytics
Europe Mobile Analytics Market
Analytics
Patent Analytics Services Market
Analytics
Connected Device Analytics Market
Analytics
TV Analytics Solutions Market
Analytics
Behavior Analytics Market
Analytics
Big Data in Automotive Market
Analytics
Global Big Data Market
Analytics
Identity Analytics Market
Analytics
Active Data Warehousing Market
Analytics
Location Analytics Market
Analytics
Extract, Transform, Load (ETL) Market
Analytics
Asia Pacific Speech Analytics Market
Analytics
Cloud Performance Management Market
Analytics
North America Speech Analytics Market
Analytics
United Kingdom Geospatial Imagery Analytics Market