
 Embedded Business Intelligence Market | 2026-2036
Embedded Business Intelligence Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded Business Intelligence Market Analysis
Platform licensing revenue is rewriting margin economics across the Embedded Business Intelligence landscape. Microsoft Power BI leverages its Azure ecosystem to anchor enterprise deployments across North America and Western Europe. Sisense competes through in-chip processing technology that reduces reliance on separate data warehouses. Tableau dominates visual analytics specialization, sustaining premium positioning among design-intensive user bases in media and consumer research.
Embedded Business Intelligence refers to the integration of data analytics, reporting, and visualization capabilities directly within operational software applications, typically delivered through REST APIs and JavaScript SDKs that render interactive dashboards without requiring users to switch contexts. Its primary purpose is to transform transactional systems into decision-support environments where end-users access actionable metrics within familiar workflows. Cloud-based deployment leads volume adoption as enterprises abandon server maintenance overhead, while hybrid solutions capture regulated sectors requiring on-premises data residency alongside elastic compute scaling. Healthcare providers and financial services within the industry vertical dimension concentrate margin pools due to compliance-driven procurement and high-frequency reporting requirements.
FDA guidelines on software as a medical device intersect with HIPAA data handling rules to shape embedded analytics requirements for healthcare applications in the United States. GDPR and the EU AI Act impose algorithmic transparency and cross-border transfer constraints on European deployments, compelling vendors to engineer regional data sovereignty features. Stakeholders must monitor how NIST cybersecurity frameworks and sector-specific breach notification laws recalibrate trust architectures for real-time embedded analytics.
Market Dynamics
API-first integration architectures are dismantling traditional BI procurement patterns, forcing vendors to embed analytics directly into operational workflows rather than selling standalone dashboard licenses. Healthcare systems and financial institutions now mandate real-time data rendering within existing software interfaces.
Growth Catalysts
- GDPR-Aligned Data Governance:European enterprises are prioritizing embedded BI solutions with regional data residency, accelerating replacement of legacy on-premise analytics stacks in Germany and France.
- Healthcare Real-Time Monitoring:Hospital networks deploying patient-facing dashboards require FDA-compliant embedded analytics, creating dedicated procurement budgets for HIPAA-integrated visualization layers.
- Cloud-Native SDK Expansion:JavaScript rendering engines are eliminating context-switching friction, pulling adoption from retail operations and logistics platforms in India.
Market Restraints
- Specialized Engineering Talent Scarcity:Shortage of developers fluent in both analytics engine architecture and healthcare compliance protocols inflates implementation timelines.
- Data Sovereignty Fragmentation:Divergent national cloud residency requirements across European member states force redundant infrastructure deployment.
- Legacy System Entrenchment:Decades-old ERP installations in manufacturing sectors resist REST API integration without expensive middleware layers.
Strategic Opportunities
- EU AI Act Algorithmic Transparency:Mandatory explainability requirements for automated decision systems create premium demand for embedded audit-trail visualization modules.
- India PLI Scheme Digital Adoption:Manufacturing incentives are pushing SME clusters toward cloud-embedded analytics without capital-intensive data warehouse investments.
- Edge-Cloud Convergence:In-chip processing integration with 5G low-latency networks enables predictive maintenance dashboards for industrial IoT deployments.
Industry Challenges
- Cross-Functional Implementation Complexity:Embedded BI projects require simultaneous coordination between software engineering, compliance, and business intelligence teams, extending deployment cycles.
- Interoperability Certification Bottlenecks:Healthcare vendors face extended FDA software-as-medical-device validation timelines when integrating third-party analytics components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded Business Intelligence Market |
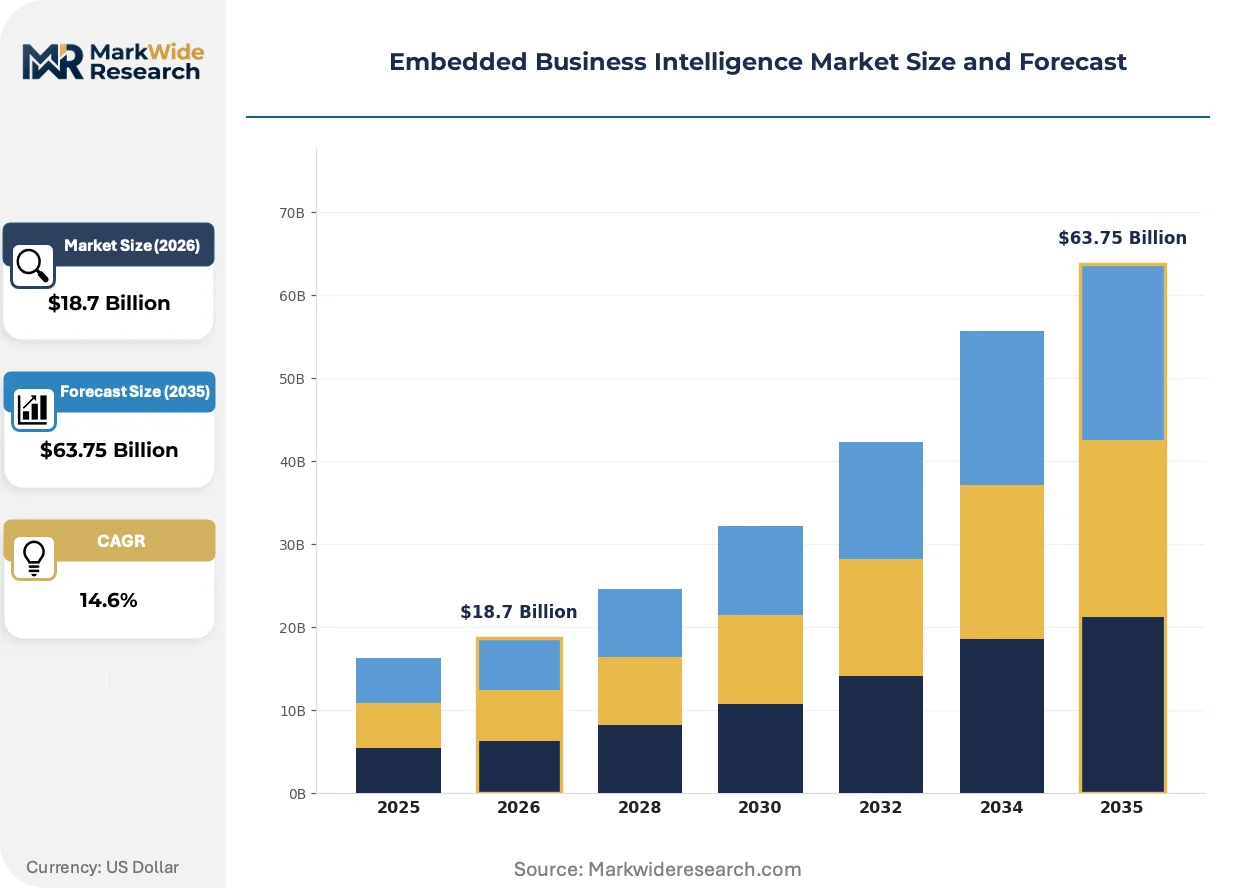
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $63.75 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dashboards, Reporting Tools, Analytics Platforms, Data Visualization Deployment: On-Premises, Cloud-Based, Hybrid Solutions, SaaS End User: SMEs, Large Enterprises, Education Sector, Healthcare Providers Industry Vertical: Finance, Retail, Telecommunications, Manufacturing |
| Companies Covered | Tableau, Qlik Sense, Sisense, Logi Analytics, Domo, Helical Insight, Microsoft Power BI, MicroStrategy, Looker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded Business Intelligence Market Emerging Trajectories
In-chip processing architectures are compressing the traditional data pipeline, eliminating extraction-transformation-loading delays that previously separated transactional systems from analytic insight. Vendors and end-users alike are restructuring around zero-latency query execution.
Columnar in-memory engines are collapsing the distinction between operational databases and analytical warehouses. Healthcare providers in the United States are deploying these engines for bedside patient monitoring dashboards that refresh without batch processing windows. The structural consequence is collapsing margin pools previously captured by separate data infrastructure vendors.
GDPR Article 22 automated decision-making rules are forcing algorithmic explainability into embedded BI interfaces. Financial services firms across Germany and France must now surface decision logic within loan origination software. Retail banking and insurance underwriting platforms are responding by rebuilding visualization layers around audit-trail transparency.
Subscription-based embedded analytics licensing is displacing perpetual software purchases in enterprise procurement. Manufacturing and logistics buyers in India now prioritize per-user monthly pricing aligned with cloud consumption models. This shift is most visible among mid-market ERP integrators bundling analytics into vertical-specific operational platforms.
Embedded Business Intelligence Market Segmentation
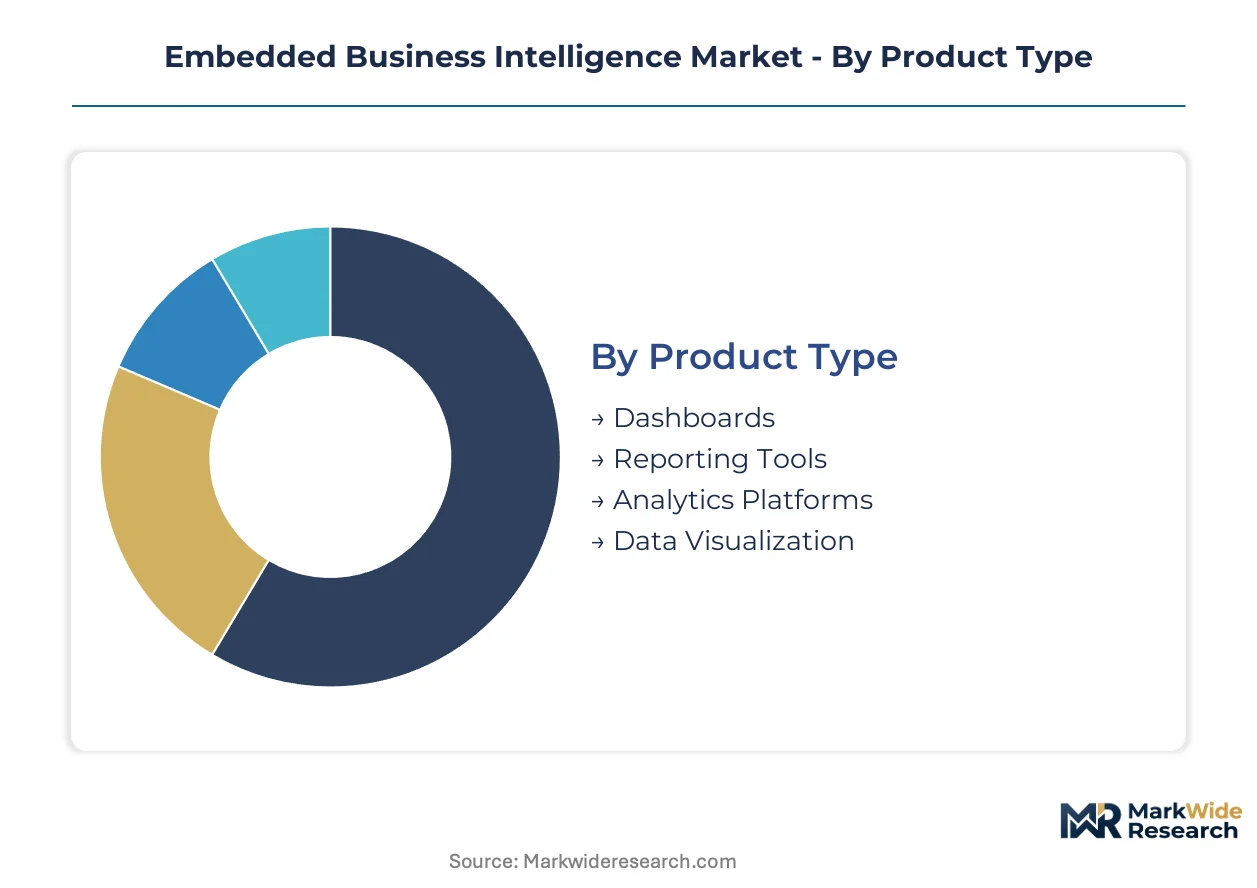
Embedded Business Intelligence vendors architect their product roadmaps around four distinct segmentation axes. Deployment modality determines infrastructure investment cycles, while industry vertical dictates compliance engineering requirements and pricing power.
Product Type:
Dashboards refresh at sub-second intervals in healthcare monitoring environments, while reporting tools operate on scheduled batch cycles with quarterly update frequencies. Analytics platforms and data visualization modules occupy intermediate refresh bands.
- Dashboards:Real-time rendering engines deliver interactive visualizations through JavaScript SDKs embedded within operational software interfaces. Hospital networks in the United States deploy these for FDA-compliant bedside patient monitoring, with HIPAA-integrated data pipelines driving procurement specifications.
- Analytics Platforms:In-chip processing architectures compress query execution timelines, eliminating traditional ETL bottlenecks between transactional and analytical systems. Financial services firms across Germany prioritize these for GDPR-aligned algorithmic transparency requirements in automated lending decisions.
- Reporting Tools:Scheduled distribution formats with static output generation serve compliance documentation needs in regulated manufacturing sectors.
- Data Visualization:Specialized rendering libraries for design-intensive user bases in media and consumer research applications.
Dashboards anchor the volume base while analytics platforms gain share at the steepest rate.
Deployment:
Cost tier stratification separates capital-intensive on-premises installations from consumption-priced cloud alternatives. Hybrid architectures command premium positioning by bridging both cost structures.
- Cloud-Based:Elastic compute scaling eliminates server maintenance overhead, with REST API delivery models enabling rapid integration into existing software stacks. Retail operations and logistics platforms in India accelerate procurement of these solutions under PLI scheme manufacturing incentives.
- Hybrid Solutions:Regional data residency features satisfy GDPR cross-border transfer constraints while preserving elastic scaling benefits. European enterprises in France and Germany mandate these configurations for algorithmic audit-trail compliance.
- On-Premises:Fixed infrastructure investments serving data sovereignty requirements in government and defense applications.
- SaaS:Per-user monthly pricing models displacing perpetual licenses among mid-market ERP integrators.
Cloud-based deployments capture the broadest customer base while hybrid solutions expand most quickly in regulated European markets.
End User:
Customer type determines implementation complexity and sales cycle duration. Large enterprises demand extensive customization, while SMEs prioritize rapid deployment templates.
- Large Enterprises:Multi-department rollouts requiring simultaneous coordination between software engineering, compliance, and business intelligence teams. These buyers mandate API-first integration architectures that embed analytics directly into existing ERP and CRM workflows.
- Healthcare Providers:FDA software-as-medical-device validation requirements extend procurement timelines, creating dedicated budgets for HIPAA-integrated visualization layers. Hospital networks in the United States concentrate demand for real-time patient monitoring dashboards.
- SMEs:Bundled analytics modules within vertical-specific operational platforms, with subscription pricing aligned to cloud consumption models.
- Education Sector:Institutional procurement through consortium purchasing agreements with extended evaluation periods.
Large enterprises anchor the volume base while healthcare providers climb the fastest amid regulatory-driven procurement acceleration.
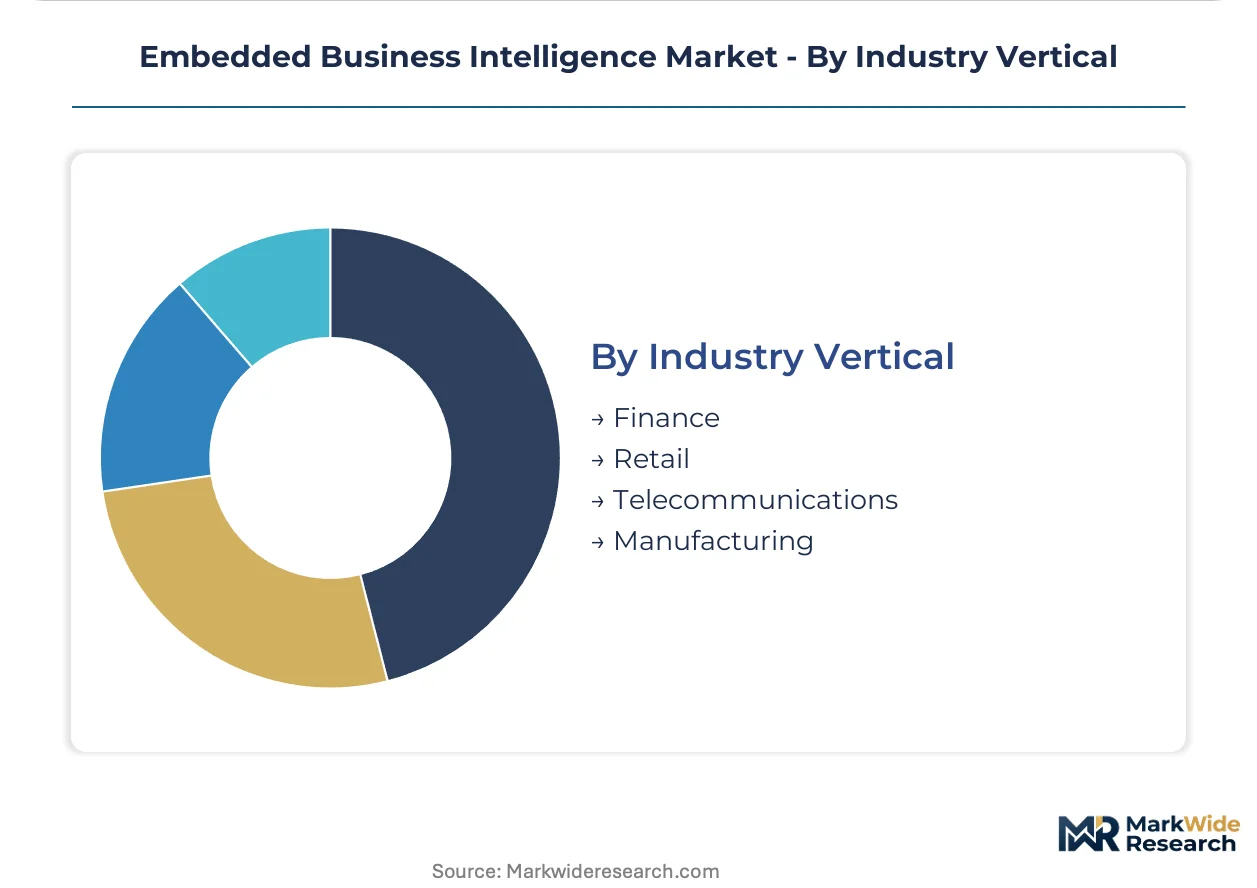
Industry Vertical:
Application-specific requirements fragment engineering priorities across compliance regimes. Finance demands algorithmic explainability, while manufacturing emphasizes predictive maintenance integration.
- Finance:EU AI Act automated decision-making rules mandate embedded audit-trail visualization for loan origination and insurance underwriting platforms. Retail banking operations across Germany and France rebuild interfaces around transparency requirements.
- Healthcare:FDA guidelines on software as a medical device intersect with HIPAA data handling protocols, shaping embedded analytics requirements for patient-facing dashboards. Real-time monitoring applications in hospital networks drive specialized engineering investments.
- Retail:Inventory optimization and customer analytics embedded within point-of-sale and e-commerce platforms.
- Manufacturing:Industrial IoT predictive maintenance dashboards leveraging edge-cloud convergence with 5G low-latency networks.
- Telecommunications:Network performance monitoring and subscriber analytics integrated into operations support systems.
Finance anchors the volume base while healthcare gains share at the steepest rate under regulatory procurement pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure investments and API-first software procurement concentrate embedded BI demand in the United States, Germany, and India. Regulatory frameworks reshape deployment architectures across these markets.
United States
Hospital networks and financial services drive embedded analytics procurement for real-time decision support. FDA software-as-medical-device guidelines intersect with HIPAA data handling protocols, mandating specialized compliance engineering. Boston and San Francisco Bay Area technology clusters anchor healthcare BI development and enterprise software integration.
Germany
Automotive and industrial manufacturing sectors demand predictive maintenance dashboards with edge-cloud convergence. GDPR Article 22 automated decision-making rules and EU AI Act transparency requirements reshape algorithmic visualization interfaces. Munich and Stuttgart engineering hubs concentrate industrial IoT analytics development for smart factory deployments.
India
PLI scheme manufacturing incentives accelerate SME adoption of cloud-embedded analytics without capital-intensive infrastructure. RBI data localization guidelines influence procurement criteria for financial services BI deployments. Bangalore and Hyderabad technology corridors host API-first platform development for logistics and retail operational software.
United Kingdom
London financial services and media sectors prioritize design-intensive visualization modules for consumer research applications. FCA operational resilience requirements intersect with GDPR cross-border transfer protocols. The Thames Valley technology cluster sustains embedded BI development for subscription-based SaaS platforms.
France
Retail banking and insurance underwriting platforms rebuild interfaces around EU AI Act audit-trail transparency mandates. CNIL enforcement of automated decision explainability drives premium demand for embedded visualization layers. Paris and Lyon fintech clusters concentrate algorithmic transparency module development for loan origination software.
Embedded Business Intelligence Market Vendor Landscape
Cloud-native specialists and legacy analytics incumbents split the embedded BI market along API-first versus desktop-originated architectural lines. Microsoft and Tableau anchor enterprise deployments through ecosystem integration and visual design specialization respectively. Three strategic archetypes dominate: hyperscale cloud platforms, in-chip processing specialists, and vertical-specific SDK providers. Competitive moves concentrate on M&A for analytics engine capabilities and strategic partnerships with ERP and CRM platform vendors.
Among cloud-platform-anchored providers, Microsoft Power BI and Tableau exemplify ecosystem-driven and design-intensive positioning respectively. Sisense occupies a position within the in-chip processing tier, reducing data warehouse dependency for latency-sensitive deployments. These three companies represent the dominant architectural approaches reshaping procurement patterns across healthcare and financial services verticals.
| Leading Market Players |
|---|
| Tableau |
| Qlik Sense |
| Sisense |
| Logi Analytics |
| Domo |
| Helical Insight |
| Microsoft Power BI |
| MicroStrategy |
| Looker |
| Others |
Supply Flow & Price Mechanics
Bangalore technology corridors anchor embedded BI platform development capacity, with API-first engineering talent density translating directly into tiered SaaS pricing power for vendors targeting mid-market ERP integrators.
Pricing Analysis
GDPR Article 22 automated decision-making rules dictate the pricing tier structure across European deployments. Three-tier pricing structure across premium, standard, and economy levels separates HIPAA-compliant healthcare modules from basic dashboard licensing. Price differentiation rests on certification grade for FDA software-as-medical-device validation and vertical-specific compliance engineering depth. Cost compression in the economy tier is intensifying because cloud-native SDK providers from India undercut legacy on-premises vendors. SME manufacturing clusters under PLI scheme incentives exhibit highest price sensitivity; hospital networks with dedicated compliance budgets show least.
Supply Chain Analysis
Upstream cloud infrastructure feedstock draws from hyperscaler data center investments across the United States, Ireland, and Singapore. Embedded BI vendors source compute capacity, JavaScript rendering engines, and columnar in-memory database licenses as core inputs. Single-source vulnerability concentrates in REST API middleware layers controlled by dominant platform ecosystems. Distribution runs through ERP and CRM channel partnerships rather than direct enterprise sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded Business Intelligence functions as a defensive-moat market where regulatory entrenchment creates durable pricing power through compliance certification requirements that lock in healthcare and financial services buyers.
For Market Incumbents: Harden API-first integration architectures against emerging vertical-specific SDK challengers by deepening in-chip processing capabilities and expanding HIPAA-validated module libraries. Prioritize backward integration into cloud infrastructure to reduce hyperscaler dependency and defend margin position from compute cost volatility.
For New Entrants and Emerging Players: India's SME manufacturing clusters under PLI scheme incentives represent the most penetrable white-space target, with minimal incumbent presence in subscription-priced operational analytics. Target logistics platform integrators with per-user monthly pricing and rapid deployment templates that bypass lengthy enterprise procurement cycles.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors in-chip processing specialists with healthcare compliance moats over cloud-platform-anchored generalists. Long-term viability hinges on regulatory entrenchment depth across FDA and EU AI Act jurisdictions. Watch FDA software-as-medical-device validation timeline acceleration as inflection indicator for healthcare vertical consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | REST API embedding into Epic and Cerner EHR systems captures hospital network procurement. |
| Acquisition of Specialist Firm | In-chip processing engine purchases eliminate data warehouse dependency for latency-sensitive deployments. |
| Strategic Partnership | Salesforce and SAP alliance agreements accelerate embedded analytics distribution through ERP channels. |
| Geographic Expansion | EU data residency infrastructure addresses GDPR Article 22 cross-border transfer constraints. |
| Product Launch | Algorithmic audit-trail visualization modules satisfy EU AI Act transparency mandates for financial services. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with CTOs, IT procurement officers, platform engineers, and healthcare compliance leads; and secondary validation through SEC filings, hyperscaler capex disclosures, FDA software-as-medical-device filings, and hospital procurement databases. Bottom-up segmentation modeling triangulated against top-down market sizing across deployment modality, organization size, vertical compliance requirements, and regional adoption patterns.
Forecast inputs considered elastic compute scaling trajectories, API-first integration penetration rates, and regulatory procurement acceleration effects across the analysis window. Segmentation dimensions modeled include deployment architecture, end-user scale tier, industry vertical compliance intensity, and geographic data sovereignty requirements. CAGRs derived from fitted growth curves anchored to disclosed platform revenue trajectories and cloud infrastructure consumption trends.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertical-specific SDK challengers would shift outcomes. Cross-checking against disclosed hyperscaler embedded analytics revenue segments is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Advanced Analytics Market
Analytics
Iraq ICT Market
Analytics
Global Analytics Software Market
Analytics
Israel ICT Market
Analytics
Europe Location Analytics Market
Analytics
North America Speech Analytics Market
Analytics
India Big Data Technology and Service Market
Analytics
Content Analytics and Search Software Market
Analytics
Speech and Voice Analytics Market
Analytics
Cognitive Analytics Solutions Market
Analytics
Middle East Geospatial Analytics Market
Analytics
In-Memory Analytics Tools Market
Analytics
Europe Edge Analytics Market
Analytics
Audio and Video Analytics Software Market
Analytics
Personal Analytics Market
Analytics
Global Marketing Attribution Software Market