
 Europe Mobile Analytics Market | 2026-2036
Europe Mobile Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Mobile Analytics Market Insights
The EU AI Act is restructuring how European enterprises procure mobile analytics, mandating explainability for algorithmic user profiling and risk-tiered governance. Adobe Systems Inc. leverages its Experience Cloud stack to anchor enterprise-grade compliance workflows across regulated sectors. IBM Corporation competes through Watson-backed anomaly detection that sustains high R&D intensity in predictive user modeling. AppDynamics navigates the performance monitoring layer with Cisco's channel control, extending telemetry depth for telecommunications operators.
Europe mobile analytics encompasses software platforms that capture, process, and visualize behavioral, performance, and transactional data from smartphones and tablets, typically ingesting event streams at millisecond latency through SDK- or API-based instrumentation. These systems serve commercial purposes ranging from conversion funnel optimization to predictive churn intervention and real-time personalization. Cloud-based deployment leads in new implementations across mid-market European firms, while on-premises configurations retain structural importance among German and Swiss banking clients with data residency requirements. Machine Learning and Artificial Intelligence segments within the technology dimension concentrate margin pools, as vendors embed automated cohort prediction and sentiment classification to differentiate from commoditized dashboard offerings.
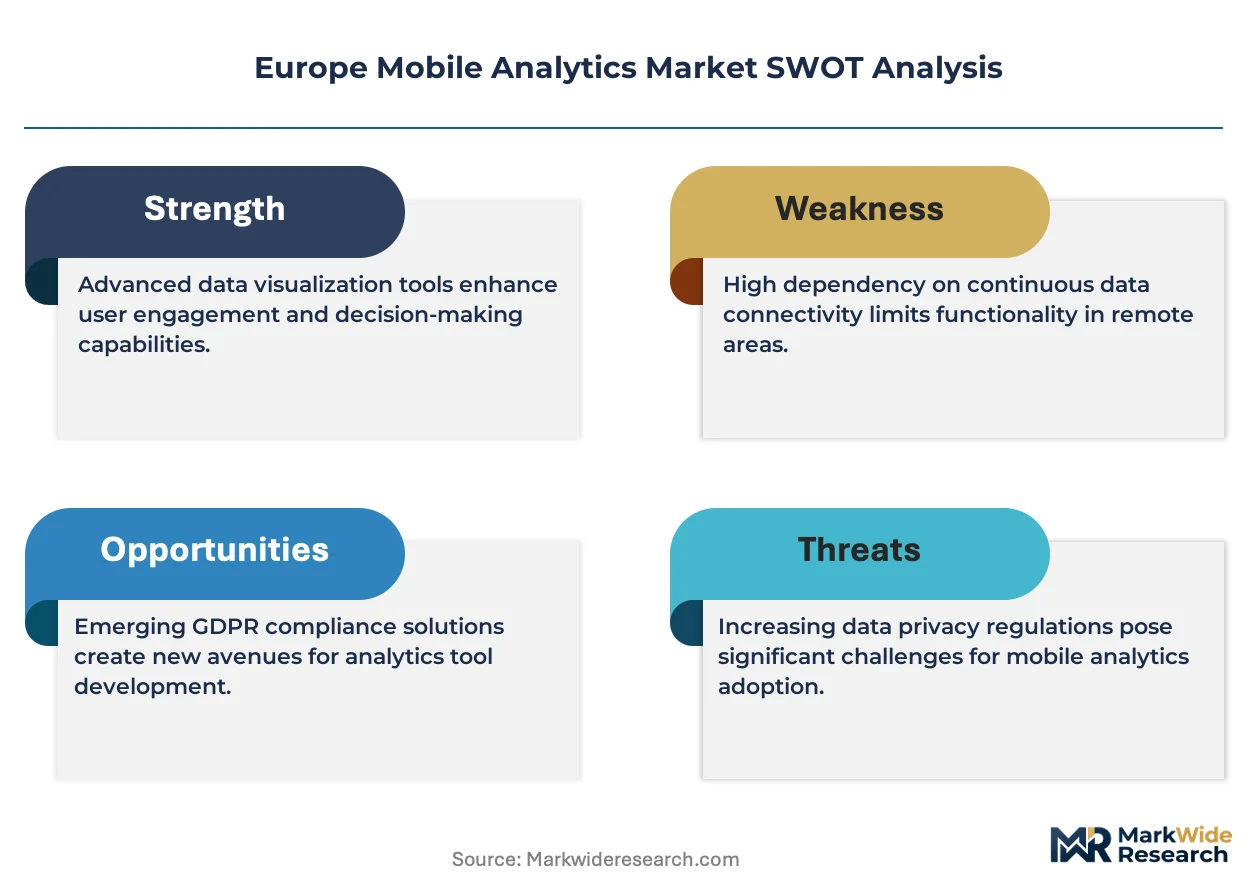
The European Data Protection Board coordinates GDPR enforcement that shapes consent architecture and cross-border data transfer protocols for analytics vendors. EMA guidelines on digital health data interoperability and the EU Cybersecurity Act's certification frameworks further constrain product design and market access for non-compliant platforms. Stakeholders must monitor evolving national implementations of the AI Act across France, Germany, and Italy to anticipate divergent compliance burdens and procurement gatekeeping.
Market Dynamics
The EU AI Act's risk-tiered governance framework is forcing European enterprises to re-architect their mobile analytics stacks around explainable algorithms and documented consent chains.
Growth Catalysts
- GDPR enforcement coordination:The European Data Protection Board's cross-border consistency mechanism creates procurement clarity for compliant vendors. Retail chains in Germany and France accelerate dashboard deployments.
- Real-time behavioral instrumentation:Millisecond-latency event streaming through SDK-based capture enables conversion funnel optimization. Fintech applications in London's corridor drive intensity.
- Cloud deployment preference:Mid-market firms across the Netherlands and Scandinavia favor SaaS configurations for faster implementation cycles. On-premises retains banking niche in Switzerland.
Market Restraints
- Data residency mandates:German and Swiss banking clients require sovereign infrastructure, fragmenting vendor economies of scale and extending sales cycles.
- Algorithmic audit costs:The EU AI Act's high-risk system documentation obligations impose compliance overhead that squeezes mid-tier platform margins.
- Cross-border transfer friction:GDPR adequacy decisions and Standard Contractual Clause negotiations create legal uncertainty for UK-EU data flows post-Brexit.
Strategic Opportunities
- Italian and Spanish market penetration:Southern European retail and logistics sectors show lower analytics maturity, offering first-mover positioning for compliant entrants.
- Predictive churn intervention:Automated cohort modeling using machine learning addresses subscription economy retention. Telecommunications operators seek differentiated capabilities.
- EMA digital health convergence:Interoperability guidelines for mobile health data create adjacent demand from pharmaceutical field forces and clinical trial platforms.
Industry Challenges
- Explainable AI talent scarcity:The intersection of data engineering and regulatory interpretation skills remains concentrated in London, Paris, and Berlin hubs.
- Legacy system integration complexity:Mainframe-era core banking infrastructure in established financial institutions resists API-native telemetry insertion.
- Certification timeline compression:EU Cybersecurity Act framework deadlines pressure product roadmaps while national implementations diverge across France, Germany, and Italy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Mobile Analytics Market |
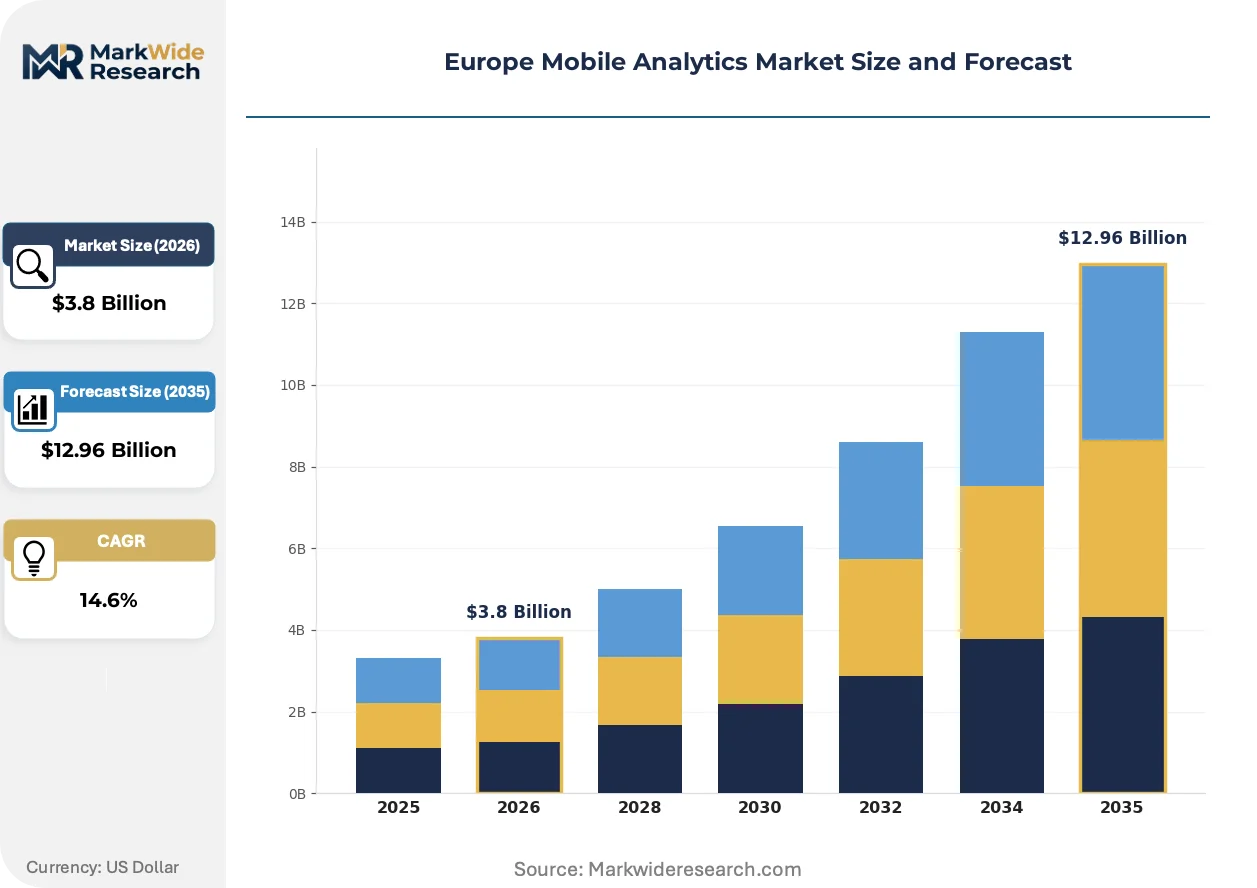
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premises, Hybrid, SaaS End User: Retail, Finance, Healthcare, Education Solution: Web Analytics, App Analytics, Performance Tracking, User Engagement Technology: Machine Learning, Big Data, Artificial Intelligence, Data Visualization |
| Companies Covered | Adobe Systems Inc., Mixpanel, AppsFlyer Ltd., IBM Corporation, Localytics, Clevertap, AppDynamics (Cisco Systems), Countly, App Annie Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Mobile Analytics Market Trends and Innovations
Edge-computing architectures and federated learning protocols are redistributing where analytics processing occurs, challenging centralized cloud hegemony in privacy-sensitive deployments.
On-device inference engines are expanding into European mobile analytics infrastructure, enabling behavioral scoring without raw data exfiltration. German automotive and French luxury retail adopters pilot these capabilities for showroom and vehicle telemetry applications. This architecture is expanding into compliance-sensitive segments by eliminating cross-border transfer exposure entirely.
The EU AI Act's high-risk system registration requirements are restructuring procurement due diligence, mandating algorithmic impact assessments before enterprise deployment. Banking and insurance buyers now embed compliance verification into RFP scoring. French and Dutch regulators issue early enforcement guidance that shapes vendor product roadmaps.
Buyers are consolidating vendor relationships around integrated experience clouds rather than point-solution stacks, compressing the acceptable supplier base. Mid-market enterprises in the United Kingdom and Nordic countries favor pre-certified platform bundles over custom integration projects. This concentration is most visible in London's fintech corridor where procurement teams prioritize audit-ready documentation over feature breadth.
Europe Mobile Analytics Market Segmentation
European enterprises configure mobile analytics procurement around compliance architecture, latency requirements, and legacy system constraints. Deployment modality and technology selection directly determine GDPR adherence costs and cross-border data transfer exposure. Buyers prioritize segments that minimize regulatory friction while preserving behavioral insight depth.
Deployment:
Procurement teams weigh sovereign data control against implementation velocity when selecting infrastructure models.
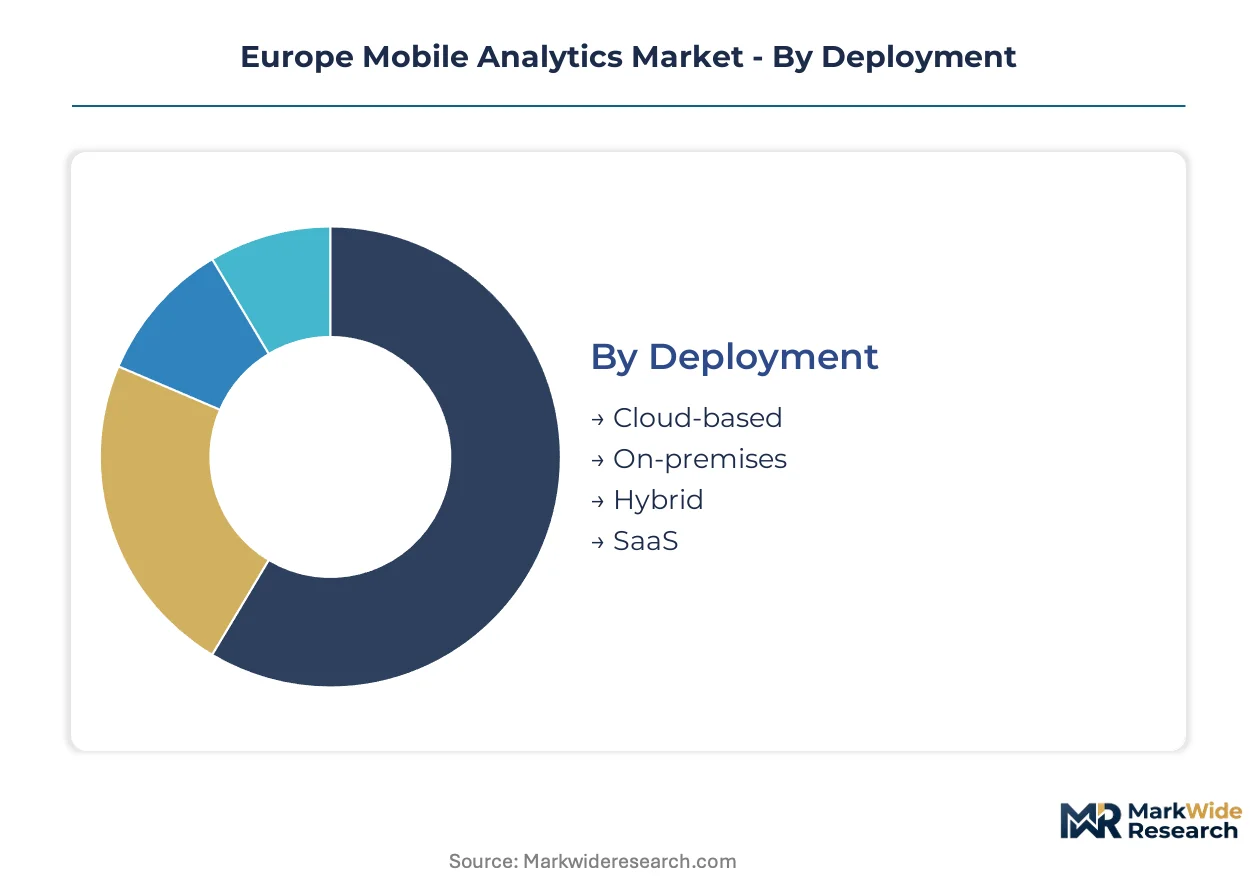
- Cloud-based:Multi-tenant SaaS architectures deliver millisecond-latency event streaming without capital expenditure. Mid-market firms across the Netherlands and Scandinavia favor this model for rapid dashboard deployment, though GDPR adequacy decisions complicate vendor selection.
- SaaS:Pre-configured subscription platforms reduce technical debt for retail chains in Germany and France optimizing in-app conversions. Standardized consent management modules accelerate compliance workflows under EU AI Act timelines.
- On-premises:Sovereign infrastructure satisfies German and Swiss banking data residency mandates. Extended sales cycles and fragmented vendor economics characterize this segment.
- Hybrid:Split architectures process sensitive behavioral data locally while pushing aggregated analytics to cloud layers. Telecommunications operators in London's fintech corridor pilot these configurations for churn prediction workloads.
Volume sits with cloud-based configurations; growth tilts toward hybrid architectures balancing compliance with computational scale.
End User:
Regulatory intensity and customer touchpoint density shape sector-specific demand patterns.
- Retail:Real-time behavioral dashboards optimize conversion funnels across German and French chains. Event-streaming SDKs capture in-app navigation patterns at millisecond granularity.
- Finance:London's fintech corridor drives predictive user modeling intensity. Algorithmic audit costs under EU AI Act high-risk system documentation squeeze mid-tier platform margins.
- Healthcare:EMA digital health data interoperability guidelines create adjacent demand from pharmaceutical field forces. On-device inference engines eliminate cross-border transfer exposure for clinical trial platforms.
- Education:Lower analytics maturity across Southern European institutions offers first-mover positioning. Privacy-sensitive student data processing favors federated learning protocols.
Finance commands premium pricing; healthcare is climbing the fastest as EMA guidelines reshape procurement specifications.
Solution:
Functional module selection reflects buyer maturity and integration complexity tolerance.
- App Analytics:SDK-based instrumentation captures smartphone and tablet behavioral streams. Retail and finance sectors deploy these for real-time personalization engines.
- User Engagement:Automated cohort prediction and sentiment classification differentiate from commoditized dashboard offerings. Telecommunications operators seek churn intervention capabilities here.
- Performance Tracking:Millisecond-latency telemetry monitors application responsiveness. AppDynamics extends depth for telecommunications operators through Cisco channel infrastructure.
- Web Analytics:Browser-based session recording complements mobile data streams. Mid-market enterprises favor pre-certified platform bundles over custom integration.
App analytics holds installed base concentration; user engagement is gaining share fastest as ML differentiation intensifies.
Technology:
Capability depth determines margin pool access and competitive defensibility.
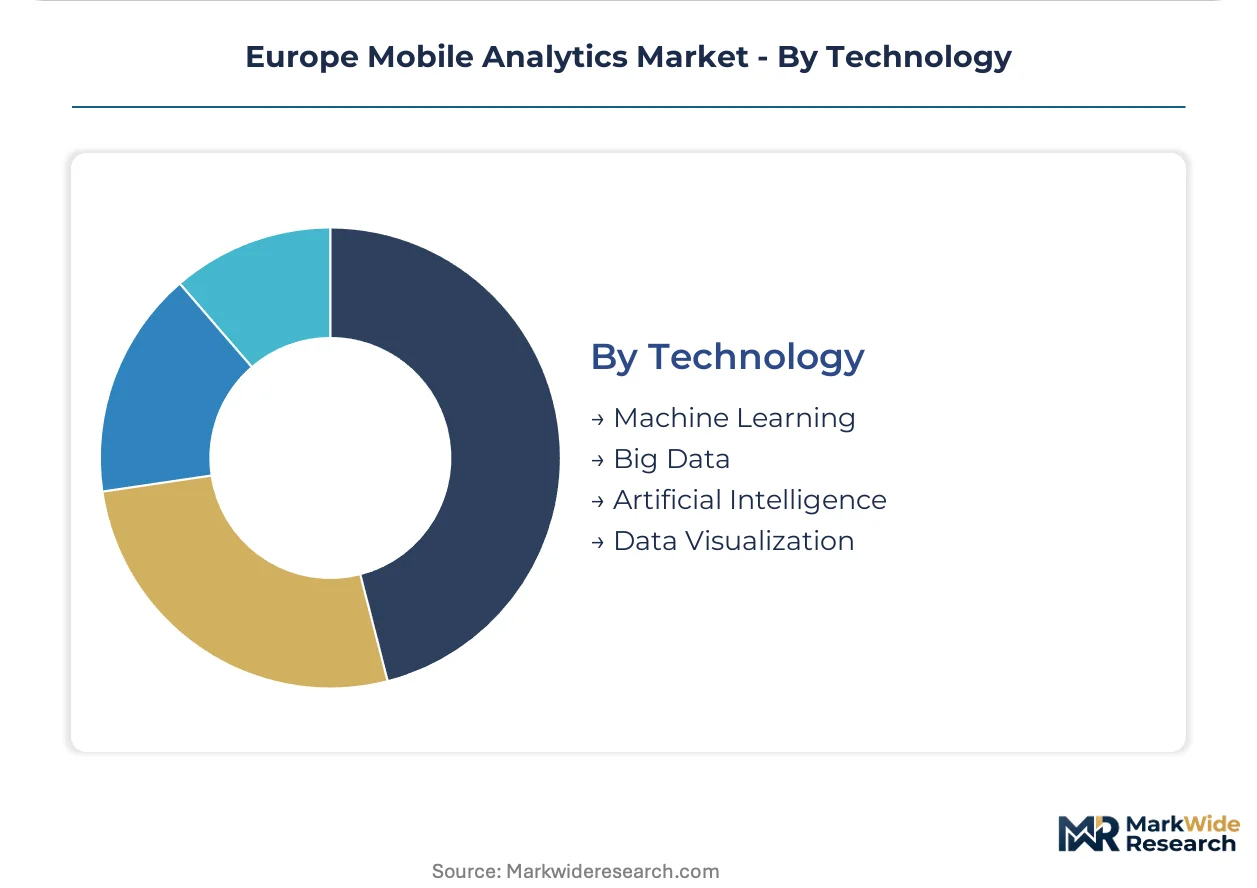
- Machine Learning:Automated cohort prediction and sentiment classification embed directly into mobile SDKs. High R&D intensity sustains vendor differentiation against commoditized offerings.
- Artificial Intelligence:Explainable algorithmic profiling satisfies EU AI Act risk-tiered governance mandates. Banking and insurance buyers embed compliance verification into RFP scoring.
- Big Data:Distributed processing architectures handle petabyte-scale event streams from European device populations. Cloud-native implementations dominate new deployments.
- Data Visualization:Real-time dashboard rendering converts behavioral signals into actionable merchandising decisions. French and Dutch regulators shape vendor roadmaps through early enforcement guidance.
Machine Learning anchors current revenue; Artificial Intelligence shows steepest expansion trajectory as explainability mandates harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London's fintech corridor concentrates the most intense demand for predictive user modeling and real-time behavioral dashboards across European mobile analytics procurement.
United Kingdom
London's financial services cluster drives premium pricing for algorithmic audit-ready platforms. The UK Information Commissioner's Office enforces GDPR adequacy decisions that shape cross-border data transfer protocols. Manchester and Edinburgh house emerging SaaS mid-market adopters favoring rapid implementation cycles.
Germany
Retail chains deploy millisecond-latency event streaming to optimize in-app conversion funnels. The Federal Financial Supervisory Authority (BaFin) mandates sovereign infrastructure for banking data residency. Berlin's startup ecosystem and Frankfurt's financial core split demand between cloud agility and on-premises compliance.
France
French luxury retail pilots on-device inference engines for showroom telemetry without raw data exfiltration. The National Commission on Informatics and Liberty (CNIL) issues early EU AI Act enforcement guidance. Paris anchors algorithmic explainability talent concentration alongside Lyon logistics platforms.
Netherlands
Amsterdam's mid-market firms favor SaaS configurations for faster dashboard deployment. The Dutch Data Protection Authority coordinates cross-border consistency mechanisms with Brussels. Rotterdam's port logistics sector experiments with federated learning for supply chain behavioral analytics.
Switzerland
Swiss banking clients require on-premises configurations satisfying strict data residency mandates. Swissmedic guidelines for digital health data create adjacent pharmaceutical demand. Zurich and Geneva extend sales cycles for vendors while commanding premium pricing for sovereign infrastructure.
Europe Mobile Analytics Market Competitive Landscape
The competitive structure tilts toward integrated experience cloud providers over point-solution specialists. Adobe Systems Inc. anchors enterprise-grade compliance workflows while IBM Corporation competes through Watson-backed anomaly detection. Three archetypes dominate: full-stack platform vendors, performance monitoring specialists, and verticalized SaaS providers. M&A activity concentrates on telemetry depth expansion and channel control consolidation.
Among US-based platform vendors, Adobe Systems Inc. and IBM Corporation exemplify the full-stack archetype with embedded regulatory workflows. AppDynamics occupies a position within the performance monitoring tier through Cisco's telecommunications channel infrastructure. These three anchors represent how vendor selection increasingly prioritizes audit-ready documentation over feature breadth in European procurement.
| Leading Market Players |
|---|
| Adobe Systems Inc. |
| Mixpanel |
| AppsFlyer Ltd. |
| IBM Corporation |
| Localytics |
| Clevertap |
| AppDynamics (Cisco Systems) |
| Countly |
| App Annie Inc. |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up analytics specialists anchor supply discipline through centralized procurement of cloud infrastructure and SDK instrumentation kits, compressing vendor margins while enforcing tiered pricing across compliance-grade segments. Their ownership concentration feeds pricing power downstream to enterprise buyers in London's fintech corridor and Frankfurt's banking core, where data residency mandates inflate sovereign infrastructure premiums.
Pricing Analysis
Outcome-based pricing anchored to conversion lift and churn reduction metrics dominates enterprise procurement in Europe's mobile analytics market. Three-tier pricing structure across premium, standard, and economy levels separates audit-ready platforms with EU AI Act documentation from mid-market SaaS bundles and basic telemetry dashboards. Cost compression in the economy tier intensifies because open-source alternatives commoditize event-streaming infrastructure. Mid-market retail chains in the Netherlands and Scandinavia exhibit highest price sensitivity, while Swiss banking clients accept premium multiples for on-premises sovereignty.
Supply Chain Analysis
EU Cybersecurity Act certification and GDPR adequacy documentation gate vendor access to European enterprise procurement, forcing upstream investment in compliance architecture. Cloud infrastructure concentrates in Ireland, Germany, and the Netherlands for data residency alignment. SDK instrumentation and on-device inference engines draw from semiconductor fabrication in Taiwan and South Korea. Single-source vulnerability in EU-based sovereign cloud providers exposes supply continuity to national implementation divergence across France, Germany, and Italy. Distribution runs through Cisco's telecommunications channel infrastructure and Adobe's enterprise sales networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe mobile analytics market reads as a cost-of-compliance story where EU AI Act documentation obligations erect barrier-to-entry moats favoring incumbent platforms with pre-certified audit trails.
For Market Incumbents: Deploy explainable AI talent concentration in London, Paris, and Berlin to defend against mid-tier platform margin erosion from algorithmic audit cost inflation. Consolidate channel control through Cisco's telecommunications infrastructure and Adobe's enterprise cloud integrations. Counter emerging threat from federated learning protocols by embedding on-device inference capabilities into core SDK offerings. For New Entrants and Emerging Players: Federated learning protocols for privacy-sensitive education and healthcare deployments offer technology-first wedge against centralized cloud hegemony. Southern European retail and logistics sectors in Italy and Spain present most penetrable geography with lower analytics maturity. Pursue go-to-market through EMA digital health interoperability certification for pharmaceutical field force adjacency. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated mid-cap specialists with pre-existing GDPR consent architecture and EU AI Act documentation workflows in Germany and Switzerland. Long-term viability hinges on regulatory compliance durability rather than feature breadth expansion. Watch for divergence in national AI Act implementation timelines across France, Germany, and Italy as inflection signal for compliance cost fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Pre-certified documentation workflows unlock procurement gates in BaFin-regulated German banking. |
| Federated Learning Protocol Development | On-device inference eliminates cross-border transfer exposure for CNIL-monitored French luxury retail. |
| Hybrid Deployment Architecture Launch | Split cloud-edge configurations address Dutch mid-market demand for GDPR-aligned scalability. |
| Telecommunications Channel Partnership | Cisco's operator relationships extend telemetry depth for London fintech corridor churn prediction. |
| Southern European Geographic Expansion | Italian and Spanish retail logistics sectors offer first-mover positioning with lower competitive density. |
Research Methodology
Multi-period observation of SDK deployment velocity, consent architecture adoption, and cloud infrastructure procurement anchored the trend analysis, supplemented by interviews with CTOs at fintech platforms, data protection officers at German retail chains, and integration specialists at telecommunications operators. Secondary validation drew from EDPB enforcement guidance, EMA digital health interoperability frameworks, and hyperscaler European region capex disclosures. Bottom-up triangulation across deployment modality splits and top-down reconciliation against aggregate SaaS subscription flows ensured dimensional consistency.
Input-output matrices mapped event-stream volume to pricing tier distributions across the projection horizon, with segmentation dimensions spanning deployment model, end-user vertical, solution module, and technology capability depth. CAGRs were derived from regression-based trend extrapolation of millisecond-latency instrumentation adoption and EU AI Act compliance cost pass-through rates. Forecast inputs included cross-border data transfer friction indices and national regulator implementation timeline divergence.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU Cybersecurity Act certification deadlines or Brexit-related GDPR adequacy revocation. Model assumptions reflect documented consent chain architectures and algorithmic explainability investment trajectories. A model refresh is warranted upon material change in EDPB cross-border enforcement consistency or EMA digital health data interoperability guideline revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global Data Fusion Market
Analytics
Latin America Location Analytics Market
Analytics
Europe Predictive Analytics Market
Analytics
App Analytics Tools Market
Analytics
Construction Data Analytics Software Market
Analytics
Analytics Sandbox Market
Analytics
Global Clickstream Analytics Market
Analytics
Marketing Analytics Software Market
Analytics
Global Business Intelligence and Analytics Market
Analytics
Global Industrial Analytics Market
Analytics
Italy Geospatial Analytics Market
Analytics
UK Video Analytics Market
Analytics
UAE Geospatial Analytics Market
Analytics
Germany Geospatial Analytics Market
Analytics
Europe Speech Analytics Market
Analytics
Latin America Location Based Data Analytics Market