
 Embedded Software Market | 2026-2036
Embedded Software Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded Software Market Analysis
The convergence of edge-native architectures with containerized deployment is reshaping how embedded systems are engineered for real-time constraints. Renesas Electronics leverages its microcontroller heritage to anchor high-reliability stacks in automotive and industrial domains. STMicroelectronics competes through broad silicon-to-software integration across IoT endpoints. NXP Semiconpositions its vehicle networking and secure element portfolios to dominate functional safety segments.
Embedded software comprises purpose-built code running on dedicated hardware without end-user modifiability, typically operating under memory constraints below 512 KB with deterministic response requirements below 10 milliseconds for hard real-time workloads. Its primary purpose is to control machinery, process sensor inputs, and execute automated decision loops in resource-constrained environments. Real-Time Operating Systems retain the largest revenue share due to their indispensability in safety-critical automotive and aerospace applications, while Security Solutions represent the fastest expansion trajectory as connected device attack surfaces multiply. Edge Computing deployment is gaining structural momentum where cloud latency violates operational constraints, creating margin pools for hybrid orchestration platforms.
FDA scrutiny of software as a medical device, FAA certification requirements for airborne embedded systems, and NHTSA cybersecurity guidelines for connected vehicles collectively elevate compliance costs and barrier thresholds for new entrants. The EU AI Act adds algorithmic accountability layers to embedded intelligence in consumer and automotive products, forcing architecture redesigns. Stakeholders must monitor how functional safety standards evolve for AI-infused embedded systems before committing long-term platform roadmaps.
Market Dynamics
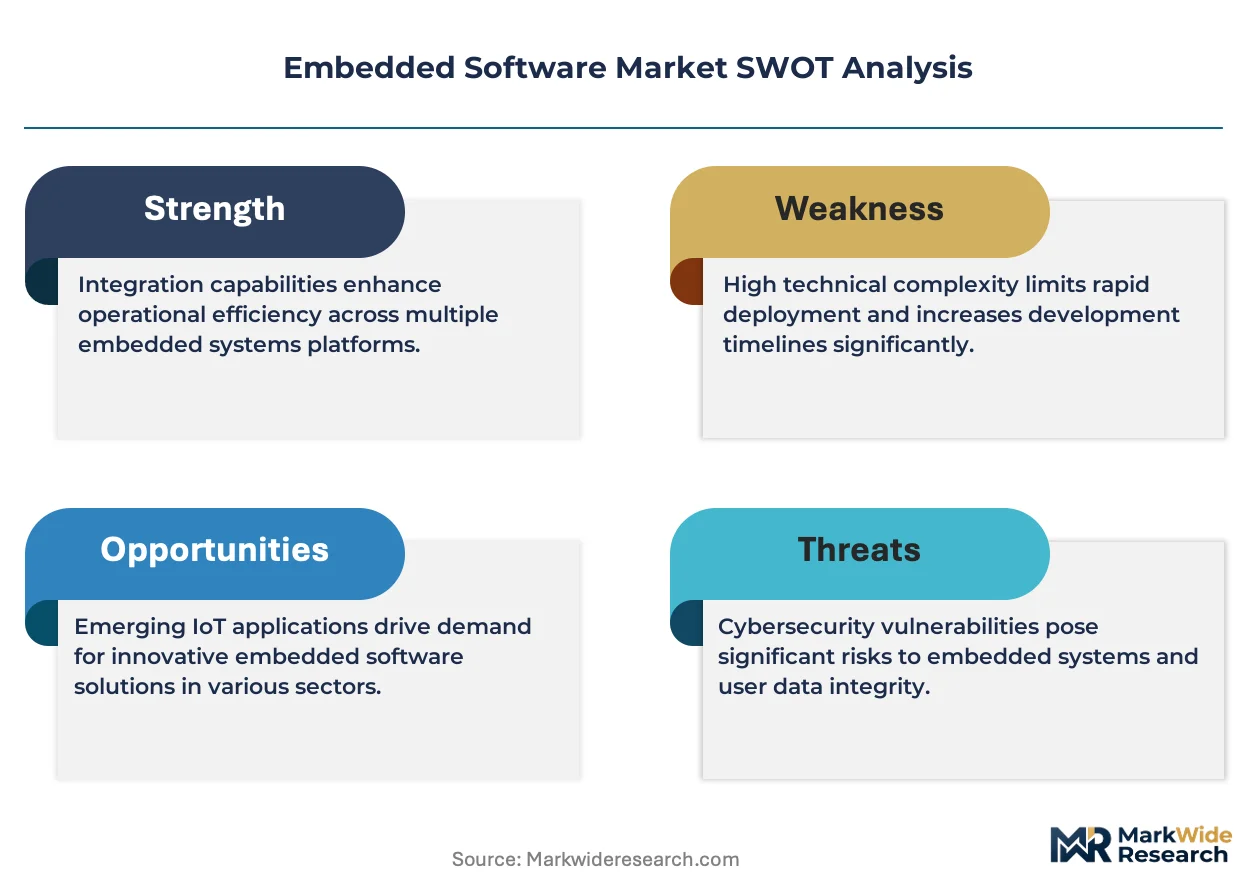
ISO 26262 functional safety mandates and the EU AI Act are forcing automotive OEMs to rearchitect embedded stacks for deterministic verification, compressing development cycles while elevating compliance costs.
Growth Catalysts
- Autonomous vehicle platforms:Automotive OEMs are expanding embedded software procurement for sensor fusion and decision-loop execution in safety-critical domains.
- EU AI Act algorithmic accountability:The regulation mandates traceability for embedded intelligence, creating mandatory upgrade cycles across consumer and automotive products.
- German engineering clusters:Stuttgart and Munich anchor Tier-1 supplier ecosystems that concentrate premium embedded development demand.
Market Restraints
- Specialized talent scarcity:Functional safety engineering expertise concentrates in Germany, Japan, and the US, constraining expansion velocity elsewhere.
- Certification cost escalation:FAA airborne system validation and FDA software-as-medical-device scrutiny multiply compliance expenditures.
- Legacy hardware lock-in:Deterministic response requirements below 10 milliseconds prevent cloud-native substitution for hard real-time workloads.
Strategic Opportunities
- Edge-native containerization:Kubernetes-based orchestration for resource-constrained environments below 512 KB opens hybrid deployment architectures.
- India PLI scheme electronics manufacturing:Production-linked incentives for semiconductor and embedded system assembly attract module-level software development.
- NHTSA cybersecurity guidelines:Connected vehicle security mandates create recurring revenue pools for over-the-air update and intrusion detection modules.
Industry Challenges
- Functional safety-AI integration:ISO 26262 lacks explicit guidance for neural network verification, forcing proprietary validation frameworks.
- Cross-domain certification timelines:Medical device FDA clearance and automotive KBA type approval operate on incompatible schedules, complicating platform reuse.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded Software Market |
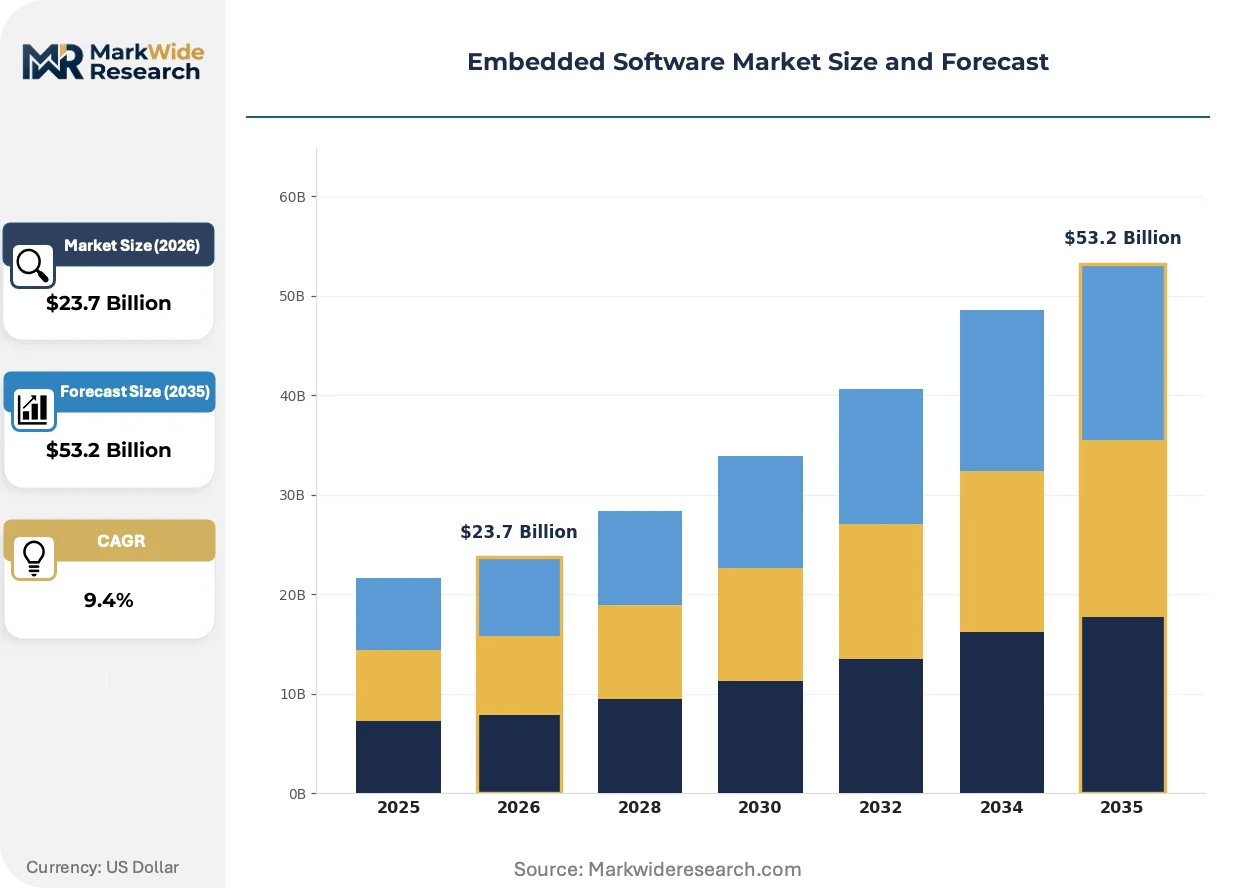
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $53.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Real-Time Operating Systems, Middleware, Development Tools, Security Solutions End User: Automotive, Consumer Electronics, Industrial Automation, Telecommunications Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Technology: IoT, AI, Machine Learning, Robotics |
| Companies Covered | Renesas Electronics, Zerynth, STMicroelectronics, aicas GmbH, Kontron, NXP Semiconductors, Sibros, Softeq, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded Software Market Emerging Trajectories
Deterministic virtualization and formal verification methods are compressing the gap between enterprise software agility and embedded reliability requirements.
Hypervisor technology is migrating from aerospace heritage systems to automotive domain controllers. Tier-1 suppliers in Germany and Japan are adopting MILS (Multiple Independent Levels of Security) architectures for mixed-criticality consolidation. This migration from physically separated ECUs to virtualized partitions reduces hardware unit counts while preserving fault isolation.
The EU AI Act risk-classification framework imposes documentation burdens on embedded intelligence in consumer products. Automotive OEMs must maintain algorithmic audit trails for autonomous decision systems. High-risk categories including driver-monitoring and emergency braking face mandatory third-party conformity assessment before CE marking.
Automotive procurement departments are consolidating vendor relationships around silicon-to-software integrated suppliers. Long-term framework agreements with Renesas, NXP, and STMicroelectronics are displacing discrete component sourcing. This concentration is most visible in Germany, where OEMs prioritize single-point accountability for functional safety compliance.
Embedded Software Market Segmentation
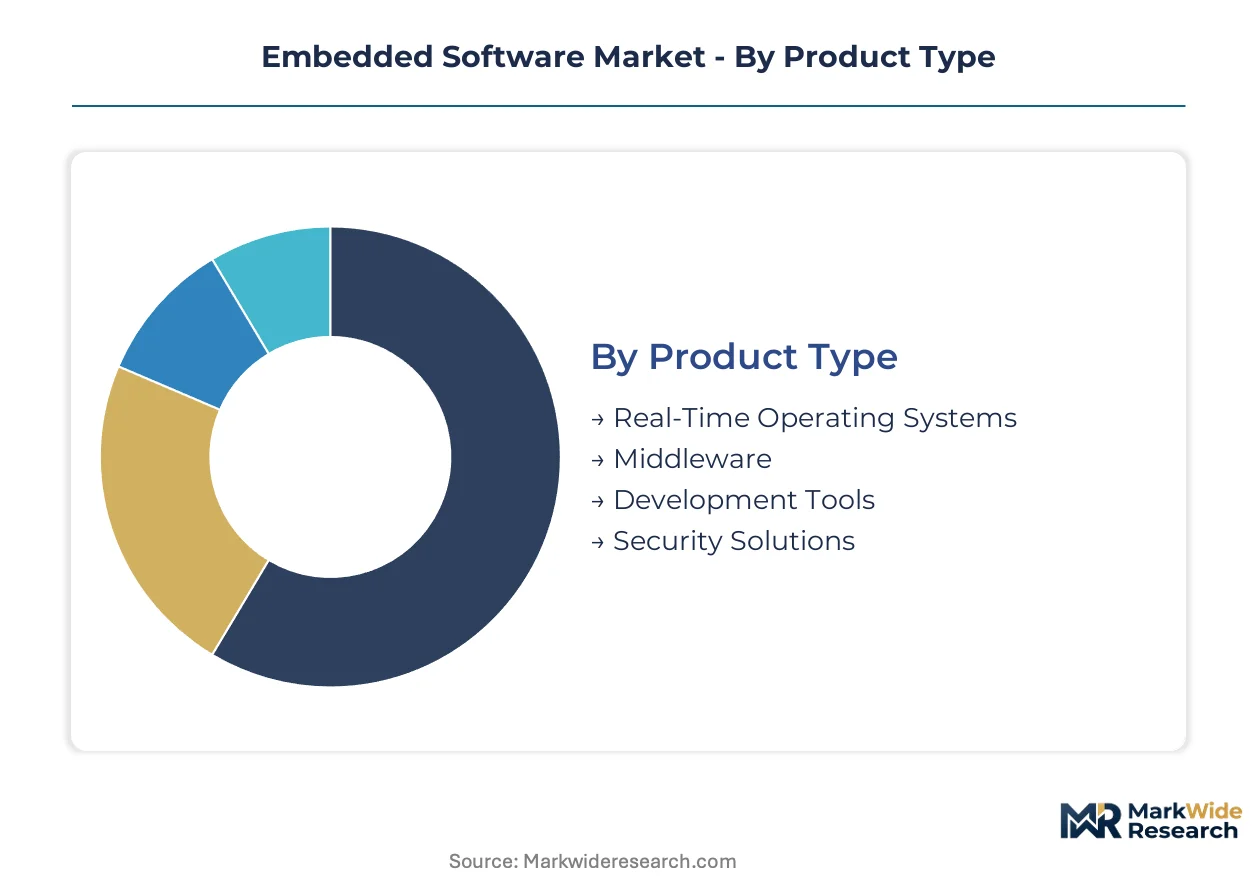
Embedded software procurement patterns diverge sharply across deployment environments and safety-criticality tiers. Automotive OEMs demand deterministic stacks under ISO 26262, while consumer electronics prioritize rapid iteration cycles.
Product Type:
Cost tier stratification separates mission-critical stacks from commodity development environments. Premium pricing concentrates in certified operating systems, while open-source middleware compresses margins at the base.
- Real-Time Operating Systems:Deterministic kernels guarantee response latencies below 10 milliseconds for hard real-time workloads. Automotive powertrain and aerospace flight-control systems in Germany and Japan anchor procurement volumes, with ISO 26262 ASIL-D certification mandatory for autonomous vehicle platforms.
- Security Solutions:Cryptographic modules, secure boot chains, and intrusion detection systems protect attack surfaces on connected devices. NHTSA cybersecurity guidelines for connected vehicles and EU AI Act algorithmic accountability mandates are accelerating upgrade cycles across automotive and medical device verticals.
- Middleware:Abstraction layers enabling hardware-software portability across heterogeneous silicon.
- Development Tools:Integrated environments for cross-compilation, debugging, and formal verification of resource-constrained binaries.
Real-Time Operating Systems command the established base. The steepest expansion runs through Security Solutions.
End User:
Application-specific reliability requirements create divergent procurement specifications across verticals. Functional safety mandates in automotive contrast with consumer electronics' time-to-market pressures.
- Automotive:Embedded stacks for autonomous driving, ADAS, and domain controllers operate under ASIL-B through ASIL-D safety integrity levels. Stuttgart and Munich engineering clusters concentrate Tier-1 supplier demand, with KBA type approval and EU AI Act conformity assessment gating market access.
- Industrial Automation:PLC firmware, motion control systems, and safety instrumented systems require deterministic cycle times. Japan's METI productivity initiatives and Germany's Industrie 4.0 adoption are expanding procurement for edge-native orchestration platforms.
- Consumer Electronics:Smartphone subsystems, wearable firmware, and smart home controllers prioritize power efficiency over hard real-time guarantees.
- Telecommunications:Baseband processing, network function virtualization, and 5G RAN software stacks.
Automotive anchors the revenue base. Industrial Automation is climbing the fastest as manufacturing digitization accelerates.
Deployment:
Volume distribution reflects latency tolerance thresholds across operational technology environments. Hard real-time constraints prevent cloud-native substitution for deterministic workloads.
- Edge Computing:Containerized workloads deployed directly on resource-constrained hardware below 512 KB memory footprints. Automotive domain controllers and industrial PLCs in Germany and Japan are adopting Kubernetes-based orchestration where cloud latency violates operational constraints.
- On-Premises:Air-gapped installations in defense, critical infrastructure, and regulated medical device manufacturing.
- Hybrid:Split architectures with local real-time loops and cloud-based analytics pipelines.
- Cloud-Based:Development, simulation, and non-real-time model training workloads.
On-Premises retains the safety-critical foundation. Edge Computing is gaining share fastest as containerization penetrates deterministic environments.
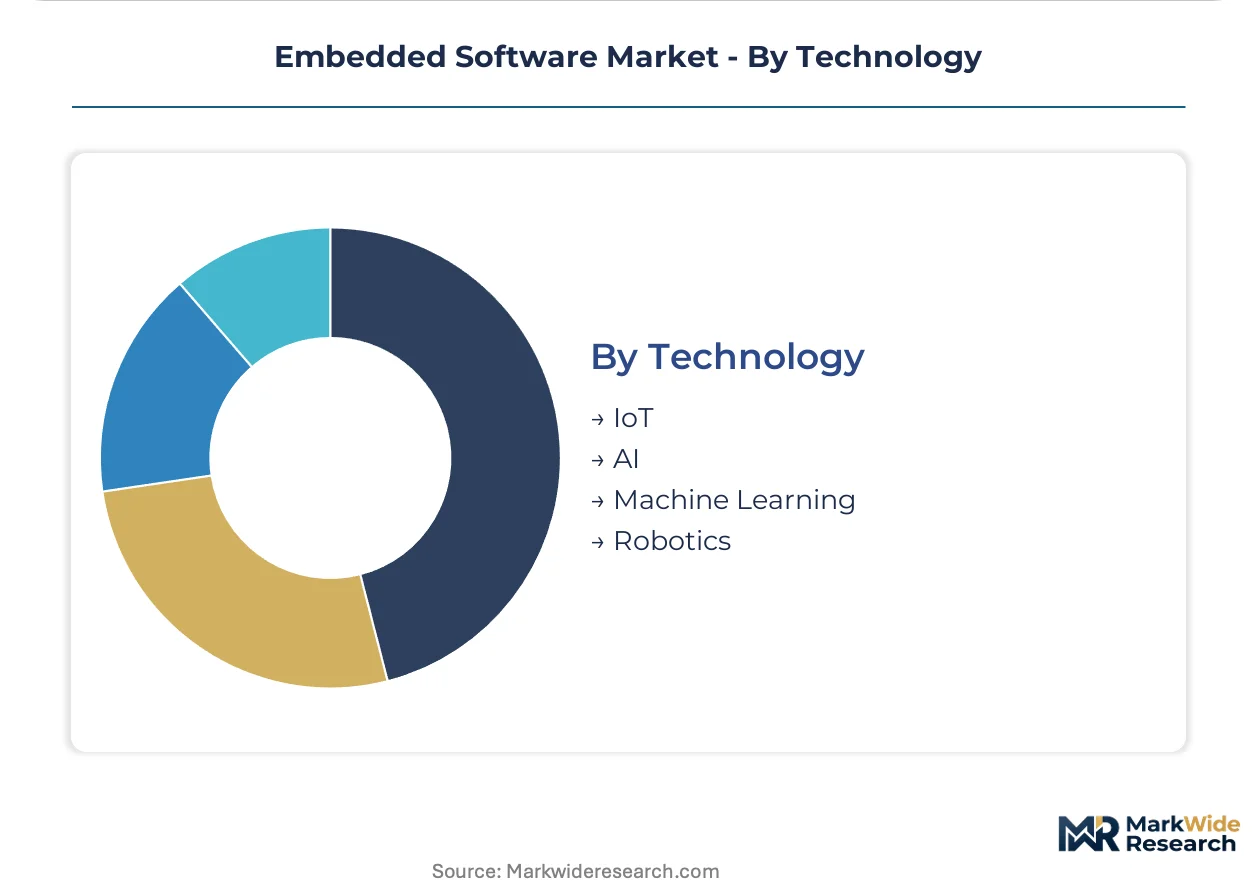
Technology:
Maturity gradients separate established connectivity stacks from emerging inference engines. Neural network deployment on microcontrollers is forcing architecture redesigns.
- IoT:Lightweight protocols, over-the-air update mechanisms, and power-optimized connectivity stacks for sensor networks. India's PLI scheme for electronics manufacturing is attracting module-level firmware development to Bangalore and Chennai clusters.
- AI:Embedded inference engines running neural networks on constrained hardware. EU AI Act risk-classification requirements and FDA software-as-medical-device scrutiny are elevating documentation burdens for algorithmic accountability.
- Machine Learning:TinyML frameworks enabling pattern recognition on sub-megabyte devices.
- Robotics:Real-time kinematics, sensor fusion, and safety-rated collaborative control systems.
IoT commands the installed base. AI is expanding most quickly as automotive OEMs integrate perception stacks into safety-critical domains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates the largest procurement budgets for safety-critical embedded stacks, with automotive OEMs and Tier-1 suppliers anchoring premium development demand across Stuttgart and Munich engineering clusters.
Germany
Automotive OEMs in Stuttgart and Munich drive ASIL-D certified stack procurement for autonomous vehicle platforms. KBA type approval and EU AI Act conformity assessment gate market access for embedded intelligence in driver-monitoring systems. Baden-Württemberg's Tier-1 supplier ecosystem concentrates development of domain controller firmware and hypervisor-based consolidation architectures.
United States
NHTSA cybersecurity guidelines for connected vehicles and FDA software-as-medical-device scrutiny elevate compliance expenditures across automotive and medical verticals. FAA airborne system validation requirements compress development cycles for aerospace flight-control stacks. Michigan and California engineering centers anchor procurement for autonomous driving perception systems and over-the-air update modules.
Japan
METI productivity initiatives accelerate edge-native orchestration platform adoption across industrial automation and robotics segments. JIS standards and functional safety expertise concentrate in Nagoya and Tokyo metropolitan clusters. Toyota and Honda supplier networks in Aichi Prefecture drive deterministic RTOS procurement for powertrain and chassis control systems.
India
PLI scheme electronics manufacturing incentives attract module-level firmware development to Bangalore and Chennai semiconductor clusters. CDSCO medical device regulations and BIS standards compliance create upgrade cycles for embedded healthcare systems. Telangana and Karnataka states concentrate IoT middleware development for export-oriented contract engineering.
South Korea
MFDS medical device software scrutiny and automotive functional safety mandates from KATRI elevate certification requirements for embedded stacks. Seoul Capital Area and Busan-Ulsan regions concentrate procurement for 5G baseband processing and vehicle networking modules. Samsung and Hyundai supplier ecosystems drive secure element integration for connected device platforms.
Embedded Software Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where silicon-to-software integration determines account access. Consolidation pressures favor vendors offering single-point accountability for functional safety compliance. Two archetypes dominate: microcontroller heritage suppliers with certified RTOS portfolios, and containerization specialists enabling Kubernetes-based edge orchestration. Competitive moves center on long-term framework agreements with automotive OEMs and MILS architecture licensing for domain controller consolidation.
Among microcontroller heritage suppliers, Renesas Electronics and STMicroelectronics exemplify the integrated silicon-to-software archetype, anchoring premium positioning through ASIL-certified stack offerings. NXP Semiconductors occupies a parallel position in vehicle networking and secure element segments, representing the functional safety-focused tier where automotive procurement departments consolidate vendor relationships.
| Leading Market Players |
|---|
| Renesas Electronics |
| Zerynth |
| STMicroelectronics |
| aicas GmbH |
| Kontron |
| NXP Semiconductors |
| Sibros |
| Softeq |
| Infineon Technologies |
| Others |
Supply Flow & Price Mechanics
Baden-Württemberg's Tier-1 supplier ecosystem anchors embedded software stack production, with Stuttgart engineering clusters concentrating ASIL-D certified development capacity. This geographic concentration grants incumbent silicon-to-software vendors substantial pricing power over automotive OEMs seeking single-point accountability for functional safety compliance.
Pricing Analysis
Cost-plus contracts with semiconductor price indexation dominate procurement between automotive OEMs and Tier-1 suppliers. Three-tier pricing structure across ASIL-D certified, ASIL-B compliant, and uncertified development tiers reflects certification investment recovery timelines. Cost compression in middleware layers is intensifying because open-source alternatives displace proprietary abstraction stacks. Consumer electronics OEMs exhibit highest price sensitivity, while German automotive procurement departments accept premium pricing for deterministic RTOS with ISO 26262 traceability.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for microcontroller-dependent embedded stacks. Taiwan, South Korea, and Germany concentrate foundry capacity and automotive-grade silicon design expertise. Raw material dependencies span 300mm silicon wafers, automotive-grade memory modules, and rare earth elements for secure element manufacturing. Single-source vulnerability persists for EUV lithography equipment. Distribution runs through direct long-term framework agreements rather than spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Functional safety engineering expertise concentrates in discrete geographic clusters, creating acute capability gaps for automotive OEMs expanding autonomous vehicle programs. This scarcity dynamic rewards early movers who secure certified talent pipelines and lock in silicon-to-software supplier relationships.
For Market Incumbents: Pre-empt emerging containerization specialists by accelerating hypervisor-based consolidation architecture licensing to German Tier-1 suppliers. Deepen backward integration into formal verification tooling to capture margin pools currently flowing to specialized validation vendors. ISO 26262 ASIL-D certification investment remains the critical defensive moat against open-source RTOS encroachment.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme electronics manufacturing corridors, where module-level firmware development lacks established ASIL-certified competitors. Target medical device embedded stacks facing FDA software-as-medical-device scrutiny, as incumbent automotive suppliers underinvest in cross-domain certification capabilities. Lead with Kubernetes-based edge orchestration for industrial automation segments where METI productivity initiatives accelerate adoption.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because EU AI Act algorithmic accountability mandates and NHTSA cybersecurity guidelines create recurring upgrade revenue streams. Acquisition targets should display dual ASIL-D and FDA clearance capabilities, enabling cross-vertical platform reuse. Monitor KBA type approval timeline compression as the signal indicating which embedded stack vendors have achieved deterministic verification scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | ISO 26262 compliance gates automotive procurement decisions and anchors premium pricing tiers. |
| Hypervisor Architecture Licensing | MILS consolidation reduces ECU counts while preserving fault isolation for domain controllers. |
| Edge-Native Containerization | Kubernetes orchestration below 512 KB memory opens hybrid deployment for industrial PLCs. |
| Cross-Domain Certification Expansion | FDA and KBA dual clearance enables platform reuse across medical and automotive verticals. |
| Secure Element Integration | NHTSA cybersecurity mandates create recurring revenue for over-the-air update modules. |
Methodological Framework
Desk research of regulatory filing databases, semiconductor trade flow records, and automotive production registries preceded structured interviews with Tier-1 supplier procurement directors, OEM platform engineers, functional safety validation specialists, and embedded software architects. Primary intelligence combined with secondary validation from SEC 10-K disclosures, EU AI Act implementation guidance, and IHS Markit vehicle production data. Bottom-up stack counts and top-down OEM R&D allocation triangulation anchored market sizing.
Assumptions held fixed include ISO 26262 ASIL tier penetration rates, EU AI Act enforcement timelines, and NHTSA cybersecurity guideline adoption curves across the analysis window. Variables stress-tested spanned semiconductor supply disruption scenarios, talent migration patterns, and open-source RTOS competitive encroachment. Segmentation modeling incorporated product type, end-user vertical, deployment architecture, and technology layer dimensions. CAGRs derived from regression against historical embedded content per vehicle trajectories and industrial automation digitization indices.
Stress conditions across wafer pricing volatility, certification backlog durations, and geopolitical trade restriction severity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and automotive OEM platform consolidation timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Test Automation Market
Software & Services
Medical E-Commerce Software Market
Software & Services
Global Help Desk Software Market
Software & Services
Cemetery Management Software Market
Software & Services
Denmark Software As a Service (Saas) Market
Software & Services
United States Contract Lifecycle Management Software Market
Software & Services
User Feedback Software Market
Software & Services
Java Integrated Development Environment (IDE) Market
Software & Services
Job Description Management Software Market
Software & Services
Model Based Testing Tools Market
Software & Services
Laboratory Management Software Market
Software & Services
Global Enterprise Architecture Tools Market
Software & Services
Subscription Management Software Market
Software & Services
Global Process Mining Software Market
Software & Services
Partner Ecosystem Platform Software Market
Software & Services
Packaged Software Market