
 Exploration and Production (E&P) Software Market | 2026-2036
Exploration and Production (E&P) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Exploration and Production (E&P) Software Market Insights
Cloud-native architecture is expanding its footprint across E&P software stacks as on-premise legacy systems face rising maintenance burdens. Schlumberger Limited leverages its digital platform portfolio to anchor enterprise-scale deployments across offshore basins. Halliburton sustains competitive pressure through specialized drilling optimization algorithms. Baker Hughes Company differentiates via integrated asset management suites that span turbine-to-reservoir workflows.
Exploration and Production (E&P) software encompasses geophysical modeling, reservoir simulation, drilling analytics, and production optimization platforms that process seismic data, well logs, and real-time sensor feeds to maximize hydrocarbon recovery economics. These systems typically operate on subsurface datasets exceeding terabyte scale, requiring high-performance computing clusters or distributed cloud architectures to execute finite-element reservoir simulations within operational decision windows. Reservoir Management and Production Monitoring command the largest installed bases, reflecting decades of capital deployment in brownfield optimization. Machine Learning and Cloud Computing represent the fastest-expanding technology layers, as operators retrain legacy decline-curve models on distributed GPU infrastructure to shorten forecast cycles.
The US EPA mandates methane monitoring and reporting thresholds that force operators to embed emissions-tracking modules directly into production software workflows. The EU CSRD extends sustainability disclosure requirements to upstream supply chains, compelling oil companies to demand audit-ready carbon accounting from their software vendors. Stakeholders must weigh the trade-off between cloud migration speed and data sovereignty constraints when selecting platforms for cross-border joint ventures.
Market Dynamics
The migration from on-premise data centers to cloud-native architectures is compressing deployment cycles and forcing vendors to rearchitect legacy reservoir simulation engines for distributed GPU clusters.
Growth Catalysts
- EPA Methane Rules:US operators must embed continuous emissions monitoring into production workflows, mandating software upgrades that integrate sensor telemetry with regulatory reporting modules.
- Permian Basin Consolidation:Shale producers in West Texas and southeastern New Mexico are standardizing on unified digital platforms to manage multi-asset portfolios across shared infrastructure.
- Machine Learning Retraining:Decline-curve analysis and predictive maintenance models are being rebuilt on neural architectures, cutting forecast generation from weeks to hours.
Market Restraints
- Data Sovereignty Constraints:Cross-border joint ventures in the North Sea and West Africa face jurisdictional conflicts over subsurface data residency, slowing cloud migration timelines.
- Legacy System Entrenchment:Brownfield operators in the Gulf of Mexico retain decades of proprietary well-log formats incompatible with modern API standards, trapping capital in maintenance contracts.
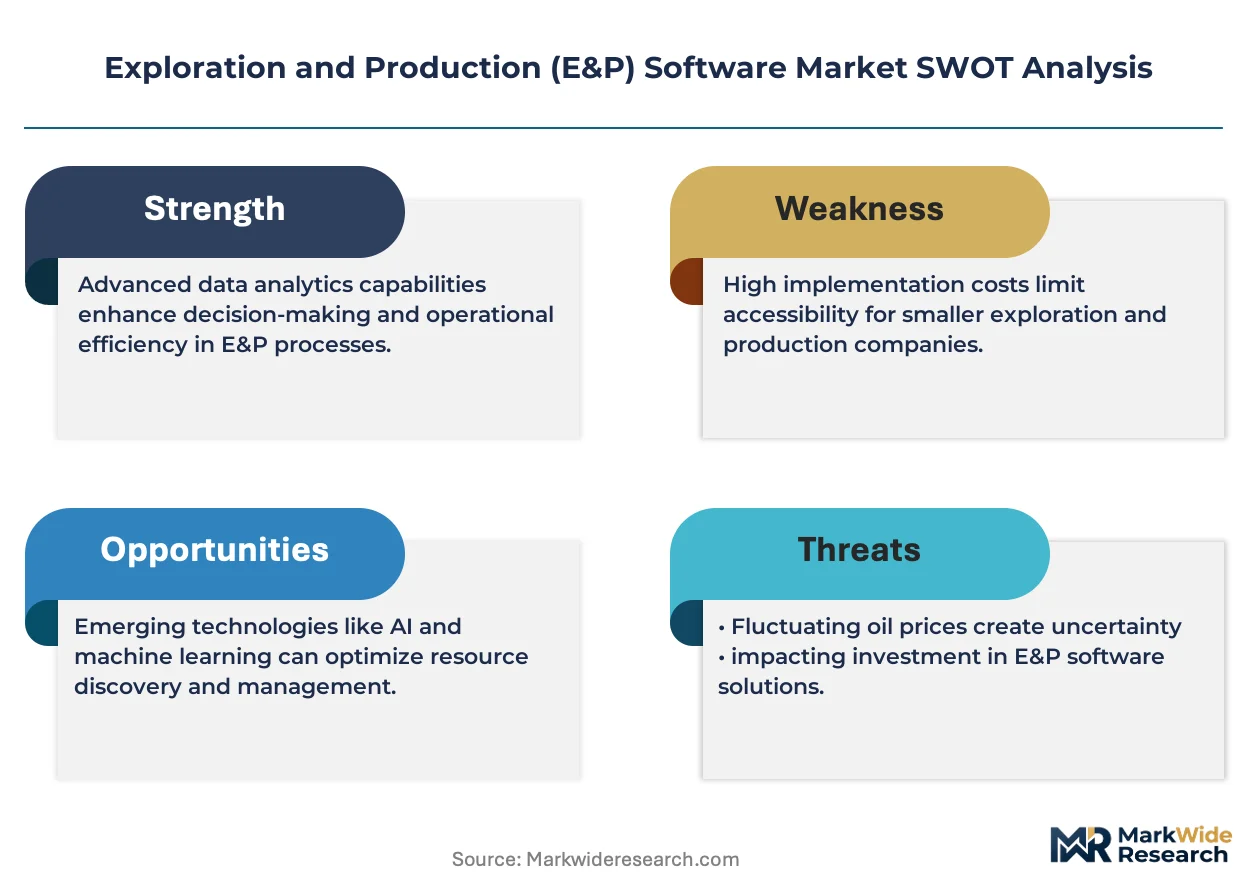
- Specialized Talent Scarcity:Reservoir engineers with dual competencies in geophysics and Python-based ML pipelines command premium compensation, inflating implementation costs for midsize independents.
Strategic Opportunities
- EU CSRD Compliance Layer:European operators now require audit-ready carbon accounting across upstream supply chains, opening subscription revenue for embedded sustainability modules.
- Offshore Brazil Pre-Salt:Petrobras-led consortia are digitizing subsalt characterization workflows, creating demand for high-fidelity seismic imaging platforms with real-time collaboration features.
- Edge Computing Convergence:Integration of subsea sensor arrays with localized processing units enables autonomous well-control decisions without satellite latency to onshore data centers.
Industry Challenges
- Seismic Data Format Fragmentation:Proprietary file structures from 1990s acquisition campaigns resist standardization, forcing expensive middleware development for unified interpretation environments.
- OT-IT Security Bridging:Production networks historically air-gapped from corporate IT now require zero-trust architectures, exposing operational technology to ransomware vectors without mature defense protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Exploration and Production (E&P) Software Market |
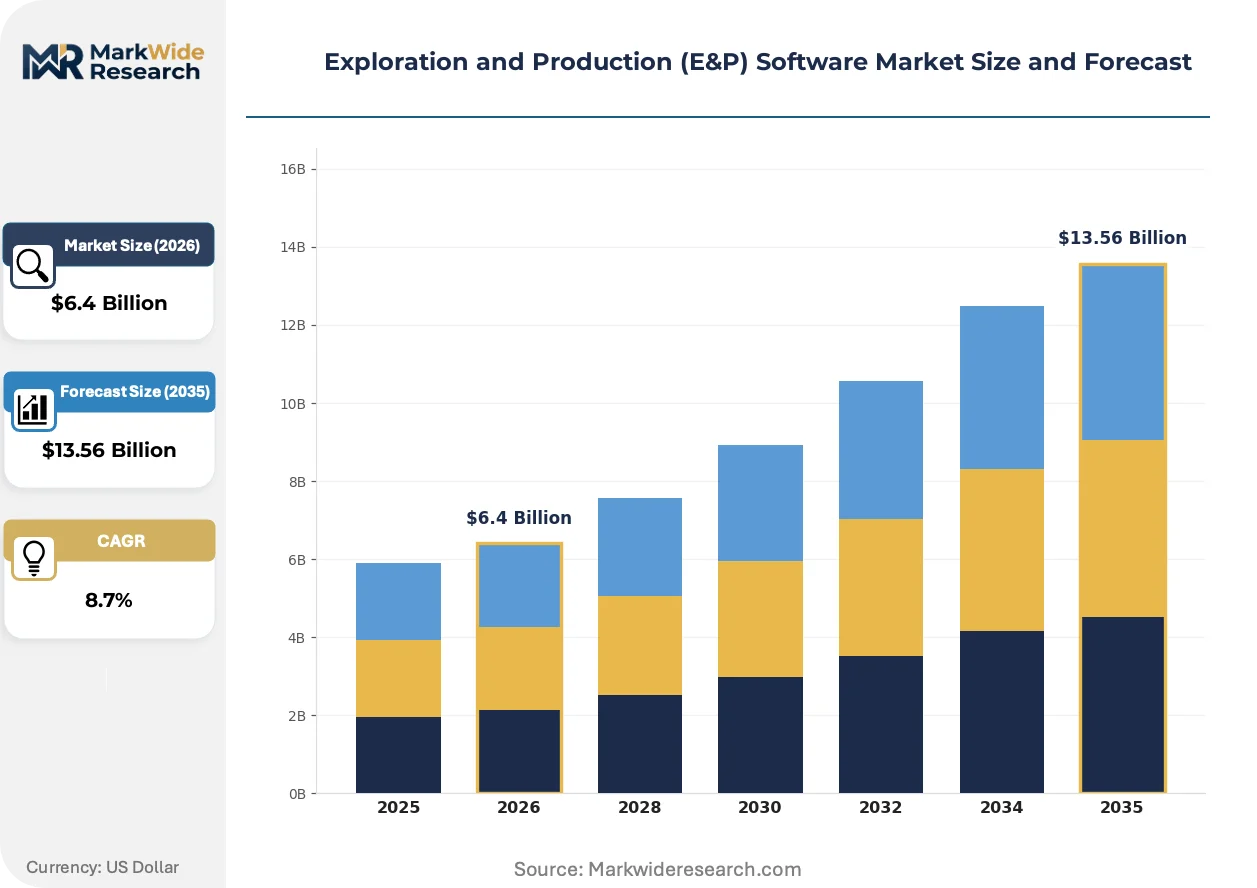
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $13.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reservoir Management, Drilling Optimization, Production Monitoring, Asset Management Application: Upstream Operations, Real-time Data Analysis, Exploration Planning, Environmental Compliance Technology: Cloud Computing, Geospatial Analytics, IoT Integration, Machine Learning End User: Oil Companies, Service Providers, Independent Operators, Regulatory Bodies |
| Companies Covered | Schlumberger Limited, Halliburton, Baker Hughes Company, Emerson Electric Co., SLB, Computer Modelling Group Ltd, CGG S.A., Paradigm B.V., ION Geophysical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Exploration and Production (E&P) Software Market Trends and Innovations
Computational workloads are redistributing across hybrid architectures as operators balance latency requirements against capital efficiency. Three developments are compressing traditional software procurement cycles.
Digital twin technology is absorbing reservoir characterization workflows previously executed on standalone physics engines. Offshore operators in the North Sea and Gulf of Mexico are deploying these twins at scale, feeding live wellbore telemetry into continuously updated subsurface models. The technology is absorbing capital previously allocated to physical well tests, redirecting spending toward simulation fidelity and scenario-planning subscriptions.
The EU CSRD mandates granular sustainability disclosures across Scope 1-3 emissions, compelling software vendors to build carbon-accounting APIs directly into production optimization suites. Operators must now trace methane venting events to individual wellhead components for auditor verification. European independents are responding by prioritizing vendors with pre-certified reporting modules over legacy platforms requiring custom integration.
Subscription pricing is displacing perpetual licenses across the independent operator segment, compressing upfront capital requirements into recurring operational expenditures. US shale producers in the Permian and Bakken formations are leading this transition, favoring month-to-month cloud access over multi-year on-premise deployments. This shift is most visible among private equity-backed portfolios where cash flow predictability outweighs long-term asset ownership.
Exploration and Production (E&P) Software Market Segmentation
E&P software procurement patterns diverge sharply by operational scale and regulatory exposure. Buyers prioritize either reservoir simulation fidelity or emissions compliance integration depending on asset portfolio composition.
Product Type:
Operators segment their software investments by whether they manage mature brownfields or greenfield developments.
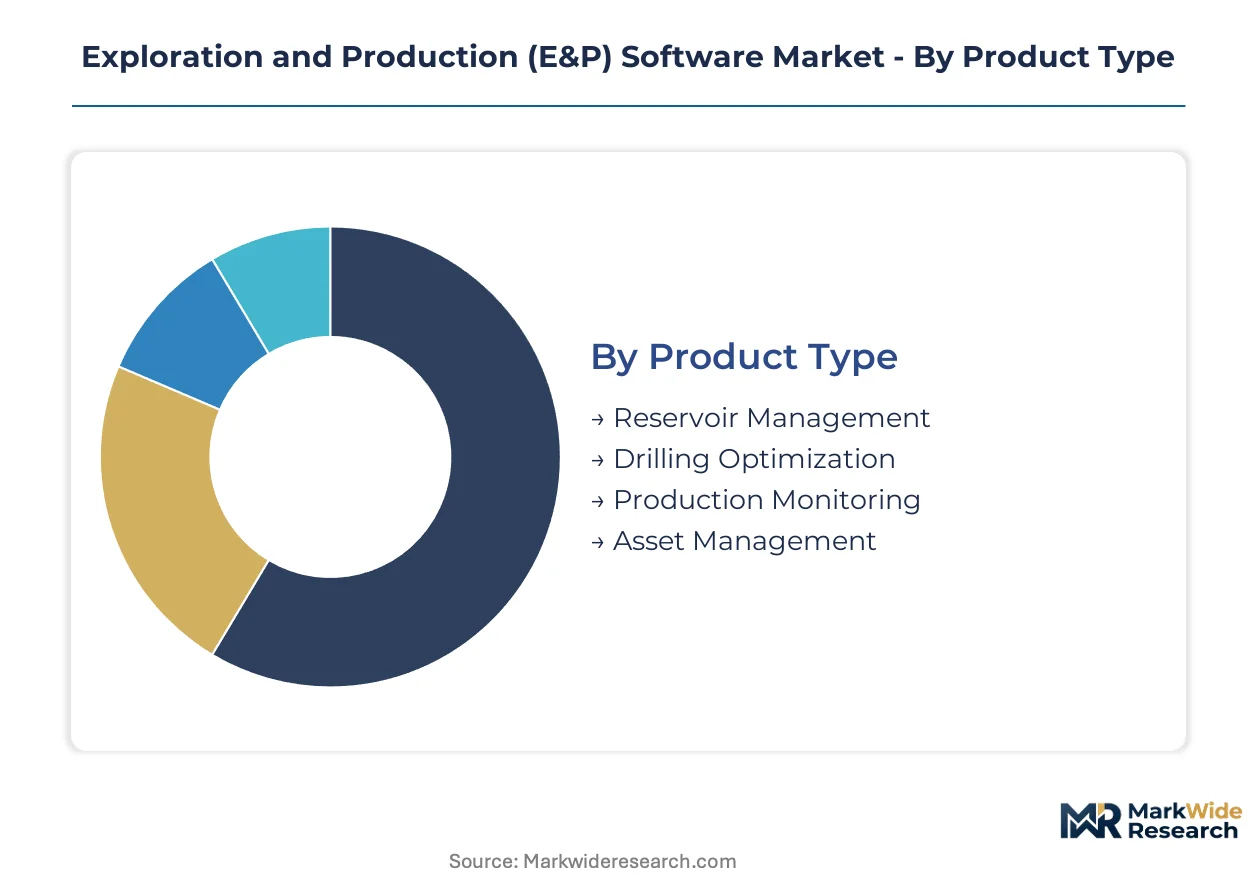
- Reservoir Management:Finite-element simulation engines process terabyte-scale seismic and well-log datasets to optimize recovery factors. Permian Basin shale producers deploy these platforms across multi-well pads to coordinate infill drilling programs. Volume sits with Reservoir Management; growth tilts toward Drilling Optimization.
- Drilling Optimization:Real-time trajectory control algorithms integrate MWD (measurement-while-drilling) telemetry with geomechanical models. Gulf of Mexico deepwater operators use these systems to reduce non-productive time in high-pressure formations. North Sea drillers prioritize this segment to navigate complex salt-layer geometries.
- Production Monitoring:SCADA-integrated dashboards track wellhead pressure, flow rates, and artificial lift performance across distributed assets.
- Asset Management:Enterprise suites spanning turbine maintenance to subsurface documentation for integrated operators.
Reservoir Management captures the largest installed base; Drilling Optimization climbs the fastest as real-time analytics displace reactive workflows.
Application:
Software deployment intensity correlates with data velocity requirements and regulatory audit frequency.
- Upstream Operations:Integrated platforms coordinate seismic acquisition, well construction, and facility management through unified data lakes. Brazilian pre-salt consortia demand these systems for subsalt characterization complexity. Norwegian operators anchor this segment through Equinor-led digitalization programs.
- Real-time Data Analysis:Edge-computing architectures process subsea sensor feeds at the wellhead to compress decision latency. US shale producers in the Permian deploy these capabilities to automate choke management during frac hits.
- Exploration Planning:Basin modeling and prospect risking tools for frontier acreage evaluation.
- Environmental Compliance:EPA-mandated methane monitoring modules with automated threshold alerting and audit trails.
Upstream Operations dominates current spending; Real-time Data Analysis expands most quickly as latency-sensitive applications migrate to edge infrastructure.
Technology:
Architecture choices divide buyers between capital efficiency and data sovereignty constraints.
- Cloud Computing:Distributed GPU clusters execute reservoir simulations previously requiring on-premise HPC investments. Independent operators in Texas favor this model to avoid data center capital deployment. West African joint ventures resist full migration due to cross-border data residency disputes.
- Machine Learning:Neural architectures retrain decline-curve models and predictive maintenance algorithms on operational datasets. Bakken shale producers use these tools to forecast artificial lift failures before production interruption.
- Geospatial Analytics:Seismic interpretation and satellite-based surface deformation monitoring for exploration teams.
- IoT Integration:Sensor telemetry aggregation from wellhead to SCADA to enterprise ERP systems.
Cloud Computing commands the widest deployment; Machine Learning gains share fastest as Python-based pipelines displace legacy statistical methods.
End User:
Purchasing authority concentrates with entities bearing direct reservoir risk or regulatory liability.
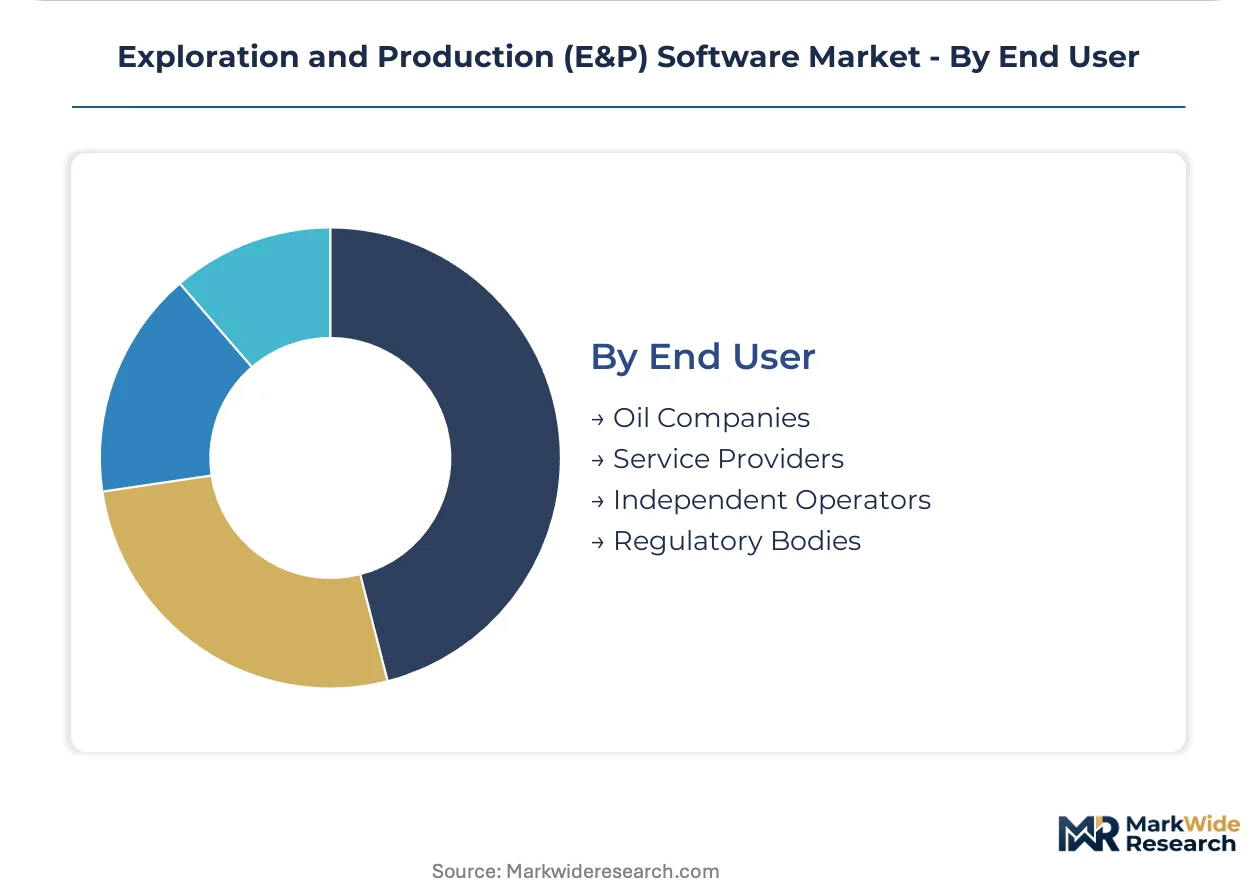
- Oil Companies:Integrated majors and NOCs specify enterprise platforms requiring vendor certification across multiple basins. Saudi Aramco and Petrobras anchor this segment through multi-year digital transformation contracts.
- Independent Operators:Private equity-backed shale producers favor subscription pricing and rapid deployment cycles. Permian-focused independents drive cloud-native adoption to minimize upfront capital.
- Service Providers:Halliburton and Schlumberger deploy proprietary platforms for integrated project delivery.
- Regulatory Bodies:EPA and EU member state agencies mandate reporting format standards that shape vendor development roadmaps.
Oil Companies control the largest procurement volumes; Independent Operators represent the steepest expansion trajectory as private capital consolidates shale positions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for E&P software concentrates in hydrocarbon-producing jurisdictions where regulatory pressure intersects with digital infrastructure investment cycles.
United States
EPA methane monitoring mandates and Permian Basin shale consolidation drive procurement intensity. Independent operators in West Texas deploy cloud-native platforms to manage multi-well pad portfolios under tightening emissions reporting thresholds. Houston anchors vendor development activity for offshore Gulf of Mexico digital twin deployments.
Brazil
Petrobras-led pre-salt digitization programs create demand for high-fidelity seismic imaging and real-time collaboration tools. The national petroleum regulator ANP imposes subsurface data retention requirements that shape local cloud architecture decisions. Rio de Janeiro concentrates software implementation expertise for deepwater reservoir characterization workflows.
Norway
Equinor's digitalization programs and the Norwegian Petroleum Directorate's data sharing regulations accelerate integrated platform adoption. Operators in the North Sea basin face data sovereignty constraints across cross-border joint ventures with UK and Danish partners. Stavanger hosts specialized vendor engineering teams focused on subsea production optimization.
Saudi Arabia
Saudi Aramco's multi-year transformation contracts and the Ministry of Energy's localization mandates reshape procurement patterns. The kingdom's push toward gas field development and unconventional resource characterization expands simulation software demand. Dhahran concentrates in-country technical support infrastructure for enterprise-scale reservoir management deployments.
United Kingdom
North Sea decommissioning liabilities and the North Sea Transition Authority's emissions reduction targets force legacy system modernization. Operators in Aberdeen and the Scottish cluster integrate carbon accounting modules into production workflows to satisfy evolving disclosure requirements. London-based trading desks demand real-time data feeds for portfolio optimization decisions.
Exploration and Production (E&P) Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated energy technology providers holding dominant positions in enterprise deployments while niche vendors capture specialized workflow segments. The vendor landscape organizes around three archetypes: full-stack platform providers, point-solution specialists in seismic imaging or drilling analytics, and emerging cloud-native challengers. Consolidation pressure intensifies as majors acquire machine learning startups to embed predictive capabilities into legacy suites. Partnership strategies dominate where data interoperability requirements exceed single-vendor delivery capacity.
Within the full-stack platform tier, Schlumberger Limited and Halliburton occupy positions exemplifying the integrated technology provider archetype, anchoring enterprise-scale deployments across multiple basins through comprehensive digital portfolios. Baker Hughes Company represents the industrial-technology hybrid model, bridging turbine maintenance and subsurface workflows. These three entities collectively shape procurement standards that smaller vendors must accommodate to participate in consortium bidding processes.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton |
| Baker Hughes Company |
| Emerson Electric Co. |
| SLB |
| Computer Modelling Group Ltd |
| CGG S.A. |
| Paradigm B.V. |
| ION Geophysical Corporation |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up shale specialists in the Permian Basin anchor procurement discipline through subscription-heavy SaaS contracts, compressing vendor margins while demanding cloud-native delivery that reshapes upstream software supply economics.
Pricing Analysis
Volume concentrates in enterprise reservoir management suites while margin capture tilts toward specialized drilling optimization modules. Pricing stratifies across premium, standard, and economy tiers with differentiation driven by API certification grade and embedded emissions compliance depth. Cost compression in the independent operator segment is intensifying because private-equity-backed portfolios prioritize cash flow predictability over long-term asset ownership. Oil companies show least price sensitivity due to multi-year digital transformation mandates, while regulatory bodies exhibit highest sensitivity through format-standardization pressures.
Supply Chain Analysis
Saudi Arabia's In-Country Total Value Add program and Brazil's ANP local-content mandates are reshaping vendor sourcing toward Dhahran and Rio de Janeiro engineering centers. Software development draws from the United States, Norway, and Saudi Arabia for reservoir simulation engines, GPU cluster infrastructure, and subsurface characterization algorithms. Single-source vulnerability sits with specialized Python-ML talent pools concentrated in Houston and Stavanger. Distribution runs through direct enterprise sales for integrated majors and cloud marketplace channels for independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained through scarce reservoir engineers commanding dual geophysics and machine-learning competencies, a bottleneck that props pricing power for talent-intensive implementation services.
For Market Incumbents: Cement platform stickiness through embedded carbon-accounting APIs that satisfy EU CSRD audit requirements, locking out point-solution competitors. Deepen backward integration into GPU cluster infrastructure to control simulation delivery costs against cloud-provider margin capture. Priority lever: pre-certification with EPA methane reporting formats to accelerate procurement cycles. For New Entrants and Emerging Players: Enter via environmental compliance modules for European independents facing Scope 1-3 disclosure mandates, the most penetrable segment due to legacy platform gaps. Target West African joint ventures constrained by data sovereignty conflicts that slow incumbent cloud migrations. Go-to-market angle: edge-computing architectures for subsea sensor integration with localized processing units. For Investors and Strategic Acquirers: Distressed-cycle entries favor cloud-native challengers with pre-built sustainability reporting layers in the North Sea basin, where decommissioning liabilities force legacy modernization. Long-term viability hinges on vendor ability to bridge operational technology and corporate IT security protocols. Signal to watch: EPA enforcement intensity on continuous emissions monitoring thresholds as inflection indicator for compliance-module demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies seismic interpretation with real-time production monitoring for Permian shale operators. |
| Acquisition of Specialist Firm | Embeds machine-learning decline-curve capabilities into legacy reservoir simulation engines. |
| Strategic Partnership | Links subsea sensor manufacturers with edge-computing providers for autonomous well control. |
| Geographic Expansion | Establishes Dhahran technical centers to satisfy Saudi Aramco localization mandates. |
| Product Launch | Introduces pre-certified EPA methane reporting modules for audit-ready compliance workflows. |
Research Methodology
SEC 10-K filings, hyperscaler capex disclosures, and EIA production data formed the secondary backbone, cross-referenced with primary interviews across reservoir engineering directors, IT procurement officers at integrated majors, and regulatory affairs leads at EPA and EU member state agencies. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators anchored forecast integrity.
Historical trendline analysis across deployment model, organization size, and regional adoption pattern dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against basin-specific digital investment cycles. Forecast inputs incorporated cloud migration velocity indices and regulatory compliance deadline clustering without year-specific anchoring.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EPA methane rule enforcement acceleration or sovereign data-localization mandate expansion. Assumptions reflect current regulatory trajectories and technology adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Sales Training Software Market
Software & Services
Global Spa and Salon Software Market
Software & Services
Collaborative Applications Market
Software & Services
Indonesia IT Services Market
Software & Services
Software Testing Company Market
Software & Services
Intelligent Enterprise Data Capture Software Market
Software & Services
Bankruptcy Software Market
Software & Services
Global Custom Software Development Services Market
Software & Services
Batch Management Software Market
Software & Services
Performing Arts Software Market
Software & Services
Global User Interface Service Market
Software & Services
Global Software Resellers Market
Software & Services
Petcare Software Market
Software & Services
Proxy Services and Software Market
Software & Services
Public Financial Management Software Market
Software & Services
Enterprise Content Management Software Market