
 China Hand Sanitizer Market | 2026-2036
China Hand Sanitizer Market Size, Share, and Industry Trends Forecast 2026-2036
China Hand Sanitizer Market Intelligence
Hospital procurement is tilting toward domestic suppliers with verified manufacturing scale and GB standard compliance. Blue Moon International leverages its detergent-to-disinfectant vertical network to control raw alcohol sourcing. Shanghai Likang Disinfection High-Tech anchors its position through specialized hospital-grade formulations. Reckitt Benckiser Household Products competes on brand recognition but navigates tightening local content preferences.
Hand sanitizer comprises alcohol-based or non-alcohol formulations designed for pathogen reduction on intact skin, typically containing ethanol at concentrations between 60% and 95% by volume with emollients to prevent dermal irritation. The product serves infection control protocols across healthcare, food service, and consumer settings where handwashing infrastructure is unavailable or insufficient. Gel formulations dominate retail shelf space due to consumer familiarity and spill resistance, while foam variants gain traction in healthcare facilities for controlled dosing and reduced waste. Spray formats occupy a premium niche in public place installations where rapid surface-and-hand dual use is valued. Tube packaging leads household penetration for portability, though dispenser systems deepen institutional adoption.
SAMR enforces disinfectant registration and label claims verification, while NMPA oversees sanitizers positioned with therapeutic indications. GB standards mandate minimum effective concentration thresholds and stability testing protocols that shape product development cycles. Stakeholders must monitor how China's dual carbon goals reshape ethanol feedstock sourcing and packaging material compliance requirements.
Market Dynamics
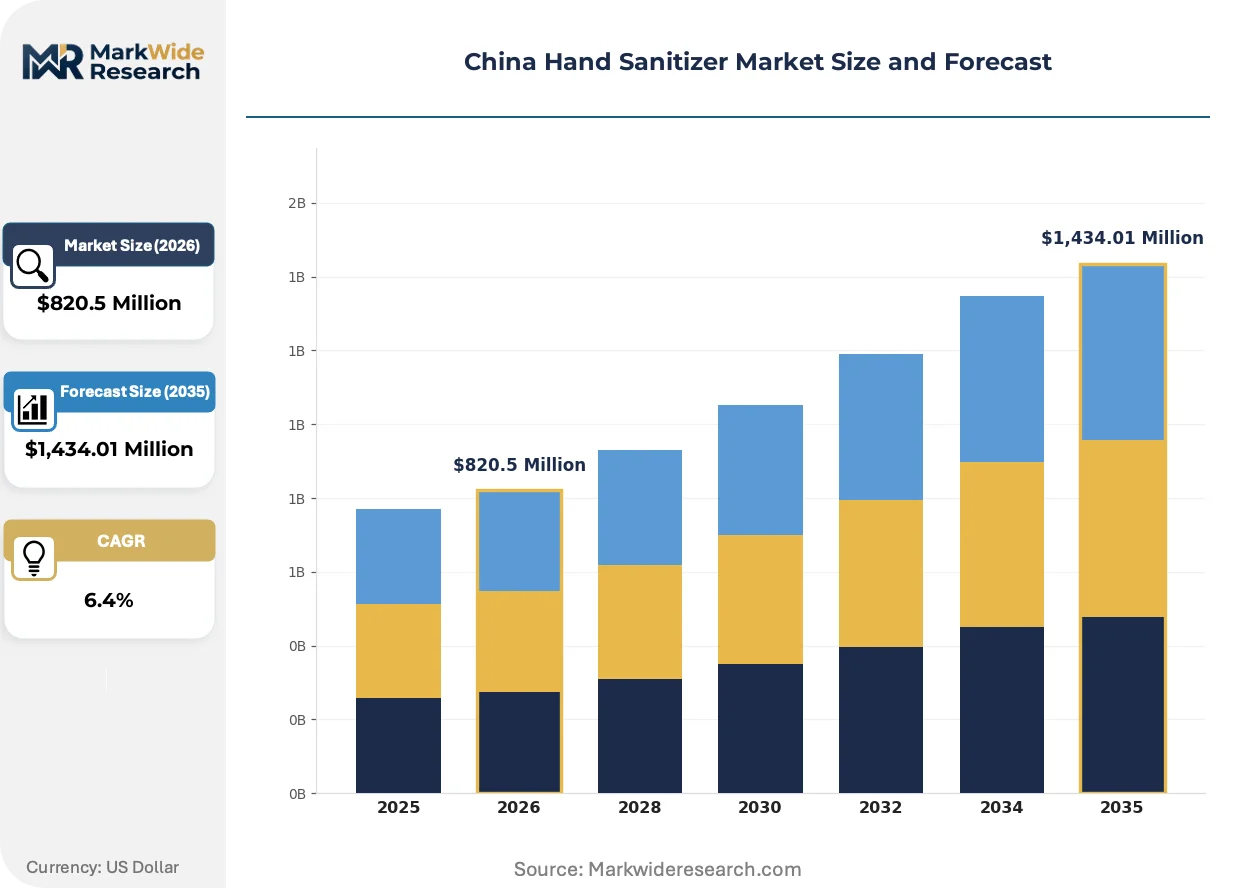
Hospital-grade ethanol procurement is consolidating under state-directed supply agreements that favor domestic producers with verified GB 27951 compliance, compressing import-dependent channels and reshaping competitive access.
Growth Catalysts
- GB Standard Enforcement:SAMR's tightened disinfectant registration protocols are disqualifying non-compliant imports and clearing shelf space for certified domestic manufacturers.
- Healthcare Infrastructure Expansion:Tier-one municipal governments in Shanghai and Beijing are mandating hand sanitizer stations in all new commercial developments above 50,000 square meters.
- Dual Carbon Feedstock Pivot:Bioethanol from agricultural residue is displacing fossil-derived alcohol in state procurement tenders, creating preferential access for producers with circular supply chains.
Market Restraints
- Ethanol Price Volatility:Corn and cassava feedstock costs fluctuate with agricultural policy shifts, squeezing margin stability for mid-scale compounders without captive fermentation capacity.
- Concentrated Raw Material Access:Industrial alcohol supply concentrates in Shandong and Jiangsu provinces, exposing national distributors to regional logistics disruptions and provincial quota systems.
- Non-Alcohol Substitution:Quaternary ammonium compound hand rubs are gaining hospital preference for surgical settings where alcohol-induced dermatitis rates trigger staff compliance failures.
Strategic Opportunities
- Western Province Penetration:Sichuan and Shaanxi healthcare networks remain under-supplied with hospital-grade formulations, presenting first-mover expansion potential for GB-certified producers.
- Dispenser System Integration:IoT-enabled consumption tracking hardware is converging with sanitizer supply contracts, enabling subscription revenue models in high-traffic transportation hubs.
- Green Packaging Mandates:MEE's plastic reduction directives for single-use containers are accelerating demand for refillable aluminum cartridges and concentrated tablet formulations.
Industry Challenges
- Formulation Chemist Scarcity:Qualified professionals capable of optimizing ethanol-glycerol-thickener stability under GB stability testing protocols command premium compensation in coastal manufacturing zones.
- SAMR Registration Timelines:New disinfectant approvals now require 14-18 months of efficacy documentation, delaying product launches and freezing working capital in pre-revenue development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Hand Sanitizer Market |
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,434.01 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gel, Foam, Spray, Liquid Packaging Type: Tubes, Bottles, Sachets, Dispensers Distribution Channel: Supermarkets, Pharmacies, Online Retail, Convenience Stores End User: Households, Healthcare Facilities, Educational Institutions, Public Places |
| Companies Covered | Blue Moon International Co. Ltd., Reckitt Benckiser Household Products (China) Co. Ltd., Shanghai Likang Disinfection High-Tech Co. Ltd., Walch Malaysia (Whealthfields Lohmann), S. C. Johnson & Son, GOJO Industries, Inc., Procter & Gamble, Lion Corporation, Health & Beyond Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Hand Sanitizer Market Strategic Shifts & Innovations
Active ingredient sourcing and delivery formats are diverging as state carbon targets and hospital infection control protocols impose conflicting technical requirements on product development cycles.
Foam-dispensing actuator technology is migrating from gel-dominant retail formats toward healthcare procurement specifications. Shanghai municipal hospitals are piloting controlled-dose systems that reduce per-use volume by 40 percent compared to squeeze bottles. This migration from consumer convenience toward institutional waste reduction is compressing SKU diversity and favoring suppliers with dual-format manufacturing lines.
GB 27951-2021 disinfectant efficacy standards are mandating accelerated stability testing protocols that extend development timelines. Manufacturers must now demonstrate 24-month active concentration retention under variable temperature storage, forcing reformulation of legacy ethanol-thickener systems. Hospital procurement departments are responding by inserting compliance verification clauses into multi-year supply agreements.
Direct hospital contracting is displacing layered distributor networks in tier-one cities. Beijing's municipal health commission now operates centralized purchasing platforms that aggregate demand across 47 public hospitals. This consolidation is most visible in pediatric and oncology wards where infection control budgets carry zero-tolerance failure thresholds.
China Hand Sanitizer Market Segmentation
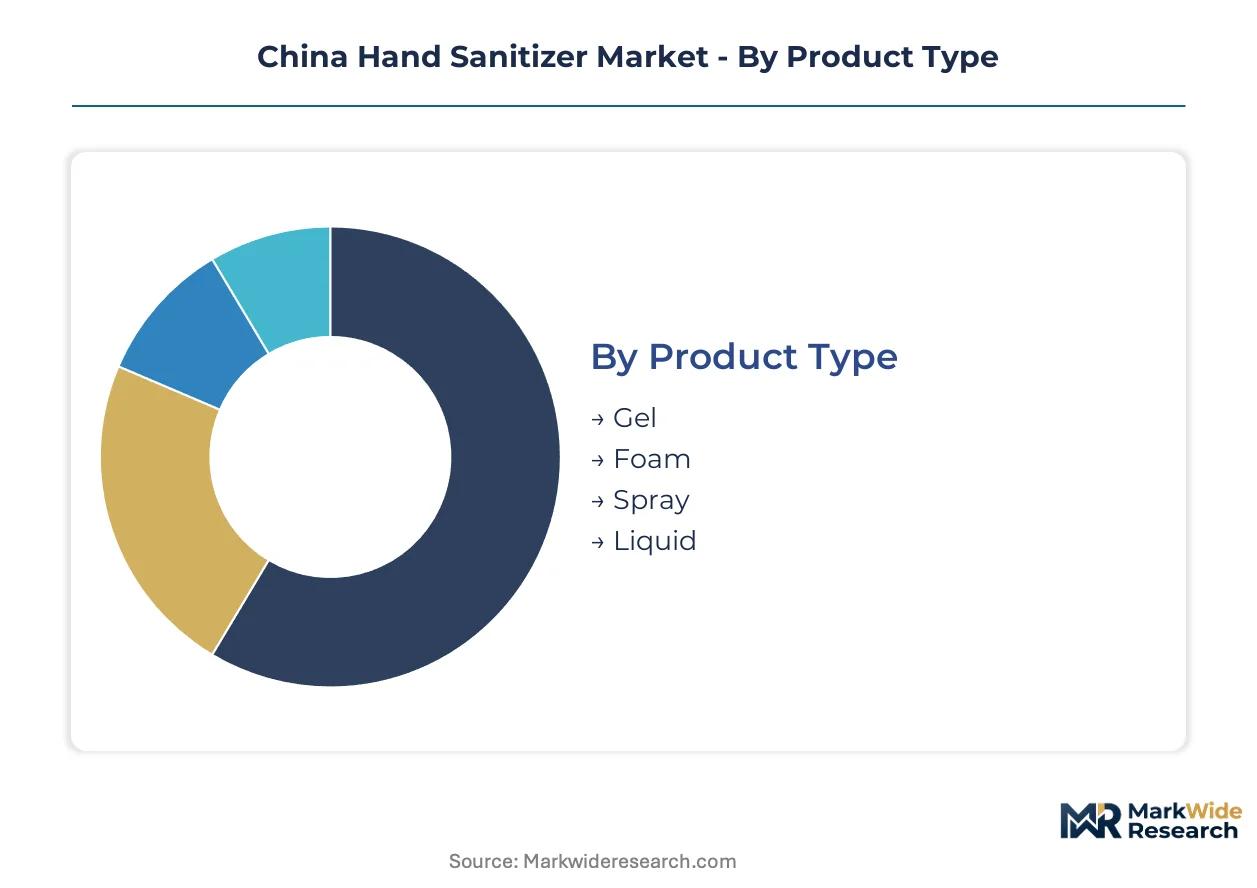
China's hand sanitizer market segments along four intersecting dimensions that determine pricing power, regulatory burden, and channel access. Product format and packaging choices shape manufacturing complexity, while distribution and end-user targeting dictate compliance requirements under SAMR and GB standards.
Product Type:
Mature gel formulations dominate shelf presence, while foam and spray formats emerge as technical differentiators in institutional procurement.
- Gel:Thickened ethanol-glycerol suspensions at 60-95% concentration provide spill resistance and controlled dosing for consumer familiarity. Household demand concentrates in Shanghai and Beijing, where retail shelf space allocation favors established viscosity profiles under GB 27951 stability protocols.
- Foam:Air-entrained formulations dispense as pre-lathered microbubbles, reducing per-use volume by 40% in hospital pilot programs. Beijing municipal hospitals are mandating controlled-dose systems in pediatric and oncology wards where waste reduction intersects with zero-tolerance infection thresholds.
- Spray:Atomized delivery enables rapid surface-and-hand dual use in transportation hubs and public installations.
- Liquid:Low-viscosity formulations serve dispenser system compatibility and bulk institutional refilling requirements.
Gel handles the majority of throughput; foam is gaining share fastest in healthcare procurement specifications.
Packaging Type:
Cost tier segmentation separates portable single-use formats from capital-intensive dispenser infrastructure.
- Tubes:Aluminum-laminate squeeze containers dominate household portability needs, with MEE plastic reduction directives accelerating refillable cartridge development in tier-one cities.
- Bottles:PET and HDPE containers anchor retail volume, though GB labeling requirements for ethanol concentration claims extend production lead times.
- Sachets:Single-serve foil pouches address travel and food-service segments where portion control trumps sustainability metrics.
- Dispensers:Wall-mounted and freestanding units with IoT-enabled consumption tracking are converging with multi-year supply contracts in high-traffic transportation infrastructure.
Bottles carry the volume base; dispenser systems are climbing fastest on subscription revenue models.
Distribution Channel:
Customer type determines channel strategy, with institutional procurement displacing layered retail networks in concentrated demand zones.
- Supermarkets:Hypermarket and supermarket chains in Shanghai and Beijing allocate premium shelf space to GB-certified domestic brands with verified manufacturing scale.
- Pharmacies:Hospital-affiliated and community pharmacy networks enforce SAMR registration verification, disqualifying non-compliant imports and clearing shelf space for certified manufacturers.
- Online Retail:E-commerce platforms aggregate fragmented household demand across western provinces, though logistics costs compress margin for ethanol-based formulations subject to hazardous material shipping restrictions.
- Convenience Stores:24-hour urban outlets capture impulse purchase occasions in commercial districts with mandated sanitizer station requirements.
Supermarkets and pharmacies dominate value capture; online retail is expanding most quickly in underpenetrated western provinces.
End User:
Application-driven segmentation imposes divergent technical specifications and compliance intensities.
- Households:Price-sensitive consumers in tier-one cities prioritize gel familiarity and portable tube formats, with brand recognition driving repeat purchase.
- Healthcare Facilities:Hospitals and clinics mandate GB 27951-2021 compliance with 24-month stability documentation, consolidating procurement under Beijing and Shanghai municipal centralized purchasing platforms.
- Educational Institutions:Schools and universities balance cost constraints with duty-of-care liability, favoring foam dispensers for controlled dosing in high-density settings.
- Public Places:Transportation hubs, commercial developments above 50,000 square meters, and municipal installations drive dispenser system adoption with IoT-enabled consumption tracking.
Healthcare facilities command premium pricing through compliance barriers; public places are the steepest expansion trajectory on infrastructure mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Beijing-Shanghai high-speed rail corridor underwrites China's hand sanitizer distribution topology, linking the Yangtze and Jing-Jin-Ji manufacturing clusters to tier-one demand centers.
Yangtze River Delta
Shanghai's municipal health commission operates centralized procurement platforms aggregating demand across 47 public hospitals. SAMR's GB 27951-2021 disinfectant registration protocols disqualify non-compliant imports here. Zhejiang and Jiangsu province manufacturers dominate ethanol feedstock processing along the lower Yangtze industrial belt.
Pearl River Delta
Guangdong province's commercial density above 50,000 square meters triggers mandatory sanitizer station requirements in Shenzhen and Guangzhou developments. MEE plastic reduction directives accelerate refillable aluminum cartridge adoption. Dongguan packaging suppliers pivot toward dispenser system integration for high-traffic transportation hubs.
Beijing-Tianjin-Hebei
Hebei province's corn ethanol fermentation capacity supplies northern hospital networks under state-directed procurement agreements. Beijing's zero-tolerance infection thresholds in pediatric and oncology wards mandate GB-certified foam dispenser systems. Tianjin port infrastructure handles imported quaternary ammonium compound raw materials.
Sichuan-Chongqing
Western healthcare networks remain under-supplied with hospital-grade formulations, presenting first-mover expansion potential. Chongqing's municipal rail expansion creates installation sites for IoT-enabled consumption tracking hardware. Provincial agricultural residue programs feed bioethanol pilot projects aligned with dual carbon procurement tenders.
Shandong Peninsula
Shandong province anchors industrial alcohol supply concentration, exposing national distributors to regional logistics disruptions. Qingdao's port facilities export ethanol-derived formulations under SAMR label claims verification. Provincial quota systems constrain feedstock access for mid-scale compounders without captive fermentation capacity.
China Hand Sanitizer Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in ethanol sourcing and actuator manufacturing. The vendor base stratifies across three tiers: multinational household brands with established retail shelf access, domestic chemical conglomerates with backward integration into alcohol feedstocks, and regional compounders serving institutional procurement specifications. Two dominant competitive moves define current positioning: direct hospital contracting displacing layered distributor networks in tier-one cities, and dispenser system integration enabling subscription revenue models.
Within the domestic chemical conglomerate tier, Blue Moon International Co. Ltd. and Shanghai Likang Disinfection High-Tech Co. Ltd. exemplify divergent sourcing strategies. Blue Moon anchors its position through detergent-to-disinfectant network control over raw alcohol procurement. Shanghai Likang occupies a specialized position in hospital-grade formulation development under GB stability protocols. Among multinational platforms, Reckitt Benckiser Household Products (China) Co. Ltd. represents brand-recognition competition navigating tightening local content preferences in municipal procurement.
| Leading Market Players |
|---|
| Blue Moon International Co. Ltd. |
| Reckitt Benckiser Household Products (China) Co. Ltd. |
| Shanghai Likang Disinfection High-Tech Co. Ltd. |
| Walch Malaysia (Whealthfields Lohmann) |
| S. C. Johnson & Son |
| GOJO Industries, Inc. |
| Procter & Gamble |
| Lion Corporation |
| Health & Beyond Inc. |
| Others |
Cost & Logistics Intelligence
Overcapacity in Shandong's industrial ethanol fermentation plants is compressing feedstock pricing power while simultaneously squeezing margin buffers for mid-scale compounders lacking captive production. This utilization dynamic forces suppliers toward volume-based hospital contracting and accelerates consolidation among distributors unable to absorb logistics cost volatility under provincial quota systems.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with Beijing and Shanghai municipal health commissions extracting 15-25% price concessions on multi-year sanitizer supply agreements above 500,000 liter annual volumes. Pricing stratifies across GB 27951-certified hospital grade, commercial institutional grade, and retail consumer tiers, with certification compliance costs driving the primary wedge between tiers. Cost compression in the retail channel is intensifying because e-commerce logistics constraints on ethanol-based hazardous material shipping force sellers to absorb last-mile premiums. Household consumers in tier-one cities show highest price sensitivity, while pediatric and oncology wards maintain near-zero elasticity due to zero-tolerance infection protocols.
Supply Chain Analysis
Export-control regime restrictions on dual-use ethanol purification technology limit access to pharmaceutical-grade feedstock processing equipment for non-domestic producers, reinforcing China's self-sufficiency trajectory in hospital-grade sanitizer manufacturing. Industrial alcohol supply concentrates in Shandong, Jiangsu, and Hebei provinces, with corn and cassava feedstock dependencies tethered to agricultural policy cycles. Single-source vulnerability runs through Shandong's fermentation corridor, where provincial quota systems constrain national distribution flexibility. Distribution runs through state-directed procurement platforms in tier-one cities, layered over traditional chemical distributor networks in western provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a post-pandemic inventory destocking cycle, with cyclical recovery justified by SAMR's tightened GB 27951-2021 enforcement timelines extending product development cycles and freezing speculative capacity additions.
For Market Incumbents: Pre-empt margin erosion in retail channels by locking multi-year ethanol supply agreements with Shandong and Hebei fermentation facilities before agricultural policy shifts tighten feedstock access. Defend hospital procurement positions through accelerated GB 27951-2021 stability documentation investments, as Beijing and Shanghai municipal platforms are disqualifying suppliers with incomplete 24-month retention data. Vertical integration into bioethanol from agricultural residue offers dual carbon compliance leverage in state tenders. For New Entrants and Emerging Players: Establish a beachhead in Sichuan and Shaanxi healthcare networks, where hospital-grade formulation supply gaps persist and first-mover GB certification yields procurement preference before incumbent distribution networks extend westward. Target educational institution foam dispenser contracts in Chongqing's municipal rail expansion zones, where IoT-enabled consumption tracking hardware integration creates subscription revenue stickiness. Lead with green packaging mandates compliance—refillable aluminum cartridges and concentrated tablet formats—to differentiate against legacy PET bottle incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward domestic chemical conglomerates with backward integration into alcohol feedstocks and verified SAMR registration pipelines, as these assets command premium valuations under tightening local content preferences. Long-term viability hinges on circular supply chain credentials aligning with dual carbon procurement tender requirements. Watch SAMR registration timeline compression as the inflection signal—accelerated approval pathways would unlock trapped working capital and trigger re-rating of development-stage compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bioethanol Feedstock | Dual carbon compliance unlocks preferential access to state-directed hospital procurement tenders under MEE directives. |
| GB 27951-2021 Certification Investment | 24-month stability documentation qualifies suppliers for Beijing and Shanghai municipal centralized purchasing platforms. |
| Dispenser System IoT Integration | Consumption tracking hardware enables subscription revenue models in high-traffic transportation infrastructure mandates. |
| Green Packaging Transition | Refillable aluminum cartridges meet MEE plastic reduction directives while commanding premium positioning in tier-one cities. |
| Western Province Distribution Buildout | Sichuan and Shaanxi healthcare network penetration captures first-mover advantage before incumbent logistics networks extend. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with plant managers at ethanol fermentation facilities, procurement leads at municipal health commissions, GB standard compliance officers, and hospital purchasing committee directors; and secondary validation through SAMR disinfectant registration databases, NMPA therapeutic indication filings, customs ethanol trade records, and provincial agricultural residue program disclosures. Bottom-up volume triangulation across product format, packaging type, distribution channel, and end-user segments was cross-checked against top-down macro consumption estimates.
Forecast inputs incorporated ethanol feedstock cost trajectories, SAMR registration timeline assumptions, municipal infrastructure mandate rollout schedules, and dual carbon procurement tender participation rates across the projection horizon. Segmentation modeling spanned product format migration from gel to foam, packaging transition from single-use plastics to refillable systems, channel shift from layered distributors to direct hospital contracting, and end-user expansion from tier-one healthcare facilities to western province networks. CAGRs were derived from slope analysis of historical procurement volume trends adjusted for regulatory inflection points.
Macroeconomic conditions sit as an overlay; deviation in corn and cassava agricultural commodity prices, ethanol feedstock tariff regimes, or provincial logistics quota enforcement would shift the trajectory. Forecasts assume stable SAMR regulatory intensity and continued municipal infrastructure mandate expansion. Material shifts in GB standard revision timelines or dual carbon policy acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Explosion Proof Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Bicycle Safety Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Radiation Protection Cabins Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Respiratory Protective Equipment (RPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Padlock Seals Market
Safety Equipment and Personal Protective Equipment (PPE)
Traffic Baton Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Eyewear Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Isolation Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Cryogenic PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Supplementary Protectors Market
Safety Equipment and Personal Protective Equipment (PPE)
Head Guards Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Collision Avoidance System Market