
 Barricade Tape Market | 2026-2036
Barricade Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Barricade Tape Market Analysis
Digital printing integration is rewriting how barricade tape carries variable messaging, serialized tracking codes, and site-specific hazard symbols directly at the point of manufacture. 3M Company leverages its materials science portfolio to embed retroreflective beads into polyethylene substrates for nighttime visibility. Berry Global, Inc. sustains cost leadership through blown-film extrusion scale across multiple North American plants. tesa SE differentiates with adhesive-backed barrier formats that adhere to rough concrete and asphalt surfaces without flagging or edge lift.
Barricade tape denotes non-adhesive or lightly adhesive polyethylene, PVC, vinyl, or paper strips manufactured in vivid colors with printed warning legends, typically two to six mils thick, engineered to cordon hazards, direct pedestrian flow, and demarcate restricted zones in industrial and public settings. Polyethylene dominates volume due to its tear resistance and outdoor weatherability, while vinyl commands premium placement in chemical exposure environments where substrate integrity is paramount. Application splits reveal construction as the mature revenue base, with event management representing the fastest-growing demand pool as temporary venue operators standardize crowd control protocols.
OSHA's workplace safety standards and the Federal Highway Administration's Manual on Uniform Traffic Control Devices govern color conventions, reflectivity minimums, and placement density for barricade tape deployed in US work zones. State-level departments of transportation in California, Texas, and Florida enforce supplemental specifications that exceed federal baselines, creating a layered compliance environment for manufacturers. Stakeholders must monitor evolving MUTCD revisions and state DOT addenda to anticipate specification shifts that could obsolete existing inventory or open qualification pathways for upgraded formulations.
Market Dynamics
OSHA's updated workplace safety signage requirements and the Federal Highway Administration's Manual on Uniform Traffic Control Devices revisions are forcing contractors and municipal agencies toward compliant reflective and color-coded tape formats, reshaping procurement specifications across construction and infrastructure sectors.
Growth Catalysts
- Hurricane Recovery Infrastructure:Municipal infrastructure agencies across Florida, Louisiana, and Texas are expanding procurement of high-visibility barrier systems for flood mitigation and roadway reconstruction projects following successive storm seasons.
- OSHA Compliance Mandates:Updated workplace safety signage requirements are pushing industrial contractors toward reflective polyethylene substrates that meet federal visibility standards in manufacturing and warehouse environments.
- Digital Printing Convergence:Variable messaging capabilities and serialized tracking codes embedded at the point of manufacture are enabling site-specific hazard communication without inventory proliferation.
Market Restraints
- Petrochemical Feedstock Volatility:Polyethylene substrate costs fluctuate with crude oil derivatives, compressing margin stability for blown-film extrusion operations concentrated in the American Southeast.
- Single-Source Concentration:Retroreflective bead supply for premium tapes concentrates among limited specialty chemical processors, creating qualification bottlenecks for manufacturers seeking MUTCD-compliant formulations.
- Vinyl Substitution Ceiling:Premium vinyl substrates face displacement pressure from advanced polyethylene blends in chemical exposure applications where substrate integrity requirements are tightening.
Strategic Opportunities
- Event Management Standardization:Temporary venue operators in California and Nevada are formalizing crowd control protocols, creating demand for serialized, color-coded barrier systems with integrated access control compatibility.
- State DOT Addenda Exceeding Federal Baselines:California, Texas, and Florida departments of transportation are enforcing supplemental specifications that open qualification pathways for upgraded reflective formulations.
- Adhesive-Backed Format Expansion:Rough concrete and asphalt adhesion capabilities are penetrating industrial maintenance applications where traditional non-adhesive formats previously dominated.
Industry Challenges
- Multi-Jurisdictional Certification Complexity:Layered compliance across federal MUTCD, OSHA standards, and state DOT addenda extends product qualification timelines and fragments inventory requirements.
- Legacy Equipment Retrofit Costs:Digital printing integration demands capital expenditure on variable-data capable extrusion lines, straining mid-scale manufacturers with fixed asset bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barricade Tape Market |
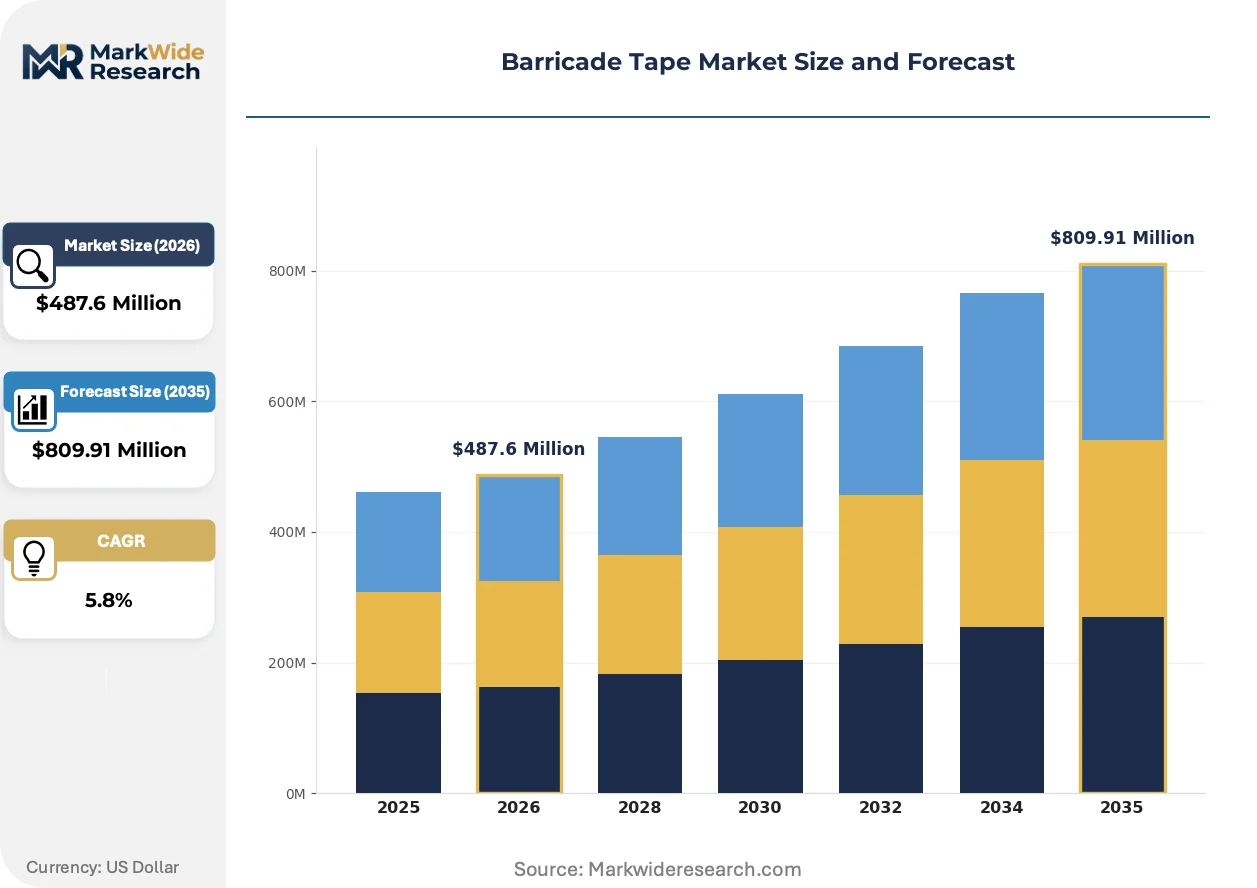
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Polyethylene, PVC, Vinyl, Paper Color: Red, Yellow, Orange, Black Application: Construction, Event Management, Hazard Identification, Traffic Control Thickness: 2 Mil, 3 Mil, 4 Mil, 6 Mil |
| Companies Covered | Shurtape Technologies, LLC, Nitto Denko Corporation, 3M Company, Henkel AG & Co. KGaA, Berry Global, Inc., Avery Dennison Corporation, tesa SE, Scapa Group plc, Intertape Polymer Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barricade Tape Market Emerging Trajectories
Digital fabrication methods and regulatory precision are compressing traditional manufacturing cycles while expanding functional capabilities beyond passive hazard marking toward active site management integration.
Thermal transfer and inkjet systems embedded directly into blown-film extrusion lines are collapsing the distinction between stock and custom barricade tape production. Municipal procurement offices in Texas and Florida are adopting digitally serialized formats for asset tracking across multi-site infrastructure portfolios. This compression eliminates minimum order quantity constraints that previously segmented large agency buyers from specialty industrial users.
REACH-compliant phthalate-free formulations are displacing legacy plasticizers in vinyl substrates destined for European export and multinational contractor specifications. Industrial hygiene officers in chemical processing facilities are demanding substrate integrity certifications that exceed baseline OSHA requirements. Manufacturers with ECHA-registered material safety data sheets are capturing specification lock-in from safety-conscious procurement committees.
Consolidated distributor agreements are replacing fragmented jobber networks as primary supply channels for construction contractors. Large rental equipment providers are bundling barrier systems with temporary fencing and lighting packages, compressing standalone tape margins while expanding volume throughput. This channel concentration is most visible in the American Southeast, where hurricane recovery project managers prioritize single-source logistics over product-level sourcing optimization.
Barricade Tape Market Segmentation
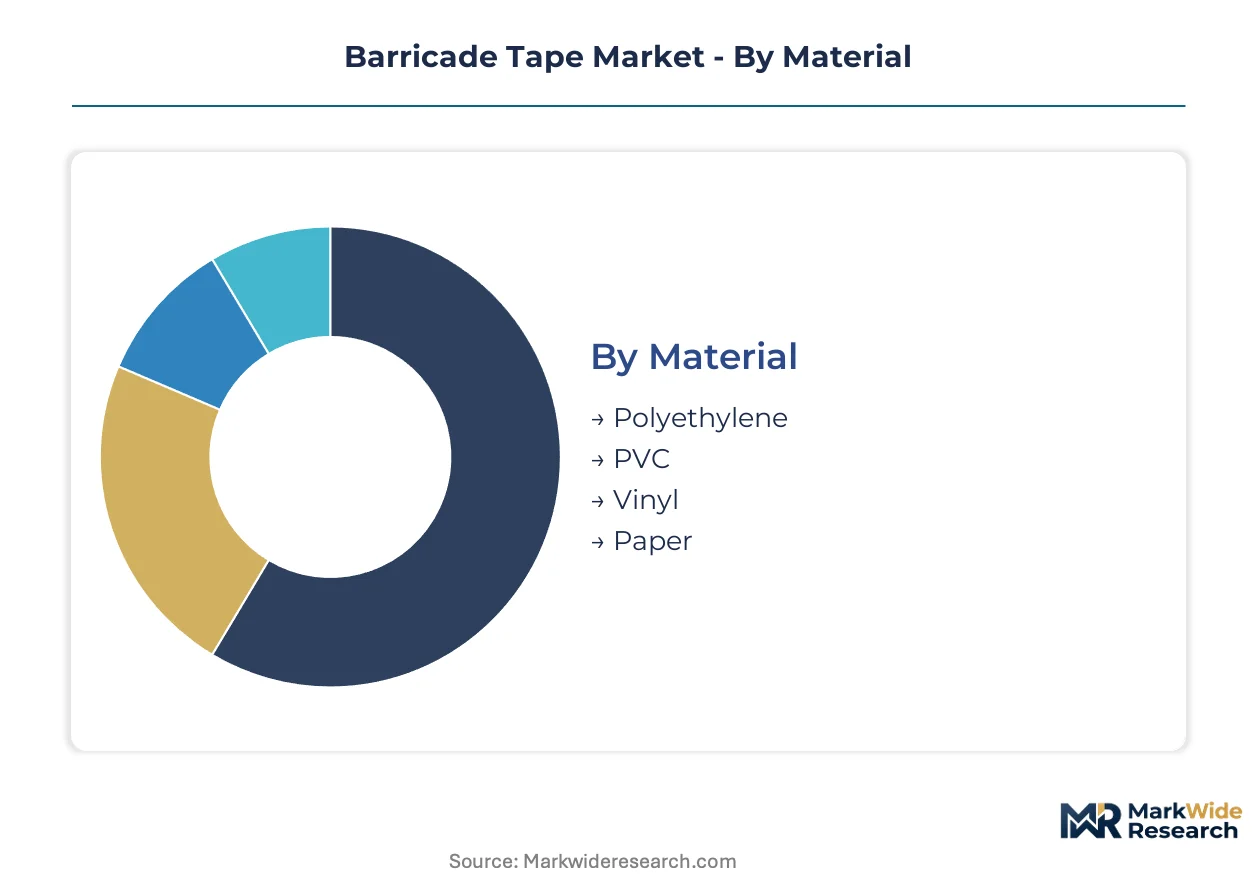
Barricade tape manufacturers configure production lines around material chemistry, visual specifications, and deployment environments. Procurement officers select formats based on substrate durability, regulatory color mandates, and site-specific hazard communication requirements.
Material:
Mature commodity substrates dominate volume throughput while specialty formulations capture premium placement in demanding environments.
- Polyethylene:Blown-film extrusion produces tear-resistant substrates with outdoor weatherability across temperature extremes. Hurricane recovery contractors in Florida and Louisiana specify polyethylene for flood zone perimeter marking where prolonged UV exposure and moisture saturation occur.
- PVC:Plasticized formulations deliver substrate integrity in chemical processing environments where solvent contact degrades standard polymers. Industrial hygiene officers in Texas petrochemical facilities mandate PVC for containment zone demarcation.
- Vinyl:Premium substrate commanding specification lock-in from multinational contractors requiring REACH-compliant phthalate-free formulations for European export.
- Paper:Short-duration indoor applications where moisture exposure is absent and cost minimization overrides durability requirements.
Polyethylene handles the majority of throughput; vinyl is the fastest mover on share.
Color:
Regulatory color conventions determine procurement specifications across federal and state jurisdictions with minimal deviation tolerance.
- Yellow:OSHA-mandated caution designation for physical hazards and trip risks in manufacturing and warehouse environments. Federal workplace safety inspectors enforce consistent application.
- Orange:Federal Highway Administration specifies orange for temporary traffic control devices in roadway work zones. State DOT addenda in California and Texas reinforce this convention with supplemental reflectivity requirements.
- Red:Fire safety equipment marking and immediate danger zones where prohibition of entry is absolute.
- Black:Combined with yellow for radiation hazard and biohazard applications in laboratory and healthcare settings.
Yellow satisfies the bulk of industrial compliance demand; orange climbs the fastest as infrastructure spending accelerates.
Application:
End-use concentration splits between mature construction procurement and emerging event management standardization.
- Construction:Mature revenue base driven by federal infrastructure spending and municipal roadway maintenance contracts. Contractors bundle barrier systems with temporary fencing and lighting packages.
- Event Management:Temporary venue operators in California and Nevada formalize crowd control protocols with serialized, color-coded systems. Music festival and sporting event producers drive specification evolution.
- Hazard Identification:Industrial facilities deploy chemical-specific legends and pictograms for confined space and electrical hazard zones.
- Traffic Control:Manual on Uniform Traffic Control Devices compliance mandates retroreflective formats for nighttime visibility in work zone applications.
Construction absorbs the largest procurement volumes; event management expands most quickly as venue operators professionalize temporary infrastructure.
Thickness:
Mil specification determines tear resistance, wind load tolerance, and reuse potential across deployment scenarios.
- 2 Mil:Lightweight format for short-duration indoor applications with minimal mechanical stress and controlled environmental conditions.
- 3 Mil:Balanced specification for standard commercial construction where moderate durability meets cost efficiency targets.
- 4 Mil:Enhanced tear resistance for outdoor construction sites and extended deployment cycles where wind exposure and handling stress accumulate.
- 6 Mil:Maximum durability for highway work zones, hurricane recovery perimeters, and heavy equipment operations where substrate failure creates liability exposure.
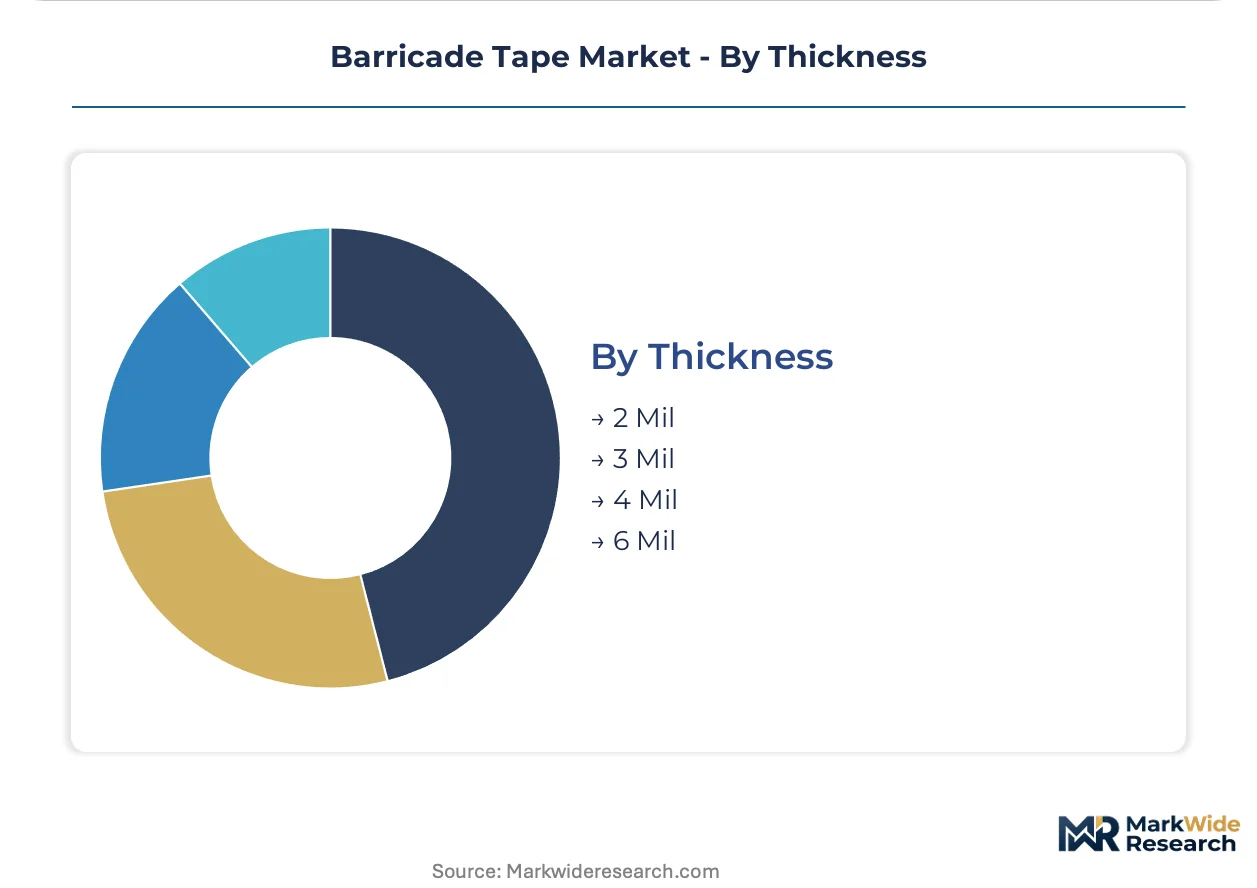
3 Mil and 4 Mil formats split the majority of procurement; 6 Mil gains share fastest as infrastructure projects extend duration and severity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexican blown-film extrusion facilities supply polyethylene substrates to hurricane recovery contractors throughout the American Southeast, establishing a cross-border procurement corridor that channels volume into Texas and Florida infrastructure projects.
United States
OSHA workplace safety signage mandates and Federal Highway Administration MUTCD revisions drive specification upgrades across construction and industrial sectors. State DOT addenda in California, Texas, and Florida enforce reflectivity minimums that exceed federal baselines. Municipal agencies in Miami-Dade County and Harris County are expanding high-visibility barrier procurement for flood mitigation perimeters.
Germany
REACH-compliant phthalate-free vinyl formulations command specification lock-in from multinational contractors serving European export markets. ECHA-registered material safety data sheets are becoming mandatory for industrial hygiene officers in chemical processing facilities. Manufacturing clusters in North Rhine-Westphalia are retrofitting extrusion lines for variable-data digital printing capabilities.
China
Domestic infrastructure spending and Belt and Road construction exports sustain polyethylene substrate demand at scale. GB standards for workplace safety signage are converging toward international color conventions. Production gravity in Zhejiang and Jiangsu provinces is shifting toward retroreflective bead integration for nighttime visibility applications.
India
BIS certification requirements for industrial safety materials are tightening procurement specifications across manufacturing and warehouse environments. State-level urban development authorities in Maharashtra and Gujarat are standardizing crowd control protocols for temporary infrastructure. Chemical processing facilities in Vadodara and Mumbai are mandating substrate integrity certifications beyond baseline workplace safety requirements.
Brazil
ANVISA regulatory alignment with international hazard communication standards is elevating color-coded barrier specifications in healthcare and laboratory settings. Petrobras maintenance contractors are driving demand for chemical-resistant vinyl formats in refinery and offshore applications. Industrial clusters in São Paulo state are adopting serialized tracking systems for multi-site asset management.
Barricade Tape Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: multinational materials science conglomerates with retroreflective integration expertise, regional blown-film specialists with scale-driven cost positions, and adhesive technology providers with surface-bonding format differentiation. Strategic moves center on digital printing line retrofits for variable-data production and distributor consolidation to capture bundled temporary infrastructure procurement.
Among diversified materials science conglomerates, 3M Company and Berry Global, Inc. occupy positions that exemplify the premium-scale archetype, while tesa SE represents the adhesive-backed format specialization vector. These three anchors demonstrate how competitive positioning stratifies across substrate chemistry, manufacturing scale, and surface-bonding technology domains.
| Leading Market Players |
|---|
| Shurtape Technologies, LLC |
| Nitto Denko Corporation |
| 3M Company |
| Henkel AG & Co. KGaA |
| Berry Global, Inc. |
| Avery Dennison Corporation |
| tesa SE |
| Scapa Group plc |
| Intertape Polymer Group, Inc. |
| Others |
Supply Flow & Price Mechanics
Retroreflective bead supply concentrates among limited specialty chemical processors in Germany and Japan, concentrating margin pools with tape manufacturers holding qualified supplier relationships and MUTCD-compliant formulations. This upstream bottleneck forces mid-tier extrusion operators toward commodity polyethylene substrates while premium pricing accrues to integrated players with captive reflective technology.
Pricing Analysis
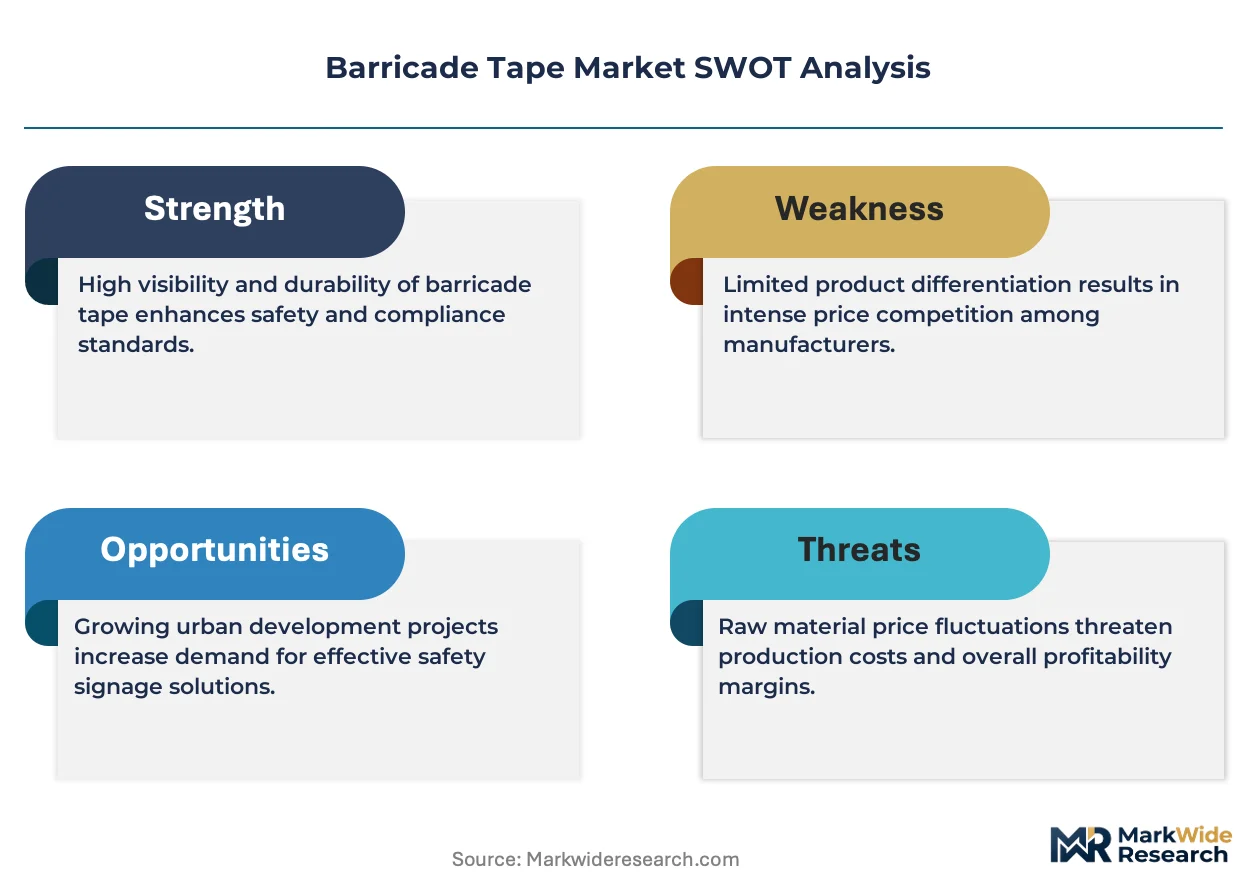
Legacy non-reflective polyethylene formats, current retroreflective premium grades, and emerging digital-print customizable tiers define the three-generation pricing spread. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and reflectivity performance rather than raw substrate cost alone. Price differentiation hinges on MUTCD compliance verification and volume procurement scale, with municipal agencies least sensitive and mid-scale construction contractors most responsive to per-roll fluctuations. Cost compression in standard-grade polyethylene is intensifying because blown-film capacity expansion across the American Southeast outpaces hurricane recovery demand growth.
Supply Chain Analysis
Blown-film extrusion capacity concentrates with Berry Global and regional specialists across Mexico, the American Southeast, and coastal China. Raw material flows draw from petrochemical feedstocks, retroreflective glass bead imports, and REACH-compliant phthalate-free plasticizers. Single-source vulnerability in specialty bead supply creates qualification bottlenecks for manufacturers seeking federal work zone certification. Distribution runs through consolidated rental equipment providers and industrial distributors replacing fragmented jobber networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Serialized digital printing and site-specific hazard communication services expand faster than substrate hardware, creating recurring-revenue attach opportunities beyond per-roll tape sales. Equipment bundling and asset tracking subscriptions now outpace standalone product growth in municipal procurement.
For Market Incumbents: Build regulatory certification moats through MUTCD pre-qualification and state DOT addenda compliance ahead of specification shifts. Deepen backward integration into retroreflective bead supply to defend against single-source concentration risk. Expand digital printing line capacity in Texas and Florida to capture hurricane recovery project demand for serialized formats. Channel control through exclusive rental equipment partnerships represents the critical lever for volume retention. For New Entrants and Emerging Players: Mid-market event management operators in California and Nevada represent the most penetrable entry point given crowd control protocol standardization and limited incumbent service bundling. Adhesive-backed formats for rough concrete and asphalt industrial maintenance applications offer specification differentiation without competing on extrusion scale. Target direct-to-venue sales bypassing consolidated distributor networks that favor established volume players. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional blown-film specialists lacking digital printing retrofit capital. Long-term viability favors platforms with variable-data production capability and multi-jurisdictional certification databases. The inflection signal to monitor is state DOT adoption of serialized tracking mandates that would obsolete non-digital inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Printing Line Retrofit | Variable-data capability eliminates minimum order constraints for municipal procurement offices. |
| Backward Integration into Reflective Beads | Captive bead supply secures MUTCD qualification timelines against specialty chemical bottlenecks. |
| Rental Equipment Bundling Partnership | Single-source logistics preference in hurricane recovery regions compresses standalone tape margins. |
| REACH-Compliant Formulation Registration | ECHA-registered data sheets lock in multinational contractor specifications for European export. |
| Serialized Asset Tracking Platform | Multi-site infrastructure portfolio management creates recurring service revenue beyond hardware sales. |
Methodological Framework
Two parallel data streams informed the analysis: primary engagement with municipal procurement officers, construction project managers, industrial safety coordinators, and rental equipment providers; and secondary validation through OSHA enforcement records, FHWA MUTCD revision documentation, state DOT specification addenda, and SEC filings from listed materials companies. Bottom-up volume estimates from extrusion capacity and top-down value reconstruction from procurement contract values were triangulated against trade flow data.
Forecast inputs include material chemistry splits, color specification mandates, thickness grade adoption curves, and application segment evolution across the projection horizon. Segmentation dimensions modeled encompass substrate type, regulatory color tier, mil specification, and end-use deployment environment. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion schedules. Industry-specific inputs incorporate hurricane recovery project pipelines and OSHA compliance enforcement intensity.
Practitioners should monitor MUTCD revision drafts, state DOT specification addenda releases, and retroreflective bead supplier qualification changes for early signals of forecast deviation. Quarterly review of municipal procurement contract awards and rental equipment provider bundling announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Isolation Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Booster Seat Type Child Safety Seats Market
Safety Equipment and Personal Protective Equipment (PPE)
Premium High Security Doors Market
Safety Equipment and Personal Protective Equipment (PPE)
Chemical Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
South America Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Machine Safeguarding Solution Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Respirator Filter Market
Safety Equipment and Personal Protective Equipment (PPE)
Surface Protection Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Protection System Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Hearing Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Solutions Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Analyzers Market
Safety Equipment and Personal Protective Equipment (PPE)
Intrinsically Safe Lighting Market
Safety Equipment and Personal Protective Equipment (PPE)
Body Armor Accessories Market