
 Reflective Air Packaging Market | 2026-2036
Reflective Air Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Reflective Air Packaging Market Analytics
Pharmaceutical cold chain logistics is pivoting toward advanced thermal protection as biologics and vaccine distribution networks expand temperature-sensitive shipping requirements. Sealed Air Corporation leverages its extensive film extrusion capabilities to dominate North American pharmaceutical packaging corridors. Pregis Corporation sustains competitive positioning through specialized inflatable cushioning systems tailored to precision electronics. Amcor plc anchors its presence across European pharmaceutical hubs with multilayer barrier film expertise.
Reflective air packaging combines metallized film laminates with trapped air cellular structures to create thermal resistance barriers with R-values typically exceeding standard polymer foams. Manufacturers bond aluminum foil or metallized polyethylene terephthalate to polyethylene bubble substrates through adhesive lamination or extrusion coating processes, producing lightweight envelopes that reflect radiant heat while convective air pockets slow conductive transfer. Bags and pouches command the largest volume share as standardized formats align with automated fulfillment lines in e-commerce distribution centers. Aluminum foil laminates capture premium margin pools where pharmaceutical cold chain compliance demands sub-ambient temperature stability across extended transit durations. Third-party logistics channels represent the fastest-growing distribution pathway as outsourced fulfillment operators consolidate packaging procurement across multi-tenant warehouse networks.
The FDA enforces strict temperature documentation protocols for pharmaceutical distribution under current Good Distribution Practice guidelines, compelling shippers to validate insulating performance across defined thermal profiles. REACH compliance within Europe restricts certain phthalate plasticizers in flexible packaging films, redirecting formulation development toward compliant polymer alternatives. Stakeholders must monitor evolving extended producer responsibility frameworks across multiple jurisdictions, as packaging waste directives increasingly assign end-of-life accountability to material suppliers and brand owners rather than downstream disposers.
Market Dynamics
The EU F-Gas Regulation is systematically dismantling hydrofluorocarbon-dependent thermal insulation alternatives, forcing cold chain logistics operators toward air-cell metallized laminates as the compliant default. This regulatory compression is redrawing competitive boundaries across pharmaceutical distribution networks.
Growth Catalysts
- Biologics cold chain expansion:Temperature-sensitive biopharmaceuticals now constitute the dominant pharmaceutical pipeline category, mandating validated thermal protection for 2-8°C and -20°C distribution lanes.
- E-commerce perishable fulfillment:Fresh grocery and meal-kit delivery networks are retrofitting automated packaging lines with standardized reflective pouch formats to reduce thermal excursion rates.
- REACH-compliant film innovation:European formulators have accelerated phthalate-free polyethylene extrusion capabilities, unlocking pharmaceutical-grade certification for regional suppliers previously locked out of compliance-driven procurement.
Market Restraints
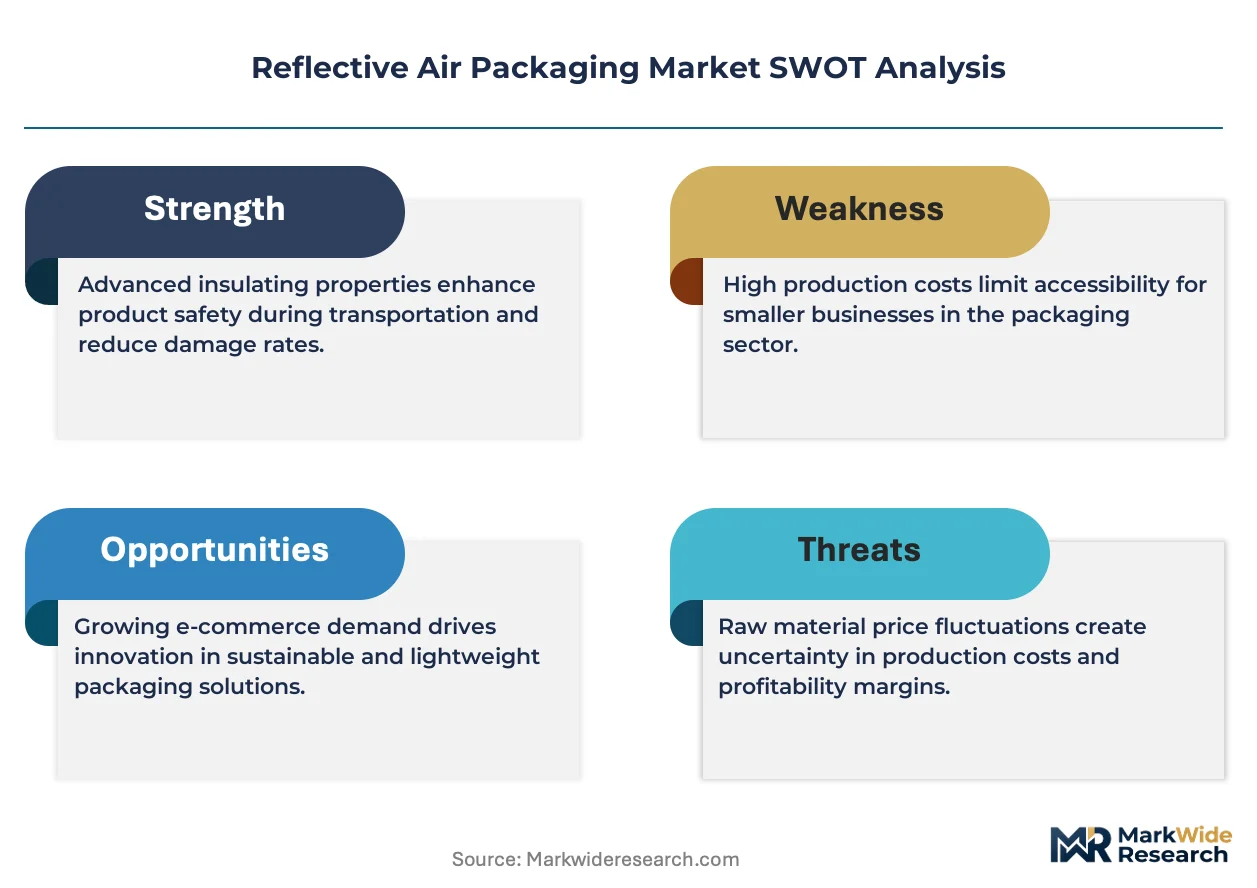
- Aluminum foil supply concentration:Primary foil rolling capacity clusters in Chinese and Russian smelter networks, exposing laminators to tariff volatility and energy cost pass-throughs.
- Metallized PET performance ceiling:Oxygen transmission rates in vapor-deposited barriers remain 3-5x higher than foil laminates, disqualifying the substrate from ultra-low-temperature vaccine distribution.
- Extended producer responsibility mandates:Germany's Packaging Act and France's AGEC law assign end-of-life recycling accountability to brand owners, compressing margins on single-use thermal envelopes.
Strategic Opportunities
- Indian pharmaceutical export corridors:CDSCO-licensed cold chain infrastructure investment is outpacing domestic reflective packaging supply, creating import substitution windows for certified regional producers.
- Reusable thermal shipper convergence:Integration of RFID temperature loggers with metallized bubble formats enables returnable asset tracking, displacing single-use expanded polystyrene in high-value electronics lanes.
- EU Green Deal procurement incentives:Public health system tendering now weights circular packaging credentials, advantaging suppliers with verified recycled content in metallized film substrates.
Industry Challenges
- Adhesive lamination technician scarcity:Precision control of polyethylene extrusion coating thickness requires specialized extruder operators, with training pipelines failing to match capacity expansion timelines.
- Thermal validation protocol complexity:ISTA 7E and ASTM D3103 qualification cycles extend 12-18 months, delaying new product commercialization and freezing out speculative R&D investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reflective Air Packaging Market |
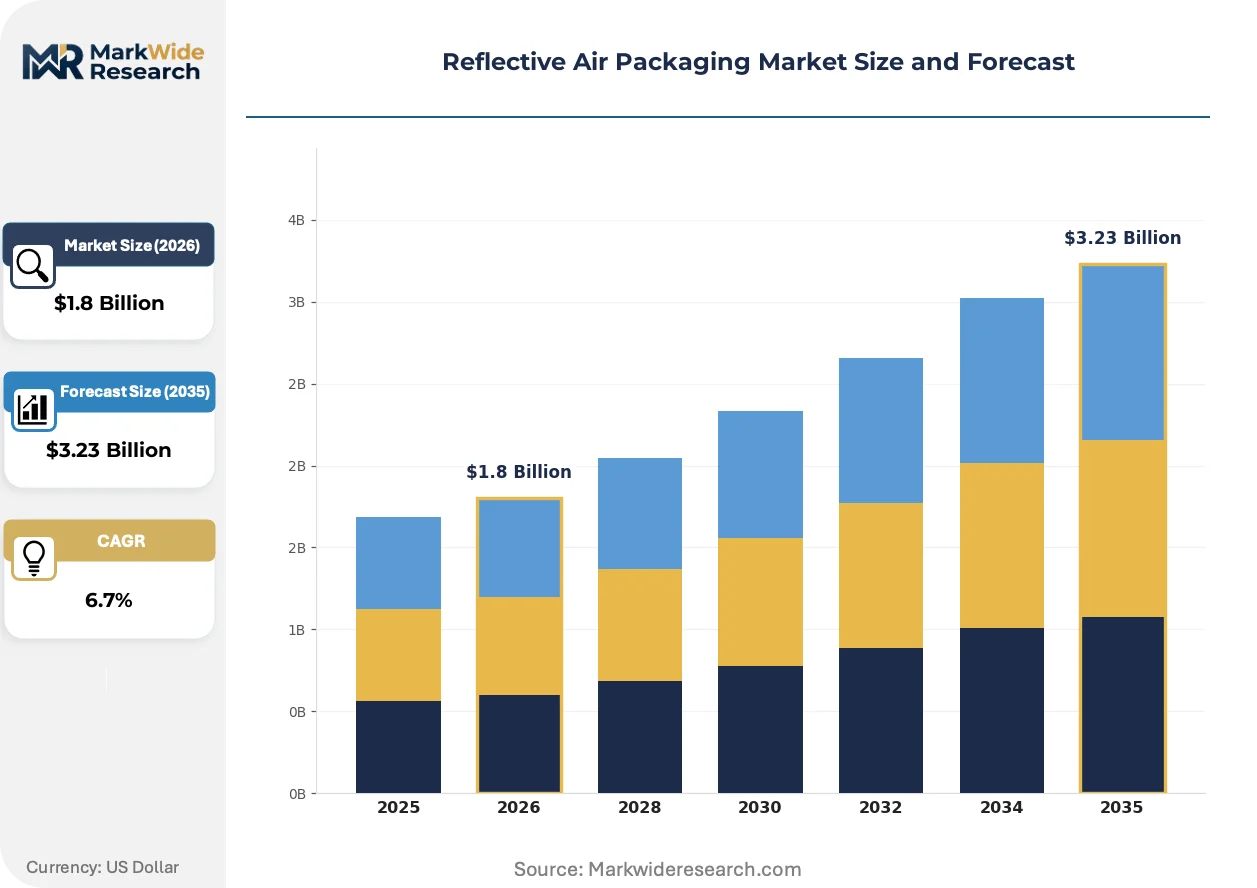
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Pouches, Wraps, Sheets Material: Polyethylene, Polypropylene, Aluminum Foil, Bubble Wrap End User: Food & Beverage, Electronics, Cosmetics, Pharmaceuticals Distribution Channel: Online Retail, Offline Retail, Direct Sales, Third-Party Logistics |
| Companies Covered | Sealed Air Corporation, Pregis Corporation, Sonoco Products Company, International Paper Company, Winpak Ltd, Amcor plc, Mondi plc, Smurfit Kappa Group, DS Smith, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reflective Air Packaging Market Evolving Landscape
Active barrier engineering is displacing passive thermal mass as the dominant design philosophy, with manufacturers embedding phase-change materials directly into air-cell matrices rather than relying on external gel packs. This convergence is compressing packout weight and extending validated duration windows.
Multi-layer coextrusion with embedded phase-change microcapsules is electrifying thermal performance benchmarks in pharmaceutical distribution. Vaccine logistics operators in Germany and Switzerland are piloting these formats for 96-hour ambient temperature stability. The technology is electrifying competitive differentiation as validated duration becomes the primary procurement criterion over unit cost.
The EU F-Gas Regulation's 2030 phase-down schedule is accelerating refrigerant-dependent cold box obsolescence across European pharmaceutical corridors. Logistics providers are retrofitting last-mile fleets with passive reflective air systems to eliminate compressor maintenance and compliance documentation. Temperature-sensitive generics distributors in Italy and Spain face the steepest adaptation curves as their thin-margin models absorb packaging cost inflation.
Consolidated procurement through third-party logistics platforms is fragmenting direct manufacturer relationships. Amazon Pharmacy and specialized healthcare 3PLs now specify thermal packaging standards across multi-tenant warehouse networks, displacing individual pharmaceutical brand owner discretion. This concentration is most visible in Dutch and Belgian distribution hubs serving pan-European e-pharmacy fulfillment.
Reflective Air Packaging Market Segmentation
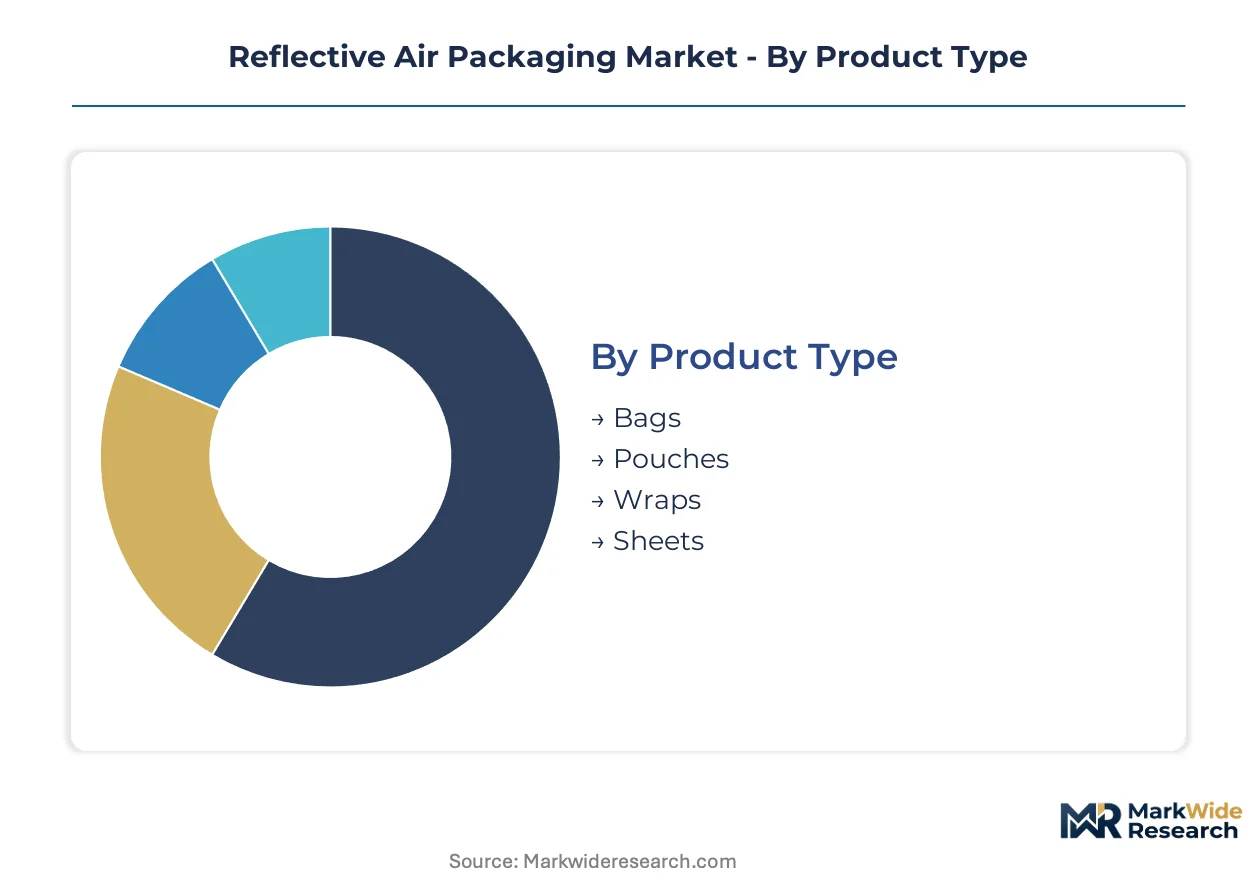
Reflective air packaging segmentation reveals how material choices and distribution pathways align with divergent thermal performance requirements. Product formats and end-use specifications create distinct margin tiers that reshape procurement patterns across pharmaceutical and e-commerce corridors.
Product Type:
Supply concentration in automated fulfillment equipment favors standardized pouch and bag formats that integrate with high-velocity packaging lines.
- Bags:Metallized film laminates bonded to polyethylene bubble substrates create self-sealing thermal envelopes with R-values exceeding conventional foams. Pharmaceutical distributors in Germany specify validated bag formats for 2-8°C biologics lanes where ISTA 7E qualification is mandatory.
- Pouches:Pre-formed reflective pouches with gusseted bottoms accommodate irregular payloads in meal-kit and fresh grocery fulfillment. E-commerce operators in the Netherlands retrofit automated lines with pouch dispensers to compress packout time per order.
- Wraps:Continuous roll formats serve custom packout operations in precision electronics where device dimensions vary significantly.
- Sheets:Flat laminate panels interleave with corrugated dunnage in multi-layer thermal shipper assemblies for ultra-low-temperature vaccine distribution.
Today's leader: Bags. Tomorrow's challenger: Pouches.
Material:
Cost tiers separate commodity polymer substrates from certified pharmaceutical-grade laminates with full traceability documentation.
- Aluminum Foil:Seven-micron annealed foil laminates deliver oxygen transmission rates below 0.01 cc/m²/day, qualifying for ultra-low-temperature vaccine corridors. REACH-compliant foil sourcing from European rolling mills commands premium positioning as Chinese supply faces tariff exposure.
- Polyethylene:Linear low-density polyethylene extrusion coatings dominate volume production for standard e-commerce thermal protection. Phthalate-free formulations certified under EU packaging directives unlock pharmaceutical procurement access for regional converters.
- Polypropylene:Biaxially oriented polypropylene films provide moisture barrier layers in multilayer laminates for tropical climate distribution.
- Bubble Wrap:Coextruded polyethylene bubble substrates with diameters ranging from 10mm to 25mm create trapped air matrices with tunable thermal resistance.
Aluminum foil commands premium pricing. Polyethylene drives volume scale.
End User:
Application-specific validation protocols segment demand by regulatory intensity and thermal excursion tolerance.
- Pharmaceuticals:Cold chain compliance under FDA and EMA guidelines mandates documented thermal validation for 2-8°C and -20°C distribution lanes. Biologics manufacturers in Switzerland and Germany specify reflective air systems with embedded phase-change materials for 96-hour ambient stability.
- Electronics:Precision semiconductor and medical device shipments require moisture-vapor transmission barriers alongside thermal protection. Cleanroom-compatible formats with low-outgassing adhesives serve high-value electronics lanes in Taiwan and South Korea.
- Food & Beverage:Meal-kit and fresh protein delivery networks specify standardized reflective pouches to reduce spoilage rates in last-mile distribution.
- Cosmetics:Temperature-sensitive active ingredients in premium skincare drive demand for lightweight thermal protection in direct-to-consumer fulfillment.
Pharmaceuticals anchor margin pools. Electronics expand fastest.
Distribution Channel:
Customer type determines whether procurement flows through consolidated 3PL platforms or direct manufacturer relationships.
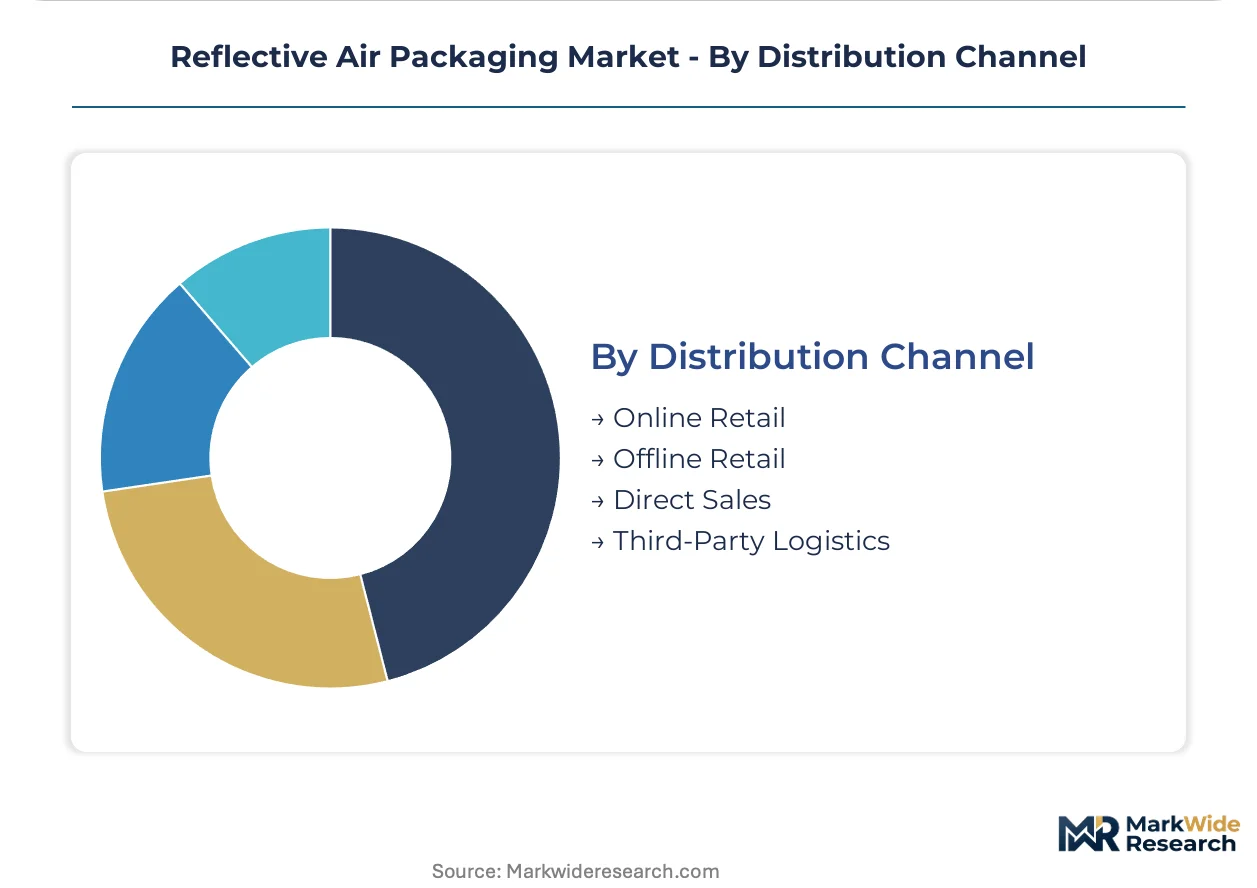
- Third-Party Logistics:Consolidated procurement through healthcare and e-commerce 3PLs now specifies thermal packaging standards across multi-tenant warehouse networks. Amazon Pharmacy and specialized healthcare logistics operators in Belgium and the Netherlands displace individual brand owner discretion with centralized standards.
- Direct Sales:Large pharmaceutical manufacturers and electronics OEMs maintain direct contracts with laminators for customized thermal shipper development. Direct relationships enable co-development of RFID-integrated reusable formats with embedded temperature loggers.
- Online Retail:Marketplace platforms aggregate small-lot procurement for emerging meal-kit brands and specialty pharmaceutical distributors.
- Offline Retail:Industrial supply distributors serve maintenance and repair operations with standard bag and wrap formats.
Third-party logistics concentrate volume. Direct sales capture customization value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's pharmaceutical export corridors anchor demand concentration for validated thermal packaging systems. Distribution networks across the country retrofit cold chain infrastructure to accommodate biologics shipment volumes. The EU F-Gas Regulation accelerates this transition by eliminating hydrofluorocarbon-dependent alternatives.
Germany
Pharmaceutical exports from Baden-Württemberg and Bavaria drive specification of ISTA 7E-qualified reflective pouches for 2-8°C distribution lanes. The country's Packaging Act assigns extended producer responsibility to brand owners, compressing margins on single-use thermal formats. Precision electronics manufacturing around Stuttgart demands cleanroom-compatible metallized laminates with low-outgassing adhesive systems.
United States
FDA enforcement of current Good Distribution Practice guidelines compels shippers to document thermal validation across defined temperature profiles. The Inflation Reduction Act's domestic manufacturing incentives support film extrusion capacity expansion in Midwest industrial corridors. Cold chain logistics operators in the Greater Boston biotech cluster pilot RFID-integrated reusable thermal shippers for high-value biologics.
India
CDSCO-licensed cold chain infrastructure investment outpaces domestic reflective packaging supply, creating import substitution opportunities for certified regional producers. The country's PLI scheme for pharmaceuticals incentivizes temperature-controlled distribution network upgrades. Export corridors from Maharashtra and Gujarat to European and North American markets require REACH-compliant metallized film laminates.
Switzerland
Swissmedic oversight of biologics distribution mandates validated thermal protection for temperature-sensitive therapeutics. The country's precision manufacturing base around Basel and Zurich specifies high-barrier foil laminates for ultra-low-temperature vaccine logistics. Logistics operators pilot multilayer coextrusion formats with embedded phase-change microcapsules for 96-hour ambient stability.
Netherlands
Consolidated procurement through healthcare and e-commerce 3PL platforms concentrates volume in Dutch distribution hubs serving pan-European fulfillment. The country's centralized logistics infrastructure in Rotterdam and Venlo enables standardized thermal packaging specifications across multi-tenant warehouse networks. Meal-kit delivery operators retrofit automated lines with gusseted reflective pouches to compress packout time per order.
Reflective Air Packaging Market Competitive Landscape
Capacity expansion dominates the current landscape as laminators add extrusion coating lines to capture pharmaceutical certification requirements. The vendor base stratifies across three tiers: multinational film converters with integrated metallization capabilities, regional specialists in bubble substrate extrusion, and logistics-integrated packaging assemblers. Two strategic archetypes occupy distinct positions: premium-tier suppliers with full pharmaceutical validation documentation, and scale-driven producers serving e-commerce commodity demand. Competitive moves concentrate on backward integration into captive foil rolling capacity and technology licensing for phase-change material integration.
Within the multinational converter tier, Sealed Air Corporation and Amcor plc anchor premium positioning through established pharmaceutical corridor relationships. Pregis Corporation exemplifies the specialized cushioning archetype, occupying a position between commodity bubble producers and full-laminate converters. These three entities represent the dominant competitive anchors, with each sitting within distinct capability clusters that reflect their historical market development paths rather than recent strategic pivots.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Pregis Corporation |
| Sonoco Products Company |
| International Paper Company |
| Winpak Ltd |
| Amcor plc |
| Mondi plc |
| Smurfit Kappa Group |
| DS Smith |
| Others |
Value Network & Pricing Analysis
Germany's Packaging Act and France's AGEC law gate both qualified supply and premium-tier pricing access, assigning extended producer responsibility to brand owners and compressing margins on single-use thermal formats while advantaging certified laminators with verified circular packaging credentials.
Pricing Analysis
Distributor margin layers separate pharmaceutical-grade foil laminates from commodity polyethylene bubble formats, with three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on ISTA 7E certification status and REACH-compliant film traceability documentation. Pricing pressure stems from aluminum foil supply concentration in Chinese and Russian smelter networks exposing laminators to tariff volatility. E-commerce meal-kit operators exhibit highest price sensitivity, while Swiss and German biologics manufacturers absorb premium pricing for validated 96-hour ambient stability formats.
Supply Chain Analysis
Single-source vulnerability sits with primary foil rolling capacity clustering in Chinese and Russian smelter networks, exposing European and North American laminators to energy cost pass-throughs and trade policy disruption. Raw material dependencies center on seven-micron annealed aluminum foil, linear low-density polyethylene extrusion coatings, and vapor-deposited metallized PET substrates. Supply chain risk manifests as tariff exposure on Chinese foil imports under evolving trade frameworks. Distribution runs through consolidated third-party logistics platforms in Dutch and Belgian hubs serving pan-European pharmaceutical fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation's 2030 phase-down schedule compounds market demand by eliminating hydrofluorocarbon-dependent alternatives, forcing cold chain operators toward compliant air-cell metallized laminates as the default thermal protection standard.
For Market Incumbents: Deploy backward integration into captive foil rolling capacity to secure supply continuity against Chinese and Russian smelter concentration risk. Sealed Air Corporation and Amcor plc should accelerate REACH-certified film extrusion capabilities to defend pharmaceutical corridor positioning against emerging regional converters. Capacity expansion in German and Swiss manufacturing clusters captures biologics cold chain growth while meeting extended producer responsibility mandates. For New Entrants and Emerging Players: Enter via CDSCO-licensed pharmaceutical export corridors in Maharashtra and Gujarat, where domestic reflective packaging supply lags infrastructure investment. Target import substitution windows for certified regional producers serving European and North American cold chain compliance requirements. Pursue co-development partnerships with Indian logistics operators to embed phase-change materials into air-cell matrices for 96-hour validated duration. For Investors and Strategic Acquirers: Roll-up economics work for regional bubble substrate extrusion specialists because adhesive lamination technician scarcity creates capability bottlenecks that scale players can arbitrage through training pipeline investments. Acquisition targets include European converters with phthalate-free polyethylene certification and RFID-integrated reusable thermal shipper development capabilities. Watch for inflection signals in German public health system tendering weights assigned to circular packaging credentials.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foil Rolling | Captive supply of seven-micron annealed foil insulates laminators from Chinese and Russian smelter tariff exposure. |
| REACH-Compliant Film Certification | Phthalate-free polyethylene extrusion unlocks pharmaceutical procurement access previously closed to regional converters. |
| Phase-Change Material Integration | Embedded microcapsules in air-cell matrices extend validated duration windows beyond 96 hours for vaccine distribution. |
| RFID-Enabled Reusable Shipper Development | Returnable asset tracking with embedded temperature loggers displaces single-use expanded polystyrene in high-value electronics lanes. |
| Third-Party Logistics Platform Consolidation | Centralized procurement specifications across multi-tenant warehouse networks displace individual brand owner discretion in Dutch and Belgian hubs. |
Research Methodology
Direct dialogue with cold chain logistics operators, pharmaceutical packaging procurement managers, metallized film extrusion plant engineers, and EU regulatory affairs specialists anchored qualitative grounding, combined with secondary validation from EMA submissions, FDA current Good Distribution Practice guidelines, EU F-Gas Regulation implementation reports, and customs trade data on aluminum foil import flows. Bottom-up capacity assessments across German, Swiss, and Indian manufacturing clusters triangulated against top-down demand modeling from biologics pipeline analysis and e-commerce perishable fulfillment expansion trajectories.
Segmentation outputs across product type, material substrate, end-use application, and distribution channel dimensions fed analytical framework construction across the projection horizon. CAGRs derived from regression analysis of historical capacity utilization, regulatory phase-down schedules, and pharmaceutical cold chain infrastructure investment patterns. Industry-specific forecast inputs incorporated ISTA 7E qualification cycle timelines and CDSCO licensing velocity for Indian pharmaceutical export corridors.
Inputs from primary field interviews and regulatory filing databases were available through the study window; gaps in real-time capacity expansion announcements from Chinese and Russian foil rolling mills introduce uncertainty bands around supply-side constraint assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Active & Intelligent Packaging
Latin America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Isothermal Packaging Market
Active & Intelligent Packaging
Easy Open Packaging Market
Active & Intelligent Packaging
Global Augmented Reality Packaging Market
Active & Intelligent Packaging
Global Controlled Intelligent Packaging Market
Active & Intelligent Packaging
Interactive Packaging Market
Active & Intelligent Packaging
Europe Active and Intelligent Packaging Market
Active & Intelligent Packaging
Active and Modified Atmosphere Packaging Market
Active & Intelligent Packaging
Multi-Sensory Packaging Market
Active & Intelligent Packaging
Global Advanced Packaging Technologies Market
Active & Intelligent Packaging
High-End Performance Packaging Market
Active & Intelligent Packaging
ASEAN and Gulf Countries MAP and VSP Packaging Market
Active & Intelligent Packaging
Global Internet of Packaging Market
Active & Intelligent Packaging
Connected Packaging Market
Active & Intelligent Packaging
United Arab Emirates Packaging Market
Active & Intelligent Packaging
Middle East and Africa Active and Intelligent Packaging Market