
 Next Generation Packaging Market | 2026-2036
Next Generation Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation Packaging Market Outlook
The split between premium active-intelligent packaging and commodity-grade conventional formats is repositioning procurement priorities across end-user categories. Amcor Plc leverages its integrated film-to-pouch manufacturing network to sustain pricing power in pharmaceutical barrier applications. Mondi Group anchors European paper-based packaging supply through kraftliner capacity concentrated in Central Europe. Sealed Air Corporation differentiates via automated packaging systems that reduce material throughput per shipped unit.
Next generation packaging encompasses engineered material systems, embedded sensor technologies, and modified-atmosphere structures designed to extend shelf life, authenticate product provenance, or enable supply-chain traceability. These systems typically incorporate multilayer polymer films with oxygen transmission rates below 1 cc/m²/day, printed electronics for temperature logging, or bio-based substrates meeting industrial compostability standards under ASTM D6400 or EN 13432. Flexible packaging leads volume deployment due to lightweighting advantages in e-commerce fulfillment, while rigid formats retain margin concentration in pharmaceutical serialization where regulatory compliance commands price premiums. Paper-based packaging is accelerating fastest among food & beverage applications as brand owners confront single-use plastic restrictions across European and North American jurisdictions.
The EPA regulates per- and polyfluoroalkyl substance content in food-contact materials, compelling substrate reformulation across US-based converters. REACH restricts Substances of Very High Concern in imported packaging articles, reshaping material sourcing for EU-facing suppliers. FDA serialization mandates for prescription drug packaging continue to drive capital allocation toward track-and-trace infrastructure. Stakeholders must calibrate R&D portfolios against divergent regional compliance calendars rather than harmonized global standards.
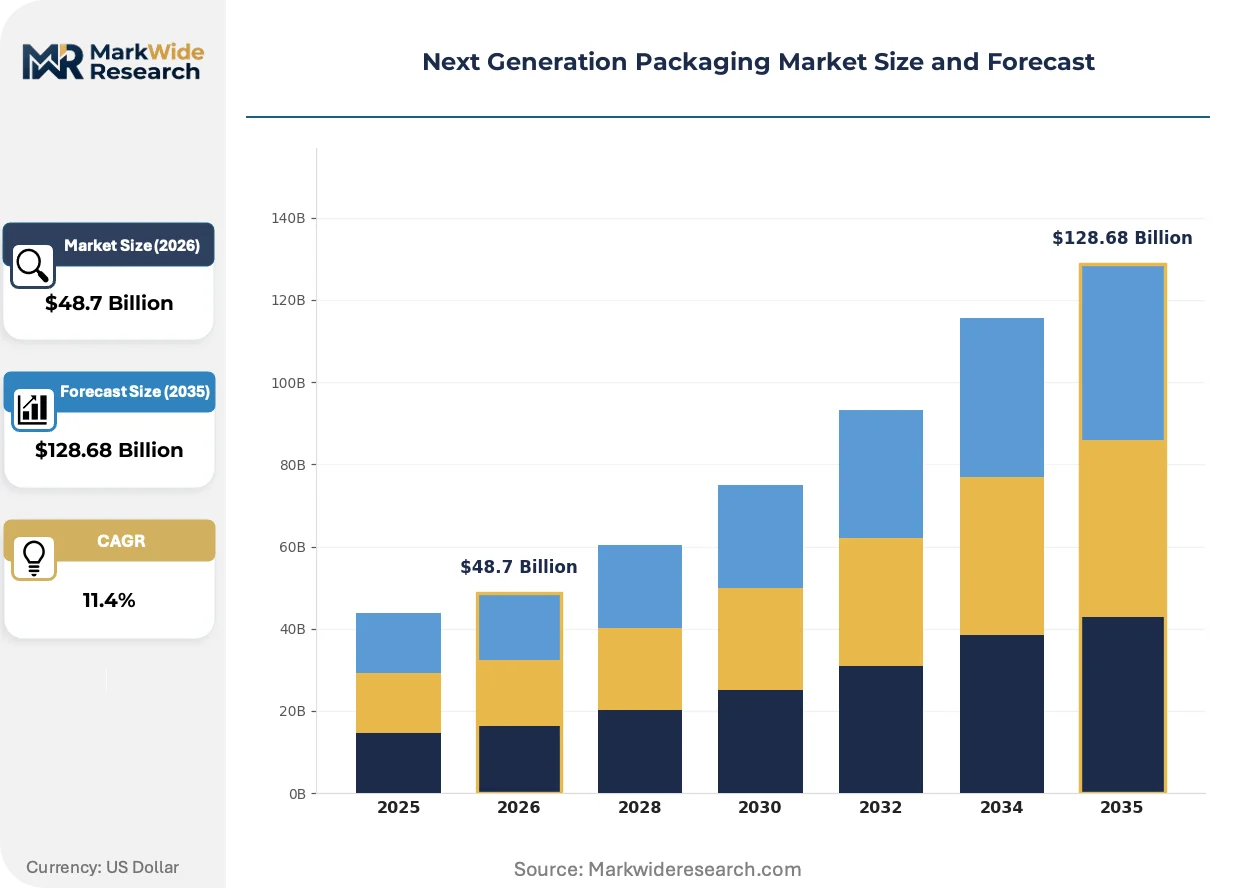
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are compressing compliance timelines for converters, forcing simultaneous substrate reformulation and digital infrastructure buildout across pharmaceutical and food-contact supply chains.
Growth Catalysts
- REACH SVHC restrictions:European chemical safety frameworks are accelerating migration toward bio-based barrier films as converters eliminate legacy additives from food-contact layers.
- Pharmaceutical serialization mandates:FDA track-and-trace requirements for prescription drug packaging are driving capital deployment into integrated printing and authentication systems.
- Industrial compostability certification:ASTM D6400 and EN 13432 standards are creating procurement preference hierarchies among brand owners facing single-use plastic restrictions.
Market Restraints
- Multilayer film complexity:Oxygen transmission rate targets below 1 cc/m²/day require incompatible polymer combinations that complicate mechanical recycling streams.
- Printed electronics yield:Temperature sensor integration suffers from defect rates that elevate unit costs above thresholds for commodity food applications.
- Biodegradable resin supply:Capacity for pharmaceutical-grade polylactic acid concentrates among a limited set of fermentation-based producers.
Strategic Opportunities
- Modified-atmosphere produce packaging:Fresh protein and prepared meal segments in Germany and China present underpenetrated demand for shelf-life extension systems.
- E-commerce lightweighting:Flexible pouch formats are capturing share from corrugated shippers in fulfillment networks seeking dimensional weight reductions.
- EU Green Deal procurement:Public sector foodservice contracts are mandating compostable serviceware, creating anchor demand for certified substrate suppliers.
Industry Challenges
- Electrochemical sensor calibration:pH and gas indicator accuracy drifts across temperature ranges, requiring field validation protocols that extend qualification timelines.
- Retrofit serialization infrastructure:Legacy pharmaceutical lines demand mechanical and software integration that disrupts validated production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation Packaging Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Metal Packaging, Paper-Based Packaging Material: Biodegradable Plastics, Glass, Aluminum, Wood Application: Food & Beverage, Personal Care, Pharmaceuticals, Electronics End User: Manufacturers, Retailers, Wholesalers, E-commerce |
| Companies Covered | Amcor Plc, Mondi Group, Berry Global, Sealed Air Corporation, Sonoco Products Company, Smurfit Kappa Group, Avery Dennison Corporation, CCL Industries, WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation Packaging Market Strategic Shifts
Active-intelligent packaging systems are converging material science with embedded electronics, compressing the traditional separation between containment function and supply-chain data generation.
Printed electrochemical sensors is unifying temperature logging with freshness indication in a single substrate layer. Pharmaceutical cold-chain shippers in Germany and the United States are piloting these formats for high-value biologics. The technology is unifying previously separate quality assurance steps into continuous monitoring, reducing manual inspection labor while expanding liability coverage for temperature excursions.
EPA per- and polyfluoroalkyl substance restrictions are compelling substrate reformulation across US-based food-contact converters. The rule eliminates grease-resistant fluorochemical treatments from paperboard and molded fiber formats. Frozen food and quick-service restaurant segments are responding with alternative barrier coatings derived from bio-waxes and clay minerals, accepting modest performance trade-offs for compliance certainty.
Brand-owner sustainability scorecards are compressing supplier qualification cycles around carbon footprint and recyclability credentials. Food and beverage manufacturers in France and the Netherlands are embedding packaging specifications into procurement RFPs that previously addressed only unit cost and lead time. This behavioral shift elevates converters with certified circular production systems while marginalizing commodity suppliers lacking third-party verification.
Next Generation Packaging Market Segmentation
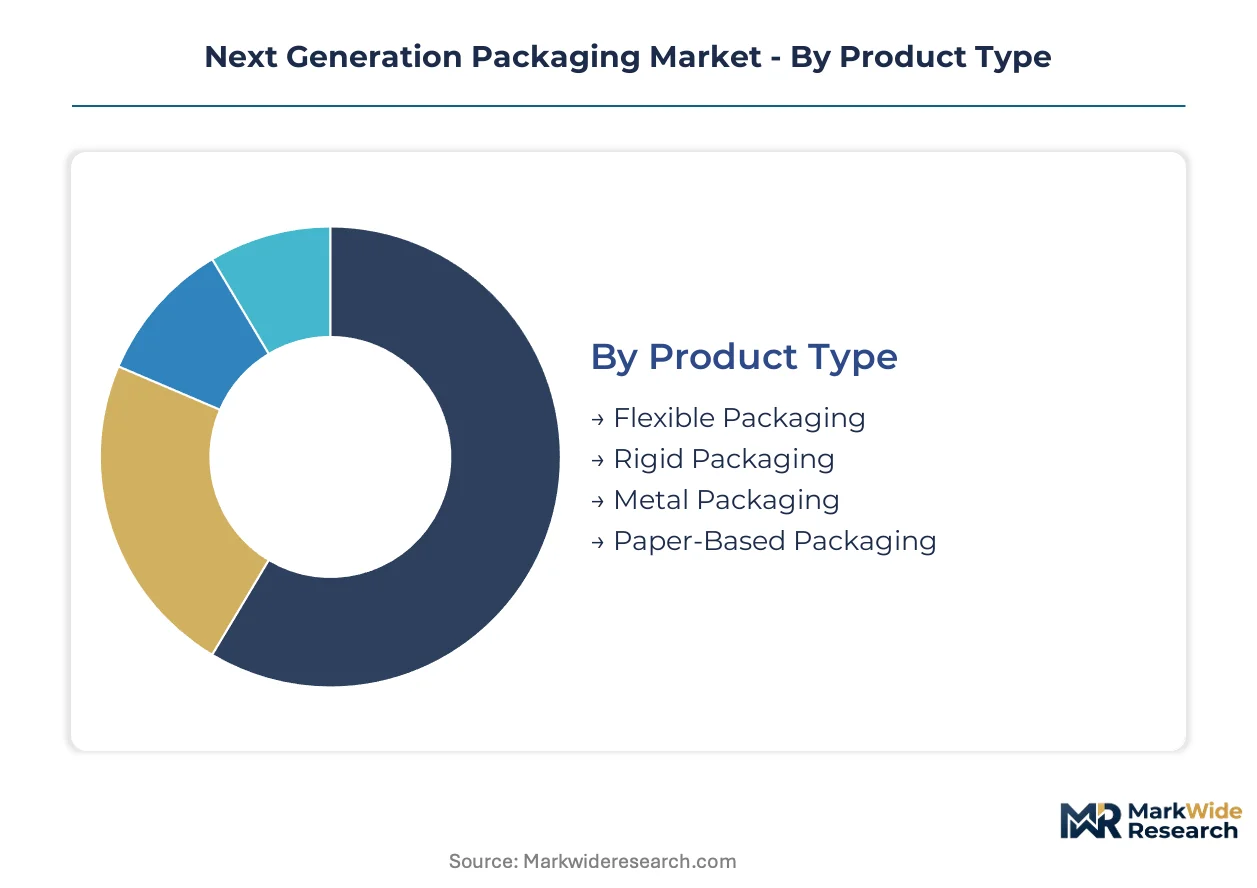
Segmentation in next generation packaging reveals where capital deployment, regulatory compliance, and margin capture concentrate. Procurement patterns diverge sharply across material systems and end-use requirements.
Product Type:
Capital intensity varies dramatically by format, with barrier film extrusion lines demanding lower upfront investment than pharmaceutical-grade rigid conversion systems.
- Flexible Packaging:Multilayer polymer films with oxygen transmission rates below 1 cc/m²/day dominate pharmaceutical and fresh protein applications. Demand clusters in German cold-chain logistics and Chinese e-commerce fulfillment networks where lightweighting reduces dimensional weight charges.
- Rigid Packaging:Injection-molded and thermoformed structures incorporate embedded authentication features for FDA serialization compliance. Pharmaceutical manufacturers in the United States allocate capital here despite longer qualification timelines.
- Metal Packaging:Aluminum aerosol and barrier containers serve personal care and food preservation segments.
- Paper-Based Packaging:Kraftliner and molded fiber formats accelerate under EU single-use plastic restrictions.
Most installed capacity flows through Flexible Packaging. Expansion is steepest in Paper-Based Packaging.
Material:
Feedstock selection determines compliance pathways across REACH, EPA, and industrial compostability regimes.
- Biodegradable Plastics:Polylactic acid and polyhydroxyalkanoate resins certified to ASTM D6400 or EN 13432 command procurement premiums in French and Dutch foodservice contracts. Supply concentrates among fermentation-based producers with pharmaceutical-grade purification capabilities.
- Glass:Borosilicate and amber formats retain share in pharmaceutical serialization where inertness and barrier permanence outweigh weight penalties.
- Aluminum:Lightweight barrier metal supports aseptic and retort applications.
- Wood:Molded fiber and solid formats serve premium cosmetics and electronics unboxing experiences.
Biodegradable Plastics attract the steepest expansion trajectory. Glass maintains the most stable installed base.
Application:
End-use requirements fragment the supplier base between commodity converters and certified pharmaceutical specialists.
- Food & Beverage:Modified-atmosphere structures extend shelf life for fresh proteins and prepared meals. German retailers and Chinese meal-kit platforms drive specification intensity around oxygen scavenging and moisture control.
- Personal Care:Premium unboxing experiences and refillable formats command structural investment in rigid and glass systems.
- Pharmaceuticals:Track-and-trace mandates from FDA and EMA drive capital into integrated printing and authentication infrastructure.
- Electronics:Anti-static and moisture-barrier formats protect high-value components during global fulfillment.
Food & Beverage channels the most installed capacity. Pharmaceuticals is climbing the fastest on compliance-driven reinvestment.
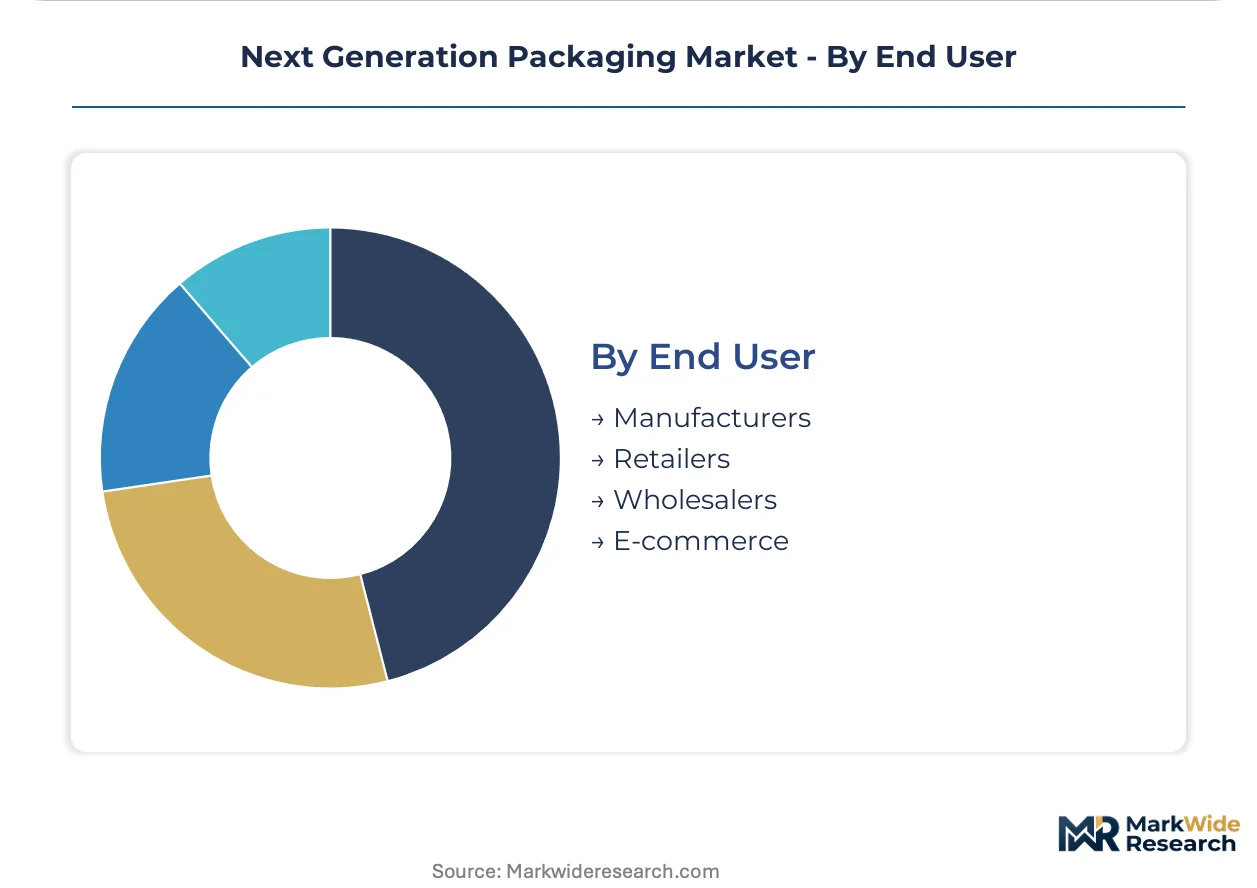
End User:
Procurement authority shapes specification complexity and contract duration across the value chain.
- Manufacturers:Brand owners in pharmaceuticals and food integrate packaging specifications into sustainability scorecards that previously addressed only unit cost. French and Dutch manufacturers now embed carbon footprint and recyclability credentials into RFP structures.
- Retailers:Private-label and store-brand packaging demands shorter lead times with standardized formats.
- Wholesalers:Bulk and institutional channels prioritize cost minimization over feature differentiation.
- E-commerce:Dimensional weight reduction drives flexible pouch adoption over corrugated shippers in fulfillment networks.
Manufacturers concentrate the most specification authority. E-commerce is gaining share fastest in volume terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer scientists and printed electronics engineers concentrate in Germany, China, and the United States, anchoring the geographic distribution of next generation packaging innovation and manufacturing scale.
United States
Pharmaceutical serialization mandates and e-commerce fulfillment networks drive specification intensity in barrier films and flexible pouch formats. FDA track-and-trace requirements for prescription drug packaging compel capital deployment into integrated authentication systems. The New Jersey-Pennsylvania pharmaceutical corridor hosts concentrated converter capacity serving cold-chain biologics shippers.
Germany
Modified-atmosphere produce packaging for fresh proteins and prepared meals commands premium pricing in retail channels. REACH Substances of Very High Concern restrictions accelerate migration toward bio-based barrier films among food-contact converters. The Rhine-Main industrial cluster anchors European kraftliner supply for paper-based packaging acceleration.
China
Meal-kit platforms and cross-border e-commerce fulfillment networks drive dimensional weight reduction through flexible pouch adoption. National dual carbon goals and single-use plastic restrictions reshape material sourcing priorities for domestic brand owners. The Yangtze River Delta concentrates multilayer film extrusion capacity serving both domestic consumption and export markets.
France
Public sector foodservice procurement under EU Green Deal frameworks mandates compostable serviceware, creating anchor demand for certified substrate suppliers. ANSM pharmaceutical packaging standards align with EMA serialization directives for track-and-trace compliance. The Paris-Saclay research cluster advances printed electrochemical sensor development for cold-chain monitoring applications.
Netherlands
Brand-owner sustainability scorecards embed carbon footprint and recyclability credentials into procurement RFP structures across food and beverage manufacturing. ECHA chemical safety frameworks eliminate legacy additives from imported packaging articles. The Port of Rotterdam logistics hub facilitates bio-based resin import flows for pharmaceutical-grade polylactic acid converters.
Next Generation Packaging Market Competitive Environment
Capital-heavy producers compete with asset-light designers across substrate development, equipment integration, and digital infrastructure layers. The market structure consolidates around integrated multinationals with captive polymer supply, regional specialists with certified circular production systems, and technology licensors with sensor platform IP. Three archetypes dominate: film-to-pouch integrators, paper-based barrier innovators, and automated packaging system providers. Competitive moves concentrate on backward integration into resin fermentation and strategic partnerships for printed electronics yield improvement.
Among integrated packaging multinationals, Amcor Plc, Mondi Group, and Sealed Air Corporation exemplify distinct strategic positions. Amcor Plc represents the film-to-pouch integration archetype with pharmaceutical barrier specialization. Mondi Group anchors European paper-based supply through Central European kraftliner concentration. Sealed Air Corporation occupies the automated systems tier where material throughput reduction per shipped unit commands pricing power. These three entities collectively illustrate how geographic production clustering, regulatory compliance depth, and format-specific engineering capabilities separate premium-tier suppliers from commodity converters.
| Leading Market Players |
|---|
| Amcor Plc |
| Mondi Group |
| Berry Global |
| Sealed Air Corporation |
| Sonoco Products Company |
| Smurfit Kappa Group |
| Avery Dennison Corporation |
| CCL Industries |
| WestRock Company |
| Others |
Value Chain & Pricing Dynamics
Captive film-to-pouch integration anchors pricing power for pharmaceutical barrier specialists while compressing margins for commodity converters lacking in-house polymer supply. This structural divide separates premium-tier suppliers commanding certification premiums from standard-grade competitors exposed to resin cost volatility.
Pricing Analysis
The bundled-vs-unbundled service split separates integrated converters offering full serialization compliance from component-only suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with FDA-validated pharmaceutical formats commanding substantial premiums over food-contact commodity films. Cost compression in standard flexible packaging intensifies as Chinese e-commerce fulfillment networks drive dimensional weight reduction demands. Brand owners in French foodservice procurement prove least price-sensitive due to EU Green Deal mandate compliance requirements, while bulk wholesalers exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from German pharmaceutical manufacturers mandate multi-supplier qualification for polylactic acid resins and multilayer barrier films. Supply concentrates in Germany, China, and the United States for specialized polymer extrusion and printed electronics integration. Raw material dependencies center on fermentation-based polylactic acid, bio-wax barrier coatings, and clay mineral grease-resistant treatments. Single-source vulnerability in pharmaceutical-grade biodegradable resin purification creates structural risk. Distribution runs through converter-direct relationships with brand-owner procurement teams, bypassing traditional distributor networks for qualified pharmaceutical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in next generation packaging rests on substrate lightweighting and premium-tier certification capture, as brand owners embed sustainability scorecards into procurement RFPs that previously addressed only unit cost.
For Market Incumbents: Anticipate regulatory compression in REACH SVHC restrictions and FDA serialization mandates by accelerating backward integration into bio-based resin fermentation. Defensive positioning requires captive supply of ASTM D6400-certified substrates and embedded sensor platform partnerships to counter emerging printed electronics specialists. Capacity addition in the Rhine-Main cluster secures European kraftliner dominance against Asian imports. For New Entrants and Emerging Players: E-commerce fulfillment networks present the most penetrable channel for flexible pouch lightweighting solutions. White-space targets include modified-atmosphere produce packaging for German fresh protein retailers and compostable serviceware for Dutch public sector foodservice contracts. Go-to-market leverage rests on rapid certification to EN 13432 standards ahead of established competitors' reformulation timelines. For Investors and Strategic Acquirers: Roll-up economics work for regional paper-based barrier innovators because EU single-use plastic restrictions are fragmenting demand across national compliance calendars. Long-term viability favors converters with certified circular production systems and integrated digital infrastructure layers. Acquisition target archetypes include automated packaging system providers with yield-improvement IP and Central European kraftliner assets. Watch for inflection in printed electrochemical sensor defect rates as the signal for mainstream cold-chain adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Resin Fermentation | Captive polylactic acid supply secures ASTM D6400 certification premiums against volatile feedstock markets. |
| Printed Electronics Yield Improvement Partnership | Reduced defect rates in temperature sensors unlock commodity food application scale beyond pharmaceutical cold-chain. |
| Rhine-Main Kraftliner Capacity Expansion | Central European paper-based packaging acceleration captures EU Green Deal procurement mandates. |
| FDA Serialization Infrastructure Retrofit | Integrated authentication systems command compliance premiums from US pharmaceutical manufacturers. |
| Modified-Atmosphere Produce Packaging Development | Shelf-life extension systems penetrate underexploited German fresh protein and Chinese meal-kit segments. |
Study Parameters
Direct dialogue with polymer scientists, pharmaceutical packaging engineers, brand-owner sustainability officers, and food-contact regulatory specialists grounded qualitative findings in operational reality. Secondary validation drew from ECHA substance restriction databases, FDA drug packaging guidance documents, EU Packaging and Packaging Waste Regulation impact assessments, and ASTM industrial compostability certification records. Bottom-up demand modeling across converter capacity and top-down macroeconomic triangulation ensured cross-verified outputs.
Bottom-up volume builds aggregated individual segment trajectories while top-down macroeconomic sanity checks anchored aggregate market scale across the projection horizon. Segmentation dimensions spanned material system, packaging format, application vertical, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to base-year estimates, with pharmaceutical serialization compliance timelines and EU plastic restriction phase-ins as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH SVHC list expansion pace and biodegradable resin capacity buildout. Deviation in FDA track-and-trace enforcement intensity or Chinese dual carbon goal acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Active & Intelligent Packaging
Active Packaging Market
Active & Intelligent Packaging
North America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Multi-Sensory Packaging Market
Active & Intelligent Packaging
ASEAN and Gulf Countries MAP and VSP Packaging Market
Active & Intelligent Packaging
Connected Packaging Market
Active & Intelligent Packaging
Easy Open Packaging Market
Active & Intelligent Packaging
Global Advanced Packaging Technologies Market
Active & Intelligent Packaging
Global Controlled Intelligent Packaging Market
Active & Intelligent Packaging
Global Augmented Reality Packaging Market
Active & Intelligent Packaging
Gel Packs Market
Active & Intelligent Packaging
United Arab Emirates Packaging Market
Active & Intelligent Packaging
Europe Active and Intelligent Packaging Market
Active & Intelligent Packaging
Heat Sensitive Cups Market
Active & Intelligent Packaging
Latin America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Active Smart and Intelligent Packaging Market
Active & Intelligent Packaging
Asia Pacific Active and Intelligent Packaging Market