
 Europe Active and Intelligent Packaging Market | 2026-2036
Europe Active and Intelligent Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Active and Intelligent Packaging Market Foresight
Foodservice distribution channels in Europe is narrowing as quick-service chains and meal-kit operators consolidate supplier panels toward packaging partners with integrated active-barrier capabilities. Amcor leverages its European extrusion network to supply oxygen-scavenging films directly to protein processors in the Netherlands and Spain. Berry Global anchors its position through blow-molded containers with embedded freshness indicators for dairy clients across Scandinavia. Sealed Air competes on automated packaging lines that marry modified-atmosphere materials with real-time gas sensors.
Active and intelligent packaging encompasses systems that interact with contents or environment to extend shelf life, ensure safety, or communicate status, typically incorporating oxygen absorbers, moisture regulators, time-temperature indicators, or RFID-enabled smart labels with data-logging thresholds of 0.1°C precision. The primary commercial purpose centers on reducing spoilage in temperature-sensitive supply chains while enabling brand authentication and consumer engagement through scannable interfaces. Active Packaging dominates current European volume as established oxygen-scavenging and ethylene-absorbing formats serve mature meat and produce sectors. Intelligent Packaging captures accelerating investment as pharmaceutical serialization rules under the EU Falsified Medicines Directive expand demand for track-and-trace smart labels. Freshness Indicators occupy a narrower but higher-margin niche where premium seafood and ready-to-eat salad brands in France and Italy differentiate through visible quality cues.
EMA pharmaceutical guidelines, the EU Packaging and Packaging Waste Regulation, and REACH chemical compliance frameworks collectively shape material selection, migration limits, and end-of-life obligations for European converters. EMA stability-testing requirements for drug packaging directly stimulate demand for temperature-logging intelligent systems in clinical distribution. Stakeholders must monitor how the EU Green Deal's recyclability targets will restrict multi-layer active film constructions and force redesign toward mono-material or paper-based intelligent substrates.
Market Dynamics
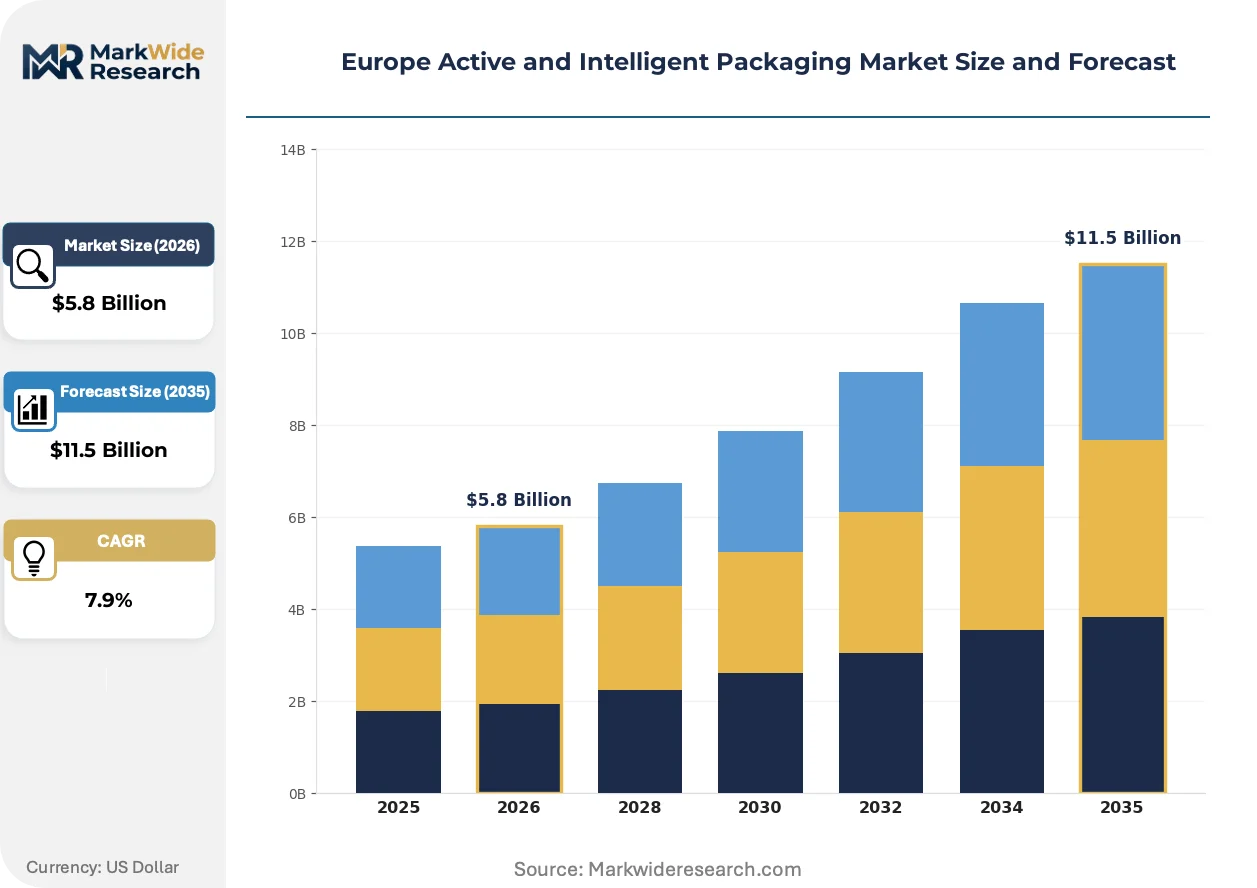
The EU Packaging and Packaging Waste Regulation is compressing converter timelines for traceable, recyclable active packaging formats while pharmaceutical serialization mandates under the Falsified Medicines Directive accelerate intelligent label deployment across temperature-sensitive supply chains.
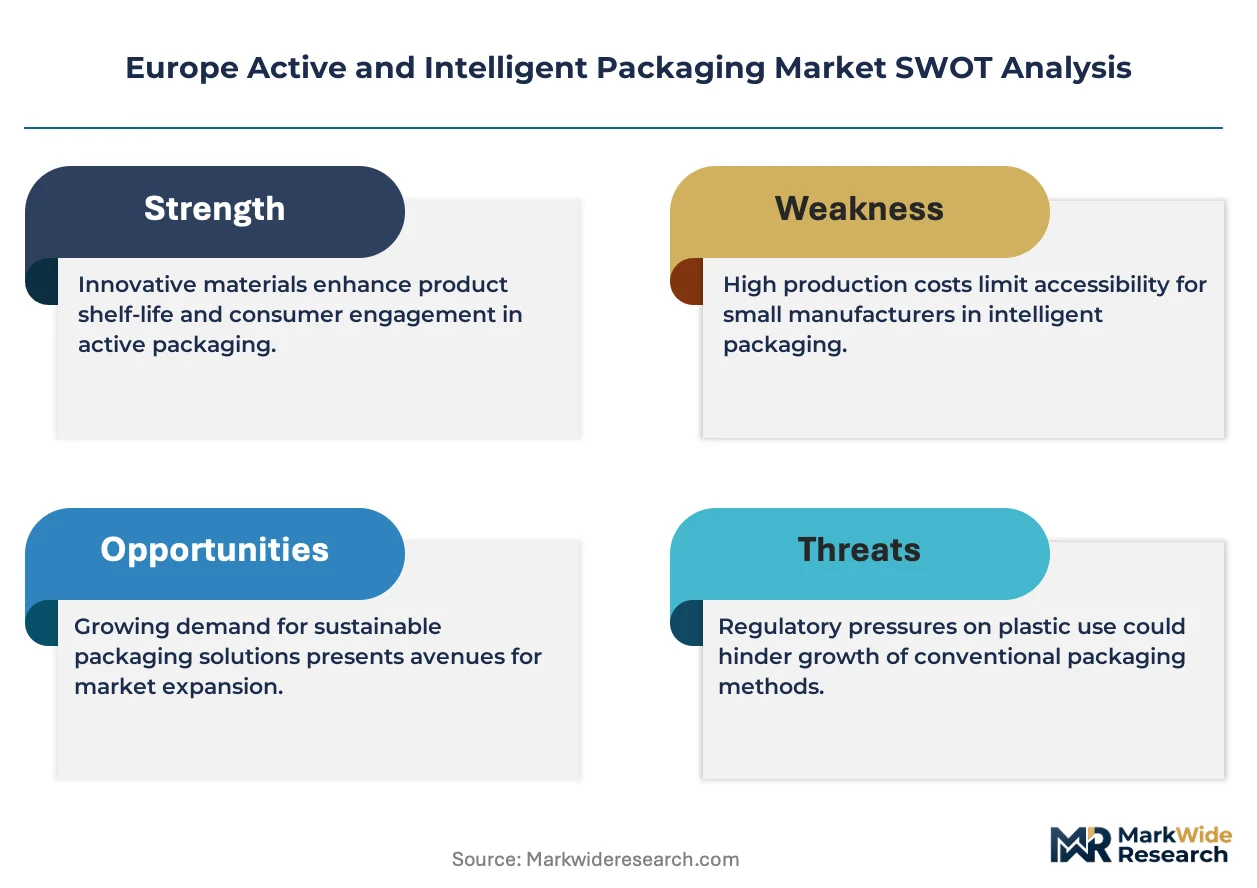
Growth Catalysts
- EMA Stability-Testing Mandates:Pharmaceutical cold-chain requirements in Germany and France are expanding demand for temperature-logging intelligent labels with 0.1°C precision thresholds.
- Foodservice Consolidation:Quick-service chains and meal-kit operators across the Netherlands and Spain are narrowing supplier panels toward partners with integrated oxygen-scavenging and modified-atmosphere capabilities.
- Ethylene-Absorbing Formats:Mature meat and produce sectors in Scandinavia continue absorbing established active packaging volumes as shelf-life extension becomes non-negotiable for export competitiveness.
Market Restraints
- Multi-Layer Film Recyclability:The EU Green Deal's recyclability targets restrict multi-layer active film constructions and force costly redesign toward mono-material or paper-based intelligent substrates.
- Specialized Substrate Concentration:Germany's industrial corridor dominates film and substrate supply, creating geographic concentration risk for converters dependent on co-located processors.
- REACH Migration Limits:Chemical compliance frameworks impose strict material selection constraints that eliminate certain oxygen-scavenger chemistries from food-contact applications.
Strategic Opportunities
- Italian Premium Seafood Segment:Freshness indicators occupy a narrow but higher-margin niche where visible quality cues differentiate ready-to-eat brands in France and Italy.
- RFID-Enabled Consumer Engagement:Scannable smart labels are hybridizing authentication with marketing, opening brand-owned data channels previously captured by retailers.
- Scandinavian Dairy Automation:Blow-molded containers with embedded indicators are penetrating automated packaging lines that marry modified-atmosphere materials with real-time gas sensors.
Industry Challenges
- Connected Platform Integration:Converters face execution friction migrating legacy production lines to connected packaging platforms capable of real-time data logging and cloud transmission.
- Cross-Functional Talent Scarcity:The convergence of materials science, sensor hardware, and software development creates acute shortages of packaging engineers with integrated electromechanical competencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Active and Intelligent Packaging Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.5 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Packaging, Intelligent Packaging, Smart Labels, Freshness Indicators Material: Plastic, Paper, Metal, Composites Application: Food & Beverage, Pharmaceuticals, Electronics, Household Products End User: Manufacturers, Retailers, Distributors, Consumers |
| Companies Covered | 3M Company, Berry Global, Amcor, Stora Enso, Coveris, Sealed Air, Multivac, Linpac, Mondi Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Active and Intelligent Packaging Market Shifts & Advancements
Active and intelligent packaging formats are converging with digital infrastructure and sustainability mandates, reshaping how converters design for circularity while preserving functional performance in temperature-sensitive supply chains.
Printed electronics is hybridizing with conventional barrier films to create disposable temperature loggers that maintain substrate flexibility while embedding NFC-readable sensor arrays. Pharmaceutical distributors in Germany and France are piloting these formats for last-mile cold-chain verification. The structural consequence is compressing the cost gap between single-use loggers and reusable data loggers, enabling item-level tracking at pallet-scale economics.
The EU Packaging and Packaging Waste Regulation tightens extended producer responsibility frameworks and mandates design-for-recycling criteria that directly impact multi-layer active film constructions. Converters must now demonstrate recyclability pathways or face market exclusion by 2030. Food processors in the Netherlands and Spain are responding by specifying mono-material oxygen scavengers that sacrifice some performance for compliance certainty.
Buyer concentration among meal-kit operators and quick-service chains is consolidating procurement power into fewer hands with stricter technical specifications. These operators now require packaging partners to deliver integrated active-barrier capabilities rather than discrete components. France and Italy exhibit the most visible compression of supplier panels, with premium seafood and ready-to-eat salad brands bundling freshness indicators into master service agreements.
Europe Active and Intelligent Packaging Market Segmentation
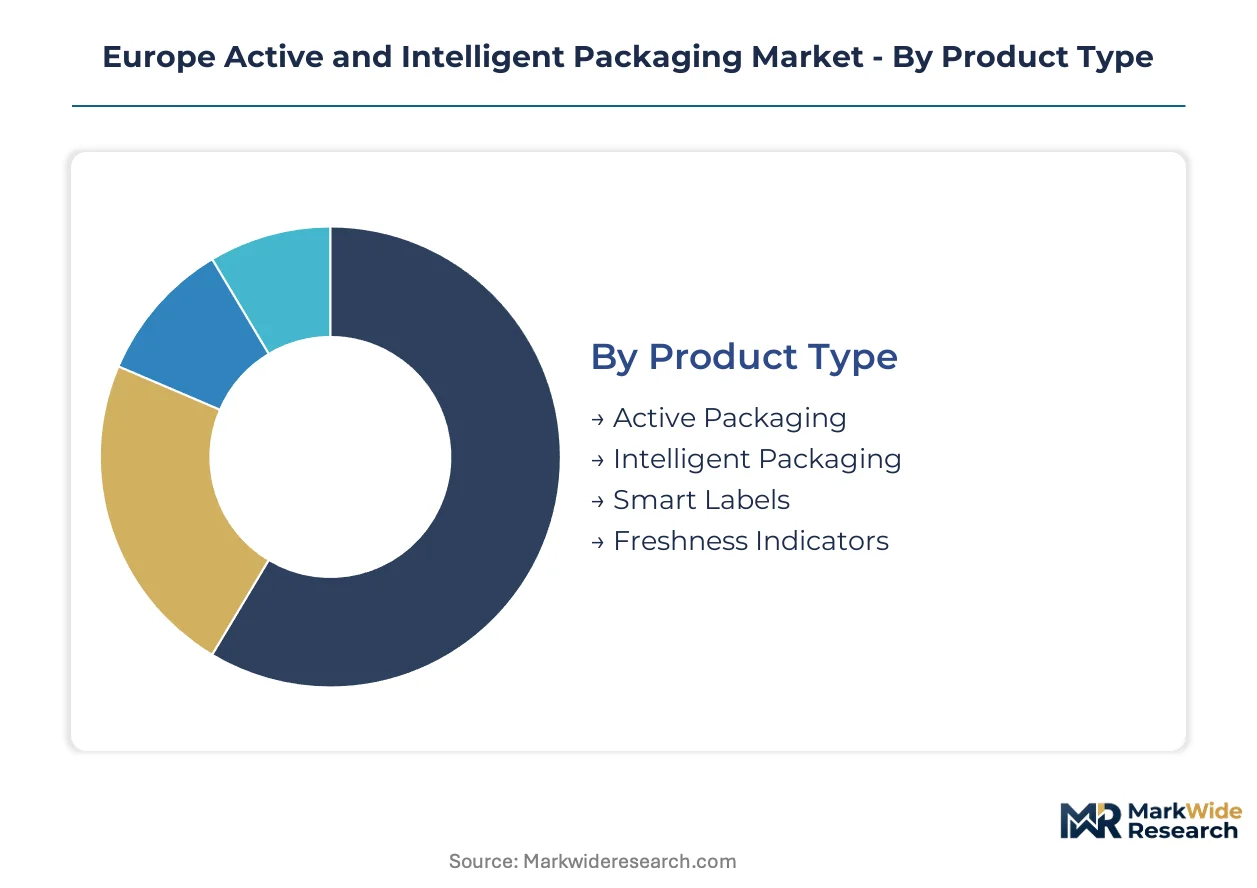
Segmentation in Europe's active and intelligent packaging market reveals how functional requirements, material constraints, and regulatory pressures fragment demand across incompatible technical specifications. Converters must align production capabilities with the specific performance thresholds each segment demands.
Product Type:
Mature formats dominate current volume while digitally-enabled systems capture accelerating investment across pharmaceutical and foodservice channels.
- Active Packaging:Oxygen-scavenging films and ethylene-absorbing sachets constitute the established base, serving meat processors in Scandinavia and produce exporters with shelf-life extension as a non-negotiable competitive requirement. REACH migration limits constrain certain scavenger chemistries, forcing material substitutions in food-contact applications.
- Intelligent Packaging:RFID-enabled smart labels with 0.1°C precision thresholds are expanding across German and French pharmaceutical cold chains under EMA stability-testing mandates. The EU Falsified Medicines Directive serialization rules accelerate track-and-trace deployment for temperature-sensitive drug distribution.
- Smart Labels:Printed electronics hybridizing with barrier substrates create disposable NFC-readable temperature loggers for last-mile verification.
- Freshness Indicators:Visible quality cues differentiate premium seafood and ready-to-eat salad brands in France and Italy through higher-margin embedded indicators.
Active Packaging retains volume leadership; Intelligent Packaging holds the steepest expansion curve.
Material:
Cost tiers separate commodity substrates from performance-engineered constructions facing recyclability redesign pressures.
- Plastic:Multi-layer barrier films with embedded scavenger layers face forced redesign under EU Green Deal recyclability targets, with Dutch and Spanish food processors specifying mono-material alternatives that sacrifice some performance for compliance certainty.
- Paper:Emerging intelligent substrates integrate printed sensor arrays for pharmaceutical applications seeking fiber-based end-of-life pathways.
- Metal:Aluminum-based oxygen absorber formats serve high-barrier pharmaceutical and electronics protection with established migration compliance.
- Composites:Hybrid constructions combining barrier properties with sensor integration encounter the sharpest regulatory pressure for recyclability demonstration by 2030.
Plastic maintains substrate dominance; paper-based intelligent formats are gaining share fastest among sustainability-mandated procurement.
Application:
End-use concentration varies sharply by regulatory intensity and spoilage cost structure.
- Food & Beverage:Oxygen-scavenging films and modified-atmosphere materials serve consolidated quick-service chains and meal-kit operators in the Netherlands and Spain that now require integrated active-barrier capabilities rather than discrete components.
- Pharmaceuticals:Temperature-logging intelligent systems penetrate clinical distribution networks under EMA guidelines, with Germany and France exhibiting the densest cold-chain infrastructure investment.
- Electronics:Moisture-regulating active formats protect humidity-sensitive components through controlled desiccant release.
- Household Products:Scent-preserving and moisture-control packaging extends shelf appeal for consumer goods with lower technical complexity thresholds.
Food & Beverage anchors volume demand; Pharmaceuticals drives the steepest value-per-unit expansion.
End User:
Customer type determines whether packaging procurement emphasizes unit economics, brand differentiation, or supply-chain control.
- Manufacturers:Protein processors and drug makers in Germany's industrial corridor co-locate with specialized film suppliers to secure captive oxygen-scavenging and modified-atmosphere material flows.
- Retailers:Quick-service chains and meal-kit operators are compressing supplier panels toward partners with integrated platform capabilities spanning active barriers and real-time monitoring.
- Distributors:Pharmaceutical logistics providers in France and Italy pilot RFID-enabled item-level tracking to satisfy serialization mandates.
- Consumers:Scannable smart labels open brand-owned data channels for engagement, though direct consumer-facing intelligent packaging remains a narrower deployment.
Manufacturers retain procurement volume leadership; Retailers are forcing the steepest consolidation pressure on converter relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium pricing for temperature-logging intelligent labels while Spanish converters compete on mono-material oxygen scavengers at tighter margins. This asymmetry reflects divergent regulatory enforcement intensity and buyer concentration across the continent.
Germany
Pharmaceutical cold-chain infrastructure in the Rhine-Ruhr and Bavarian industrial corridors drives dense demand for 0.1°C precision data loggers. EMA stability-testing mandates under the EU Falsified Medicines Directive accelerate serialization-compliant smart label deployment. Munich and Frankfurt host co-located drug manufacturers and specialized film suppliers that capture captive substrate flows.
France
Premium seafood and ready-to-eat salad brands in the Île-de-France and Provence-Alpes-Côte d'Azur regions differentiate through embedded freshness indicators with visible quality cues. ANSM pharmaceutical guidelines reinforce traceability requirements that expand intelligent packaging procurement. Lyon and Marseille anchor converter networks serving Mediterranean export corridors.
Netherlands
Quick-service chains and meal-kit operators in the Randstad cluster consolidate supplier panels toward integrated active-barrier capabilities. REACH migration limits constrain certain scavenger chemistries, forcing material substitutions in Rotterdam's food-contact processing hub. Eindhoven's printed electronics specialists pilot NFC-readable temperature loggers for last-mile verification.
Spain
Protein processors in Catalonia and the Basque Country specify mono-material oxygen scavengers that sacrifice performance for EU Green Deal recyclability compliance. The country's national pharmaceutical regulator enforces serialization timelines that lag German and French adoption curves. Barcelona and Bilbao concentrate blow-molded container fabrication for dairy automation lines.
Italy
Visible freshness indicators penetrate Lombardy and Emilia-Romagna's premium food packaging segments where brand differentiation commands higher-margin procurement. EFSA food-contact frameworks shape material selection for oxygen-scavenging films serving Parma's cured meat processors. Milan anchors design-for-recycling innovation as converters anticipate 2030 extended producer responsibility thresholds.
Europe Active and Intelligent Packaging Market Competitive Landscape
Diversified materials conglomerates and specialized packaging converters split the market along capability-integration fault lines. Consolidation pressure from quick-service chain procurement compresses margins for discrete-component suppliers while rewarding end-to-end platform providers. Three archetypes dominate: substrate-integrated scavenger specialists, sensor-embedded smart label developers, and automated packaging line integrators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as converters race to demonstrate recyclability pathways before 2030 exclusion deadlines.
Within the diversified materials tier, Amcor plc and Berry Global exemplify scale-driven substrate integration. Sealed Air Corporation occupies a distinct position marrying modified-atmosphere materials with real-time monitoring hardware. These three entities anchor the competitive structure through geographic footprint breadth and regulatory compliance depth across German pharmaceutical and Dutch foodservice corridors.
| Leading Market Players |
|---|
| 3M Company |
| Berry Global |
| Amcor |
| Stora Enso |
| Coveris |
| Sealed Air |
| Multivac |
| Linpac |
| Mondi Group |
| Others |
Supply & Pricing Matrix
Germany's industrial corridor concentrates specialized film and substrate supply, anchoring margin pools downstream with pharmaceutical cold-chain converters and premium foodservice distributors who co-locate to secure captive material flows. This geographic clustering creates asymmetric pricing power where proximity to EMA-compliant production lines commands substantial customization premiums.
Pricing Analysis
Configured-to-order intelligent labels with 0.1°C precision thresholds command substantial premiums over standard oxygen-scavenging films. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation, with EMA-validated temperature loggers at the apex. Cost compression in standard active films is intensifying because Dutch and Spanish food processors are specifying mono-material alternatives for EU Green Deal compliance. Quick-service chains exhibit acute price sensitivity, while pharmaceutical distributors demonstrate inelastic demand for serialization-compliant smart labels.
Supply Chain Analysis
Tariff exposure between Germany and non-EU substrate suppliers dominates supply chain risk planning for multi-layer film converters. Geographic supply concentrates in Germany, France, and the Netherlands, with raw material dependencies spanning ethylene-scavenger chemistries, printed sensor arrays, and NFC-readable substrates. Single-source vulnerability in specialized electromechanical components creates acute shortages of packaging engineers with integrated competencies. Distribution runs through co-located processor networks in the Rhine-Ruhr and Randstad clusters before reaching consolidated retail procurement panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable competitive positioning. EMA stability-testing mandates and EU Falsified Medicines Directive serialization rules erect substantial compliance barriers that protect incumbent converters with established validation histories.
For Market Incumbents: Pre-empt emerging entrants by securing backward integration into printed electronics manufacturing before Eindhoven's sensor specialists scale production. Add capacity in Munich's pharmaceutical corridor to capture EMA-mandated temperature-logging demand. Certification investment in mono-material oxygen scavengers defends against EU Green Deal redesign deadlines. For New Entrants and Emerging Players: Spanish protein processors represent underpenetrated terrain for recyclability-first mono-material formats that sacrifice performance for compliance certainty. Italian premium seafood brands offer accessible entry through visible freshness indicators with shorter regulatory validation cycles. A go-to-market angle anchored in design-for-recycling consulting bundled with substrate supply bypasses incumbent scale advantages. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap converters with captive pharmaceutical validation relationships and demonstrated EU regulatory navigation capabilities. Long-term viability hinges on 2030 extended producer responsibility threshold preparedness. The signal to watch is consolidation velocity among quick-service chain procurement panels as buyer concentration accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Certification | EMA validation for 0.1°C precision temperature loggers secures pharmaceutical procurement lock-in. |
| Mono-Material Redesign | EU Green Deal recyclability pathways protect market access against 2030 exclusion deadlines. |
| Printed Electronics Integration | NFC-readable sensor arrays embedded in barrier films compress cost gaps with reusable data loggers. |
| Geographic Co-Location Expansion | Rhine-Ruhr and Bavarian corridor proximity captures captive substrate flows from drug manufacturers. |
| Supplier Panel Consolidation Defense | Integrated active-barrier capabilities prevent displacement by discrete-component competitors. |
Research Methodology
Desk research of EMA stability-testing guidelines, EU Packaging and Packaging Waste Regulation filings, and REACH migration limit databases preceded structured interviews with pharmaceutical cold-chain logistics directors, foodservice procurement leads at quick-service chains, flexible packaging plant managers, and printed electronics R&D specialists. Secondary validation drew from customs trade data, SEC filings of diversified materials conglomerates, and Cefic chemical industry reports. Bottom-up demand modeling triangulated against top-down regulatory mandate timelines.
Assumptions held fixed include EMA pharmaceutical guideline enforcement intensity and EU Green Deal recyclability target adherence rates, while variables included meal-kit operator consolidation velocity and printed electronics cost reduction curves. Segmentation dimensions spanned product type, material substrate, application end-use, and customer procurement archetype across the modeling period. CAGRs derived from installed base growth in temperature-sensitive supply chains and replacement cycle acceleration for multi-layer films facing redesign mandates. Industry-specific inputs incorporated oxygen-scavenger chemistry substitution rates and RFID smart label adoption curves under Falsified Medicines Directive timelines.
Practitioners should monitor EMA guideline revision schedules and EU Packaging and Packaging Waste Regulation enforcement granularity for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Active & Intelligent Packaging
Connected Packaging Market
Active & Intelligent Packaging
Latin America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Reflective Air Packaging Market
Active & Intelligent Packaging
Active Packaging Market
Active & Intelligent Packaging
Global Active and Intelligent Packaging Market
Active & Intelligent Packaging
Ambient Packaging Market
Active & Intelligent Packaging
Multi-Sensory Packaging Market
Active & Intelligent Packaging
Middle East and Africa Active and Intelligent Packaging Market
Active & Intelligent Packaging
Global Advanced Packaging Technologies Market
Active & Intelligent Packaging
Isothermal Packaging Market
Active & Intelligent Packaging
Global Augmented Reality Packaging Market
Active & Intelligent Packaging
Active and Modified Atmosphere Packaging Market
Active & Intelligent Packaging
North America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Gel Packs Market
Active & Intelligent Packaging
ASEAN and Gulf Countries MAP and VSP Packaging Market
Active & Intelligent Packaging
Heat Sensitive Cups Market