
 North America Active and Intelligent Packaging Market | 2026-2036
North America Active and Intelligent Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Active and Intelligent Packaging Market Analytics
Pharmaceutical cold-chain logistics is broadening its share of active and intelligent packaging procurement as biologics and temperature-sensitive therapies expand across the United States and Canada. Amcor plc leverages its integrated film and container manufacturing footprint to supply multi-layer barrier systems with embedded RFID temperature loggers. Sealed Air Corporation anchors North American distribution through its automated packaging equipment paired with intelligent film technologies. BASF SE competes via its specialty polymer additives that enable oxygen-scavenging and moisture-control active layers.
Active and intelligent packaging encompasses systems that interact with packaged contents or external environments to monitor, record, communicate, or modify conditions, incorporating functional additives, printed electronics, or microelectromechanical sensors typically operating across temperature ranges from -80°C to +60°C and humidity thresholds below 5% relative humidity for pharmaceutical applications. Intelligent Packaging leads technology adoption where RFID-enabled track-and-trace systems command premium positioning due to FDA DSCSA compliance deadlines and pharmaceutical serialization requirements. Modified Atmosphere Packaging sustains mature volume in fresh protein and prepared foods across Plastic substrates, which dominate material selection for their barrier tunability and sensor integration compatibility.
The FDA enforces pharmaceutical serialization and traceability standards that directly mandate machine-readable smart labels for prescription drug distribution, while the EPA regulates volatile organic compound emissions from adhesive and coating processes used in intelligent label manufacturing. Health Canada and PMRA coordinate parallel cold-chain integrity requirements for cross-border biologics shipments, creating dual-compliance design constraints for packaging suppliers. Stakeholders must monitor evolving state-level extended producer responsibility legislation in California and New York that will reshape material recovery obligations for embedded electronic packaging components.
Market Dynamics
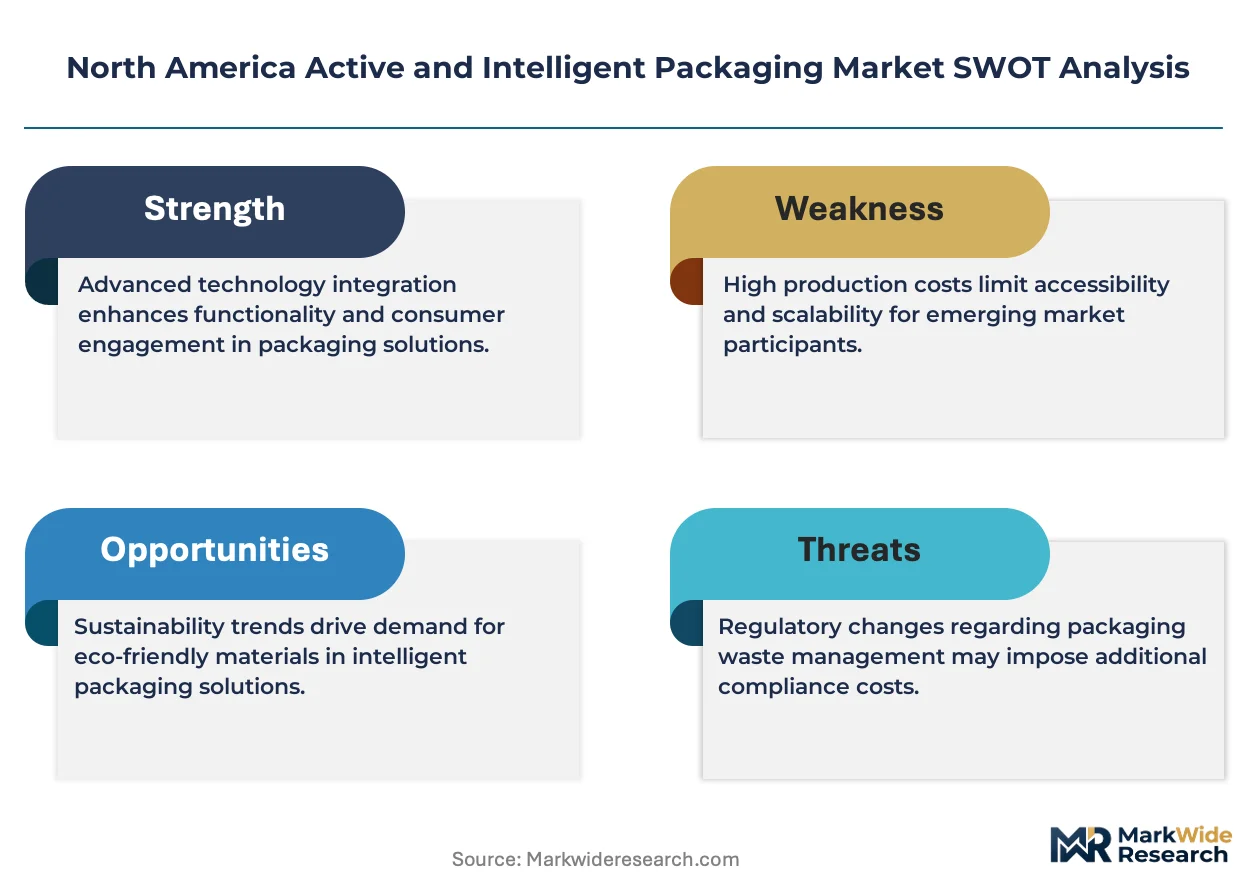
FDA DSCSA serialization deadlines are compressing implementation timelines for pharmaceutical distributors across the United States and Canada, forcing simultaneous upgrades to labeling infrastructure and cold-chain monitoring systems.
Growth Catalysts
- Biologics expansion:Cell and gene therapies requiring ultra-low temperature storage are multiplying demand for RFID-enabled temperature loggers in the Great Lakes corridor.
- FSMA traceability mandates:The FDA's enhanced record-keeping requirements for high-risk foods are accelerating smart label adoption among protein processors.
- Printed sensor substrates:Advances in flexible electronics manufacturing are reducing unit costs for time-temperature indicators in cross-border Canadian shipments.
Market Restraints
- Silver and copper feedstock volatility:Conductive ink formulations depend on precious metal prices that swing unpredictably, squeezing printed electronics margins.
- Single-source RFID inlay concentration:Three suppliers control North American antenna manufacturing, creating vulnerability for label converters.
- California EPR legislation:Extended producer responsibility rules for embedded batteries and circuits are adding compliance overhead without federal harmonization.
Strategic Opportunities
- Canadian cannabis cold-chain:Provincial distributors in Ontario and British Columbia are mandating track-and-trace packaging for THC-infused edibles and extracts.
- Printed electrochemical sensors:Integration of gas-sensing films with QR-code readability is opening food freshness monitoring for mid-tier retailers.
- USDA bio-based procurement preferences:Federal purchasing guidelines favor active packaging derived from agricultural feedstocks, creating specification advantages.
Industry Challenges
- Electronics-embedded packaging design talent:Few packaging engineers possess dual competency in polymer science and circuit layout, slowing product development cycles.
- Multi-jurisdiction serialization alignment:Reconciling FDA unit-level requirements with Health Canada's lot-based systems demands redundant label architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Active and Intelligent Packaging Market |
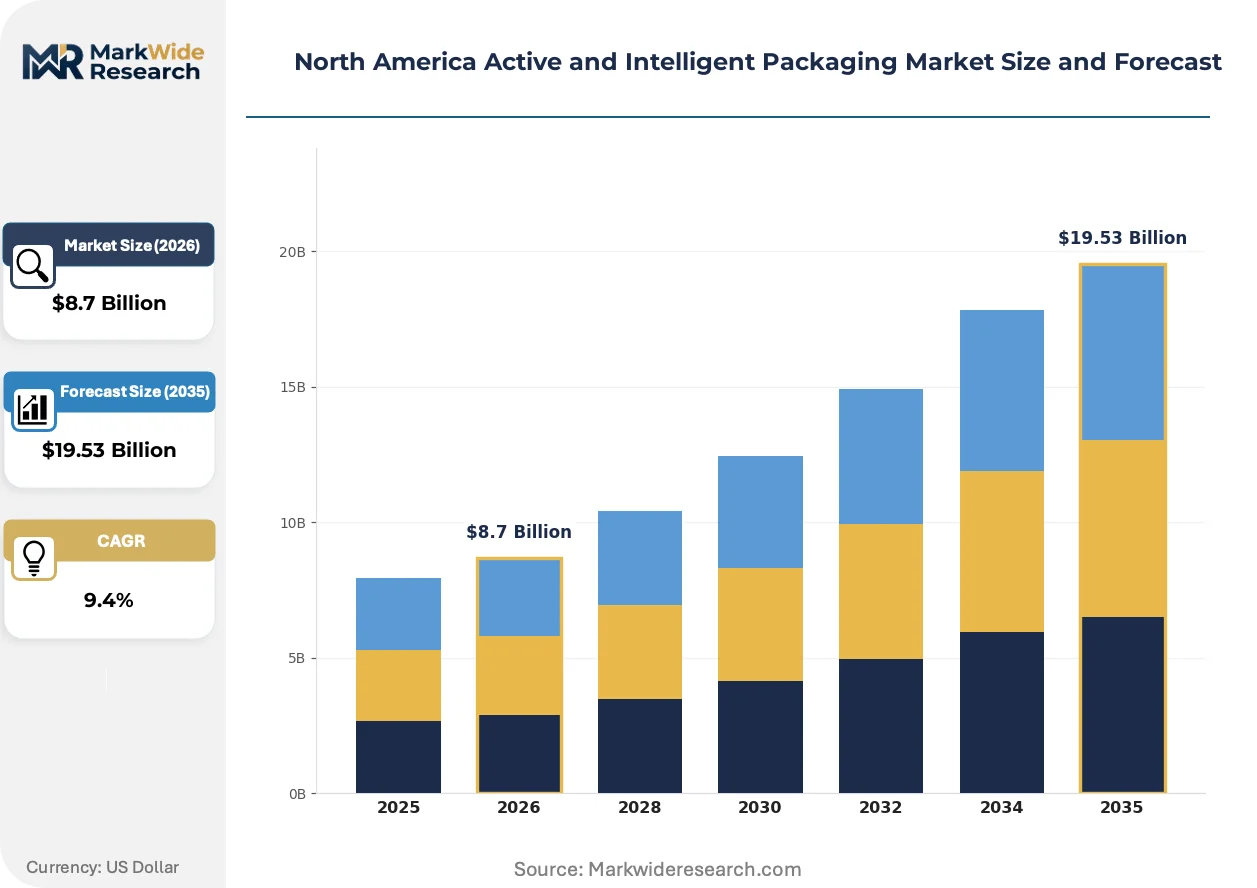
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Packaging, Intelligent Packaging, Modified Atmosphere Packaging, Smart Labels End User: Food & Beverage, Healthcare, Electronics, Consumer Goods Material: Plastic, Metal, Paper, Composites Technology: RFID, QR Codes, Sensors, NFC |
| Companies Covered | Amcor plc, BASF SE, Sealed Air Corporation, Avery Dennison Corporation, Sonoco Products Company, DuPont, Honeywell International Inc., Crown Holdings Inc., WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Active and Intelligent Packaging Market Evolving Landscape
Printed sensor technologies are merging with conventional barrier films to create single-structure solutions that eliminate separate data logger attachments. This convergence is compressing equipment footprints and reducing material layers.
Flexible printed electronics is converging with multi-layer coextrusion processes to embed temperature and humidity sensing directly into pharmaceutical blister lidding. Contract packagers in Illinois and New Jersey are adopting these integrated structures to eliminate secondary label application steps. The technology is converging with high-speed form-fill-seal lines, enabling real-time data transmission without line speed penalties.
The FDA's Food Traceability Final Rule is mandating electronic sortable records for leafy greens, nut butters, and ready-to-eat products by November 2026. Compliance investments are cascading through co-packing networks, with third-party logistics providers in California and Texas upgrading warehouse management systems to capture smart label data streams. Fresh produce distributors are responding by pre-qualifying packaging suppliers based on interoperability with GS1 standards.
Pharmaceutical buyers are consolidating vendor relationships from multiple specialty converters to single-source partners capable of delivering both active barrier films and intelligent label integration. This consolidation is displacing fragmented procurement models that separated primary packaging from data-capture components. The shift is most visible among mid-sized generic manufacturers in Ohio and Pennsylvania seeking to streamline qualification audits.
North America Active and Intelligent Packaging Market Segmentation
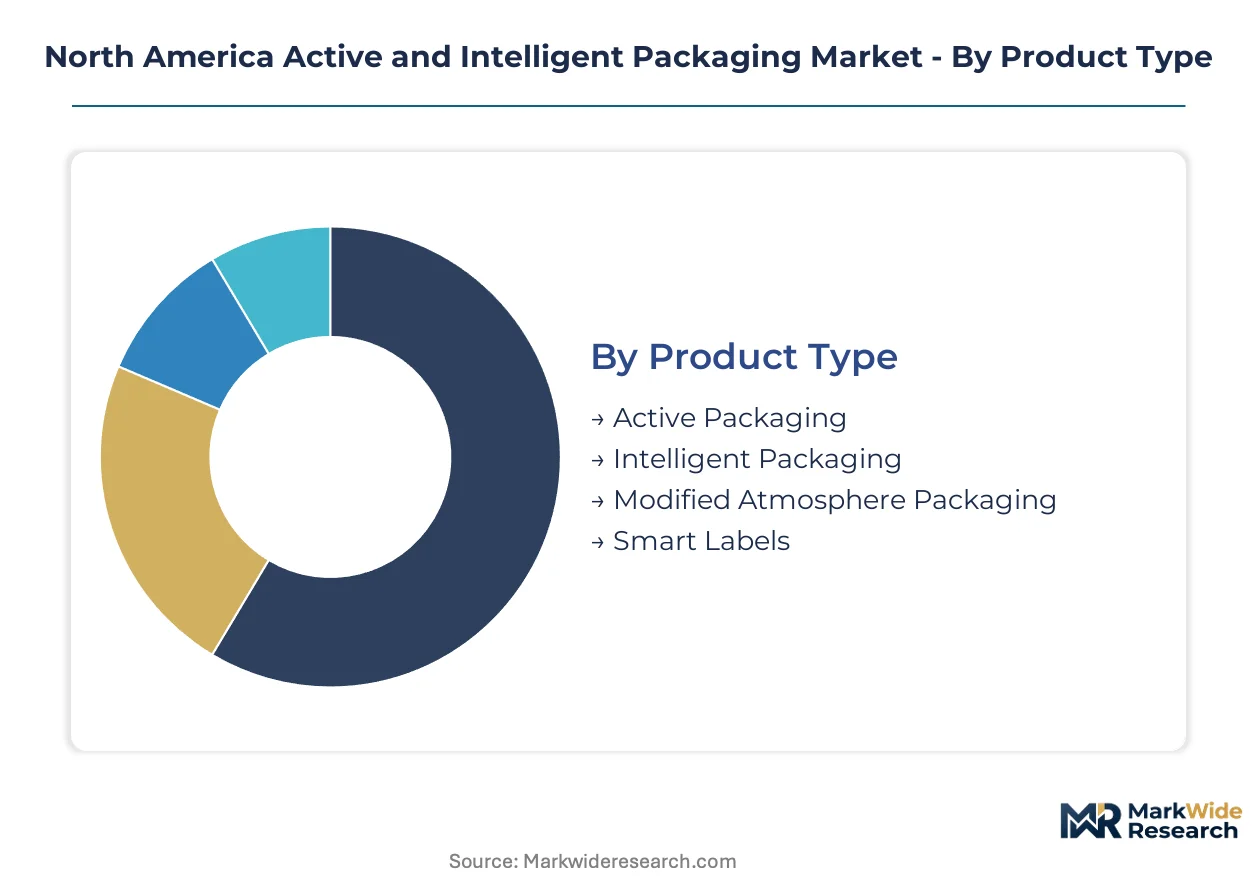
Active and intelligent packaging in North America exhibits distinct performance profiles across technology platforms, end-use verticals, and material substrates. Understanding these segment boundaries enables suppliers to align R&D investment with regulatory compliance windows and procurement consolidation trends reshaping buyer-seller relationships.
Product Type:
Technology specifications differentiate functional capabilities from passive barrier properties to real-time environmental responsiveness.
- Active Packaging:Oxygen scavengers, moisture absorbers, and ethylene removers embedded in polymer matrices extend shelf life for fresh proteins. FDA FSMA traceability mandates are accelerating adoption among Great Lakes meat processors seeking to reduce spoilage claims.
- Intelligent Packaging:RFID-enabled track-and-trace systems with temperature logging capabilities dominate pharmaceutical cold-chain applications. Health Canada and FDA dual-compliance requirements for cross-border biologics shipments are compressing implementation timelines for distributors.
- Modified Atmosphere Packaging:Gas-flush barrier systems with CO2/N2 equilibrium control protect ready-to-eat salads and prepared foods. Midwest co-packers in Illinois and Ohio are upgrading form-fill-seal lines to integrate MAP with smart label compatibility.
- Smart Labels:Printed time-temperature indicators and NFC-enabled authentication tags attach to existing primary packaging. California and New York state-level extended producer responsibility legislation is adding compliance overhead for embedded electronic components.
Intelligent Packaging leads on scale; Smart Labels lead on momentum.
End User:
Application intensity varies sharply by sector regulatory burden and product perishability.
- Food & Beverage:Protein processors and fresh produce distributors deploy modified atmosphere and time-temperature monitoring to satisfy FDA Food Traceability Final Rule requirements for leafy greens and nut butters. GS1 standard interoperability is becoming a pre-qualification criterion for packaging supplier selection.
- Healthcare:Cell and gene therapy manufacturers in the Great Lakes corridor require ultra-low temperature RFID loggers operating at -80°C. Pharmaceutical serialization under FDA DSCSA deadlines is forcing simultaneous infrastructure upgrades for labeling and cold-chain monitoring.
- Electronics:Humidity-indicating desiccant packs with color-change indicators protect semiconductors during Great Lakes-to-Texas logistics corridors. ESD-sensitive component manufacturers specify active moisture control for extended warehouse storage.
- Consumer Goods:NFC-enabled authentication tags combat counterfeiting in cosmetics and premium spirits. California cannabis distributors mandate track-and-trace packaging for THC-infused products under provincial regulations in Ontario and British Columbia.
Healthcare commands premium pricing; Food & Beverage dominates procurement volume.
Material:
Substrate selection determines sensor integration compatibility and barrier tunability.
- Plastic:Multi-layer coextruded films with embedded printed electronics dominate pharmaceutical blister lidding. Illinois and New Jersey contract packagers are adopting integrated plastic structures to eliminate secondary label application steps.
- Metal:Aluminum lidding with RFID inlay compatibility serves high-barrier pharmaceutical applications. Precious metal feedstock volatility in conductive ink formulations is squeezing printed electronics margins.
- Paper:Fiber-based substrates with printed electrochemical sensors enable gas-sensing freshness indicators for mid-tier retailers. USDA bio-based procurement preferences favor agricultural feedstock-derived active packaging.
- Composites:Hybrid plastic-paper-metal laminates balance barrier performance with sustainability credentials. California extended producer responsibility rules are reshaping material recovery obligations for complex multi-substrate structures.
Plastic anchors current deployment; Paper is climbing the fastest on sustainability-driven specification shifts.
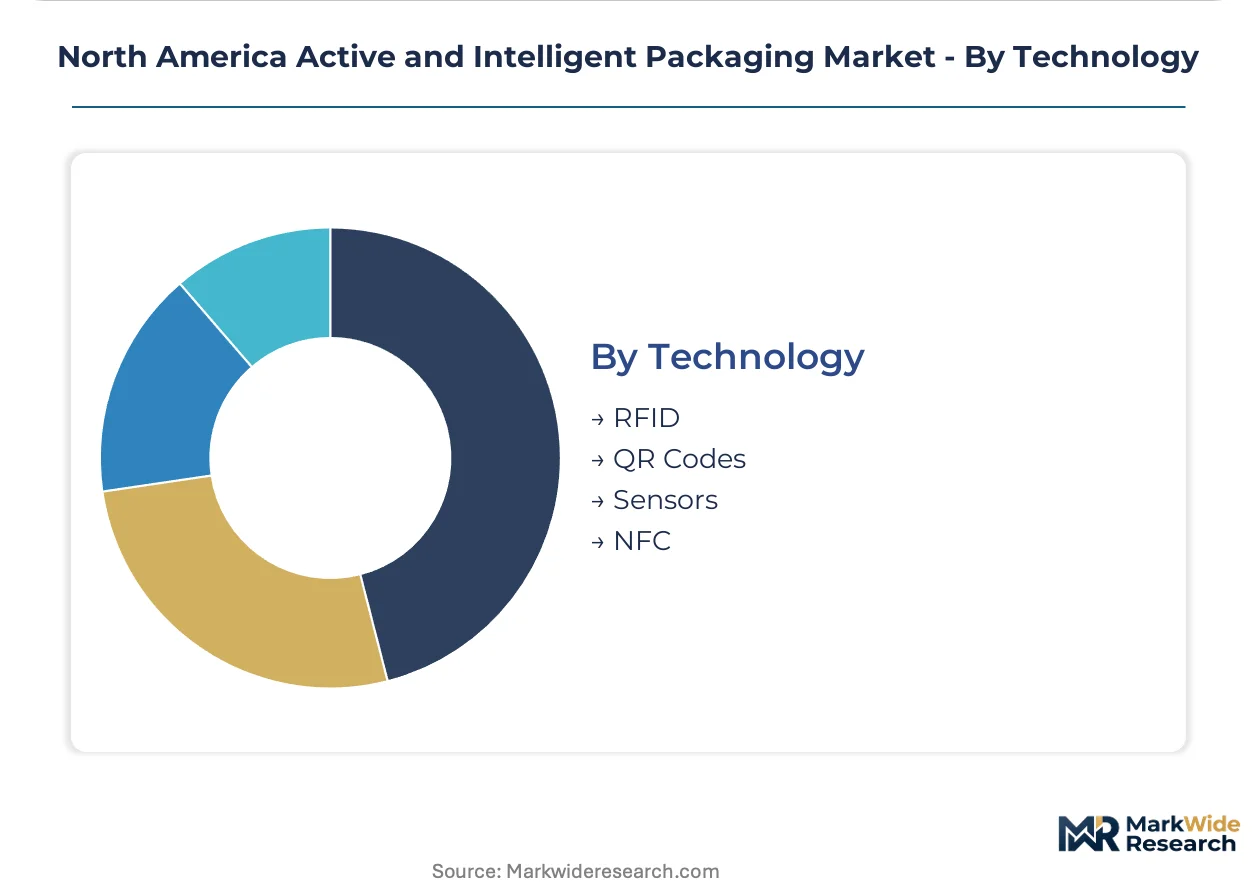
Technology:
Data capture and transmission protocols segment by infrastructure requirements and unit economics.
- RFID:UHF and HF inlays with temperature logging capabilities satisfy pharmaceutical serialization mandates. Three suppliers control North American antenna manufacturing, creating supply vulnerability for label converters.
- QR Codes:Optical readability without specialized hardware enables consumer-facing freshness applications. Integration with printed electrochemical sensors is opening food monitoring for cost-sensitive retail tiers.
- Sensors:Flexible printed electronics with humidity and gas-sensing films merge with conventional barrier films. Advances in manufacturing are reducing unit costs for time-temperature indicators in cross-border Canadian shipments.
- NFC:Near-field communication enables smartphone-readable authentication and temperature logs. Ontario and British Columbia cannabis distributors are mandating NFC track-and-trace for provincial supply chains.
RFID leads on compliance-driven revenue; NFC is expanding most quickly on consumer engagement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting packaging procurement toward jurisdictions with harmonized compliance frameworks, as manufacturers seek to avoid the cost penalties of dual-track certification for cross-border shipments between the United States and Canada.
United States
FDA DSCSA serialization deadlines and FSMA traceability mandates are compressing implementation timelines for pharmaceutical distributors and food processors. The EPA regulates volatile organic compound emissions from adhesive processes used in intelligent label manufacturing. Contract packagers in Illinois and New Jersey are adopting integrated plastic structures with embedded printed electronics to eliminate secondary label application steps.
Canada
Health Canada and PMRA coordinate cold-chain integrity requirements for cross-border biologics shipments, creating dual-compliance design constraints for packaging suppliers. Provincial distributors in Ontario and British Columbia mandate track-and-trace packaging for THC-infused cannabis products under provincial regulations. Advances in flexible electronics manufacturing are reducing unit costs for time-temperature indicators in cross-border Canadian shipments.
Mexico
Nearshoring of pharmaceutical and electronics manufacturing is expanding demand for temperature-monitoring packaging solutions in the Mexico City Metro and Bajío Region industrial corridors. The country's national pharmaceutical regulator aligns with FDA traceability standards for export-oriented production. Fresh produce distributors in Sinaloa and Jalisco are deploying modified atmosphere packaging with smart label compatibility for US-bound shipments.
North America Active and Intelligent Packaging Market Competitive Landscape
Consolidation of vendor relationships dominates the current landscape as pharmaceutical buyers shift from fragmented procurement models toward single-source partners capable of delivering both active barrier films and intelligent label integration. The market structure exhibits tiered concentration with multinational material suppliers, specialized packaging converters, and printed electronics specialists occupying distinct strategic positions. Two archetypes define competitive positioning: integrated film-and-sensor manufacturers and equipment-anchored solution providers. M&A activity and portfolio diversification represent the dominant competitive moves as players seek to bridge capability gaps between polymer science and circuit layout competencies.
Within the integrated material supplier tier, Amcor plc and BASF SE exemplify archetypes combining polymer manufacturing with functional additive capabilities. Sealed Air Corporation anchors the equipment-integrated segment through automated packaging machinery paired with intelligent film technologies. These three entities represent divergent strategic postures—material-led vertical control versus equipment-driven system integration—reflecting the market's bifurcation between substrate innovation and line-speed optimization.
| Leading Market Players |
|---|
| Amcor plc |
| BASF SE |
| Sealed Air Corporation |
| Avery Dennison Corporation |
| Sonoco Products Company |
| DuPont |
| Honeywell International Inc. |
| Crown Holdings Inc. |
| WestRock Company |
| Others |
Value Network & Pricing Analysis
California's extended producer responsibility legislation for embedded batteries and circuits gates qualified supply access and premium-tier pricing power for active and intelligent packaging converters serving pharmaceutical and food traceability mandates across the United States and Canada.
Pricing Analysis
Distributor margins in the pharmaceutical cold-chain segment absorb significant cost pressure from RFID inlay concentration, where three suppliers control North American antenna manufacturing. Three-tier pricing structure across premium, standard, and economy levels separates FDA DSCSA-compliant serialization systems from basic time-temperature indicators and entry-level QR-code freshness tags. Cost compression in printed electronics stems from silver and copper feedstock volatility squeezing conductive ink margins. Generic pharmaceutical manufacturers in Ohio and Pennsylvania exhibit highest price sensitivity due to procurement consolidation pressures, while cell and gene therapy developers accept premium positioning for ultra-low temperature logging capabilities.
Supply Chain Analysis
Returns and refurbishment flows for embedded electronic packaging components remain underdeveloped as California and New York extended producer responsibility rules reshape material recovery obligations without federal harmonization. Manufacturing concentration spans the United States for pharmaceutical blister lidding with embedded printed electronics, Canada for cross-border biologics cold-chain solutions, and Mexico for nearshored electronics assembly serving US-bound produce shipments. Raw material dependencies center on specialty polymer additives from BASF SE, conductive ink formulations drawing from precious metal feedstocks, and multi-layer coextrusion equipment anchored in Illinois and New Jersey contract packaging facilities. Single-source vulnerability in RFID antenna manufacturing creates supply risk for label converters. Distribution runs through co-packing networks in the Great Lakes corridor and third-party logistics providers upgrading warehouse management systems for GS1 standard interoperability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in active and intelligent packaging rests on printed sensor substrate cost-down curves and pharmaceutical buyer consolidation toward single-source partners capable of delivering integrated barrier films and intelligent label systems.
For Market Incumbents: Lock in long-term supply agreements with the three dominant RFID antenna manufacturers to neutralize single-source vulnerability before new entrants capture pharmaceutical procurement consolidation waves. Deepen backward integration into specialty polymer additive production to match BASF SE's oxygen-scavenging capabilities and defend against equipment-anchored competitors like Sealed Air Corporation. Prioritize dual FDA-Health Canada compliance certification to capture cross-border biologics shipments where dual-track requirements currently fragment vendor relationships. For New Entrants and Emerging Players: The premium-to-economy tier price gap in printed time-temperature indicators offers entry space for flexible electronics specialists targeting mid-tier food retailers with QR-code-integrated gas-sensing freshness monitors. Canadian provincial cannabis distributors in Ontario and British Columbia present the most penetrable regulatory-mandated segment with track-and-trace packaging requirements still consolidating supplier bases. Lead with USDA bio-based procurement preference positioning to differentiate against petroleum-derived incumbent offerings in federal purchasing channels. For Investors and Strategic Acquirers: Roll-up economics work for printed electronics specialists because pharmaceutical buyers are consolidating from fragmented multi-vendor procurement toward single-source partners, creating scalable platform value in combining polymer science and circuit layout competencies. Target acquisition archetypes include flexible printed electronics manufacturers with FDA Master File experience and mid-sized label converters possessing Health Canada establishment licenses. Monitor FDA DSCSA enforcement discretion signals and Health Canada serialization alignment negotiations as inflection indicators for cross-border compliance harmonization that would eliminate redundant label architecture costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Polymer Additives | Captures margin from oxygen-scavenging and moisture-control active layers that BASF SE currently dominates. |
| Dual FDA-Health Canada Compliance Certification | Eliminates redundant label architectures for cross-border biologics shipments between Michigan and Ontario corridors. |
| Printed Electrochemical Sensor Platform Launch | Opens QR-code-integrated food freshness monitoring for cost-sensitive mid-tier retailers seeking FSMA compliance. |
| Strategic Partnership with RFID Antenna Manufacturers | Neutralizes supply vulnerability from three-supplier concentration in North American inlay manufacturing. |
| Sustainability Repositioning via Bio-Based Substrates | Aligns with USDA federal purchasing preferences and California extended producer responsibility compliance requirements. |
Research Methodology
Direct dialogue with pharmaceutical packaging procurement directors, contract packager operations managers in Illinois and New Jersey, flexible printed electronics R&D leads, and FDA regulatory affairs consultants grounded qualitative insights for this analysis. Secondary validation drew from FDA DSCSA guidance documents, Health Canada ICH Q9 quality risk management filings, EPA volatile organic compound emission standards for adhesive processes, and GS1 US healthcare traceability implementation resources. Bottom-up triangulation across technology platform adoption curves and top-down reconciliation with pharmaceutical cold-chain logistics expenditure patterns ensured segmentation integrity.
Segmented outputs across the projection horizon reflect technology platform splits between active packaging, intelligent packaging, modified atmosphere packaging, and smart labels; end-use verticals spanning food and beverage, healthcare, electronics, and consumer goods; material substrates including plastic, metal, paper, and composites; and geographic clusters within the United States, Canada, and Mexico. CAGRs were derived from regression analysis of historical pharmaceutical serialization investment cycles and printed electronics unit cost decline curves. Forecast inputs incorporated FDA Food Traceability Final Rule compliance deadlines and provincial cannabis track-and-trace mandate implementation timelines.
Caveats apply where precious metal feedstock volatility, single-source RFID inlay supply disruption, or state-level extended producer responsibility rule fragmentation could materially shift the outlook for printed electronics cost curves and compliance-driven procurement timing. Practitioners should monitor FDA DSCSA enforcement discretion announcements, Health Canada serialization system alignment negotiations, and California EPR rulemaking progress for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Active & Intelligent Packaging
Global Internet of Packaging Market
Active & Intelligent Packaging
Easy Open Packaging Market
Active & Intelligent Packaging
Active Packaging Market
Active & Intelligent Packaging
United Arab Emirates Packaging Market
Active & Intelligent Packaging
Connected Packaging Market
Active & Intelligent Packaging
Multi-Sensory Packaging Market
Active & Intelligent Packaging
Global Controlled Intelligent Packaging Market
Active & Intelligent Packaging
Ambient Packaging Market
Active & Intelligent Packaging
Highly Visible Packaging Market
Active & Intelligent Packaging
High-End Performance Packaging Market
Active & Intelligent Packaging
Active Smart and Intelligent Packaging Market
Active & Intelligent Packaging
Global Augmented Reality Packaging Market
Active & Intelligent Packaging
Active and Modified Atmosphere Packaging Market
Active & Intelligent Packaging
Heat Sensitive Cups Market
Active & Intelligent Packaging
Middle East and Africa Active and Intelligent Packaging Market
Active & Intelligent Packaging
Gel Packs Market