
 Intelligent PDU Market | 2026-2036
Intelligent PDU Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent PDU Market Intelligence
The European Union's updated Energy Efficiency Directive is rebalancing the competitive landscape for data center power infrastructure. Schneider Electric SE leverages its EcoStruxure platform for integrated power management. Vertiv Group Corp specializes in thermal and power solutions for hyperscale clients. Eaton Corporation plc differentiates through its cybersecurity-certified intelligent PDUs.
An intelligent Power Distribution Unit is a networked device distributing electric power to rack-mounted equipment while enabling remote control. These units provide real-time monitoring of voltage, current, and power consumption at the individual outlet level. Switched and Monitored PDU product types are seeing high adoption in new data center builds. While Colocation Centers are a mature application, Edge Computing Facilities represent a significant new growth vector.
International Electrotechnical Commission (IEC) standard 62368-1 governs safety requirements for IT and AV equipment. The European Union's RoHS directive restricts hazardous substances, while the US EPA's ENERGY STAR program encourages energy efficiency in data center components. Vendor success depends on aligning product roadmaps with the distinct power density and remote management needs of hyperscale versus edge deployments.
Market Dynamics
The convergence of stringent energy efficiency regulations and the escalating power density demands of hyperscale computing defines the market's central dynamic. This dual pressure forces data center operators to invest in granular power monitoring and remote control capabilities, directly benefiting intelligent PDU adoption.
Growth Catalysts
- Regulatory Mandates:The EU's Corporate Sustainability Reporting Directive (CSRD) compels large enterprises to disclose energy consumption and carbon footprints, accelerating investment in intelligent PDUs for accurate data collection and reporting.
- Hyperscale Infrastructure Build-Out:The rapid construction of hyperscale data centers, particularly concentrated in the United States, requires advanced power distribution solutions to manage high-density server racks and optimize power usage effectiveness (PUE).
- Edge Computing Expansion:The proliferation of edge computing facilities creates demand for remotely managed PDUs that can be controlled and monitored from a central location, reducing operational overhead for distributed IT infrastructure.
Market Restraints
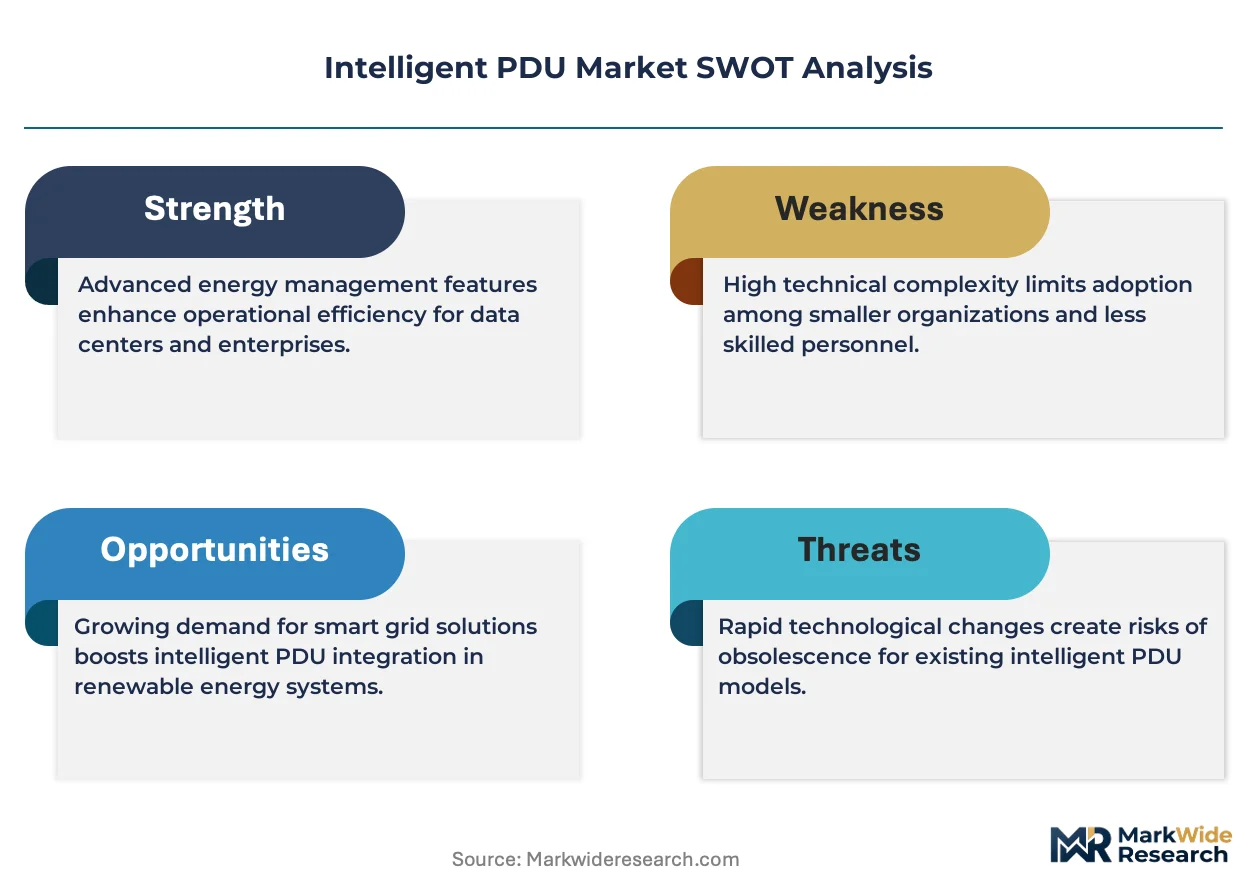
- Higher Upfront Cost:The initial capital expenditure for intelligent PDUs is significantly higher than for basic power strips, posing a financial barrier for small to medium-sized enterprises and projects with constrained budgets.
- Integration with Legacy Systems:Complexities in integrating modern intelligent PDUs with older Data Center Infrastructure Management (DCIM) software can create interoperability issues and deter upgrades in established facilities.
- Component Supply Chain Concentration:A heavy reliance on a few specific regions in Asia for critical electronic components and semiconductors exposes the PDU supply chain to geopolitical risks and potential disruptions.
Strategic Opportunities
- Liquid Cooling Integration:The emergence of direct-to-chip and immersion liquid cooling in high-performance computing creates an opportunity for specialized PDUs designed to monitor and manage the unique power requirements of these systems.
- Energy Efficiency Incentives:Government programs like the US EPA's ENERGY STAR for data center equipment provide a tailwind, encouraging procurement of certified energy-efficient PDUs to meet sustainability goals and qualify for incentives.
- Emerging Data Center Hubs:Underpenetrated markets in Southeast Asia and Latin America represent significant growth vectors as cloud providers expand their regional presence, requiring new investments in advanced data center power infrastructure.
Industry Challenges
- Multi-Standard Compliance:Vendors face the operational challenge of designing and certifying products to meet a diverse array of global standards, including IEC 62368-1 for safety and the EU's RoHS directive for hazardous substances.
- Platform Interoperability:Ensuring seamless communication and interoperability between PDUs from different manufacturers and various third-party management software platforms remains a persistent challenge for data center operators managing mixed-vendor environments.
- Skilled Personnel Shortage:A deficit of technicians with hybrid expertise in both electrical power systems and IP networking complicates the deployment, configuration, and maintenance of sophisticated intelligent PDU networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent PDU Market |
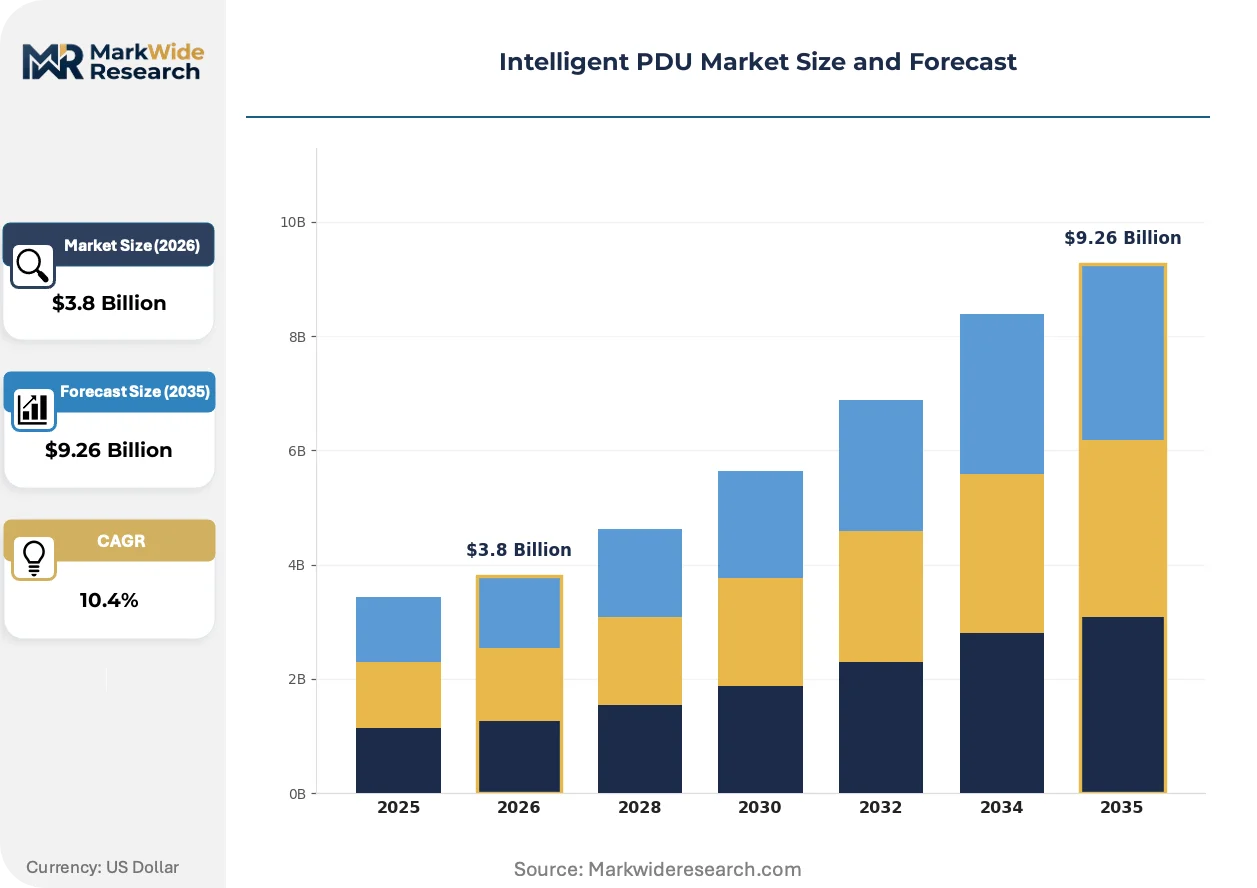
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $9.26 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metered PDU, Basic PDU, Switched PDU, Automatic Transfer Switch PDU, Monitored PDU Technology: SNMP, Modbus, HTTP/HTTPS, Telnet, Serial Communication Application: Data Centers, Colocation Centers, Network Closets, Telecom Rooms End User: Cloud Service Providers, Managed Service Providers, Telecommunication Companies, Edge Computing Facilities |
| Companies Covered | Legrand SA, ABB Ltd, Schneider Electric SE, Raritan, Inc., Cyber Power Systems, Inc., Eaton Corporation plc, Delta Electronics, Inc., Socomec SA, Vertiv Group Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent PDU Market Strategic Shifts & Innovations
The market's evolution is defined by the integration of software-defined control and advanced analytics directly into power distribution hardware. This shift transforms PDUs from passive components into active, data-generating nodes within the intelligent data center ecosystem, driven by sustainability and operational efficiency imperatives.
Onboard processing and AI-powered analytics represent a significant product evolution. This technology allows the PDU to perform real-time load balancing analysis and predictive failure detection at the edge, independent of a central DCIM platform. Hyperscale and financial services data centers are early adopters, seeking to maximize uptime and power efficiency. This embedded intelligence is automating routine power optimization tasks, freeing up data center staff to focus on more strategic initiatives.
The European Union's Energy Efficiency Directive (EED) is a powerful regulatory driver. It imposes strict requirements for data centers to monitor, measure, and report their energy consumption with high granularity. This directly increases the business case for deploying intelligent PDUs capable of outlet-level metering. Switched and Monitored PDU segments are experiencing heightened demand in the EU as operators upgrade infrastructure to ensure compliance and avoid penalties.
A notable demand-side shift involves the move from one-time hardware purchases to more flexible, service-oriented procurement models. This trend disrupts the traditional reseller channel, as some vendors and managed service providers begin to offer PDU hardware bundled with ongoing software updates and remote monitoring services. This "PDU-as-a-Service" approach is most prominent within the colocation sector, where tenants value predictable operational expenses over large capital outlays.
Intelligent PDU Market Segmentation
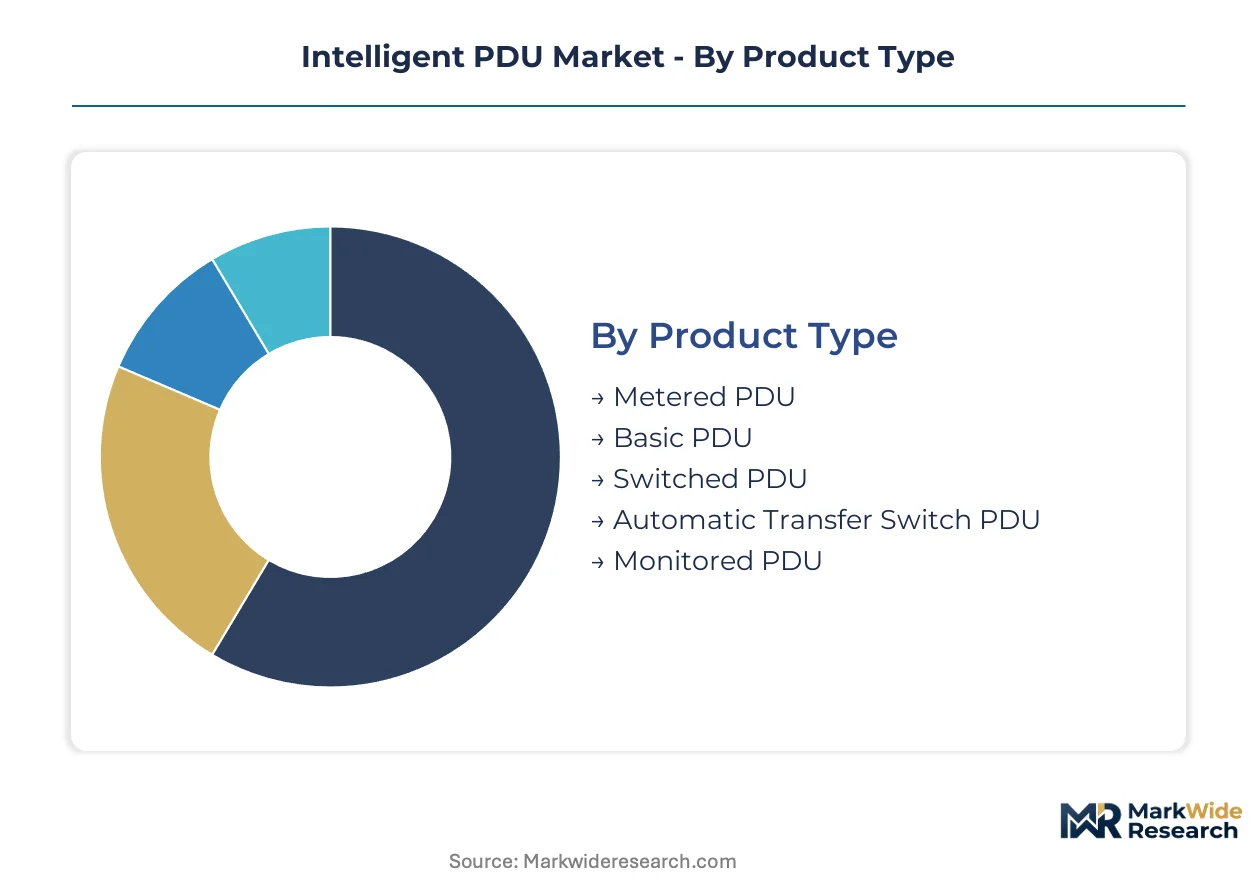
The Intelligent PDU market delineates into several key segments, reflecting the diverse operational needs and technological preferences of data center environments. Understanding these distinctions is crucial for vendors to align product roadmaps with specific end-user requirements and evolving infrastructure demands. This segmentation illuminates where innovation and investment are most concentrated.
Product Type:
Buyers in the Intelligent PDU market prioritize distinct functionalities, ranging from basic power distribution to advanced remote control and granular monitoring capabilities.
- Switched PDU:These units offer individual outlet control, allowing remote power cycling of connected equipment, which is critical for managing distributed IT infrastructure. Demand concentrates in edge computing facilities and hyperscale data centers, reducing operational costs.
- Monitored PDU:These PDUs provide aggregated and outlet-level power consumption data, enabling data center operators to track energy usage and optimize power efficiency. Hyperscale data centers adopt these units to meet stringent PUE targets.
- Metered PDU:These units offer aggregated current, voltage, and power monitoring at the PDU level, supporting overall rack-level energy management.
- Basic PDU:These provide reliable power distribution without advanced monitoring or remote control, serving cost-sensitive applications in smaller network closets.
- Automatic Transfer Switch PDU:These devices ensure continuous power by automatically switching to a secondary power source upon primary failure, enhancing redundancy for critical IT loads.
Basic PDU leads volumes today; Switched PDU is gaining share fastest.
Technology:
Different communication protocols define how intelligent PDUs integrate into diverse network architectures, catering to varying customer IT environments and security requirements.
- SNMP:Simple Network Management Protocol is widely used for monitoring and managing network devices, including intelligent PDUs, within enterprise data centers. Its broad compatibility drives adoption in IT infrastructure.
- HTTP/HTTPS:These web-based protocols enable secure remote access and management of PDU interfaces through standard web browsers, simplifying configuration and monitoring for technicians. Cloud service providers favor HTTPS for encrypted communication.
- Modbus:This serial communication protocol is prevalent in industrial control systems, integrating PDUs into specialized facility management systems.
- Telnet:An older network protocol, Telnet offers command-line interface access for PDU management, though its unencrypted nature limits its use in secure environments.
- Serial Communication:Direct serial connections via RS-232 or RS-485 offer reliable local PDU management, used for initial setup or without IP connectivity.
SNMP maintains a dominant position; HTTP/HTTPS adoption shows the steepest expansion trajectory.
Application:
The volume and density of IT equipment within an environment directly influence the type and sophistication of intelligent PDU solutions required.
- Data Centers:These facilities house large-scale computing infrastructure, driving demand for high-density, remotely managed PDUs that optimize power distribution and energy efficiency. Hyperscale data centers in the United States are significant consumers.
- Colocation Centers:These facilities lease space and infrastructure, requiring intelligent PDUs for granular power monitoring and billing, ensuring fair resource allocation. European colocation providers deploy advanced PDUs for EU Energy Efficiency Directive compliance.
- Network Closets:Smaller IT environments in office buildings, these require basic intelligent PDUs for remote power cycling and environmental monitoring.
- Telecom Rooms:These spaces house telecommunications equipment, utilizing intelligent PDUs for reliable power delivery and remote diagnostics of network gear.
Data Centers consume the largest share; Network Closets are experiencing steady growth.
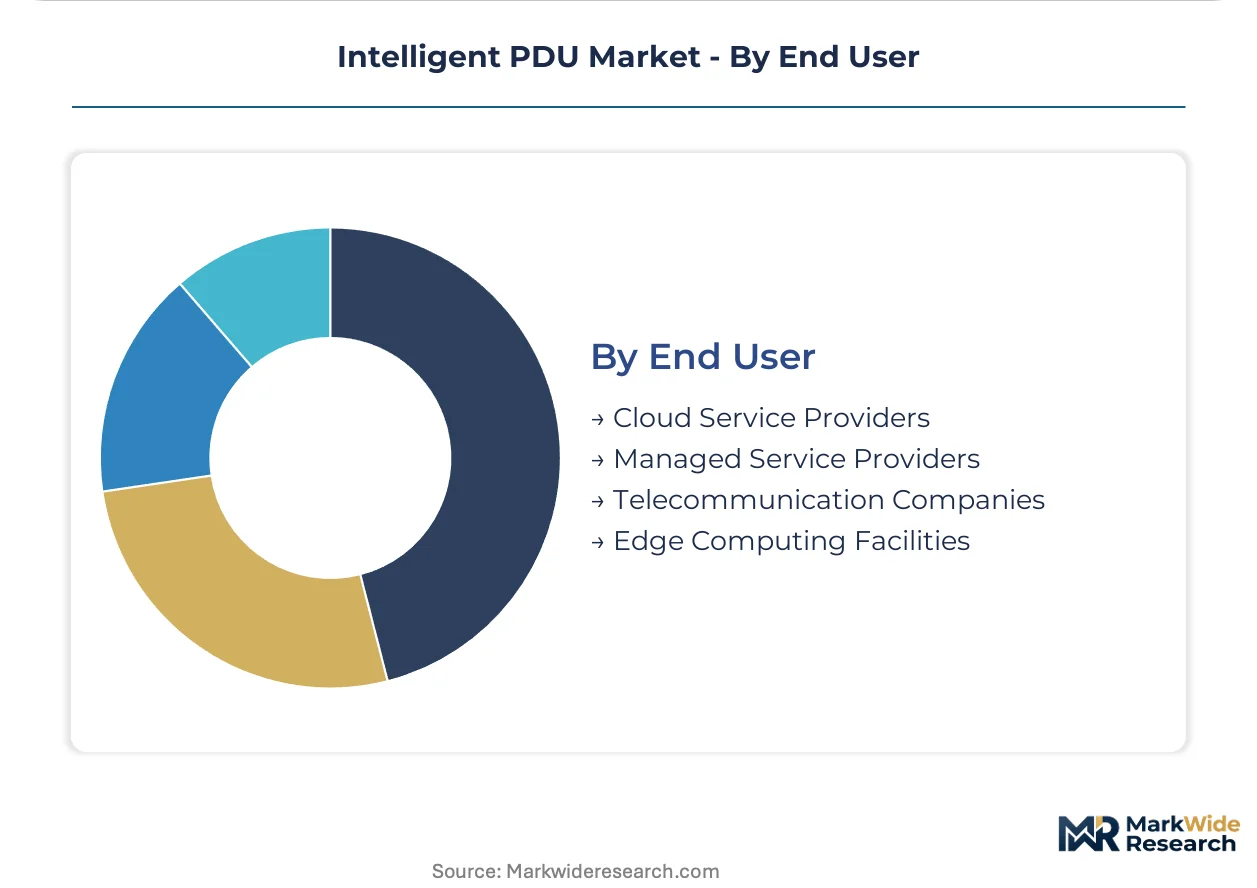
End User:
The maturity of an end user's IT infrastructure and their operational model dictates the specific intelligent PDU features and service levels they require.
- Cloud Service Providers:These entities operate massive, distributed data centers, requiring intelligent PDUs for dynamic load balancing, real-time power monitoring, and remote management. They demand high-density solutions for server rack utilization.
- Edge Computing Facilities:These distributed, smaller-scale sites require intelligent PDUs with robust remote control and monitoring capabilities to minimize on-site maintenance. Their proliferation creates demand for manageable solutions.
- Managed Service Providers:These companies leverage intelligent PDUs to offer clients enhanced uptime and transparent power usage reporting for hosted IT equipment.
- Telecommunication Companies:Telecom providers deploy intelligent PDUs in their central offices and cell tower sites for reliable power distribution and remote diagnostics of network equipment.
Cloud Service Providers constitute the largest end-user segment; Edge Computing Facilities are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A highly skilled technical workforce and robust digital infrastructure anchor significant demand for intelligent PDUs across key global markets. Data center operators seek advanced power management solutions to meet rising power density requirements and stringent energy efficiency mandates. This drives investment in regions with mature IT ecosystems and expanding cloud infrastructure.
United States
The United States leads demand for intelligent PDUs, driven by extensive hyperscale data center construction and rapid edge computing expansion. The US EPA's ENERGY STAR program encourages the procurement of certified energy-efficient PDUs, aligning with sustainability objectives. Major data center hubs like Northern Virginia and Silicon Valley are concentrating investments in advanced power distribution.
Germany
Germany's intelligent PDU market responds to strict EU regulations, particularly the Energy Efficiency Directive, which mandates granular energy monitoring and reporting. The EU's Corporate Sustainability Reporting Directive also compels enterprises to invest in accurate data collection for energy consumption. Data center clusters in Frankfurt and Berlin are upgrading infrastructure to ensure compliance and enhance operational efficiency.
China
China's rapid hyperscale cloud infrastructure build-out and extensive digital transformation initiatives create substantial demand for intelligent PDUs. The country's dual carbon goals and MIIT policies encourage energy-efficient data center operations. Major IT hubs in the Yangtze River Delta and Beijing-Tianjin-Hebei regions are seeing significant deployments of advanced power management solutions.
India
India represents a significant growth vector for intelligent PDUs as cloud service providers expand their regional presence and new data center hubs emerge. The National Digital Communications Policy promotes digital infrastructure development, indirectly boosting demand for reliable power solutions. Cities like Mumbai and Bengaluru are experiencing increased investment in advanced data center power infrastructure to support digital growth.
Intelligent PDU Market Key Industry Players
The competitive structure tilts toward established industrial technology giants and specialized power management providers. These entities command significant market share through extensive product portfolios, global distribution networks, and deep customer relationships. The landscape features a tiered mix, from multinational conglomerates offering integrated solutions to mid-sized specialists focusing on specific PDU functionalities. Key competitive moves include portfolio diversification into full-stack data center infrastructure, strategic partnerships for software integration, and geographic expansion into high-growth regions like Southeast Asia. Companies also prioritize technology licensing to accelerate innovation in areas such as AI-powered analytics.
Specialists in integrated power and thermal management solutions, Schneider Electric SE and Vertiv Group Corp, exemplify providers offering comprehensive data center infrastructure. Schneider Electric SE, a French multinational corporation, leverages its EcoStruxure platform for integrated power management across diverse environments. Vertiv Group Corp, headquartered in the United States, focuses on thermal and power solutions specifically for hyperscale clients. Eaton Corporation plc, an Irish-domiciled multinational power management company, occupies a strong position by differentiating through cybersecurity-certified intelligent PDUs. These players anchor the market's premium and high-performance segments, leveraging their long-standing expertise in critical power applications and advanced monitoring capabilities.
| Leading Market Players |
|---|
| Legrand SA |
| ABB Ltd |
| Schneider Electric SE |
| Raritan, Inc. |
| Cyber Power Systems, Inc. |
| Eaton Corporation plc |
| Delta Electronics, Inc. |
| Socomec SA |
| Vertiv Group Corp |
| Others |
Cost & Logistics Intelligence
Semiconductor component costs, influenced by global manufacturing hubs, directly impact intelligent PDU pricing across all tiers. This upstream cost pressure flows through to end-user acquisition prices, particularly for advanced, feature-rich units.
Pricing Analysis
The split between bundled hardware and ongoing service contracts defines the intelligent PDU market's pricing structure. This hybrid model combines per-unit transactional sales for hardware with subscription-based fees for software updates and remote monitoring. Price differentiation stems from the customization level required for hyperscale deployments and the certification level, such as ENERGY STAR compliance. Pricing pressure stems from increased competition in standard PDU segments, particularly from Asian manufacturers. Small to medium-sized enterprises are most price-sensitive, while hyperscale cloud providers are least sensitive due to their focus on performance and efficiency.
Supply Chain Analysis
Logistics and freight costs significantly influence the intelligent PDU supply chain, particularly for high-volume deployments. Geographic supply concentration for critical electronic components and assembly centers in China, Malaysia, and Vietnam remains high. The supply chain relies on semiconductors, passive electronic components, and copper cabling. Component supply chain concentration in Asia creates single-source vulnerability, exposing the market to geopolitical risks. Distribution runs through a mix of direct sales to large enterprises and value-added resellers for smaller clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Intelligent PDU market is transitioning into a late-cycle quality story. Demand shifts towards premium specifications, driven by hyperscale data centers requiring advanced, high-density power management solutions.
For Market Incumbents: Anchor existing customer relationships by expanding software-defined power management platforms. Invest in cybersecurity certifications to differentiate products against emerging pure-play software vendors offering PDU-agnostic analytics. Acquire specialized edge computing PDU providers to broaden market reach. Deepen R&D into AI-powered predictive maintenance to enhance platform capabilities.
For New Entrants and Emerging Players: A significant price-point gap exists between premium hyperscale-grade PDUs and basic rack power strips. Target mid-market colocation centers and distributed edge computing facilities, which represent the most penetrable segments. Offer PDU-as-a-Service models with predictable operational expenses to attract budget-conscious clients. Focus on robust remote management features to reduce operational overhead for distributed IT infrastructure.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized power management expertise intersects with software integration capabilities. The market offers stable, long-term growth driven by persistent data center expansion over the next decade. Target niche providers with proprietary AI analytics or robust cybersecurity features for critical infrastructure. Increased M&A activity involving software and hardware integration companies is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand EcoStruxure Platform Integration | Schneider Electric SE enhances its comprehensive data center management capabilities. |
| Invest in Cybersecurity Certifications | Eaton Corporation plc strengthens its differentiation in secure power distribution solutions. |
| Develop Edge-Optimized PDU Solutions | Vertiv Group Corp addresses the unique remote management needs of distributed IT infrastructure. |
| Offer PDU-as-a-Service Models | Vendors provide flexible procurement options, particularly for colocation tenants. |
| Advance AI-Powered Predictive Analytics | Companies enable real-time load balancing and proactive failure detection at the PDU level. |
Research Approach
Multiple input streams — primary interviews, secondary publications, and internal databases — were reconciled to construct a robust market view. This involved combining insights from data center operators, IT procurement managers, PDU engineers, and colocation facility managers with secondary data from SEC filings of public companies, industry association reports, and government energy efficiency programs. Bottom-up data validation with top-down market sizing ensured data consistency.
Data stream reconciliation formed the basis of the analytical framework applied across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical data trends and projected future demand drivers. Key forecast inputs included hyperscale data center construction pipelines and edge computing deployment forecasts.
Caveats apply where geopolitical disruptions or rapid technological shifts could materially shift the outlook. Forecasts reflect assumptions regarding component supply chain stability and the evolution of energy efficiency mandates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Portable Air Cooler Market
Energy Management Systems
Grid Optimization Solution Market
Energy Management Systems
Wi-Fi Smart Thermostat Market
Energy Management Systems
Bed Cooling System Market
Energy Management Systems
Global Next-Generation Building Energy Management Systems Market
Energy Management Systems
Smart Cooling Systems Market
Energy Management Systems
Outage Management System (OMS) Market
Energy Management Systems
Global Thermal Management Technologies Market
Energy Management Systems
North America Home Energy Management System (HEMS) Market
Energy Management Systems
Global Digital Thermostats Market
Energy Management Systems
Europe Home Energy Management System Market
Energy Management Systems
Building Energy Management Solution Market
Energy Management Systems
Grid Operations Management Software Market
Energy Management Systems
North America Energy Management Systems Market
Energy Management Systems
Smart Programmable Thermostat Market
Energy Management Systems
Airflow Management Market