
 Drinkware Market | 2026-2036
Drinkware Market Size, Share, and Industry Trends Forecast 2026-2036
Drinkware Market Intelligence
Asset-light leasing models for co-branded drinkware production is narrowing the capital barrier for mid-tier competitors. Hydro Flask leverages its vertical integration in vacuum-insulated manufacturing to sustain margin control across North American channels. Newell Brands anchors broad retail penetration through multi-brand portfolio scale, while YETI Holdings competes on premium positioning in outdoor and professional segments.
Drinkware comprises vessels designed for beverage containment, consumption, and temperature retention, typically constructed with double-wall vacuum insulation, borosilicate glass, or food-grade polymers rated for thermal shock resistance and chemical leaching prevention. The primary purpose spans domestic hydration, commercial foodservice, athletic use, and corporate branding applications. Stainless steel water bottles command the strongest margin pools due to durability premiums and sustainability positioning, while plastic mugs face structural decline as BPA restrictions tighten across jurisdictions. Online retail channels are capturing the fastest volume expansion, though specialty stores retain outsized influence in premium gift and corporate customization segments.
The FDA governs food-contact material safety and BPA migration limits for polymer-based drinkware sold in the United States, while the EPA tracks lifecycle impacts of disposable alternatives that drive reusable substitution. REACH compliance in Europe restricts phthalate and heavy metal content in imported vessels, creating certification friction for Asian manufacturers. California's Proposition 65 adds state-level warning requirements that shape labeling and material sourcing decisions. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to front-run compliance costs or absorb margin compression from reactive adaptation.
Market Dynamics
Stainless steel vacuum insulation technology is compressing production cycles and enabling mass customization at scale, forcing asset-heavy manufacturers to reconfigure fixed-cost structures or cede share to agile contract producers.
Growth Catalysts
- FDA BPA Migration Limits:Polymer-based drinkware faces mandatory testing protocols that accelerate stainless steel substitution in child-focused and athletic segments.
- California Proposition 65:Warning label mandates for heavy metal content reshape sourcing decisions, favoring domestic stainless steel suppliers over Asian polymer converters.
- Double-Wall Vacuum Insulation:Manufacturing process refinements reduce unit costs by 12-18% at volume, unlocking price points that penetrate mid-market hospitality procurement.
Market Restraints
- Raw Material Concentration:Nickel and chromium supply chains concentrate in Indonesian and Russian mining operations, exposing margin stability to geopolitical friction and export quota volatility.
- REACH Compliance Friction:European chemical registration requirements impose 18-24 month certification timelines on Asian polymer suppliers, constraining rapid product iteration for EU-bound volumes.
- Technical Limitation:Current laser engraving technology cannot achieve color fidelity on powder-coated stainless steel above 600 DPI, limiting premium customization margins in corporate gift segments.
Strategic Opportunities
- Extended Producer Responsibility Frameworks:EU and California take-back mandates create first-mover advantage for brands with closed-loop recycling infrastructure and material traceability systems.
- Smart Hydration Integration:Convergence of Bluetooth-enabled consumption tracking with vacuum-insulated vessels opens recurring-revenue models in employer wellness programs and insurance incentive schemes.
- Specialty Store Channel:Premium gift and customization segments retain outsized margin pools as online retail compresses standard SKU profitability, rewarding experiential retail partnerships.
Industry Challenges
- Certification Timeline Compression:Multi-jurisdiction food-contact safety approvals require parallel testing tracks that strain quality assurance staffing and delay seasonal product launches.
- Supply Chain Reconfiguration:Nearshoring initiatives demand retooling of automated welding and electropolishing lines, with 14-18 month capital recovery periods that conflict with quarterly earnings pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drinkware Market |
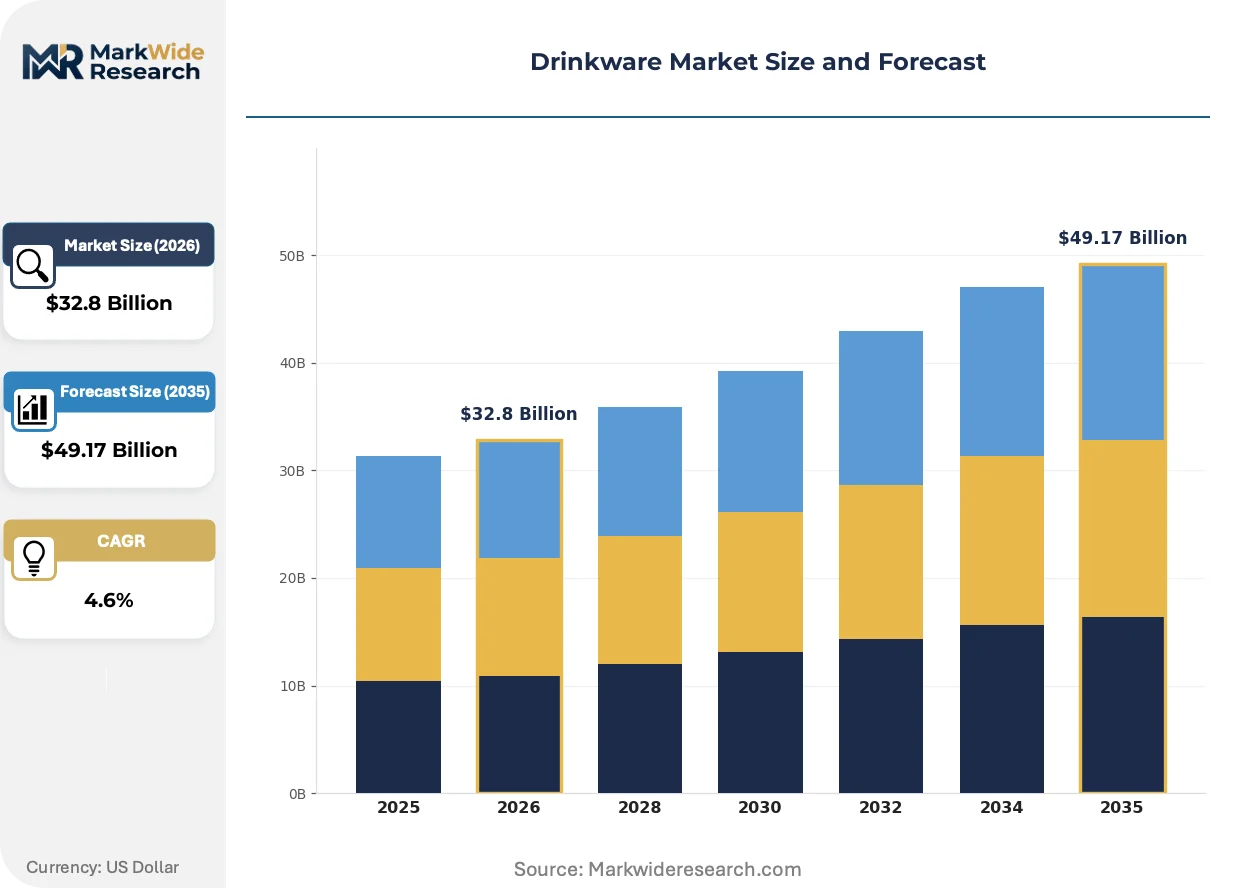
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $49.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mugs, Tumblers, Water Bottles, Flasks Material: Glass, Plastic, Stainless Steel, Ceramic End User: Households, Offices, Sports Teams, Restaurants Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Thermos LLC, Hydro Flask, Newell Brands Inc., CamelBak, S'well, YETI Holdings Inc., Stanley, Corkcicle, Tupperware Brands Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drinkware Market Strategic Shifts & Innovations
Digital manufacturing workflows and regulatory chemistry restrictions are converging to redefine material specifications, production economics, and buyer procurement criteria across temperature-retention vessel categories.
Laser powder bed fusion is virtualizing traditional metal forming for complex internal geometries in premium vacuum chambers. Custom athletic and medical device manufacturers adopt these additive workflows for sub-1,000 unit runs. The technology is virtualizing economies of scale, compressing minimum viable order quantities from 10,000 to 500 units without tooling amortization penalties.
REACH Annex XVII restrictions on nickel release rates tighten migration thresholds for prolonged skin contact applications. German and French market surveillance authorities now require third-party batch testing documentation at point of import. Stainless steel suppliers with in-house metallurgical laboratories capture accelerated approval timelines, while commodity traders face extended customs holds and demurrage costs.
Bulk procurement by corporate wellness programs and hospitality chains is consolidating purchase authority away from individual facility managers. National account structures with annual volume commitments and co-branded SKU exclusivity displace spot-market purchasing in the United States and United Kingdom. Facility services integrators and group purchasing organizations now intermediate 40-50% of commercial drinkware acquisition decisions, compressing supplier margins in exchange for multi-year contract security.
Drinkware Market Segmentation
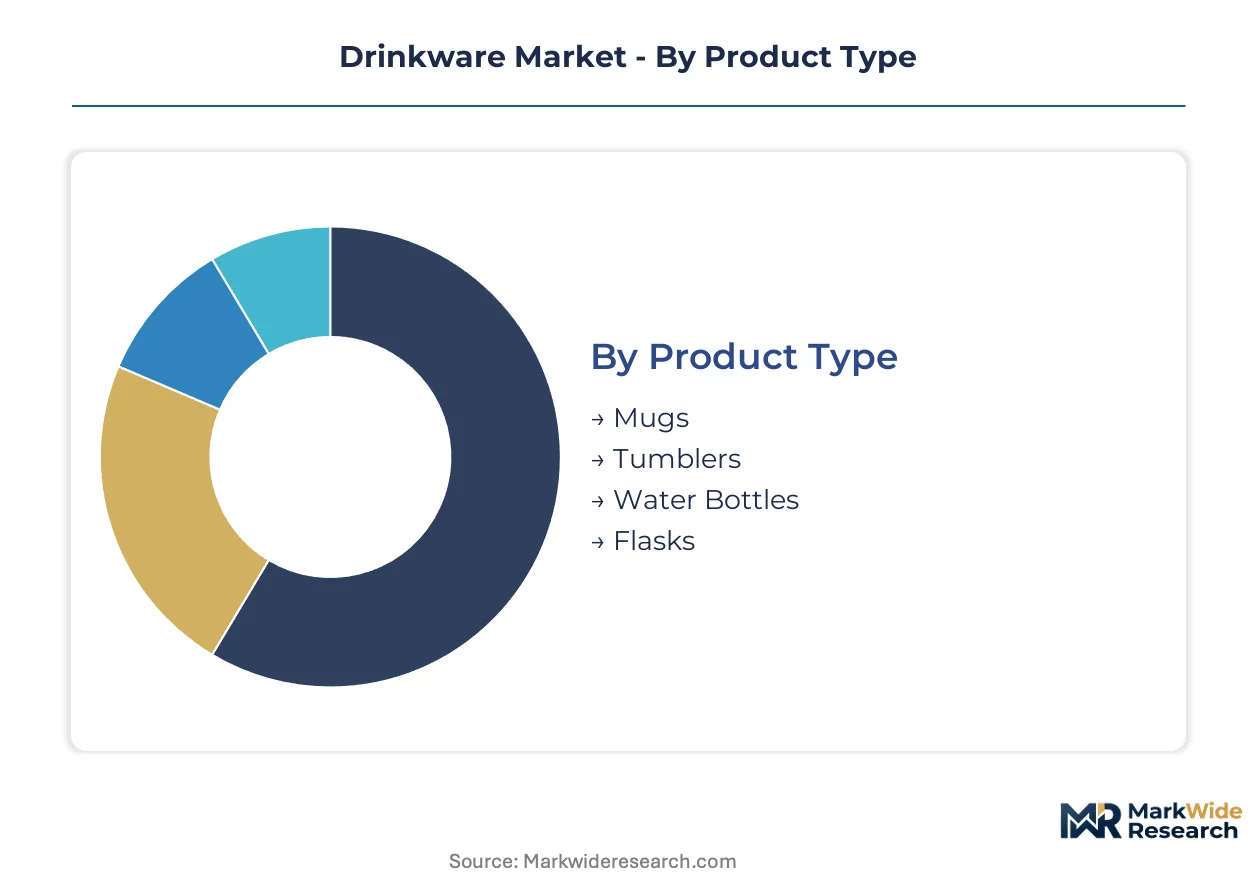
Drinkware segmentation reveals how material specifications, thermal performance requirements, and procurement authority patterns fragment demand across distinct buyer cohorts. Understanding these divides exposes where margin pools concentrate and which technology investments align with volume trajectories.
Product Type:
Mature formats dominate household penetration while emerging designs capture athletic and professional hydration occasions.
- Mugs:Ceramic and glass compositions with single-wall or vacuum-insulated construction serve stationary consumption in domestic and office settings. Demand concentrates in United States corporate wellness programs where employer-funded hydration stations displace disposable cups.
- Tumblers:Open-top vessels with splash-resistant lids and tapered profiles fit automotive cup holders and commute patterns. California and New York urban markets drive premium customization for co-branded employer merchandise.
- Water Bottles:Narrow-neck cylindrical designs with carry loops dominate athletic and educational institutional procurement.
- Flasks:Compact curved profiles with captive lids target outdoor recreation and personal beverage transport.
Water bottles handle the majority of throughput; tumblers are the fastest mover on share.
Material:
Cost tier stratification separates commodity substitution from durability premiums and regulatory compliance positioning.
- Stainless Steel:Double-wall vacuum-insulated 18/8 or 316-grade construction delivers thermal retention and chemical stability for athletic and child-focused segments. FDA BPA migration limits and California Proposition 65 warning requirements accelerate substitution away from polymer alternatives in United States markets.
- Glass:Borosilicate formulations rated for thermal shock resistance serve premium domestic and specialty foodservice applications where taste neutrality outweighs fragility trade-offs. German and French hospitality procurement favors certified lead-free crystal for front-of-house presentation.
- Plastic:Tritan copolyester and polypropylene face structural compression as REACH Annex XVII restrictions and state-level BPA prohibitions constrain formulation flexibility.
- Ceramic:Glazed stoneware and porcelain retain position in gift and domestic segments where aesthetic differentiation commands price premiums.
Stainless steel commands the dominant revenue position; glass is climbing the fastest as hospitality procurement elevates sustainability credentials.
End User:
Customer type determines volume scale, customization complexity, and contract structure across procurement relationships.
- Households:Individual and family-unit purchases through retail and direct-to-consumer channels prioritize design variety and price accessibility.
- Offices:Corporate wellness programs and facility services integrators consolidate purchasing authority with annual volume commitments and co-branded SKU exclusivity.
- Sports Teams:Athletic organizations and educational institutions demand durable vessels with institutional color matching and mascot customization.
- Restaurants:Foodservice operators balance front-of-house presentation requirements with back-of-house durability and dishwasher compatibility.
Households generate the highest absolute unit volumes; offices are expanding most quickly as employer wellness budgets formalize hydration infrastructure.
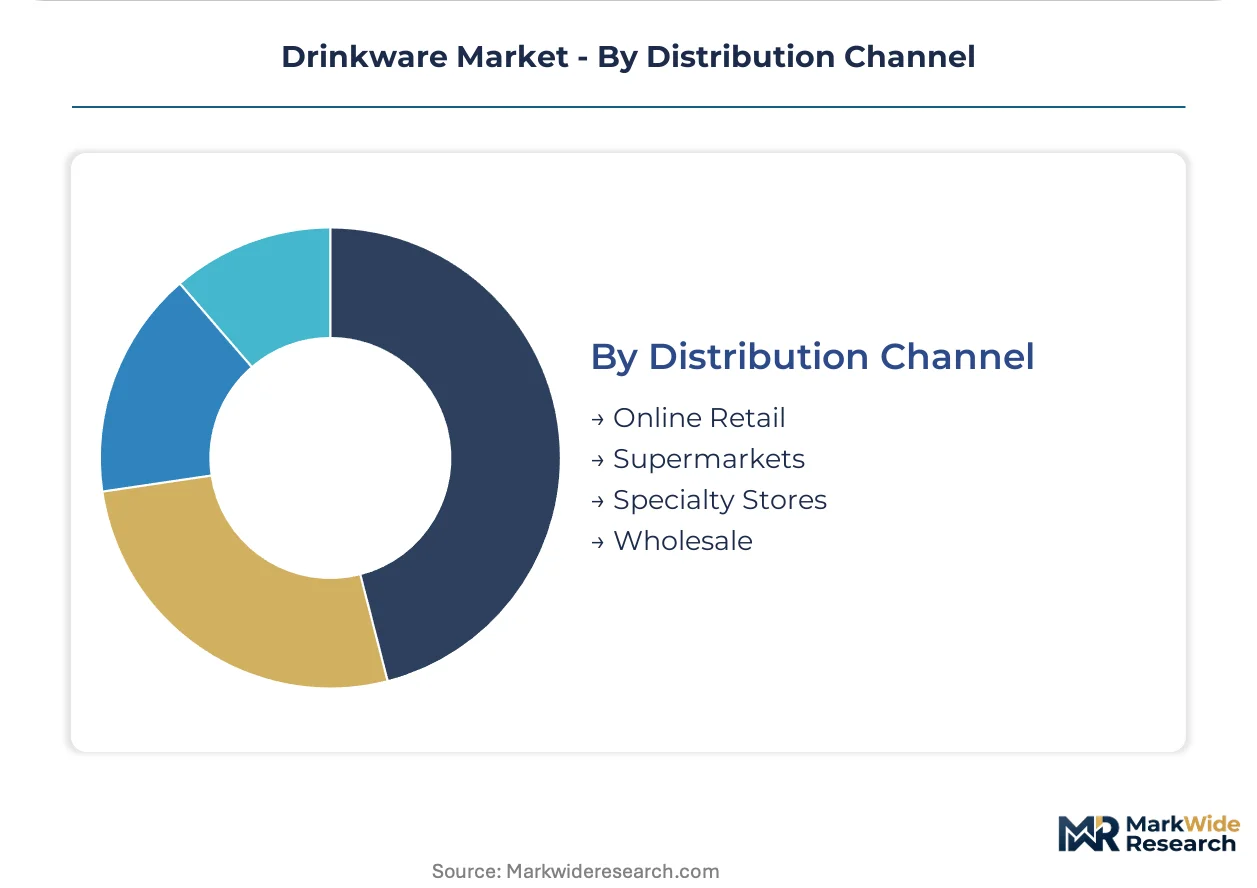
Distribution Channel:
Channel selection shapes margin realization, brand control, and customer relationship depth across the value chain.
- Online Retail:Direct-to-consumer and marketplace platforms capture standard SKU volume with compressed margins and limited customization support.
- Supermarkets:Mass retail placement drives impulse substitution of disposable alternatives with entry-price reusable options.
- Specialty Stores:Premium gift, outdoor, and kitchenware retailers retain outsized margin pools through experiential merchandising and corporate customization services. United Kingdom and United States specialty channels intermediate high-value hospitality and employer gift procurement.
- Wholesale:Foodservice distributors and group purchasing organizations aggregate demand from fragmented restaurant and institutional accounts.
Online retail moves the largest unit volumes; specialty stores deliver the steepest expansion trajectory in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate wellness programs and hospitality procurement departments concentrate purchase authority in the United States, while German and Japanese buyers prioritize material traceability and extended producer responsibility compliance.
United States
Employer-funded hydration infrastructure and co-branded corporate gift programs drive stainless steel tumbler demand. California Proposition 65 mandates heavy metal warning labels that reshape supplier selection toward domestic stainless steel mills. Los Angeles and New York City clusters host specialty retailers that intermediate premium customization for technology and finance sector clients.
Germany
Hospitality chains and institutional foodservice operators prioritize REACH Annex XVII nickel release compliance for front-of-house presentation vessels. ECHA batch testing documentation requirements at point of import favor suppliers with in-house metallurgical laboratories. Bavaria's industrial manufacturing corridor concentrates precision metal forming capabilities for vacuum-insulated chamber production.
China
Contract manufacturers serve global brand OEM demand through automated welding and electropolishing lines in the Yangtze River Delta. SAMR food-contact material safety standards and GB standards for stainless steel grades constrain export-bound production specifications. Zhejiang and Guangdong provinces host powder-coating and laser engraving clusters that enable mass customization at scale.
Japan
Premium domestic consumers and corporate gift buyers demand JIS-standard stainless steel with verified metallurgical composition. METI circular economy guidelines encourage closed-loop recycling infrastructure investment by major retailers. Osaka-Kobe industrial zone maintains specialized vacuum chamber sealing capabilities for high-performance thermal retention products.
United Kingdom
Group purchasing organizations and facility services integrators consolidate 40-50% of commercial drinkware acquisition decisions. UK REACH alignment with EU chemical restrictions maintains phthalate and heavy metal content barriers for Asian polymer suppliers. London and Manchester specialty retail corridors sustain experiential merchandising for premium gift and employer merchandise segments.
Drinkware Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented tier structures. The vendor base organizes around scale-driven mass retailers, premium outdoor specialists, and agile contract manufacturers. Three archetypes dominate: vertically integrated vacuum-insulation specialists, multi-brand portfolio holding companies, and private-label contract producers. Competitive moves concentrate on co-branding partnerships with corporate wellness programs and rapid nearshoring of automated welding capacity.
Among North American holding companies, Newell Brands Inc. exemplifies multi-brand portfolio scale across mass retail channels, while YETI Holdings Inc. occupies a premium positioning archetype in outdoor and professional segments. Hydro Flask represents the vertically integrated specialist model with captive vacuum-insulation manufacturing capabilities. These three anchors illustrate how margin control strategies diverge between asset-heavy manufacturing and asset-light brand licensing approaches.
| Leading Market Players |
|---|
| Thermos LLC |
| Hydro Flask |
| Newell Brands Inc. |
| CamelBak |
| S'well |
| YETI Holdings Inc. |
| Stanley |
| Corkcicle |
| Tupperware Brands Corporation |
| Others |
Cost & Logistics Intelligence
Indonesian and Russian nickel-chromium mining concentration anchors raw material cost volatility, channeling margin capture toward vacuum-insulation specialists with captive metallurgical sourcing and long-term offtake agreements with stainless steel mills.
Pricing Analysis
Certification level creates the primary spread across FDA-grade, REACH-compliant, and uncertified tiers in this market. Three-tier pricing structure across premium vacuum-insulated, standard single-wall, and economy polymer vessels reflects material grade and thermal performance testing. Cost compression in mid-market hospitality procurement is intensifying because automated welding lines reduce unit economics at scale. Corporate wellness programs exhibit lowest price sensitivity due to employer-funded budgets, while mass retail consumers drive entry-point substitution.
Supply Chain Analysis
Export-control friction on precision welding equipment limits technology transfer to contract manufacturers in emerging production zones. China, Indonesia, and Germany anchor global supply through Yangtze River Delta powder-coating clusters, Sulawesi nickel smelting operations, and Bavarian vacuum-chamber forming capabilities. Production draws from nickel ore, chromium alloys, and borosilicate glass feedstocks. Single-source vulnerability concentrates in Indonesian nickel processing following export quota volatility. Distribution runs through specialty retail partnerships for premium customization and direct-to-consumer platforms for standard SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through group purchasing organizations and facility services integrators that now intermediate 40-50% of commercial acquisition decisions, compressing supplier margins in exchange for multi-year contract security.
For Market Incumbents: Harden metallurgical certification capabilities to accelerate FDA and REACH approval timelines against Asian contract manufacturers facing extended customs holds. Deepen backward integration into stainless steel sourcing through captive supply agreements with domestic mills, insulating margin stability from Indonesian export quota volatility.
For New Entrants and Emerging Players: Pursue white-space positioning in smart hydration integration for employer wellness programs, where Bluetooth-enabled consumption tracking opens recurring-revenue models. Target the United Kingdom group purchasing organization channel with rapid customization turnaround and JIS-standard material traceability documentation.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturers lacking closed-loop recycling infrastructure. Long-term viability hinges on material traceability systems and extended producer responsibility compliance positioning. Watch for California take-back mandate enforcement as an inflection signal for recycling infrastructure valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Recycling Infrastructure | Extended producer responsibility mandates in California and the EU reward first-mover investment with accelerated approval timelines. |
| Smart Hydration Platform Integration | Bluetooth-enabled consumption tracking converges with vacuum insulation to unlock recurring-revenue employer wellness contracts. |
| Domestic Stainless Steel Sourcing | Proposition 65 warning requirements favor domestic mill relationships over Asian polymer converters in United States procurement. |
| Specialty Retail Channel Partnerships | Experiential merchandising in Los Angeles and New York clusters sustains premium customization margins against online compression. |
| Nearshoring of Automated Welding | Bavarian and Osaka-Kobe precision metal forming capabilities reduce certification friction for EU and Japanese hospitality buyers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA food-contact material filings, REACH Annex XVII compliance databases, and customs trade records for nickel and chromium alloy imports. Interviews with stainless steel procurement directors at vacuum-insulation specialists, category buyers at group purchasing organizations, regulatory affairs leads at polymer converters, and specialty retail merchandising heads inform demand-side dynamics. Bottom-up SKU-level volume aggregation triangulates against top-down market sizing from trade association data and SEC filings by holding companies.
Forecast inputs include material substitution rates from polymer to stainless steel, corporate wellness program budget expansion trajectories, and hospitality procurement consolidation patterns across the analysis window. Segmentation dimensions span product type, material grade tier, end-user procurement authority, and distribution channel control. CAGRs derive from regression analysis of historical volume trajectories adjusted for regulatory catalyst timing and raw material cost pass-through elasticity.
Macroeconomic conditions sit as an overlay; deviation in nickel spot prices, freight rate volatility, or employer wellness budget freezes would shift the trajectory. Forecasts reflect documented assumptions about FDA BPA migration limit enforcement and REACH nickel release threshold tightening. Cross-checking against ECHA import surveillance data and California Proposition 65 settlement records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Robot Vacuum Cleaners Market
Household Items
Manual Bottle Opener Market
Household Items
Residential Air Purifiers Market
Household Items
Plastic Bathtub Market
Household Items
Industrial Vacuum Cleaner Market
Household Items
Smart Toilet Market
Household Items
Titanium Thermos Cup Market
Household Items
Sorting Hampers Market
Household Items
Shower Caddies Market
Household Items
Stainless Steel Water Bottles Market
Household Items
US Air Purifier Market
Household Items
Saudi Arabia Cookware Market
Household Items
Cookware Market
Household Items
Electric Soap Dispenser Market
Household Items
Range Hood Cleaning Service Market
Household Items
Europe & UK Nonstick Cookware Market