
 Portable Air Humidifier and Dehumidifier Market | 2026-2036
Portable Air Humidifier and Dehumidifier Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Air Humidifier and Dehumidifier Market Analytics
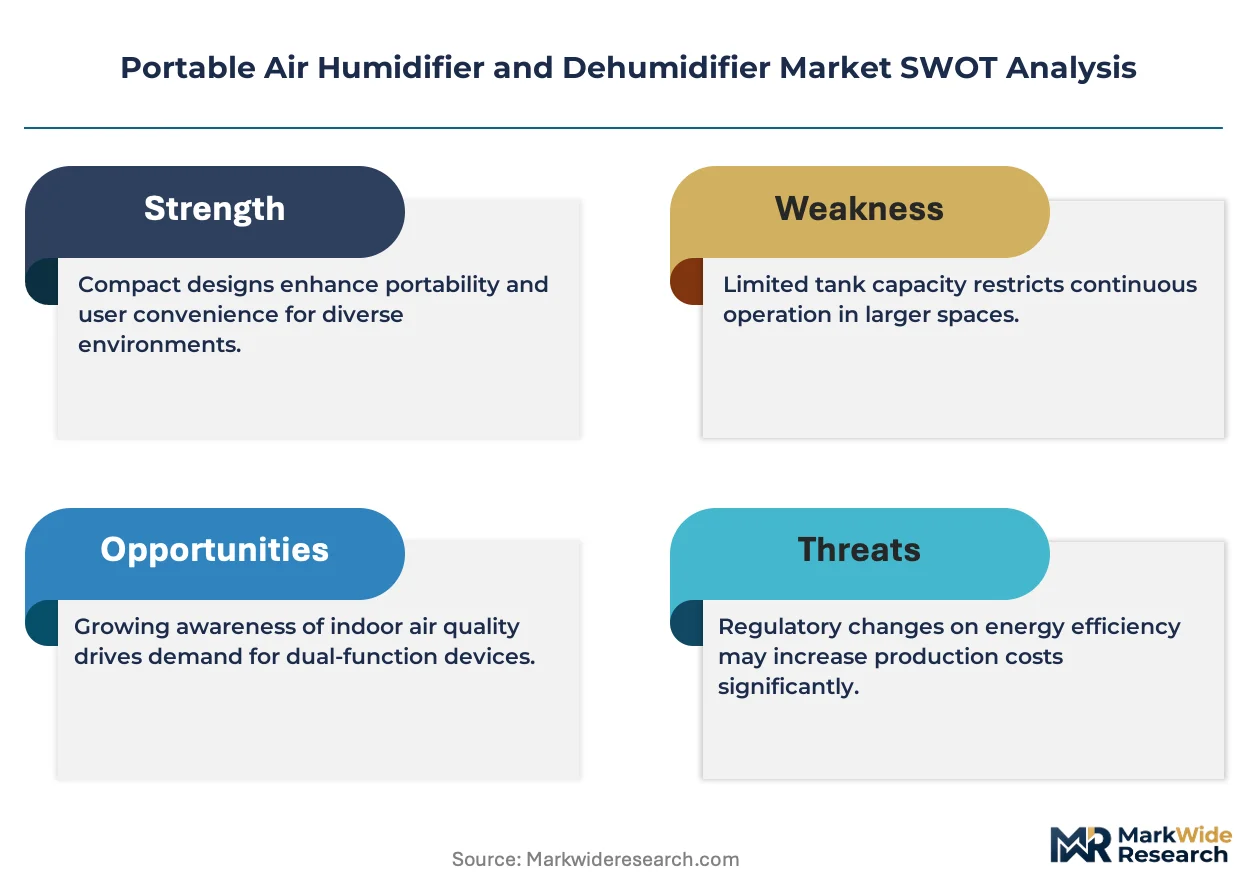
The capital-intensity gap between premium OEMs and value-tier assemblers is collapsing as sensor miniaturization and IoT module commoditization level the technology playing field. Honeywell International Inc. leverages its building-automation heritage to bundle climate-control software with hardware, sustaining recurring revenue streams. Guardian Technologies LLC anchors its position through pharmacy and big-box retail channel control, dominating shelf space in North American mass-market distribution.
Portable air humidifiers and dehumidifiers are electromechanical appliances designed to add or remove moisture from localized air volumes, typically operating across output ranges from 300 milliliters per day for personal units to 50 liters per day for commercial-grade systems using compressor-based or thermoelectric cooling technologies. Their primary purpose spans respiratory health management, mold prevention, and preservation of moisture-sensitive equipment or inventory in controlled environments. Ultrasonic and desiccant product types capture divergent margin pools, with ultrasonic humidifiers leading residential volume due to silent operation while desiccant dehumidifiers command premium pricing in cold-climate industrial applications. Smart technology integration represents the fastest-expanding segment as Wi-Fi-enabled humidity sensing and automated scheduling displace manual controls across homeowner and office space end users.
The EPA and FCC shape United States market access through energy-efficiency mandates and wireless device certification requirements, while China's SAMR enforces GB standards for electrical safety and electromagnetic compatibility in domestic manufacturing. These frameworks elevate compliance costs for new entrants but protect incumbents with established testing infrastructure and regulatory affairs capabilities. Stakeholders must monitor evolving interoperability standards between climate appliances and centralized building management systems as the decisive battleground for differentiation shifts from hardware performance to software ecosystem integration.
Market Dynamics
Smart home ecosystem integration is compressing hardware margins while expanding software monetization potential across the portable climate-control appliance sector. The shift from standalone humidity management to connected building-automation nodes is redistributing value capture toward platform operators and away from pure-play manufacturers.
Growth Catalysts
- EPA Indoor Air Quality Guidelines:Tightening federal moisture-control standards for residential environments are mandating humidity monitoring in new construction and major renovations across the United States.
- Sensor Miniaturization:Falling costs for MEMS humidity sensors and compact IoT modules are enabling sub-$50 connected units that previously required premium positioning.
- Climate-Stressed Homeowners:Prolonged drought-flood cycles in the American Southwest and Southeast are creating year-round demand for dual-function climate appliances.
Market Restraints
- Compressor Component Concentration:Rotary compressor supply for dehumidifier units clusters among Japanese and Chinese motor manufacturers, exposing assemblers to shipping disruptions and input cost volatility.
- Desiccant Material Limitations:Silica gel and zeolite regeneration cycles impose energy-efficiency penalties that constrain adoption in residential segments sensitive to electricity costs.
- Wireless Certification Friction:FCC Part 15 compliance timelines for Wi-Fi-enabled units extend product launch windows by four to six months versus non-connected equivalents.
Strategic Opportunities
- India Urban Middle-Class Expansion:Air-conditioned apartment stock in Delhi, Mumbai, and Bangalore is creating first-time demand for humidity management in previously unserved tropical climates.
- Matter Protocol Convergence:Cross-platform smart home interoperability standards are reducing engineering overhead for multi-ecosystem compatibility.
- Pharmacy Channel Penetration:CVS, Walgreens, and regional drugstore chains are expanding wellness-device assortments, creating shelf-space access for clinically positioned respiratory health products.
Industry Challenges
- Firmware Engineering Talent Scarcity:Embedded systems developers capable of low-power wireless stack optimization command premium compensation that strains mid-tier OEM R&D budgets.
- Legacy HVAC Integration Complexity:Proprietary communication protocols from established building-automation vendors resist standardized API access, complicating third-party humidifier-dehumidifier coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Air Humidifier and Dehumidifier Market |
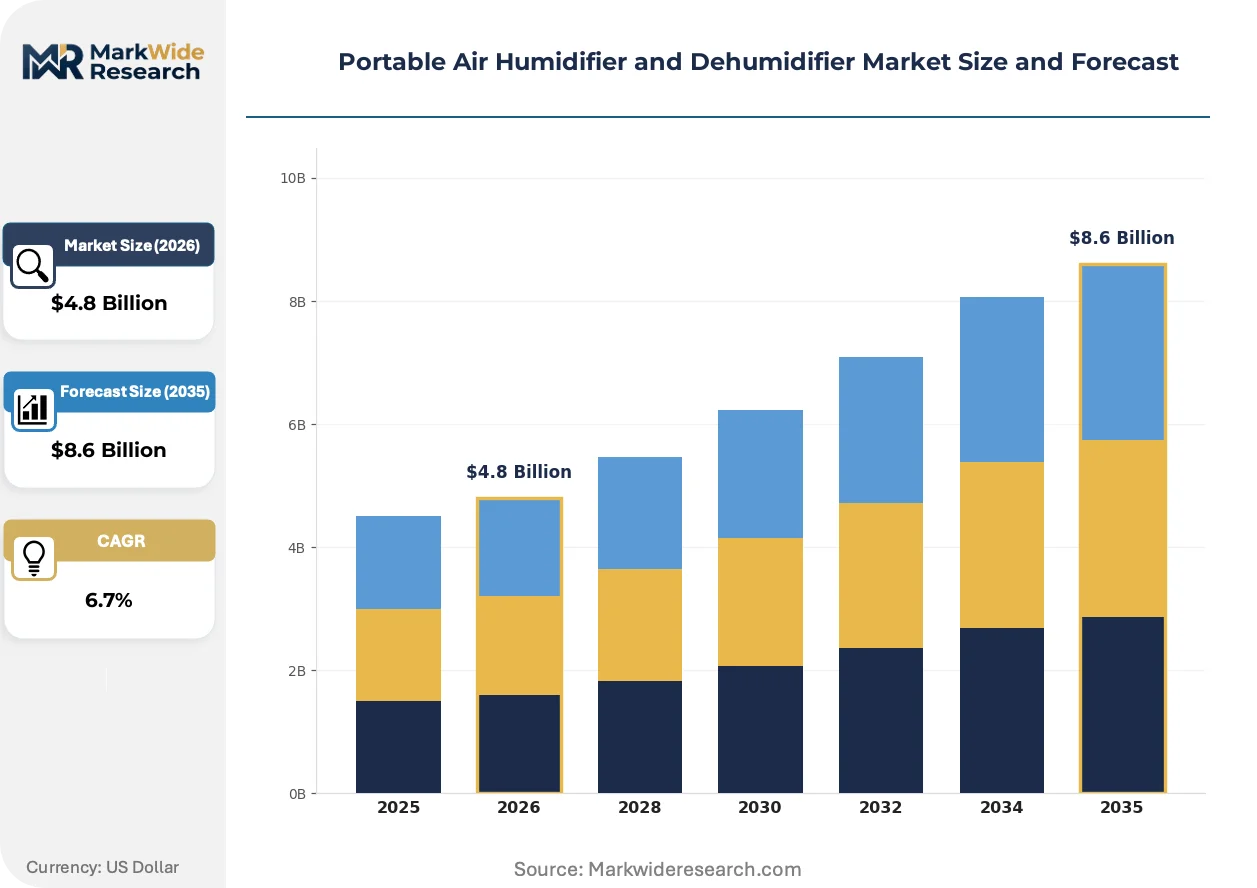
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic, Evaporative, Steam, Desiccant Application: Residential, Commercial, Industrial, Healthcare Technology: Smart, Manual, Hybrid, Energy-efficient End User: Homeowners, Office Spaces, Hospitals, Retailers |
| Companies Covered | Honeywell International Inc., Danby, Newell Brands Inc., Whirlpool Corp., Guardian Technologies LLC, Koninklijke Philips NV, Dyson Group Co., LG Electronics Inc., Arovast Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Air Humidifier and Dehumidifier Market Evolving Landscape
Electromechanical climate control is yielding computational dominance as humidity management becomes a software-defined function within broader environmental optimization platforms. The hardware-software boundary is dissolving across residential and light-commercial deployments.
Thermoelectric Peltier cooling is fragmenting the sub-20-liter dehumidifier category by eliminating compressor noise and vibration constraints. Apartment dwellers and bedroom users are adopting these units despite lower moisture-removal rates per watt-hour. The technology is fragmenting price-performance segmentation by enabling silent operation at mass-market price points previously associated only with premium desiccant systems.
REACH chemical restrictions and the EU F-Gas Regulation are phasing out hydrofluorocarbon refrigerants in compressor-based dehumidifiers sold across European member states. Manufacturers are reformulating cooling circuits with hydrocarbon alternatives that require revised safety testing protocols. Cold-climate residential users in Germany, Scandinavia, and the Baltic states face reduced unit availability during the transition period as certification timelines extend.
Subscription-based filter replacement and predictive maintenance alerts are displacing transactional aftermarket sales for consumable components. Amazon Alexa and Google Home ecosystem users are accepting recurring charges for automated supply replenishment tied to usage telemetry. This pattern is most visible in United States metropolitan markets where smart-speaker penetration exceeds sixty percent among homeowners aged thirty-five to fifty-four.
Portable Air Humidifier and Dehumidifier Market Segmentation
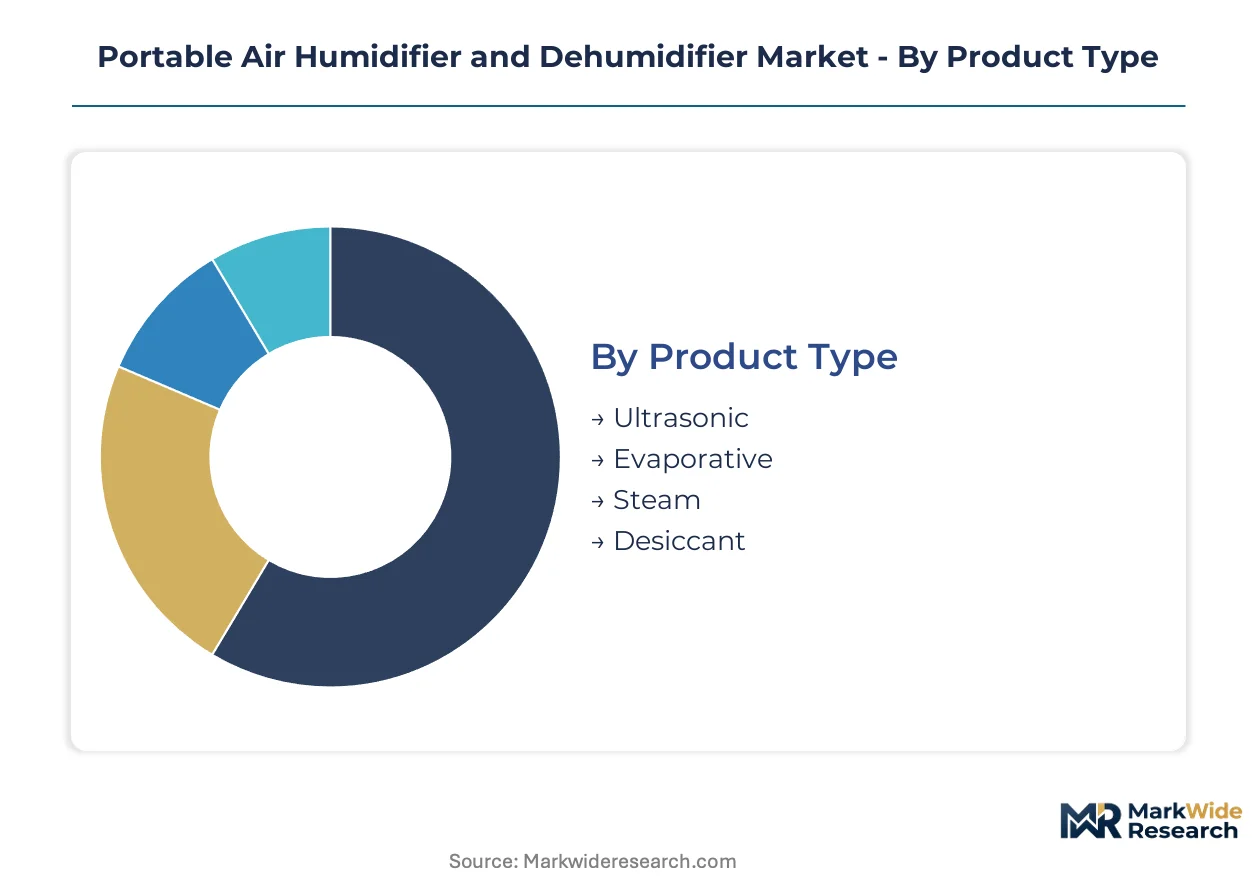
Segmentation in portable climate control reveals how moisture-management needs fragment across acoustic sensitivity, operational scale, and connectivity requirements. Distinct buyer cohorts prioritize silent bedroom operation, industrial-grade moisture extraction, or seamless smart-home orchestration.
Product Type:
Ultrasonic and evaporative systems dominate domestic manufacturing footprints in China and Vietnam, while desiccant units rely on specialized Japanese and European component supply chains for zeolite rotor assemblies.
- Ultrasonic:Piezoelectric transducers generate micro-fine mist through high-frequency vibration without heating elements. Demand clusters in United States suburban housing and Japanese apartment complexes where silent nighttime operation is non-negotiable. Falling MEMS sensor costs enable sub-$40 connected variants.
- Desiccant:Zeolite or silica gel rotors absorb moisture through physical adsorption, then regenerate via internal heating. Cold-climate industrial buyers in Germany and Scandinavia favor these units for sub-5°C operation where compressor-based systems fail. REACH F-Gas compliance is accelerating hydrocarbon refrigerant transitions.
- Evaporative:Wick-based natural evaporation without mineral dust dispersion suits hard-water regions in Southwestern United States and Australian metropolitan areas.
- Steam:Boiling-element humidification delivers sterile output for clinical environments in United States hospitals and German eldercare facilities.
Ultrasonic commands the established base. The steepest expansion runs through desiccant as cold-climate industrial regulations tighten.
Application:
Residential volume scales through mass-market retail channels, while healthcare and industrial segments concentrate in specialized procurement with extended certification timelines.
- Residential:Bedroom and living-room units drive unit economics through seasonal replacement cycles. United States homeowners in Florida and Arizona sustain year-round demand patterns that flatten revenue seasonality.
- Healthcare:Operating theaters and respiratory wards require HEPA-integrated humidification with continuous monitoring. FDA 510(k) pathways and Joint Commission accreditation extend sales cycles to 18-24 months.
- Commercial:Open-plan offices and hospitality spaces prioritize aesthetic integration and centralized BMS compatibility.
- Industrial:Electronics manufacturing and pharmaceutical storage demand precision humidity control within ±2% RH tolerances.
Residential captures volume leadership. Healthcare delivers margin expansion through regulatory barriers.
Technology:
Smart connectivity is redistributing engineering investment toward firmware and cloud infrastructure, while manual units retreat to price-sensitive emerging-market entry points.
- Smart:Wi-Fi-enabled humidity sensing with app-based scheduling and voice-assistant integration. United States smart-speaker penetration above sixty percent among prime homeowner demographics sustains subscription filter-replenishment monetization.
- Manual:Dial-control operation without connectivity serves budget-conscious buyers in Indian tier-2 cities and Southeast Asian mass retail.
- Hybrid:Combines automated sensing with override manual controls for transitional buyer segments.
- Energy-efficient:EPA ENERGY STAR certification and EU Ecodesign compliance drive compressor optimization and Peltier thermoelectric adoption.
Smart technology is gaining share fastest. Manual operation defends position in emerging-market entry tiers.
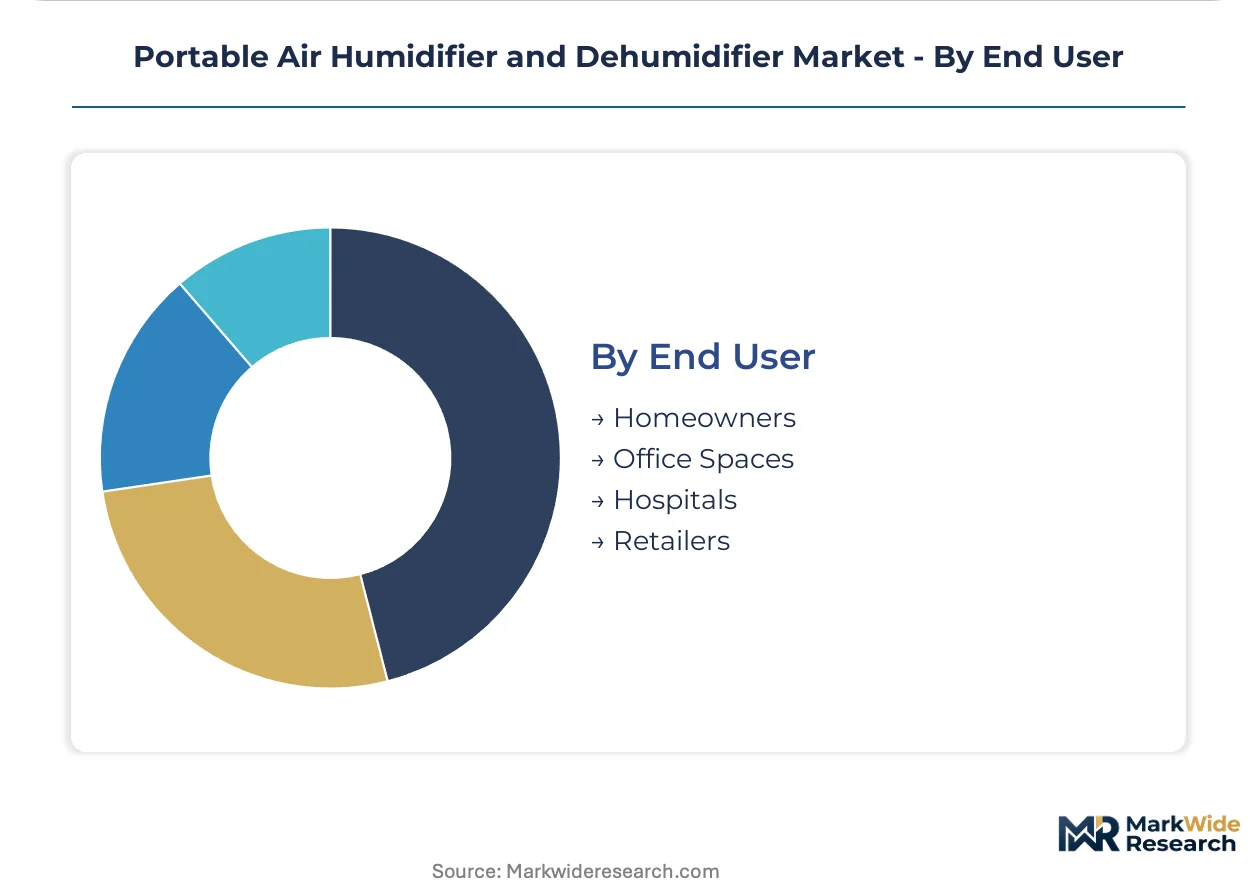
End User:
Homeowner procurement flows through Amazon, Home Depot, and pharmacy chains, while hospital purchasing consolidates through GPOs and integrated delivery networks.
- Homeowners:Individual buyers responding to seasonal discomfort, pediatric respiratory concerns, or musical instrument preservation needs. CVS and Walgreens wellness-device expansions are creating shelf-space access for clinically positioned SKUs.
- Hospitals:Infection-control committees and facilities engineering jointly specify redundant humidity management for critical care zones.
- Office Spaces:Facility managers prioritize lease-compliant climate control with minimal tenant disruption during installation.
- Retailers:Inventory protection for moisture-sensitive electronics, textiles, and specialty foods drives warehouse-scale dehumidification.
Homeowners anchor unit volume. Hospitals concentrate value through specification authority and replacement-part lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Humidifier deployment patterns diverge sharply across climates: arid-zone homeowners in the American Southwest run units year-round for respiratory comfort, while tropical Asian buyers prioritize dehumidification for mold prevention and electronics protection.
United States
Seasonal humidity extremes in Florida and Arizona sustain replacement-driven demand cycles that flatten revenue seasonality for retailers. The EPA's tightening indoor air quality guidelines are mandating humidity monitoring in new residential construction across moisture-prone states. Dallas-Fort Worth and Phoenix metropolitan clusters concentrate distribution infrastructure for mass-market ultrasonic units.
China
Smart home integration accelerates fastest among Shanghai and Shenzhen apartment dwellers upgrading from manual dial-control units. SAMR enforces GB standards for electrical safety and electromagnetic compatibility, elevating compliance costs for Wi-Fi-enabled product launches. The Yangtze River Delta manufacturing corridor dominates OEM assembly for ultrasonic transducer and MEMS sensor modules.
Germany
Cold-climate industrial buyers in Bavaria and North Rhine-Westphalia favor desiccant dehumidifiers for sub-5°C warehouse operation. The EU F-Gas Regulation is phasing out hydrofluorocarbon refrigerants, forcing hydrocarbon cooling circuit reformulation and extended safety certification timelines. Hamburg and Berlin logistics hubs coordinate distribution for REACH-compliant units across Nordic export markets.
India
Air-conditioned apartment stock in Delhi-NCR, Mumbai, and Bangalore is creating first-time humidity management demand among tropical middle-class households. BIS certification requirements for electrical appliances extend product registration timelines for imported smart units. The Maharashtra-Gujarat industrial corridor is attracting contract manufacturing investment for manual-control entry-tier dehumidifiers.
Japan
Silent-operation specifications in Tokyo and Osaka apartment complexes sustain premium positioning for ultrasonic humidifiers with piezoelectric transducers. METI energy-efficiency labeling programs differentiate products in retail channels. The Kansai region maintains specialized supply chains for zeolite rotor assemblies used in compact desiccant systems.
Portable Air Humidifier and Dehumidifier Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrated among building-automation heritage firms and diversified electronics conglomerates. The middle tier fragments across regional assemblers and private-label contractors competing on sensor module integration speed. Three archetypes dominate: ecosystem platform operators bundling software subscriptions, pharmacy-channel shelf-space controllers, and component-integrated OEMs with captive MEMS supply. Competitive moves center on strategic partnerships with smart-home platforms and vertical integration into humidity sensor fabrication.
Among diversified technology conglomerates, Honeywell International Inc. and LG Electronics Inc. exemplify ecosystem platform operators leveraging building-automation software heritage. Guardian Technologies LLC occupies a position within the pharmacy-channel archetype, anchoring mass-market distribution through retail shelf-space concentration. Koninklijke Philips NV represents the health-technology integration vector, sitting within the premium-tier positioning cluster that bundles clinical-grade specifications with consumer accessibility.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Danby |
| Newell Brands Inc. |
| Whirlpool Corp. |
| Guardian Technologies LLC |
| Koninklijke Philips NV |
| Dyson Group Co. |
| LG Electronics Inc. |
| Arovast Corp. |
| Others |
Value Network & Pricing Analysis
MEMS humidity sensor commoditization is displacing legacy capacitive sensing modules across portable climate appliance production, simultaneously shifting component sourcing from Japanese precision manufacturers to Chinese MEMS foundries and collapsing the cost floor for connected unit pricing. This substitution dynamic compresses margins for premium OEMs while enabling value-tier assemblers to field Wi-Fi-enabled products at mass-market price points.
Pricing Analysis
Long-term offtake agreements dominate procurement between major retailers and OEMs, insulating volume commitments from spot-market volatility in compressor and transducer inputs. Three-tier pricing structure across premium, standard, and economy levels separates ENERGY STAR-certified smart units from manual dial-control entry tiers and pharmacy-channel clinically positioned SKUs. Cost compression in the ultrasonic residential segment is intensifying because falling sensor costs enable sub-$40 connected variants that previously required premium positioning. Pharmacy-channel buyers exhibit lowest price sensitivity due to wellness-device positioning, while Indian tier-2 city mass retail shows highest elasticity.
Supply Chain Analysis
China and Vietnam anchor ultrasonic transducer and plastic injection molding for residential humidifier housings, while Japan and Germany maintain specialized zeolite rotor fabrication for desiccant dehumidifier cores. Rotary compressor supply draws from Japanese and Chinese motor manufacturers, creating single-source vulnerability for dehumidifier assemblers dependent on discrete cooling circuit components. Distribution runs through Amazon and Home Depot for United States homeowners, pharmacy chains for clinically positioned units, and regional mass retail for emerging-market manual-control segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward pharmacy chains and smart-home platform operators as channel consolidation concentrates shelf-space allocation and ecosystem gatekeeping authority. This fragmentation among pure-play manufacturers versus integrated platform operators restructures value capture away from hardware producers.
For Market Incumbents: Secure exclusive filter-replenishment subscription agreements with Amazon Alexa and Google Home ecosystems before platform operators develop private-label alternatives. Invest in captive MEMS humidity sensor production to defend margin position against Chinese value-tier entrants exploiting commoditized IoT modules. The EPA's tightening indoor air quality guidelines create certification barriers that favor established testing infrastructure over new entrants. For New Entrants and Emerging Players: Differentiate on silent-operation thermoelectric Peltier technology for apartment bedroom segments where compressor noise creates dissatisfaction with incumbent offerings. Target India's air-conditioned apartment stock in Delhi-NCR and Bangalore with manual-control entry tiers before smart-home penetration accelerates. Pursue pharmacy channel penetration through CVS and Walgreens wellness-device expansions with clinically positioned respiratory health messaging. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors component-integrated OEMs with captive sensor supply over pure-play brand marketers. Long-term viability hinges on software ecosystem integration rather than hardware performance differentiation. Watch Matter protocol adoption rates as the inflection indicator for multi-platform compatibility becoming table stakes rather than premium positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Home Platform Integration | Wi-Fi-enabled humidity sensing with Alexa and Google Home voice control locks in recurring filter-subscription revenue streams. |
| Pharmacy Channel Expansion | CVS and Walgreens wellness-device shelf-space access positions humidifiers as respiratory health solutions rather than seasonal appliances. |
| MEMS Sensor Vertical Integration | In-house piezoelectric transducer production defends margin compression from Chinese value-tier competitors exploiting commoditized modules. |
| Matter Protocol Certification | Cross-platform interoperability reduces engineering overhead for multi-ecosystem compatibility across Apple, Google, and Amazon smart home networks. |
| Hydrocarbon Refrigerant Transition | EU F-Gas Regulation compliance enables continued access to German and Scandinavian cold-climate industrial desiccant replacement markets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with smart home platform engineers, pharmacy chain category buyers, OEM procurement directors, and HVAC facilities managers. Secondary validation drew from EPA indoor air quality guideline releases, SAMR GB standard filings, EU F-Gas Regulation implementation timelines, and customs records for ultrasonic transducer trade flows. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across product type, application, technology, and end-user segmentation dimensions.
Across the analysis window, the analytical framework modeled volume and value outputs through product type stratification, connectivity tier, regional regulatory cluster, and channel structure. CAGRs were derived from regression analysis of historical shipment patterns against macroeconomic and regulatory driver indices. Forecast inputs incorporated smart-speaker household penetration curves, EPA guideline implementation schedules, and REACH chemical restriction phase-in timelines.
The analysis sits within stated boundaries; outcomes outside sustained smart-home ecosystem adoption or accelerated EPA indoor air quality enforcement would require recalibration. Forecasts reflect documented assumptions regarding MEMS sensor cost trajectories and pharmacy channel expansion rates. Recalibration cycles align with material shifts in platform operator partnership policies and refrigerant regulation implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Countertop Market
Household Items
Permanent Marker Market
Household Items
Cups and Pots Market
Household Items
North America Ceramic Barbeque Grill Market
Household Items
Sorting Hampers Market
Household Items
Knife Market
Household Items
Mason Jars and Canning Supplies Market
Household Items
Aquarium Hydrometers Market
Household Items
Smart Memory Foam Market
Household Items
Electric Clothes Drying Hanger Market
Household Items
Hydralight Lanterns Market
Household Items
GCC Gas Hobs Market
Household Items
Germany Induction Hobs Market
Household Items
Collapsible Water Bottle Market
Household Items
Ironing Boards Market
Household Items
Silicone Soap Mold Market