
 Integrated Smart Toilet Market | 2026-2036
Integrated Smart Toilet Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated Smart Toilet Market Insights
Aftermarket service revenue from sensor calibration and nozzle replacement is reconfiguring profit pools away from one-time hardware sales. TOTO leverages its vertically integrated ceramics and electronics supply chain to capture recurring maintenance streams. LIXIL sustains competitive pressure through its INAX brand's extensive service network across Japanese prefectures. Kohler anchors North American positioning with dedicated smart plumbing technician certification programs.
An integrated smart toilet fuses ceramic sanitary ware with embedded sensors, microprocessor-controlled water jets, and heated seating systems operating on 110-220V electrical supply with IPX4 minimum moisture protection ratings, designed to deliver automated personal hygiene and waste management in residential and commercial restrooms. The washlet segment dominates Japanese replacement demand where bidet functionality originated, while IoT-enabled units with leak detection and usage analytics represent the fastest-expanding category among hospitality developers seeking operational visibility. Water-saving features with dual-flush mechanisms below 1.28 gallons per flush concentrate margin pools in markets with active drought-response building codes.
EPA WaterSense certification shapes North American product eligibility for utility rebate programs, while Japan's Ministry of Economy, Trade and Industry (METI) enforces standby power regulations that constrain idle electricity draw for heated seats. The EU Ecodesign Directive and CE marking requirements for electrical bathroom appliances govern European market access and testing protocols. Stakeholders must monitor evolving interoperability standards between smart home platforms and municipal water management systems as infrastructure digitization advances.
Market Dynamics
Aftermarket revenue streams from sensor calibration and nozzle replacement cycles are restructuring profit pools away from one-time hardware transactions, compelling manufacturers to build recurring service capabilities into their core business models.
Growth Catalysts
- Water-efficiency mandates:EPA WaterSense certification unlocks utility rebate eligibility across multiple US jurisdictions, accelerating specification in drought-response building codes.
- Aging demographics:Japan's metropolitan corridor from Tokyo to Osaka sustains replacement demand as hygiene expectations and mobility needs converge in residential renovations.
- Luxury housing pipelines:South Korean premium residential developments specify integrated units as standard amenity, embedding bidet functionality in new construction specifications.
Market Restraints
- Ceramics supply concentration:Specialty vitreous china production clusters in specific manufacturing regions, exposing procurement to freight cost volatility and capacity constraints.
- Electrical infrastructure retrofit costs:110-220V supply requirements and IPX4 moisture protection ratings necessitate bathroom rewiring in older residential stock, delaying adoption.
- Standby power regulations:Japan's METI enforces idle electricity draw limits for heated seating systems, compressing margin on entry-tier units and complicating feature bundling.
Strategic Opportunities
- Hospitality IoT integration:Leak detection and usage analytics capabilities attract hotel developers seeking operational visibility across property portfolios.
- EU Ecodesign alignment:CE marking compliance for electrical bathroom appliances opens procurement pathways in European renovation markets with tightening efficiency standards.
- Smart home platform convergence:Interoperability with municipal water management systems creates specification advantages as infrastructure digitization advances in urban cores.
Industry Challenges
- Certified technician scarcity:Smart plumbing installation and maintenance requires specialized training programs that remain underdeveloped in North American vocational channels.
- Sensor calibration complexity:Precision nozzle alignment and pressure sensor validation demand proprietary diagnostic tools that fragment service capabilities across brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated Smart Toilet Market |
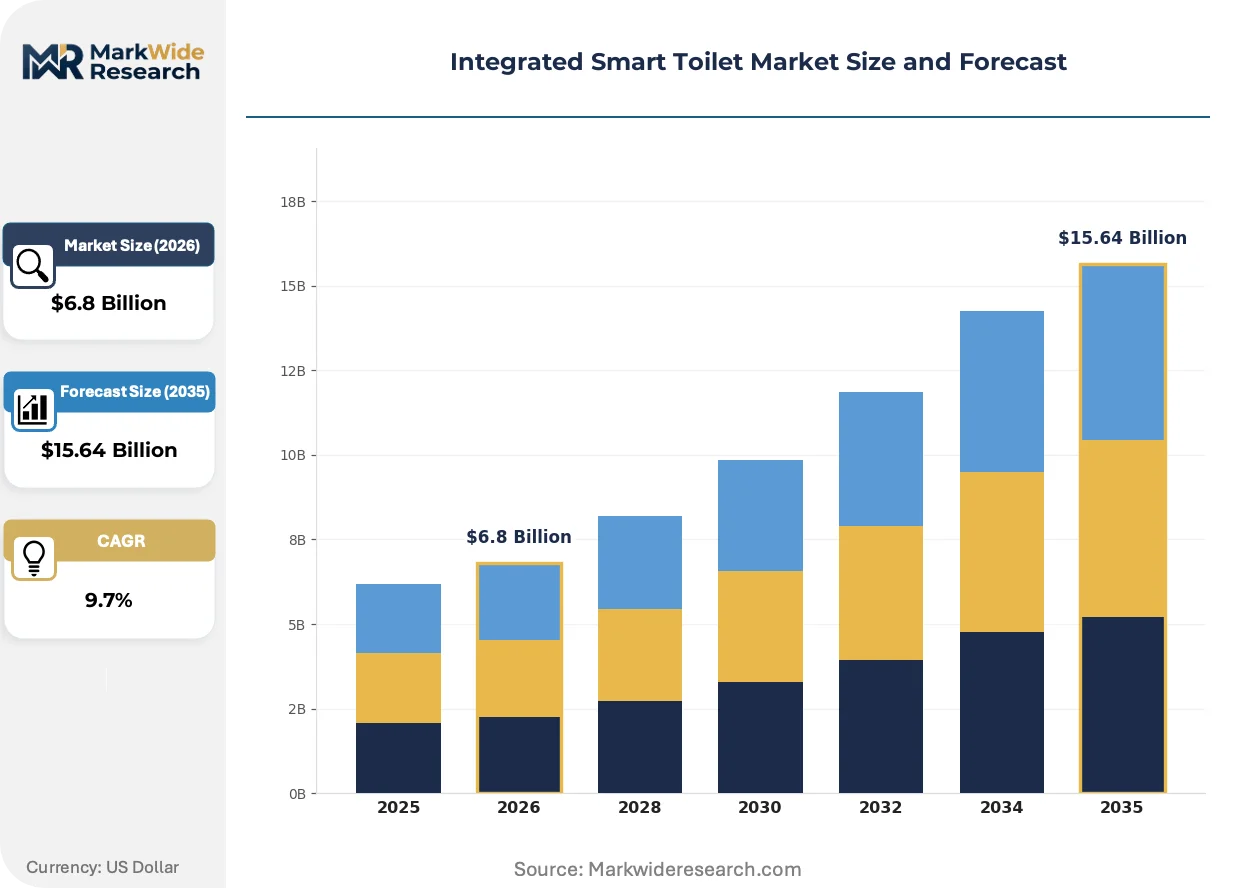
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.64 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: One-Piece, Two-Piece, Smart Bidet, Washlet Technology: IoT-Enabled, Sensor-Activated, Remote Control, Voice Command End User: Residential, Commercial, Healthcare, Hospitality Features: Heated Seat, Self-Cleaning, Deodorizer, Water Saving |
| Companies Covered | TOTO, LIXIL, Kohler, Jomoo, Villeroy & Boch, Duravit, Roca Sanitario, HUIDA, Dongpeng, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated Smart Toilet Market Trends and Innovations
Digital integration of waste management analytics with building automation systems is compressing the traditional boundary between sanitary hardware and facility management software, creating new specification criteria for commercial developers.
Edge computing architectures embedded directly in toilet control modules is virtualizing the data processing layer that previously required gateway infrastructure. Hospitality chains deploying these units across property portfolios capture real-time occupancy patterns and water consumption metrics without centralized server dependencies. This distributed intelligence architecture is virtualizing the facility management stack and displacing legacy building automation interfaces.
EU Ecodesign Directive amendments for electrical bathroom appliances are tightening testing protocols for moisture ingress and standby power consumption. Manufacturers serving European markets must recertify product lines against evolving efficiency benchmarks that now include lifecycle carbon accounting. Hospitality procurement teams in Germany and France are prioritizing suppliers with validated CE marking documentation to preempt installation delays.
Service contract unbundling is separating hardware ownership from maintenance obligations in commercial installations. Facility managers in Japanese prefectures increasingly specify TOTO and INAX units with captive service agreements rather than capital purchase models. This procurement pattern concentrates in high-traffic commercial restrooms where downtime costs exceed hardware depreciation schedules.
Integrated Smart Toilet Market Segmentation
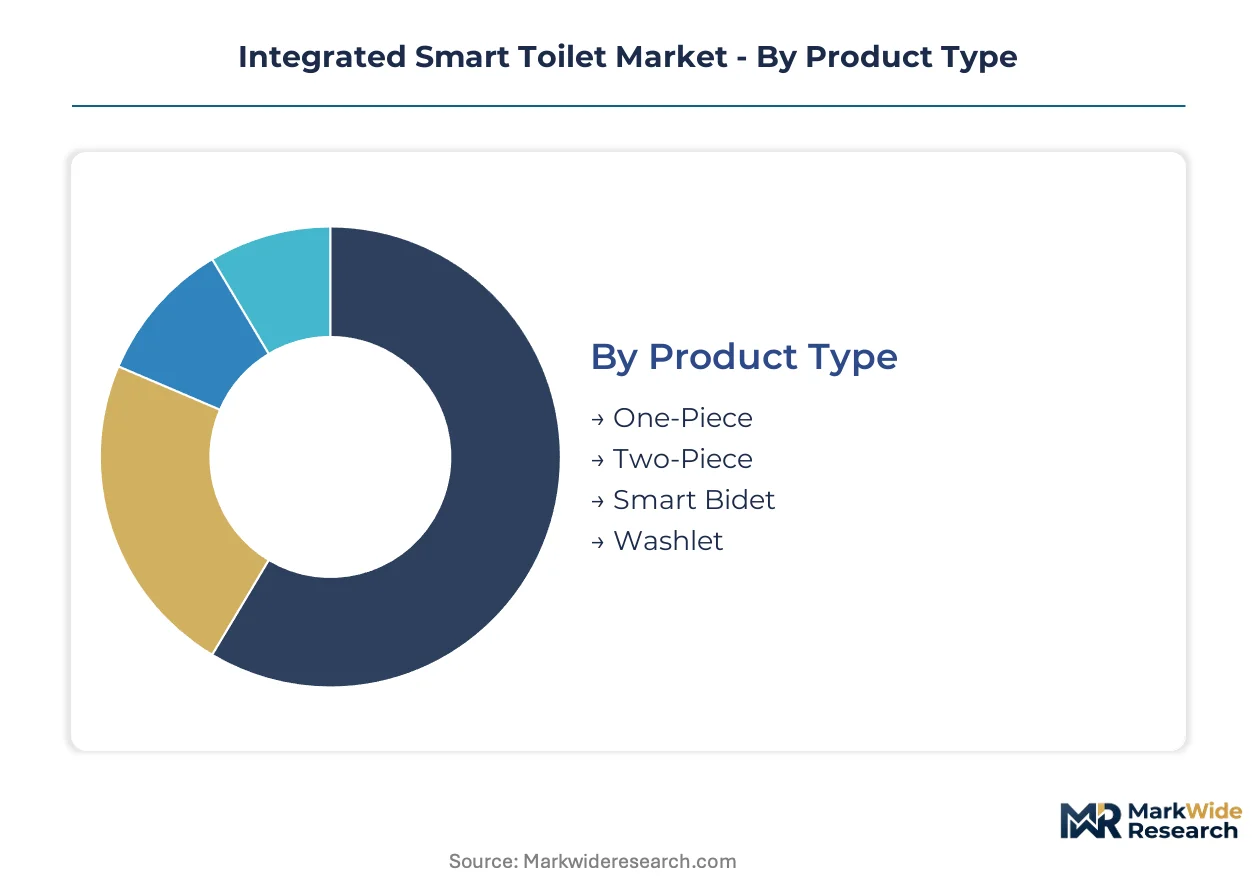
Segmentation in integrated smart toilets separates replacement-driven hardware from digitally enabled service platforms. Cycle time varies dramatically across categories, with ceramic fixtures turning over in decades while sensor modules refresh in 3-5 year intervals.
Product Type:
Replacement cycles stretch from 15-year ceramic lifespans to 5-year electronic refresh intervals, creating divergent aftermarket revenue profiles.
- One-Piece:Monolithic ceramic construction eliminates seam points where bacteria accumulate. Luxury residential developments in Seoul specify these units as standard amenity, driven by hygiene expectations and seamless aesthetic integration.
- Two-Piece:Separate tank and bowl components reduce shipping costs and simplify installation logistics. Commercial property managers in Tokyo's high-rise residential towers favor this format for maintenance accessibility and lower capital outlay per unit.
- Smart Bidet:Retrofit attachments converting conventional toilets to bidet functionality. Apartment renovation markets in Osaka sustain steady demand where full fixture replacement is structurally impractical.
- Washlet:Integrated seat-replacement systems with embedded water jets and heating elements. Japan's aging population drives replacement demand concentrated in the Tokyo-Osaka corridor where this technology originated.
Two-piece units dominate installed base. One-piece configurations are where expansion concentrates.
Technology:
Cost tiers separate premium connected platforms from basic electromechanical systems, with hospitality procurement gravitating toward data-generating capabilities.
- IoT-Enabled:Edge computing modules process occupancy and consumption data locally before cloud transmission. Hotel developers across Germany and France prioritize these units for portfolio-wide operational visibility and predictive maintenance scheduling.
- Sensor-Activated:Infrared proximity detectors trigger lid actuation and flush sequences without physical contact. Healthcare facilities specify these for infection control protocols, particularly in surgical recovery wards.
- Remote Control:Handheld or wall-mounted interfaces adjusting water pressure, temperature, and nozzle position. Residential users in South Korea's premium housing segments expect this functionality as baseline amenity.
- Voice Command:Integration with smart home assistants enabling hands-free operation. Early adoption concentrates in Japanese tech-forward households and luxury hospitality suites seeking differentiation.
Sensor-activated systems dominate installed base. IoT-enabled configurations are climbing the fastest.
End User:
Application context determines specification priorities, with commercial operators prioritizing durability metrics and residential buyers emphasizing comfort features.
- Residential:Single-family and multi-unit dwellings where user control and aesthetic integration drive selection. South Korean luxury developers embed bidet functionality as standard specification in new construction.
- Commercial:High-traffic restrooms in office buildings and retail centers where vandal resistance and rapid cycle times matter. Facility managers favor captive service agreements over capital purchase models.
- Healthcare:Hospitals and long-term care facilities requiring antimicrobial surfaces and touchless operation. Japan's geriatric care infrastructure sustains specialized demand for accessibility-optimized designs.
- Hospitality:Hotels and resorts where guest experience differentiation justifies premium procurement. Leak detection and usage analytics capabilities attract portfolio operators seeking operational visibility.
Residential applications dominate installed base. Hospitality represents the steepest expansion trajectory.
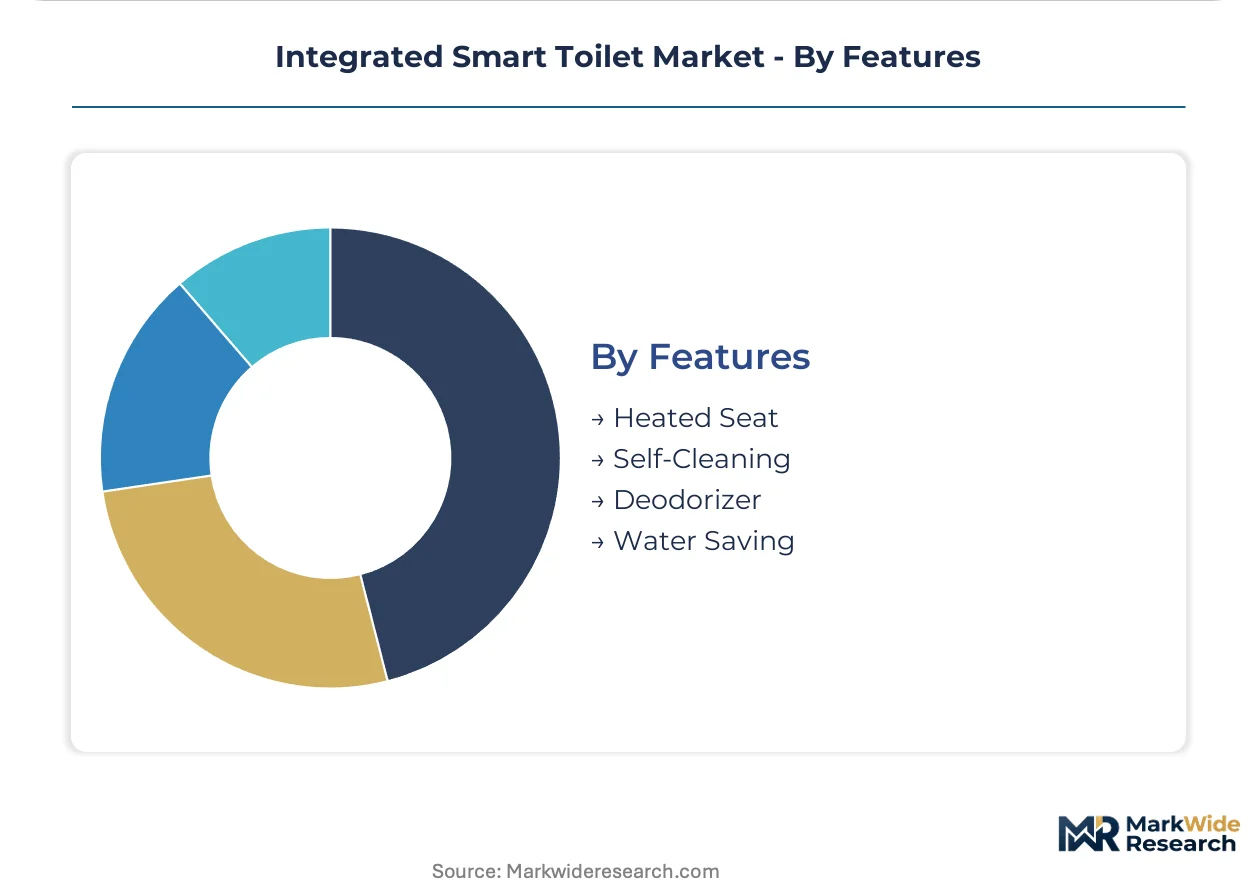
Features:
Margin pools concentrate in energy-intensive comfort features versus efficiency-driven water conservation technologies.
- Heated Seat:Resistive or PTC ceramic heating elements maintaining surface temperature. Japan's METI standby power regulations constrain idle electricity draw, compressing margin on entry-tier implementations.
- Self-Cleaning:Electrolyzed water or UV-C systems sanitizing nozzles between uses. Healthcare and hospitality procurement teams prioritize this capability for infection control compliance.
- Deodorizer:Activated carbon or catalyst-based air filtration integrated in the bowl rim. Premium residential specifications in Seoul and Tokyo treat this as expected amenity.
- Water Saving:Dual-flush mechanisms and pressure-assisted designs achieving sub-1.28 gallon per flush performance. EPA WaterSense certification unlocks utility rebate eligibility across drought-response US jurisdictions.
Heated seating dominates installed base. Water-saving configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese buyers demonstrate the lowest price elasticity, accepting premium positioning for hygiene-integrated fixtures, while retrofit costs suppress elasticity in older US housing stock where electrical infrastructure demands dominate total cost of ownership calculations.
United States
Utility rebate programs tied to EPA WaterSense certification accelerate specification in drought-response jurisdictions across California and Arizona. The federal environmental regulator mandates sub-1.28 gallon per flush performance thresholds for rebate eligibility. Installation concentrates in Sun Belt metro corridors where new construction bypasses retrofit constraints.
Japan
Aging demographics and established hygiene culture sustain replacement cycles concentrated in the Tokyo-Osaka metropolitan corridor. METI enforces standby power regulations constraining idle electricity draw for heated seating systems. Kitakyushu's ceramics cluster supplies vitreous china components to domestic assembly operations.
South Korea
Luxury residential developers in Seoul embed bidet functionality as standard amenity in premium housing pipelines. The national standards body aligns electrical safety certifications with IPX4 moisture protection ratings for bathroom appliances. Gyeonggi Province manufacturing zones export sensor modules to regional assembly facilities.
Germany
CE marking compliance under EU Ecodesign Directive amendments governs market access for electrical bathroom appliances. The federal transport and digital infrastructure ministry coordinates building efficiency standards with municipal water management digitization. Bavaria's industrial automation sector supplies edge computing components for IoT-enabled hospitality specifications.
France
Hospitality procurement teams prioritize suppliers with validated CE marking documentation to preempt installation delays in renovation markets. The national environmental agency enforces lifecycle carbon accounting in public building specifications. Île-de-France hotel developers deploy leak detection capabilities across portfolio properties for operational visibility.
Integrated Smart Toilet Market Competitive Landscape
Vertically integrated ceramics specialists and distributed electronics assemblers split the market into contrasting capability configurations. Consolidation pressure concentrates around captive service network scale and proprietary diagnostic tool ecosystems. Two strategic archetypes dominate: backward-integrated sanitary ware manufacturers controlling upstream vitreous china production, and modular electronics suppliers specializing in sensor-activation subsystems. Competitive moves center on M&A targeting regional service capabilities and technology licensing agreements for interoperability protocols.
Within the vertically integrated tier, TOTO exemplifies the archetype combining ceramics production with captive maintenance infrastructure. LIXIL occupies a comparable position through its distributed service network across Japanese prefectures. Kohler anchors North American positioning with dedicated technician certification programs. These three represent the dominant strategic configurations rather than exhaustive market coverage.
| Leading Market Players |
|---|
| TOTO |
| LIXIL |
| Kohler |
| Jomoo |
| Villeroy & Boch |
| Duravit |
| Roca Sanitario |
| HUIDA |
| Dongpeng |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Japan's Kitakyushu ceramics cluster compresses margin pools for non-integrated assemblers while amplifying pricing power for TOTO and LIXIL's captive vitreous china operations. This concentration dynamic forces three-tier pricing stratification across premium, standard, and economy levels, with aftermarket service bundling determining lifetime value capture.
Pricing Analysis
Aftermarket service contracts now drive lifetime value differentiation, with sensor calibration and nozzle replacement cycles generating recurring revenue streams that hardware margins alone cannot match. Pricing stratifies across premium, standard, and economy tiers based on certification grade—EPA WaterSense and METI standby compliance—and vertical integration depth. Cost compression in entry-tier units is intensifying because METI electricity draw limits constrain feature bundling. Residential buyers in Japan's Tokyo-Osaka corridor demonstrate lowest price sensitivity, while US retrofit markets face highest total cost of ownership barriers from electrical infrastructure upgrades.
Supply Chain Analysis
Supplier-financing facilities extended by Japanese ceramics producers enable inventory positioning for Korean and German assembly operations facing working capital constraints. Vitreous china production draws from Japan's Kitakyushu cluster, sensor modules from South Korea's Gyeonggi Province, and edge computing components from Germany's Bavaria region. Raw material dependencies span specialty ceramics, semiconductor-grade sensors, and PTC heating elements. Single-source vulnerability concentrates in Japan's ceramics base. Distribution runs through captive service networks for commercial accounts and retail channels for residential replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a replacement-cycle upswing driven by Japan's aging demographic infrastructure refresh, creating favorable conditions for service-integrated incumbents.
For Market Incumbents: Harden defensive positions by deepening backward integration into sensor module production and expanding captive technician certification programs across North American vocational channels. Sensor calibration complexity and proprietary diagnostic tool ecosystems create moats against modular electronics assemblers. Priority investment rests on interoperability protocol licensing to lock in hospitality IoT specifications. For New Entrants and Emerging Players: Build out white-space positions in US Sun Belt metro corridors where new construction bypasses retrofit constraints and utility rebate programs accelerate specification. The most penetrable segment lies in commercial property management seeking operational visibility through leak detection analytics. A direct contracting model with facility managers bypasses incumbent retail channel control. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated ceramics specialists with established service networks. Long-term viability centers on recurring revenue share expansion over hardware shipment volumes. Acquisition targets should demonstrate captive maintenance infrastructure and validated CE marking pathways. The signal to watch is hospitality procurement team prioritization of suppliers with portfolio-wide predictive maintenance capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Modules | Captive supply of calibration-critical components secures aftermarket revenue streams against modular competitors. |
| Technician Certification Program Expansion | Kohler's North American smart plumbing training addresses certified technician scarcity constraining installation capacity. |
| IoT Platform Interoperability Licensing | Protocol standardization with municipal water management systems creates specification advantages in urban digitization projects. |
| CE Marking Documentation Investment | Validated EU Ecodesign compliance preempts installation delays in German and French hospitality renovation markets. |
| Captive Service Agreement Unbundling | TOTO's facility management contracts in Japanese prefectures concentrate high-traffic commercial restroom procurement. |
Research Methodology
The analysis maps washlet replacement cycles, IoT-enabled hospitality specifications, and bidet retrofit attachments, each validated through facility managers, smart plumbing technicians, ceramics procurement leads, and hospitality development executives. Primary interviews with these stakeholders combined with secondary validation from EPA WaterSense certification databases, METI standby power filings, EU Ecodesign Directive amendments, and customs trade data for vitreous china components. Bottom-up unit shipment estimates triangulated against top-down construction spending and renovation permit data.
Forecast assumptions held fixed the regulatory compliance timelines for EPA WaterSense, METI standby power limits, and EU Ecodesign amendments, while varying replacement cycle acceleration rates and hospitality IoT adoption curves across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user application, and feature bundling configuration. CAGRs derived from regression analysis against demographic aging indices, new construction permitting, and utility rebate program expansion. Industry-specific inputs incorporated ceramics capacity utilization rates and sensor module refresh intervals.
Stress conditions across tariff exposure for Japanese ceramics imports, freight cost volatility for vitreous china, and METI regulatory stringency adjustments were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Macroeconomic deviation in construction lending, regulatory acceleration in standby power limits, or technological disruption in solid-state heating elements would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Wipes Market
Household Items
GCC Gas Hobs Market
Household Items
Titanium Thermos Cup Market
Household Items
Luxury Massage Chair Market
Household Items
Mason Jars and Canning Supplies Market
Household Items
Trash Can Market
Household Items
Stainless Steel Toilet Paper Dispenser Market
Household Items
Smart Memory Foam Market
Household Items
Middle East Handheld Vacuum Cleaner Market
Household Items
Shower Caddies Market
Household Items
Turkey Cookware Market
Household Items
Germany Induction Hobs Market
Household Items
United States Barbeque Grill Market
Household Items
Steam Cleaners Market
Household Items
Toilet Care Wipes Market
Household Items
Netherlands Cookware Market