
 Insulated Dog House Market | 2026-2036
Insulated Dog House Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Dog House Market Analytics
Market Context
Specialized woodworking and rotational-molding technician availability is rotating toward larger pet-product conglomerates, compressing craft-level production capacity across the insulated dog house landscape. ASL Solutions leverages captive manufacturing in the upper Midwest to sustain year-round output of foam-core polymer units. Petmate anchors mass-market distribution through big-box retail partnerships and private-label arrangements. Blythe Wood Works specializes in custom cedar builds with integrated HVAC ports, occupying the premium architectural segment where hand-finish labor remains scarce.
Technical Definition and Structural Segments
An insulated dog house is an enclosed shelter engineered with thermal-barrier materials—typically expanded polystyrene, polyurethane foam, or natural wool batting—between structural skins to maintain stable interior temperatures across ambient extremes from sub-zero conditions to sustained heat above 90°F. Composite and plastic variants dominate volume production due to moisture resistance and moldability, while wood constructions retain preference among buyers seeking aesthetic integration with residential architecture. The extra-large size tier leads absolute dollar contribution as multi-dog households and commercial kennel operators prioritize scalable climate control. Online retailers represent the fastest-growing distribution channel, disintermediating traditional pet-store footprints and enabling direct-to-consumer configuration tools that reduce return rates for size-mismatched purchases.
Regulatory Frame and Outlook
OSHA workplace standards indirectly shape commercial kennel procurement by mandating adequate shelter square footage per animal, while EPA regulations on volatile organic compound emissions constrain adhesive and sealant choices in domestic manufacturing. The Consumer Product Safety Commission monitors small-component choking hazards, particularly for detachable door flaps and ventilation grilles in units marketed for toy breeds. Stakeholders must monitor evolving state-level animal welfare codes that increasingly specify minimum R-value thresholds for outdoor housing in jurisdictions with seasonal temperature swings.
Market Dynamics
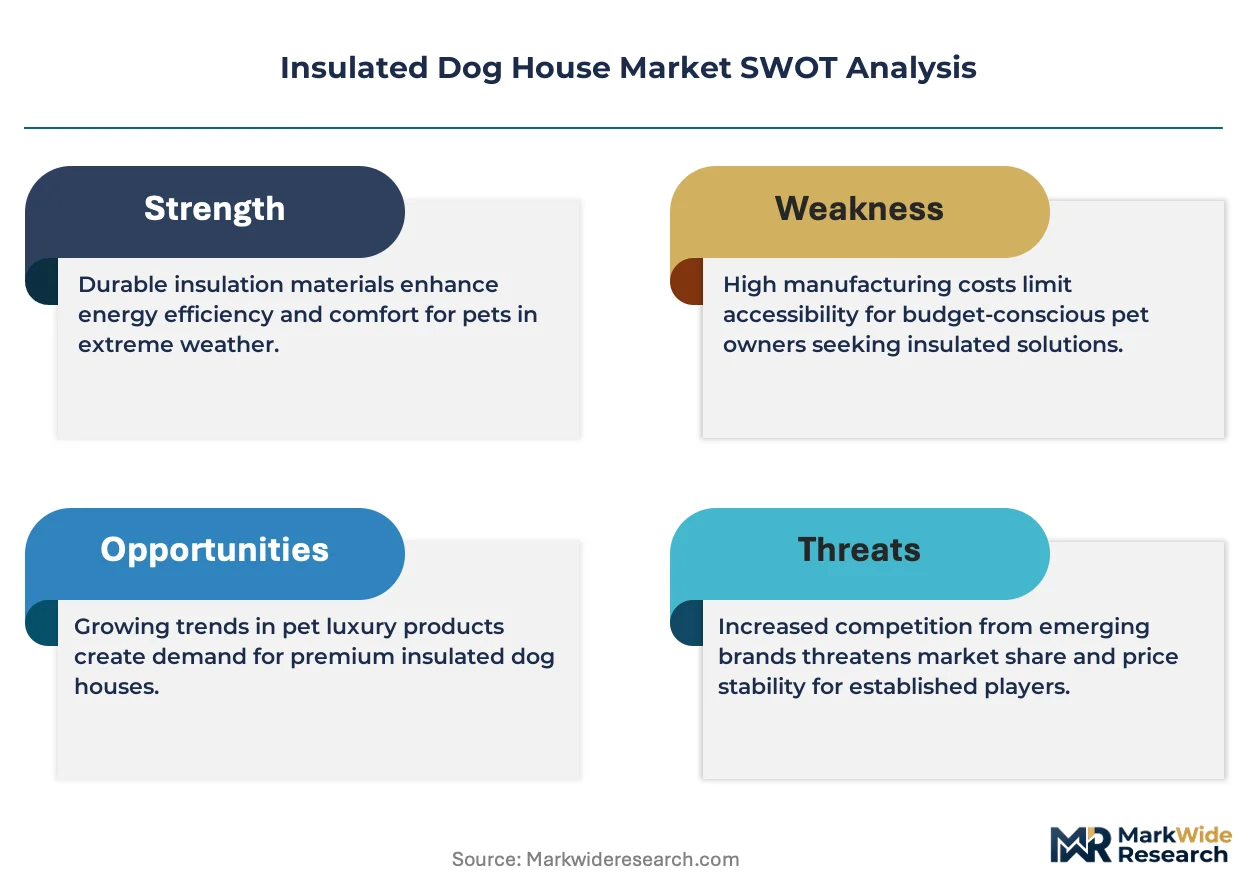
EPA volatile organic compound restrictions on adhesives and sealants are compressing domestic manufacturing flexibility while concentrating production among facilities with captive chemical-handling permits.
Growth Catalysts
- Pet Humanization in Suburban Households:Working and companion dogs receive climate-controlled shelter investments comparable to residential HVAC systems, expanding the addressable base for premium thermal-barrier units.
- OSHA Commercial Kennel Mandates:Workplace shelter standards mandate adequate square footage per animal, institutionalizing procurement of extra-large climate-controlled housing across veterinary boarding and breeding operations.
- Rotational Molding Scale Economies:Foam-core polymer construction achieves moisture resistance and thermal performance at unit costs below cedar alternatives, accelerating volume production capacity.
Market Restraints
- Treated Lumber Input Volatility:Pressure-treated wood pricing fluctuates with construction sector demand cycles, compressing margin stability for cedar-focused manufacturers.
- Specialized Technician Scarcity:Craft-level woodworking and rotational-molding labor concentrates in upper Midwest manufacturing clusters, limiting geographic diversification of production.
- Natural Wool Substitution Pressure:Synthetic batting alternatives achieve comparable R-values at lower moisture-absorption risk, eroding preference for heritage insulation materials.
Strategic Opportunities
- Direct-to-Consumer Configuration Tools:Online retailers deploy size-matching algorithms that reduce return rates for dimension-critical purchases, capturing channel margin previously allocated to brick-and-mortar footprints.
- State Animal Welfare Code Escalation:Jurisdictions with seasonal temperature swings increasingly specify minimum R-value thresholds for outdoor housing, mandating replacement cycles for non-compliant legacy shelters.
- HVAC Integration Architectures:Premium cedar builds incorporate dedicated climate-system ports, converging residential mechanical infrastructure with pet shelter design.
Industry Challenges
- Hand-Finish Labor Bottlenecks:Architectural-grade custom construction requires skilled woodworking capacity that remains scarce relative to mass-market polymer output.
- Multi-Jurisdiction Compliance Mapping:Manufacturers must track evolving state-level thermal-performance codes that lack federal harmonization, fragmenting product certification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Dog House Market |
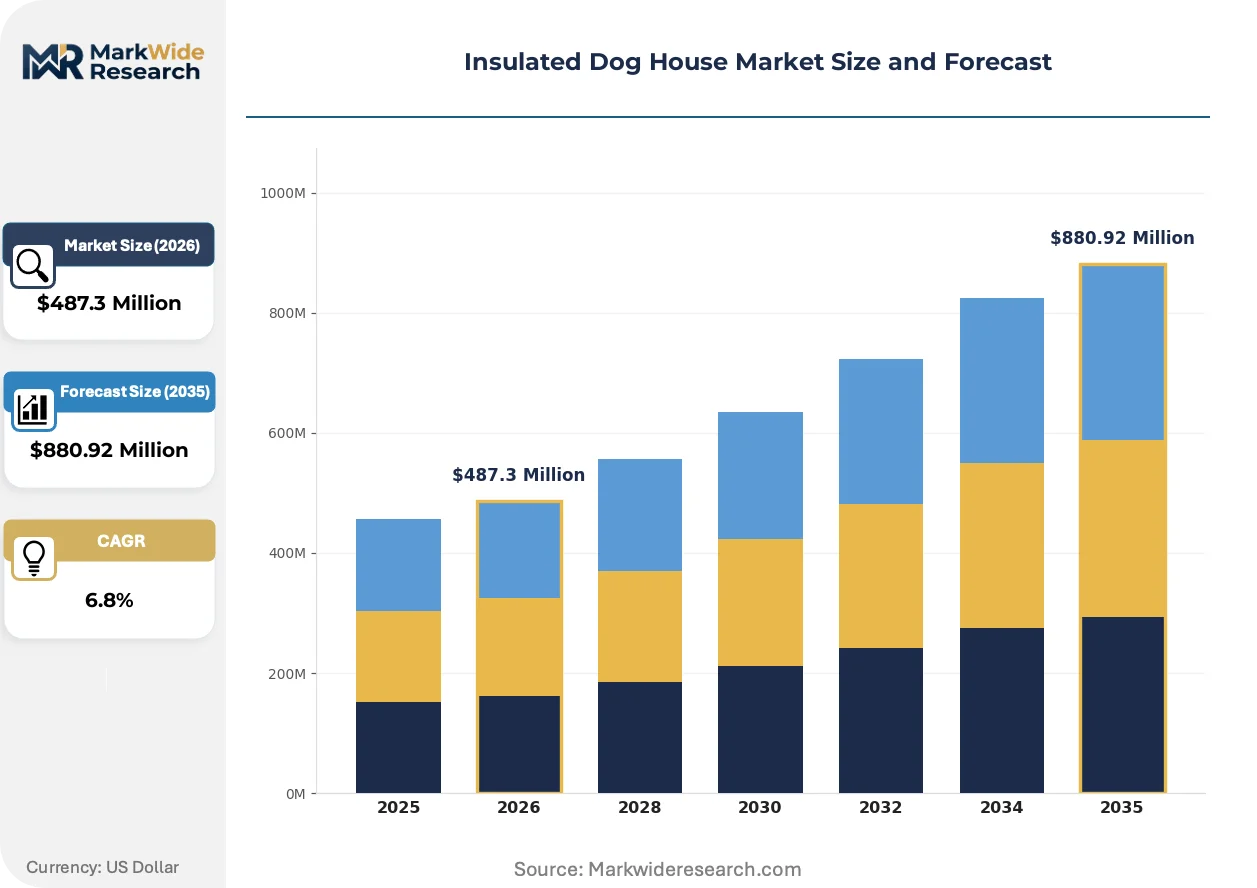
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood, Plastic, Metal, Composite Size: Small, Medium, Large, Extra Large End User: Pet Owners, Animal Shelters, Pet Hotels, Breeders Distribution Channel: Online Retailers, Pet Stores, Home Improvement Stores, Specialty Shops |
| Companies Covered | Petmate, ASL Solutions, Dogloo, Precision Pet Products, Suncast Corporation, Northland Pet Supply, Doowaggle, Blythe Wood Works, Apex Shed Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Dog House Market Evolving Landscape
Material science advances and channel restructuring are actively fragmenting how insulated dog houses are specified, manufactured, and delivered to end-users.
Phase-change material integration is bifurcating thermal management approaches. Microencapsulated paraffin wax layers absorb and release latent heat across diurnal temperature swings, stabilizing interior conditions without active power. Commercial kennel operators in Texas and Florida are specifying these units for working dog facilities exposed to prolonged heat cycles. This capability is bifurcating the market between passive thermal-mass designs and active HVAC-dependent systems.
REACH substance restrictions on isocyanate-based polyurethane formulations are constraining European manufacturing inputs. Domestic producers face reformulation timelines and alternative sourcing for foam-core insulation that maintains R-value performance. Small-batch cedar specialists in Germany and Scandinavia are gaining relative advantage as natural-material exemptions reduce regulatory compliance burden versus polymer competitors.
Configuration-driven purchasing is displacing standard SKU selection. Buyers utilize online visualization tools to specify dimensions, port placements, and finish grades prior to order confirmation. This behavioral shift concentrates demand among retailers with parametric design capabilities, compressing traditional pet-store distribution for made-to-measure segments. The southeastern United States exhibits highest adoption intensity, correlating with elevated heat-stress risk and corresponding precision requirements for thermal regulation.
Insulated Dog House Market Segmentation
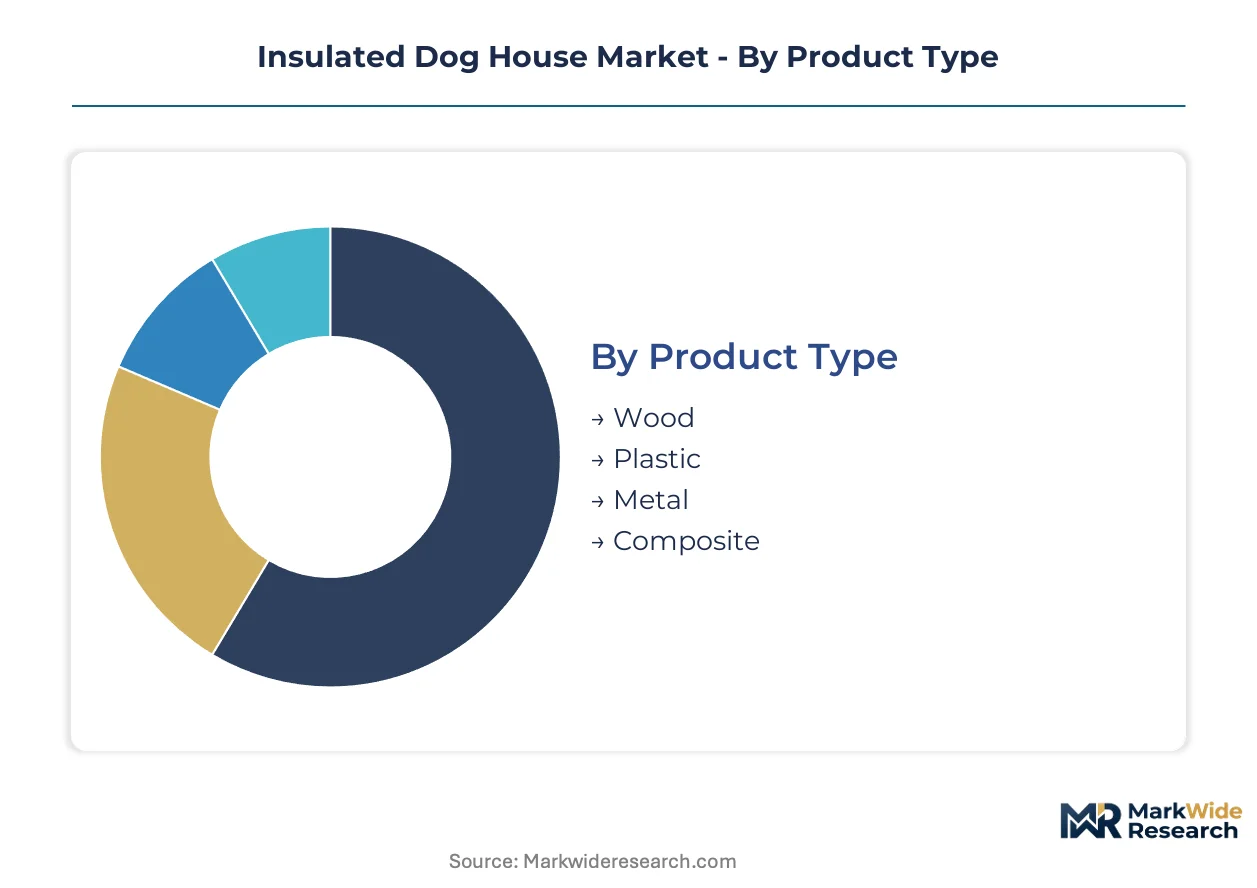
Insulated dog house procurement varies sharply by use case and channel, with material selection driven by climate exposure, aesthetic requirements, and regulatory compliance. Size tiers correlate directly with institutional versus household demand patterns. Distribution channel choice determines configuration flexibility and return-rate economics.
Product Type:
Wood faces the most acute substitution pressure from polymer alternatives as moisture resistance and maintenance-free operation displace traditional cedar specifications in humid climates.
- Wood:Cedar and pressure-treated pine constructions integrate with residential architecture through stain-matching and custom millwork. Southeastern United States homeowners specify these units for aesthetic continuity with outdoor living spaces, though EPA volatile organic compound restrictions on adhesives constrain domestic manufacturing flexibility.
- Plastic:Rotational-molded polyethylene shells with foam-core insulation achieve thermal performance at unit costs below cedar alternatives. Mass-market volume concentrates in big-box retail partnerships where moisture resistance and moldability accelerate procurement for multi-dog households.
- Metal:Galvanized steel frames with insulated panel inserts serve commercial kennel operators prioritizing durability and sanitization protocols. OSHA workplace standards mandate adequate shelter square footage per animal, institutionalizing metal-frame procurement across veterinary boarding facilities.
- Composite:Wood-plastic hybrid constructions balance aesthetic customization with moisture resistance, occupying mid-tier positioning between premium cedar and mass-market polymer units.
Plastic anchors the volume base while composite gains share at the steepest rate as buyers seek middle-ground solutions.
Size:
Cost tier stratification separates premium architectural builds from standard utility shelters, with institutional procurement concentrating at the upper end of the dimensional range.
- Small:Compact enclosures for toy breeds incorporate detachable door flaps and reduced ventilation grilles monitored by the Consumer Product Safety Commission for choking hazards. Urban households in space-constrained environments drive specification.
- Medium:Single-dog shelters for working breeds balance thermal mass against footprint efficiency, with direct-to-consumer configuration tools reducing return rates for dimension-critical purchases.
- Large:Multi-dog compatible structures serve suburban households with companion animals, where pet humanization trends elevate climate-control investments comparable to residential HVAC systems.
- Extra Large:Scalable climate-controlled housing leads absolute dollar contribution as commercial kennel operators and breeding facilities prioritize batch thermal management under state animal welfare codes specifying minimum R-value thresholds.
Extra large commands the highest revenue per unit while large expands most quickly among suburban household upgrades.
End User:
Application maturity separates established pet owner demand from emerging institutional procurement governed by workplace and welfare regulations.
- Pet Owners:Suburban households invest in climate-controlled shelters as companion animal status elevates thermal-barrier specifications toward residential building standards.
- Animal Shelters:Municipal and nonprofit facilities prioritize sanitizable surfaces and durable construction under budget constraints, favoring polymer over cedar for operational longevity.
- Pet Hotels:Veterinary boarding operations mandate OSHA-compliant square footage per animal, institutionalizing extra-large climate-controlled housing procurement with dedicated HVAC integration ports.
- Breeders:Commercial breeding facilities in Texas and Florida specify phase-change material integration for working dog facilities exposed to prolonged heat cycles, stabilizing interior conditions without active power.
Pet owners provide the installed base volume while pet hotels climb the fastest as workplace shelter standards proliferate.
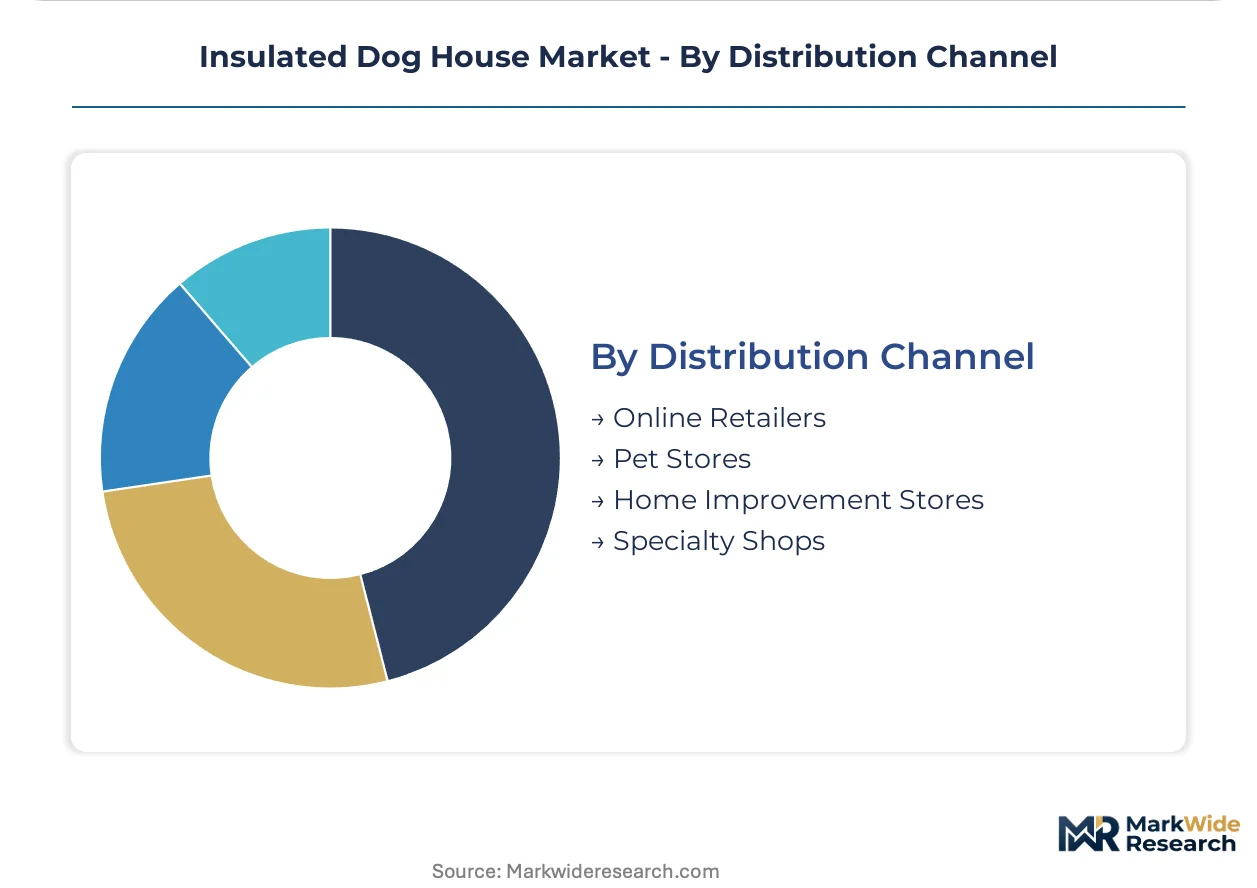
Distribution Channel:
Customer type fragmentation separates configuration-driven purchasers from specification-driven institutional buyers, with channel choice determining margin capture and return-rate exposure.
- Online Retailers:Parametric design capabilities enable direct-to-consumer configuration tools that reduce return rates for size-mismatched purchases, concentrating demand among retailers with visualization technology.
- Pet Stores:Traditional brick-and-mortar footprints face compression as made-to-measure segments migrate online, retaining primarily impulse purchases and replacement parts.
- Home Improvement Stores:Big-box retail partnerships anchor mass-market distribution for plastic and composite units, with private-label arrangements capturing channel margin.
- Specialty Shops:Architectural-grade custom construction requires skilled woodworking capacity that remains scarce relative to mass-market polymer output, limiting geographic coverage.
Online retailers capture the steepest expansion trajectory while home improvement stores defend the volume base through established logistics infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in the southeastern United States where heat-stress risk elevates thermal-performance specifications, while cost-sensitive procurement dominates Midwest manufacturing clusters serving mass-market polymer units.
United States
Suburban pet humanization in Florida, Georgia, and Texas drives specification of climate-controlled shelters with integrated HVAC ports. EPA volatile organic compound restrictions on adhesives and sealants compress domestic manufacturing flexibility, favoring facilities with captive chemical-handling permits. ASL Solutions anchors production in the upper Midwest to sustain year-round foam-core polymer output.
Germany
REACH substance restrictions on isocyanate-based polyurethane formulations constrain foam-core insulation sourcing for rotational-molded units. Natural-material exemptions reduce regulatory compliance burden for small-batch cedar specialists in Bavaria and Baden-Württemberg, gaining relative advantage over polymer competitors. Craft-level woodworking capacity concentrates in Black Forest manufacturing clusters.
United Kingdom
RSPCA welfare codes specifying minimum shelter standards institutionalize replacement cycles for non-compliant legacy housing across England and Wales. Online retailers with parametric design capabilities capture channel margin from traditional pet-store footprints. Greater London and Southeast England exhibit highest adoption intensity for configuration-driven purchasing.
Canada
Health Canada monitors small-component choking hazards for detachable door flaps in units marketed for toy breeds. Sub-zero climate exposure in Prairie Provinces and Ontario elevates R-value specifications toward passive thermal-mass designs. Alberta and British Columbia manufacturing clusters specialize in wood-plastic composite constructions balancing moisture resistance with aesthetic customization.
Australia
Prolonged heat cycles in Queensland and New South Wales drive specification of phase-change material integration for working dog facilities. TGA-equivalent product safety oversight applies to imported polymer units. Melbourne and Sydney distribution hubs concentrate direct-to-consumer configuration tool deployment, reducing return rates for dimension-critical purchases.
Insulated Dog House Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the insulated dog house landscape. The market structures around a consolidated premium tier with scarce hand-finish labor and a fragmented mass-market tier competing on rotational-molding scale economies. Three archetypes dominate: captive-manufacturing polymer specialists, architectural-grade custom woodworkers, and mass-market private-label distributors. Competitive moves concentrate on direct-to-consumer channel expansion and state-level regulatory compliance certification.
Within the captive-manufacturing tier, ASL Solutions exemplifies geographic concentration of foam-core polymer production in the upper Midwest. Among architectural-grade specialists, Blythe Wood Works occupies a position representing premium cedar construction with integrated HVAC ports. At the mass-market end, Petmate anchors big-box retail distribution through private-label arrangements, situating scale-driven procurement as the volume base.
| Leading Market Players |
|---|
| Petmate |
| ASL Solutions |
| Dogloo |
| Precision Pet Products |
| Suncast Corporation |
| Northland Pet Supply |
| Doowaggle |
| Blythe Wood Works |
| Apex Shed Company |
| Others |
Value Network & Pricing Analysis
Synthetic batting substitution for natural wool insulation is simultaneously concentrating production in upper Midwest polymer clusters and compressing margin stability for cedar-focused manufacturers facing pressure-treated lumber volatility. This input shift bifurcates pricing power between rotational-molding scale economies and scarce hand-finish woodworking capacity.
Pricing Analysis
Geographic price spreads between southeastern United States premium specifications and Midwest mass-market units reflect climate-driven performance tiering. Three-tier pricing structure across architectural-grade custom builds, configured mid-market composites, and standard polymer SKUs separates buyers by customization level and thermal certification. Cost compression in cedar segments stems from construction sector demand cycles for pressure-treated inputs. Commercial kennel operators show lowest price sensitivity due to OSHA mandate compliance requirements, while suburban household upgraders exhibit highest elasticity.
Supply Chain Analysis
Inventory lead times for foam-core polymer shells run shorter than custom cedar millwork due to captive rotational-molding capacity in the upper Midwest. Supply concentrates in the United States for domestic manufacturing, with Germany and Canada contributing specialty woodworking and composite inputs respectively. Raw material dependencies include expanded polystyrene resin, pressure-treated lumber, and galvanized steel framing. Tariff exposure on Canadian softwood imports constitutes the primary structural risk. Distribution runs through big-box retail partnerships for volume tiers and direct-to-consumer configuration platforms for made-to-measure segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates opportunity across three distinct competitive arenas as pet humanization splits demand between institutional compliance procurement and residential aesthetic integration.
For Market Incumbents: Fortify position by deepening captive manufacturing of foam-core polymer units in the upper Midwest to defend against cedar specialist encroachment in premium segments. Secure state-level R-value certification pre-approvals before animal welfare code escalations fragment compliance requirements. Channel control through big-box private-label arrangements remains the critical defensive lever against online retailer disintermediation. For New Entrants and Emerging Players: Lead with phase-change material integration targeting commercial kennel operators in Texas and Florida where prolonged heat cycles create specification white-space. The online direct-to-consumer channel offers lowest barrier-to-entry for configured composite builds displacing traditional pet-store distribution. A go-to-market angle emphasizing parametric size-matching algorithms captures return-rate economics from established retailers lacking visualization capabilities. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed pet product conglomerates holding rotational-molding capacity but lacking HVAC integration architecture expertise. Long-term viability centers on convergence with residential mechanical infrastructure standards. The signal to watch is state-level R-value threshold adoption velocity as replacement cycle catalyst for non-compliant legacy inventory.| Strategic Initiative | Industry Significance |
|---|---|
| HVAC Integration Architecture Development | Converges residential mechanical infrastructure with pet shelter design for premium tier capture. |
| Direct-to-Consumer Configuration Platform Launch | Deploys parametric design capabilities reducing return rates for dimension-critical purchases. |
| State R-Value Certification Pre-Approval | Secures compliance positioning before animal welfare code escalations fragment requirements. |
| Phase-Change Material Product Line Extension | Targets Texas and Florida commercial kennel operators exposed to prolonged heat cycles. |
| Midwest Rotational-Molding Capacity Expansion | Captures scale economies in foam-core polymer production serving mass-market volume tiers. |
Research Methodology
The analysis maps wood, plastic, metal, and composite construction sub-sectors, each validated through plant managers at rotational-molding facilities, procurement leads at commercial kennel operators, and category buyers at big-box retailers. Primary interview data triangulates against secondary sources including EPA regulatory filings, OSHA workplace standard documentation, state animal welfare code databases, and customs records for treated lumber imports. Bottom-up unit economics and top-down market sizing converge through iterative stakeholder validation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include material type, size tier, end-user application, and distribution channel complexity. CAGRs derive from demand elasticity analysis and replacement cycle dynamics. Industry-specific forecast inputs incorporate pet ownership demographic shifts and regulatory compliance timeline assumptions.
Forecasts assume regulatory continuity in EPA volatile organic compound regimes and OSHA workplace shelter standards; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Argentina Pet Food Market
Pet Care Products
Outdoor Cat House Market
Pet Care Products
Dog Harness Market
Pet Care Products
Europe Pet Treats Market
Pet Care Products
Frozen Pet Food Market
Pet Care Products
Outdoor Cat Houses and Furniture Market
Pet Care Products
Interactive Dog Toys Market
Pet Care Products
Kitten Milk Replacer and Formula Market
Pet Care Products
Dog Shampoo Market
Pet Care Products
US Pet Treats Market
Pet Care Products
Indonesia Pet Care Market
Pet Care Products
US Dog Food Market
Pet Care Products
Dog Litter Boxes Market
Pet Care Products
Mexico Pet Food Market
Pet Care Products
North America Pet Diet Market
Pet Care Products
Global Pet Stroller Market